
 Veterinary Computed Tomography Scanner Market | 2026-2036
Veterinary Computed Tomography Scanner Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Computed Tomography Scanner Market Analytics
European veterinary equipment manufacturing is pivoting toward compact, mobile CT platforms suited for clinic-based deployment. Siemens Healthineers leverages its human imaging heritage to anchor premium multi-slice veterinary systems across German and Swiss markets. GE Healthcare competes through integrated service networks that sustain long-term customer relationships in North American academic veterinary centers. Canon Medical Systems Corporation specializes in cone-beam architectures that differentiate its portfolio for dental and maxillofacial applications in companion animal practice.
Veterinary computed tomography scanners are X-ray-based imaging systems producing cross-sectional anatomical reconstructions with sub-millimeter spatial resolution, typically operating at 80–140 kVp tube potentials adapted for species ranging from exotic avians to equine patients. Their primary purpose is non-invasive diagnostic visualization of neoplastic, orthopedic, and neurological pathologies in animals where conventional radiography yields insufficient contrast or spatial detail. Portable systems command expanding share among independent veterinary clinics seeking to avoid capital-intensive fixed-room installations, while multi-slice scanners concentrate margin pools in tertiary referral hospitals performing complex oncologic staging and interventional planning. Cone Beam CT technology penetrates fastest in dentistry and oral surgery applications where reduced radiation dose and focused field-of-view match procedural requirements.
The FDA Center for Veterinary Medicine and USDA Animal and Plant Health Inspection Service jointly shape device approval pathways and radiation safety protocols for veterinary imaging equipment in the United States, while ISO 13485 quality management standards govern manufacturing consistency across international supply chains. The EU Medical Device Regulation, though primarily human-focused, creates precedent pressure for enhanced clinical evidence documentation among manufacturers distributing in European veterinary markets. Stakeholders must monitor how evolving veterinary telemedicine regulations and state-level practice acts reshape site-of-service requirements for advanced diagnostic imaging.
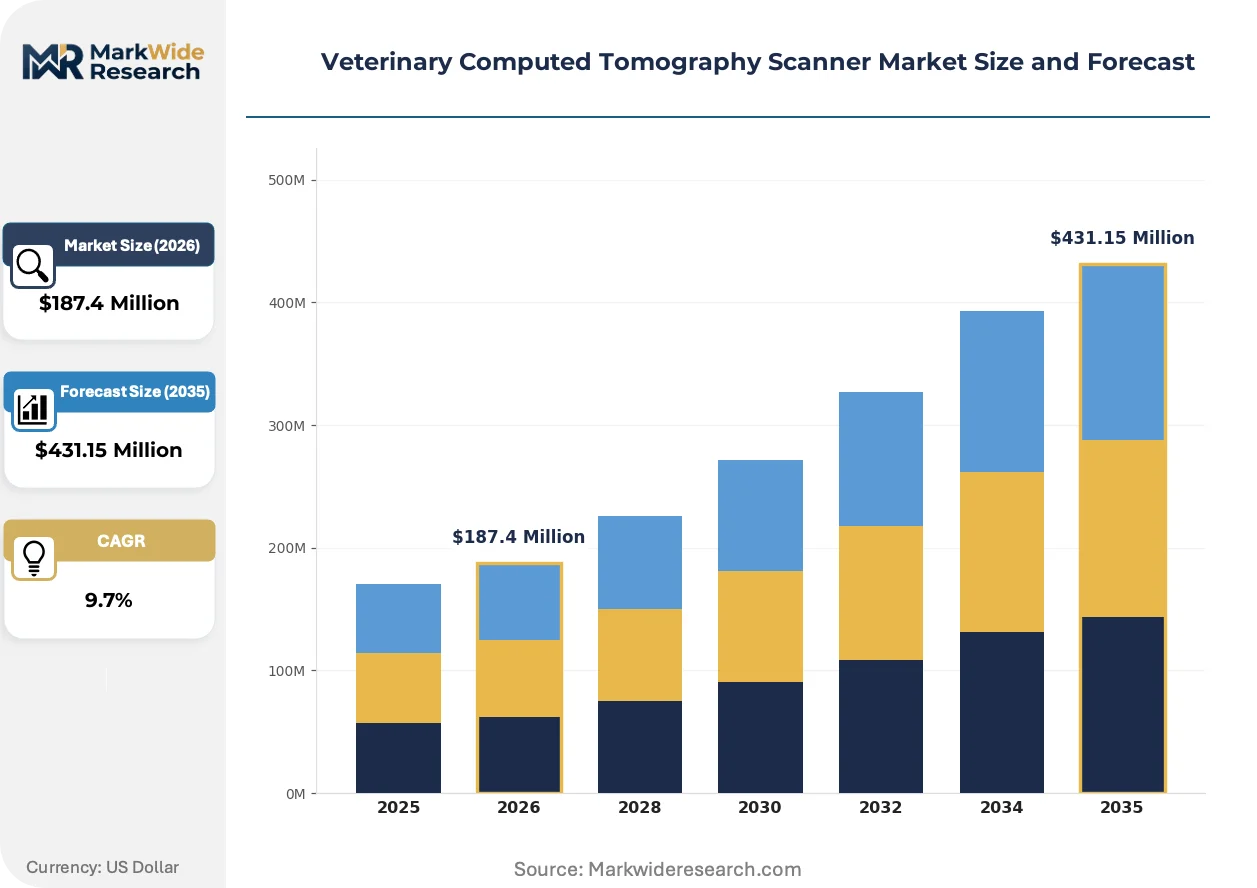
Market Dynamics
Portable cone-beam CT platforms are compressing capital barriers for independent veterinary clinics, redistributing diagnostic capacity away from tertiary referral hospitals and fragmenting equipment procurement patterns across companion animal practice networks.
Growth Catalysts
- Oncology referral volume:Specialty veterinary hospitals in the United States are expanding CT staging protocols for canine and feline neoplasia, creating installed base demand for multi-slice systems capable of whole-body imaging.
- ISO 13485 certification pathways:Harmonized quality management standards across international supply chains are accelerating regulatory clearance timelines for manufacturers seeking multi-jurisdiction market entry.
- Equine diagnostic imaging:Large-animal veterinary practices in Kentucky and Florida are adopting mobile CT configurations for distal limb and cervical spine evaluation, extending addressable species coverage beyond traditional companion animal markets.
Market Restraints
- Xenon detector supply concentration:High-purity scintillator crystal production concentrates among Japanese and German specialty chemical suppliers, exposing equipment manufacturers to input cost volatility and single-source risk.
- FDA Center for Veterinary Medicine device classification:Cross-species imaging claims trigger extended premarket notification requirements, compressing product development timelines and elevating compliance expenditure for novel system architectures.
- Conventional radiography substitution:Digital radiography systems with computed tomography reconstruction software present lower capital alternatives for orthopedic screening, constraining CT penetration in price-sensitive general practice segments.
Strategic Opportunities
- Telemedicine-integrated teleradiology:State-level veterinary practice act modifications in California and Texas are enabling remote CT interpretation services, creating channel innovation for equipment vendors to bundle hardware with subscription-based diagnostic support.
- Avian and exotic species imaging:Zoological and wildlife rehabilitation centers represent underpenetrated end-use verticals requiring specialized low-dose protocols and modified patient positioning systems.
- EU Medical Device Regulation precedent pressure:Enhanced clinical evidence documentation requirements for human medical devices are elevating veterinary product quality benchmarks, creating competitive differentiation for manufacturers with robust safety dossiers.
Industry Challenges
- Veterinary radiographer certification scarcity:American College of Veterinary Radiology residency positions remain limited, constraining specialist workforce availability to operate and interpret advanced imaging equipment in expanding practice networks.
- Legacy PACS integration complexity:Hospital information system interoperability requirements demand customized DICOM configuration for each vendor platform, extending installation timelines and elevating field service engineering costs.
- Radiation safety officer training mandates:State radiation control program requirements for personnel certification create operational friction for clinics seeking to deploy CT capability without dedicated nuclear medicine expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Computed Tomography Scanner Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $431.15 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Performance Systems, Portable Systems, Multi-Slice Scanners, Low-Cost Solutions End User: Veterinary Clinics, Research Institutions, Animal Hospitals, Academic Institutions Technology: CT Angiography, Cone Beam CT, Dual-Energy CT, 3D Imaging Technologies Application: Oncology, Neurology, Orthopedics, Internal Medicine |
| Companies Covered | Epica International, Neurologica Corporation, Siemens Healthineers, Xoran Technologies, Hallmarq Veterinary Imaging, GE Healthcare, Sound, Animage, Canon Medical Systems Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Computed Tomography Scanner Market Evolving Landscape
Cone-beam CT architectures are compressing equipment footprints while elevating spatial resolution for dental and maxillofacial applications, fundamentally restructuring how imaging capability deploys across veterinary practice settings.
Portable cone-beam CT systems are decentralizing diagnostic access by enabling point-of-care imaging within standard examination rooms rather than dedicated shielded suites. Independent veterinary clinics in suburban United States markets are adopting these configurations to capture referral revenue previously directed to specialty hospitals. This technology is decentralizing capital investment patterns and compressing patient throughput times for routine dental and sinus evaluations.
The FDA Center for Veterinary Medicine's evolving guidance on software-as-a-medical-device claims is reshaping product development priorities for reconstruction algorithm vendors. Manufacturers must now document cross-species validation datasets before deploying machine learning-enhanced image processing. Multi-slice CT platforms with iterative reconstruction capabilities face the most significant compliance burden, prompting some vendors to segment product lines by species indication.
Subscription-based service contracting is displacing traditional equipment ownership models among North American veterinary groups. Corporate practice consolidators are negotiating fleet management agreements that bundle hardware, maintenance, and radiologist interpretation through single vendor relationships. This restructuring concentrates procurement authority at regional headquarters rather than individual clinic level, favoring suppliers with integrated service networks over standalone equipment manufacturers.
Veterinary Computed Tomography Scanner Market Segmentation
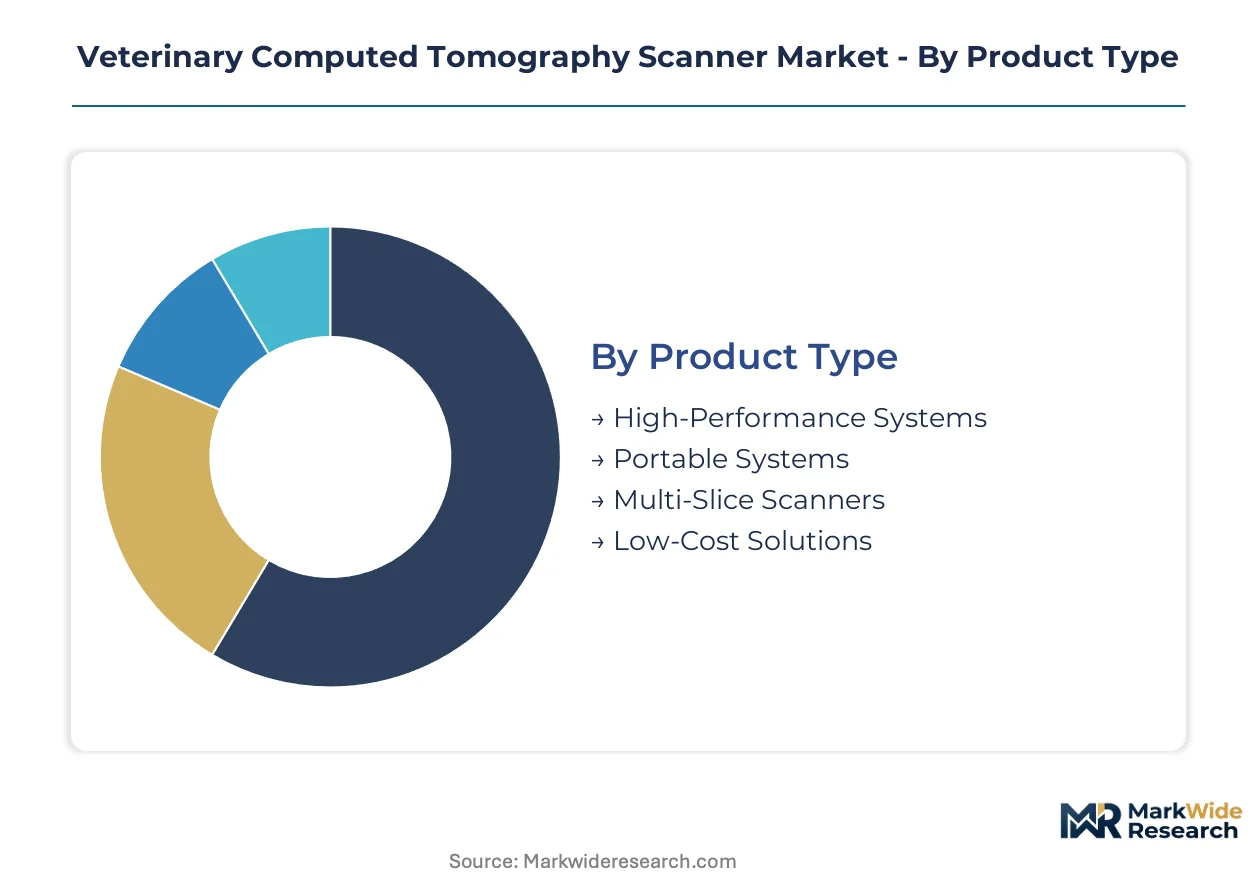
Veterinary CT scanner segmentation reflects divergent capital deployment strategies across practice types, from corporate consolidators seeking fleet standardization to independent clinics prioritizing point-of-care accessibility. Equipment manufacturers configure product lines around these procurement patterns, aligning technical specifications with distinct clinical workflows and species coverage requirements.
Product Type:
Capital intensity and throughput requirements separate buyers into distinct equipment tiers, with procurement authority concentrating differently across each segment.
- High-Performance Systems:These platforms deploy 64-slice or greater detector arrays with sub-millimeter isotropic resolution, engineered for tertiary referral hospitals performing complex oncologic staging and interventional planning. Demand concentrates in United States academic veterinary centers where NIH-funded research programs require advanced imaging capabilities for translational studies.
- Portable Systems:Mobile configurations mounted on wheeled gantries or truck-based platforms enable imaging at equine facilities and wildlife rehabilitation sites without patient transport. Kentucky equine practices and Florida racetrack veterinary services represent concentrated demand for cervical spine and distal limb evaluation capabilities.
- Multi-Slice Scanners:16-to-32 slice systems balance acquisition speed with capital cost for specialty hospitals performing routine whole-body protocols.
- Low-Cost Solutions:Refurbished human systems and single-slice architectures serve price-sensitive general practices in rural United States markets.
Volume sits with Multi-Slice Scanners; growth tilts toward Portable Systems.
End User:
Site-of-service economics and reimbursement structures shape equipment selection criteria across institutional categories.
- Veterinary Clinics:Independent and corporate-affiliated companion animal practices represent the broadest installed base, with procurement decisions increasingly centralized at regional headquarters for multi-site operators. California and Texas practice act modifications enabling teleradiology integration are accelerating subscription-based service contracting in this segment.
- Animal Hospitals:24-hour emergency and specialty referral centers command the highest equipment utilization rates and generate margin pools for premium multi-slice configurations. These institutions in metropolitan United States markets are expanding CT staging protocols for canine lymphoma and feline oral squamous cell carcinoma.
- Research Institutions:NIH and USDA-funded facilities require validated imaging biomarkers for preclinical toxicology studies.
- Academic Institutions:Veterinary teaching hospitals combine clinical service with residency training missions.
Procurement authority is concentrating at Animal Hospitals; expansion is climbing fastest in Veterinary Clinics.
Technology:
Radiation dose profiles and reconstruction algorithms differentiate technical approaches for species-specific applications.
- Cone Beam CT:Flat-panel detector architectures deliver focused field-of-view imaging at reduced radiation exposure, purpose-built for dental and maxillofacial applications in companion animal practice. German and Swiss manufacturers are pivoting production toward compact, clinic-deployable configurations suited for European suburban veterinary markets.
- Dual-Energy CT:Spectral imaging capabilities enable material decomposition for urolith characterization and gout diagnosis, with adoption concentrated in United States tertiary referral hospitals with board-certified radiologist staffing.
- CT Angiography:Contrast-enhanced vascular protocols require precise injection timing and cardiac gating for thoracic studies.
- 3D Imaging Technologies:Volume rendering and multiplanar reconstruction software packages extend diagnostic utility across all hardware platforms.
Installed base tilts toward 3D Imaging Technologies; steepest expansion trajectory belongs to Cone Beam CT.
Application:
Clinical indication drives protocol standardization and radiologist specialization requirements across practice networks.
- Oncology:Whole-body staging protocols for canine and feline neoplasia generate the highest scan volumes per installed system, with American College of Veterinary Radiology board-certified specialists interpreting thoracic and abdominal metastasis surveys. United States specialty hospitals are expanding CT-guided biopsy and radiation planning services in this indication.
- Orthopedics:Complex fracture assessment and pre-surgical planning for total hip replacement utilize high-resolution bone algorithm reconstructions. Equine practitioners in Kentucky and Florida are adopting mobile CT for distal limb evaluation where radiographic superimposition limits diagnostic confidence.
- Neurology:Brain and spinal cord imaging requires anesthesia protocols and specialized positioning devices for small patients.
- Internal Medicine:Thoracic and abdominal screening for non-neoplastic conditions represents routine utilization.
Scan volume concentrates in Oncology; neurology applications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity scintillator crystal production concentrates in Japan and Germany, anchoring detector supply chains for equipment manufacturers serving veterinary imaging markets worldwide.
United States
Specialty veterinary hospitals in metropolitan markets are expanding CT staging protocols for canine lymphoma and feline oral squamous cell carcinoma. The FDA Center for Veterinary Medicine oversees device classification pathways that shape premarket notification requirements for cross-species imaging claims. Kentucky and Florida equine practices are adopting mobile CT configurations for distal limb evaluation at racetrack facilities.
Germany
Siemens Healthineers leverages its human imaging heritage to anchor premium multi-slice veterinary systems across German and adjacent Swiss markets. The EU Medical Device Regulation creates precedent pressure for enhanced clinical evidence documentation among manufacturers distributing in European veterinary markets. Bavarian and Baden-Württemberg industrial clusters concentrate precision engineering capabilities for compact, clinic-deployable CT platforms.
Japan
Japanese specialty chemical suppliers dominate high-purity xenon detector scintillator crystal production, exposing equipment manufacturers to input cost volatility and single-source risk. METI industrial standards influence quality management benchmarks that propagate through international supply chains. Tokyo and Osaka metropolitan veterinary teaching hospitals combine clinical service with residency training missions for advanced imaging protocols.
United Kingdom
Corporate veterinary practice consolidators are negotiating fleet management agreements that bundle hardware, maintenance, and radiologist interpretation through single vendor relationships. The UK's departure from EU regulatory alignment has created parallel compliance pathways for imaging equipment approvals. Greater London and Southeast England specialty referral centers command the highest equipment utilization rates for premium multi-slice configurations.
Australia
Zoological and wildlife rehabilitation centers represent underpenetrated end-use verticals requiring specialized low-dose protocols and modified patient positioning systems. The TGA maintains veterinary medical device oversight that references human-equipment safety standards with species-specific adaptations. Queensland and New South Wales exotic animal practices are pioneering avian CT imaging applications for raptor rehabilitation and captive breeding programs.
Veterinary Computed Tomography Scanner Market Competitive Landscape
Global majors compete with regional champions across service network coverage and species-specific protocol validation. The market structure tilts toward consolidated procurement authority at corporate headquarters rather than individual clinic level, favoring suppliers with integrated hardware-maintenance-interpretation bundles. Three archetypes dominate: diversified imaging conglomerates with human-healthcare heritage, veterinary-focused equipment specialists, and compact-platform innovators targeting point-of-care deployment. Competitive moves concentrate on subscription-based service contracting and fleet standardization agreements with multi-site practice networks.
Within the diversified imaging tier, Siemens Healthineers and GE Healthcare exemplify global-scale competitors leveraging human-market R&D spillover into veterinary applications. Canon Medical Systems Corporation occupies a specialist position anchored in cone-beam architectures for dental and maxillofacial segments. Hallmarq Veterinary Imaging represents the pure-play veterinary archetype with species-focused engineering heritage. Xoran Technologies sits within the compact-platform innovation cluster targeting clinic-based deployment without dedicated shielded suites.
| Leading Market Players |
|---|
| Epica International |
| Neurologica Corporation |
| Siemens Healthineers |
| Xoran Technologies |
| Hallmarq Veterinary Imaging |
| GE Healthcare |
| Sound |
| Animage |
| Canon Medical Systems Corporation |
| Others |
Value Network & Pricing Analysis
Xenon detector scintillator crystal costs transmit downstream through three distinct equipment pricing tiers, with Japanese and German specialty chemical suppliers anchoring input pricing power that equipment manufacturers absorb through warranty bundling strategies.
Pricing Analysis
Warranty and service contract bundling separates premium multi-slice configurations from unbundled portable cone-beam alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects detector array density and ISO 13485 certification tier. Pricing pressure stems from refurbished human system availability in rural United States markets. Corporate consolidators exhibit lowest price sensitivity; independent clinics in suburban markets face highest capital constraint.
Supply Chain Analysis
Photoresist-grade scintillator crystal supply rests on Japanese and German specialty chemical producers, with xenon detector manufacturing concentrated in Japan, Germany, and the United States. High-purity crystal growth furnaces and precision-machined tungsten collimators constitute critical component dependencies. Single-source vulnerability in scintillator substrate supply exposes equipment assemblers to input cost volatility. Distribution runs through authorized dealer networks serving academic veterinary centers and corporate practice consolidators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA Center for Veterinary Medicine's cross-species imaging classification requirements create a cost-of-compliance moat that elevates barriers for undercapitalized entrants while rewarding established players with validated safety dossiers.
For Market Incumbents: Hedge against portable cone-beam substitution by securing exclusive service contracts with corporate consolidators. Backward integration into detector refurbishment capabilities insulates margin pools from Japanese scintillator supply shocks. Defensive patent positioning around iterative reconstruction algorithms for multi-slice platforms preserves premium tier pricing power.
For New Entrants and Emerging Players: California and Texas veterinary practice act modifications enabling teleradiology integration open a window for subscription-based hardware-interpretation bundles targeting independent clinics. Avian and exotic species imaging protocols represent the most penetrable white-space vertical. Go-to-market execution should prioritize zoological rehabilitation center pilot programs with species-specific positioning device co-development.
For Investors and Strategic Acquirers: Corporate consolidator fleet standardization announcements are the leading indicator that procurement authority concentration will accelerate. Long-term viability favors suppliers with integrated hardware-maintenance-interpretation capabilities. Acquisition targets should display robust ISO 13485 documentation and established service networks. Watch state radiation control program training mandate modifications as workforce availability inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Notification Pathway | Cross-species validation datasets satisfy FDA Center for Veterinary Medicine software-as-a-device claims. |
| ISO 13485 Certification Investment | Harmonized quality management accelerates multi-jurisdiction regulatory clearance timelines. |
| Corporate Practice Fleet Agreement | Regional headquarters procurement authority favors integrated service network suppliers. |
| Cone-Beam Platform Miniaturization | Compact clinic-deployable configurations capture suburban independent practice demand. |
| Teleradiology Service Integration | State practice act modifications enable remote interpretation subscription bundling. |
Research Methodology
Independent corroboration across equipment manufacturer sales executives, veterinary radiology residency program directors, and corporate practice procurement officers underwrites the qualitative findings. Secondary validation draws from FDA Center for Veterinary Medicine device classification databases, USDA Animal and Plant Health Inspection Service radiation safety protocols, and ISO 13485 certification registries. Bottom-up installed base enumeration triangulates against top-down addressable market sizing.
Rate-of-change decomposition across the projection horizon segments volume and value by product type, end user institution category, technology architecture, and clinical application indication. CAGRs derive from equipment replacement cycle analysis and specialty hospital expansion trajectories. Modeled inputs incorporate NIH-funded research program imaging biomarker requirements and state-level veterinary telemedicine regulatory evolution.
The model assumes a particular technology adoption path; alternative pathways for machine learning-enhanced iterative reconstruction would alter the outlook. Forecasts reflect documented assumptions regarding specialty hospital referral volume growth and corporate consolidation pace. Regulatory delay in FDA software-as-device guidance and scintillator supply disruption represent primary revision triggers. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Specialty PACS Market
Medical Imaging
Breast MRI Screening Market
Medical Imaging
Japan Magnetic Resonance Imaging Market
Medical Imaging
Cephalometric X-Ray System Market
Medical Imaging
Global Image-Guided Radiation Therapy (IGRT) Market
Medical Imaging
Digital X-Ray Imaging Market
Medical Imaging
Handheld Dental X-Ray Systems Market
Medical Imaging
3D Imaging Surgical Solution Market
Medical Imaging
Image Guided Radiotherapy Market
Medical Imaging
Orthopedic Radiology Equipment Market
Medical Imaging
United States Diagnostic Imaging Market
Medical Imaging
Meningitis Imaging Market
Medical Imaging
Global Contrast Enhanced Digital Mammography (CEDM) Market
Medical Imaging
Spain Computed Tomography Market
Medical Imaging
United Kingdom Computed Tomography Market
Medical Imaging
Italy Mammography Market