
 Italy Computed Tomography Market | 2026-2036
Italy Computed Tomography Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Computed Tomography Market Foresight
The EU Green Deal's healthcare decarbonization targets are expanding procurement criteria for energy-efficient imaging equipment across Italian public health systems. Siemens Healthineers leverages its Munich-based R&D pipeline to sustain technology leadership in dual-energy CT platforms. GE Healthcare Technologies anchors its Italian position through localized service networks and refurbished equipment channels. Koninklijke Philips competes on spectral-detector architectures that reduce dose exposure per examination.
Computed tomography is a diagnostic imaging modality that reconstructs cross-sectional anatomical images from multiple X-ray projections acquired at successive angles around a patient, with modern systems employing scintillation crystal arrays and photon-counting detectors to achieve sub-millimeter spatial resolution. Its primary purpose is non-invasive visualization of soft tissue, bone, and vascular structures for disease detection, treatment planning, and interventional guidance. CT scanners remain the dominant product category in Italy's installed base, though mobile CT units are gaining traction for emergency deployment and rural access expansion. Multi-slice CT technology leads hospital procurement specifications, while dual-energy CT represents the fastest-growing technology segment as radiology departments pursue material decomposition capabilities for enhanced lesion characterization.
Italy's national pharmaceutical regulator, the Agenzia Italiana del Farmaco, enforces EU MDR compliance timelines that accelerate replacement of legacy CT systems lacking updated technical documentation. The Istituto Superiore di Sanità coordinates radiation safety protocols that shape dose optimization requirements across public and private imaging facilities. Stakeholders must monitor regional health authority budget allocations and EU cohesion fund disbursements to anticipate equipment procurement waves.
Market Dynamics
Italy's CT market is restructuring around the EU Medical Device Regulation's conformity assessment deadlines, which are forcing radiology departments to retire legacy scanners lacking updated technical documentation before the enforcement window closes.
Growth Catalysts
- Oncology imaging demand:Italian hospital networks are compressing replacement cycles for multi-slice CT systems to support precision radiotherapy planning and immunotherapy response monitoring.
- EU Green Deal procurement criteria:Energy-efficient imaging equipment specifications are expanding across Lombardy and Emilia-Romagna public health clusters, directing capital toward low-dose dual-energy platforms.
- Photon-counting detector maturation:Sub-millimeter spatial resolution capabilities are enabling material decomposition for enhanced lesion characterization in cardiovascular and pulmonary departments.
Market Restraints
- Helium supply concentration:Superconducting magnet cooling depends on concentrated Middle Eastern and North American helium extraction, exposing Italian operators to price volatility and allocation disruptions.
- EU MDR technical documentation gaps:Legacy CT systems installed before 2017 lack the clinical evidence packages required for renewed CE marking, accelerating functional obsolescence.
- Interventional radiology substitution:MRI-guided biopsy and contrast-enhanced ultrasound are displacing low-acuity CT examinations in abdominal and pelvic imaging protocols.
Strategic Opportunities
- Southern Italy access expansion:Calabria, Sicily, and Basilicata maintain CT scanner density below half the northern regional average, creating deployment white space for mobile and fixed systems.
- AI-integrated reconstruction:Deep learning-based noise reduction algorithms are converging with photon-counting hardware to enable diagnostic-quality imaging at sub-mSv dose levels.
- EU cohesion fund disbursements:Recovery and Resilience Facility allocations for health infrastructure modernization are creating concentrated procurement windows through 2026.
Industry Challenges
- Radiation physicist staffing:The Istituto Superiore di Sanità's dose optimization protocols require specialized personnel that Italian training programs are not producing at replacement rates.
- Legacy PACS integration:New spectral-detector architectures face interoperability friction with hospital information systems running on decade-old DICOM implementations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Computed Tomography Market |
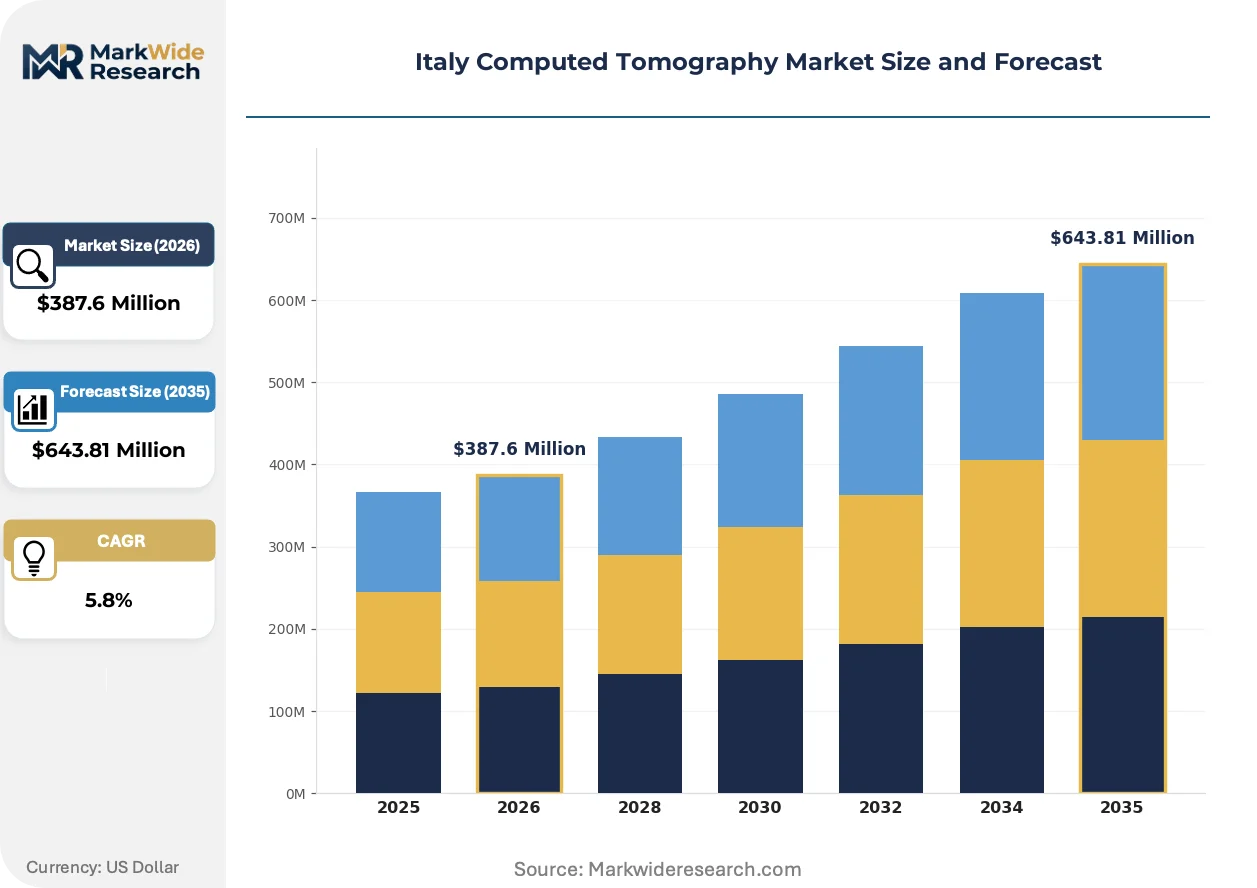
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CT Scanners, Mobile CT, Cone Beam CT, High-Resolution CT End User: Hospitals, Diagnostic Centers, Research Institutions, Outpatient Clinics Technology: Multi-Slice CT, Helical CT, 3D Imaging, Dual-Energy CT Application: Oncology, Neurology, Cardiology, Trauma Care |
| Companies Covered | GE Healthcare Technologies, Siemens Healthineers, Koninklijke Philips, Canon Medical Systems Corporation, FUJIFILM Holdings Corporation, Carestream Health, Hitachi Medical Corporation, Agfa-Gevaert Group, Shimadzu Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Computed Tomography Market Shifts & Advancements
Artificial intelligence is embedding across the CT value chain, compressing reconstruction times and enabling point-of-care decision support while regulatory frameworks struggle to keep pace with validation requirements.
Photon-counting CT is automating material decomposition workflows that previously required dual-energy acquisition protocols. Radiology departments at Policlinico Gemelli and Ospedale Maggiore are piloting these systems for coronary plaque characterization. The technology is automating calcium suppression and iodine mapping, reducing per-examination interpretation time by eliminating manual dual-energy post-processing steps.
The EU Medical Device Regulation's Article 120 transition timelines are compressing conformity assessment pathways for CT equipment with software-as-medical-device components. Notified bodies in Germany and the Netherlands are developing streamlined review processes for AI-enabled reconstruction algorithms. Northern Italian hospital procurement offices are prioritizing vendors with completed MDR certification to avoid supply interruption risk.
Service unbundling is separating hardware maintenance from software update subscriptions across Italian public health networks. Regional health authorities in Veneto and Tuscany are negotiating outcome-based equipment utilization contracts that tie payment to scanner uptime and dose efficiency metrics. Private diagnostic chains are responding by internalizing first-line service capabilities and purchasing parts-only support from manufacturers.
Italy Computed Tomography Market Segmentation
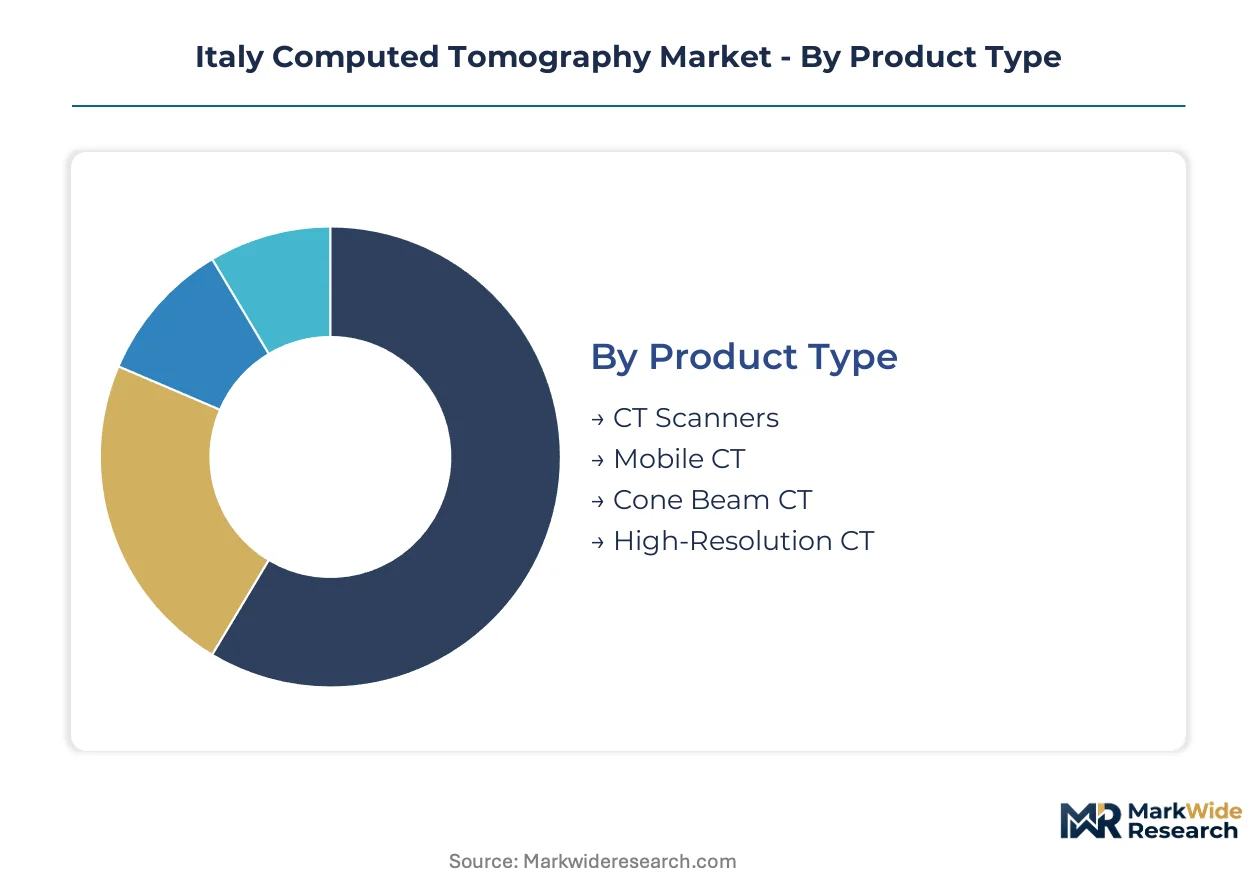
Italian CT procurement patterns diverge sharply between public hospital networks and private diagnostic chains, with technology selection driven by EU MDR certification timelines and regional budget cycles. Segmentation reveals where capital concentrates and which modalities face replacement pressure.
Product Type:
EU MDR conformity assessment burdens fall heaviest on stationary CT scanners requiring full technical documentation renewal, while mobile CT units navigate lighter regulatory pathways through temporary deployment exemptions.
- CT Scanners:Fixed-installation systems with gantry-mounted X-ray tubes and detector arrays rotating at sub-second speeds. Lombardy and Emilia-Romagna public health clusters are compressing replacement cycles for multi-slice platforms to meet EU MDR deadlines. Leading the category by volume: CT Scanners. Growing fastest: Mobile CT.
- Mobile CT:Truck-mounted or trailer-based systems with self-contained power and climate control for emergency deployment. Calabria and Sicily regional authorities are expanding mobile fleets to address scanner density gaps below half the northern average.
- Cone Beam CT:Flat-panel detector systems optimized for maxillofacial and dental imaging with reduced radiation dose profiles. Italian private dental chains are adopting these for implant planning and orthodontic assessment.
- High-Resolution CT:Sub-millimeter slice thickness systems targeting interstitial lung disease and small-airway pathology. Pulmonology departments at Policlinico Gemelli are piloting these for early fibrosis detection protocols.
Stationary CT scanners dominate installed base value. Mobile CT is expanding most quickly through southern regional access programs.
End User:
Cost tier stratification separates capital-intensive hospital procurement from diagnostic center leasing models, with research institutions occupying a narrow premium niche.
- Hospitals:Comprehensive imaging departments with 24/7 emergency coverage and interventional capabilities. Northern Italian hospital networks are accelerating dual-energy CT adoption for precision oncology workflows. Leading the category by volume: Hospitals. Gaining share fastest: Diagnostic Centers.
- Diagnostic Centers:Outpatient-focused facilities with high throughput and specialized service lines. Private chains in Veneto and Tuscany are internalizing service capabilities to negotiate outcome-based utilization contracts.
- Research Institutions:Academic medical centers with protocol development and clinical trial imaging mandates. Ospedale Maggiore and Policlinico Gemelli are piloting photon-counting systems for coronary plaque characterization studies.
- Outpatient Clinics:Limited-service facilities performing low-complexity examinations with referral relationships to hospital networks. These clinics face margin pressure from MRI and ultrasound substitution in abdominal imaging.
Public hospitals anchor equipment value. Private diagnostic centers are climbing the fastest as service unbundling spreads.
Technology:
Application maturity curves separate established multi-slice platforms from emerging spectral architectures, with helical CT occupying a transitional cost-performance position.
- Multi-Slice CT:Detector arrays with 64 to 320 simultaneous slice acquisition enabling cardiac and vascular imaging. These systems form the procurement baseline across Italian regional health authority tenders. Leading the category by volume: Multi-Slice CT. Steepest expansion trajectory: Dual-Energy CT.
- Helical CT:Continuous patient translation during gantry rotation for volumetric acquisition. These systems are approaching functional obsolescence as EU MDR documentation gaps force retirement of pre-2017 installations.
- 3D Imaging:Isotropic voxel reconstruction enabling multiplanar reformatting and volume rendering. Radiology departments are integrating these capabilities with AI-based noise reduction for sub-mSv dose protocols.
- Dual-Energy CT:Spectral acquisition at two distinct tube voltages for material decomposition and iodine mapping. EU Green Deal procurement criteria in Lombardy are directing capital toward these low-dose platforms.
Multi-slice CT commands installed base share. Dual-energy platforms are gaining share fastest through material decomposition demand.
Application:
Customer type differentiation separates high-acuity trauma networks from scheduled oncology workflows, with cardiology representing a technology-upgrade pivot point.
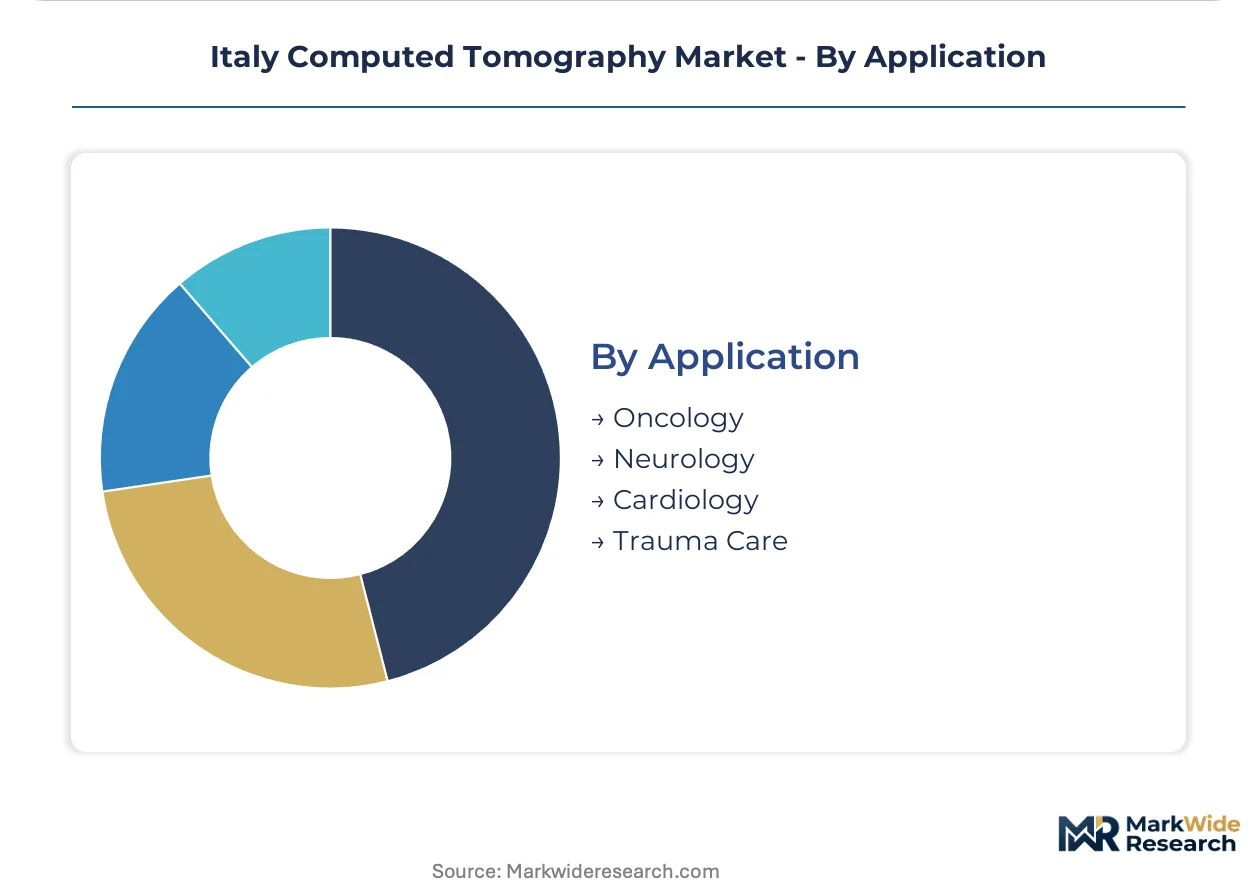
- Oncology:Staging, treatment planning, and response assessment for solid tumors and hematologic malignancies. Italian hospital networks are prioritizing spectral-detector architectures for immunotherapy monitoring protocols. Leading the category by volume: Oncology. Fastest volume growth: Cardiology.
- Neurology:Stroke imaging, dementia workup, and neurosurgical planning with perfusion and spectroscopy extensions. The Istituto Superiore di Sanità's dose protocols are driving demand for photon-counting detectors in repeat-examination populations.
- Cardiology:Coronary calcium scoring, angiography, and structural heart intervention planning. Policlinico Gemelli's pilot programs are validating photon-counting CT for plaque characterization against invasive catheterization.
- Trauma Care:Whole-body scanning for polytrauma with rapid reconstruction for emergency surgical decision-making. Mobile CT units are penetrating this segment for field deployment and rural access expansion.
Oncology anchors departmental revenue. Cardiology applications are expanding most quickly through coronary imaging technology advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Milan anchors Italy's CT scanner procurement activity through the Lombardy regional health cluster, where public hospital networks maintain the densest installed base and fastest replacement cycles.
Lombardy
Oncology departments at Policlinico di Milano and IRCCS Istituto Nazionale dei Tumori are compressing replacement cycles for dual-energy CT systems to support precision radiotherapy planning. The EU Green Deal's healthcare decarbonization targets are expanding procurement criteria for energy-efficient imaging equipment across the regional health authority. Milan's metropolitan hospital network is piloting photon-counting detector systems for coronary plaque characterization studies.
Emilia-Romagna
Public health clusters in Bologna and Modena are directing capital toward low-dose spectral-detector platforms under EU Green Deal procurement specifications. The Agenzia Italiana del Farmaco enforces EU MDR compliance timelines that accelerate retirement of legacy helical CT systems lacking updated technical documentation. Bologna's university hospital network is validating AI-integrated reconstruction algorithms for sub-mSv dose protocols.
Veneto
Regional health authorities in Padua and Verona are negotiating outcome-based equipment utilization contracts that tie payment to scanner uptime and dose efficiency metrics. The Istituto Superiore di Sanità coordinates radiation safety protocols that shape dose optimization requirements across public and private imaging facilities. Private diagnostic chains in the Veneto region are internalizing first-line service capabilities and purchasing parts-only support from manufacturers.
Lazio
Rome's Policlinico Gemelli is piloting photon-counting CT systems for coronary plaque characterization against invasive catheterization benchmarks. The EU Medical Device Regulation's Article 120 transition timelines are compressing conformity assessment pathways for CT equipment with software-as-medical-device components. Research institutions in the capital are developing streamlined review processes for AI-enabled reconstruction algorithms.
Southern Regions
Calabria, Sicily, and Basilicata maintain CT scanner density below half the northern regional average, creating deployment white space for mobile and fixed systems. EU cohesion fund disbursements through the Recovery and Resilience Facility are creating concentrated procurement windows for health infrastructure modernization through 2026. Regional authorities are expanding mobile CT fleets to address rural access gaps and emergency deployment requirements.
Italy Computed Tomography Market Competitive Landscape
The competitive structure tilts toward diversified health technology conglomerates with integrated imaging portfolios. Siemens Healthineers leverages its Munich-based R&D pipeline to sustain technology leadership in dual-energy CT platforms. GE Healthcare Technologies anchors its Italian position through localized service networks and refurbished equipment channels. Koninklijke Philips competes on spectral-detector architectures that reduce dose exposure per examination. The market recognizes three strategic archetypes: German-engineered precision platforms, American service-anchored distribution models, and Dutch spectral-detector specialists. Dominant competitive moves include service unbundling that separates hardware maintenance from software subscriptions, and outcome-based contracting that ties vendor payment to equipment utilization metrics.
Among diversified health technology conglomerates, Siemens Healthineers, GE Healthcare Technologies, and Koninklijke Philips exemplify the three prevailing competitive models. Siemens Healthineers represents the German-engineered precision archetype with dual-energy CT platforms. GE Healthcare Technologies occupies the service-anchored distribution position through localized networks and refurbished channels. Koninklijke Philips anchors the spectral-detector specialization vector with dose-reduction architectures. Each conglomerate structures its Italian presence around distinct value chain control points rather than homogeneous product competition.
| Leading Market Players |
|---|
| GE Healthcare Technologies |
| Siemens Healthineers |
| Koninklijke Philips |
| Canon Medical Systems Corporation |
| FUJIFILM Holdings Corporation |
| Carestream Health |
| Hitachi Medical Corporation |
| Agfa-Gevaert Group |
| Shimadzu Corporation |
| Others |
Supply & Pricing Matrix
Captive service networks anchor pricing power for CT equipment manufacturers serving Italian hospital networks. Siemens Healthineers, GE Healthcare Technologies, and Koninklijke Philips leverage vertically integrated maintenance operations to sustain premium positioning against refurbished equipment channels and third-party service providers.
Pricing Analysis
Outcome-based pricing anchors vendor contracts across Lombardy and Emilia-Romagna public health clusters. Regional health authorities negotiate payment tied to scanner uptime percentages and dose efficiency metrics rather than capital expenditure alone. Price differentiation separates MDR-certified spectral-detector platforms from legacy multi-slice systems facing accelerated obsolescence. Cost compression in the refurbished equipment tier intensifies as GE Healthcare Technologies expands localized reconditioning facilities. Private diagnostic chains exhibit highest price sensitivity due to leasing model margins, while research institutions at Policlinico Gemelli demonstrate lowest sensitivity for photon-counting pilot programs.
Supply Chain Analysis
Single-source vulnerability sits with Middle Eastern and North American helium extraction operations feeding superconducting magnet cooling requirements. German-engineered precision components and Dutch spectral-detector arrays draw from concentrated European manufacturing bases, while scintillation crystal production rests on Japanese and Chinese material processing. Tariff exposure runs through EU medical device import classifications affecting Asian-origin detector subassemblies. Distribution runs through manufacturer-direct service organizations and authorized third-party imaging equipment specialists serving regional health authority procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Italy CT market represents a consolidation play as EU MDR certification deadlines force retirement of legacy systems lacking updated technical documentation, eliminating marginal competitors unable to fund conformity assessment pathways.
For Market Incumbents: Deepen backward integration into photon-counting detector manufacturing to secure supply continuity against Asian component volatility. Expand AI-integrated reconstruction software subscriptions to capture recurring revenue streams as hardware margins compress. Prioritize MDR certification completion for dual-energy platforms before Article 120 transition timelines close, locking out uncertified rivals from northern Italian procurement tenders. For New Entrants and Emerging Players: Begin with mobile CT deployment across Calabria, Sicily, and Basilicata where scanner density sits below half the northern regional average. Target EU cohesion fund disbursement windows through Recovery and Resilience Facility allocations for health infrastructure modernization. Pursue outcome-based contracting models that align payment with equipment utilization metrics, bypassing capital-intensive fixed-installation competition. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified health technology conglomerates seeking Italian service network expansion. Long-term viability favors targets with completed MDR certification and established relationships with regional health authority procurement offices. Watch EU cohesion fund disbursement velocity as the inflection indicator for southern regional equipment procurement waves.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certification Completion | EU Medical Device Regulation deadlines lock uncertified competitors out of public hospital tenders across Lombardy and Emilia-Romagna. |
| AI-Integrated Reconstruction Development | Deep learning noise reduction algorithms enable diagnostic-quality imaging at sub-mSv dose levels demanded by Istituto Superiore di Sanità protocols. |
| Mobile CT Fleet Expansion | Calabria and Sicily regional authorities address scanner density gaps below half the northern average through emergency deployment vehicles. |
| Outcome-Based Contracting Adoption | Veneto and Tuscany health authorities tie vendor payment to scanner uptime percentages and dose efficiency metrics. |
| Photon-Counting Detector Pilot Programs | Policlinico Gemelli and Ospedale Maggiore validate coronary plaque characterization against invasive catheterization benchmarks. |
Research Methodology
Document review covered EU Medical Device Regulation implementation guidance, Agenzia Italiana del Farmaco compliance timelines, and Recovery and Resilience Facility disbursement records, complemented by interviews with radiology department heads, biomedical engineers, regional health authority procurement managers, and GPO contracts specialists. Secondary validation drew from hospital procurement databases, notified body certification registries, Istituto Superiore di Sanità radiation safety protocols, and EU cohesion fund tracking systems. Bottom-up equipment installation data triangulated against top-down regional health expenditure flows.
Cross-referencing historical replacement cycle patterns with expert panel input on EU MDR transition timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user category, technology architecture, and clinical application area, with regional budget cycle phasing as an Italy-specific overlay. CAGRs derived from equipment procurement velocity curves weighted by MDR-driven replacement acceleration. Forecast inputs incorporated helium supply volatility indices and AI reconstruction algorithm regulatory validation timelines.
Underlying measurement precision varies by segment; stationary CT scanner replacement flows carry tighter precision than mobile deployment trajectories dependent on cohesion fund allocation timing. Forecasts reflect documented assumptions regarding EU MDR enforcement rigor and regional health authority budget continuity. Deviation in Recovery and Resilience Facility disbursement schedules or notified body certification backlogs would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Medical Imaging Informatics Market
Medical Imaging
Cryo-Electron Microscopy Market
Medical Imaging
Molecular Breast Imaging Market
Medical Imaging
Digital Radiology Market
Medical Imaging
Dental Digital X Ray Market
Medical Imaging
North America Digital X-Ray Market
Medical Imaging
Teleultrasound System Market
Medical Imaging
China Digital Radiology Market
Medical Imaging
Digital Pathology Market
Medical Imaging
Australia Digital Radiology Market
Medical Imaging
Global Medical Imaging Phantoms Market
Medical Imaging
United States Diagnostic Imaging Market
Medical Imaging
AI Capsule Endoscopy Reading Platform Market
Medical Imaging
Handheld Ultrasound Scanners Market
Medical Imaging
Medical X-Ray Equipment and Imaging Software Market
Medical Imaging
Non-Invasive & Minimally Invasive Medical Imaging and Visualization Systems Market