
 Weightbearing Low Dose (CT) Systems Market | 2026-2036
Weightbearing Low Dose (CT) Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Weightbearing Low Dose (CT) Systems Market Analytics
Equipment leasing and pay-per-scan service models is tilting competitive dynamics toward asset-light entrants. CurveBeam leverages its dedicated extremity CT focus to sustain premium positioning in orthopedic workflows. Siemens Healthineers anchors its presence through integrated hospital system contracts and broad service networks. Planmeca Group differentiates via vertical control over imaging software and hardware manufacturing.
Weightbearing Low Dose CT Systems employ cone-beam acquisition geometry with sub-millisievert dose protocols to capture three-dimensional bone and joint architecture under physiological load conditions. The technology serves primarily to detect occult fractures, monitor arthritic progression, and plan reconstructive procedures without supine positioning artifacts. Low-Dose CT product configurations command the strongest volume momentum as radiation safety benchmarks tighten across installed bases. Orthopedic Applications concentrate the deepest margin pools due to procedure-specific reimbursement and repeat scanning protocols for surgical planning. Artificial Intelligence technology integration is expanding fastest among technology segments as automated segmentation reduces radiologist interpretation time.
FDA 510(k) clearance requirements and ALARA dose principles govern device commercialization and clinical deployment in the United States. The EU MDR framework and CE marking obligations shape European market access with intensified post-market surveillance demands. Stakeholders must monitor evolving reimbursement codes for weightbearing extremity imaging as payer coverage decisions will determine site-level capital commitment thresholds.
Market Dynamics
The convergence of ALARA dose mandates with orthopedic demand for physiological-load imaging is compressing equipment replacement cycles and tilting procurement toward low-dose cone-beam platforms.
Growth Catalysts
- FDA 510(k) pathway compression:Streamlined clearance for predicate-equivalent low-dose devices accelerates manufacturer time-to-revenue. Orthopedic clinics capture earlier access to weightbearing extremity diagnostics.
- Repeat-scan protocols:Arthritic progression monitoring and pre-operative planning require serial imaging without cumulative radiation exposure. Low-dose CT satisfies this clinical need.
- Artificial Intelligence integration:Automated bone segmentation reduces radiologist interpretation burden. Hospital radiology departments expand deployment of AI-enhanced extremity systems.
Market Restraints
- Detector crystal supply concentration:Cesium iodide and cadmium telluride substrates concentrate among Asian material processors. Equipment manufacturers face input cost volatility and single-source risk.
- Reimbursement code fragmentation:CMS and private payers maintain inconsistent coverage for weightbearing extremity CPT codes. Capital commitment thresholds vary unpredictably across US metropolitan markets.
- Conventional CT substitution:Supine multi-detector systems with iterative dose reduction algorithms compete for orthopedic referrals. Price-sensitive hospital systems delay dedicated extremity purchases.
Strategic Opportunities
- Podiatric and sports medicine expansion:Ankle and foot imaging under load remains underpenetrated outside academic medical centers. Outpatient surgery centers represent greenfield installation targets.
- Pay-per-scan service models:Asset-light entrants bypass capital-intensive direct sales. Orthopedic group practices convert fixed equipment costs to variable per-procedure expenses.
- EU MDR post-market surveillance data:Real-world radiation exposure registries under intensified vigilance requirements differentiate compliant manufacturers. CE-marked systems with documented dose tracking command preference.
Industry Challenges
- Cross-functional talent scarcity:Clinical applications specialists must bridge cone-beam physics, orthopedic biomechanics, and PACS integration. Training pipelines for this hybrid profile remain thin.
- Legacy PACS interoperability:Weightbearing DICOM datasets with non-standard acquisition geometries require middleware adaptation. Hospital IT departments resist workflow disruption.
- Site planning complexity:Structural load requirements for upright positioning systems exceed conventional CT room specifications. Renovation timelines extend sales-to-installation intervals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Weightbearing Low Dose (CT) Systems Market |
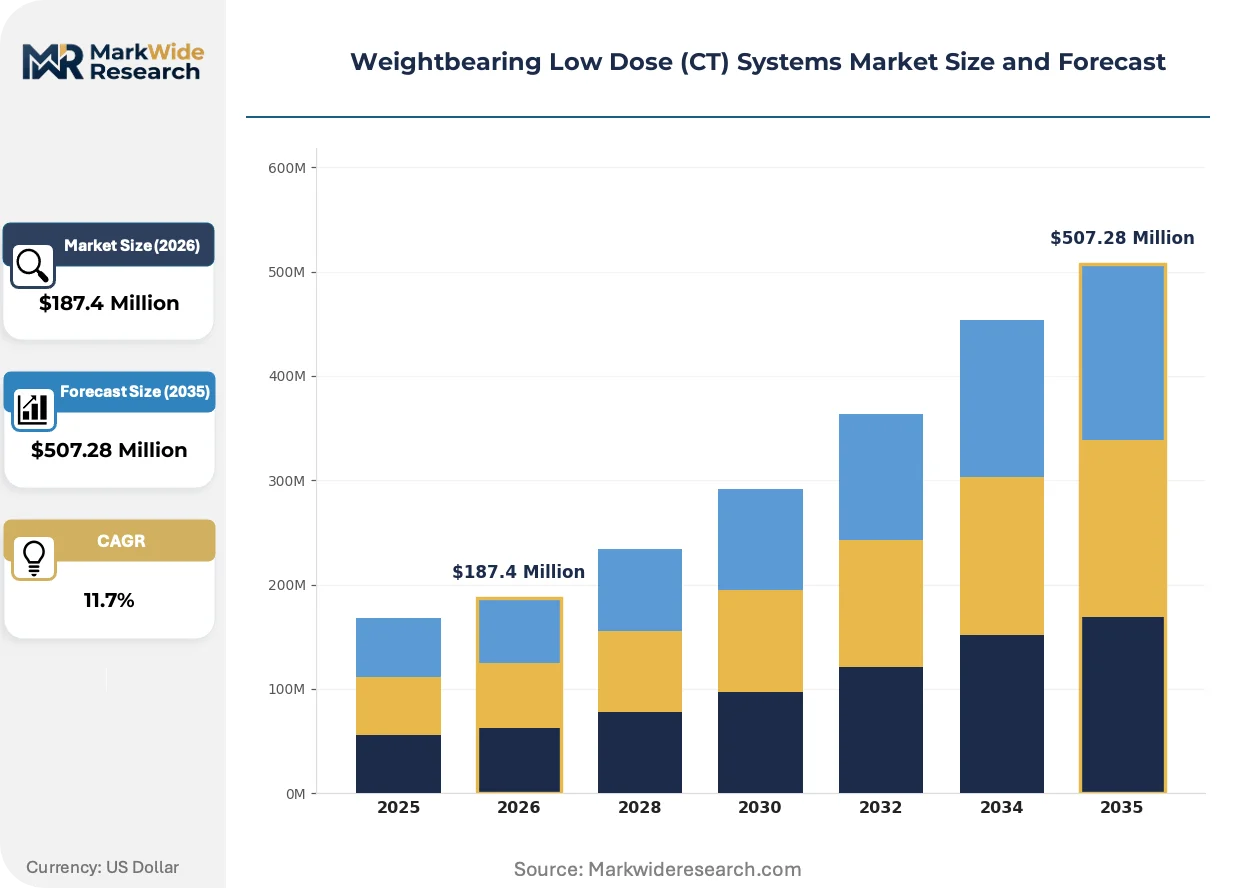
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional CT, Low-Dose CT, Digital X-Ray, Dual-Energy CT End User: Hospitals, Diagnostic Centers, Research Institutions, Orthopedic Clinics Technology: 3D Imaging, Image Reconstruction, Artificial Intelligence, Smart Sensors Application: Orthopedics, Oncology, Pain Management, Sports Medicine |
| Companies Covered | Planmeca Group, CurveBeam, EOS Imaging, Carestream Health, Planmed Oy, NeuroLogica, Xoran Technologies, Siemens Healthineers, Alphatec Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Weightbearing Low Dose (CT) Systems Market Evolving Landscape
Photon-counting detector layers and iterative reconstruction algorithms are collapsing the dose-resolution tradeoff that historically constrained orthopedic adoption of weightbearing CT platforms.
Flat-panel photon-counting detectors with cadmium zinc telluride substrates are collapsing the signal-to-noise gap between cone-beam extremity systems and conventional multi-detector CT. Academic orthopedic departments in Germany and the United States pilot these substrates for sub-millisievert foot and ankle protocols. The technology is collapsing manufacturer R&D roadmaps toward single-platform dose leadership rather than feature differentiation.
The EU MDR's intensified post-market clinical follow-up obligations are forcing manufacturers to embed real-time dose monitoring and automated exposure logging as standard firmware. European notified bodies now require periodic safety update reports with patient-level radiation metrics. Low-dose extremity CT systems with native dose tracking architecture secure faster CE certificate renewals and hospital tender advantages.
Orthopedic group purchasing organizations are consolidating procurement authority across independent clinics and ambulatory surgery centers. Aggregated volume commitments displace individual site capital budgets as the primary purchase mechanism. This concentration is most visible in the southeastern and southwestern United States, where super-regional orthopedic networks negotiate multi-year equipment leases with embedded service tiers.
Weightbearing Low Dose (CT) Systems Market Segmentation
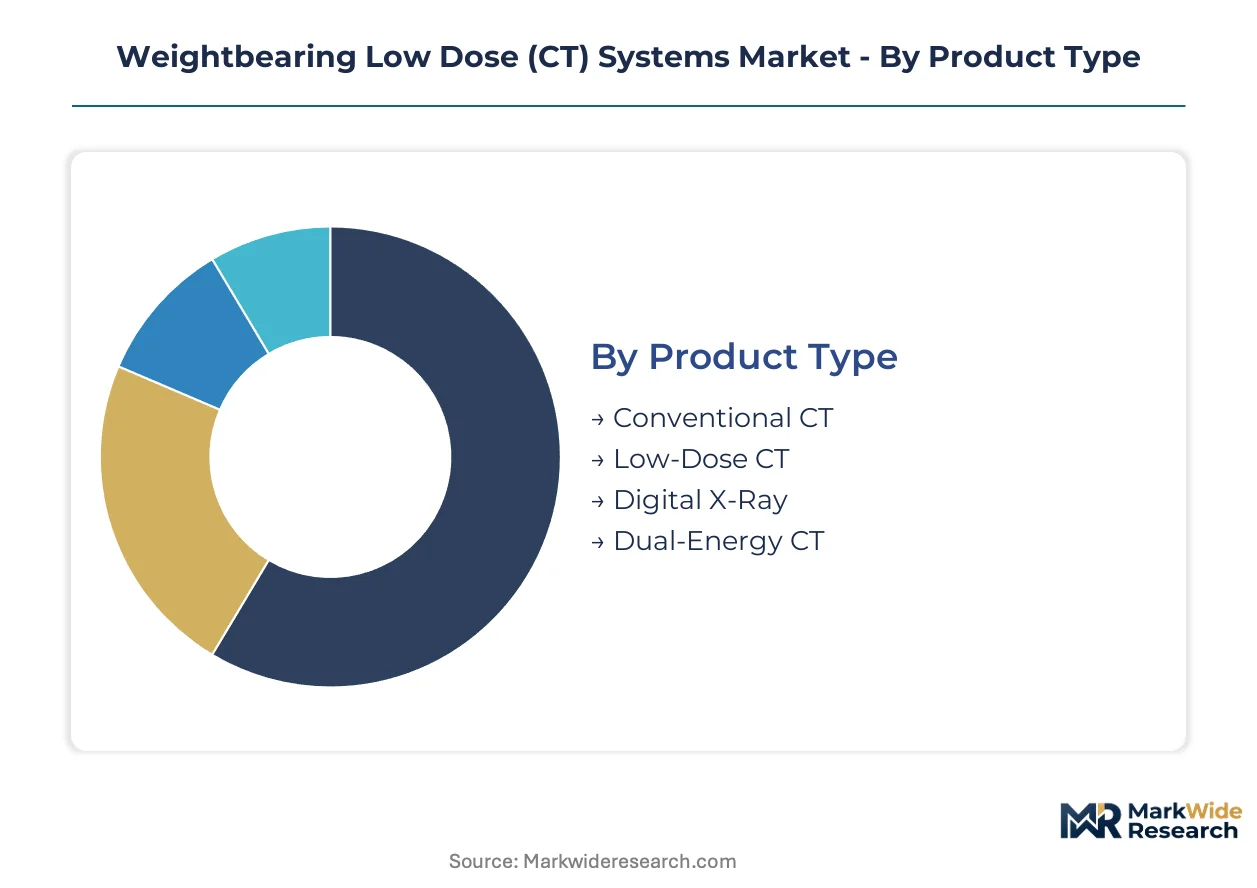
Segmentation in weightbearing extremity imaging reveals how dose reduction priorities, clinical workflow integration, and reimbursement pathways fragment procurement decisions across care settings. Manufacturers must align platform specifications with distinct capital commitment thresholds and repeat-scan protocols.
Product Type:
Mature hospital-installed bases still carry conventional CT footprints, though replacement cycles now favor emerging low-dose cone-beam architectures.
- Low-Dose CT:Sub-millisievert acquisition protocols using cone-beam geometry capture three-dimensional bone architecture under physiological load. Orthopedic clinics in the United States concentrate procurement here as ALARA mandates tighten and repeat-scan arthritic monitoring expands.
- Conventional CT:Supine multi-detector systems with iterative reconstruction algorithms retain installed base dominance in general radiology departments. Price-sensitive hospital systems delay dedicated extremity purchases where these platforms satisfy intermittent orthopedic referrals.
- Digital X-Ray:Two-dimensional weightbearing radiography serves initial fracture screening and post-operative alignment checks at lower capital cost.
- Dual-Energy CT:Spectral imaging capabilities enable gout crystal characterization and bone marrow edema detection in academic medical centers.
Low-Dose CT handles the majority of throughput; Dual-Energy CT is gaining share fastest among replacement decisions.
End User:
Customer type determines whether procurement flows through centralized hospital capital committees or decentralized clinic operating budgets.
- Orthopedic Clinics:Specialized extremity practices drive dedicated cone-beam adoption for pre-operative planning and post-operative monitoring. Southeastern and southwestern United States super-regional networks negotiate multi-year equipment leases with embedded service tiers.
- Hospitals:Integrated health systems anchor volume through broad radiology department contracts and PACS infrastructure. Siemens Healthineers secures presence via these system-wide agreements.
- Diagnostic Centers:Independent imaging facilities balance throughput requirements against reimbursement uncertainty for weightbearing extremity CPT codes.
- Research Institutions:Academic orthopedic departments pilot photon-counting cadmium zinc telluride substrates for sub-millisievert foot and ankle protocols.
Hospitals retain the deepest installed base; Orthopedic Clinics are expanding most quickly as independent practices consolidate.
Technology:
Software and sensor layers now differentiate hardware platforms more than gantry mechanics or tube specifications.
- Artificial Intelligence:Automated bone segmentation algorithms collapse radiologist interpretation time for complex hindfoot reconstructions. Hospital radiology departments expand deployment of AI-enhanced extremity systems to manage throughput pressure.
- Image Reconstruction:Iterative algorithms and deep learning denoising recover diagnostic quality from ultra-low-dose raw data.
- 3D Imaging:Volumetric rendering capabilities enable surgical planning with patient-specific anatomical models.
- Smart Sensors:Real-time dose monitoring and automated exposure logging satisfy EU MDR post-market surveillance obligations.
Image Reconstruction underpins every platform; Artificial Intelligence is climbing the fastest as FDA 510(k) pathways compress for predicate-equivalent algorithms.
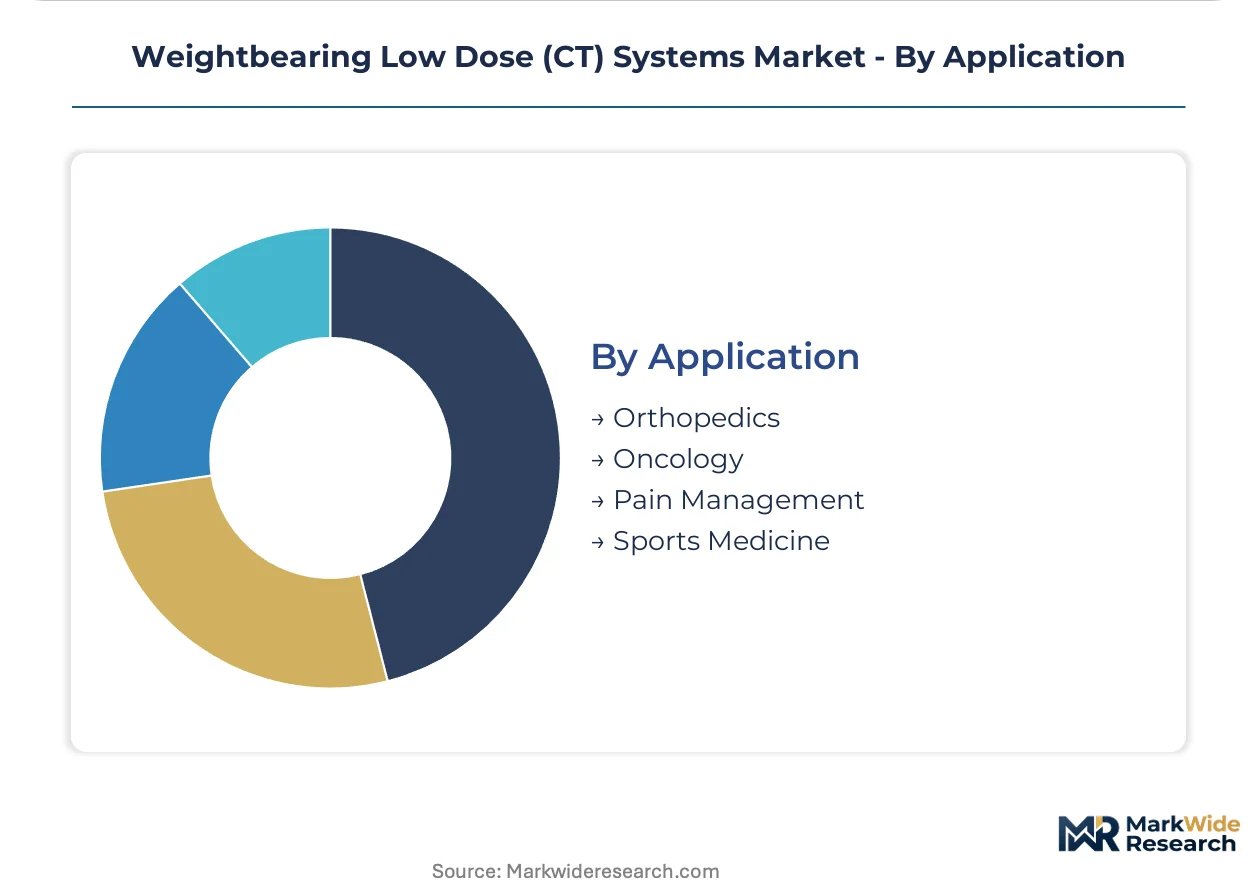
Application:
Procedure-specific reimbursement and repeat scanning frequency determine margin pool depth across clinical domains.
- Orthopedics:Arthritic progression monitoring and reconstructive surgical planning require serial imaging without cumulative radiation exposure. This concentration supports premium pricing for dedicated extremity platforms.
- Sports Medicine:Ankle and foot imaging under load remains underpenetrated outside academic medical centers. Outpatient surgery centers represent greenfield installation targets for pay-per-scan service models.
- Oncology:Metastatic bone disease staging occasionally leverages weightbearing protocols for lower extremity load-bearing assessment.
- Pain Management:Chronic foot and ankle pain evaluations drive diagnostic utilization in podiatric practices.
Orthopedics commands the deepest margin pools; Sports Medicine shows the steepest expansion trajectory as ambulatory surgery center penetration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) pathway compression and ALARA dose mandates in the United States are accelerating equipment replacement cycles. European regulators under EU MDR intensify post-market surveillance requirements. Asian markets concentrate detector crystal supply chains while expanding diagnostic infrastructure.
United States
Orthopedic super-regional networks in the southeastern and southwestern states negotiate multi-year equipment leases with embedded service tiers. CMS maintains inconsistent coverage for weightbearing extremity CPT codes, creating reimbursement uncertainty across metropolitan markets. The Greater Boston and New York Metro clusters anchor academic orthopedic departments piloting photon-counting detector substrates.
Germany
Academic orthopedic departments in Bavaria and Baden-Württemberg pilot sub-millisievert foot and ankle protocols using cadmium zinc telluride substrates. EU MDR intensified post-market clinical follow-up obligations force manufacturers to embed real-time dose monitoring as standard firmware. The Munich and Heidelberg medical technology clusters concentrate R&D partnerships between university hospitals and imaging equipment developers.
United Kingdom
NHS England procurement frameworks favor systems with documented dose tracking architecture for faster tender approvals. The Medicines and Healthcare products Regulatory Agency enforces CE marking obligations with heightened vigilance on radiation exposure registries. London and Manchester academic medical centers drive adoption of AI-enhanced extremity systems for radiology throughput management.
Japan
PMDA streamlined approval pathways for predicate-equivalent low-dose devices compress manufacturer time-to-revenue in the orthopedic diagnostic segment. METI industrial policy supports domestic production of flat-panel photon-counting detectors to reduce import dependency. The Tokyo and Osaka metropolitan areas concentrate installed bases of dedicated extremity CT platforms in private orthopedic clinics.
South Korea
MFDS regulatory harmonization with FDA 510(k) standards accelerates clearance timelines for low-dose cone-beam systems. The Ministry of Trade, Industry and Energy funds domestic development of iterative reconstruction algorithms through national R&D programs. Seoul Capital Area hospital systems anchor demand for integrated PACS-compatible weightbearing imaging platforms.
Weightbearing Low Dose (CT) Systems Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement pathways. Hospital system contracts and broad service networks anchor volume for integrated health technology conglomerates. Dedicated extremity imaging specialists occupy premium positioning through orthopedic workflow integration. Pay-per-scan service models and equipment leasing structures enable asset-light entrants to bypass capital-intensive direct sales channels. Strategic moves concentrate on AI algorithm licensing and detector substrate supply partnerships rather than horizontal consolidation.
Within the dedicated extremity imaging tier, CurveBeam and Planmeca Group exemplify product-specialist positioning. CurveBeam occupies a position focused on orthopedic workflow integration. Planmeca Group sits within the vertical manufacturing control archetype through in-house imaging software and hardware production. Siemens Healthineers anchors the channel-controlling tier through integrated hospital system contracts. EOS Imaging and Carestream Health represent mid-scale specialists competing on regional service density.
| Leading Market Players |
|---|
| Planmeca Group |
| CurveBeam |
| EOS Imaging |
| Carestream Health |
| Planmed Oy |
| NeuroLogica |
| Xoran Technologies |
| Siemens Healthineers |
| Alphatec Holdings |
| Others |
Value Network & Pricing Analysis
Detector fabrication undercapacity across East Asian substrate processors is compressing procurement timelines for equipment manufacturers while elevating input cost pass-through into system pricing. This utilization squeeze simultaneously tightens supplier bargaining power and forces buyers toward longer-term contract structures.
Pricing Analysis
Certification level creates the primary spread between premium FDA 510(k)-cleared systems and standard CE-marked configurations. Three-tier pricing structure across premium, standard, and economy levels reflects ALARA compliance depth, AI software bundling, and service tier embedding. Cost compression in the economy tier is intensifying because hospital systems delay dedicated extremity purchases. Orthopedic group purchasing organizations demonstrate the least price sensitivity due to aggregated volume leverage, while independent diagnostic centers face acute capital constraint.
Supply Chain Analysis
Contract manufacturing for flat-panel detector assemblies concentrates among specialized electronics manufacturing services in Japan, South Korea, and Taiwan. Cesium iodide and cadmium zinc telluride substrates draw from controlled vapor deposition facilities in Japan and Germany. Single-source vulnerability pervades photon-counting detector layer supply. Distribution runs through hospital system procurement committees and orthopedic GPO aggregators rather than direct equipment sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive advantage as PACS interoperability and AI algorithm marketplaces create winner-take-most dynamics. The shift from standalone hardware to integrated workflow ecosystems redefines defensibility.
For Market Incumbents: Entrench position through captive AI development pipelines and exclusive hospital system EHR integration contracts. Acquire middleware specialists addressing legacy PACS interoperability friction. CurveBeam's orthopedic workflow anchoring and Siemens Healthineers' system-wide agreements exemplify this defensive posture against pay-per-scan service model disruption. For New Entrants and Emerging Players: Pursue podiatric and sports medicine ambulatory surgery centers in the southeastern United States where super-regional network consolidation creates equipment lease aggregation opportunities. Deploy asset-light pay-per-scan models to bypass capital-intensive direct sales. Target greenfield installations lacking incumbent service relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across AI-enhanced software layers relative to hardware manufacturing. Long-term viability favors platform plays with recurring revenue attachment over pure equipment vendors. Acquisition screening should prioritize middleware developers with FDA-cleared segmentation algorithms. The signal to watch is GPO contract renewal timing as super-regional orthopedic networks consolidate procurement authority.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Streamlined predicate-equivalent submissions compress time-to-revenue for low-dose extremity platforms. |
| Hospital System Partnership | Integrated EHR-PACS contracts lock in replacement cycles and block service model entrants. |
| Software Companion Development | AI segmentation algorithms differentiate hardware platforms and capture recurring licensing revenue. |
| Reimbursement Strategy | CMS CPT code alignment determines site-level capital commitment thresholds across metropolitan markets. |
| CE Marking Pathway | EU MDR dose tracking documentation accelerates tender approvals in European hospital procurement. |
Research Methodology
Cross-validation between primary clinician interviews and secondary regulatory filings anchors the qualitative findings. The research incorporated orthopedic surgeons, hospital biomedical engineers, GPO contracts managers, and radiology department heads alongside FDA 510(k) databases, CMS reimbursement schedules, EU MDR notified body documentation, and hospital procurement records. Bottom-up equipment shipment analysis triangulates against top-down healthcare capital expenditure tracking.
Calibration against historical replacement cycle data and ALARA mandate implementation timelines shaped the projection framework. The analytical model segments by product configuration, end-user facility type, technology integration level, and clinical application across the projection horizon. CAGRs derive from weighted average of equipment lease growth, pay-per-scan penetration, and installed base expansion. Forecast inputs include detector substrate supply constraints and orthopedic GPO consolidation velocity.
Sensitivities concentrate around CMS reimbursement code revisions and detector crystal supply disruptions. Forecasts reflect documented assumptions regarding regulatory clearance timelines and hospital capital budget elasticity. Quarterly review of GPO contract awards and EU MDR safety update report filings is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Dental Imaging Market
Medical Imaging
Global Dental Panoramic Radiography Market
Medical Imaging
Italy Nuclear Imaging Market
Medical Imaging
Mobile Radiography Systems Market
Medical Imaging
Canada Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Medical Imaging Management Market
Medical Imaging
AI-Assisted Radiology Market
Medical Imaging
SPECT Scanning Services Market
Medical Imaging
Radiology Positioning Aids Market
Medical Imaging
US Diagnostic Imaging Services Market
Medical Imaging
AI Surgical Video Intelligence System Market
Medical Imaging
Australia Digital X-Ray Market
Medical Imaging
Asia Pacific Nuclear Imaging Market
Medical Imaging
Global Mini C-Arm Market
Medical Imaging
AI Radiology Worklist Orchestration Market
Medical Imaging
Neurophotonics Market