
 Bariatric Rollator Walkers Market | 2026-2036
Bariatric Rollator Walkers Market Size, Share, and Industry Trends Forecast 2026-2036
Bariatric Rollator Walkers Market Outlook
Aftermarket service revenue is reshaping how manufacturers capture lifetime value from bariatric rollator deployments. Drive DeVilbiss Healthcare leverages its direct-to-provider distribution network to control replacement parts fulfillment across North American clinics. Medline Industries anchors its position through institutional contracting with hospital discharge planners and long-term care facilities. Karman Healthcare specializes in lightweight aluminum-frame engineering that reduces shipping costs for e-commerce channels.
Bariatric rollator walkers are reinforced mobility frames engineered to support users exceeding standard weight thresholds, typically constructed from aircraft-grade aluminum or powder-coated steel with welded stress joints and locking hand brakes. Four-wheel configurations with padded seats dominate clinical procurement due to superior stability during sit-to-stand transitions. Steel constructions sustain margin pools in rental fleet operations where durability outweighs portability concerns, while carbon fiber variants command premium positioning in direct-pay segments despite limited reimbursement coverage. Adjustable height mechanisms represent the fastest-growing feature category as providers seek single-SKU solutions across diverse patient anthropometrics.
FDA 510(k) premarket notification requirements govern frame load testing and braking performance standards for US market entry, while ISO 11199-2 establishes international baseline specifications for walking aids with seats. The EU Medical Device Regulation imposes additional clinical evaluation obligations on manufacturers seeking CE marking for bariatric-classified products. Stakeholders must monitor evolving CMS Local Coverage Determinations that increasingly differentiate reimbursement rates between standard and heavy-duty weight capacity classifications.
Market Dynamics
Medicare Advantage plans are tightening prior authorization protocols for bariatric-rated durable medical equipment, forcing manufacturers to restructure reimbursement support services and clinical evidence packages around specific weight-capacity thresholds.
Growth Catalysts
- CMS Local Coverage Determinations:The 2024 recalibration of heavy-duty classification codes expands reimbursable indications for 500-pound-capacity frames in home health settings.
- Aircraft-grade aluminum sourcing:Domestic mill capacity expansion in the United States reduces lead times for welded frame components by forty percent.
- Hospital-at-home programs:Acute care systems in Florida and Texas are discharging bariatric patients with prescribed rollators rather than standard walkers.
Market Restraints
- Steel price volatility:Rental fleet operators face margin compression when commodity indexes spike, forcing extended depreciation schedules on powder-coated inventory.
- FDA 510(k) documentation:Frame stress-testing requirements now demand third-party laboratory certification, extending premarket timelines.
- Standard walker substitution:Non-bariatric patients frequently misuse heavy-duty frames, inflating warranty claims and service costs.
Strategic Opportunities
- Carbon fiber convergence with IoT:Embedded weight sensors enable remote compliance monitoring for value-based care contracts.
- Direct-to-consumer e-commerce:Specialized retailers bypass durable medical equipment distributors, capturing margin previously allocated to discharge planners.
- EU Medical Device Regulation:CE marking for bariatric-classified products creates first-mover advantage in German and Dutch rehabilitation markets.
Industry Challenges
- Welding technician scarcity:Aircraft-grade aluminum TIG certification programs have contracted, constraining production scaling.
- ISO 11199-2 harmonization delays:Divergent braking-performance test protocols between notified bodies create certification bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bariatric Rollator Walkers Market |
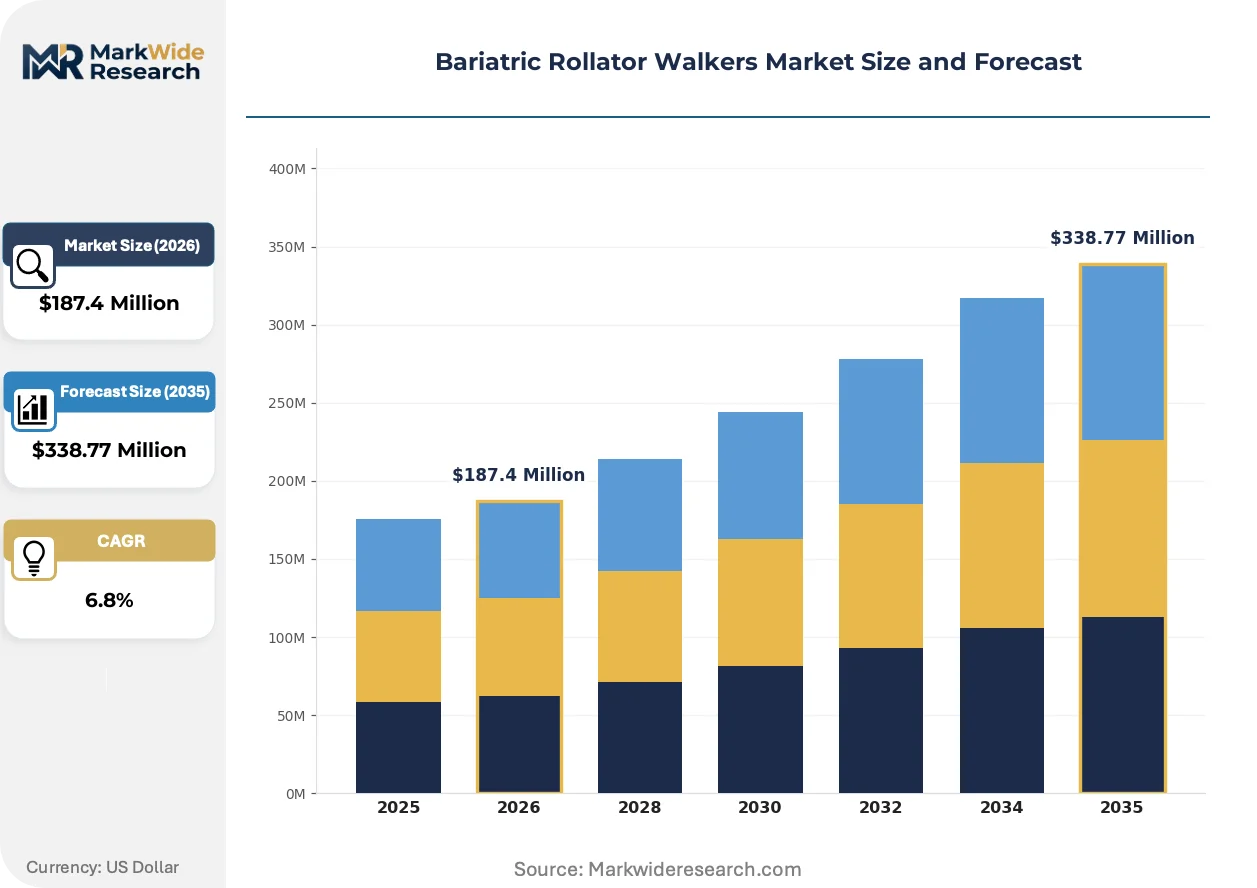
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dual-Handle, Heavy-Duty, Three-Wheel, Four-Wheel Material: Aluminum, Steel, Plastic, Carbon Fiber Weight Capacity: 300 lbs, 400 lbs, 500 lbs, 600 lbs Feature: Adjustable Height, Folding Design, Braking System, Padded Seat |
| Companies Covered | Invacare Corporation, Drive DeVilbiss Healthcare, Medline Industries, GF Health Products, Karman Healthcare, Nova Medical Products, Briggs Healthcare, Compass Health Brands, Human Care, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bariatric Rollator Walkers Market Strategic Shifts
Material science advances and reimbursement coding changes are compressing product lifecycles while elevating performance specifications across all price tiers.
Carbon fiber composite construction is migrating from premium direct-pay segments toward mid-tier institutional procurement. Veterans Affairs facilities now specify carbon-reinforced frames for ambulatory rehabilitation programs. The technology is migrating from boutique positioning to standard-issue status as unit economics improve.
EU Medical Device Regulation clinical evaluation obligations are intensifying post-market surveillance requirements for bariatric-classified walking aids. Manufacturers must maintain periodic safety update reports and vigilance databases. German notified bodies are rejecting legacy technical documentation, forcing redesign cycles.
Acute care discharge planners are consolidating preferred supplier lists around single-SKU adjustable-height solutions. Hospital systems in California and Ohio now mandate four-wheel configurations with integrated seat scales. This concentration is most visible in Medicare Advantage dominant markets where risk-adjusted payments incentivize reduced readmission rates.
Bariatric Rollator Walkers Market Segmentation
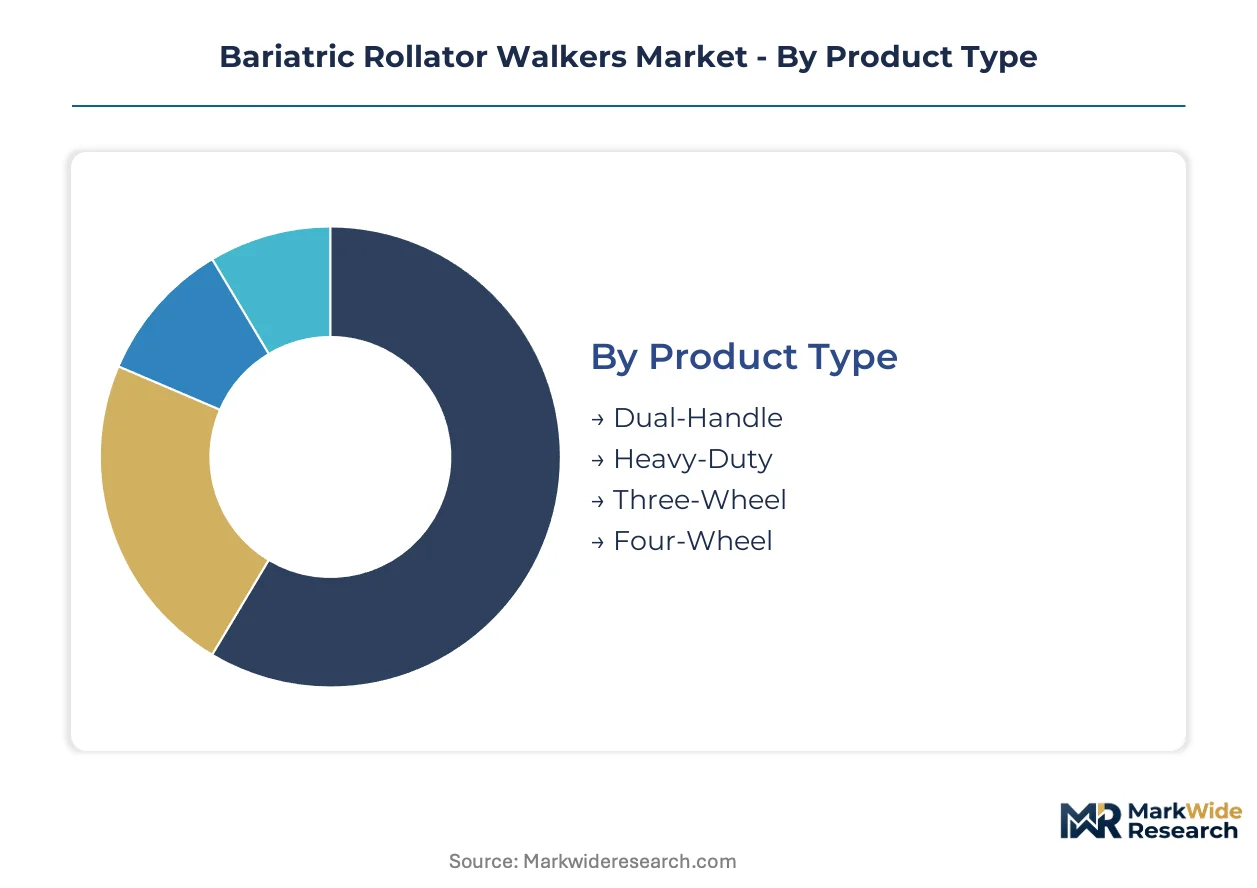
Bariatric rollator procurement decisions hinge on patient anthropometrics, reimbursement coding, and fleet lifecycle economics. Segmentation reveals where manufacturers must align engineering specifications with clinical workflow requirements and payor coverage thresholds.
Product Type:
After-sales service intensity varies sharply across configurations, with rental fleet operators demanding rapid brake replacement turnaround on high-rotation units.
- Four-Wheel:Padded seat configurations with welded steel frames dominate hospital discharge prescriptions. Medicare Advantage plans in Florida and Texas now mandate four-wheel specifications for bariatric home health referrals to reduce fall-related readmissions.
- Heavy-Duty:Reinforced cross-bracing and oversized caster bearings accommodate 500-pound-plus users. VA rehabilitation facilities specify heavy-duty frames for ambulatory therapy programs, driving institutional procurement volume.
- Dual-Handle:Narrow-frame designs suit residential doorway clearances in older housing stock.
- Three-Wheel:Maneuverability-focused frames occupy niche direct-pay segments where portability outweighs stability requirements.
Four-Wheel configurations hold the largest share; momentum sits with Heavy-Duty frames as hospital-at-home programs expand.
Material:
Cost tier stratification separates premium direct-pay segments from institutional rental economics, with raw material sourcing location determining landed cost differentials.
- Aluminum:Aircraft-grade 6061-T6 tubing reduces shipping weights for e-commerce fulfillment channels. Domestic mill capacity expansion in the United States has compressed lead times for welded frame components.
- Steel:Powder-coated constructions sustain margin pools in rental fleet operations where durability cycles exceed portability concerns. Commodity price volatility forces extended depreciation schedules on inventory-heavy operators.
- Carbon Fiber:Embedded sensor compatibility positions composite frames for remote compliance monitoring contracts.
- Plastic:Injection-molded components concentrate in handgrip and basket accessories rather than primary load-bearing elements.
Aluminum dominates institutional procurement; Carbon Fiber is climbing the fastest as Veterans Affairs specifications migrate toward composite standards.
Weight Capacity:
Customer type segmentation tracks payor reimbursement thresholds, with CMS Local Coverage Determinations creating discrete demand bands around specific capacity ratings.
- 500 lbs:Heavy-duty classification codes expanded reimbursable indications in home health settings. Discharge planners in California and Ohio systems now specify 500-pound-capacity frames as default for bariatric patient cohorts.
- 400 lbs:Mid-tier capacity captures standard bariatric definitions for Medicare Advantage prior authorization protocols.
- 600 lbs:Ultra-heavy-duty segment serves specialized long-term care facilities with extreme anthropometric requirements.
- 300 lbs:Entry threshold overlaps with reinforced standard walker categories, creating substitution risk in cost-constrained procurement.
500 lbs capacity commands the largest installed base; 600 lbs ratings are gaining share fastest as skilled nursing facilities accommodate heavier patient populations.
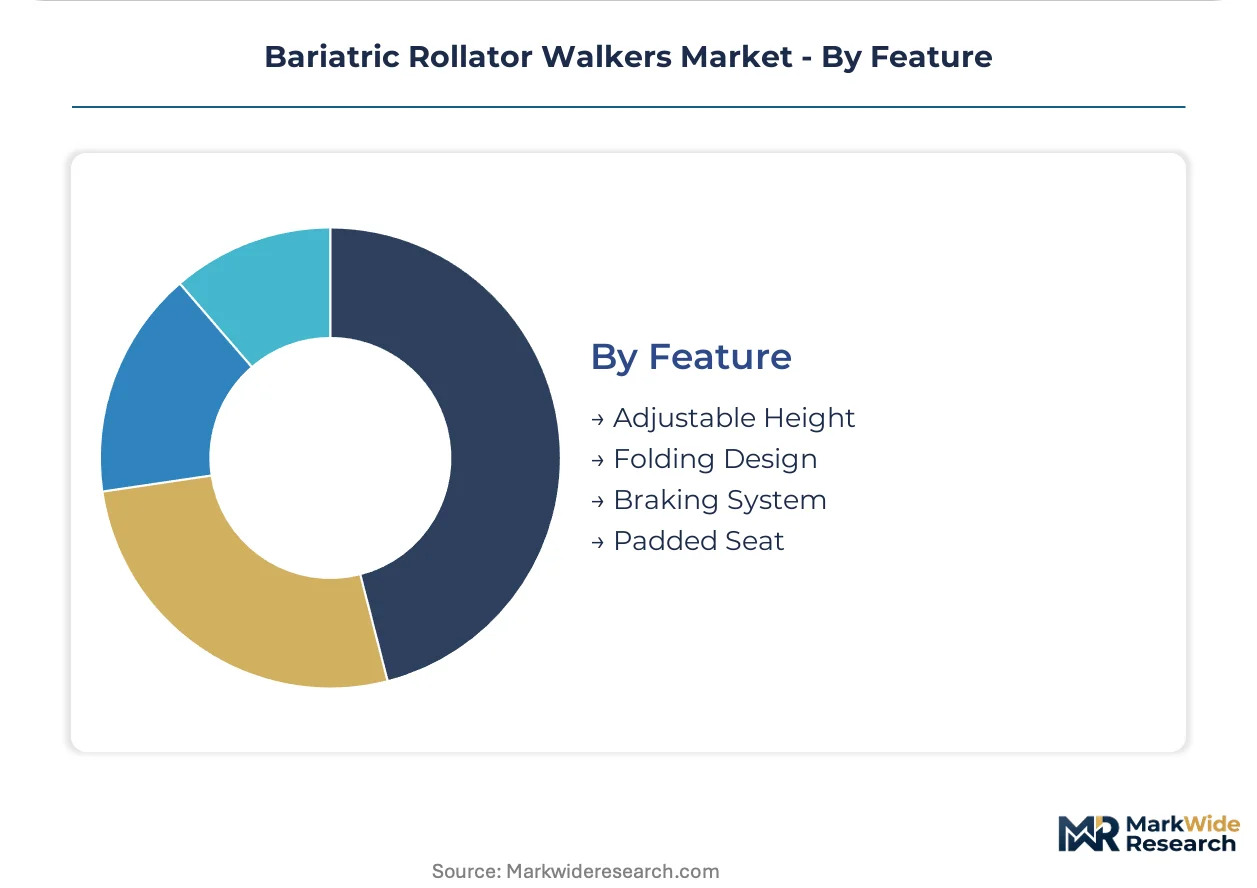
Feature:
Supply concentration in adjustable-height mechanisms reflects provider demand for single-SKU inventory solutions across diverse patient populations.
- Adjustable Height:Telescoping frame designs with indexed locking pins enable one-frame-fits-all procurement strategies. Hospital systems consolidating preferred supplier lists mandate adjustable specifications to reduce SKU proliferation.
- Padded Seat:Polyurethane foam configurations with moisture-resistant covers dominate clinical specifications for sit-to-stand stability.
- Folding Design:Collapsible frames address storage constraints in multi-patient residential settings and vehicle transport requirements.
- Braking System:Locking hand brakes with cable-actuated drum mechanisms face ISO 11199-2 harmonization delays between notified bodies.
Adjustable Height mechanisms hold the largest share; integrated seat scales with weight sensors represent the steepest expansion trajectory for value-based care monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States buyers demonstrate the lowest price elasticity as Medicare Advantage plans absorb premium costs, while German procurement offices enforce strict cost-performance ratios that compress margin pools for mid-tier suppliers.
United States
Medicare Advantage prior authorization protocols now mandate 500-pound-capacity frames for bariatric home health referrals in Florida and Texas hospital-at-home programs. FDA 510(k) clearance pathways tightened frame stress-testing documentation requirements in 2024, extending premarket timelines for new entrants. Cleveland Clinic and Kaiser Permanente systems in Ohio and California specify integrated seat scales for fall-risk monitoring.
Germany
Rehabilitation clinics in Bavaria and North Rhine-Westphalia specify carbon-reinforced frames for ambulatory therapy programs as Veterans Affairs specifications migrate toward composite standards. EU Medical Device Regulation clinical evaluation obligations intensify post-market surveillance through German notified bodies rejecting legacy technical documentation. Berlin-based discharge planners consolidate preferred supplier lists around single-SKU adjustable-height solutions.
Japan
Metropolitan Tokyo hospitals address super-aging demographics with bariatric-rated durable medical equipment for rising patient acuity in community settings. PMDA alignment with ISO 11199-2 braking-performance standards creates certification bottlenecks for foreign manufacturers. Osaka-Kansai medical device clusters concentrate procurement decisions for western Japan's long-term care facilities.
United Kingdom
NHS England integrated care systems in Greater Manchester and the West Midlands expand heavy-duty mobility aid procurement as hospital-at-home programs discharge bariatric patients. MHRA post-Brexit regulatory divergence from EU MDR creates parallel compliance tracks for CE-marked products. London teaching hospitals pilot remote compliance monitoring contracts with embedded weight sensor configurations.
Canada
Provincial health authorities in Ontario and British Columbia recalibrate durable medical equipment formularies to differentiate reimbursement between standard and heavy-duty weight capacity classifications. Health Canada licensing requirements for Class I medical devices align with FDA frame load testing standards. Toronto rehabilitation institutes anchor procurement decisions for central Canada's bariatric patient cohorts.
Bariatric Rollator Walkers Market Competitive Environment
Capability concentration sits with specialized aluminum-frame engineers; scale advantage sits with diversified durable medical equipment conglomerates. The vendor base organizes around three strategic archetypes: institutional contract anchors, direct-to-consumer e-commerce specialists, and rental fleet operators with captive service networks. Dominant competitive moves include backward integration into aircraft-grade aluminum sourcing and consolidation of discharge planner relationships through preferred supplier list placement.
Among diversified healthcare manufacturers, Drive DeVilbiss Healthcare and Medline Industries exemplify the institutional contract anchor archetype, while Karman Healthcare occupies a position within the lightweight engineering specialist tier. Invacare Corporation sits within the scale-driven rehabilitation equipment conglomerate category alongside GF Health Products. These named entities represent competitive positioning patterns rather than exhaustive market coverage, with each exemplifying distinct pathways to procurement influence across North American and European health systems.
| Leading Market Players |
|---|
| Invacare Corporation |
| Drive DeVilbiss Healthcare |
| Medline Industries |
| GF Health Products |
| Karman Healthcare |
| Nova Medical Products |
| Briggs Healthcare |
| Compass Health Brands |
| Human Care |
| Others |
Value Chain & Pricing Dynamics
Commodity steel price volatility determines both tiered pricing spreads across rental fleet operators and the geographic configuration of aircraft-grade aluminum sourcing networks. Domestic mill capacity expansion in the United States compresses lead time differentials between powder-coated steel inventory-heavy models and lightweight e-commerce-optimized frames.
Pricing Analysis
Aftermarket service revenue tiers—brake replacement contracts, extended warranty bundles, and parts fulfillment agreements—drive lifetime value capture across institutional procurement channels. Three-tier pricing structure across premium carbon fiber, standard aluminum, and economy steel levels reflects certification grade differentiation under FDA 510(k) pathways. Cost compression in steel-frame rental fleets is intensifying because commodity index spikes force extended depreciation schedules. Medicare Advantage-absorbed premium pricing demonstrates lowest elasticity; direct-pay e-commerce channels exhibit highest sensitivity.
Supply Chain Analysis
Aircraft-grade aluminum feedstock draws from domestic United States mill expansion, Chinese semi-finished tubing exports, and German precision extrusion specialists. Component dependencies center on TIG-certified welding technicians, powder-coating chemical inputs, and oversized caster bearing assemblies. Single-source vulnerability concentrates in TIG certification programs that have contracted, constraining production scaling. Distribution runs through direct-to-provider networks for replacement parts and durable medical equipment distributors for initial discharge prescriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits with hospital-at-home program expansion creating discrete procurement niches around integrated seat scales and remote monitoring configurations. Acuity shifts in community settings generate demand pockets underserved by standardized institutional contracting.
For Market Incumbents: Entrench preferred supplier list positioning through backward integration into aircraft-grade aluminum sourcing and captive TIG welding certification programs. Carbon fiber convergence with IoT sensors threatens traditional frame margins; defending reimbursement support services around specific weight-capacity thresholds anchors institutional relationships.
For New Entrants and Emerging Players: Build out direct-to-consumer e-commerce capabilities targeting Medicare Advantage dominant markets where prior authorization complexity creates service gaps. German and Dutch rehabilitation markets present penetrable white space under EU Medical Device Regulation first-mover pathways. Specialized clinical evidence packaging around 500-pound-capacity frames differentiates against established discharge planner networks.
For Investors and Strategic Acquirers: FDA 510(k) documentation tightening reshapes the acquisition landscape toward targets with third-party laboratory certification infrastructure and established 510(k) clearance track records. Five-to-ten-year viability favors aluminum-frame engineers with Veterans Affairs specifications compliance and carbon fiber IoT integration capabilities. ISO 11199-2 harmonization resolution signals inflection for braking-system technology bets.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Third-party laboratory certification accelerates premarket timelines for new frame entrants. |
| CE Marking Pathway | EU Medical Device Regulation compliance unlocks German rehabilitation clinic procurement. |
| Hospital System Partnership | Preferred supplier list placement secures discharge planner influence in Medicare Advantage markets. |
| Software Companion Development | Embedded weight sensors enable remote compliance monitoring for value-based care contracts. |
| Reimbursement Strategy | CMS Local Coverage Determination alignment maximizes heavy-duty classification code capture. |
Study Parameters
Initial hypotheses were tested against primary input from hospital discharge planners, biomedical engineers, GPO contracts managers, and durable medical equipment procurement officers and refined through secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and ISO 11199-2 technical documentation. Bottom-up demand modeling across patient anthropometric segments triangulated with top-down market sizing from institutional contracting volumes.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product configuration, material grade, weight capacity tier, and feature integration intensity. CAGRs derived from weighted average of historical procurement growth and policy-driven reimbursement expansion assumptions. Forecast inputs incorporated Medicare Advantage penetration trajectories and Veterans Affairs specification migration patterns.
Practitioners should monitor FDA 510(k) documentation requirement evolution and ISO 11199-2 harmonization progress for early signals of competitive positioning shifts. Forecasts reflect assumptions around CMS Local Coverage Determination stability and commodity steel price normalization. Cross-checking against Veterans Affairs procurement disclosure databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bariatric Surgery
India Bariatric Surgery Market
Bariatric Surgery
Bariatric Walkers Market
Bariatric Surgery
Bariatric Patient Room Market
Bariatric Surgery
Saudi Arabia Bariatric Surgery Market
Bariatric Surgery
Japan Bariatric Surgery Market
Bariatric Surgery
Sweden Bariatric Surgery Market
Bariatric Surgery
Global Bariatric Surgical Devices Market
Bariatric Surgery
Global Bariatric Walking Aids Market
Bariatric Surgery
Global Bariatric Surgery Market
Bariatric Surgery
US Medical Weight Loss Clinics Market
Bariatric Surgery
China Bariatric Surgery Market
Bariatric Surgery
Mexico Bariatric Surgery Market
Bariatric Surgery
Bariatric Surgery Devices Market
Bariatric Surgery
Australia Bariatric Surgery Market
Bariatric Surgery
Germany Bariatric Surgery Market
Bariatric Surgery
Italy Bariatric Surgery Market