
 SPECT Scanning Services Market | 2026-2036
SPECT Scanning Services Market Size, Share, and Industry Trends Forecast 2026-2036
SPECT Scanning Services Market Analytics
Oncology is recalibrating SPECT scanning demand as hospital networks prioritize molecular imaging for precision treatment pathways. GE Healthcare dominates gamma camera installations across North American academic medical centers. Siemens Healthineers leverages hybrid imaging R&D intensity to extend its European service footprint. Philips Healthcare anchors outpatient facility partnerships through managed equipment service contracts.
Single photon emission computed tomography reconstructs gamma ray distributions using rotating gamma cameras and radiotracer kinetics, typically resolving functional abnormalities at 8-12 millimeter spatial resolution for cardiac perfusion and bone metabolism assessment. Hybrid imaging—combining SPECT with computerized tomography—captures premium margin pools as clinicians demand anatomical co-registration for lesion localization. Digital imaging detector technology is displacing conventional Anger camera architectures, with advanced cadmium-zinc-telluride semiconductors shortening scan duration and lowering radiotracer dose requirements.
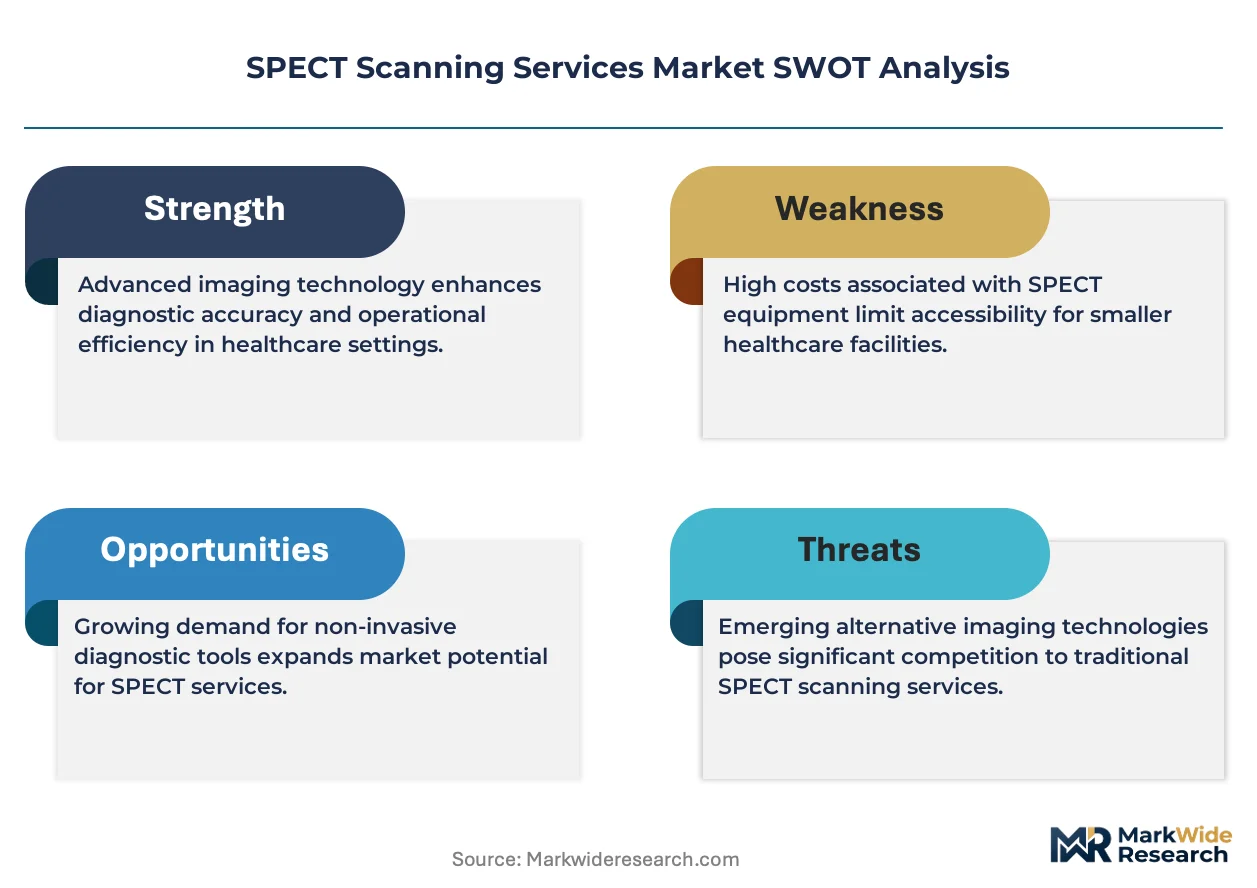
The FDA governs radiopharmaceutical manufacturing and clinical trial endpoints for SPECT tracers under 21 CFR Part 312, while the Nuclear Regulatory Commission enforces dose calibration and technologist certification standards for clinical operations. In Europe, EMA centralized marketing authorization procedures and REACH chemical safety protocols constrain radiotracer supply chain configurations. Stakeholders must monitor reimbursement parity between SPECT and PET modalities as health technology assessment bodies recalibrate value frameworks for molecular imaging.
Market Dynamics
Digital cadmium-zinc-telluride detector arrays are compressing scan durations and tracer dosages, forcing service providers to recalibrate throughput models and capital replacement cycles across hospital networks and outpatient imaging centers.
Growth Catalysts
- Oncology Precision Pathways:Hospital networks are embedding SPECT protocols into tumor staging workflows, expanding molecular imaging utilization for treatment monitoring.
- 21 CFR Part 312 Streamlining:The FDA's updated radiopharmaceutical guidance is accelerating tracer approval pathways and reducing clinical trial endpoint friction.
- German Centralized Procurement:University hospital networks in Germany are consolidating nuclear medicine service lines under unified purchasing frameworks, concentrating demand.
Market Restraints
- Molybdenum-99 Supply Concentration:Reactor-dependent isotope production clusters in Canada and the Netherlands create vulnerability for technetium-99m availability.
- Anger Camera Stranded Assets:Conventional sodium iodide detector installations face accelerated obsolescence as digital CZT platforms capture premium reimbursement.
- PET Substitution Pressure:Positron emission tomography's superior spatial resolution is displacing SPECT for neurological and oncological indications in affluent markets.
Strategic Opportunities
- Cardiac Amyloidosis Protocols:Pyrophosphate tracer imaging for transthyretin cardiac amyloidosis is opening new service lines in cardiology departments.
- Managed Equipment Services:Philips Healthcare's outpatient facility partnership model demonstrates channel innovation for capital-constrained imaging centers.
- Hybrid Imaging Convergence:SPECT-CT integration is capturing margin pools through anatomical-functional co-registration for lesion localization.
Industry Challenges
- Nuclear Medicine Technologist Shortage:Certification requirements under NRC standards are constraining workforce expansion as clinical volumes rise.
- Legacy PACS Integration:Digital detector platforms require costly interoperability upgrades with hospital information systems and radiology workflow engines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | SPECT Scanning Services Market |
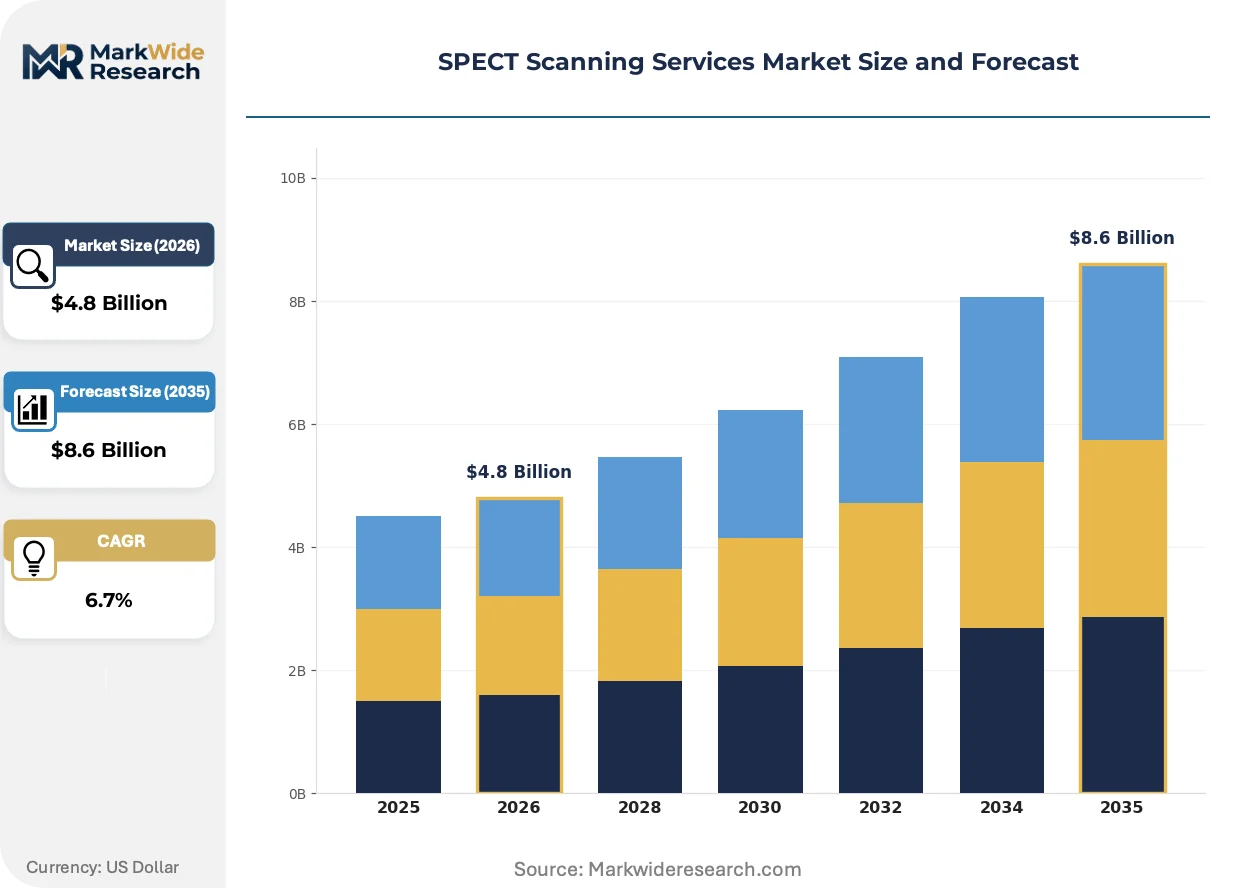
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Photon Emission Computed Tomography, Hybrid Imaging, Radiopharmaceuticals, Imaging Software End User: Hospitals, Diagnostic Centers, Research Institutions, Outpatient Facilities Technology: Gamma Cameras, Advanced Detectors, Digital Imaging, Computerized Tomography Application: Oncology, Neurology, Cardiology, Infection Detection |
| Companies Covered | GE Healthcare, Siemens Healthineers, Philips Healthcare, Canon Medical Systems, Cardinal Health, Bracco, Curium Pharma, Lantheus Medical Imaging, Mediso Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
SPECT Scanning Services Market Evolving Landscape
Artificial intelligence reconstruction algorithms and semiconductor detector materials are compressing acquisition times while expanding diagnostic utility, reshaping competitive positioning around throughput efficiency and clinical accuracy.
Cadmium-zinc-telluride semiconductor detectors are automating image acquisition workflows by replacing photomultiplier tubes with direct-conversion electronics. Academic medical centers in North America are deploying CZT-equipped gamma cameras for cardiac perfusion studies, cutting scan times by half. This automation is enabling same-day diagnostic protocols and expanding outpatient capacity without proportional capital expansion.
EMA centralized marketing authorization procedures are constraining radiotracer supply chain configurations across European Union member states. REACH chemical safety protocols impose documentation burdens on precursor manufacturing, elevating compliance costs for tracer producers. German and French hospital networks are responding by consolidating procurement through centralized nuclear medicine service lines to secure supply continuity.
Buying committees at hospital networks are unbundling equipment acquisition from maintenance and radiopharmaceutical supply contracts. Traditional bundled leasing arrangements are fragmenting into separate negotiations for gamma camera hardware, software subscriptions, and isotope logistics. This pattern is most visible in the United States, where health system consolidation has concentrated purchasing authority at regional network headquarters.
SPECT Scanning Services Market Segmentation
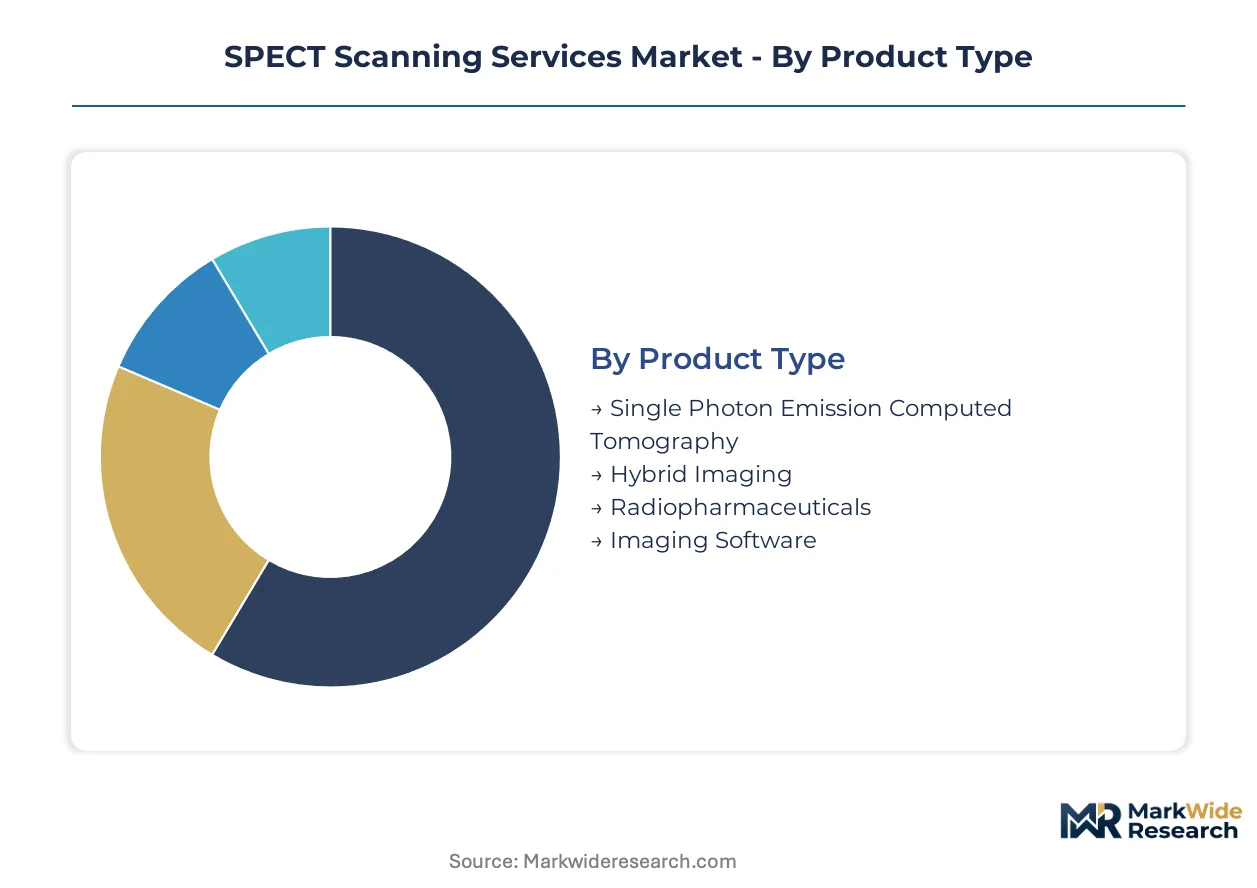
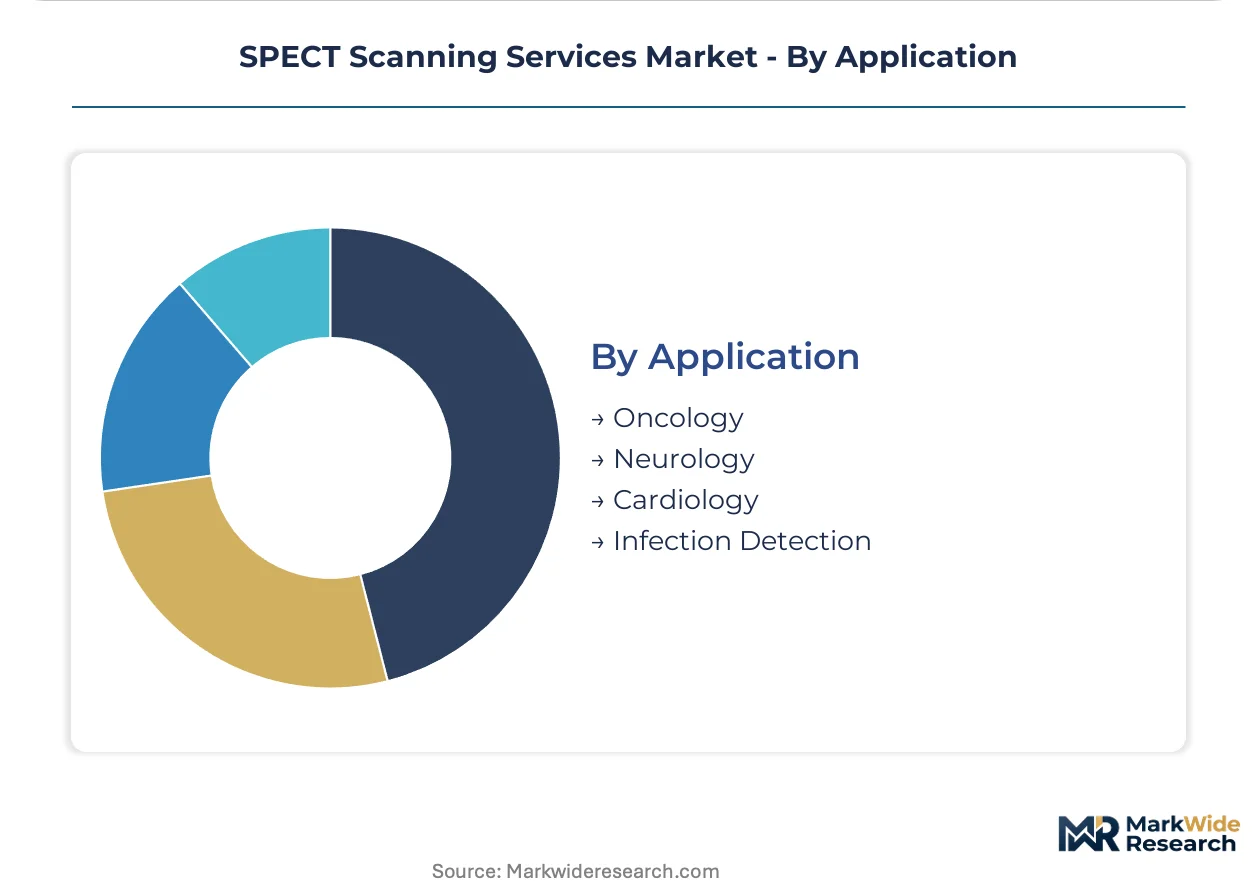
Service providers calibrate capital deployment and staffing models around distinct technology configurations and clinical settings. Segmentation reveals where reimbursement premiums concentrate and where digital transitions are compressing operational margins.
Product Type:
Supply concentration in detector manufacturing and isotope production shapes competitive dynamics across hardware and consumable segments.
- Single Photon Emission Computed Tomography:Conventional rotating gamma camera systems utilizing sodium iodide or CZT detectors for functional imaging. Hospital networks in Germany are consolidating procurement for these systems under centralized nuclear medicine service lines to secure volume pricing and maintenance continuity.
- Hybrid Imaging:SPECT-CT platforms combining functional gamma ray detection with anatomical CT co-registration. Academic medical centers across the United States are prioritizing these configurations for lesion localization protocols, capturing premium reimbursement through enhanced diagnostic specificity.
- Radiopharmaceuticals:Technetium-99m and other tracer compounds for myocardial perfusion and bone metabolism studies.
- Imaging Software:Reconstruction algorithms and PACS integration modules for workflow management.
Hybrid imaging absorbs the bulk of installed capacity; radiopharmaceuticals are expanding most quickly as novel tracers gain clinical validation.
End User:
Customer type determines capital intensity requirements and reimbursement pathway complexity.
- Hospitals:Integrated health systems with inpatient and emergency capabilities requiring 24/7 nuclear medicine coverage. Oncology departments are embedding SPECT protocols into tumor staging workflows, expanding molecular imaging utilization for treatment monitoring.
- Diagnostic Centers:Dedicated outpatient imaging facilities focused on high-throughput cardiac and bone scans. These operators are adopting managed equipment service contracts to limit capital exposure while maintaining access to digital CZT platforms.
- Research Institutions:Academic centers conducting clinical trials for novel radiotracers and imaging protocols.
- Outpatient Facilities:Ambulatory settings providing same-day diagnostic services.
Hospitals command the largest share of procedure volume; outpatient facilities are climbing the fastest as same-day protocols proliferate.
Technology:
Detector architecture transitions are forcing capital replacement cycles and workforce retraining investments.
- Gamma Cameras:Traditional Anger camera systems with photomultiplier tubes and sodium iodide crystals. Conventional installations face accelerated obsolescence as digital CZT platforms capture premium reimbursement and shorten scan durations.
- Advanced Detectors:Cadmium-zinc-telluride semiconductor arrays enabling direct gamma ray conversion. North American academic medical centers are deploying CZT-equipped systems for cardiac perfusion studies, cutting acquisition times by half and expanding daily throughput.
- Digital Imaging:Solid-state detector platforms with automated acquisition workflows.
- Computerized Tomography:CT components for anatomical co-registration in hybrid configurations.
Gamma cameras retain the largest installed base; advanced detectors are gaining share fastest through replacement demand.
Application:
Clinical indication determines tracer selection, reimbursement rates, and competitive intensity from PET alternatives.
- Oncology:Tumor staging, treatment response assessment, and metastasis detection using bone-seeking and tumor-specific tracers. Hospital networks are prioritizing molecular imaging for precision treatment pathways, though PET substitution pressure intensifies for neurological and oncological indications in affluent markets.
- Cardiology:Myocardial perfusion imaging and viability assessment for coronary artery disease. Pyrophosphate tracer protocols for transthyretin cardiac amyloidosis are opening new service lines as awareness expands among cardiology departments.
- Neurology:Cerebral blood flow and receptor binding studies for dementia and movement disorders.
- Infection Detection:White blood cell labeling for localized infection and fever of unknown origin.
Cardiology dominates procedure volume; oncology is expanding most rapidly as staging protocols proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Isotope production clusters in Canada and the Netherlands supply technetium-99m to imaging centers worldwide, while consumption concentrates in hospital networks across Germany, the United States, and Japan. Service providers calibrate procurement strategies around these geographic asymmetries.
United States
FDA guidance under 21 CFR Part 312 accelerates radiopharmaceutical approval pathways for academic medical centers. The Nuclear Regulatory Commission enforces technologist certification standards that constrain workforce expansion. Boston and Houston hospital networks deploy hybrid SPECT-CT platforms for cardiac amyloidosis protocols.
Germany
University hospital networks consolidate nuclear medicine procurement under centralized frameworks to secure volume pricing. EMA centralized marketing authorization and REACH chemical safety protocols elevate compliance costs for tracer producers. The Rhine-Ruhr and Bavarian medical clusters anchor service line consolidation efforts.
Japan
PMDA marketing authorization procedures govern radiotracer clinical trial endpoints for oncology staging applications. METI industrial policy supports domestic isotope production diversification. Tokyo and Osaka academic centers prioritize CZT detector adoption for myocardial perfusion imaging.
Canada
Chalk River reactor infrastructure historically dominated global molybdenum-99 supply before conversion to low-enriched uranium targets. Health Canada regulates radiopharmaceutical manufacturing standards for domestic distribution. Ontario and Quebec hospital networks maintain emergency isotope reserves against supply disruption scenarios.
Netherlands
Petten reactor facilities supply technetium-99m generators across European Union member states under EMA distribution protocols. ANSM chemical safety requirements align with REACH documentation burdens for precursor handling. The Randstad medical corridor concentrates nuclear medicine service demand from Belgian and German border regions.
SPECT Scanning Services Market Competitive Landscape
Top-tier vendors anchor premium hybrid imaging installations, while mid-tier service providers compete on outpatient throughput efficiency. The vendor base stratifies across three tiers: integrated conglomerates with radiopharmaceutical divisions, standalone imaging equipment specialists, and regional service contractors. Dominant competitive moves include managed equipment service contract expansion and semiconductor detector technology licensing.
Within the integrated conglomerate tier, GE Healthcare and Siemens Healthineers occupy positions spanning gamma camera hardware and isotope logistics. Philips Healthcare exemplifies the service-contract archetype through outpatient facility partnerships. Canon Medical Systems represents mid-tier equipment specialization without captive radiopharmaceutical supply.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Philips Healthcare |
| Canon Medical Systems |
| Cardinal Health |
| Bracco |
| Curium Pharma |
| Lantheus Medical Imaging |
| Mediso Ltd |
| Others |
Value Network & Pricing Analysis
Molybdenum-99 reactor production costs cascade through technetium-99m generator pricing, concentrating margin pressure on imaging centers dependent on Canadian and Dutch isotope supply while digital CZT detector premiums recalibrate equipment procurement tiers across hospital networks.
Pricing Analysis
Margin tightening in outpatient diagnostic centers reflects unbundling of equipment acquisition from maintenance and radiopharmaceutical supply contracts. Three-tier pricing structure across premium hybrid SPECT-CT, standard digital gamma cameras, and economy Anger camera refurbishments stratifies by detector architecture and after-sales service bundling. Cost-down pressure on conventional sodium iodide installations accelerates because reimbursement parity shifts toward shorter-scan digital protocols. Hospital purchasing committees demonstrate lowest price sensitivity for hybrid imaging platforms, while independent imaging centers negotiate aggressively on per-scan radiopharmaceutical supply terms.
Supply Chain Analysis
Nuclear medicine technologist certification bottlenecks in the United States and Germany constrain manufacturing capacity expansion for digital detector assembly. Isotope production clusters in Canada and the Netherlands, plus CZT semiconductor fabrication in Japan and the United States, anchor upstream supply. Raw material dependencies span enriched uranium targets, cadmium-zinc-telluride ingots, and specialized scintillation crystals. Single-source vulnerability concentrates at the Chalk River and Petten reactor facilities for molybdenum-99. Distribution runs through centralized hospital procurement frameworks in Germany and GPO contracts across United States health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The SPECT scanning services market sits in a detector technology transition phase as cadmium-zinc-telluride semiconductor arrays displace conventional Anger camera architectures and compress capital replacement cycles.
For Market Incumbents: Deepen captive radiopharmaceutical supply integration to defend against PET substitution pressure in oncology staging protocols. Expand managed equipment service contracting to lock in outpatient facility relationships before digital CZT platforms commoditize hardware margins. Prioritize workforce training partnerships with NRC-certified technologist programs to preempt labor-constrained throughput ceilings. For New Entrants and Emerging Players: 21 CFR Part 312 streamlining in the United States opens a window for novel tracer developers to bypass incumbent radiopharmaceutical supply relationships. Target cardiac amyloidosis pyrophosphate imaging protocols in cardiology departments as the most penetrable clinical application with expanding reimbursement. Pursue hospital-at-home and ambulatory surgical center partnerships as a go-to-market angle bypassing entrenched academic medical center procurement. For Investors and Strategic Acquirers: FDA clearance of AI reconstruction algorithms for CZT-equipped systems is the leading indicator that semiconductor detector penetration is approaching inflection. Long-term viability favors vertically integrated platforms spanning hardware, software, and isotope logistics over standalone equipment manufacturers. Monitor German university hospital network consolidation announcements as a signal for regional procurement authority concentration that would reshape vendor competitive dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| CZT Detector Manufacturing Scale-Up | Shortens scan durations and expands outpatient throughput capacity for health systems. |
| Managed Equipment Service Expansion | Philips Healthcare's partnership model demonstrates channel control without capital burden. |
| Novel Radiotracer FDA Submission | Pyrophosphate cardiac amyloidosis protocols open reimbursement pathways in cardiology. |
| Hospital Procurement Consolidation | German centralized frameworks concentrate purchasing authority and squeeze vendor margins. |
| AI Reconstruction Algorithm Licensing | Automated acquisition workflows reduce technologist labor requirements per scan. |
Research Methodology
FDA 510(k) filings, EMA centralized marketing authorization procedures, and hospital procurement databases formed the secondary backbone for market sizing and competitive positioning analysis. Primary interviews with nuclear medicine department directors, GPO contracts managers, biomedical engineers, and radiopharmaceutical manufacturing executives supplied operational validation and forward-looking demand signals. Bottom-up procedure volume estimates across oncology, cardiology, and neurology applications triangulated against top-down health system capital expenditure disclosures.
Bottom-up modeling anchored forecast outputs, with top-down reconciliation against national health expenditure trends and imaging reimbursement code valuations. Segmentation dimensions included detector technology tier, hybrid versus standalone configuration, end-user facility type, and clinical application area. CAGRs derived from fitted adoption curves for digital CZT replacement cycles and tracer protocol expansion rates. Forecast inputs incorporated NRC technologist certification pipeline constraints and EMA REACH compliance cost trajectories for radiopharmaceutical producers.
The model assumes a particular technology adoption path; alternative pathways for solid-state photon-counting detectors would alter the outlook for conventional CZT platform viability. Forecasts reflect assumptions around isotope supply continuity from aging reactor infrastructure and reimbursement parity maintenance between SPECT and PET modalities. Material deviation in molybdenum-99 supply disruption frequency or CMS imaging fee schedule adjustments warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
North America Medical Imaging Software Market
Medical Imaging
France Mammography Market
Medical Imaging
Portable Cardiology Ultrasound Systems Market
Medical Imaging
AI Surgical Video Intelligence System Market
Medical Imaging
Multiphoton Microscopy Market
Medical Imaging
Italy Nuclear Imaging Market
Medical Imaging
Fluorescence Microscopy Market
Medical Imaging
Germany Computed Tomography Market
Medical Imaging
Medical X-Ray Films Market
Medical Imaging
Asia-Pacific Digital X-Ray Devices Market
Medical Imaging
Pre-Clinical Imaging System Market
Medical Imaging
Global Mobile Medical Imaging Services Market
Medical Imaging
Dental Digital X Ray Market
Medical Imaging
Intravascular Imaging Market
Medical Imaging
Retinal Imaging Devices Market
Medical Imaging
Diagnostic Imaging Services Market