
 Vendor Neutral Archive Market | 2026-2036
Vendor Neutral Archive Market Size, Share, and Industry Trends Forecast 2026-2036
Vendor Neutral Archive Market Outlook
North American data center expansion is rewriting deployment economics for medical imaging archives. Siemens Healthineers leverages its installed base of diagnostic equipment to drive bundled archive sales across integrated delivery networks. GE Healthcare anchors its position through deep integration with hospital IT ecosystems and enterprise imaging platforms. Philips competes by extending its cloud-native HealthSuite architecture into multi-site archive deployments.
A vendor neutral archive is a medical imaging storage system that standardizes DICOM and non-DICOM data into a centralized repository accessible by any viewing or analysis application, typically supporting storage tiering from flash to tape with retrieval latency under five seconds for primary diagnostic reads. Its commercial purpose eliminates proprietary data lock-in while enabling longitudinal patient records across disparate care settings. Cloud storage deployments are capturing the fastest expansion as health systems abandon capital-intensive on-premises infrastructure, while hybrid solutions retain dominance among large academic medical centers balancing latency sensitivity with disaster recovery requirements. Healthcare providers represent the deepest end-user margin pool, though research institutions are emerging as a specialized growth corridor for multi-tenant archive configurations.
FDA 21 CFR Part 820 quality system requirements shape product validation pathways for archive software marketed as medical devices, while HIPAA security rules mandate encryption and access logging that directly influence procurement specifications. The Office of the National Coordinator for Health IT interoperability standards are forcing legacy PACS vendors toward API-first architectures that benefit neutral archive platforms. Stakeholders must weigh cloud egress cost structures against the operational flexibility of subscription models when evaluating total cost of ownership for decade-long imaging retention obligations.
Market Dynamics
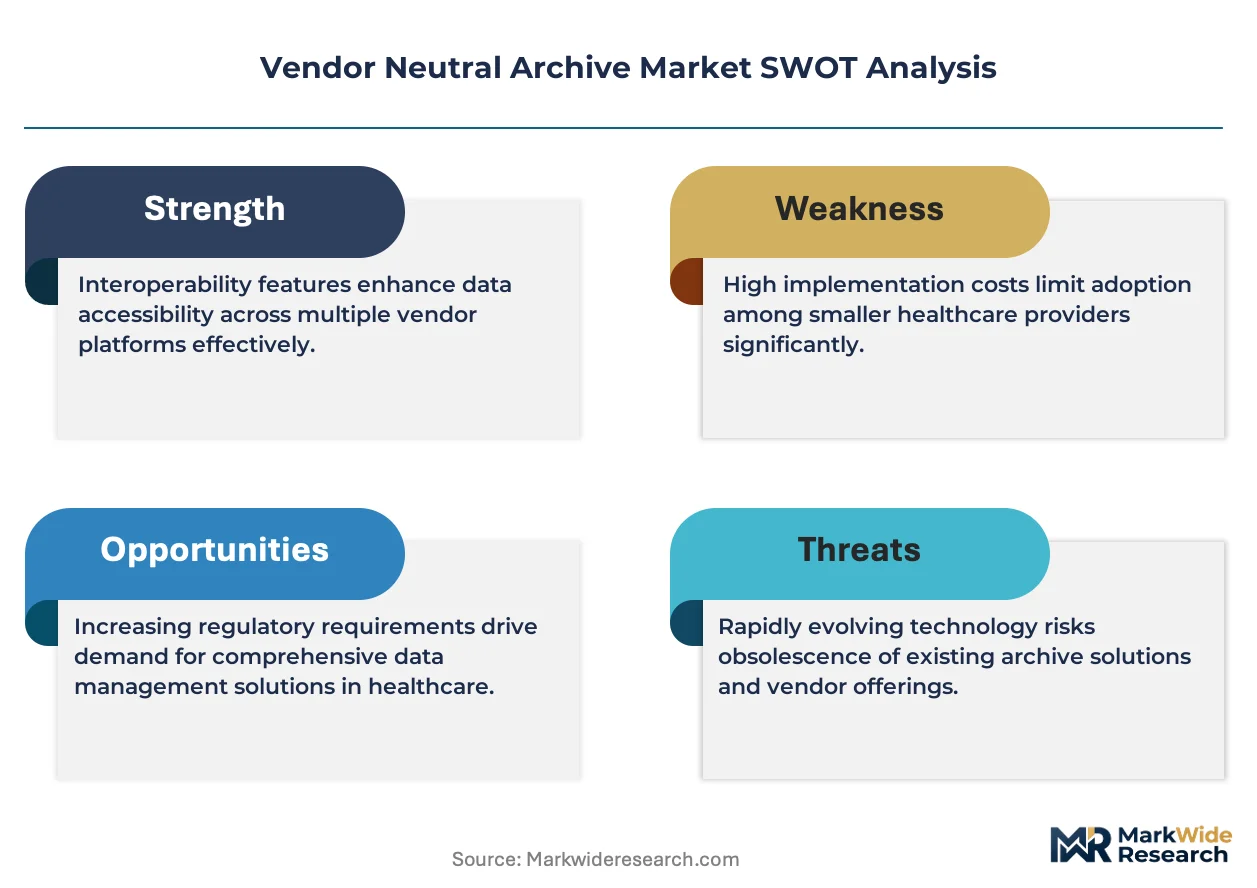
Hospital procurement committees are mandating DICOMweb-native architectures to escape proprietary PACS lock-in, forcing infrastructure decisions toward centralized storage platforms that decouple imaging capture from diagnostic viewing workflows.
Growth Catalysts
- HIPAA data retention mandates:Extended storage obligations for medical images are compelling health systems to consolidate fragmented archives into unified repositories with automated lifecycle management.
- Cloud storage economics:Subscription-based operational expenditure models are displacing capital-intensive on-premises SAN arrays, particularly among mid-size community hospital networks.
- Interoperability frameworks:The Office of the National Coordinator for Health IT API requirements are accelerating decommissioning of siloed departmental imaging systems.
Market Restraints
- Cloud egress cost volatility:Retrieval fees for large imaging studies can exceed storage costs, creating unpredictable operational expenditure spikes for high-volume radiology departments.
- Legacy infrastructure entrenchment:Embedded PACS installations with decade-long depreciation schedules delay replacement cycles at academic medical centers.
- AI diagnostic workflow fragmentation:Proprietary AI algorithms tied to specific vendor platforms create new data silos that partially undermine neutral archive value propositions.
Strategic Opportunities
- Research imaging monetization:Multi-tenant archive configurations serving pharmaceutical clinical trials represent an underpenetrated revenue stream beyond traditional healthcare delivery.
- Edge-to-cloud tiering architectures:Flash storage at radiology workstations combined with glacier-class cloud retention addresses latency-sensitive primary reads while optimizing long-term costs.
- FDA 21 CFR Part 820 validation services:Quality system documentation for archive software marketed as medical devices creates adjacent professional services demand.
Industry Challenges
- DICOM standard version heterogeneity:Inconsistent implementation of DICOMweb across legacy modalities complicates unified archive ingestion pipelines.
- Cross-departmental workflow re-engineering:Cardiology, pathology, and radiology departments maintain separate imaging governance committees that resist consolidated procurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vendor Neutral Archive Market |
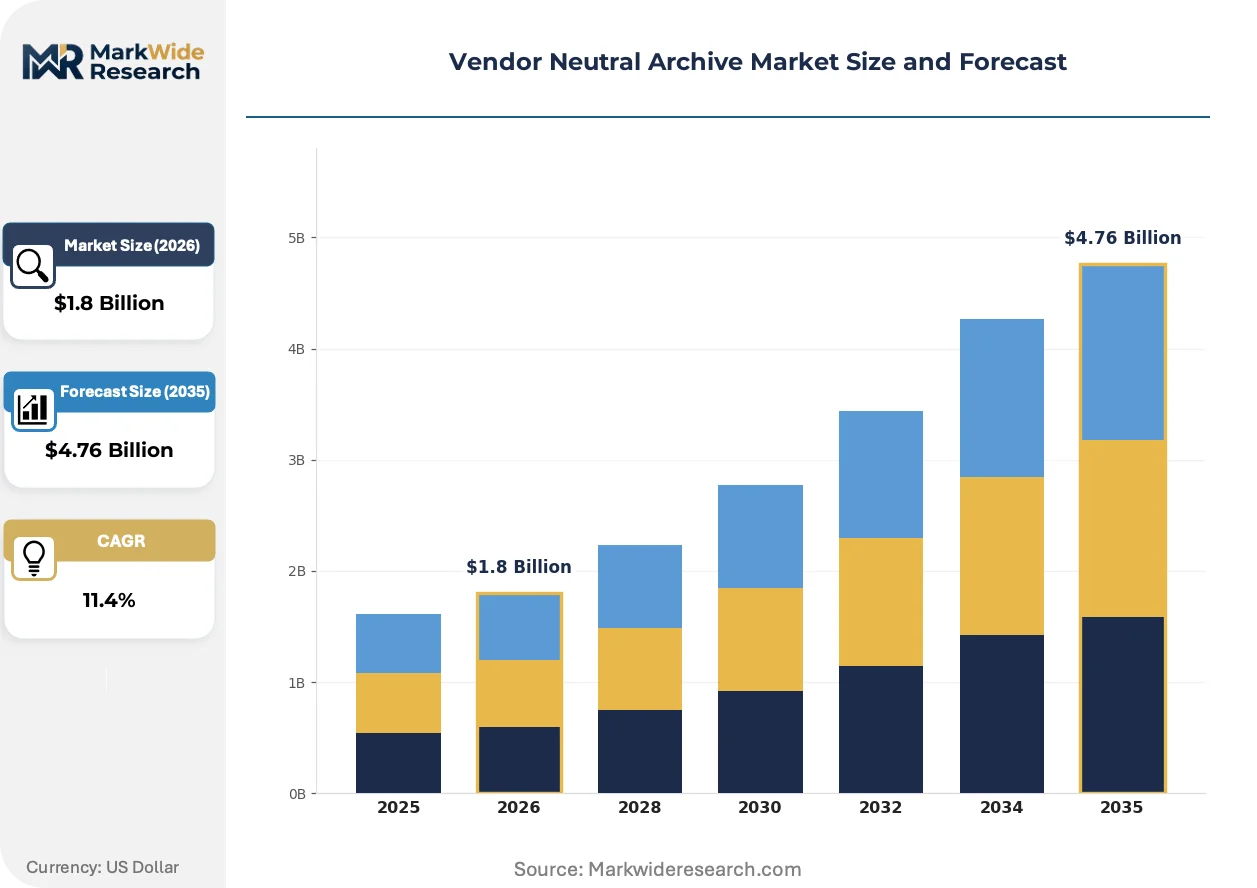
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud Storage, On-Premises Solution, Hybrid Solution, Software Solutions End User: Healthcare Providers, Research Institutions, Government Agencies, Educational Organizations Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Service Type: Data Migration, Backup Services, Archiving Services, Technical Support |
| Companies Covered | Sectra AB, Siemens Healthineers, Agfa Healthcare, Merative, Hyland Software, GE Healthcare, Koninklijke Philips N.V., Canon Medical Systems Corporation, FUJIFILM Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vendor Neutral Archive Market Strategic Shifts
Containerized microservices architectures are displacing monolithic archive software, enabling elastic scaling of ingestion pipelines during peak imaging hours and independent update cycles for security patches.
Software-defined storage with erasure coding is virtualizing the hardware abstraction layer beneath medical imaging repositories. Regional health information exchanges in Germany are deploying these platforms to pool storage resources across competing hospital systems. The approach is virtualizing capital allocation decisions, converting fixed infrastructure into metered utility consumption.
EU AI Act risk classification requirements are reshaping procurement specifications for diagnostic imaging platforms. Archive vendors must now document training data provenance and algorithmic transparency to support downstream AI deployment. European hospital procurement frameworks are embedding these compliance checkpoints into tender evaluation criteria ahead of full enforcement.
Radiology group purchasing organizations are consolidating vendor evaluation authority previously dispersed across individual hospital IT departments. These entities now mandate API-first architectures and cloud portability clauses in multi-year archive agreements. The concentration of buying power is most pronounced in United States integrated delivery networks exceeding ten affiliated hospitals.
Vendor Neutral Archive Market Segmentation
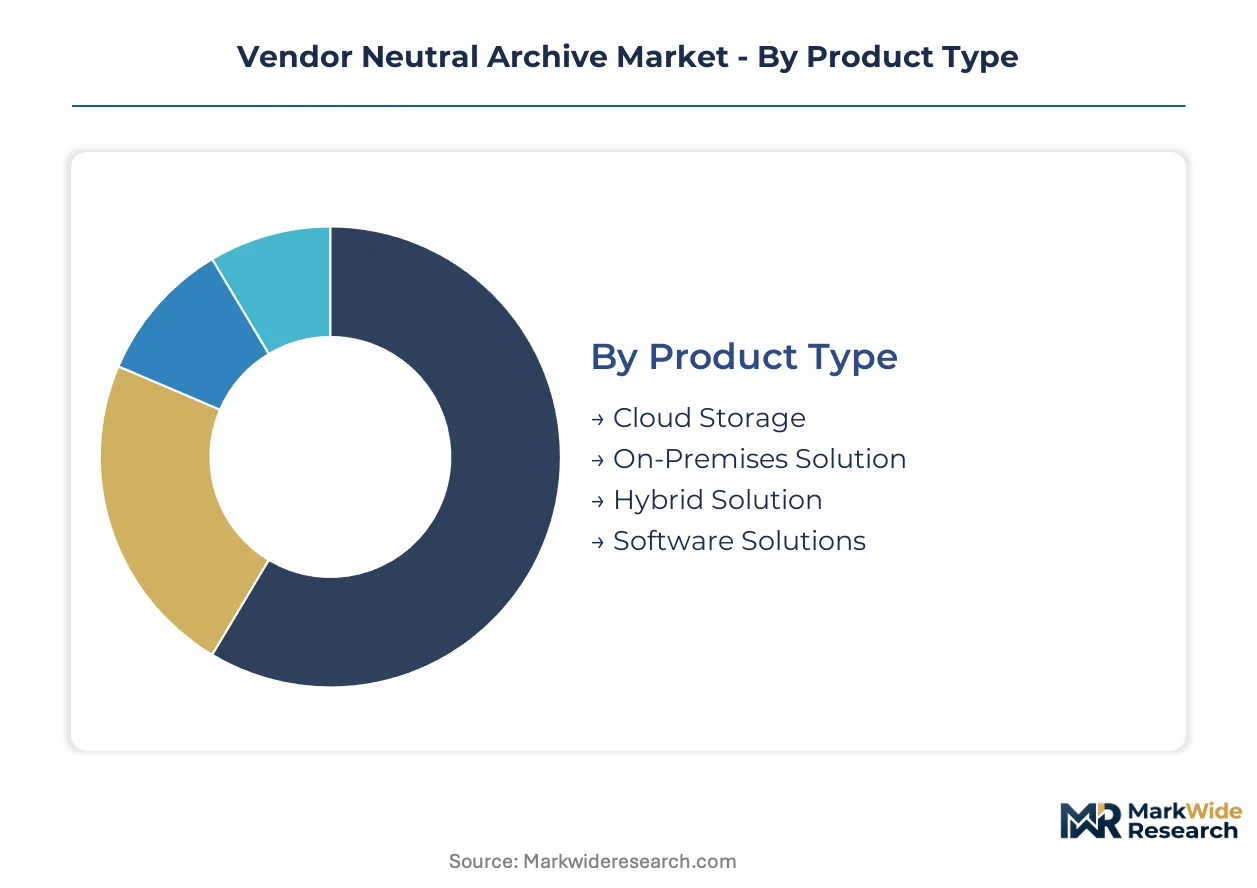
Segmentation in the Vendor Neutral Archive Market reveals distinct procurement patterns across infrastructure maturity levels and organizational risk profiles. Healthcare delivery networks select archive architectures based on capital availability, regulatory jurisdiction, and diagnostic workflow latency requirements.
Product Type:
Mature enterprise storage arrays coexist with emerging cloud-native platforms across the product spectrum.
- Cloud Storage:Fully managed object storage with S3-compatible APIs and automated tiering from hot to cold storage classes. United States integrated delivery networks are consolidating into multi-tenant cloud repositories to eliminate data center capital cycles and satisfy HIPAA Business Associate Agreement requirements for encryption and audit logging.
- On-Premises Solution:Dedicated hardware appliances with software-defined storage controllers deployed within hospital-owned facilities. German university hospitals retain these configurations to satisfy Bundesdatenschutzgesetz data localization mandates and maintain sub-100ms retrieval latency for emergency radiology reads.
- Hybrid Solution:Flash-tier primary storage at radiology workstations coupled with cloud-based disaster recovery replication. Flash arrays handle primary diagnostic reads while glacier-class cloud retention optimizes decade-long imaging obligations.
- Software Solutions:Containerized microservices deployed on customer-managed Kubernetes clusters with erasure-coded redundancy.
On-Premises Solution handles the majority of throughput; Cloud Storage is gaining share fastest.
End User:
Customer archetypes span from high-volume clinical operators to specialized research consumers with distinct governance frameworks.
- Healthcare Providers:Hospital systems and imaging centers requiring 24/7 availability for diagnostic workflows with sub-five-second retrieval SLAs. United States community hospital networks are migrating from departmental PACS to enterprise VNA platforms to consolidate radiology, cardiology, and pathology imaging under unified governance committees.
- Research Institutions:Academic medical centers and pharmaceutical sponsors managing multi-site clinical trial imaging with de-identification pipelines. These entities demand multi-tenant archive configurations with granular access controls for external investigator collaboration.
- Government Agencies:National health services and veterans administration systems with sovereign data requirements.
- Educational Organizations:Medical schools and training hospitals with episodic access patterns and limited retention obligations.
Healthcare Providers command the dominant procurement volume; Research Institutions are expanding most quickly.
Deployment:
Infrastructure location decisions reflect trade-offs between operational control and capital efficiency across the deployment continuum.
- Public Cloud:Shared infrastructure operated by hyperscale providers with consumption-based pricing and automatic redundancy across availability zones. Mid-size United States hospital networks are abandoning owned data centers for public cloud to convert imaging storage from capital expenditure to operational expenditure.
- Private Cloud:Single-tenant virtualized infrastructure hosted in dedicated colocation facilities or on-premises. French hospital networks deploy private cloud configurations to satisfy CNIL guidance on health data processing and maintain direct control over encryption key management.
- Hybrid Cloud:Workload orchestration across on-premises and cloud resources with policy-driven data placement.
- On-Premises:Physical servers and storage arrays within hospital-owned facilities with no external network dependency.
Public Cloud captures the steepest expansion trajectory; Private Cloud retains the highest average contract value.
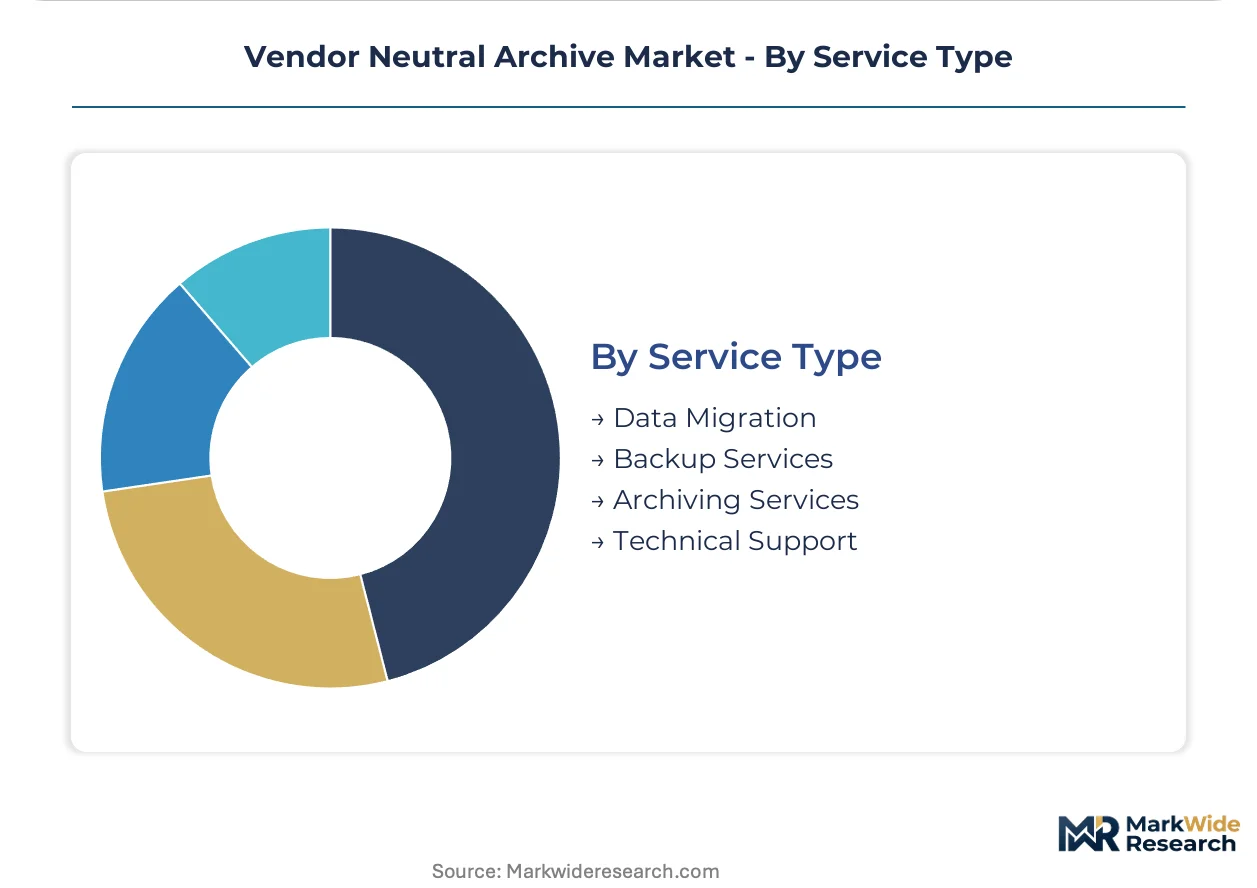
Service Type:
Professional services surrounding archive operations represent margin accretive extensions beyond software licensing.
- Data Migration:Structured extraction from legacy PACS with DICOM normalization and metadata enrichment. Migration projects for decade-old imaging archives require specialized tooling to reconcile DICOM standard version heterogeneity across modalities from multiple manufacturers.
- Backup Services:Immutable snapshot replication with ransomware-resistant air-gapped retention. Healthcare providers in the United States are mandating backup services with isolated recovery environments to satisfy HIPAA security rule contingency planning requirements.
- Archiving Services:Lifecycle management with automated tiering and legal hold capabilities.
- Technical Support:24/7 incident response and software maintenance with guaranteed resolution SLAs.
Data Migration generates the highest project-based revenue; Backup Services are climbing the fastest on recurring contract attach rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health systems in the United States deploy cloud-native archives for multi-site consolidation, while German hospitals retain on-premises infrastructure to satisfy data localization mandates. Japanese academic medical centers pioneer hybrid configurations balancing latency-sensitive diagnostic reads with glacier-class retention economics.
United States
Integrated delivery networks exceeding ten affiliated hospitals mandate API-first architectures and cloud portability clauses in multi-year agreements. HIPAA security rules enforce encryption and access logging specifications that directly shape procurement evaluations. Hospital networks across Texas and Florida are consolidating departmental PACS into enterprise VNA platforms to unify radiology, cardiology, and pathology imaging governance.
Germany
University hospitals in Bavaria and Baden-Württemberg maintain dedicated hardware appliances to satisfy Bundesdatenschutzgesetz data localization requirements and sustain sub-100ms retrieval latency for emergency radiology. Regional health information exchanges deploy software-defined storage to pool resources across competing hospital systems. The EMA's evolving guidance on diagnostic imaging platform validation influences tender specifications for archive software marketed as medical devices.
Japan
Academic medical centers in the Kanto and Kansai regions balance flash-tier primary storage at radiology workstations with cloud-based disaster recovery replication. METI's digital health infrastructure initiatives accelerate decommissioning of siloed departmental imaging systems. Tokyo-area hospital networks are migrating from capital-intensive SAN arrays to subscription-based operational expenditure models for decade-long imaging retention obligations.
United Kingdom
NHS trusts in London and the Southeast evaluate multi-tenant cloud repositories to eliminate data center capital cycles while satisfying national interoperability frameworks. The MHRA's alignment with MDR requirements shapes quality system documentation expectations for archive software deployments. Hospital procurement committees in the Midlands and North England mandate DICOMweb-native architectures to escape proprietary PACS lock-in.
France
Hospital networks deploy private cloud configurations to satisfy CNIL guidance on health data processing and maintain direct control over encryption key management. The EU AI Act's risk classification requirements are embedding compliance checkpoints into tender evaluation criteria ahead of full enforcement. Academic medical centers in Île-de-France and Auvergne-Rhône-Alpes are consolidating fragmented archives into unified repositories with automated lifecycle management.
Vendor Neutral Archive Market Competitive Environment
Capability concentration sits with diagnostic equipment manufacturers possessing embedded installed bases; scale advantage sits with enterprise software vendors offering cross-platform interoperability. The market structures around three tiers: imaging modality manufacturers bundling archive sales with hardware contracts, pure-play software vendors delivering cloud-native platforms, and IT conglomerates integrating storage into broader hospital information systems. Dominant competitive moves include strategic partnerships between archive vendors and AI diagnostic developers, plus portfolio diversification into adjacent clinical data management services.
Among imaging equipment manufacturers, Siemens Healthineers and GE Healthcare exemplify the bundled-archive archetype, leveraging diagnostic installed bases to drive integrated delivery network contracts. Philips occupies a position spanning both equipment and enterprise software vectors through its cloud-native architecture extensions. Within the pure-play software tier, Hyland Software and Merative represent specialists in content management platform expansion into medical imaging repositories.
| Leading Market Players |
|---|
| Sectra AB |
| Siemens Healthineers |
| Agfa Healthcare |
| Merative |
| Hyland Software |
| GE Healthcare |
| Koninklijke Philips N.V. |
| Canon Medical Systems Corporation |
| FUJIFILM Holdings Corporation |
| Others |
Value Chain & Pricing Dynamics
Silicon Valley cloud infrastructure clusters anchor capacity expansion for medical imaging storage, concentrating hyperscale provider leverage over hospital procurement committees negotiating decade-long retention contracts. This geographic concentration of cloud compute and storage resources translates directly into pricing power for subscription-based archive platforms displacing capital-intensive on-premises alternatives.
Pricing Analysis
United States-Germany price spreads exceed thirty percent for equivalent storage tiers, reflecting divergent data localization compliance burdens and cloud egress fee structures. Pricing stratifies across enterprise, mid-market, and community hospital tiers, with HIPAA Business Associate Agreement certification and sub-100ms latency SLAs commanding substantial premiums. Cost compression in mid-market cloud tiers is intensifying as hyperscale providers compete for integrated delivery network consolidation contracts. Community hospital networks exhibit highest price sensitivity, while academic medical centers prioritize latency guarantees over per-terabyte rates.
Supply Chain Analysis
Flash memory modules and software-defined storage controllers feed from Taiwan, South Korea, and United States fabrication facilities into archive hardware assembly. Raw material dependencies span NAND flash wafers, enterprise-grade SSD controllers, and specialized DICOM parsing chipsets. Supply chain risk centers on single-source vulnerability for advanced node semiconductor components subject to export control restrictions. Distribution runs through radiology group purchasing organizations consolidating vendor evaluation authority across multi-hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Data migration and backup services represent the fastest-expanding recurring-revenue layer, outpacing hardware licensing growth as health systems outsource legacy PACS extraction and ransomware-resistant retention to specialized vendors.
For Market Incumbents: Harden cloud-native architecture investments against pure-play software entrants exploiting API-first interoperability mandates from the Office of the National Coordinator for Health IT. Deepen professional services capabilities in FDA 21 CFR Part 820 validation documentation to capture adjacent quality system demand. Vertical integration into AI diagnostic workflow layers defends against algorithmic fragmentation undermining neutral archive value propositions. For New Entrants and Emerging Players: Pursue research institution multi-tenant configurations serving pharmaceutical clinical trials, an underpenetrated segment with distinct governance frameworks and higher margin tolerance than healthcare delivery networks. Target mid-size United States community hospital networks abandoning owned data centers for subscription-based operational expenditure models. Lead with edge-to-cloud tiering architectures addressing latency-sensitive primary reads while optimizing long-term retention economics. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-utility play because medical imaging retention obligations span patient lifetimes, creating predictable recurring revenue streams resistant to cyclical healthcare expenditure cuts. Acquisition targets should display containerized microservices architectures enabling elastic scaling and independent security patch cycles. Watch for inflection when radiology group purchasing organization consolidation exceeds fifty percent of United States hospital procurement volume.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Enables HIPAA-compliant multi-tenant architectures for integrated delivery networks consolidating fragmented PACS. |
| AI Workflow Integration Partnership | Prevents proprietary diagnostic algorithms from creating new data silos undermining neutral archive value. |
| FDA Validation Services Expansion | Captures adjacent professional services demand from archive software marketed as medical devices. |
| Edge-to-Cloud Tiering Architecture | Balances sub-five-second retrieval SLAs for emergency radiology with glacier-class retention economics. |
| Research Institution Multi-Tenancy | Opens pharmaceutical clinical trial imaging revenue beyond traditional healthcare delivery margins. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital purchasing committee members, radiology department heads, biomedical engineers, and GPO contracts managers, cross-referenced against secondary sources including FDA 510(k) filings, hospital procurement databases, CMS Medicare imaging expenditure data, and DICOM standard committee documentation. Bottom-up triangulation of vendor shipment data with top-down health system IT budget allocations validated market sizing.
Calibration against historical cloud storage adoption curves in adjacent healthcare IT segments anchored growth trajectory assumptions across the projection horizon. Segmentation modeling spanned deployment model, organization size, diagnostic workflow latency requirements, and regional regulatory cluster. CAGRs were derived from logistic diffusion curves fitted to infrastructure replacement cycle data, incorporating HIPAA data retention mandate compliance deadlines and DICOMweb standard adoption rates as structural accelerants.
Sensitivities concentrate around cloud egress fee volatility and legacy PACS depreciation schedule delays at academic medical centers. Cross-checking against hyperscaler healthcare vertical revenue disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Brazil Computed Tomography Market
Medical Imaging
Global Mammography Systems Market
Medical Imaging
Global Orthopedic Imaging Equipment Market
Medical Imaging
Nuclear Medicine Software Market
Medical Imaging
Saudi Arabia Diagnostic Imaging Market
Medical Imaging
Global Electroretinography Market
Medical Imaging
Republic of Ireland (ROI) and Northern Ireland MRI and CT Scan Radiology Services Market
Medical Imaging
Medical Image Exchange System Market
Medical Imaging
Canada Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Global Micro-Ultrasound Systems Market
Medical Imaging
Handheld Dental X-Ray Systems Market
Medical Imaging
Industrial X-Ray Machine Market
Medical Imaging
Treatment Planning Systems and Advanced Image Processing Market
Medical Imaging
Global MRI Scanner Market
Medical Imaging
Global 3D Ultrasound Market
Medical Imaging
South America Nuclear Imaging Market