
 North America Fluoroscopy Market | 2026-2036
North America Fluoroscopy Market Size, Share, and Industry Trends Forecast 2026-2036
North America Fluoroscopy Market Insights
The FDA's Medical Device Regulation is restructuring capital deployment timelines for fluoroscopy OEMs. Siemens Healthineers leverages its installed base of angiography-fluoroscopy hybrids to sustain service revenue streams across integrated delivery networks. GE Healthcare anchors its North American position through backward integration into detector manufacturing, while Canon Medical Systems Corporation competes on image-processing software differentiation.
Fluoroscopy denotes real-time X-ray imaging using continuous radiation exposure to visualize dynamic physiological processes, typically operating at 30 frames per second with dose rates measured in air kerma. The technology enables interventional guidance during cardiac catheterization, orthopedic fixation, and gastrointestinal contrast studies. Mobile C-Arms command the largest revenue share within product type segmentation due to their deployment flexibility across hybrid operating rooms. Digital fluoroscopy technology leads the technology dimension, displacing analog architectures as hospitals prioritize DICOM-integrated workflow and automated dose tracking. Pain management applications represent the fastest-expanding application segment as ambulatory surgery centers expand image-guided injection volumes.
The FDA, alongside Health Canada and the Centers for Medicare & Medicaid Services, shapes market access through radiation safety standards, reimbursement coding, and equipment accreditation requirements. CMS physician fee schedule adjustments directly influence capital purchase cycles by altering the economic returns on fluoroscopy-assisted procedures. Stakeholders must monitor how state-level certificate-of-need regulations evolve as health systems seek to centralize high-volume interventional suites.
Market Dynamics
Orthopedic surgical suites across Texas and California health networks are consolidating fluoroscopy procurement at the system level, compressing vendor negotiation cycles and elevating equipment standardization requirements.
Growth Catalysts
- CMS physician fee schedule adjustments:Reimbursement coding changes for image-guided procedures directly accelerate capital purchase cycles in ambulatory surgery centers.
- Pain management volume expansion:Epidural steroid injections and nerve blocks now require real-time visualization, pulling mobile C-Arms into outpatient settings.
- Digital detector technology:Flat-panel replacements for image intensifiers reduce dose exposure while enabling DICOM-integrated workflow automation.
Market Restraints
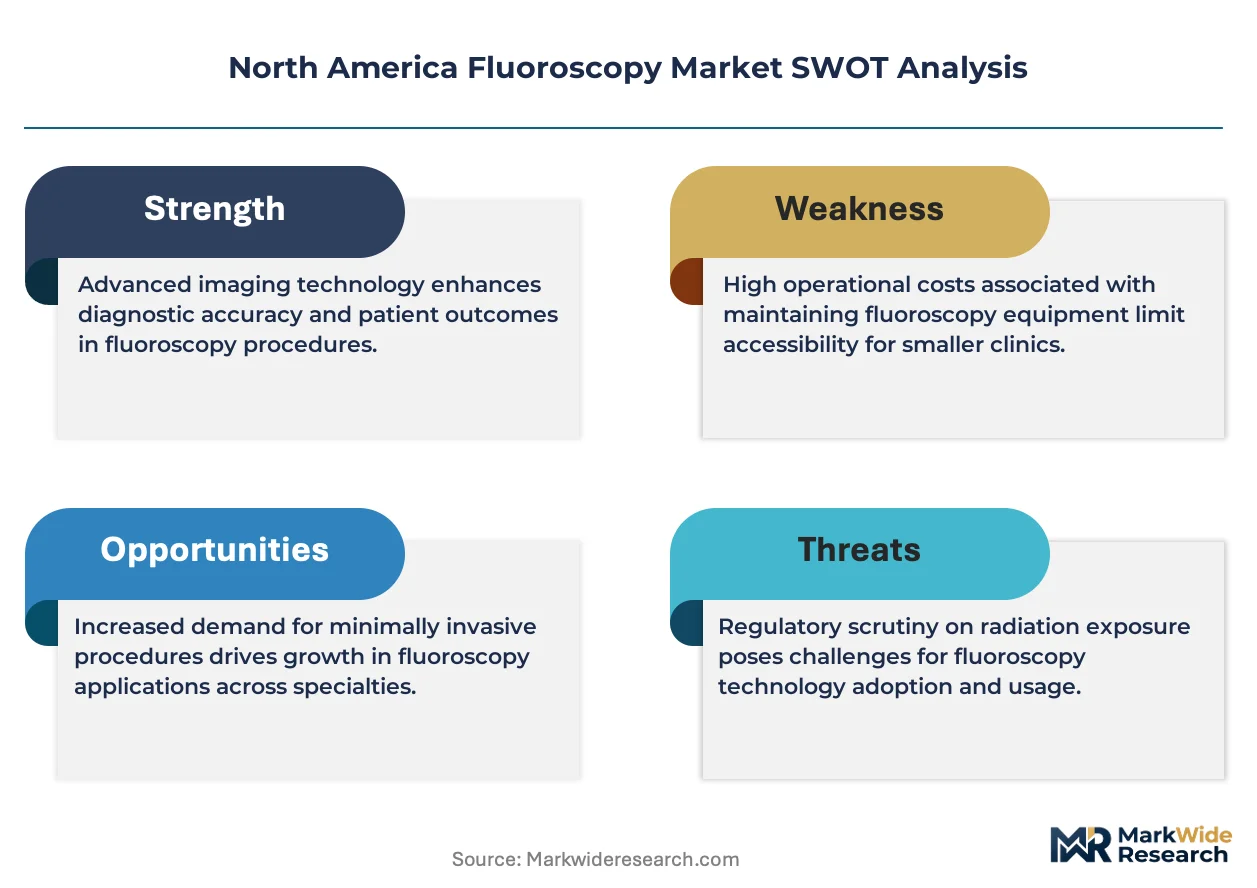
- FDA Medical Device Regulation compliance costs:Radiation dose reporting mandates under the strengthened framework extend product development timelines and certification expenses.
- Flat-panel detector supply concentration:Manufacturing of amorphous silicon arrays concentrates in East Asian foundries, creating input vulnerability for North American OEMs.
- Analog system installed base:Legacy equipment in rural hospitals and smaller imaging centers delays full digital conversion and service revenue capture.
Strategic Opportunities
- Texas health network consolidation:System-level procurement at HCA Houston Healthcare and Baylor Scott & White creates multi-hospital contract leverage points for integrated service agreements.
- AI-enabled dose optimization:Machine learning algorithms for automatic exposure control converge with real-time image enhancement to differentiate premium system tiers.
- Ambulatory surgery center expansion:Certificate-of-need relaxation in several states enables de novo facility construction with bundled equipment financing.
Industry Challenges
- Medical physicist staffing shortages:Qualified professionals for equipment acceptance testing and annual compliance surveys are scarce in secondary metropolitan markets.
- Legacy PACS integration complexity:Digital fluoroscopy systems must interface with decade-old hospital IT architectures, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Fluoroscopy Market |
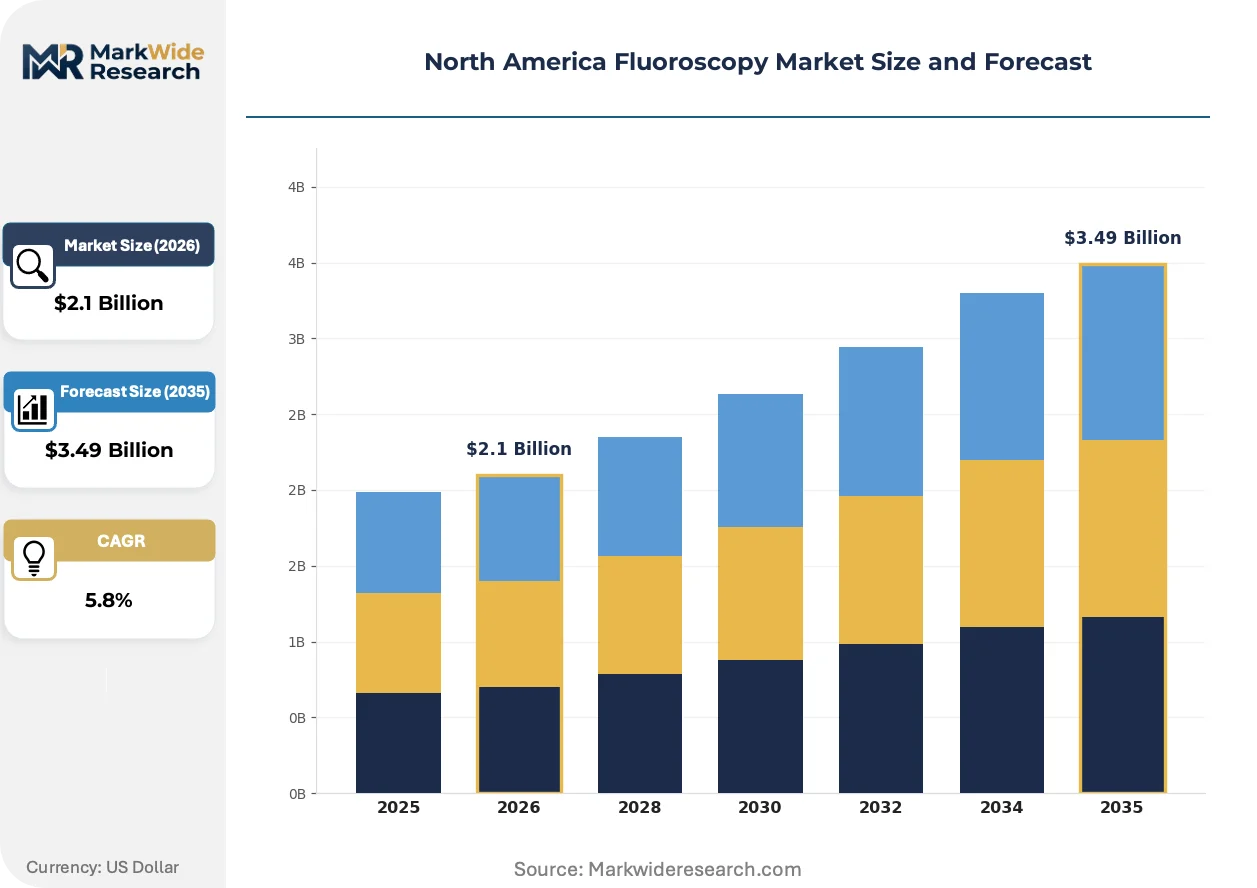
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Fluoroscopy Systems, Mobile Fluoroscopy Systems, C-Arms, Table-Top Fluoroscopy Application: Cardiology, Gastroenterology, Orthopedics, Pain Management End User: Hospitals, Outpatient Clinics, Diagnostic Centers, Research Laboratories Technology: Digital Fluoroscopy, Analog Fluoroscopy, Hybrid Systems, Real-Time Imaging |
| Companies Covered | GE Healthcare, Siemens Healthineers, Canon Medical Systems Corporation, Koninklijke Philips NV, Carestream Health, Hologic Inc, Shimadzu Medical, Orthoscan Inc, Fujifilm Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Fluoroscopy Market Trends and Innovations
Real-time imaging architectures are converging with surgical navigation and dose-tracking software, compressing the functional boundary between diagnostic and interventional platforms.
Flat-panel detector technology is unifying image acquisition across fixed angiography suites and mobile C-Arms. Texas Medical Center hospitals are deploying these systems in hybrid operating rooms at accelerated replacement cycles. This convergence is compressing the price-performance gap between premium fixed installations and mid-tier mobile units.
The FDA's renewed scrutiny of radiation dose reporting under its Medical Device Regulation framework is mandating automated air kerma tracking and structured dose archives. Manufacturers must embed compliance documentation into system firmware before market authorization. Cardiac catheterization labs in California face the steepest adaptation curve due to higher procedure volumes and prior manual reporting workflows.
Health system procurement committees now bundle fluoroscopy acquisitions with multi-year service contracts and training commitments. Integrated delivery networks in California are displacing standalone capital purchases with performance-based equipment utilization agreements. This shift is most visible at Kaiser Permanente and Sutter Health, where standardization across 20-plus facilities drives vendor selection criteria.
North America Fluoroscopy Market Segmentation
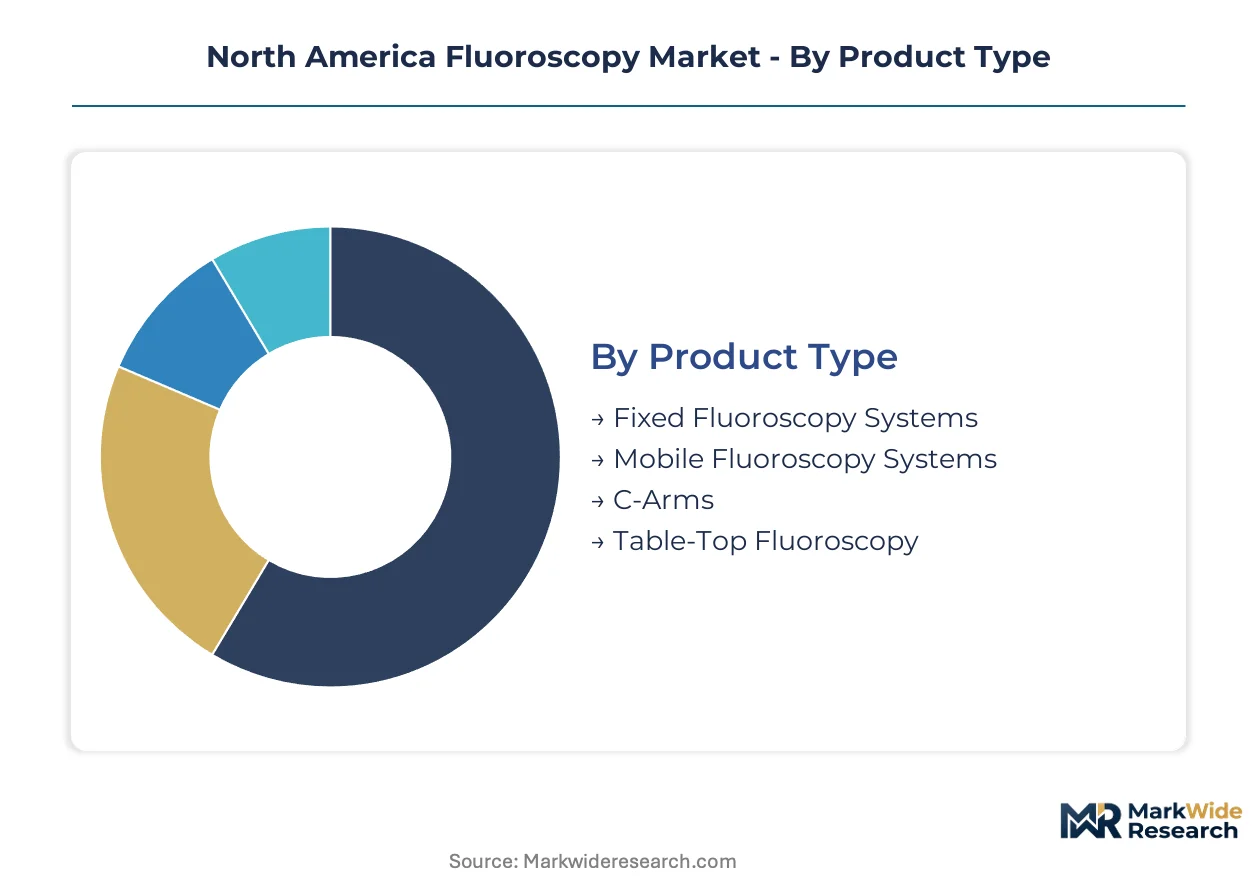
Capital allocation across fluoroscopy segments varies dramatically based on installation permanence and detector sophistication. Procurement committees weigh upfront equipment costs against service revenue potential and replacement cycle frequency.
Product Type:
Capital-intensity stratification separates fixed installations requiring structural room modifications from deployable platforms with lower site preparation costs.
- Mobile Fluoroscopy Systems:Deployable units with motorized positioning and battery-backed operation enable rapid redeployment across surgical suites. Texas health networks including HCA Houston Healthcare are standardizing on mobile platforms to maximize utilization rates across hybrid operating rooms.
- C-Arms:Arc-shaped gantry configurations with isocentric rotation deliver multi-planar imaging without patient repositioning. California ambulatory surgery centers are pulling C-Arms into outpatient settings for image-guided spine and pain management procedures.
- Fixed Fluoroscopy Systems:Ceiling-mounted or floor-anchored installations with integrated patient tables command premium pricing for cardiac catheterization labs.
- Table-Top Fluoroscopy:Compact units for gastrointestinal and urological examinations occupy lower price tiers with reduced detector coverage areas.
Mobile systems absorb the bulk of installed capacity; C-Arms are expanding most quickly across outpatient settings.
Application:
Procedure reimbursement rates and volume growth trajectories determine which clinical specialties drive equipment procurement cycles.
- Pain Management:Epidural steroid injections, nerve blocks, and vertebroplasty now mandate real-time visualization for safety and precision. Ambulatory surgery centers in California and Texas are expanding dedicated pain suites with C-Arm fluoroscopy to capture shifted volumes from hospital-based settings.
- Orthopedics:Intraoperative guidance for fracture fixation, joint replacement, and spinal instrumentation requires high-resolution bone visualization with low soft-tissue contrast. Texas Medical Center hospitals are deploying hybrid operating rooms with integrated fluoroscopy for complex trauma cases.
- Cardiology:Coronary angiography and electrophysiology procedures depend on fixed angiography-fluoroscopy hybrids with advanced roadmapping capabilities.
- Gastroenterology:Barium studies and therapeutic endoscopy utilize lower-dose fluoroscopy with specialized contrast delivery systems.
Cardiology maintains the largest installed base; pain management is climbing the fastest as outpatient migration accelerates.
End User:
Procurement authority and financing mechanisms diverge sharply between consolidated health systems and independent facility operators.
- Hospitals:Integrated delivery networks in California and Texas leverage multi-facility contracts to standardize equipment platforms and service agreements. Kaiser Permanente and Sutter Health are displacing standalone capital purchases with performance-based utilization agreements across 20-plus facilities.
- Outpatient Clinics:Freestanding ambulatory surgery centers face compressed capital cycles tied to certificate-of-need regulations and bundled procedure financing.
- Diagnostic Centers:Independent imaging facilities prioritize throughput optimization and rapid patient turnaround for contrast-based studies.
- Research Laboratories:Academic medical centers demand advanced imaging capabilities for interventional device development and preclinical validation.
Hospitals command the dominant share of capital deployment; outpatient clinics are gaining share fastest as site-of-care shifts accelerate.
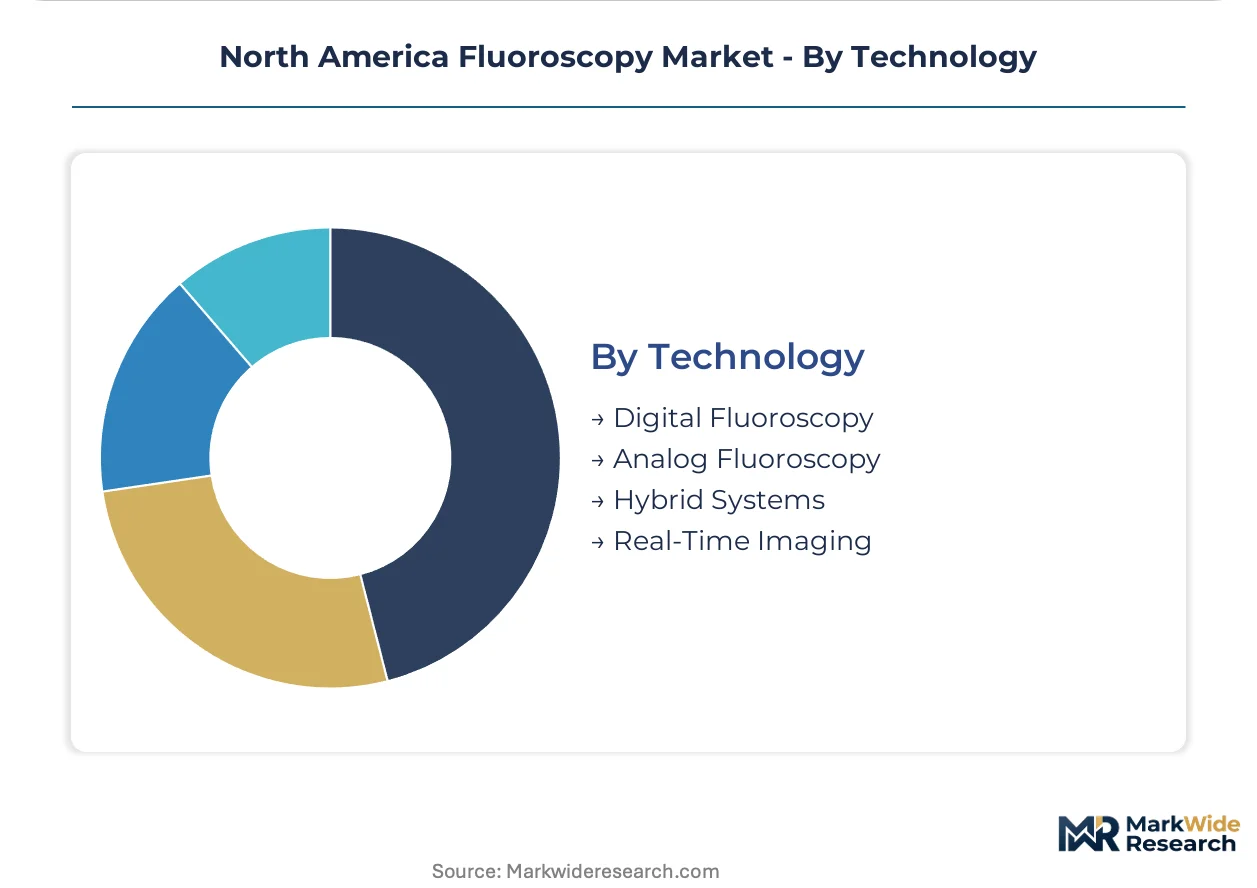
Technology:
Detector architecture and dose-tracking capabilities now determine regulatory compliance posture and workflow integration potential.
- Digital Fluoroscopy:Flat-panel detector arrays with amorphous silicon or cesium iodide scintillation layers deliver DICOM-integrated image distribution and automated exposure control. FDA radiation dose reporting mandates under the Medical Device Regulation framework are accelerating displacement of analog architectures.
- Hybrid Systems:Converged diagnostic-interventional platforms combine fluoroscopy with CT or MRI navigation for complex electrophysiology and oncology procedures. Texas Medical Center deployments are compressing replacement cycles for these premium installations.
- Analog Fluoroscopy:Image intensifier-based systems with video camera chains persist in rural hospitals and smaller imaging centers where capital constraints delay full digital conversion.
- Real-Time Imaging:Sub-second latency architectures with 30 frames-per-second acquisition enable dynamic physiological visualization for interventional guidance.
Digital fluoroscopy holds the overwhelming installed base; hybrid systems are expanding at the steepest trajectory as surgical navigation converges with real-time imaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas Medical Center and California health networks anchor North American fluoroscopy demand through system-level procurement consolidation. Integrated delivery networks leverage multi-facility contracts to standardize equipment platforms across hybrid operating rooms. FDA radiation dose reporting mandates under the Medical Device Regulation framework reshape compliance timelines for manufacturers serving both markets.
United States
Kaiser Permanente and Sutter Health displace standalone capital purchases with performance-based utilization agreements spanning twenty-plus facilities. CMS physician fee schedule adjustments directly accelerate capital purchase cycles in ambulatory surgery centers. Texas Medical Center hospitals deploy hybrid operating rooms with integrated fluoroscopy for complex trauma cases at accelerated replacement cycles.
California
Cardiac catheterization labs face the steepest adaptation curve for FDA radiation dose reporting mandates due to higher procedure volumes. Ambulatory surgery centers expand dedicated pain suites with C-Arm fluoroscopy to capture shifted volumes from hospital-based settings. The San Francisco Bay Area and Los Angeles health networks concentrate procurement authority for system-wide equipment standardization.
Texas
HCA Houston Healthcare and Baylor Scott & White create multi-hospital contract leverage points for integrated service agreements. Certificate-of-need relaxation enables de novo ambulatory surgery center construction with bundled equipment financing. The Texas Medical Center cluster compresses vendor negotiation cycles through consolidated imaging procurement at the system level.
Canada
Health Canada radiation safety standards elevate compliance documentation requirements for equipment market authorization. Provincial health authorities in Ontario and Quebec centralize procurement for angiography-fluoroscopy hybrids across academic medical centers. Vancouver and Toronto hospital networks prioritize DICOM-integrated workflow automation in digital fluoroscopy replacements.
North America Fluoroscopy Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the North American fluoroscopy market. The vendor base stratifies into three tiers: integrated imaging conglomerates with installed base leverage, detector technology specialists with upstream manufacturing control, and regional equipment fabricators with service localization advantages. Dominant competitive moves include backward integration into detector manufacturing and multi-year service contract bundling with capital acquisitions.
Among diversified imaging conglomerates, GE Healthcare and Siemens Healthineers occupy positions defined by installed base scale and hybrid system portfolios. Canon Medical Systems Corporation represents the imaging technology specialist archetype with software differentiation strategies. These three companies exemplify how market positioning converges on integrated service revenue streams and detector supply chain control.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Canon Medical Systems Corporation |
| Koninklijke Philips NV |
| Carestream Health |
| Hologic Inc |
| Shimadzu Medical |
| Orthoscan Inc |
| Fujifilm Healthcare |
| Others |
Pricing and Supply Chain Analysis
Integrated delivery networks in California and Texas anchor procurement volume, compressing vendor margins through multi-hospital performance-based utilization agreements that bundle equipment with multi-year service commitments.
Pricing Analysis
Short lead-time premiums for flat-panel detector arrays command pricing advantages over standard procurement cycles, with OEMs passing through expedited logistics costs to hospital systems facing accelerated replacement timelines. Three-tier pricing structure across premium, standard, and economy levels separates hybrid angiography-fluoroscopy systems from mobile C-Arms and tabletop units, with price differentiation resting on detector resolution grade and FDA 510(k) clearance tier. Cost compression in mid-tier mobile systems is intensifying because Texas health networks are standardizing platforms across 20-plus facilities, squeezing per-unit margins. Ambulatory surgery centers exhibit highest price sensitivity due to certificate-of-need capital constraints, while cardiac catheterization labs absorb premium pricing for dose-tracking compliance features.
Supply Chain Analysis
Transpacific freight volatility from East Asian component hubs elevates landed costs for amorphous silicon detector arrays and cesium iodide scintillation layers. Manufacturing concentrates in South Korea, Taiwan, and Japan for flat-panel substrates, while North American OEMs source X-ray tube assemblies from Germany and Japan. Raw material dependencies include rare earth phosphors, high-purity silicon wafers, and precision bearings for isocentric gantry rotation. Single-source vulnerability for amorphous silicon backplanes creates supply continuity exposure during foundry allocation cycles. Distribution runs through manufacturer-direct sales organizations serving integrated delivery networks, with regional service subsidiaries handling installation and preventive maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flat-panel detector foundry capacity constraints prop pricing power for OEMs with captive supply arrangements, insulating premium system tiers from cost pass-through pressures.
For Market Incumbents: Anticipate margin compression in mobile C-Arm segments as Texas and California health networks consolidate procurement authority across 20-plus facilities, forcing standardization discounts. Defensive positioning requires backward integration into detector manufacturing or exclusive long-term supply agreements with East Asian foundries. Priority investment in AI-enabled dose optimization software differentiates premium tiers from emerging competitors with hardware-only portfolios. For New Entrants and Emerging Players: Capture ambulatory surgery center expansion in certificate-of-need relaxation states, where bundled equipment financing gaps create white-space for mid-tier mobile systems with simplified service contracts. The most penetrable segment lies in pain management suites requiring basic C-Arm functionality without hybrid angiography integration. Go-to-market execution through GPO contracts managers bypasses direct hospital procurement committee barriers. For Investors and Strategic Acquirers: The window for entry favors detector technology specialists with upstream manufacturing control and software-enabled service revenue streams. Long-term viability hinges on consolidation plays in a market where installed base scale determines service contract profitability. Watch FDA Medical Device Regulation enforcement intensity as the inflection signal for compliance cost barriers favoring scaled incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for Dose-Tracking Software | Automated air kerma reporting satisfies Medical Device Regulation mandates before market authorization. |
| Hospital System Partnership | Multi-facility performance agreements with Kaiser Permanente or Sutter Health lock in replacement cycles. |
| Backward Integration into Detector Manufacturing | Captive amorphous silicon array production insulates GE Healthcare from East Asian foundry allocation cycles. |
| Software Companion Development | AI-enabled exposure control algorithms differentiate premium hybrid systems from mid-tier mobile units. |
| Reimbursement Strategy | CMS physician fee schedule alignment accelerates capital purchase cycles in ambulatory surgery centers. |
Research Methodology
Multi-period observation of hospital procurement database trends, CMS reimbursement coding changes, and FDA 510(k) clearance timelines anchored the trend analysis, supplemented by interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and medical physicists across California, Texas, and Ontario health networks. Secondary validation drew from FDA Medical Device Reporting databases, Health Canada radiation safety filings, CMS Medicare cost reports, and SEC 10-K disclosures from diversified imaging conglomerates. Bottom-up equipment shipment tracking across mobile C-Arm, fixed angiography, and hybrid system categories triangulated against top-down health system capital expenditure surveys.
Segment-weighting approaches distributed total market value across product type, application, end user, and technology dimensions, with detector architecture and dose-tracking capability serving as cross-cutting classification variables. CAGRs were derived from logistic diffusion curves modeling digital fluoroscopy displacement of analog installed bases, calibrated against historical replacement cycles in cardiac catheterization labs and hybrid operating rooms. Procedure volume trajectories for pain management, orthopedics, and cardiology applications informed demand-side elasticity estimates.
The model holds under stable FDA Medical Device Regulation enforcement and continued certificate-of-need relaxation in target states; deviation in tariff regimes for East Asian detector components or sudden CMS reimbursement cuts would shift capital purchase cycle timing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Argentina Mammography Market
Medical Imaging
Asia-Pacific Digital X-Ray Devices Market
Medical Imaging
US Gadolinium-Based Contrast Media Market
Medical Imaging
US Contrast Media Market
Medical Imaging
Mexico Mammography Market
Medical Imaging
Mobile Tomography Market
Medical Imaging
Global Medical Image Management Market
Medical Imaging
United States Diagnostic Imaging Market
Medical Imaging
United Kingdom Diagnostic Imaging Equipment Market
Medical Imaging
Global Veterinary CT Scanner Market
Medical Imaging
Portable Cardiology Ultrasound Systems Market
Medical Imaging
Teleultrasound System Market
Medical Imaging
Angiography Imaging Systems Market
Medical Imaging
X-Ray Flat Panel Detectors Market
Medical Imaging
Ultrasound Market
Medical Imaging
Non-Invasive Coronary Imaging Market