
 Small Animal Imaging (in-Vivo) Market | 2026-2036
Small Animal Imaging (in-Vivo) Market Size, Share, and Industry Trends Forecast 2026-2036
Small Animal Imaging (in-Vivo) Market Analysis
The small animal imaging sector is pivoting around a widening gap between premium multimodal systems and commodity optical platforms. Bruker Corporation leverages its cryogen-free MRI portfolio to dominate high-end preclinical installations. PerkinElmer, Inc. competes through integrated optical-bioluminescence workflows that sustain recurring reagent revenue. Thermo Fisher Scientific Inc. anchors its position with radiography suites bundled into pharmaceutical CDMO partnerships.
Small animal in-vivo imaging encompasses non-invasive visualization technologies applied to rodent and other small-species models, typically achieving spatial resolutions from micrometers to sub-millimeters depending on modality. These systems enable longitudinal disease monitoring, pharmacokinetic tracing, and efficacy validation before human trials. Optical imaging leads current installed base volume due to lower capital thresholds and compact footprints, though micro PET segments capture disproportionate margin pools from radioisotope-dependent service contracts. MRI systems represent the fastest-growing product category as cryogen-free superconducting designs reduce facility infrastructure barriers.
FDA 21 CFR Part 11 and EMA Good Laboratory Practice standards shape data integrity requirements that determine system qualification burdens and software validation costs for vendors. EPA and NRC oversight of radioisotope handling further constrains micro PET and micro CT deployment to licensed institutional sites. Stakeholders must monitor evolving FDA guidance on AI-enabled image reconstruction algorithms, as regulatory clarity on machine-learning diagnostic outputs will determine next-generation platform qualification timelines and competitive differentiation.
Market Dynamics
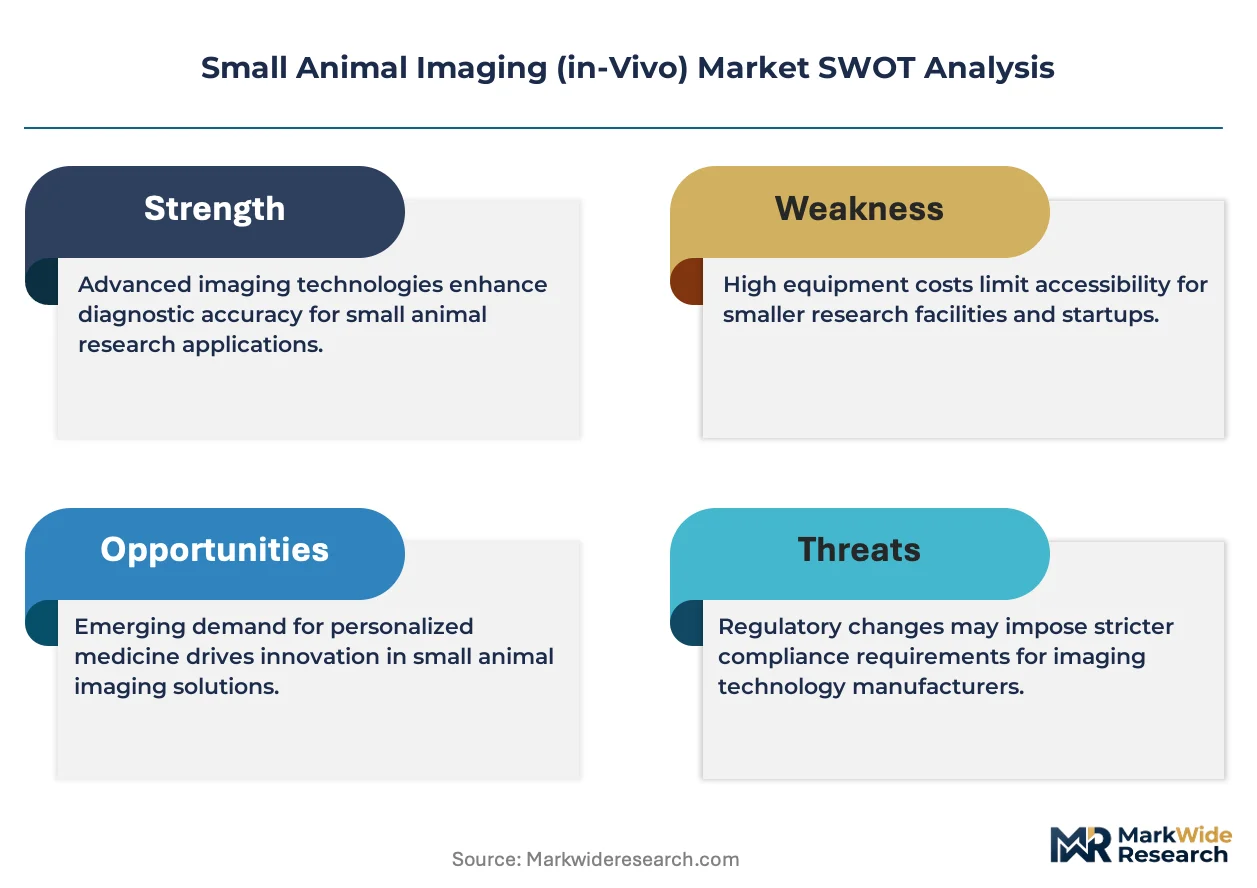
Preclinical imaging vendors face a bifurcation pressure between cryogen-free MRI platforms that reduce facility overhead and optical systems competing on reagent-attach revenue. FDA 21 CFR Part 11 compliance costs now determine vendor qualification timelines and customer switching thresholds.
Growth Catalysts
- NIH Translational Research Funding:Sustained federal appropriations for rodent model studies in the United States drive replacement cycles for aging optical installations. Academic medical centers prioritize multimodal suites that satisfy grant reviewer expectations for longitudinal data integrity.
- Cryogen-Free Superconducting Designs:Elimination of liquid helium dependency reduces site preparation costs and expands MRI addressability to mid-tier pharmaceutical contract research organizations. Vendors report shortened sales cycles where infrastructure barriers previously stalled procurement.
- EMA Good Laboratory Practice Harmonization:Standardized data integrity requirements across European member states reduce vendor validation burden for multi-site preclinical trials. Pharmaceutical sponsors consolidate vendor lists to platforms pre-qualified under mutual recognition agreements.
Market Restraints
- Radioisotope Supply Concentration:Molybdenum-99 production concentrates in aging research reactors in Canada and the Netherlands. Micro PET operators face scheduling volatility that compresses scanner utilization rates and extends study timelines.
- Capital Intensity of Multimodal Suites:Combined MRI-PET-CT installations require shielded suites exceeding standard laboratory construction budgets. Mid-sized biotechnology firms defer purchases or outsource imaging to specialized contract research organizations.
- NRC Licensing Friction:United States institutions face protracted approval cycles for radiopharmaceutical handling. Site-specific radiation safety committees impose additional validation layers that delay operational startup by quarters.
Strategic Opportunities
- AI-Enabled Image Reconstruction:Machine learning algorithms promise scan-time reduction and motion-correction capabilities. FDA guidance clarity on algorithm validation will determine which vendors qualify next-generation platforms first.
- India Preclinical Services Outsourcing:Cost arbitrage attracts pharmaceutical sponsors seeking GLP-compliant imaging at reduced per-study expense. Domestic contract research organizations invest in optical and micro CT capacity to capture this demand migration.
- Integrated Bioluminescence-Reagent Workflows:Per-subject luciferin consumption generates recurring revenue streams that offset capital equipment margin compression. Vendors bundle substrate supply contracts with hardware leases to lock customer lifetime value.
Industry Challenges
- Multimodality Data Fusion Expertise:Cross-platform image registration requires computational biology skill sets scarce in standard veterinary pathology departments. Institutions compete for trained personnel who can operate MRI, PET, and optical pipelines within unified analytical frameworks.
- Legacy System Integration:Pharmaceutical sponsors maintain decade-old optical installations with proprietary data formats. New platform procurement demands expensive migration tools or parallel validation studies that duplicate animal usage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Animal Imaging (in-Vivo) Market |
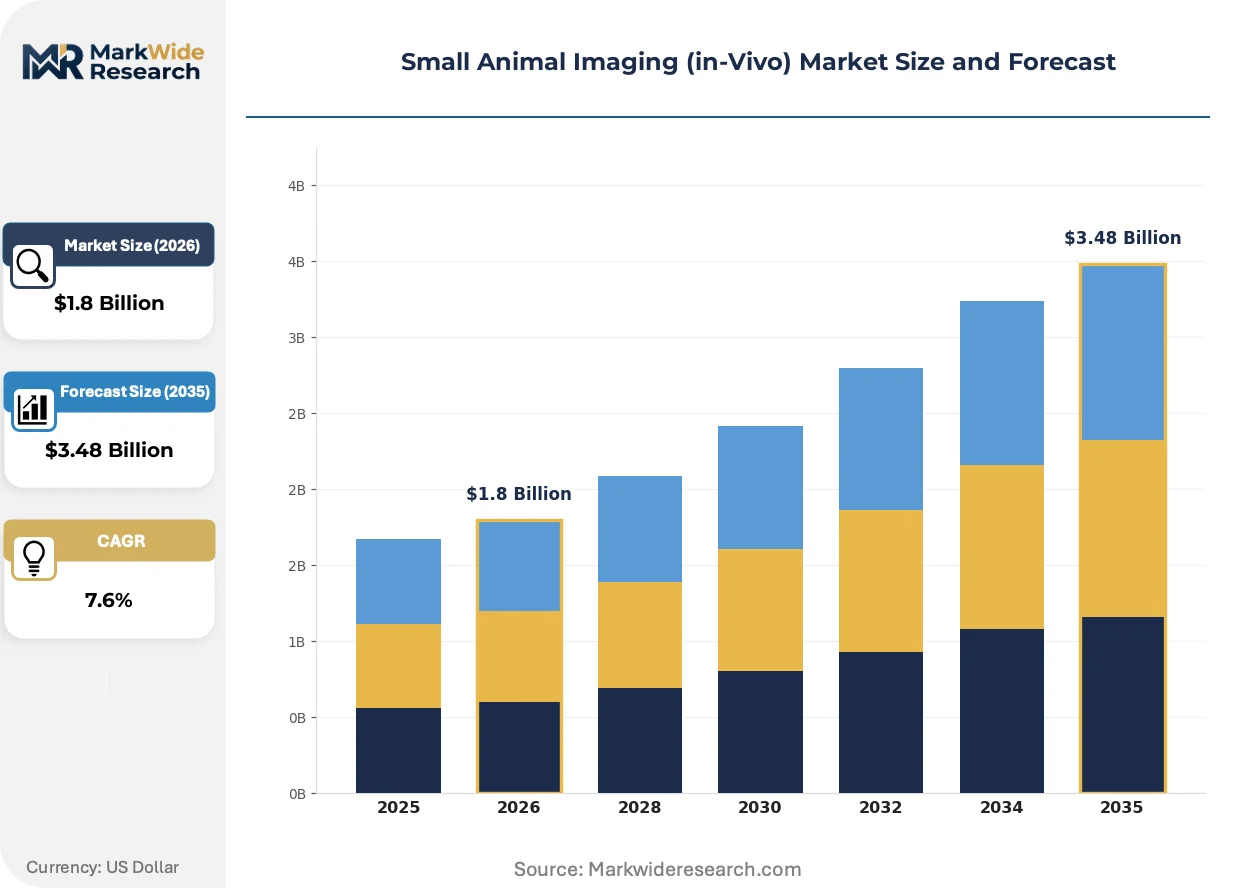
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Micro CT, Micro PET, MRI Systems, Optical Imaging End User: Research Institutions, Pharmaceutical Companies, Academic Institutions, Contract Research Organizations Technology: Bioluminescence, Fluorescence, Radiography, Magnetic Resonance Application: Oncology Research, Cardiovascular Studies, Neurological Investigations, Drug Development |
| Companies Covered | Bruker Corporation, PerkinElmer, Inc., FUJIFILM Holdings Corporation, Miltenyi Biotec, Aspect Imaging Ltd., Mediso Ltd., Thermo Fisher Scientific Inc., Promega Corporation, LI-COR Biosciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Animal Imaging (in-Vivo) Market Emerging Trajectories
Preclinical imaging hardware is absorbing computational methods that previously operated as post-processing software. This integration is compressing study timelines and altering vendor competitive differentiation.
Cryogen-free superconducting MRI systems are converging with compact footprint designs that fit standard laboratory spaces without structural modification. Pharmaceutical contract research organizations in the United States and Germany are adopting these platforms to avoid dedicated magnet rooms. This convergence is displacing permanent magnet MRI from mid-market consideration and consolidating high-field capability among vendors with helium-free intellectual property.
FDA draft guidance on AI-enabled medical devices is extending to preclinical imaging reconstruction algorithms. Vendors must now submit validation packages demonstrating algorithm performance across diverse rodent models and disease indications. Micro PET segments face the steepest compliance burden due to quantitative tracer kinetic modeling requirements, while optical imaging vendors exploit regulatory ambiguity to accelerate feature releases.
Pharmaceutical sponsors are unbundling imaging services from traditional contract research organization relationships. Dedicated preclinical imaging specialists now compete for study placement through fee-for-service portals that disclose real-time scanner availability. This channel disintermediation concentrates in the United States and United Kingdom where sponsor procurement functions maintain approved vendor databases with dynamic pricing visibility.
Small Animal Imaging (in-Vivo) Market Segmentation
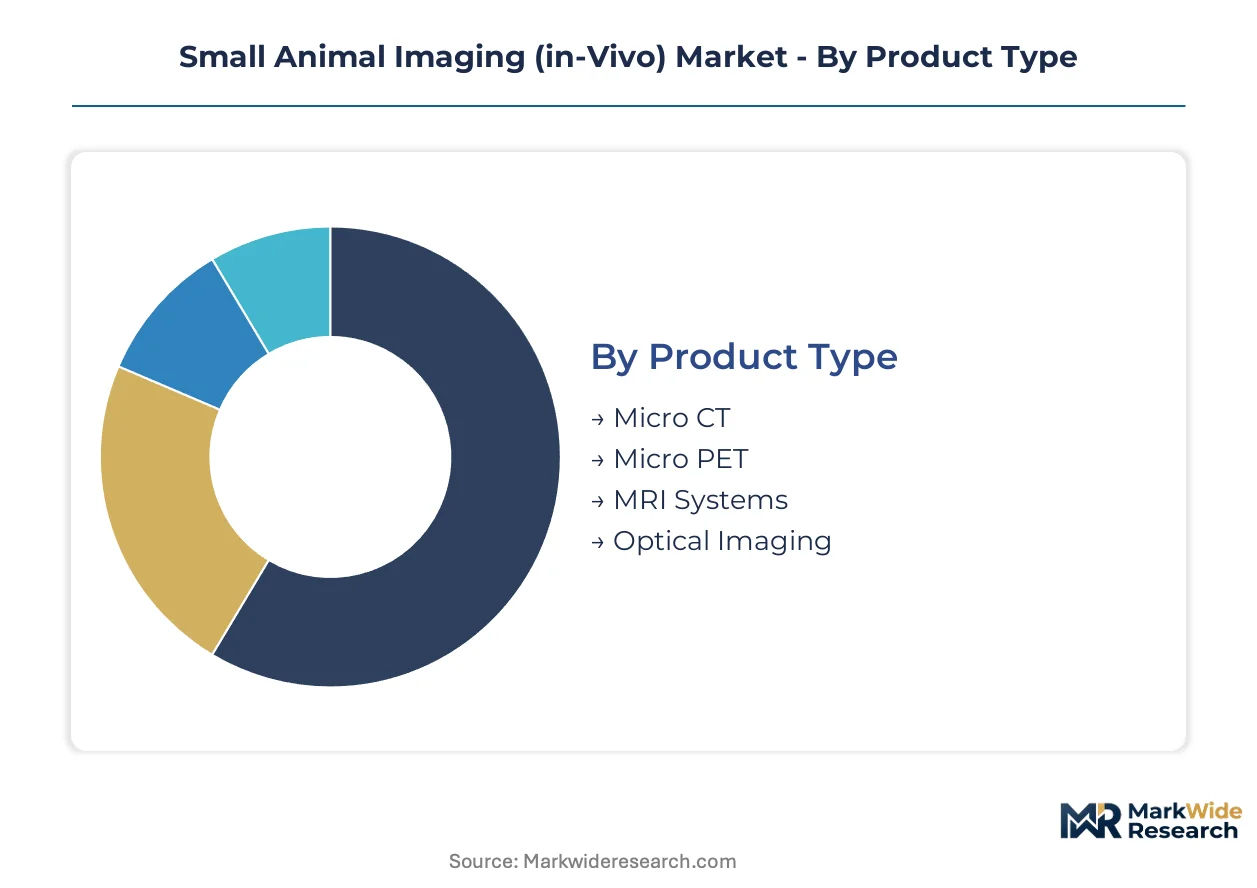
Segmentation in small animal imaging reveals divergent capital requirements and operational constraints across hardware categories. Procurement decisions hinge on facility infrastructure, regulatory licensing burdens, and reagent supply chain dependencies that vary sharply by modality and end-use.
Product Type:
Capital intensity stratifies sharply: cryogen-free MRI and multimodal suites demand seven-figure infrastructure investments, while optical platforms operate at fractionally lower thresholds.
- MRI Systems:Cryogen-free superconducting designs eliminate liquid helium dependency and reduce site preparation costs. Pharmaceutical contract research organizations in the United States and Germany prioritize these platforms to avoid dedicated magnet rooms and accelerate procurement cycles.
- Optical Imaging:Compact footprints and minimal facility modifications enable rapid deployment in standard laboratory spaces. Academic medical centers leverage lower capital thresholds to maintain longitudinal study pipelines despite constrained equipment budgets.
- Micro CT:Ionizing radiation requirements necessitate shielded installations and institutional radiation safety committee oversight.
- Micro PET:Radioisotope-dependent operations face Molybdenum-99 supply volatility and NRC licensing friction that compress utilization rates.
Optical imaging absorbs the bulk of installed capacity; MRI systems are expanding most quickly as cryogen-free designs broaden addressability.
End User:
Customer type determines validation burden and procurement authority, with pharmaceutical sponsors imposing stricter vendor qualification standards than academic counterparts.
- Pharmaceutical Companies:FDA 21 CFR Part 11 compliance mandates drive consolidation toward pre-qualified multimodal vendors. Sponsors unbundle imaging from traditional contract research organization relationships, creating fee-for-service procurement channels with real-time pricing visibility.
- Contract Research Organizations:Mid-tier CROs in India invest in optical and micro CT capacity to capture cost-arbitrage demand from Western pharmaceutical sponsors. GLP-compliant infrastructure investments position domestic operators for study placement migration.
- Research Institutions:NIH translational research funding sustains replacement cycles for aging optical installations.
- Academic Institutions:Grant reviewer expectations for longitudinal data integrity steer procurement toward multimodal suites despite capital constraints.
Pharmaceutical companies command premium pricing tolerance; contract research organizations are climbing the fastest as outsourcing accelerates.
Technology:
Detection modality dictates reagent economics, regulatory exposure, and computational reconstruction requirements.
- Bioluminescence:Luciferin substrate consumption generates recurring revenue streams that offset hardware margin compression. PerkinElmer bundles substrate supply contracts with equipment leases to lock customer lifetime value across study durations.
- Magnetic Resonance:Quantitative imaging biomarkers enable longitudinal disease monitoring without ionizing radiation exposure. FDA draft guidance on AI-enabled reconstruction algorithms is extending validation burdens to preclinical platforms, with vendors submitting performance packages across diverse rodent models.
- Fluorescence:Near-infrared probe development expands multiplexing capabilities for vascular and metabolic imaging.
- Radiography:Traditional X-ray platforms face displacement by micro CT in preclinical applications requiring three-dimensional anatomical resolution.
Bioluminescence dominates current reagent attach revenue; magnetic resonance is gaining share fastest as cryogen-free designs penetrate mid-market installations.
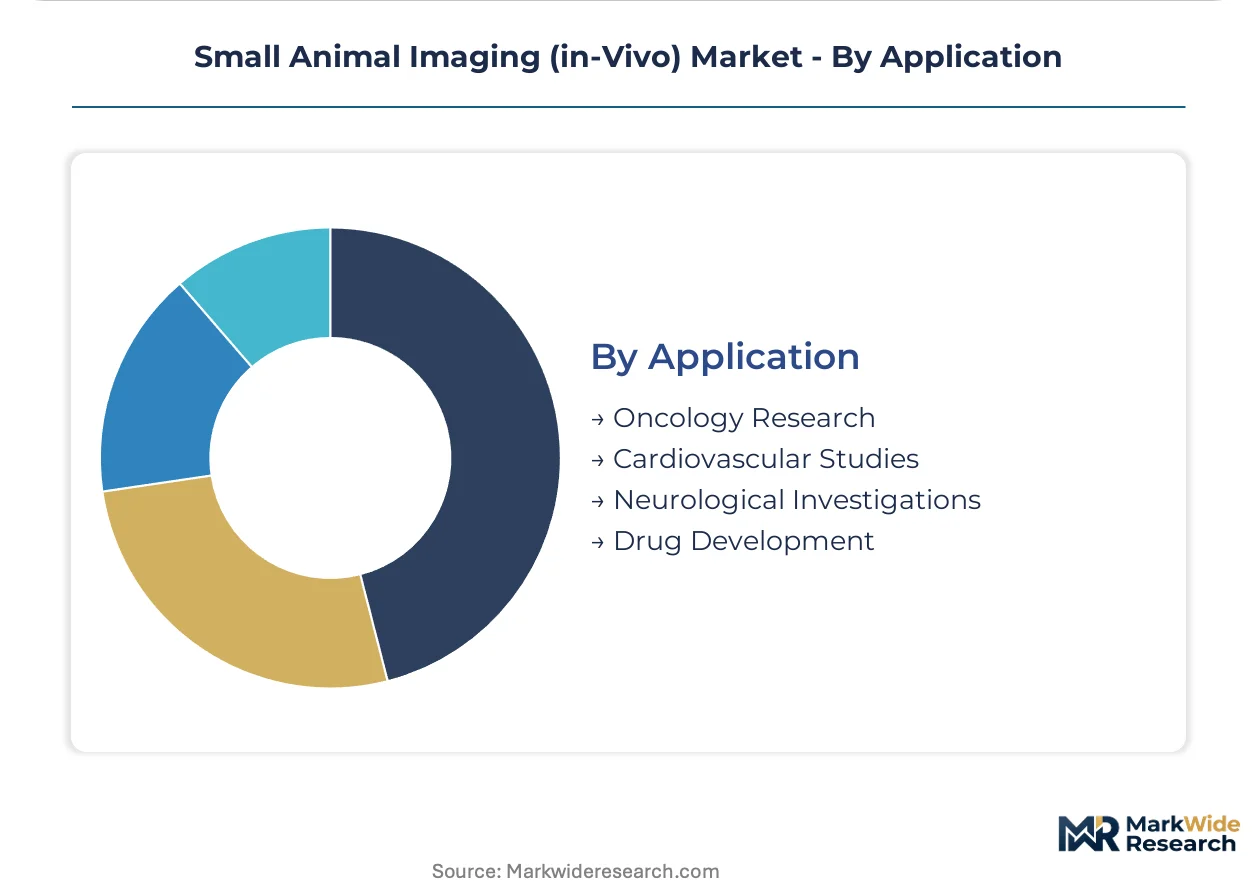
Application:
Therapeutic area focus shapes modality selection, with oncology demanding quantitative tracer kinetics and neurological studies prioritizing soft-tissue contrast.
- Oncology Research:Tumor burden quantification and metastasis tracking drive multimodal PET-CT and bioluminescence adoption. Radioisotope scheduling volatility from Molybdenum-99 production concentration compresses micro PET utilization rates.
- Drug Development:Pharmacokinetic tracing and efficacy validation require longitudinal imaging protocols that satisfy FDA and EMA data integrity standards. Pharmaceutical sponsors maintain decade-old optical installations with proprietary formats, demanding expensive migration tools for platform upgrades.
- Neurological Investigations:Blood-brain barrier permeability studies leverage MRI contrast agents and optical reporter systems.
- Cardiovascular Studies:Vascular remodeling and plaque progression monitoring combine micro CT angiography with fluorescence molecular tomography.
Oncology research commands the largest share of scanner hours; drug development applications are expanding most quickly as translational pipelines thicken.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Longwood Medical Area anchors preclinical imaging demand through dense concentrations of academic medical centers and pharmaceutical research campuses. NIH funding flows concentrate in this corridor, driving multimodal suite procurement cycles.
United States
NIH translational research appropriations sustain replacement demand for aging optical installations across academic medical centers. FDA 21 CFR Part 11 compliance mandates tighten vendor qualification standards for pharmaceutical sponsors. The Boston-Cambridge biotech corridor hosts the densest concentration of cryogen-free MRI deployments among mid-tier contract research organizations.
Germany
Pharmaceutical contract research organizations in Baden-Württemberg and Bavaria prioritize cryogen-free superconducting designs to avoid dedicated magnet room construction. EMA Good Laboratory Practice harmonization reduces multi-site validation burdens for preclinical trial vendors. The Heidelberg-Mannheim life science cluster concentrates micro PET-CT installations serving European pharmaceutical sponsors.
China
Domestic contract research organizations in Shanghai and Suzhou expand optical and micro CT capacity to capture Western pharmaceutical outsourcing migration. NMPA alignment with international GLP standards accelerates vendor pre-qualification timelines for multinational sponsors. The Zhangjiang Hi-Tech Park hosts the fastest-growing concentration of bioluminescence workflow installations.
India
Cost arbitrage attracts pharmaceutical sponsors seeking GLP-compliant imaging at reduced per-study expense to Hyderabad and Bangalore contract research organizations. CDSCO enforcement of preclinical data integrity standards rises alongside export-oriented sponsor demands. The Genome Valley biotechnology cluster anchors domestic investment in optical imaging capacity expansion.
United Kingdom
Academic institutions in the Oxford-Cambridge-London golden triangle maintain longitudinal study pipelines despite constrained capital equipment budgets. MHRA convergence with FDA data integrity expectations shapes vendor selection criteria for pharmaceutical sponsors. The Francis Crick Institute in London concentrates multimodal suite deployments serving collaborative preclinical research programs.
Small Animal Imaging (in-Vivo) Market Vendor Landscape
Premium-margin players sit above commodity-margin players across the modality spectrum, with cryogen-free MRI and multimodal PET-CT suites commanding pricing power while optical platforms compete on reattach revenue. The vendor base stratifies into three tiers: diversified life science conglomerates with imaging divisions, dedicated preclinical imaging specialists, and optical-bioluminescence workflow providers. Consolidation pressure concentrates among mid-tier players lacking helium-free MRI intellectual property or integrated reagent supply chains. Dominant competitive moves include cryogen-free technology licensing agreements and pharmaceutical CDMO partnership bundling.
Among diversified instrument manufacturers, Bruker Corporation, PerkinElmer, Inc., and Thermo Fisher Scientific Inc. exemplify contrasting strategic archetypes. Bruker anchors the cryogen-free superconducting segment through proprietary magnet designs that reduce facility infrastructure barriers. PerkinElmer occupies a position defined by recurring reagent revenue streams from integrated bioluminescence workflows. Thermo Fisher sits within the pharmaceutical services bundling tier, leveraging CDMO relationships to anchor radiography suite placements. These three entities collectively represent the spectrum of competitive positioning available to market participants.
| Leading Market Players |
|---|
| Bruker Corporation |
| PerkinElmer, Inc. |
| FUJIFILM Holdings Corporation |
| Miltenyi Biotec |
| Aspect Imaging Ltd. |
| Mediso Ltd. |
| Thermo Fisher Scientific Inc. |
| Promega Corporation |
| LI-COR Biosciences |
| Others |
Supply Flow & Price Mechanics
Cryogen-free superconducting MRI platforms versus commodity optical systems bifurcate capital expenditure thresholds and facility infrastructure requirements across both pricing negotiations and vendor qualification timelines. Pharmaceutical sponsors in the United States absorb seven-figure multimodal suite investments while academic medical centers negotiate reagent-attach contracts that shift lifetime value toward recurring substrate consumption.
Pricing Analysis
Scanner throughput and longitudinal data integrity uptime anchor value-based pricing negotiations between vendors and pharmaceutical sponsors. Three-tier pricing structure across premium cryogen-free MRI, standard permanent-magnet systems, and economy optical platforms reflects FDA 21 CFR Part 11 certification burdens and helium-free intellectual property premiums. Cost compression in optical segments intensifies as PerkinElmer and LI-COR Biosciences compete on luciferin supply contract bundling. Academic institutions exhibit highest price sensitivity due to NIH grant funding volatility, while pharmaceutical CDMO partnerships demonstrate lowest sensitivity given regulatory pre-qualification requirements.
Supply Chain Analysis
Domestic-content mandates in China's NMPA pre-qualification pathways reshape magnet and radioisotope sourcing strategies for multinational vendors. Superconducting wire production concentrates in Japan, Germany, and the United States, while Molybdenum-99 for micro PET tracers feeds from aging research reactors in Canada and the Netherlands. Single-source vulnerability in helium-free magnet intellectual property creates supply chain concentration risk. Distribution runs through pharmaceutical CDMO partnership bundling and fee-for-service procurement portals with real-time scanner availability disclosure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA 21 CFR Part 11 compliance costs erect a formidable barrier-to-entry moat that consolidates vendor qualification lists around pre-certified multimodal platform providers. This regulatory burden protects incumbent margins while forcing new entrants to absorb extended validation timelines before revenue recognition.
For Market Incumbents: To counter optical-bioluminescence workflow providers compressing hardware margins through reagent-attach revenue, Bruker Corporation and Thermo Fisher Scientific should deepen backward integration into cryogen-free magnet manufacturing and radiopharmaceutical handling infrastructure. Capacity addition in India and China positions these vendors to capture pharmaceutical outsourcing migration while maintaining GLP compliance arbitrage.
For New Entrants and Emerging Players: CDSCO enforcement alignment with FDA data integrity standards in India opens a window for domestic contract research organizations to capture Western sponsor study placement through cost-competitive optical and micro CT capacity. The most penetrable segment sits with mid-tier pharmaceutical sponsors unbundling imaging from traditional CRO relationships. A fee-for-service portal with real-time pricing transparency serves as the optimal go-to-market mechanism.
For Investors and Strategic Acquirers: Re-rating potential sits with cryogen-free MRI specialists given FDA draft guidance on AI-enabled reconstruction algorithms creating next-generation platform differentiation. Long-term viability over a multi-year horizon favors vendors with integrated reagent supply chains and helium-free intellectual property portfolios. The signal to watch is regulatory clarity on machine-learning diagnostic outputs determining qualification timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Cryogen-Free Magnet Technology Licensing | Helium-free designs from Bruker reduce facility barriers for mid-tier CROs in Germany and the United States. |
| Bioluminescence Reagent Supply Bundling | PerkinElmer's luciferin contracts lock customer lifetime value across multi-year oncology study durations. |
| Pharmaceutical CDMO Partnership Anchoring | Thermo Fisher's radiography suite placements leverage existing drug manufacturing service relationships. |
| AI-Enabled Reconstruction Algorithm Validation | FDA guidance compliance determines which vendors qualify next-generation micro PET platforms first. |
| India Preclinical Services Outsourcing Capture | Hyderabad and Bangalore CROs invest in GLP-compliant optical capacity to attract Western sponsor migration. |
Methodological Framework
FDA 510(k) filings, EMA preclinical trial databases, and NIH RePORTER funding records formed the secondary backbone for market sizing and vendor qualification tracking. Primary interviews with preclinical imaging directors at pharmaceutical sponsors, radiation safety officers at academic medical centers, and procurement leads at contract research organizations validated capital expenditure patterns and replacement cycle timing. Bottom-up triangulation across scanner installation databases and top-down reconciliation against NIH translational research appropriations anchored volume estimates.
Historical trendline analysis of cryogen-free MRI adoption rates, optical platform replacement cycles, and micro PET utilization patterns informed projection modeling across the analysis window. Segmentation dimensions included modality type, end-user category, technology detection method, and therapeutic application focus. CAGRs were derived from weighted average of vendor-reported booking trends and sponsor-reported imaging budget allocations. Cryogen-free superconducting design penetration and AI-enabled reconstruction algorithm regulatory clearance timelines served as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for cryogen-free MRI intellectual property licensing or Molybdenum-99 production reactor decommissioning would alter the outlook. Forecasts reflect assumptions regarding FDA guidance finalization, NIH funding continuity, and EMA GLP harmonization stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
India Ultrasound Devices Market
Medical Imaging
Preclinical Ultrasound Systems Market
Medical Imaging
France Magnetic Resonance Imaging Market
Medical Imaging
India Digital Radiology Market
Medical Imaging
C-Arms Market
Medical Imaging
US Digital Radiology Market
Medical Imaging
Mobile Vascular Imaging Market
Medical Imaging
Asia-Pacific Digital Radiology Market
Medical Imaging
Global Magnetic Resonance Imaging System Market
Medical Imaging
Surgical Imaging Robots Market
Medical Imaging
Pediatric Imaging Market
Medical Imaging
AI-Assisted Digital Radiography Equipment Market
Medical Imaging
Diagnostic Ultrasound Market
Medical Imaging
Dental Imaging Market
Medical Imaging
Global 3D Ultrasound Market
Medical Imaging
Handheld Ultrasound Scanners Market