
 Europe Military Helicopters Market | 2026-2036
Europe Military Helicopters Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Military Helicopters Market Foresight
CS25 military certification and its associated qualification cycles is unwinding the competitive landscape for European suppliers. Airbus Helicopters leverages its integrated supply chain and Pan-European manufacturing footprint to dominate multi-role platform deliveries. Leonardo sustains strong positioning through specialized tiltrotor and naval helicopter competencies centered at its Italian facilities. NHIndustries competes as a consortium-based alternative, anchoring its market presence on the NH90 program's established European operator base.
Military helicopters constitute rotary-wing aircraft engineered for armed forces operations, typically featuring tandem or side-by-side crew seating, armor protection, and payload capacities exceeding 2,500 kg for external lift missions. Turbine engines power most platforms, with specific fuel consumption and power-to-weight ratios determining operational altitude and hover performance envelopes. Attack helicopters command concentrated R&D investment due to precision munitions integration requirements and survivability enhancements. Transport helicopters carry mature margin pools across fleet sustainment and mid-life upgrade contracts. Autonomous systems represent the fastest-evolving technology segment, with fly-by-wire architectures enabling reduced crew complements and expanded mission profiles.
EU Green Deal emissions benchmarks and the F-Gas Regulation constrain turbine engine refrigerant selections and fuel efficiency standards for new platform certifications. EASA military certification protocols, supplemented by national military airworthiness authorities in France and Germany, govern design approvals and cross-border operational clearances. Stakeholders must monitor how REACH chemical restrictions affect composite material supply chains and how the EU AI Act's risk classifications shape autonomous flight control development roadmaps.
Market Dynamics
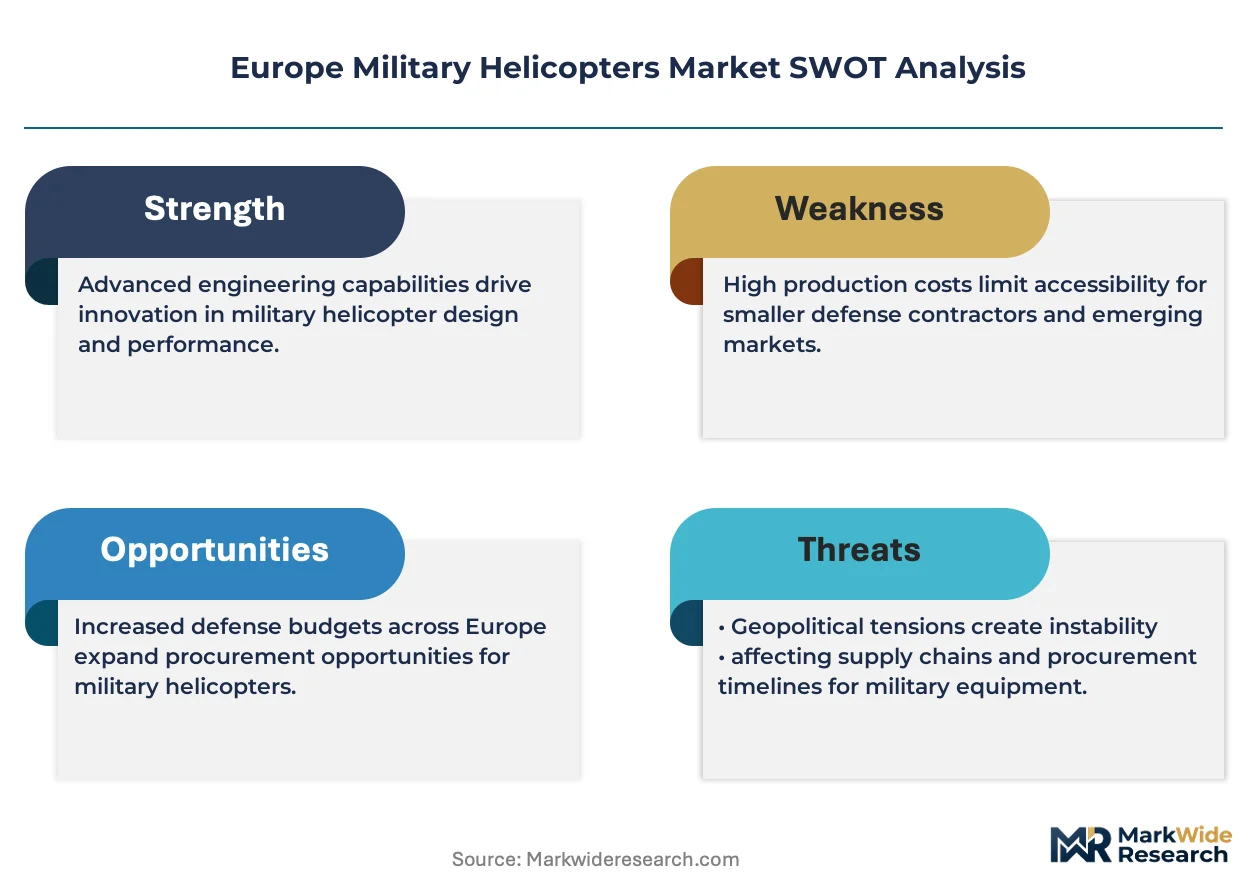
EU Green Deal emissions benchmarks and F-Gas Regulation constraints are forcing turbine engine manufacturers to redesign thermal management systems and refrigerant selections before new platform certifications expire. Defense ministries in France, Germany, and the United Kingdom now embed fuel efficiency thresholds into procurement specifications, reshaping supplier qualification requirements across the supply base.
Growth Catalysts
- Combat Search-and-Rescue Modernization:European air forces are retiring Cold War-era fleets and mandating multi-role platforms with integrated medical evacuation and tactical transport capabilities.
- EU Green Deal Defense Sustainability Framework:Emissions reduction mandates create procurement preference for platforms demonstrating measurable fuel efficiency improvements and alternative fuel compatibility.
- Tiltrotor Technology Maturation:Vertical lift platforms combining helicopter hover with fixed-wing speed are attracting naval and special operations investment for shipboard and expeditionary missions.
Market Restraints
- Turbine Engine Supply Concentration:Safran Helicopter Engines and Rolls-Royce control critical powerplant architectures, creating single-source vulnerability for new platform development timelines.
- CS25 Military Certification Cycles:EASA qualification protocols extend development schedules by 18-36 months, compressing manufacturer cash conversion cycles and raising program risk.
- Autonomous System Substitution:Uncrewed aerial systems for reconnaissance and light cargo missions are displacing manned helicopter requirements in lower-threat operational envelopes.
Strategic Opportunities
- Nordic Defense Cooperation:Norway, Sweden, and Finland are harmonizing rotary-wing requirements through NORDEFCO frameworks, creating consolidated procurement volumes for multi-role platforms.
- Fly-by-Wire Retrofit Market:Mid-life upgrade programs for NH90 and Tiger fleets present aftermarket revenue pools for flight control modernization and crew complement reduction.
- Naval Helicopter Replacement Wave:Anti-submarine warfare platforms approaching service limits in France, Italy, and the United Kingdom open competitions for marinized tiltrotor or compound helicopter solutions.
Industry Challenges
- Composite Material Compliance:REACH chemical restrictions on epoxy resins and carbon fiber precursors force supply chain requalification, delaying production ramps and raising unit costs.
- Autonomous Flight Control Certification:The EU AI Act's risk classification system for safety-critical algorithms creates unresolved validation protocols for reduced-crew or single-pilot operational modes.
- Skilled Technician Scarcity:Turbine engine overhaul and avionics integration specializations face retirement-driven attrition, constraining fleet availability rates across operator bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Military Helicopters Market |
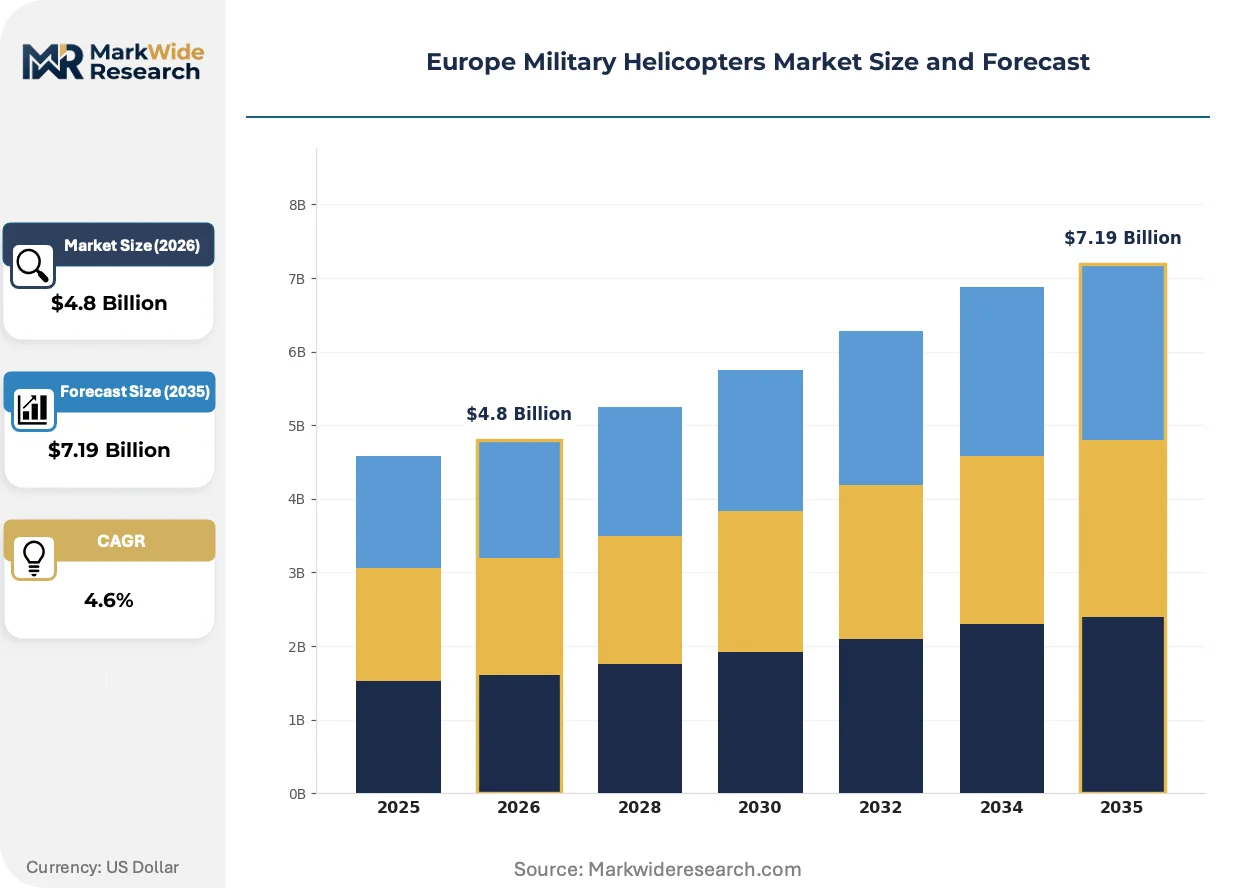
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Attack Helicopters, Transport Helicopters, Utility Helicopters, Reconnaissance Helicopters Development Stage: Prototype, Under Development, Operational, Decommissioned End User: Military, Government Agencies, Private Contractors, Defense Forces Technology: Fly-by-Wire, Avionics, Turbine Engines, Autonomous Systems |
| Companies Covered | Airbus Helicopters, Leonardo, Russian Helicopters, Boeing, Lockheed Martin, Sikorsky Aircraft, Bell Helicopter, MD Helicopters, NHIndustries, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Military Helicopters Market Shifts & Advancements
Open systems architectures are displacing proprietary avionics stacks, enabling faster sensor and weapons integration without airframe redesign. Defense procurement offices now mandate modular standards that accelerate capability insertion across platform lifecycles.
Hybrid-electric propulsion is fragmenting traditional turbine-dominated powertrain strategies. Airbus Helicopters and Leonardo are flight-testing electric auxiliary systems for torque boost and emergency power, with French and German defense ministries funding demonstration programs through 2028. This technology is fragmenting engine supplier relationships as airframers seek electrical system partnerships outside established turbine networks.
The EU AI Act's high-risk system classification is reshaping autonomous flight control development timelines. Manufacturers must demonstrate algorithmic transparency and human oversight protocols before military certification, compressing R&D roadmaps for single-pilot and optionally-manned platforms. French and German airworthiness authorities are establishing precedents that will govern subsequent European programs.
Performance-based logistics contracts are replacing transactional spare parts purchasing. Defense ministries in the United Kingdom and Italy now contract for availability guarantees rather than component deliveries, transferring inventory risk to manufacturers and their tier-one suppliers. This model concentrates in naval helicopter fleets where operational readiness metrics directly link to contract renewals.
Europe Military Helicopters Market Segmentation
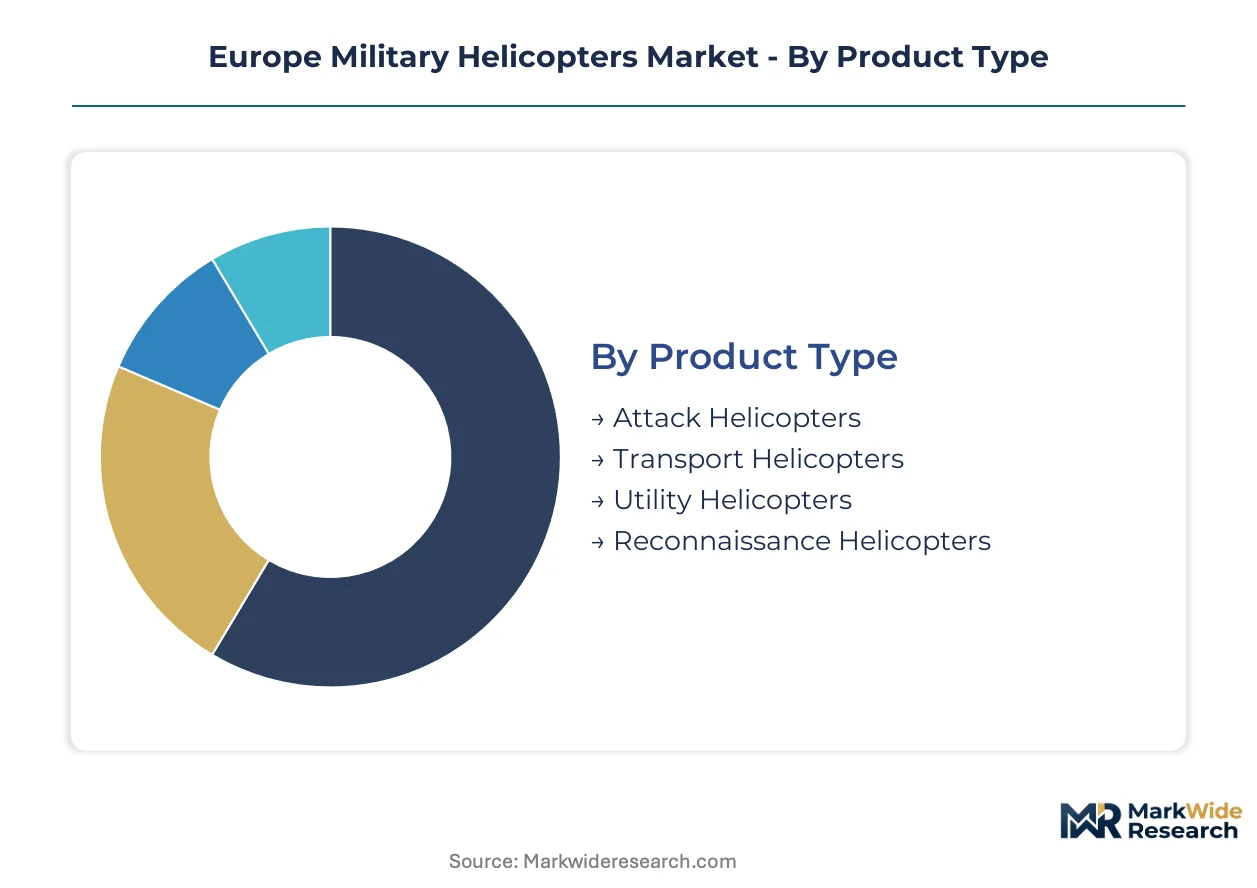
European defense procurement frameworks segment rotary-wing platforms by operational role, maturity stage, and technical architecture. EASA military certification protocols and national airworthiness authorities create divergent qualification pathways that reshape how manufacturers prioritize development investments across these dimensions.
Product Type:
REACH chemical restrictions on composite airframes and the EU Green Deal's emissions benchmarks differentiate procurement eligibility across platform categories.
- Attack Helicopters:These platforms integrate precision munitions systems, armor protection, and tandem crew configurations optimized for close air support and anti-armor missions. French and German defense ministries concentrate modernization spending here, driven by NATO interoperability requirements and fleet replacement timelines for Cold War-era airframes.
- Transport Helicopters:External lift capacities exceeding 2,500 kg define these platforms, with side-by-side crew seating and modular cabin configurations for troop transport and medical evacuation. The United Kingdom prioritizes this segment through performance-based logistics contracts that transfer availability risk to manufacturers.
- Utility Helicopters:Multi-role platforms balance payload flexibility with operational economics across training, liaison, and light transport missions.
- Reconnaissance Helicopters:Sensor-dense configurations with reduced radar signatures serve intelligence-gathering roles before uncrewed system substitution.
Transport Helicopters handle the majority of throughput; Attack Helicopters are gaining share fastest on defense modernization priorities.
Development Stage:
Platform maturity determines which EASA certification pathways apply and whether EU AI Act risk classifications govern autonomous flight control approvals.
- Operational:Fielded platforms with established military type certificates dominate fleet sustainment revenue pools across French, German, and Italian operator bases. These airframes attract mid-life upgrade investment for avionics modernization and fly-by-wire retrofit, extending service lives through 2040.
- Under Development:Next-generation programs face compressed cash conversion cycles as CS25 military qualification protocols extend schedules by 18-36 months. French and German defense ministries fund tiltrotor and hybrid-electric demonstrations through this stage, with alternative fuel compatibility now embedded in procurement specifications.
- Prototype:Technology demonstrators validate autonomous flight control architectures and reduced-crew operational modes before full-scale engineering development.
- Decommissioned:End-of-life platforms generate spare parts demand and fleet transition planning for operator logistics commands.
Operational platforms anchor current revenue; Under Development programs show the steepest expansion trajectory on sustainability-driven procurement.
End User:
Budget authority and operational risk tolerance vary sharply across institutional customer types, fragmenting pricing structures and contract terms.
- Defense Forces:National military services in France, Germany, and the United Kingdom command consolidated procurement volumes with multi-year framework agreements. These customers mandate modular open systems architectures and performance-based availability guarantees, concentrating supplier relationships on Airbus Helicopters, Leonardo, and NHIndustries.
- Government Agencies:Coast guard, border patrol, and emergency response organizations operate dual-use platforms with civilian certification overlays. Nordic Defense Cooperation frameworks harmonize requirements across Norway, Sweden, and Finland, creating pooled procurement for search-and-rescue configurations.
- Military:Service branches with dedicated aviation commands maintain specialized maintenance infrastructure and pilot training pipelines.
- Private Contractors:Logistics and training providers lease operational hours rather than owning fleet assets, preferring turnkey availability contracts.
Defense Forces concentrate the majority of platform deliveries; Government Agencies are expanding most quickly on dual-use mission requirements.
Technology:
Supply-side capability scarcity for electrical system integration is fragmenting traditional turbine engine supplier relationships as hybrid architectures mature.
- Turbine Engines:Safran Helicopter Engines and Rolls-Royce control powerplant architectures with specific fuel consumption ratings determining operational altitude envelopes. F-Gas Regulation constraints force thermal management redesigns before new platform certifications, with French and German airworthiness authorities establishing precedent for emissions compliance validation.
- Autonomous Systems:Fly-by-wire architectures enable reduced crew complements and expanded mission profiles, though EU AI Act high-risk system classifications create unresolved validation protocols. Algorithmic transparency requirements compress R&D roadmaps for single-pilot operational modes.
- Fly-by-Wire:Digital flight control systems replace mechanical linkages, enabling stability augmentation and automatic terrain following.
- Avionics:Open systems standards displace proprietary stacks, accelerating sensor and weapons integration without airframe redesign.
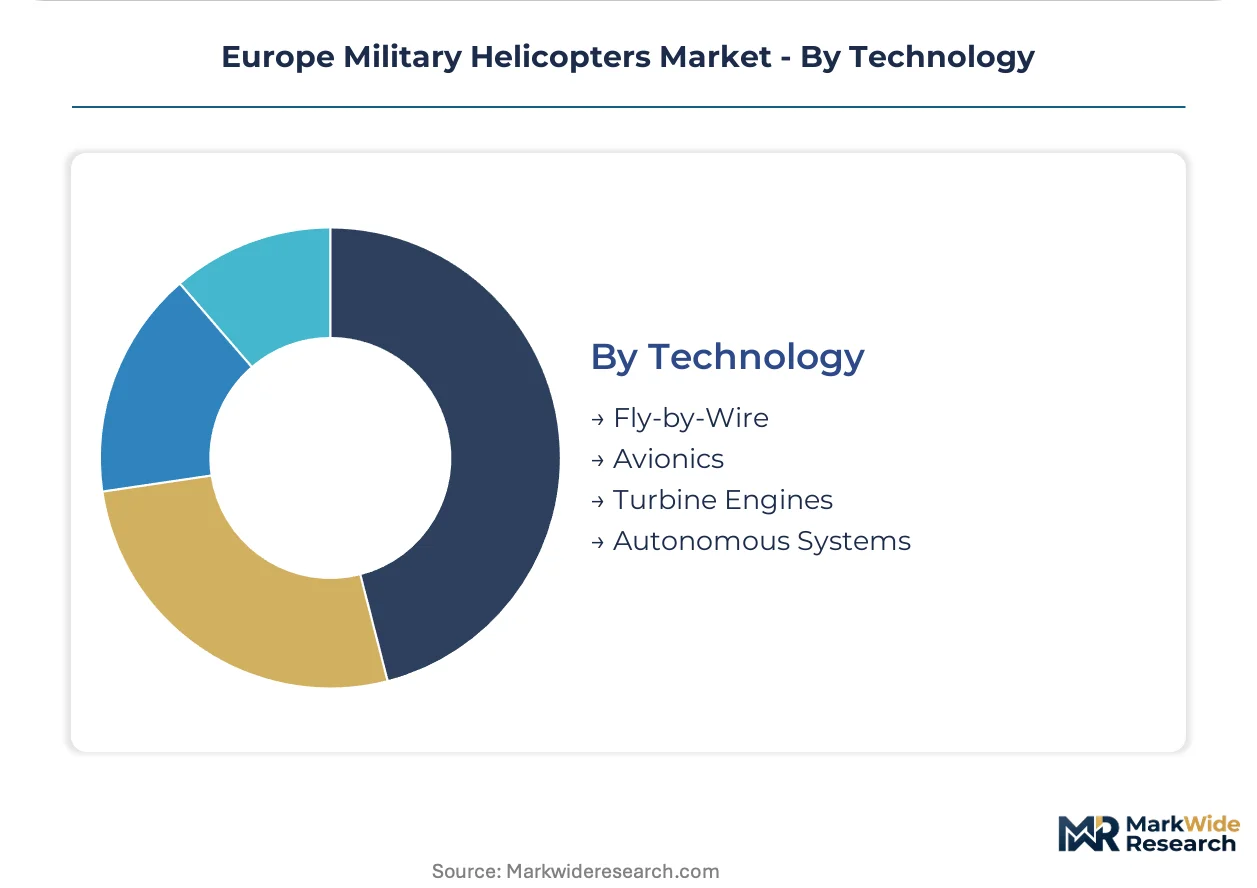
Turbine Engines handle current propulsion requirements; Autonomous Systems are climbing the fastest on crew reduction mandates and operational risk transfer.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal defense sustainability framework is redistributing procurement volumes toward nations with established airworthiness authorities and multi-role platform requirements. National defense ministries now embed emissions benchmarks and alternative fuel compatibility into rotary-wing acquisition specifications.
France
The Direction Générale de l'Armement funds attack helicopter modernization and naval tiltrotor demonstrations through 2028. ANSM airworthiness precedents for autonomous flight controls are shaping EU AI Act implementation timelines. The Provence-Alpes-Côte d'Azur cluster around Marignane anchors Airbus Helicopters' final assembly and flight test infrastructure.
Germany
The Federal Ministry of Defence consolidates NH90 fleet sustainment and Tiger mid-life upgrades under performance-based logistics contracts. KBA-aligned military certification protocols for hybrid-electric propulsion are establishing EU-wide emissions compliance templates. Bavaria's aerospace corridor between Munich and Donauwörth concentrates turbine engine R&D and fly-by-wire integration facilities.
United Kingdom
The Ministry of Defence prioritizes combat search-and-rescue replacements and naval helicopter availability guarantees in its rotary-wing budget. UK Military Aviation Authority certification requirements for reduced-crew operational modes are compressing development schedules for autonomous platforms. The South West England cluster around Yeovil sustains Leonardo's naval helicopter final assembly and systems integration capabilities.
Italy
The Direzione degli Armamenti Aeronautici directs investment toward tiltrotor maturation and anti-submarine warfare platform replacements. EASA military certification coordination with French and German authorities is streamlining cross-border operational clearances for consortium-developed airframes. The Lazio and Campania regions host Leonardo's tiltrotor flight test centers and naval helicopter production lines.
Nordic Region
NORDEFCO frameworks are harmonizing Norway, Sweden, and Finland rotary-wing requirements into consolidated multi-role procurement volumes. REACH chemical restrictions on composite materials are forcing supply chain requalification across Scandinavian operator bases. The Oslo-Stockholm-Helsinki corridor is emerging as a coordinated testbed for cold-weather autonomous flight control validation.
Europe Military Helicopters Market Competitive Landscape
Player mix skews toward integrated European airframers with Pan-European manufacturing footprints and specialized tiltrotor competencies. The vendor base concentrates around three structural positions: consortium-based platform developers leveraging pooled national investment, vertically integrated airframers controlling proprietary flight control architectures, and engine specialists with captive thermal management expertise. Dominant competitive moves include backward integration into electrical system partnerships for hybrid propulsion and geographic expansion through Nordic defense cooperation frameworks.
Within the integrated airframer tier, Airbus Helicopters and Leonardo occupy positions defined by manufacturing scale and specialization depth. Airbus Helicopters exemplifies the Pan-European consortium model with final assembly distributed across French and German facilities. Leonardo represents the vertically integrated specialist archetype, anchoring tiltrotor and naval helicopter development at Italian engineering centers. NHIndustries sits within the multi-national joint venture category, sustaining market presence through the NH90 program's established operator base across European defense forces.
| Leading Market Players |
|---|
| Airbus Helicopters |
| Leonardo |
| Russian Helicopters |
| Boeing |
| Lockheed Martin |
| Sikorsky Aircraft |
| Bell Helicopter |
| MD Helicopters |
| NHIndustries |
| Others |
Supply & Pricing Matrix
Performance-based logistics contracts with availability guarantees lock in multi-year revenue visibility for airframers while transferring operational risk from defense ministries to manufacturers. French and German procurement offices now embed fuel efficiency thresholds and emissions compliance into contract indexation clauses, reshaping how turbine engine suppliers negotiate thermal management system upgrades.
Pricing Analysis
Cost-plus contracts with labor and materials indexation dominate military helicopter procurement across European defense ministries. Price differentiation separates platforms certified to CS25 military protocols from those carrying only national airworthiness approvals, with EASA-qualified airframes commanding premiums. Pricing pressure stems from EU Green Deal emissions mandates forcing turbine engine redesigns before certification deadlines. Government agencies operating dual-use platforms show highest price sensitivity, while defense forces prioritize availability guarantees over unit cost.
Supply Chain Analysis
Safran Helicopter Engines' single-source control over Arriel and Arrano powerplant architectures creates chokepoint vulnerability for new platform development timelines. Manufacturing concentrates in France, Germany, and Italy, with carbon fiber precursors and epoxy resin systems drawing from established aerospace corridors. REACH chemical restrictions on composite materials pose regulatory risk requiring supply chain requalification. Distribution runs through national military logistics commands with consolidated spare parts pooling across NATO frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European military helicopter demand sits in early-cycle expansion as defense ministries accelerate Cold War-era fleet replacements under NATO interoperability mandates. Sustainability-driven procurement specifications for alternative fuel compatibility and emissions reduction are creating new competitive entry points.
For Market Incumbents: Secure long-term turbine engine supply agreements before F-Gas Regulation redesign cycles compress margin pools. Lock in electrical system partnerships for hybrid-electric architectures outside traditional Safran and Rolls-Royce networks, as autonomous flight control development demands algorithmic transparency investment ahead of EU AI Act validation protocols. For New Entrants and Emerging Players: EASA military certification fast-tracks through French ANSM or German KBA precedents offer entry pathways for reduced-crew operational modes. White-space concentrates in Nordic Defense Cooperation frameworks where Norway, Sweden, and Finland harmonize multi-role requirements. Target naval tiltrotor demonstrations for anti-submarine warfare replacements, positioning through cold-weather flight test validation partnerships. For Investors and Strategic Acquirers: Specialized avionics integrators with open systems architecture expertise represent attractive acquisition targets as modular standards displace proprietary stacks. Long-term viability hinges on fly-by-wire retrofit capabilities for NH90 and Tiger mid-life upgrades. Watch EU AI Act risk classification precedents for autonomous flight controls as the inflection signal for single-pilot platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Electric Propulsion Partnership | Airframers bypass traditional turbine networks through electrical system alliances with French and German defense ministry funding. |
| Performance-Based Logistics Contract | UK and Italian defense ministries transfer availability risk to manufacturers, concentrating revenue in fleet sustainment pools. |
| Fly-by-Wire Retrofit Program | Mid-life upgrades for operational NH90 and Tiger fleets extend service lives through 2040 with reduced crew complements. |
| NORDEFCO Framework Integration | Norway, Sweden, and Finland consolidate procurement volumes for multi-role platforms with cold-weather operational validation. |
| Open Systems Architecture Certification | Modular avionics standards accelerate sensor integration without airframe redesign, reshaping supplier qualification requirements. |
Research Methodology
Operator-level perspectives from fleet commanders, defense procurement officers, turbine engine overhaul technicians, and avionics integration specialists anchored the qualitative base. Primary interviews triangulated with EASA certification databases, national military airworthiness authority filings, and EU defense procurement registries. Secondary validation drew from REACH chemical restriction notices, EU Green Deal implementation frameworks, and NATO logistics pooling agreements. Bottom-up platform delivery forecasts reconciled with top-down defense budget appropriations across the analysis window.
Sensitivity analysis tested forecast outputs against alternative adoption curves for autonomous flight control certification and hybrid-electric propulsion maturation. Segmentation modeling spanned operational role, development stage, end-user institution, and technology architecture, with regional clusters further split by national airworthiness authority jurisdiction. CAGRs derived from regression analysis of historical procurement cycles and announced modernization program timelines. Industry-specific inputs included turbine engine specific fuel consumption trajectories and CS25 military certification schedule assumptions.
The analysis sits within stated boundaries; outcomes outside sustained NATO interoperability commitments or accelerated EU AI Act implementation would require recalibration. Forecasts reflect documented assumptions on defense budget trajectories, certification protocol timelines, and composite material supply chain stability. Practitioners should keep alternative scenarios live as emissions regulation stringency and autonomous system substitution rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Global Commercial Aircraft Seat Actuation Market
Aircraft
Military Multirole Aircraft Market
Aircraft
Freighter Aircraft Market
Aircraft
Global Business Jets Market
Aircraft
Asia-Pacific Heavy-Lift Helicopter Market
Aircraft
France Aviation Market
Aircraft
Heavy-Lift Helicopter Market
Aircraft
America Freighter Aircraft Market
Aircraft
Military Transport Aircraft Market
Aircraft
Aircraft Seals Market
Aircraft
Helicopter Flight Management System Market
Aircraft
Aircraft Exterior Mounts Market
Aircraft
Belly Fairing Modifications for Freighter and Combi Aircraft Market
Aircraft
LAMEA Aircraft Band Clamps Market
Aircraft
Aircraft Band Clamps Market
Aircraft
Asia-Pacific Military Helicopters Market