
 France Aviation Market | 2026-2036
France Aviation Market Size, Share, and Industry Trends Forecast 2026-2036
France Aviation Market Foresight
Market Context
Defense procurement from the French Armed Forces is expanding as geopolitical priorities shift toward strategic autonomy. Airbus SE leverages its integrated design-to-assembly pipeline to dominate commercial wide-body programs. Safran SA sustains propulsion leadership through turbofan and nacelle specialization. Dassault Aviation anchors military and business jet segments with delta-wing fighter expertise.
Technical Definition and Segments
France aviation encompasses the design, manufacture, maintenance, and operation of fixed-wing aircraft, rotorcraft, and unmanned aerial vehicles certified to EASA CS-25 and CS-23 airworthiness standards, serving commercial transport, national defense, and private mobility missions. Commercial Jets leads Aircraft Type by installed fleet value, while Drones represents the fastest-expanding category driven by civil BVLOS regulatory openings. Maintenance, Repair, Overhaul commands the largest margin pool within Service Type due to long-tail aftermarket contracts, whereas Composite Materials within Technology is displacing aluminum primary structures in next-generation programs.
Regulatory Frame
EASA certification requirements, EU Green Deal SAF blending mandates, and France's Military Programming Law collectively shape fleet procurement timelines, engine emissions thresholds, and defense industrial base obligations. ANSM and DGAC coordinate operational safety oversight with environmental compliance enforcement. Stakeholders must monitor SAF infrastructure buildout pace and reindustrialization subsidy allocation under the France 2030 investment plan.
Market Dynamics
The France aviation market pivots on EU Green Deal mandates forcing fleet renewal timelines, with sustainable aviation fuel infrastructure buildout now determining procurement cycles for commercial operators and defense contractors alike.
Growth Catalysts
- Military Programming Law:French Armed Forces procurement under the LPM framework sustains domestic production capacity across fighter, transport, and rotary-wing categories.
- Occitanie cluster concentration:Toulouse aerospace ecosystem integrates design, assembly, and testing functions within a 50-kilometer radius, compressing program development cycles.
- SAF blending mandates:EU Green Deal requirements for synthetic fuel adoption accelerate engine retrofit programs and new propulsion R&D allocation.
Market Restraints
- Aluminum-titanium supply concentration:Primary aerospace metal suppliers cluster in German and Spanish smelting corridors, exposing French fabricators to cross-border logistics friction.
- EASA certification timelines:Extended validation periods for novel propulsion architectures delay revenue recognition on next-generation programs by 18-24 months.
- Lithium-sulfur battery energy density:Current cell chemistry limits electric propulsion to sub-regional aircraft below 19 seats, capping addressable market for zero-emission platforms.
Strategic Opportunities
- Nouvelle-Aquitaine drone corridor:Uncontrolled airspace over Landes forest enables beyond-visual-line-of-sight testing for civil UAV operators under DGAC experimental permits.
- Hydrogen propulsion convergence:Cryogenic storage systems paired with fuel cell stacks open retrofit pathways for regional turboprop fleets serving Corsica and Alpine routes.
- France 2030 reindustrialization subsidies:Direct state aid for clean aviation manufacturing anchors foreign supplier investment in Saint-Nazaire and Bordeaux facilities.
Industry Challenges
- Composite technician scarcity:Carbon fiber layup and autoclave curing skills concentrate among retiring cohorts, constraining production ramp rates for A350 derivative programs.
- Legacy system integration:Digital thread implementation across Dassault's CATIA environments clashes with NATO interoperability standards for Rafale export configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Aviation Market |
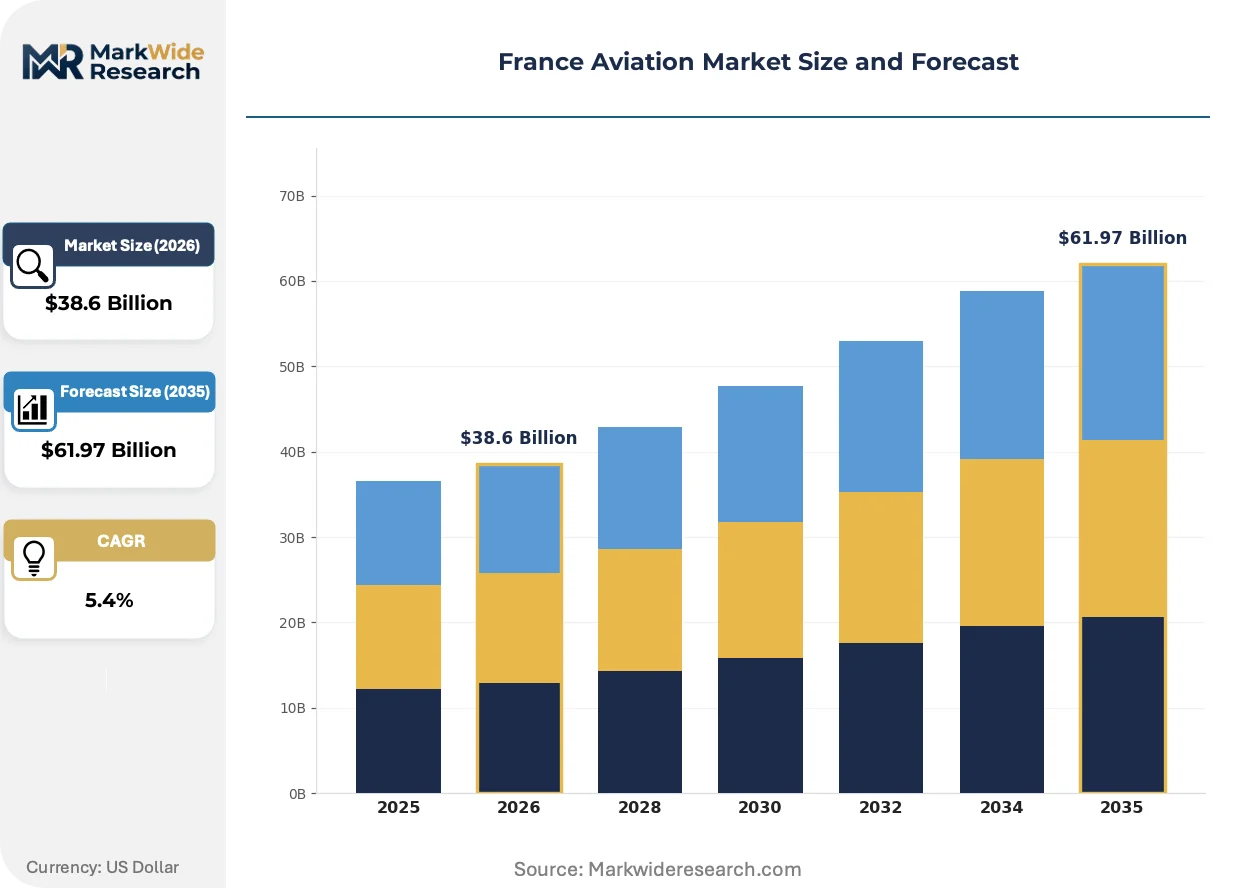
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $61.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Commercial Jets, Business Jets, Helicopters, Cargo Planes, Drones Service Type: Maintenance, Repair, Overhaul, Ground Handling, Flight Training Customer Type: Airlines, Charter Operators, Defense Forces, Cargo Carriers, Flight Schools Technology: Avionics, Composite Materials, Fly-by-Wire, Turbofan Engines, Navigation Systems |
| Companies Covered | Thales, DAHER, Airbus SE, Embraer S.A, General Dynamics Corporation, Safran SA, ATR, Pilatus Aircraft Ltd., Dassault Aviation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Aviation Market Shifts & Advancements
Propulsion electrification and digital manufacturing threads are compressing development cycles while regulatory pressure on emissions intensifies specification requirements across the supply base.
Hybrid-electric distributed propulsion is consolidating around megawatt-class motor-generator architectures for regional aircraft retrofits. French turbofan specialists partner with power electronics firms to integrate silicon carbide inverters into nacelle designs. This convergence is consolidating subsystem supplier tiers from three layers to two, squeezing mid-tier avionics houses.
EU Green Deal sustainable aviation fuel mandates now require 2% synthetic blending by 2025, rising to 70% by 2050. Refinery operators in Fos-sur-Mer and Le Havre retool hydroprocessed ester facilities to accept biomass and power-to-liquid feedstocks. Short-haul operators serving Mediterranean routes face the steepest cost pass-through pressure.
Airframe leasing firms now unbundle maintenance reserves from base rentals, shifting MRO selection authority to operators. Lessors like AerCap and SMBC Aviation Capital pilot usage-based fee structures tied to flight-hour thresholds. This restructuring is most visible among low-cost carriers based at Paris-Beauvais and Lyon-Saint-Exupéry.
France Aviation Market Segmentation
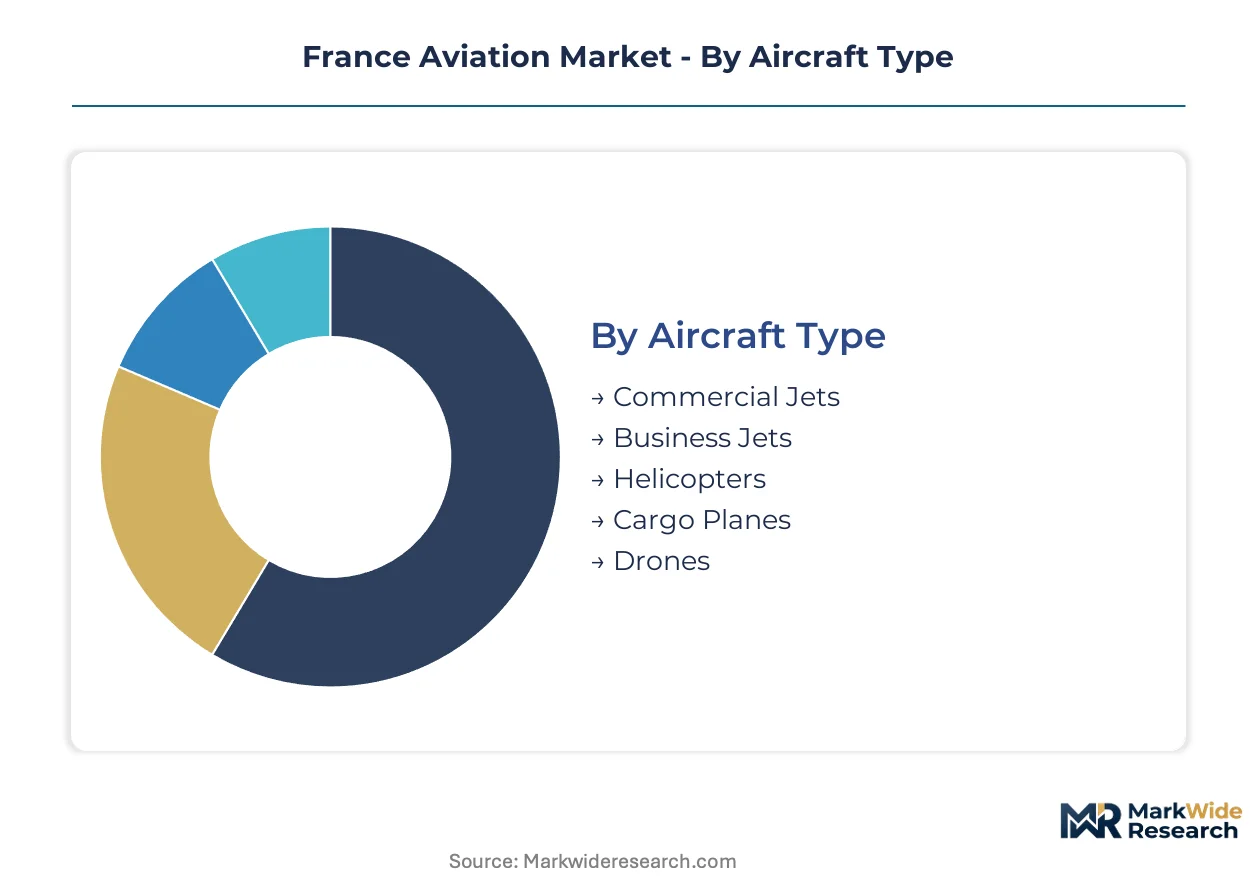
France aviation segmentation reveals how procurement authority, certification requirements, and operational mission shape supplier relationships. Buyers in this market select aircraft and service tiers based on EASA compliance obligations, fleet scale, and access to the Occitanie industrial cluster.
Aircraft Type:
Cost tier separates buyers in this category, with capital intensity and utilization patterns driving fleet composition decisions across French operators.
- Commercial Jets:Wide-body and narrow-body platforms certified to EASA CS-25 standards dominate installed fleet value. Air France-KLM and Transavia France concentrate renewal demand around Toulouse-assembled Airbus A320neo and A350 families, with SAF compatibility now a gate criterion for procurement committees.
- Drones:Civil unmanned aerial vehicles operating under DGAC beyond-visual-line-of-sight permits represent the category climbing fastest. Agricultural spraying operators in Nouvelle-Aquitaine and infrastructure inspection firms around Lyon are expanding BVLOS fleets under experimental regulatory frameworks.
- Business Jets:Dassault Falcon platforms serve corporate mobility missions from Le Bourget and Cannes-Mandelieu, with fractional ownership models compressing delivery cycles for mid-cabin configurations.
- Helicopters:Airbus Helicopters H125 and H145 variants anchor emergency medical services in Alpine regions and offshore crew transport from Marseille-Fos.
- Cargo Planes:Dedicated freighter conversions of passenger airframes support express logistics hubs at Paris-Charles de Gaulle and Lyon-Saint-Exupéry, with e-commerce volume dictating night-flight slot allocations.
Volume sits with Commercial Jets; growth tilts toward Drones.
Service Type:
Margin concentration distinguishes this category, with contract duration and technical specialization determining supplier profitability.
- Maintenance, Repair, Overhaul:Long-tail aftermarket contracts for engine and airframe overhaul generate the deepest margin pools. Safran and Air France Industries KLM Engineering hold dominant positions on CFM LEAP and Pratt & Whitney GTF servicing, with component repair authorization from EASA Part 145 facilities in Paris and Bordeaux.
- Ground Handling:Paris-Charles de Gaulle and Orly slot-constrained operations drive consolidation among Swissport and Dnata France, with turnaround time guarantees now tied to penalty clauses.
- Flight Training:ENAC and private academies in Montpellier and Grenoble supply ab-initio and type-rating capacity, with simulator fidelity requirements escalating for A350 and B787 transition courses.
Revenue concentrates in Maintenance, Repair, Overhaul; expansion is steepest in Flight Training as pilot shortage intensifies recruitment.
Customer Type:
Procurement authority and fleet scale differentiate buyers, with state-backed contracts carrying industrial offset obligations absent in private transactions.
- Airlines:Network carriers and low-cost operators at Paris-Beauvais and Lyon-Saint-Exupéry drive narrow-body demand, with leasing structures unbundling MRO selection from base rentals.
- Defense Forces:French Armed Forces procurement under the Military Programming Law mandates domestic workshare on Rafale, A400M, and NH90 programs, with Dassault Aviation and Airbus Defence and Space anchoring fighter and transport categories.
- Cargo Carriers:Express integrators and dedicated freighter operators prioritize payload-range economics on Mediterranean and intra-European lanes.
- Charter Operators:Business aviation brokers and ad-hoc carriers serve seasonal demand from Côte d'Azur airports, with empty-leg optimization platforms compressing yield management cycles.
- Flight Schools:ENAC and civilian academies order piston trainers from Daher and Diamond Aircraft, with EASA Part-FCL syllabus harmonization dictating fleet commonality.
Contract value centers on Airlines; Defense Forces anchor strategic industrial capacity.
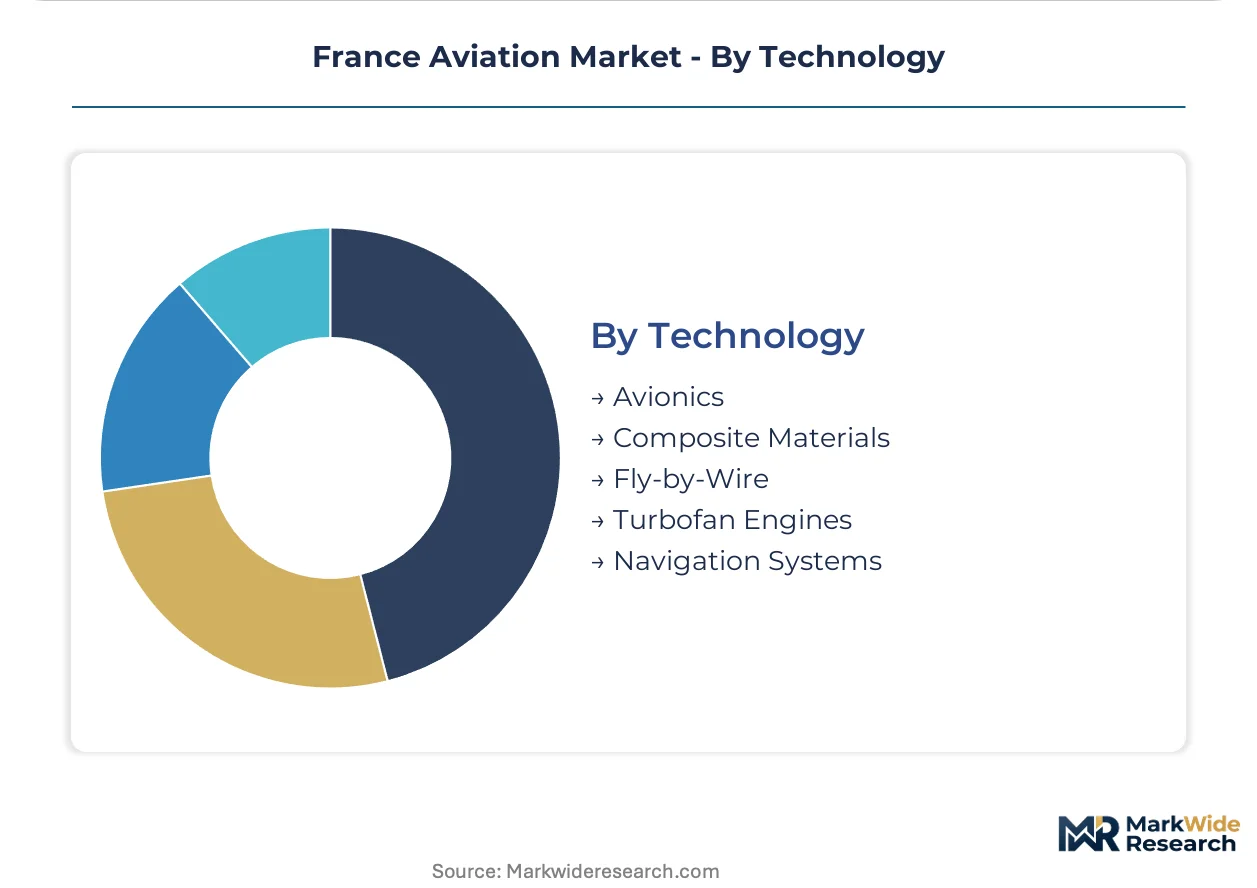
Technology:
Material substitution and control architecture evolution separate legacy platforms from next-generation specifications in this category.
- Composite Materials:Carbon fiber reinforced polymer primary structures displace aluminum in wing boxes and fuselage barrels. Airbus A350 programs at Toulouse and Saint-Nazaire drive demand for automated fiber placement and out-of-autoclave curing, though technician scarcity constrains production ramp rates.
- Turbofan Engines:High-bypass ratio propulsion systems from CFM International and Safran Aircraft Engines dominate commercial installed base, with LEAP-1A and -1B variants powering A320neo and B737 MAX fleets.
- Avionics:Integrated modular electronics from Thales and Collins Aerospace consolidate flight management, communication, and surveillance functions, with cybersecurity certification now extending EASA validation timelines.
- Fly-by-Wire:Digital flight control architectures with triple-redundant command chains anchor Airbus control philosophy, with retrofit demand minimal given fleet age profiles.
- Navigation Systems:Multi-constellation GNSS receivers with EGNOS augmentation support precision approaches at regional airports lacking ground-based infrastructure.
Adoption concentrates in Composite Materials; development investment tilts toward Turbofan Engines as SAF compatibility becomes mandatory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Occitanie aerospace cluster around Toulouse anchors French aviation production under the France 2030 tax-incentive framework, concentrating design-to-assembly pipelines within a 50-kilometer radius.
Île-de-France
Le Bourget business aviation terminals and Charles de Gaulle cargo hubs drive demand for corporate jets and dedicated freighter conversions. ANSM coordinates operational safety oversight with DGAC enforcement of EU Green Deal SAF mandates. Thales and Safran headquarters in Paris-Saclay anchor avionics and propulsion R&D allocation.
Auvergne-Rhône-Alpes
Airbus Helicopters production at Marignane and engine test facilities in Lyon sustain rotary-wing and turbofan manufacturing capacity. The Military Programming Law directs defense procurement toward regional suppliers for NH90 and Tiger program components. Saint-Étienne composites facilities supply carbon fiber structures to Toulouse assembly lines.
Provence-Alpes-Côte d'Azur
Cannes-Mandelieu business aviation infrastructure and Marseille-Fos offshore helicopter bases concentrate corporate and energy-sector fleet operations. DGAC experimental permits enable beyond-visual-line-of-sight drone testing for agricultural operators in the Var. Fos-sur-Mer refineries retool hydroprocessed ester facilities for sustainable aviation fuel production.
Nouvelle-Aquitaine
Uncontrolled airspace over Landes forest enables civil UAV beyond-visual-line-of-sight corridor development under DGAC supervision. Daher operates final assembly lines for TBM turboprops and Kodiak utility aircraft at Tarbes. Bordeaux-Mérignac hosts Dassault Aviation Falcon completion centers and France 2030 reindustrialization subsidy recipients.
Hauts-de-France
Charles de Gaulle and Orly slot-constrained ground handling operations drive consolidation among Swissport and Dnata France under turnaround time guarantee contracts. Air France Industries KLM Engineering maintains EASA Part 145 overhaul capacity at Paris-Charles de Gaulle. Le Havre refinery operators expand power-to-liquid feedstock acceptance for EU Green Deal synthetic fuel mandates.
France Aviation Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated OEMs commanding commercial wide-body programs and tiered suppliers capturing aftermarket margin pools. The vendor base organizes around three strategic archetypes: full-system integrators with design-to-assembly pipelines, propulsion and nacelle specialists with long-term engine service contracts, and composite airframe fabricators with automated fiber placement capabilities. Competitive moves concentrate on strategic partnerships for SAF-compatible propulsion architectures and capacity expansion in Occitanie cluster facilities.
Within the full-system integrator tier, Airbus SE exemplifies integrated commercial aircraft production, while Dassault Aviation occupies a position spanning military fighters and business jets. Safran SA anchors the propulsion-specialist archetype through turbofan and nacelle leadership. These three companies represent the dominant competitive anchors structuring supplier relationships and procurement authority flows across French aviation.
| Leading Market Players |
|---|
| Thales |
| DAHER |
| Airbus SE |
| Embraer S.A |
| General Dynamics Corporation |
| Safran SA |
| ATR |
| Pilatus Aircraft Ltd. |
| Dassault Aviation |
| Others |
Supply & Pricing Matrix
Carbon fiber prepreg costs cascade from Japanese and American precursor suppliers through Saint-Étienne autoclave facilities to Toulouse assembly lines, compressing margins for tier-two fabricators serving A350 derivative programs while concentrating pricing power among Occitanie cluster incumbents.
Pricing Analysis
Lead-time premiums dominate aircraft component transactions, with EASA-certified engine parts commanding 15-20% markups for 30-day turnaround versus standard 90-day cycles. Three-tier pricing structure across premium, standard, and economy levels separates OEM-authorized repairs from independent MROs and surplus parts brokers. Pricing pressure stems from EU Green Deal SAF mandates forcing premature fleet retirements and shrinking addressable aftermarket for legacy turbofan architectures. Low-cost carriers at Paris-Beauvais exhibit highest price sensitivity, while defense procurement under Military Programming Law carries lowest elasticity due to offset obligations.
Supply Chain Analysis
Logistics costs from German aluminum smelters and Spanish titanium corridors expose French airframe fabricators to Rhine barge congestion and cross-border customs friction. Primary aerospace metals draw from German, Spanish, and Italian metallurgical clusters; carbon fiber precursors rest on Japanese and American chemical suppliers; avionics semiconductors hinge on Taiwanese foundry capacity. Single-source vulnerability concentrates in LEAP engine hot-section castings from Safran's Gennevilliers facility. Distribution runs through Airbus' Saint-Nazaire logistics hub for wide-body programs and regional MRO networks for aftermarket parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
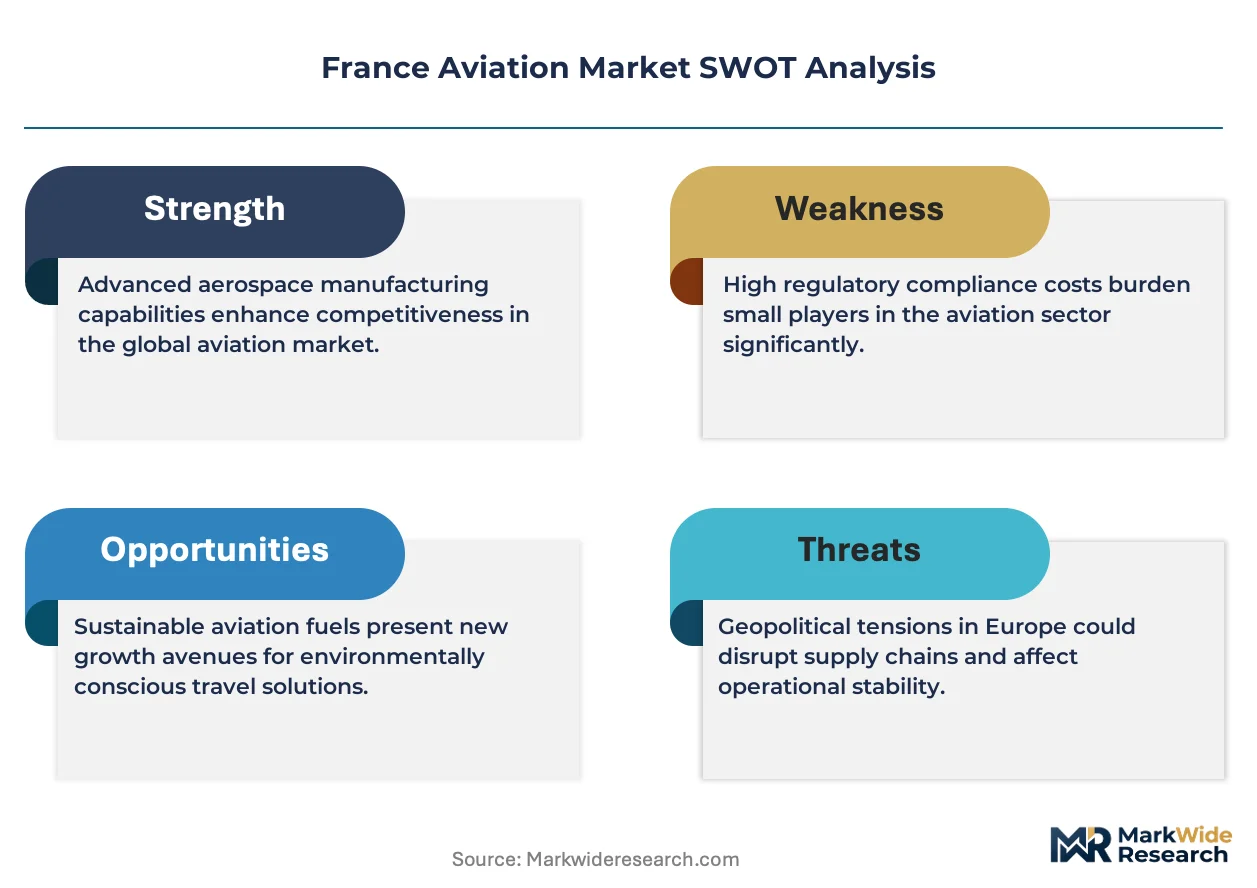
France aviation sits at a propulsion transition inflection, with hydrogen fuel cell architectures displacing regional turboprop fleets and SAF retrofit obligations compressing legacy engine residual values.
For Market Incumbents: Cement dominance in SAF-compatible propulsion architectures through captive nacelle production at Le Havre facilities and accelerated LEAP engine upgrade cycles. Lock in Military Programming Law workshare via Rafale F5 development contracts. Vertical integration into cryogenic storage systems insulates against Korean and Japanese hydrogen tank supplier bottlenecks. For New Entrants and Emerging Players: EU Green Deal SAF blending mandates in France open a window for power-to-liquid refinery partnerships at Fos-sur-Mer and Le Havre. Target the Nouvelle-Aquitaine drone corridor for BVLOS agricultural spraying platforms under DGAC experimental permits. Pursue joint-venture structures with Occitanie cluster incumbents to bypass EASA certification timeline barriers. For Investors and Strategic Acquirers: France 2030 reindustrialization subsidy allocation announcements are the leading indicator that clean aviation manufacturing capacity will concentrate in Saint-Nazaire and Bordeaux facilities. Five-to-ten-year viability favors composite airframe fabricators with automated fiber placement capabilities and established EASA Part 21G production organization approvals. Monitor DGAC hydrogen propulsion certification pathway progress as inflection signal for regional aircraft retrofit market timing.| Strategic Initiative | Industry Significance |
|---|---|
| SAF Refinery Partnership | Power-to-liquid feedstock agreements at Fos-sur-Mer secure EU Green Deal compliance for Air France-KLM. |
| Hydrogen Propulsion Certification | DGAC type validation for fuel cell regional aircraft opens Corsica and Alpine route retrofits. |
| Composite Capacity Expansion | Automated fiber placement lines at Saint-Nazaire support A350 production ramp amid technician scarcity. |
| Defense Offset Consolidation | Military Programming Law workshare aggregation strengthens Dassault's Rafale export competitiveness. |
| Drone Corridor Infrastructure | Landes forest BVLOS testing permits under DGAC supervision anchor agricultural UAV operator scaling. |
Research Methodology
Document review covered EASA certification databases, EU Green Deal regulatory filings, and Military Programming Law procurement records, complemented by interviews with Airbus procurement executives, Safran propulsion engineers, DGAC certification leads, and Air France-KLM fleet planners. Secondary validation drew from ANSM safety incident reports, France 2030 investment plan disclosures, and Occitanie cluster economic development data. Bottom-up fleet demand modeling triangulated against top-down GDP-aviation elasticity benchmarks.
Installed base value projections and service revenue trajectories across the analysis window reflect segment-level CAGRs derived from airframe delivery backlogs and engine shop visit intervals. Segmentation dimensions modeled include aircraft type, service tier, customer procurement authority, and propulsion technology generation. Forecast inputs incorporated SAF infrastructure buildout pace, EASA certification timeline distributions, and Military Programming Law budget appropriation cycles.
The model assumes a particular technology adoption path; alternative pathways for hydrogen propulsion would alter the outlook if cryogenic storage weight penalties exceed 15% of payload capacity. Forecasts reflect assumptions regarding EU Green Deal mandate enforcement timing and reindustrialization subsidy allocation efficiency. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
UK Military Aviation Market
Aircraft
Middle East and Africa Military Helicopters Market
Aircraft
Aerospace Turbojet Market
Aircraft
North America General Aviation Market
Aircraft
Online in-Flight Shopping Market
Aircraft
Global Electronic Flight Bag Market
Aircraft
Commercial Turboprop Aircrafts Market
Aircraft
Civil Helicopter Market
Aircraft
India Winglets Market
Aircraft
Aircraft Lavatory System Market
Aircraft
Aircraft Flight Control Computers Market
Aircraft
Ultra-Light Aircraft Market
Aircraft
Air Speed Indicator Market
Aircraft
Aerobatic Aircraft Market
Aircraft
Asia-Pacific Aircraft Windshield Wiper and Washer System Market
Aircraft
Middle East and Africa Aviation Market