
 Europe Helicopters Market | 2026-2036
Europe Helicopters Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Helicopters Market Foresight
REACH compliance is recalibrating the cost-of-entry calculus for helicopter manufacturers serving European operators. Airbus Helicopters SAS leverages its vertically integrated supply chain to absorb regulatory compliance costs while sustaining production scale across its Marignane facility. Leonardo S.p.A anchors its competitive position through specialized tiltrotor and naval helicopter architectures that navigate Italy's domestic procurement preferences and NATO interoperability requirements.
A helicopter is a rotary-wing aircraft generating lift and thrust via horizontally spinning rotor blades, typically powered by turboshaft engines operating at rotational speeds between 200 and 500 RPM depending on configuration, designed for vertical takeoff, hover, and low-speed maneuverability inaccessible to fixed-wing platforms. Civil Helicopters occupy the largest revenue pool across Europe driven by offshore oil-and-gas logistics and executive transport, while Military Helicopters concentrate margin in upgrade-and-retrofit programs as governments prioritize fleet modernization over new-build procurement. Multi-Rotor technology leads the technology dimension in unmanned applications, though Single-Rotor architectures dominate manned commercial and defense segments through proven payload-range economics.
EMA airworthiness standards and the EU AI Act jointly shape product certification timelines and autonomous flight system development for next-generation platforms. EASA operational regulations governing pilot training hours and noise abatement corridors directly influence fleet utilization rates and route economics for urban air mobility entrants. Stakeholders must monitor how CSRD disclosure requirements will reshape supplier due diligence and capital allocation across the European helicopter value chain.
Market Dynamics
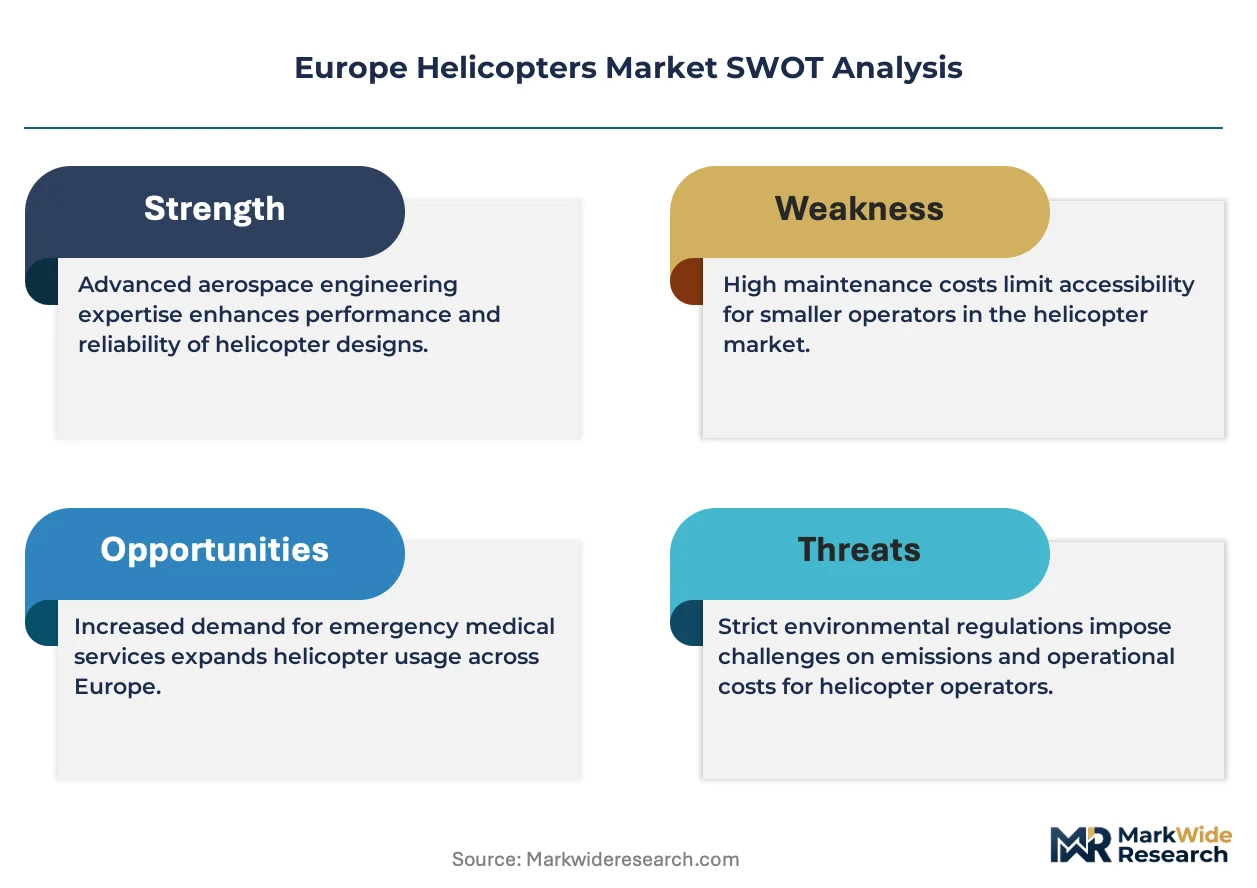
REACH compliance and the EU Green Deal are compressing the operational envelope for turbine-powered platforms while accelerating investment in hybrid-electric architectures and sustainable aviation fuel certification pathways.
Growth Catalysts
- EU Green Deal mandates:Binding emissions targets for turbine engines are forcing fleet operators toward newer, cleaner platforms and creating replacement demand across Germany, France, and Italy.
- Offshore wind expansion:North Sea energy logistics require heavy-lift rotorcraft for turbine maintenance, driving procurement from Danish and Dutch operators.
- EMS fleet modernization:Western European health systems are retiring aging airframes in favor of IFR-capable platforms with enhanced patient-care modules.
Market Restraints
- Turboshaft engine supply concentration:Production of critical powerplants clusters with two North American and one European OEM, exposing buyers to allocation risk during demand surges.
- Specialized alloy input costs:Titanium and nickel-based superalloy prices fluctuate with aerospace demand cycles, compressing margin on fixed-price contracts.
- Airframe certification timelines:EASA CS-29 amendments for crashworthiness and fuel system integrity extend type certification by 18-24 months versus historical baselines.
Strategic Opportunities
- Eastern European defense procurement:NATO interoperability requirements in Poland, Romania, and the Baltic states are opening tenders for utility and attack helicopter platforms.
- Urban air mobility corridors:EASA SC-VTOL certification frameworks enable eVTOL entrants to access controlled airspace above Milan, Paris, and Barcelona metropolitan zones.
- Sustainable aviation fuel blending mandates:The EU ReFuelEU Aviation regulation creates guaranteed offtake for SAF-certified turbine operators serving offshore energy routes.
Industry Challenges
- Flight crew training pipeline gaps:EASA Part-FCL instrument rating requirements and simulator availability constraints limit qualified pilot throughput for IFR EMS and offshore operations.
- Legacy avionics integration complexity:Retrofitting digital glass cockpits into 1980s-era airframes demands custom engineering that strains MRO capacity and certification resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Helicopters Market |
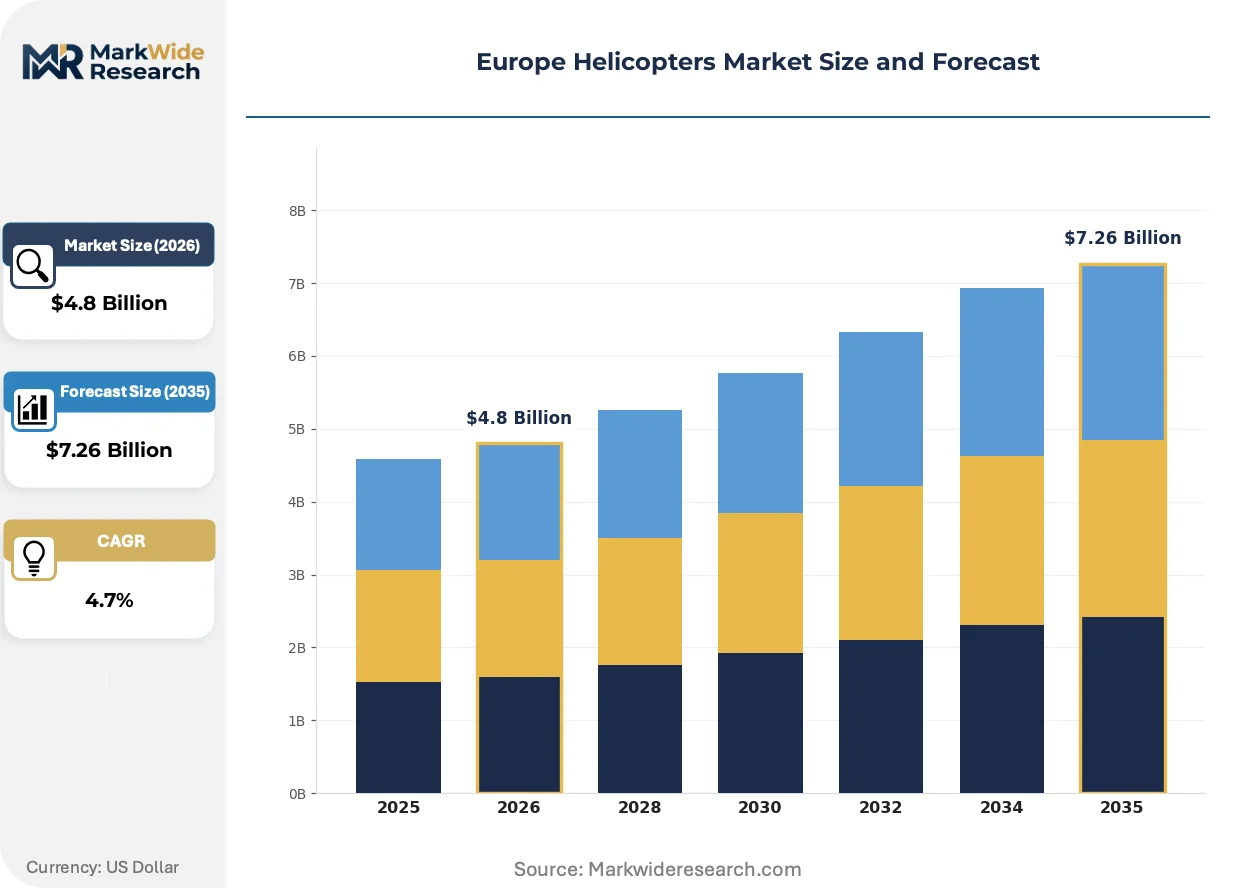
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.26 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Civil Helicopters, Military Helicopters, Cargo Helicopters, Utility Helicopters Technology: Multi-Rotor, Single-Rotor, Coaxial, Compound Application: Emergency Services, Law Enforcement, Air Ambulance, Tourism End User: Government Agencies, Private Operators, Commercial Airlines, EMS Providers |
| Companies Covered | The Boeing Company, Lockheed Martin Corporation, Airbus Helicopters SAS, Turkish Aerospace Industries, BAE Systems, Leonardo S.p.A, Textron Inc., Rostec, Russian Helicopters, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Helicopters Market Shifts & Advancements
Hybrid-electric propulsion architectures and autonomous flight systems are displacing conventional mechanical designs across multiple mission profiles, while regulatory frameworks race to certify platforms that did not exist when current airworthiness standards were drafted.
Hybrid-electric drivetrains combine turbine engines with battery-electric boost systems to optimize fuel burn during hover and high-power phases. Offshore operators in the North Sea are piloting these configurations for crew-change missions to reduce fuel costs and emissions exposure. This technology is electrifying the mid-weight utility segment by enabling single-engine equivalent economics with twin-engine redundancy margins.
The EU AI Act establishes conformity assessment requirements for autonomous decision-making systems in aviation, including obstacle detection and emergency landing algorithms. Manufacturers must demonstrate explainability and human oversight protocols before EASA will grant operational approval. Urban air mobility developers face the steepest compliance burden as their business models depend on reduced-crew or single-pilot operations.
Service contracts are unbundling from airframe sales as operators seek to transfer residual value risk to OEMs and lessors. Norwegian and UK offshore fleet managers now prefer power-by-the-hour arrangements with guaranteed availability clauses over traditional time-and-material MRO. This restructuring concentrates working capital requirements with manufacturers while giving operators predictable unit economics across volatile flight-hour environments.
Europe Helicopters Market Segmentation
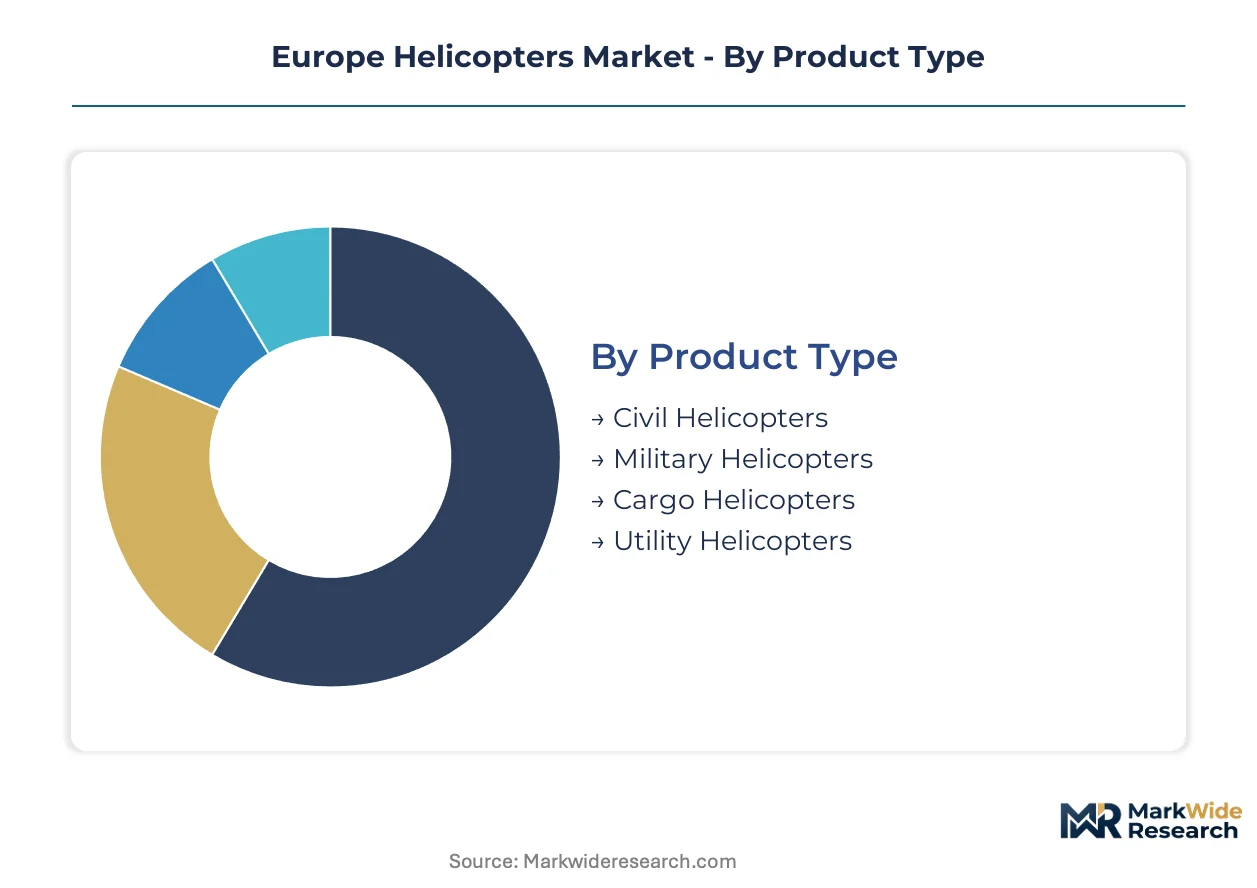
Helicopter procurement in Europe follows mission-specific performance requirements rather than generic platform categories. Buyers prioritize payload-range economics, certification timelines, and regulatory compliance pathways when selecting across product, technology, and end-use segments.
Product Type:
Defense ministries and offshore energy operators drive platform selection through operational envelope requirements and fleet standardization mandates.
- Civil Helicopters:Turboshaft-powered platforms certified under EASA CS-29 for passenger transport and executive missions. North Sea offshore logistics and corporate shuttle services in Germany, France, and Italy concentrate demand for IFR-capable twin-engine configurations.
- Military Helicopters:Combat and utility rotorcraft designed for NATO interoperability, troop transport, and battlefield reconnaissance. Eastern European defense modernization in Poland and Romania is expanding procurement for multi-role platforms with digital avionics suites.
- Cargo Helicopters:Heavy-lift configurations optimized for external load operations and logistics support.
- Utility Helicopters:Versatile platforms spanning training, light transport, and surveillance missions with modular mission equipment.
Volume sits with Civil Helicopters; growth tilts toward Military Helicopters.
Technology:
Architectural choices reflect trade-offs between mechanical complexity, power efficiency, and autonomous flight readiness.
- Multi-Rotor:Electric and hybrid-electric configurations with distributed propulsion for unmanned cargo and urban air mobility. EASA SC-VTOL certification frameworks in Milan and Paris are enabling commercial deployment of eVTOL platforms for last-mile logistics.
- Single-Rotor:Conventional main-rotor/tail-rotor designs dominating manned commercial and defense segments through proven reliability and established MRO networks. German and French operators favor these architectures for EMS and offshore crew-change missions.
- Coaxial:Counter-rotating rotor systems eliminating tail rotor requirements for compact footprint operations.
- Compound:Hybrid designs combining rotor lift with fixed-wing thrust for high-speed transit applications.
Single-Rotor architectures retain volume dominance; Multi-Rotor systems are expanding most quickly.
Application:
Mission profiles dictate equipment specifications, from patient-care modules to surveillance sensor packages.
- Emergency Services:Rapid response platforms with winch systems, searchlights, and rescue hoists for disaster relief and mountain rescue. Alpine regions in Switzerland and Austria deploy these fleets for high-altitude extraction missions.
- Air Ambulance:IFR-equipped rotorcraft with intensive-care interiors for inter-hospital patient transfer. Western European health systems in the UK, Germany, and Netherlands are retiring aging airframes for next-generation platforms with enhanced medical capabilities.
- Law Enforcement:Surveillance and patrol configurations with electro-optical sensors and secure communications.
- Tourism:Sightseeing and charter operations serving scenic corridors and urban experiences.
Air Ambulance commands procurement volume; Emergency Services shows the steepest expansion trajectory.
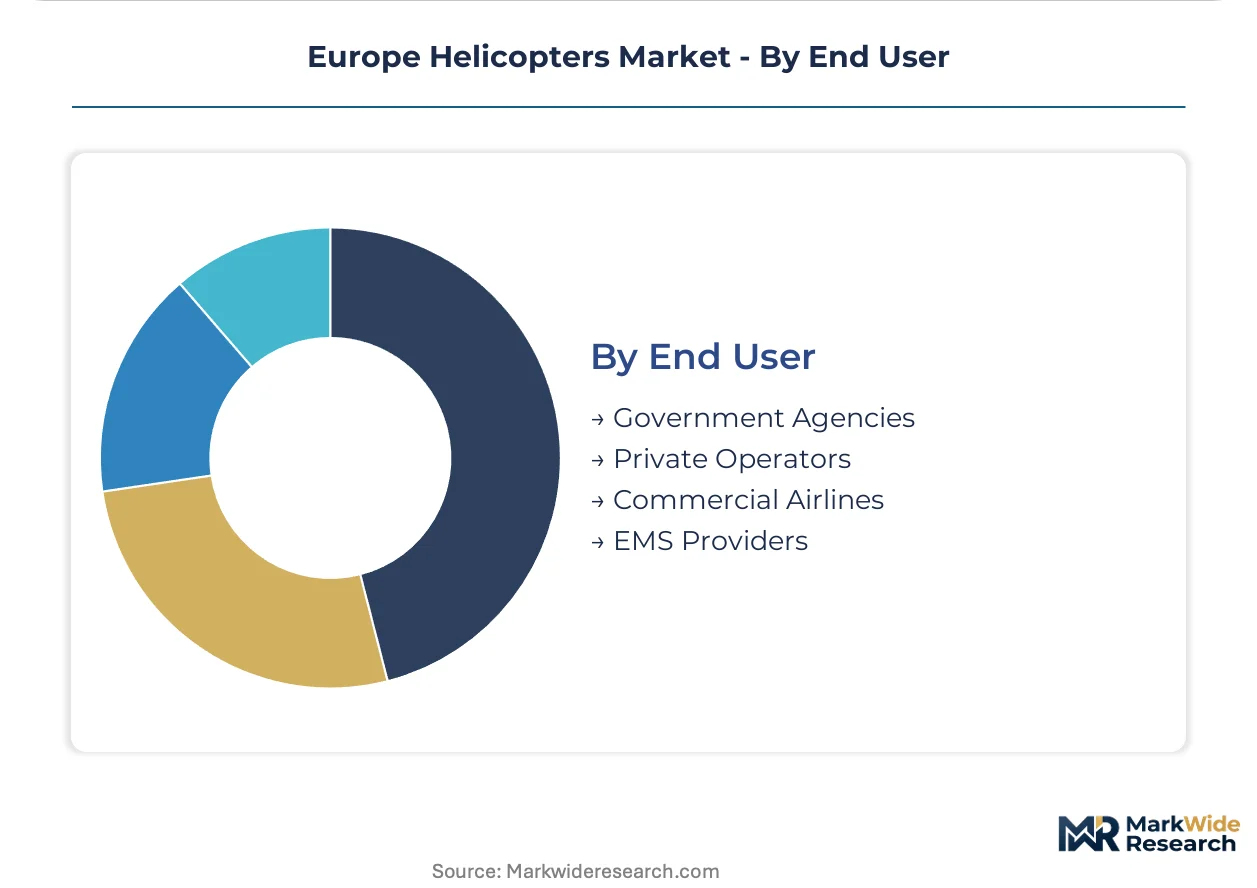
End User:
Capital structure and risk tolerance differentiate buyer behavior across public and private operators.
- EMS Providers:Specialized air medical operators with dedicated pilot and clinical crews operating under EASA Part-CAT and Part-SPA. Fleet managers in France and Italy prefer power-by-the-hour contracts to transfer residual value risk to OEMs.
- Government Agencies:Defense ministries, coast guards, and national police forces with sovereign procurement authority and NATO alignment requirements. Polish and Romanian defense budgets are accelerating utility and attack helicopter tenders.
- Private Operators:Corporate flight departments and charter services with asset-light leasing strategies.
- Commercial Airlines:Scheduled helicopter services connecting urban centers and offshore installations.
EMS Providers anchor current fleet investment; Government Agencies are gaining share fastest through defense modernization programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense modernization and offshore energy logistics concentrate demand across Germany, France, and Italy, while Eastern European NATO members accelerate procurement for interoperability requirements.
Germany
Bundeswehr fleet renewal and North Sea offshore wind maintenance drive twin-engine utility procurement. The EU Green Deal mandates compress operational envelopes for aging turbine platforms, forcing replacement cycles. Airbus Helicopters SAS maintains production scale at its Marignane facility to serve German EMS and defense operators.
France
Air medical fleet expansion and naval helicopter modernization anchor domestic demand. EASA CS-29 amendments for crashworthiness extend certification timelines for new platforms. The Provence-Alpes-Côte d'Azur corridor hosts intensive pilot training infrastructure for IFR-capable EMS operations.
Italy
Leonardo S.p.A anchors specialized tiltrotor and naval architectures serving domestic procurement preferences. NATO interoperability requirements shape multi-role platform selection for airborne early warning and utility missions. The Lazio region concentrates final assembly and systems integration capacity for Mediterranean defense exports.
United Kingdom
North Sea oil-and-gas logistics and coast guard search-and-rescue sustain heavy-lift demand. Power-by-the-hour contracting preferences transfer residual value risk from offshore fleet managers to OEMs. Aberdeen and Great Yarmouth harbor specialized MRO infrastructure for turbine engine overhaul.
Poland
NATO defense modernization programs accelerate attack and utility helicopter tenders. The EU ReFuelEU Aviation regulation creates blended sustainable aviation fuel mandates for turbine operators. Warsaw defense procurement offices prioritize platforms with established interoperability across allied force structures.
Europe Helicopters Market Competitive Landscape
European producers anchor the integrated systems tier; North American specialists hold the heavy-lift and attack platform segments. The vendor structure concentrates around three strategic archetypes: vertically integrated OEMs with captive engine supply, tiltrotor and specialized naval architects, and government-backed national champions. Competitive positioning hardens through M&A consolidation of avionics suppliers and strategic partnerships for hybrid-electric propulsion development.
Within the European integrated tier, Airbus Helicopters SAS and Leonardo S.p.A exemplify divergent specialization strategies—one leveraging production scale across utility and EMS segments, the other anchoring naval and tiltrotor architectures. Among North American heavy-lift specialists, The Boeing Company and Lockheed Martin Corporation occupy positions shaped by defense export licensing and NATO procurement alignment. Turkish Aerospace Industries represents the emerging national champion archetype, building indigenous capacity through licensed production and regional defense partnerships.
| Leading Market Players |
|---|
| The Boeing Company |
| Lockheed Martin Corporation |
| Airbus Helicopters SAS |
| Turkish Aerospace Industries |
| BAE Systems |
| Leonardo S.p.A |
| Textron Inc. |
| Rostec |
| Russian Helicopters |
| Others |
Supply & Pricing Matrix
EU Green Deal emissions mandates are forcing fleet operators toward newer turbine platforms, compelling manufacturers to absorb compliance costs while defending margin positions through captive engine supply and long-term service contracts. This demand-side pressure reshapes how OEMs structure pricing across civil and defense segments.
Pricing Analysis
Volume concentrates in civil twin-engine configurations while margin pools in military upgrade programs and specialized naval architectures. Three-tier pricing structure across premium IFR-certified platforms, standard VFR utility models, and economy training helicopters reflects certification grade and after-sales bundling intensity. Cost compression in the mid-weight utility segment is intensifying because REACH compliance and sustainable aviation fuel certification add fixed overhead. EMS providers in France and Italy show highest price sensitivity due to power-by-the-hour contracting preferences, while Eastern European defense ministries prioritize NATO interoperability over unit cost.
Supply Chain Analysis
Refurbishment flows for 1980s-era airframes strain MRO capacity as operators extend service life rather than absorb new-build certification delays. Critical turboshaft engine production clusters in the United States and France, with titanium and nickel-based superalloy sourcing anchored in aerospace demand cycles. Single-source vulnerability for specialized avionics components creates allocation risk during fleet modernization surges. Distribution runs through OEM-direct channels for defense procurement and specialized lessors for civil offshore operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Helicopters Market operates as a cost-of-compliance story where REACH and EU Green Deal standards erect regulatory moats favoring vertically integrated incumbents with captive certification resources.
For Market Incumbents: Deepen backward integration into turboshaft engine supply to insulate against North American OEM allocation risk during Eastern European defense procurement surges. Expand Marignane and Lazio region final assembly capacity to capture NATO interoperability-driven demand from Poland and Romania while accelerating hybrid-electric R&D to preempt eVTOL entrants in urban air mobility corridors. For New Entrants and Emerging Players: EASA SC-VTOL certification frameworks in France and Italy open a window for electric multi-rotor platforms targeting last-mile logistics above Milan and Paris metropolitan zones. Target unmanned cargo applications in North Sea offshore wind maintenance where incumbents lack optimized payloads. Pursue power-by-the-hour partnerships with Norwegian and UK fleet managers to transfer residual value risk and secure guaranteed utilization. For Investors and Strategic Acquirers: The window for entry favors mid-cap avionics specialists with EASA CS-29 amendment compliance capabilities. Long-term viability rests on positioning for defense modernization cycles and sustainable aviation fuel infrastructure buildout. Monitor Polish and Romanian tender announcements for attack and utility helicopter platforms as inflection indicators for regional procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Electric Propulsion Development | Combines turbine engines with battery-electric boost to optimize fuel burn during North Sea hover operations. |
| EASA SC-VTOL Certification Pathway | Enables eVTOL entrants to access controlled airspace above Milan, Paris, and Barcelona metropolitan zones. |
| Power-by-the-Hour Contract Expansion | Transfers residual value risk from offshore fleet managers to OEMs while guaranteeing availability clauses. |
| Backward Integration into Engine Supply | Insulates against Safran and Pratt & Whitney allocation risk during Eastern European demand surges. |
| NATO Interoperability Alignment | Unlocks Polish and Romanian defense tenders requiring standardized communication and weapon systems. |
Research Methodology
Multi-period observation of fleet utilization rates, certification timeline extensions, and sustainable aviation fuel blending mandates anchored the trend analysis, supplemented by interviews with EMS fleet managers, defense procurement officers, MRO facility directors, and EASA certification specialists. Secondary validation drew from EASA CS-29 amendment filings, EU ReFuelEU Aviation regulatory texts, NATO standardization agreements, and customs data on titanium and superalloy trade flows. Bottom-up platform-level demand estimates triangulated against top-down defense budget allocations across Germany, France, Italy, Poland, and Romania.
Input-output matrices mapped turboshaft engine supply constraints against offshore wind installation schedules and EMS fleet replacement cycles across the projection horizon. Segmentation dimensions modeled include product type, technology architecture, mission application, and end-user capital structure, with additional granularity on EASA Part-CAT versus Part-SPA operational categories. CAGRs derived from regression analysis of historical procurement patterns against regulatory compliance cost trajectories, incorporating hybrid-electric technology readiness levels and SAF infrastructure deployment timelines as scenario variables.
The model assumes a particular technology adoption path; alternative pathways for battery-electric range extension or hydrogen fuel cell integration would alter the outlook for mid-weight utility segment economics. Practitioners should monitor EASA CS-29 amendment implementation pace and Polish defense tender award announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aircraft Door Market
Aircraft
North America Light and Very Light Jets Market
Aircraft
Tandem Rotor Helicopter Market
Aircraft
Ultra-Light Aircraft Market
Aircraft
Autonomous Aircraft Propulsion Systems Market
Aircraft
Commercial Aircraft Landing Gear Market
Aircraft
Aerobatic Aircraft Market
Aircraft
Latin America General Aviation Market
Aircraft
Aircraft Autopilot System Market
Aircraft
Global Commercial Aircraft Windows and Windshields Market
Aircraft
Attack Helicopter Market
Aircraft
America Freighter Aircraft Market
Aircraft
Air Speed Indicator Market
Aircraft
US Business Jet Market
Aircraft
Australia Aviation Market
Aircraft
Japan Aerospace and Defense Market