
 Global Business Jets Market | 2026-2036
Global Business Jets Market Size, Share, and Industry Trends Forecast 2026-2036
Global Business Jets Market Analysis
Fractional ownership and operating lease structures is fragmenting the traditional dedicated-purchase model across business aviation. Bombardier Inc. leverages its Global and Challenger families to sustain dominance in the ultra-long-range and large-cabin segments. Gulfstream Aerospace Corporation differentiates through cabin altitude and speed capabilities, while Embraer S.A. competes aggressively in the light and midsize tiers with its Phenom and Praetor lines.
Business jets are turbine-powered aircraft designed for private or corporate transport, typically seating four to nineteen passengers and operating at altitudes above commercial air traffic with cruise speeds exceeding Mach 0.80. Light Jets serve entry-level buyers and short-haul missions where acquisition cost and runway performance constrain selection, while Ultra-Long-Range Jets command the widest margin pools by enabling nonstop intercontinental flights for trans-Pacific and Middle East-to-Americas routes. Charter Operators represent the fastest-growing end-user channel as asset-light travel preferences expand among corporations reducing capital deployment on balance-sheet aircraft.
The FAA enforces Part 25 certification standards that govern airworthiness and operational limits for business jets in the United States, while EASA applies its CS-25 framework across European jurisdictions with escalating focus on noise and emissions compliance. China's CAAC implements type certification reciprocity agreements that condition market access for foreign original equipment manufacturers. Stakeholders must monitor SAF blending mandates and carbon border adjustments as these frameworks increasingly determine fleet planning timelines and residual value curves.
Market Dynamics
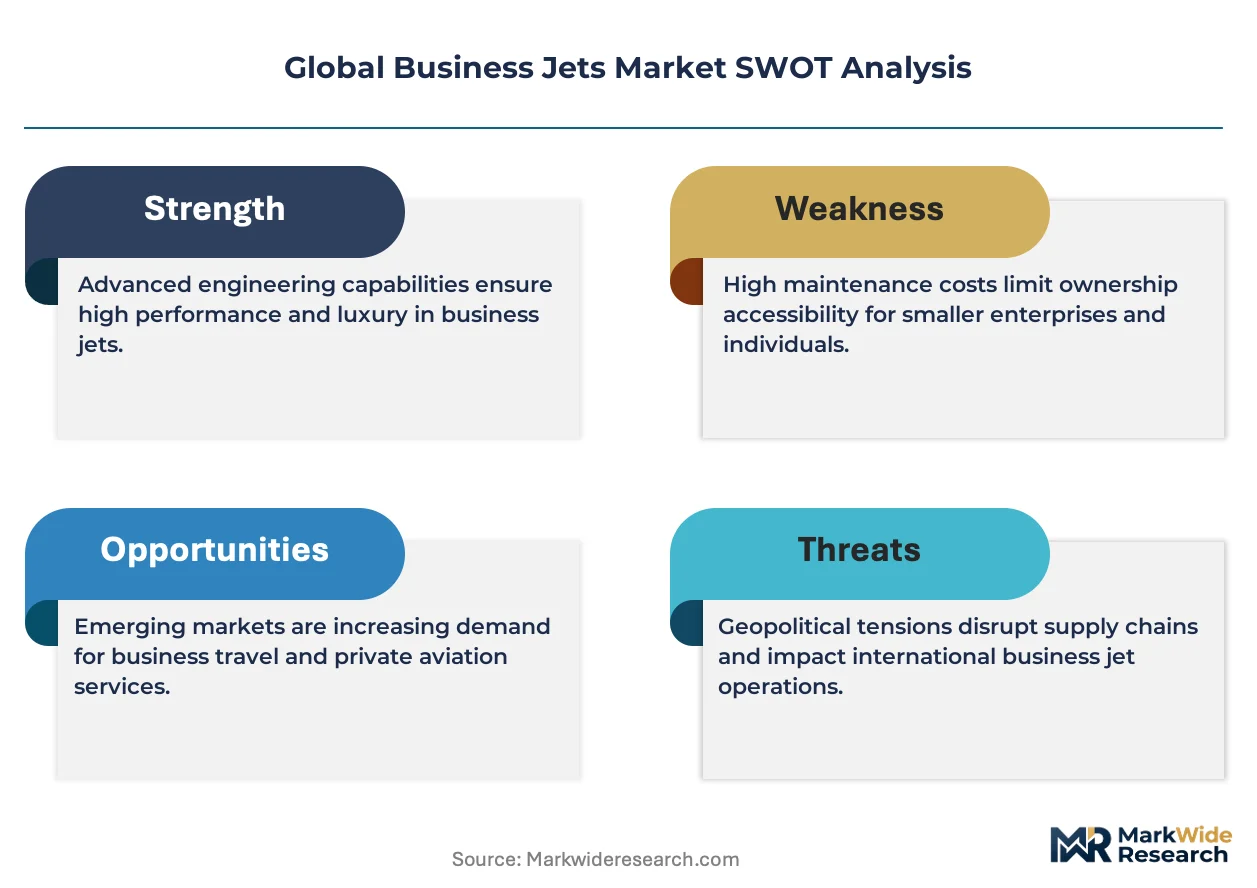
ICAO carbon offset rules and sustainable aviation fuel mandates are compressing fleet renewal timelines while fragmenting ownership models across business aviation, forcing operators to restructure capital deployment around asset-light configurations.
Growth Catalysts
- SAF blending mandates:ICAO's Carbon Offsetting and Reduction Scheme for International Aviation compels corporate flight departments to accelerate aircraft replacements with fuel-efficient platforms certified for higher SAF ratios.
- Airspace liberalization:China's CAAC relaxation of general aviation access in low-altitude corridors opens direct routing for private operators between second-tier cities, cutting block times on domestic trunk routes.
- Fractional ownership platforms:Asset-light travel preferences among Fortune 500 treasury departments are displacing balance-sheet acquisitions with hourly-access contracts that transfer residual value risk to fleet managers.
Market Restraints
- Jet fuel price volatility:Gulf Coast kerosene benchmarks expose operators to margin erosion that cannot be fully passed through to charter clients under fixed-rate contracts.
- Engine OEM concentration:Pratt & Whitney and Rolls-Royce control propulsion supply for the ultra-long-range segment, creating single-source vulnerability for airframers developing clean-sheet designs.
- Runway infrastructure gaps:Secondary airports in India and Southeast Asia lack precision approach capabilities that would unlock point-to-point missions for light and midsize jets.
Strategic Opportunities
- Brazil's agribusiness corridors:Soy and beef processing clusters in Mato Grosso and Goiás generate unserved demand for turboprop-to-jet upgrades among commodity traders managing just-in-time supply chains.
- Electrification convergence:Battery-electric propulsion for sub-500 nautical mile missions is hybridizing with conventional turbine architectures to create parallel hybrid demonstrators targeting the light jet segment.
- EU carbon border adjustments:The Carbon Border Adjustment Mechanism creates regulatory arbitrage for European-registered operators acquiring newer aircraft with verified lifecycle emissions documentation.
Industry Challenges
- Part 25 certification timelines:FAA validation of new avionics suites and fly-by-wire systems extends development cycles, delaying revenue service entry for clean-sheet programs.
- Supply chain reconfiguration friction:Titanium and specialty alloy sourcing from Russian suppliers requires qualification of alternative vendors, freezing engineering change orders on in-production airframes.
- Flight crew training capacity:Simulator availability constraints at CAE and FlightSafety International bottleneck type rating throughput just as fractional fleets expand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Business Jets Market |
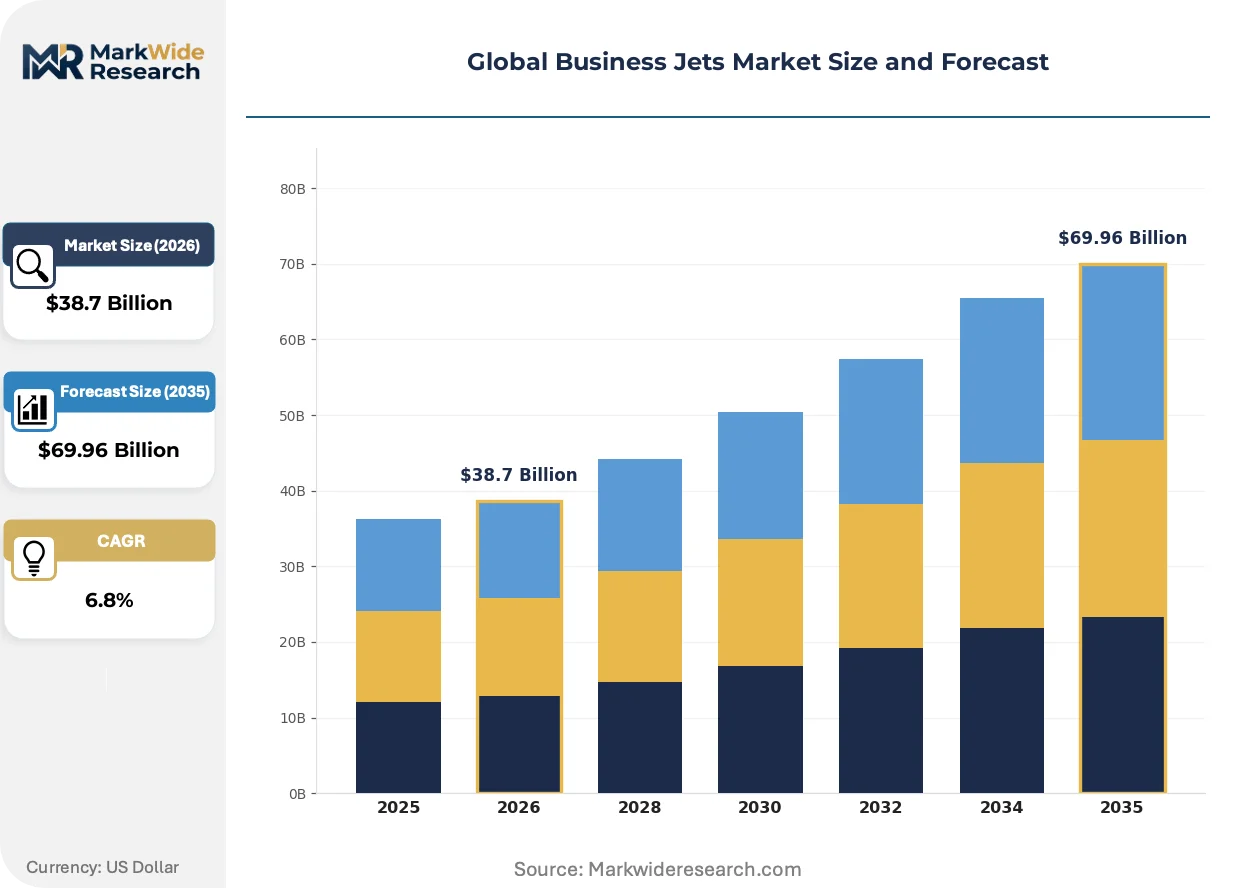
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Light Jets, Midsize Jets, Large Jets, Ultra-Long-Range Jets End User: Corporate, Government, Private, Charter Operators Engine Type: Turbofan, Turboprop, Piston, Hybrid Service Type: Charter, Dedicated Ownership, Fractional Ownership, Leasing |
| Companies Covered | Bombardier Inc., Gulfstream Aerospace Corporation, Dassault Aviation, Embraer S.A., Textron Aviation Inc., The Boeing Company, Airbus SAS, Honda Aircraft Company, General Dynamics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Business Jets Market Emerging Trajectories
Propulsion architectures and certification frameworks are converging to redefine performance benchmarks across cabin classes, while ownership structures fragment in response to capital efficiency pressures.
Hybrid-electric propulsion systems for light jet applications are hybridizing turbine reliability with battery-augmented takeoff performance. Charter operators in the United States and United Arab Emirates are evaluating these configurations for 300-400 nautical mile shuttle missions. The technology is hybridizing acquisition cost structures by reducing engine maintenance reserves and enabling smaller turbine cores.
EASA's CS-25 noise and emissions compliance escalation is tightening certification thresholds for Stage 5 noise limits and NOx standards. European-registered operators face accelerated retirement of pre-2010 airframes that cannot be retrofitted with compliant engine nacelles. The large-cabin segment is responding with factory-installed acoustic treatments and chevron nozzle designs that add weight but preserve airport access.
Hourly-access membership models are displacing traditional quarter-share fractional structures among North American corporate travel managers. NetJets and Flexjet are consolidating demand from mid-cap companies that previously maintained wholly owned aircraft. This pattern concentrates most visibly in the United States, where tax treatment of operating leases favors expense recognition over depreciation schedules.
Global Business Jets Market Segmentation
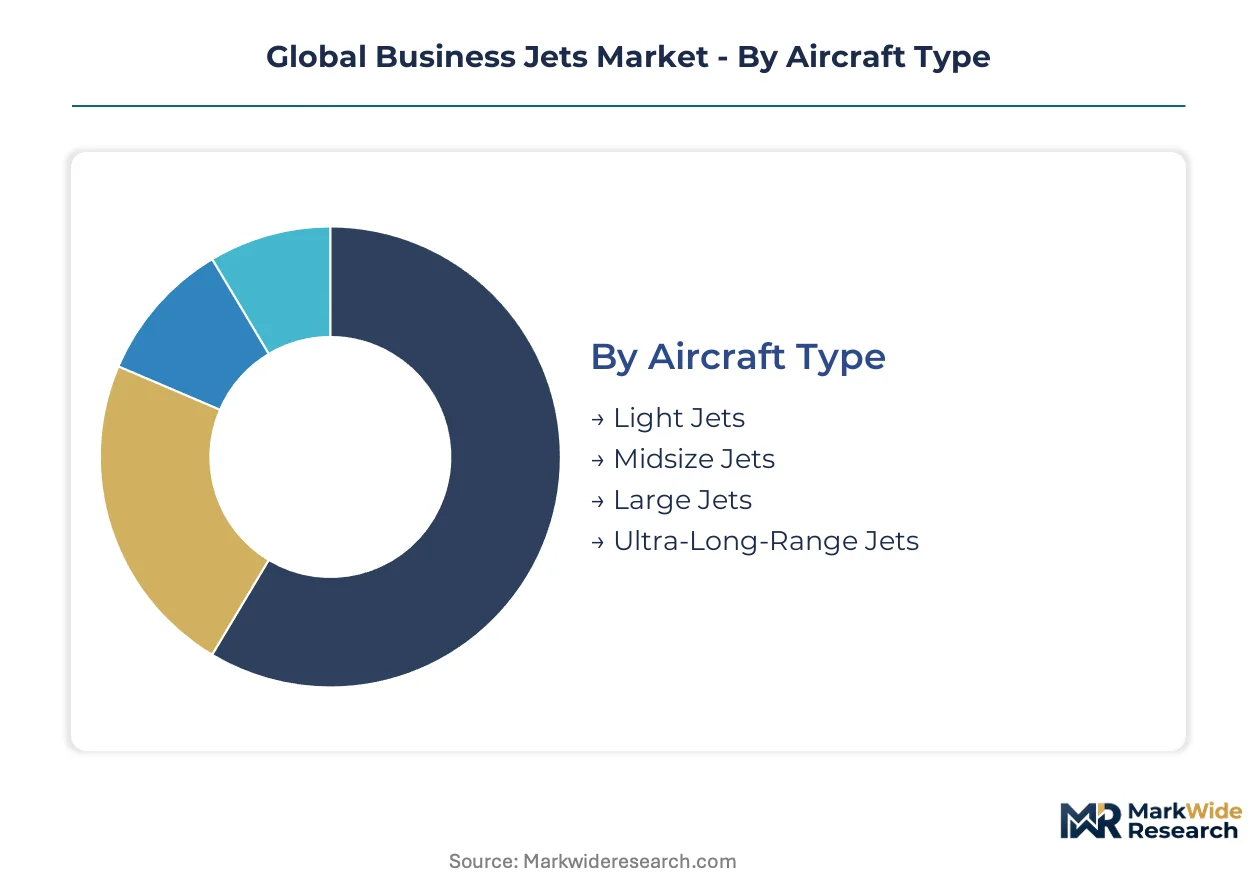
Segmentation in business aviation reveals how capital deployment, operational requirements, and regulatory exposure fragment across buyer profiles. Fleet managers use these categories to align aircraft capability with mission profiles and ownership cost structures.
Aircraft Type:
After-sales-service intensity varies sharply across cabin classes, with engine maintenance reserves and avionics upgrade cycles driving lifetime cost divergence between light and ultra-long-range platforms.
- Light Jets:Entry-level platforms seating four to eight passengers with maximum ranges below 2,000 nautical miles. Demand concentrates among owner-operators in the United States accessing secondary airports with shorter runways, constrained by acquisition budgets and single-pilot certification requirements.
- Midsize Jets:Transcontinental-capable aircraft bridging cabin comfort with operating economics. Corporate flight departments in Texas and California deploy these for coast-to-coast missions without refueling stops, balancing passenger load against fuel burn efficiency.
- Large Jets:Intercontinental platforms with stand-up cabins and full galleys. Demand clusters with Fortune 500 headquarters in Illinois and New York where executive travel requires sleep-capable configurations.
- Ultra-Long-Range Jets:Nonstop trans-Pacific and Middle East-to-Americas capability with premium cabin altitude systems. Sovereign wealth funds and family offices in the United Arab Emirates and Singapore drive specification intensity for these highest-margin airframes.
By volume, Light Jets leads. By growth pace, Ultra-Long-Range Jets is ahead.
End User:
Customer type determines acquisition financing structures and utilization patterns, with treasury departments imposing divergent capital efficiency thresholds across corporate and private ownership models.
- Corporate:Flight departments managing balance-sheet aircraft for C-suite mobility. United States-based multinationals in technology and financial services dominate this channel, prioritizing schedule control over charter availability.
- Government:State-owned fleets for head-of-state transport and ministry operations. Procurement in Saudi Arabia and Qatar emphasizes security specifications and diplomatic protocol compliance over unit economics.
- Private:Individual high-net-worth owners seeking exclusive asset control. Demand in Monaco and Geneva clusters around large-cabin acquisitions with bespoke interior completions.
- Charter Operators:Asset-light fleet managers selling hourly access to diversified client bases. This channel is expanding most quickly in the United States and United Arab Emirates as mid-cap corporations abandon wholly owned aircraft.
Corporate maintains the largest installed base. Charter Operators is climbing the fastest.
Engine Type:
Propulsion architecture dictates maintenance intervals, fuel compatibility, and residual value trajectories, with OEM concentration creating supply vulnerability for clean-sheet programs.
- Turbofan:High-bypass jet engines dominating business aviation above light-jet categories. Pratt & Whitney and Rolls-Royce supply these for ultra-long-range platforms, with SAF certification becoming a discriminator for fleet renewal decisions.
- Turboprop:Gas turbine driving propellers for short-field performance and fuel efficiency. Brazilian agribusiness corridors in Mato Grosso favor these for unpaved airstrip access, though jet upgrades are accelerating.
- Piston:Reciprocating engines limited to very light jet derivatives and legacy airframes. Training fleets in Florida and Arizona retain these for cost-sensitive ab initio instruction.
- Hybrid:Battery-electric augmentation of turbine cores for takeoff power reduction. Demonstrator programs in the United States target 300-400 nautical mile shuttle missions with reduced engine maintenance reserves.
Turbofan commands revenue concentration. Hybrid is gaining share fastest.
Service Type:
Ownership structure fragmentation reflects capital efficiency pressures, with tax treatment and residual value risk transfer determining contract selection.
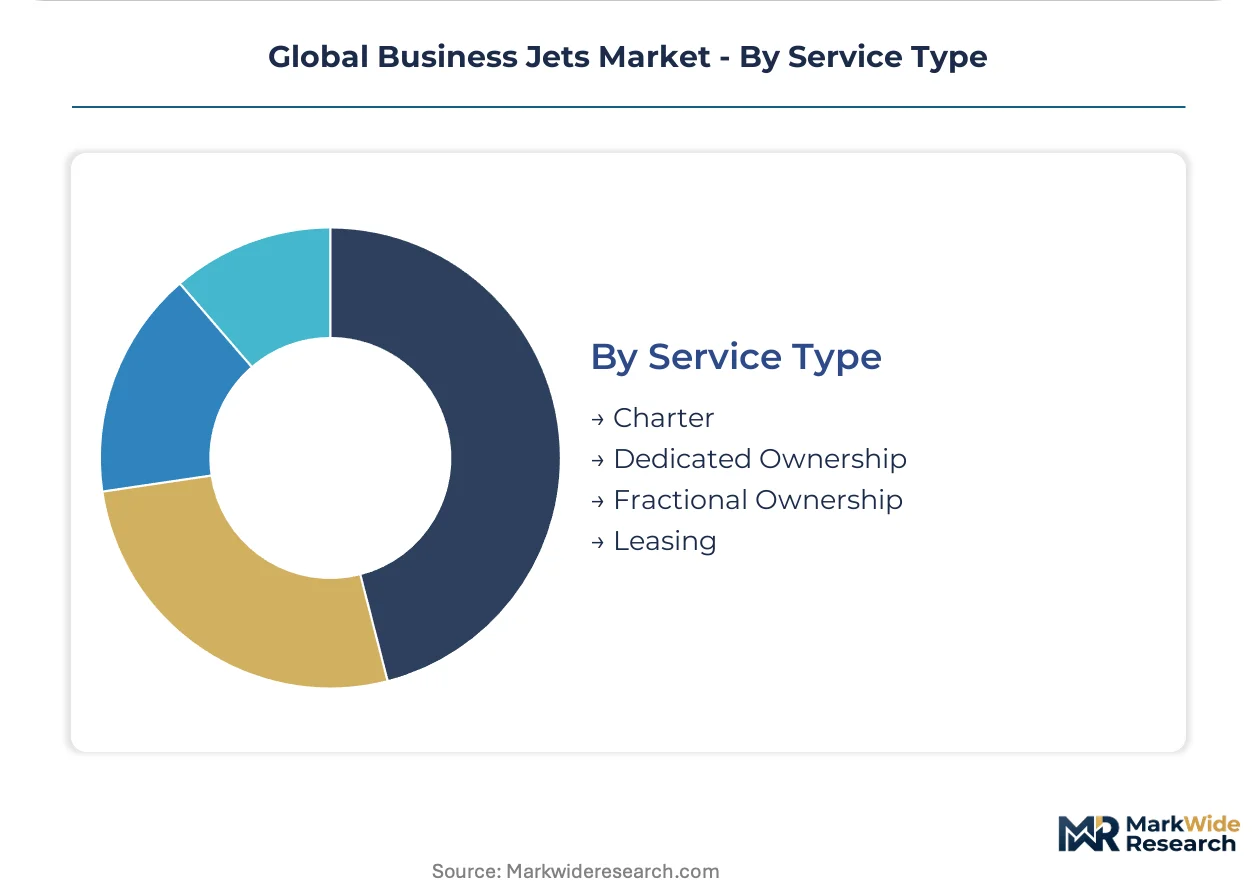
- Charter:Ad hoc hourly access with no capital commitment. United States corporate travel managers in mid-cap manufacturing favor this for irregular mission profiles.
- Dedicated Ownership:Full asset control with balance-sheet depreciation. Family offices in Switzerland and Luxembourg retain this model for privacy and customization latitude.
- Fractional Ownership:Depreciating equity shares with guaranteed hourly access. NetJets and Flexjet dominate this channel in the United States, consolidating demand from former whole-aircraft owners.
- Leasing:Operating leases transferring residual value risk to lessors. European operators exploit this structure under EU carbon border adjustment mechanisms favoring newer aircraft documentation.
Charter leads by transaction volume. Fractional Ownership shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate flight departments and sovereign wealth funds concentrate aircraft procurement in jurisdictions with favorable tax treatment and expanding business aviation infrastructure. The United States, China, United Arab Emirates, and select European markets anchor demand, with secondary growth emerging in Brazil and India as regulatory barriers ease.
United States
Fortune 500 treasury departments in Texas and California are displacing wholly owned aircraft with fractional ownership contracts. The FAA enforces Part 25 certification standards that govern airworthiness for all business jet operations. Teterboro Airport in New Jersey and Van Nuys Airport in Los Angeles serve as the densest corporate aviation clusters, handling the highest volume of ultra-long-range arrivals.
China
Second-tier city corporations are expanding charter access as general aviation infrastructure matures. The CAAC implements type certification reciprocity agreements conditioning market access for foreign original equipment manufacturers. The Yangtze River Delta corridor between Shanghai and Hangzhou is witnessing dedicated business aviation terminal construction to accommodate growing private operator demand.
United Arab Emirates
Sovereign wealth funds and family offices in Dubai and Abu Dhabi are driving specification intensity for premium cabin altitude systems. The GCAA aligns with ICAO carbon offset frameworks while maintaining streamlined registration protocols for foreign-owned aircraft. Al Maktoum International Airport is expanding dedicated business aviation facilities to capture trans-Indian Ocean traffic.
Brazil
Agribusiness commodity traders in Mato Grosso and Goiás are upgrading from turboprops to light jets for just-in-time supply chain management. ANVISA and the national aviation regulator coordinate on crew medical certification standards. São Paulo's Congonhas Airport remains the primary departure point for domestic shuttle missions serving soy and beef processing clusters.
Germany
Industrial conglomerates in Bavaria and Baden-Württemberg are accelerating fleet renewal amid EASA CS-25 noise and emissions compliance escalation. The Carbon Border Adjustment Mechanism creates regulatory arbitrage for operators acquiring newer aircraft with verified lifecycle emissions documentation. Munich Airport hosts the densest concentration of large-cain completions facilities serving European-registered corporate fleets.
Global Business Jets Market Vendor Landscape
Channel-controlling players compete with product-specialist players across cabin class segments, creating a tiered structure where scale-driven OEMs dominate ultra-long-range deliveries while regional specialists capture light jet volume. The market consolidates around airframers with integrated completions capabilities and established aftermarket service networks. Two strategic archetypes prevail: full-range portfolio operators spanning light through ultra-long-range categories, and segment-focused specialists optimizing single-class economics. Dominant competitive moves include strategic partnerships with fractional ownership platforms and geographic expansion of authorized service centers.
Within the full-range portfolio tier, Bombardier Inc. and Gulfstream Aerospace Corporation exemplify channel-controlling players with established global service footprints. Embraer S.A. occupies a specialist position in the light and midsize categories, competing aggressively on acquisition cost and runway performance. These three entities anchor the competitive structure, representing divergent approaches to cabin class coverage and aftermarket capture.
| Leading Market Players |
|---|
| Bombardier Inc. |
| Gulfstream Aerospace Corporation |
| Dassault Aviation |
| Embraer S.A. |
| Textron Aviation Inc. |
| The Boeing Company |
| Airbus SAS |
| Honda Aircraft Company |
| General Dynamics |
| Others |
Supply Flow & Price Mechanics
Titanium and specialty alloy sourcing from Russian suppliers determines both margin compression in the ultra-long-range segment and the geographic reconfiguration of forging capacity. Gulf Coast kerosene benchmarks feed directly into cost-plus charter contracts, while Pratt & Whitney and Rolls-Royce engine concentration creates single-source chokepoints that widen pricing spreads between light and large-cabin platforms.
Pricing Analysis
Cost-plus contracts indexed to Gulf Coast jet fuel benchmarks dominate charter operator agreements, with fuel surcharges passing through volatility to corporate clients. Price differentiation rests on SAF certification tiers and cabin altitude specifications, with European-registered operators paying premiums for verified lifecycle emissions documentation. Pricing pressure stems from fractional ownership platforms compressing hourly rates as NetJets and Flexjet consolidate demand. Charter Operators exhibit highest price sensitivity due to asset-light balance sheets, while sovereign wealth funds in the United Arab Emirates show lowest sensitivity to acquisition premiums.
Supply Chain Analysis
Spirit AeroSystems and GKN Aerospace hold concentrated contract manufacturing capacity for wing structures and engine nacelles across the United States and United Kingdom. Titanium feedstock draws from Russian and Kazakh mines, while avionics suites source from Honeywell and Collins Aerospace facilities in Arizona and Iowa. Single-source vulnerability in ultra-long-range engine supply creates structural risk for clean-sheet programs awaiting Pratt & Whitney PW800 or Rolls-Royce Pearl certification. Distribution runs through authorized service centers at Teterboro and Van Nuys, with factory-direct completions for large-cabin deliveries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Business aviation is approaching a platform-economics inflection as hourly-access membership models and SAF certification standards create interoperability requirements between fractional fleets and fuel suppliers.
For Market Incumbents: Insulate residual value positions by accelerating factory-installed SAF-compatible engine nacelles before EASA CS-25 Stage 5 deadlines tighten. Secure captive titanium supply through backward integration into alternative forging partnerships outside Russian supply corridors. Channel control through exclusive NetJets and Flexjet fleet agreements defends against emerging lessor competition. For New Entrants and Emerging Players: Brazil's agribusiness corridors in Mato Grosso and Goiás present the most penetrable white-space for turboprop-to-jet upgrades among commodity traders. Battery-electric hybrid demonstrators targeting 300-400 nautical mile shuttle missions unlock entry into the light jet segment without competing on turbine core development. Go-to-market through São Paulo-based charter brokers with unpaved airstrip operational expertise. For Investors and Strategic Acquirers: The market sits at a fleet-renewal acceleration phase that favors aftermarket service networks with SAF-handling infrastructure. Acquisition targets should combine authorized service center footprints with fractional ownership platform relationships. Watch for ICAO carbon offset rule tightening as the inflection signal that compresses replacement timelines and lifts residual values for compliant airframes.| Strategic Initiative | Industry Significance |
|---|---|
| SAF Infrastructure Partnership | Secures fuel supply for NetJets and Flexjet fleets under ICAO CORSIA compliance deadlines. |
| Authorized Service Center Expansion | Captures aftermarket revenue from Bombardier and Gulfstream operators in Dubai and Singapore. |
| Hybrid-Electric Propulsion Investment | Positions for 300-400 nautical mile shuttle missions with reduced engine maintenance reserves. |
| Fractional Platform Integration | Consolidates demand from mid-cap corporations abandoning wholly owned aircraft. |
| Titanium Supply Reconfiguration | Qualifies alternative vendors to unlock engineering change orders on in-production airframes. |
Methodological Framework
Desk research of FAA Part 25 certification databases, EASA CS-25 regulatory filings, and ICAO carbon offset framework documentation preceded structured interviews with corporate flight department managers, fractional ownership platform executives, and engine OEM supply chain directors. Secondary validation drew from SEC 10-K filings of Bombardier and General Dynamics, Gulf Coast jet fuel benchmark data, and business aviation registration records. Bottom-up aircraft delivery forecasts triangulated against top-down corporate travel spend analysis.
Forecast assumptions held SAF blending mandate timelines and EASA noise compliance thresholds fixed while varying fractional ownership adoption rates and Chinese airspace liberalization pace. Segmentation modeling spanned aircraft type, end-user category, engine architecture, and service structure across the projection horizon. CAGRs derived from fleet renewal cycle analysis and residual value curve projections, with inputs from flight crew training capacity constraints and simulator availability at CAE and FlightSafety International.
The forecast holds incumbent behavior within observed patterns; aggressive moves by battery-electric propulsion startups or Gulf state sovereign wealth funds acquiring distressed completions facilities would shift outcomes. Quarterly review of ICAO CORSIA implementation progress, Pratt & Whitney engine delivery backlogs, and CAAC low-altitude corridor expansion is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Reusable Launch Vehicles Market
Aircraft
Flap Track Fairing Drag Reduction Upgrade Kits Market
Aircraft
Aircraft Strut Market
Aircraft
Crashworthy Aircraft Seats Market
Aircraft
Global Aircraft Transparencies Market
Aircraft
Asia-Pacific General Aviation Market
Aircraft
Aircraft Landing Gear Market
Aircraft
Aircraft Leasing Market
Aircraft
North America Light and Very Light Jets Market
Aircraft
Tandem Rotor Helicopter Market
Aircraft
Freighter Aircraft Market
Aircraft
Aerobatic Aircraft Market
Aircraft
Multi-Band SATCOM and 6G-Ready Aircraft Radome Systems Market
Aircraft
Southeast Asia Business Jet Market
Aircraft
Commercial Aircraft Lighting Market
Aircraft
Commercial Aircraft Lavatory System Market