
 Asia-Pacific Heavy-Lift Helicopter Market | 2026-2036
Asia-Pacific Heavy-Lift Helicopter Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Heavy-Lift Helicopter Market Outlook
Japan's METI carbon-neutrality roadmap for aviation is expanding procurement criteria for low-emission rotorcraft across government tenders. Airbus SE leverages its A400M supply chain to sustain dual-use technology transfers into heavy-lift platforms. Boeing anchors Pacific Rim defense contracts through its CH-47 Chinook production line. Hindustan Aeronautics Limited differentiates via indigenous platform development under India's import substitution mandates.
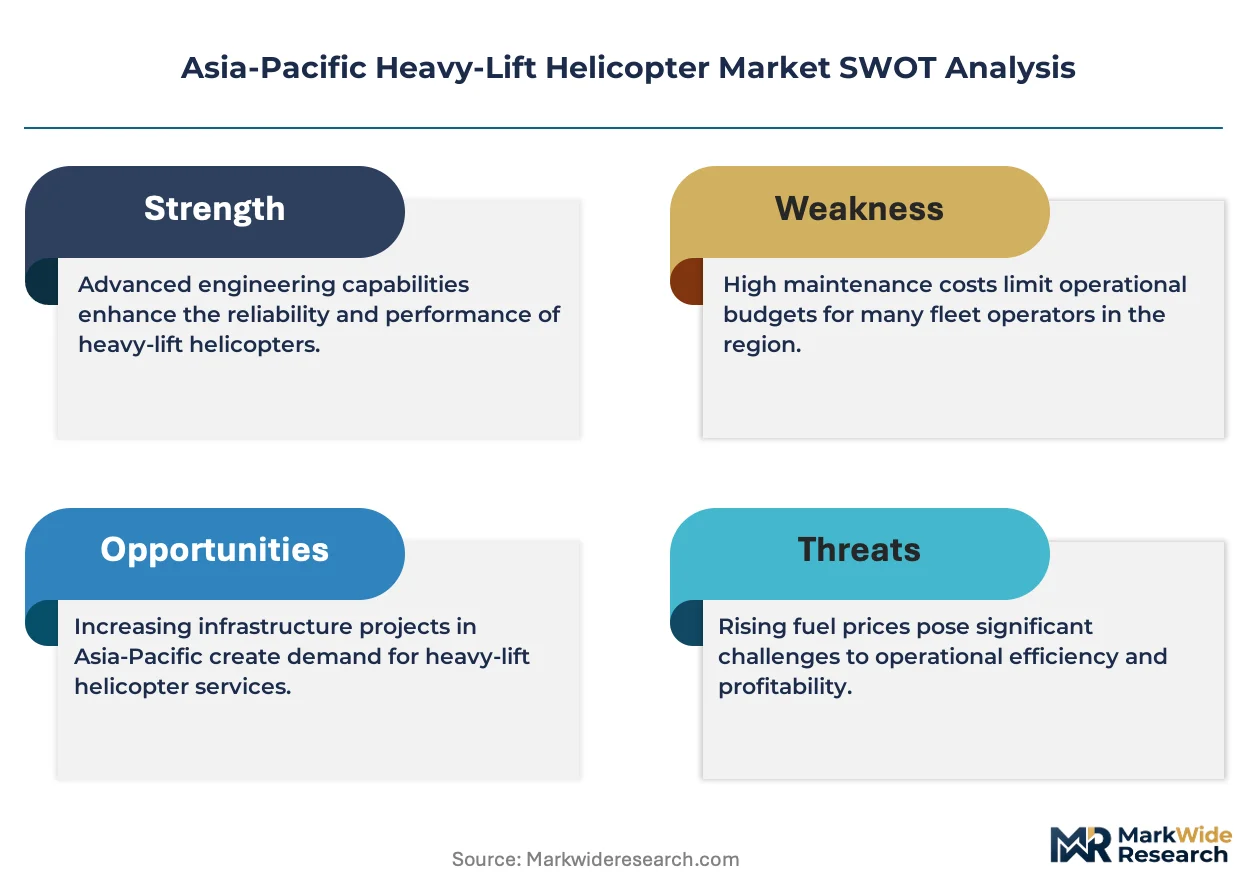
Asia-Pacific heavy-lift helicopters are rotary-wing aircraft with maximum takeoff weights exceeding twenty metric tons, engineered for external load operations using dual main rotors or single-rotor configurations with augmented powerplants. These platforms serve primary roles in tactical troop transport, offshore logistics, and construction sling-load missions across challenging terrain and maritime environments. Multi-role helicopters capture the broadest end-user footprint by combining cargo, search-rescue, and medical evacuation capabilities in single airframes. Offshore deployment generates concentrated margin pools where platform availability rates directly tie to oilfield operating economics. Fly-by-wire technology leads R&D allocation as operators demand reduced pilot workload during precision load placement in high-wind conditions.
Australia's Civil Aviation Safety Authority enforces stringent maintenance intervals for aging heavy-lift fleets, while China's CAAC aligns type certification with GB standards for rotorcraft structural integrity. India's DGCA mandates indigenous content thresholds under defense procurement procedures, reshaping supplier qualification pathways. Stakeholders must monitor how cross-border certification reciprocity evolves between national regulators as fleet commonality becomes a cost imperative for regional operators.
Market Dynamics
Fly-by-wire flight control architectures are compressing pilot workload requirements across precision external-load operations, fundamentally altering fleet upgrade priorities for operators serving Himalayan infrastructure corridors and Southeast Asian offshore logistics networks.
Growth Catalysts
- India's defense procurement procedures:Indigenous content thresholds mandate minimum 60% local sourcing for heavy-lift platforms, redirecting supply chain qualification toward domestic aerospace component manufacturers.
- Offshore oil and gas logistics:Platform availability rates directly determine field operating economics, driving accelerated fleet renewal cycles among Southeast Asian operators facing aging Sikorsky S-61 retirements.
- Carbon-neutrality procurement criteria:Japan's METI roadmap expands tender eligibility for low-emission rotorcraft across government search-rescue and disaster response contracts.
Market Restraints
- Turboshaft engine supply concentration:GE Aviation and Rolls-Royce dominate powerplant certification, creating single-source vulnerability for 15,000+ shaft-horsepower class engines required for twenty-metric-ton lift capacity.
- Australia's fatigue management rules:Civil Aviation Safety Authority tightened aerial crane operation duty limits, compressing available flight hours per airframe and elevating effective operating costs.
- Composite airframe repair infrastructure:Regional MRO capacity for advanced polymer structural restoration remains concentrated in Singapore and Sydney, extending turnaround times for operators in secondary markets.
Strategic Opportunities
- Philippines archipelago connectivity:Island-to-island sling-load construction for renewable energy installations remains underserved by fixed-wing alternatives, creating white-space demand for heavy-lift rotorcraft with 5,000+ kilogram external payload.
- Dual-use technology convergence:Military-to-civil transfer of terrain-following radar and automated load stabilization systems enables new commercial applications in precision logging and high-voltage tower erection.
- China's GB standards alignment:CAAC type certification reciprocity with select Asia-Pacific regulators is streamlining cross-border fleet deployment for multinational construction contractors.
Industry Challenges
- Flight crew qualification pipelines:External-load certification requirements exceed standard commercial helicopter training curricula, constraining operator expansion in Australia's mining and Indonesia's geothermal sectors.
- Legacy avionics integration:Retrofitting analog-era CH-47 and Mi-26 fleets with digital flight management systems demands extended downtime and specialized engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Heavy-Lift Helicopter Market |
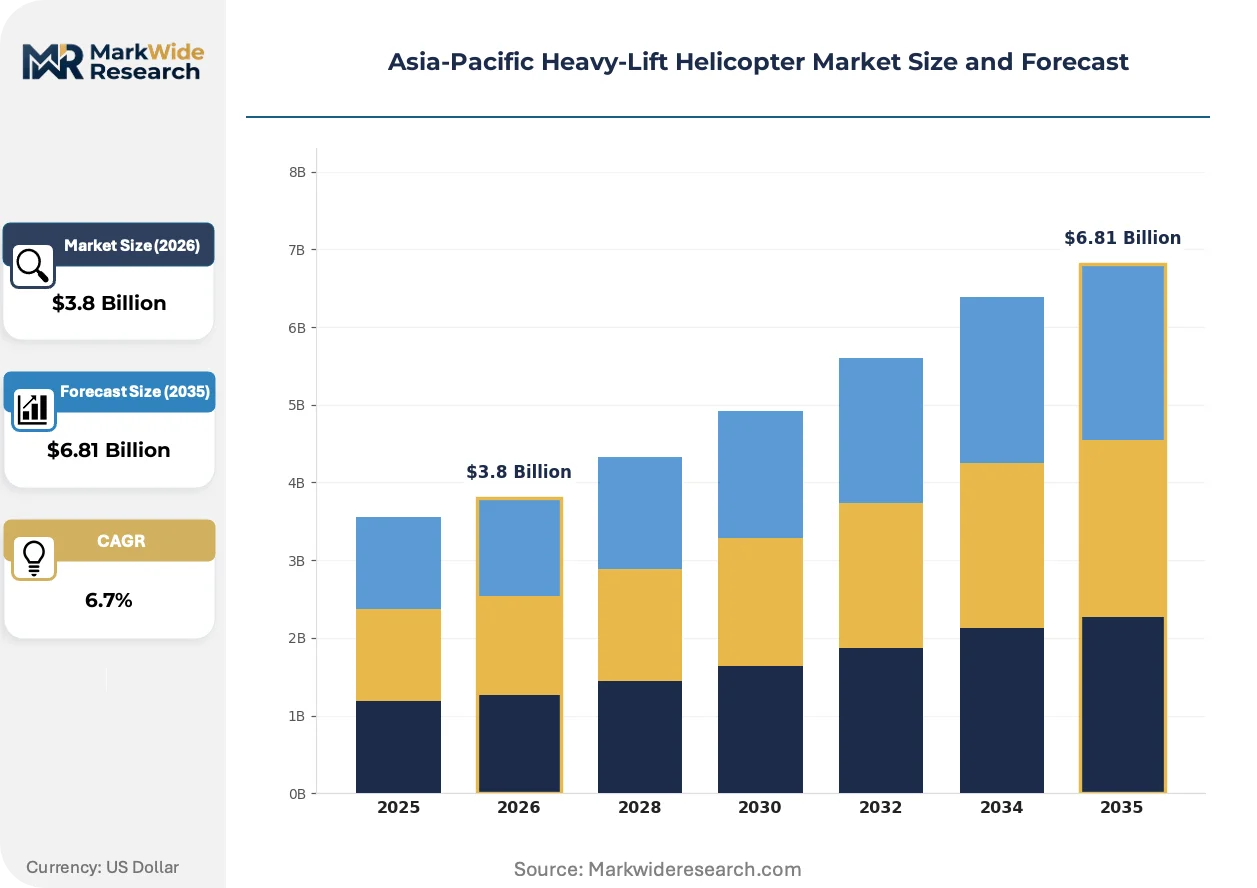
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Utility Helicopters, Cargo Helicopters, Multi-role Helicopters, Transport Helicopters End User: Government, Military, Oil & Gas, Construction Deployment: Onshore, Offshore, Remote Areas, Urban Settings Technology: Fly-by-wire, Avionics Enhancements, Automation, Rotorcraft Control Systems |
| Companies Covered | The Boeing Company, Airbus SE, Lockheed Martin Corporation, Textron Inc., Russian Helicopters, Leonardo S.p.A., Aviation Industry Corporation of China, Hindustan Aeronautics Limited, Kawasaki Heavy Industries, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Heavy-Lift Helicopter Market Strategic Shifts
Active vibration suppression and health monitoring systems are displacing scheduled component replacement across Asia-Pacific heavy-lift fleets, compressing maintenance economics and reshaping aftermarket revenue pools for regional MRO providers.
Modular mission equipment packages are modularizing platform configuration flexibility. Offshore logistics operators in Malaysia and Indonesia now swap cabin layouts between passenger transport and cargo sling modes within four-hour turnaround windows. This capability is modularizing fleet utilization rates and reducing dedicated-airframe requirements for multi-role contracts.
India's DGCA is aligning indigenous content verification protocols with defense procurement procedure amendments, tightening supplier audit scope for foreign OEMs seeking platform qualification. Helicopter manufacturers are restructuring joint venture frameworks with Hindustan Aeronautics Limited to satisfy component traceability mandates. The restructuring is redirecting technology transfer negotiations toward avionics and dynamic systems rather than complete airframe assembly.
Power-by-the-hour contracting is displacing traditional spares procurement across Australian mining and aerial firefighting operators. Rio Tinto and BHP are unbundling engine overhaul responsibility from airframe lease agreements, transferring operational risk to OEM service divisions. The unbundling is most visible in Western Australia's Pilbara region, where iron ore infrastructure maintenance demands 300+ annual flight hours per heavy-lift unit.
Asia-Pacific Heavy-Lift Helicopter Market Segmentation
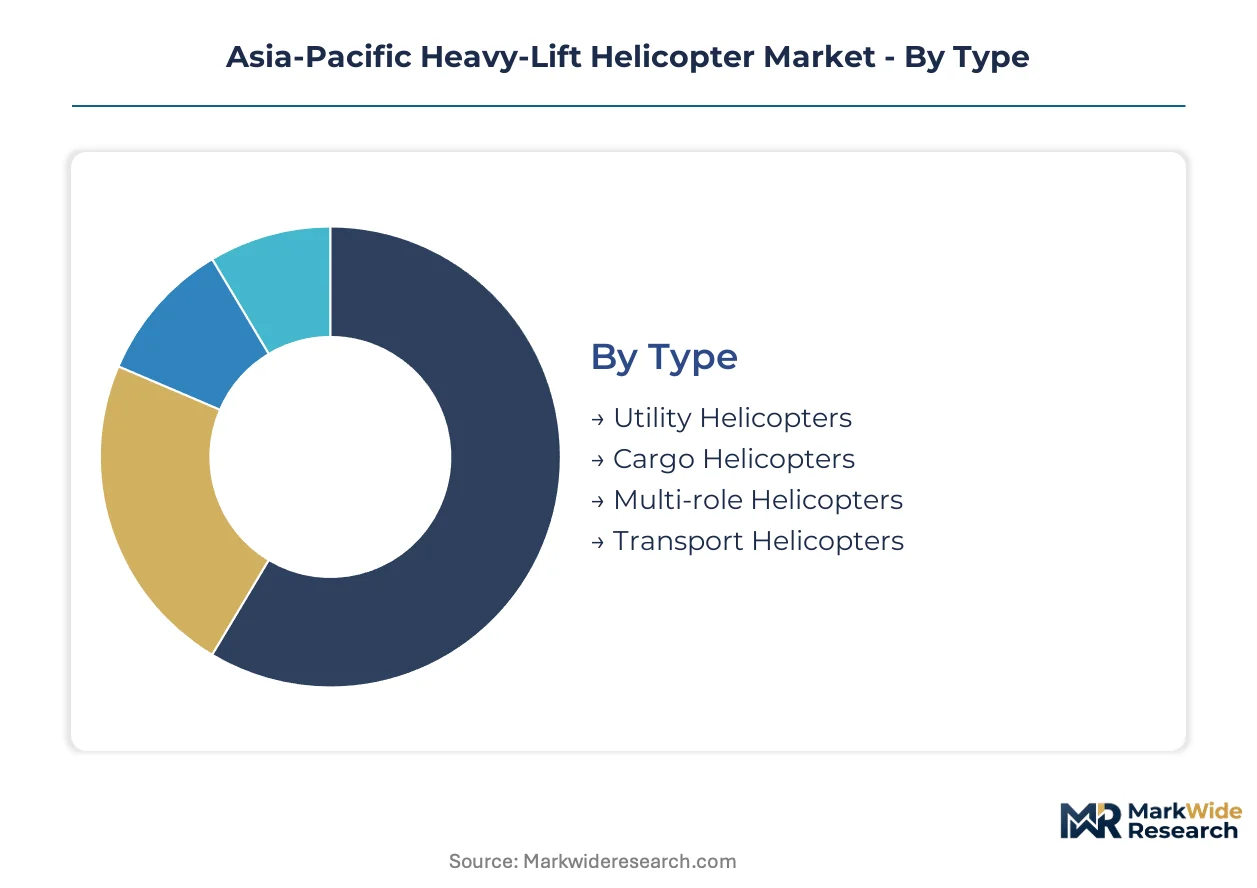
Segmentation in the Asia-Pacific heavy-lift helicopter market reveals how mission profiles and regulatory environments reshape procurement priorities. Platform configuration choices directly determine operational economics across Himalayan infrastructure corridors and Southeast Asian offshore logistics networks.
Type:
Volume concentrates in multi-role configurations while premium margins accrue to specialized cargo platforms engineered for maximum external payload.
- Multi-role Helicopters:These airframes combine cargo transport, search-rescue, and medical evacuation capabilities in single configurations. India's defense modernization programs and Australia's aerial firefighting contracts drive concentrated demand for platforms that switch mission profiles without structural modification.
- Cargo Helicopters:Purpose-built for external sling-load operations with reinforced transmission systems and extended cargo hooks. Offshore logistics operators in Malaysia and Indonesia pay availability premiums for units certified to twenty-metric-ton lift capacity, where platform downtime directly halts oilfield production.
- Utility Helicopters:General-purpose configurations optimized for troop transport and basic logistics support.
- Transport Helicopters:Fixed-cabin designs prioritizing internal payload volume over external load flexibility.
Today's leader: Multi-role Helicopters. Tomorrow's challenger: Cargo Helicopters.
End User:
Military procurement anchors volume while oil and gas operators generate the steepest margin expansion through availability-based contracting.
- Oil & Gas:Offshore platform logistics demands 95%+ availability rates, driving power-by-the-hour service agreements and accelerated fleet renewal cycles. Southeast Asian operators facing Sikorsky S-61 retirements are consolidating procurement around twin-rotor platforms with automated load stabilization.
- Military:Tactical airlift requirements across India's Himalayan infrastructure corridors and Japan's island defense posture favor heavy-lift platforms with terrain-following radar and defensive countermeasures. DGCA indigenous content mandates reshape supplier qualification pathways for foreign OEMs.
- Government:Search-rescue and disaster response contracts increasingly incorporate METI carbon-neutrality criteria in Japan.
- Construction:Sling-load tower erection and precision logging applications in Australia's mining regions and the Philippines' renewable energy buildout.
Defense procurement dominates current fleet orders. Commercial energy logistics is climbing the fastest.
Deployment:
Offshore environments command premium pricing while remote area operations face crew qualification constraints that limit operator expansion.
- Offshore:Maritime logistics platforms require corrosion-resistant airframes and enhanced autorotation capabilities for over-water operations. Australia's Civil Aviation Safety Authority enforces stringent maintenance intervals that elevate effective operating costs above onshore equivalents.
- Remote Areas:Himalayan infrastructure corridors and Indonesia's geothermal sectors demand external-load certification that exceeds standard commercial helicopter training curricula, constraining qualified flight crew availability.
- Onshore:Mining logistics and construction support across Western Australia's Pilbara region and India's northeastern states.
- Urban Settings:Limited penetration due to noise restrictions and airspace congestion; confined to specialized heavy-lift crane operations in Japanese and Australian metropolitan construction zones.
Offshore deployment captures the widest margin pools. Remote area operations face the tightest crew supply bottlenecks.
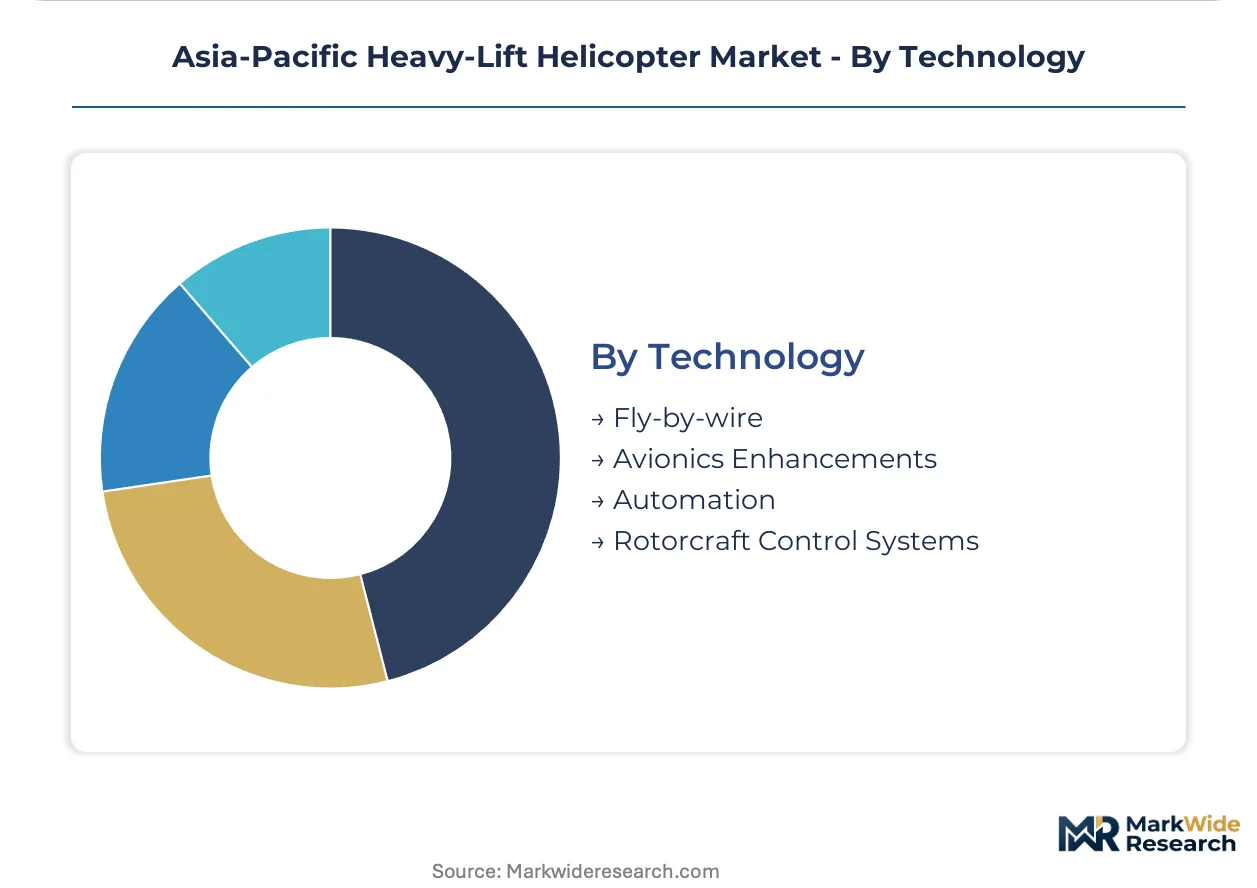
Technology:
Automation investments concentrate where precision load placement in high-wind conditions determines contract win rates.
- Fly-by-wire:Digital flight control architectures reduce pilot workload during precision external-load operations and enable automated load stabilization. CAAC alignment with GB standards is streamlining type certification for Chinese-manufactured systems seeking regional export.
- Automation:Terrain-following radar and automated hover-hold systems transfer from military platforms to commercial logging and high-voltage tower erection applications. Dual-use technology convergence opens white-space demand in previously inaccessible terrain.
- Avionics Enhancements:Digital flight management retrofits for legacy CH-47 and Mi-26 fleets demand extended downtime and specialized engineering resources.
- Rotorcraft Control Systems:Active vibration suppression and health monitoring systems displacing scheduled component replacement across regional MRO networks.
Fly-by-wire systems anchor current upgrade spending. Full automation packages are gaining share fastest in precision construction segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Heavy-lift helicopter operations in the Asia-Pacific trace their modern lineage to Vietnam War-era military logistics networks that established maintenance infrastructure and flight crew training pipelines across the region. Japan's Kawasaki Heavy Industries licensed Bell Helicopter technology in the 1950s, seeding domestic manufacturing capabilities that later expanded into indigenous platform development. Today's market distributes procurement across defense modernization programs, offshore energy logistics, and Himalayan infrastructure corridors.
India
Defense procurement procedures and Himalayan infrastructure development drive concentrated demand for twenty-metric-ton lift capacity platforms. DGCA indigenous content mandates require minimum sixty percent local sourcing, redirecting supply chain qualification toward Hindustan Aeronautics Limited joint ventures. The northeastern states host active sling-load operations for high-altitude road and power transmission construction.
Japan
Island defense posture and disaster response requirements sustain demand for multi-role heavy-lift configurations. METI carbon-neutrality procurement criteria expand tender eligibility for low-emission rotorcraft across government search-rescue contracts. The Kanto region concentrates fleet maintenance infrastructure and flight crew certification facilities.
Australia
Mining logistics and aerial firefighting operations anchor commercial demand, with Rio Tinto and BHP unbundling engine overhaul responsibility through power-by-the-hour agreements. CASA tightened fatigue management rules compress available flight hours per airframe for aerial crane operations. Western Australia's Pilbara region generates three-hundred-plus annual flight hours per heavy-lift unit.
China
CAAC alignment with GB standards for rotorcraft structural integrity is streamlining type certification for domestically manufactured systems. Dual-use technology convergence from military platforms enables commercial applications in precision construction and high-voltage tower erection. The Yangtze River Delta hosts concentrated MRO capacity for composite airframe restoration.
Southeast Asia
Offshore oil and gas logistics drive accelerated fleet renewal cycles among operators facing aging Sikorsky S-61 retirements. Platform availability rates directly determine field operating economics, concentrating margin pools around twin-rotor configurations with automated load stabilization. Malaysia and Indonesia host modular mission equipment swapping capabilities between passenger transport and cargo sling modes.
Asia-Pacific Heavy-Lift Helicopter Market Competitive Environment
Premium-margin players sit above commodity-margin players across technology transfer depth and indigenous content compliance. The vendor base clusters around three strategic archetypes: Western OEMs leveraging established military supply chains, state-backed national champions serving import substitution mandates, and emerging domestic integrators capturing maintenance and upgrade contracts. Consolidation pressure intensifies as defense procurement procedures in India and China elevate local partnership requirements. Joint venture restructuring and avionics technology licensing represent the dominant competitive moves reshaping qualification pathways.
Within the state-backed national champion tier, Hindustan Aeronautics Limited exemplifies import substitution positioning through indigenous platform development under India's defense procurement mandates. Aviation Industry Corporation of China occupies a parallel position serving CAAC certification alignment with GB standards. Among Western OEMs with established regional presence, Airbus SE and The Boeing Company anchor dual-use technology transfer frameworks, with the former leveraging A400M supply chain synergies and the latter anchoring Pacific Rim defense contracts through CH-47 production continuity. These three represent divergent responses to escalating indigenous content thresholds across Asia-Pacific procurement jurisdictions.
| Leading Market Players |
|---|
| The Boeing Company |
| Airbus SE |
| Lockheed Martin Corporation |
| Textron Inc. |
| Russian Helicopters |
| Leonardo S.p.A. |
| Aviation Industry Corporation of China |
| Hindustan Aeronautics Limited |
| Kawasaki Heavy Industries |
| Others |
Value Chain & Pricing Dynamics
Defense procurement offices in India and Japan anchor pricing power through availability-based contracting that bundles airframe lease, engine overhaul, and flight crew certification into unified service agreements. This concentration of sophisticated buyers forces OEMs toward power-by-the-hour structures that transfer operational risk from operator to manufacturer.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates platform transactions, with premium tiers capturing twin-rotor configurations certified to twenty-metric-ton lift capacity and economy tiers covering legacy CH-47 retrofits. Price differentiation rests on indigenous content compliance thresholds and fly-by-wire automation packages. Cost compression in standard-tier units is intensifying because DGCA mandates are forcing joint venture restructuring. Government search-rescue operators exhibit lowest price sensitivity; Southeast Asian offshore logistics contractors face highest budget pressure.
Supply Chain Analysis
Certification reciprocity between CAAC and select Asia-Pacific regulators gates supplier qualification, compressing eligible component sources to AVIC-certified facilities in China, GE Aviation powerplant lines in the United States, and Rolls-Royce manufacturing in the United Kingdom. Turboshaft engine supply draws from concentrated aerospace foundries; composite airframe materials hinge on specialized polymer suppliers. Single-source vulnerability for fifteen-thousand-plus shaft-horsepower engines represents the dominant structural risk. Distribution runs through HAL joint ventures and direct OEM service divisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific heavy-lift helicopter procurement has shifted toward late-cycle quality specifications as operators prioritize platform availability rates over unit acquisition cost. Carbon-neutrality mandates in Japan and indigenous content thresholds in India are elevating technical compliance requirements above price competition.
For Market Incumbents: Acquire flight crew certification pipelines and composite MRO infrastructure in secondary markets to lock in aftermarket revenue streams. Backward integration into turboshaft engine maintenance capacity defends margin position against power-by-the-hour unbundling. HAL joint venture restructuring threatens Western OEM supplier access; securing avionics technology licensing agreements preserves qualification pathways under DGCA mandates. For New Entrants and Emerging Players: Enter via Philippines archipelago sling-load construction for renewable energy installations, where fixed-wing alternatives cannot serve island-to-island logistics. Automated load stabilization systems transferred from military platforms open white-space demand in precision logging and high-voltage tower erection. Partner with Australian mining operators seeking unbundled engine overhaul responsibility to bypass fleet ownership barriers. For Investors and Strategic Acquirers: State-backed national champions are the most active acquirer in this space, consolidating joint venture frameworks to satisfy indigenous content mandates. Long-term viability centers on dual-use technology convergence enabling military-to-civil transfer of terrain-following radar and automated hover-hold systems. Watch CAAC-GB standards alignment progress as the signal indicating accelerated cross-border fleet deployment opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture Restructuring | HAL partnerships satisfy DGCA indigenous content verification protocols for foreign OEM platform qualification. |
| Power-by-the-Hour Service Expansion | Rio Tinto and BHP contracts transfer operational risk from Australian mining operators to OEM divisions. |
| Fly-by-Wire Technology Licensing | CAAC alignment with GB standards streamlines type certification for Chinese-manufactured control systems. |
| Composite MRO Capacity Buildout | Singapore and Sydney concentration creates bottleneck for regional operators needing polymer structural restoration. |
| Flight Crew Certification Pipeline Investment | CASA fatigue rules and external-load requirements constrain qualified crew availability across Australia's mining sector. |
Study Parameters
Multiple input streams — fleet operator interviews, defense procurement officer consultations, MRO provider assessments, and regulatory filing analysis — were reconciled to construct demand estimates across the Asia-Pacific region. Primary engagement captured platform engineering directors, CASA certification leads, HAL joint venture managers, and offshore logistics procurement heads. Secondary validation drew from CAAC type certification databases, DGCA defense procurement procedure amendments, METI carbon-neutrality tender documentation, and civil aviation safety authority maintenance interval records. Bottom-up fleet deployment tracking and top-down defense budget allocation analysis were cross-referenced for triangulation.
Historical fleet renewal cycles were cross-referenced against panel input from OEM service divisions and power-by-the-hour contract negotiators to anchor growth assumptions across the projection horizon. Segmentation modeling captured platform configuration, end-user vertical, deployment environment, and technology tier dimensions. CAGRs were derived from slope analysis of fleet age distributions and replacement timelines. Industry-specific forecast inputs included Sikorsky S-61 retirement schedules and Himalayan infrastructure corridor construction pipelines.
Inputs from CAAC certification bulletins and DGCA indigenous content audits were available through the study window; gaps in real-time joint venture restructuring negotiations introduce uncertainty bands around supplier qualification timelines. Forecasts reflect assumptions regarding regulatory reciprocity evolution and defense procurement procedure stability. A model refresh is warranted upon material change in CAAC-GB standards alignment progress or DGCA indigenous content threshold amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Multi-Band SATCOM and 6G-Ready Aircraft Radome Systems Market
Aircraft
Aircraft Band Clamps Market
Aircraft
Aircraft Jack Market
Aircraft
Global Aircraft Heat Exchanger Market
Aircraft
Japan Aviation Market
Aircraft
Aeronautical Wind Tunnel Market
Aircraft
Europe Freighter Aircraft Market
Aircraft
Aircraft Oxygen System Market
Aircraft
Commercial Aircraft Market
Aircraft
Europe Light and Very Light Jets Market
Aircraft
Aircraft Anchoring System Market
Aircraft
North America Light and Very Light Jets Market
Aircraft
Drone Turbojet Engine Market
Aircraft
Wind Tunnel Market
Aircraft
Commercial Aircraft in-Seat Power System Market
Aircraft
Asia-Pacific Aviation Market