
 Heavy-Lift Helicopter Market | 2026-2036
Heavy-Lift Helicopter Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy-Lift Helicopter Market Analysis
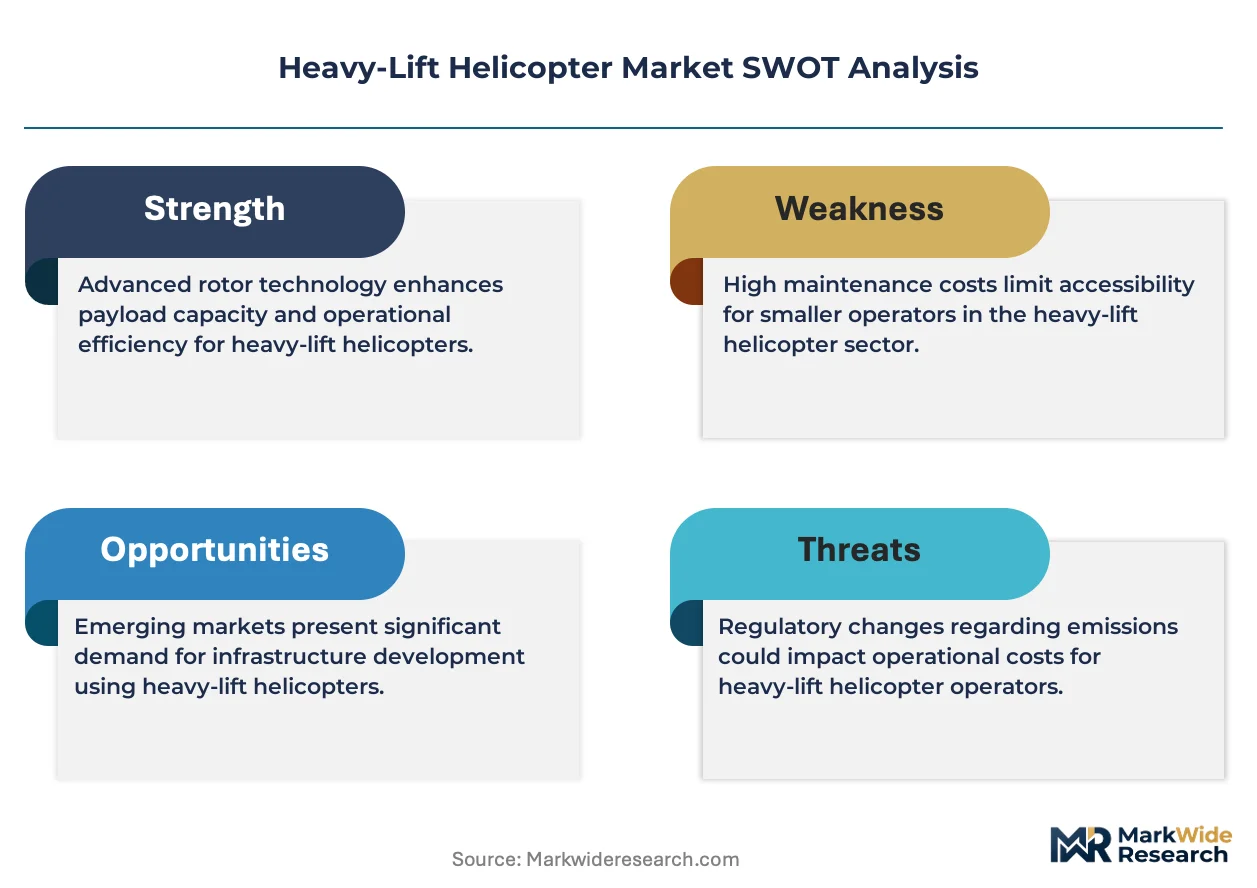
FAA Part 29 airworthiness reform is restructuring the cost-of-entry calculus for new heavy-lift platforms, demanding expanded crashworthiness and systems redundancy that smaller entrants cannot absorb. Sikorsky leverages its integrated military supply chain to sustain domestic production scale. Airbus Helicopters anchors European civil certification pathways. Boeing competes across dual-use contracts that straddle defense logistics and disaster relief mandates.
Heavy-lift helicopters are rotorcraft engineered to transport external sling loads exceeding nine metric tons, utilizing twin-turboshaft powerplants and articulated main rotor systems to generate the thrust and stability required for vertical replenishment, infrastructure emplacement, and mass casualty evacuation. Super heavy-lift helicopter platforms dominate capital deployment in military and offshore energy logistics where payload thresholds exceed twenty metric tons. Search and rescue applications are absorbing advanced avionics upgrades fastest, as terrain-following radar and degraded-visual-environment systems become standard fit. Hybrid propulsion technology remains nascent but captures disproportionate R&D allocation from operators seeking fuel efficiency gains and regulatory pre-positioning.
FAA certification standards, EASA CS-29 requirements, and EU Green Deal aviation decarbonization timelines collectively shape product roadmaps, airframe retirement schedules, and market access conditions for non-compliant legacy fleets. Military end users face parallel pressure from domestic defense procurement rules that prioritize sovereign assembly and component traceability. Stakeholders must weigh the capital intensity of clean-sheet designs against the diminishing aftermarket viability of pre-digital airframes as regulatory baselines harden.
Market Dynamics
Hybrid propulsion architecture is electrifying heavy-lift helicopter development trajectories as FAA Part 29 airworthiness reform demands crashworthiness upgrades that reshape capital allocation across the rotorcraft value chain.
Growth Catalysts
- Deepwater offshore expansion:Oil and gas operators are renewing fleets to access reservoirs beyond 1,500 meters depth, requiring super heavy-lift platforms with external sling capacity exceeding twenty metric tons.
- FAA Part 29 reform:Stricter crashworthiness and systems redundancy mandates are accelerating retirement of pre-digital airframes and creating replacement demand for compliant new-build rotorcraft.
- EU Green Deal aviation decarbonization:The timeline is forcing hybrid-electric R&D investment ahead of 2035 fleet compliance deadlines, positioning early movers for regulatory pre-certification.
Market Restraints
- Turboshaft engine supply concentration:Production of high-output powerplants for twenty-metric-ton-plus platforms concentrates among three Western suppliers, creating single-source vulnerability for new entrants.
- Titanium and composite input volatility:Main rotor hub forgings and airframe monocoque structures face aerospace-grade material allocation competition from commercial fixed-wing programs.
- CS-29 noise certification stringency:EASA's expanded acoustic measurement protocols add twelve to eighteen months to European civil type certification timelines.
Strategic Opportunities
- India infrastructure logistics:Himalayan road construction and high-altitude dam projects lack surface access for heavy equipment, creating demand for super heavy-lift vertical replenishment.
- Degraded-visual-environment avionics convergence:Terrain-following radar fused with synthetic vision systems opens civilian SAR and emergency medical service contracts previously restricted to military operators.
- US military modernization:The CH-53K program and Future Vertical Lift initiative are restructuring defense procurement toward sovereign assembly requirements that favor domestic supply chain capture.
Industry Challenges
- Flight control software certification:Fly-by-wire integration for heavy-lift stability demands specialized aerospace engineering talent pools concentrated at legacy military rotorcraft houses.
- Legacy fleet digital retrofit:Pre-1990 airframes lack databus architecture for modern avionics, forcing operators toward greenfield acquisition rather than upgrade pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy-Lift Helicopter Market |
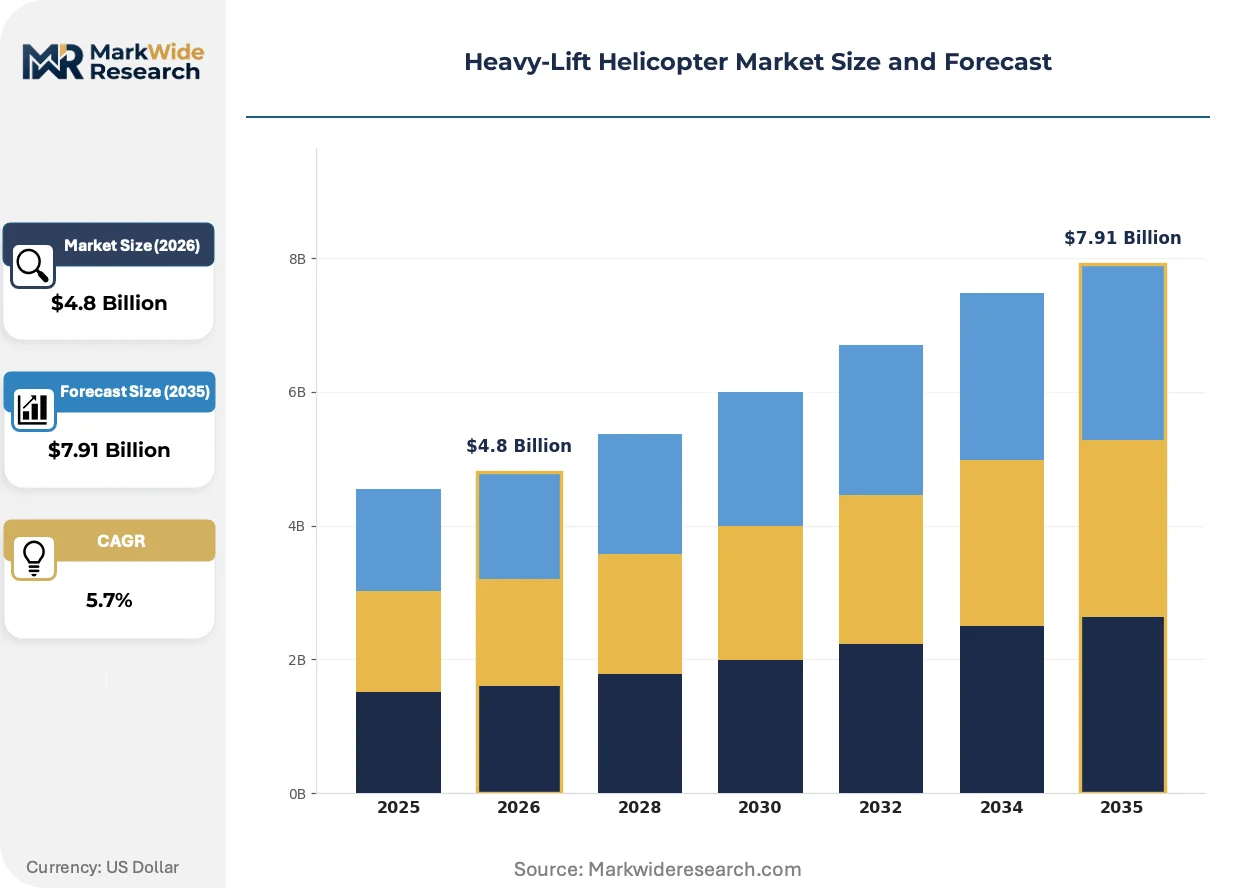
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medium-Lift Helicopter, Super Heavy-Lift Helicopter, Heavy-Lift Utility Helicopter, Heavy-Lift Cargo Helicopter Application: Construction, Humanitarian Aid, Oil & Gas, Search & Rescue End User: Government, Military, Commercial, Utility Operators Technology: Hybrid Propulsion, Fly-By-Wire, Advanced Avionics, Rotorcraft Control Systems |
| Companies Covered | Leonardo, Changhe Aircraft Industry Group, Sikorsky, Columbia Helicopters, Kazan Helicopters, Boeing, Airbus Helicopters, Erickson Incorporated, Rosoboronexport, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy-Lift Helicopter Market Emerging Trajectories
Electrification of propulsion architectures is compressing traditional turboshaft dominance as regulatory baselines harden and operators seek fuel efficiency arbitrage. Three convergent forces are restructuring product roadmaps and competitive positioning.
Hybrid-electric distributed propulsion is electrifying heavy-lift rotorcraft design philosophy. Siemens and Rolls-Royce are testing megawatt-class electric motors for supplemental thrust during hover and peak load phases. Offshore energy operators in the North Sea are piloting these configurations for platform resupply missions. The technology is electrifying the trade-off between payload capacity and fuel consumption that has governed rotorcraft economics since the 1960s.
EASA CS-29 noise and emissions amendments are forcing acoustic signature reduction into preliminary design phases rather than aftermarket mitigation. The regulation mandates cumulative noise limits across takeoff, flyover, and approach profiles that legacy tandem-rotor designs cannot meet without airframe redesign. Civil certification applicants are responding with main rotor blade planform optimization and active vibration suppression systems.
Contracting authorities are unbundling airframe procurement from through-life support, fragmenting the traditional bundled-lease model. Military end-users in the United States and civil operators in Norway are separating platform acquisition from maintenance, repair, and overhaul obligations. This shift is most visible in USMC CH-53K contracting, where performance-based logistics agreements now cover power-by-the-hour arrangements distinct from airframe purchase.
Heavy-Lift Helicopter Market Segmentation
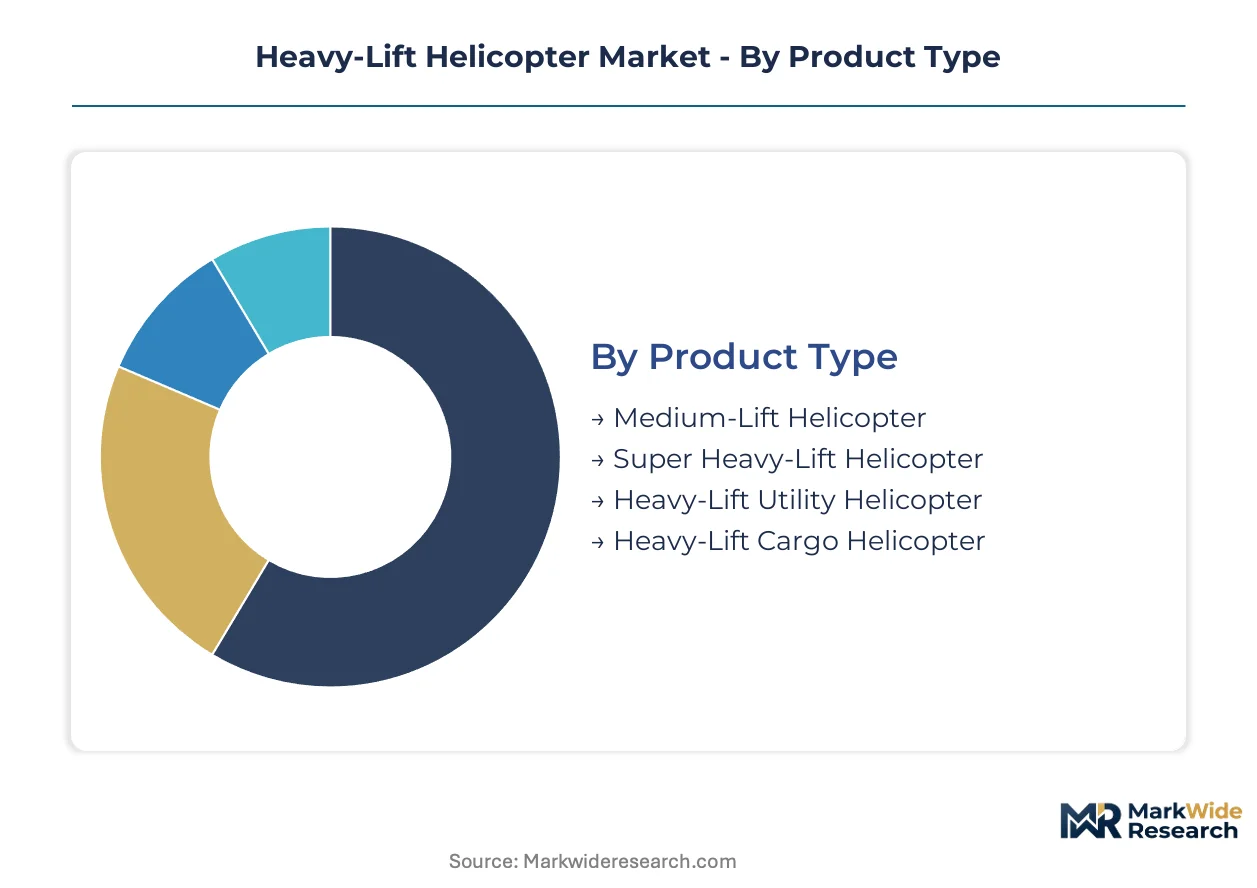
Payload thresholds and certification requirements fragment procurement patterns across operator types. Segmentation reveals how FAA Part 29 reform and EU Green Deal timelines concentrate investment in specific product tiers while marginalizing legacy configurations.
Product Type:
Volume procurement concentrates in utility platforms under twenty metric tons. Premium deployment gravitates toward super heavy-lift configurations serving deepwater energy logistics.
- Super Heavy-Lift Helicopter:External sling capacity exceeding twenty metric tons enables vertical replenishment of offshore platforms beyond 1,500 meters depth. North Sea operators and USMC logistics commands drive replacement demand as pre-digital airframes face FAA crashworthiness mandates.
- Heavy-Lift Utility Helicopter:Twin-turboshaft architectures between nine and sixteen metric tons dominate civil infrastructure and emergency medical service contracts. Himalayan road construction programs in India and high-altitude dam projects in the Andes absorb fleet renewals where surface access remains impossible.
- Medium-Lift Helicopter:Platforms under nine metric tons serve construction logistics and regional cargo networks with lower capital intensity.
- Heavy-Lift Cargo Helicopter:Specialized internal bay configurations transport palletized military supplies and disaster relief materiel.
Mature deployment sits with Heavy-Lift Utility Helicopter. Newer deployment is concentrated in Super Heavy-Lift Helicopter.
Application:
Energy extraction commands capital intensity per mission hour. Civil protection applications absorb avionics innovation fastest.
- Oil & Gas:Offshore platform resupply and subsea installation logistics require super heavy-lift external sling operations in degraded visual environments. North Sea operators pilot hybrid-electric configurations to preempt EU aviation decarbonization deadlines.
- Search & Rescue:Terrain-following radar and synthetic vision systems transform mission capability in mountain and maritime environments. Norwegian civil operators and Alpine rescue services drive adoption of fly-by-wire stability augmentation.
- Construction:Vertical replenishment of heavy equipment for remote infrastructure projects lacks surface transport alternatives.
- Humanitarian Aid:Disaster relief mandates demand rapid deployment of bulk supplies to infrastructure-damaged regions.
Procurement scale clusters with Oil & Gas. Technology refresh rates peak in Search & Rescue.
End User:
Sovereign assembly requirements reshape defense procurement economics. Commercial operators face unbundled contracting for airframe and through-life support.
- Military:CH-53K program and Future Vertical Lift initiative mandate domestic supply chain capture with component traceability requirements. Performance-based logistics agreements now separate platform acquisition from power-by-the-hour maintenance arrangements.
- Commercial:Offshore energy operators fragment traditional bundled-lease models, separating airframe procurement from maintenance obligations. North Sea pilot programs for hybrid propulsion concentrate in this segment.
- Government:Federal agencies manage disaster relief stockpiles and border security logistics with mixed civil-mission fleets.
- Utility Operators:Regional infrastructure and powerline construction contractors operate on project-based utilization models.
Regulatory pre-positioning dominates Military procurement. Fuel efficiency arbitrage drives Commercial investment.
Technology:
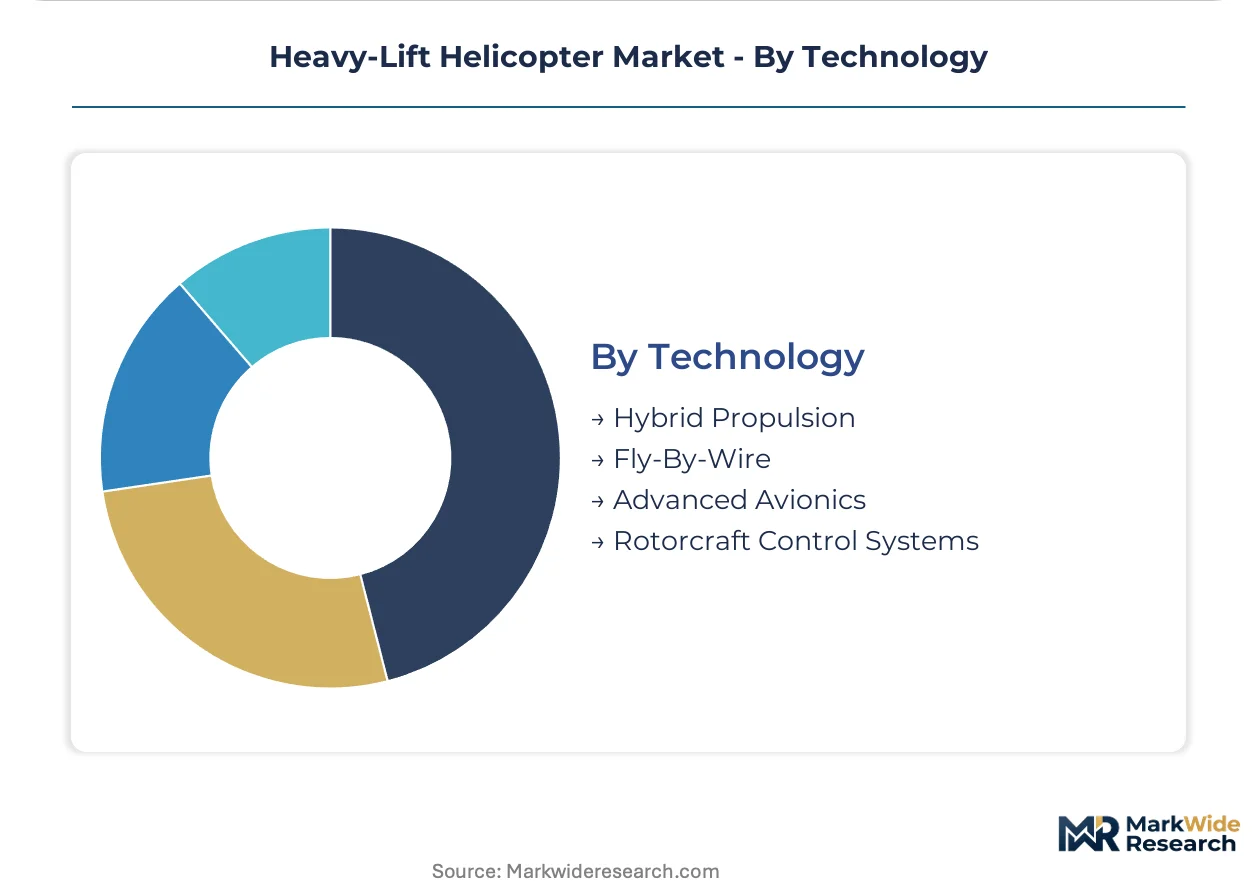
Certification complexity concentrates engineering talent at legacy rotorcraft houses. Electrification timelines compress traditional turboshaft development cycles.
- Hybrid Propulsion:Megawatt-class electric motors provide supplemental thrust during hover and peak load phases. Siemens and Rolls-Royce testing programs target North Sea platform resupply missions ahead of 2035 fleet compliance deadlines.
- Fly-By-Wire:Digital flight control integration demands specialized aerospace engineering pools concentrated at Sikorsky and Airbus Helicopters. FAA Part 29 reform mandates expanded systems redundancy that pre-analog airframes cannot accommodate.
- Advanced Avionics:Degraded-visual-environment systems fuse terrain-following radar with synthetic vision for civilian SAR contracts.
- Rotorcraft Control Systems:Active vibration suppression and blade planform optimization address EASA CS-29 noise certification stringency.
R&D allocation concentrates in Hybrid Propulsion. Certification pathways mature fastest in Fly-By-Wire.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States military modernization and offshore energy logistics concentrate procurement volumes. FAA Part 29 reform and sovereign assembly mandates reshape domestic supply chain capture. Specific national programs and certification pathways fragment regional deployment patterns.
United States
CH-53K production and Future Vertical Lift initiative drive defense procurement scale. FAA crashworthiness mandates accelerate retirement of pre-digital airframes. Connecticut and Pennsylvania industrial clusters host integrated military rotorcraft supply chains with component traceability requirements.
Norway
North Sea platform resupply missions pilot hybrid-electric configurations for decarbonization compliance. EU Green Deal aviation timelines force 2035 fleet pre-positioning. Stavanger and Bergen offshore logistics hubs concentrate super heavy-lift operator investment in degraded-visual-environment avionics.
India
Himalayan road construction and high-altitude dam projects demand vertical replenishment where surface access fails. Ministry of Defence procurement rules prioritize indigenous assembly partnerships. Hindustan Aeronautics facilities in Bengaluru and Lucknow anchor civil-military rotorcraft integration programs.
United Kingdom
Search and rescue service privatization absorbs fly-by-wire stability upgrades fastest. CAA noise certification alignment with EASA CS-29 amendments extends type approval timelines. Aberdeen and Cornwall offshore energy clusters drive super heavy-lift fleet renewal for North Sea logistics.
China
Infrastructure logistics in western provinces and plateau border regions require high-altitude heavy-lift capability. CAAC certification harmonization with FAA Part 29 standards shapes import substitution timelines. AVIC production facilities in Jingdezhen and Tianjin advance indigenous twin-turboshaft platform development.
Heavy-Lift Helicopter Market Vendor Landscape
United States producers anchor the defense-contractor tier; European specialists hold civil certification pathways. The market structure concentrates around legacy military rotorcraft houses with integrated supply chains and digital flight control expertise. Two strategic archetypes dominate: sovereign-assembly defense contractors and civil-certification platform specialists. Competitive moves center on performance-based logistics unbundling and hybrid propulsion R&D partnerships.
Within the sovereign-assembly tier, Sikorsky and Boeing represent integrated military supply chain capture. Airbus Helicopters occupies the civil-certification specialist position across European and export markets. Leonardo exemplifies dual-use platform development spanning defense logistics and offshore energy contracts.
| Leading Market Players |
|---|
| Leonardo |
| Changhe Aircraft Industry Group |
| Sikorsky |
| Columbia Helicopters |
| Kazan Helicopters |
| Boeing |
| Airbus Helicopters |
| Erickson Incorporated |
| Rosoboronexport |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed defense contractors and private-equity-rolled-up aftermarket specialists dominate ownership structures, concentrating pricing power with integrated producers while fragmenting bargaining leverage among unbundled service operators seeking power-by-the-hour arrangements.
Pricing Analysis
Lead-time-driven pricing stratification rewards premium positioning for crashworthiness-compliant new-build rotorcraft with sub-twelve-month delivery windows, while pre-digital airframes trade at spot-market discounts reflecting retirement risk under FAA Part 29 reform. Three-tier pricing structure across certified-new, retrofitted-midlife, and legacy-economy tiers segments buyer segments, with offshore energy operators least price-sensitive due to mission-critical platform resupply requirements and civil infrastructure contractors most exposed to cost compression. Pricing pressure stems from titanium and composite input volatility competing with commercial fixed-wing programs for aerospace-grade material allocation.
Supply Chain Analysis
Domestic-content mandates in US defense procurement and India's indigenous assembly partnerships are reshaping sourcing patterns, forcing tier-one suppliers to establish sovereign production footprints. Manufacturing gravity centers on the United States, France, and Russia for final airframe assembly, with critical dependencies on UK-based Rolls-Royce and US-based GE Aviation for high-output turboshaft powerplants and Japanese Toray for carbon fiber prepregs. Single-source vulnerability concentrates in twenty-metric-ton-plus engine supply among three Western producers. Distribution runs through military procurement channels with component traceability requirements and fragmented commercial leasing structures separating airframe acquisition from through-life support obligations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Heavy-lift helicopter manufacturing is becoming a vertical-integration race where control over flight control software talent pools and sovereign assembly credentials determines margin capture across defense and civil contracts.
For Market Incumbents: Hedge against hybrid propulsion disruption by securing megawatt-class electric motor partnerships with Siemens and Rolls-Royce before 2035 compliance deadlines harden competitive moats. Lock in titanium forging capacity through long-term offtake agreements with specialty metals suppliers facing allocation competition from commercial aerospace. Defend certification pathway advantages by accelerating FAA Part 29 reform pre-positioning to strand pre-digital competitor airframes. For New Entrants and Emerging Players: Maintenance, repair, and overhaul specialists represent the most penetrable channel partner type for unbundled service contracts fragmenting traditional bundled-lease models. Target Indian civil infrastructure logistics where Himalayan road construction and high-altitude dam projects lack surface access alternatives and indigenous assembly partnerships lower regulatory barriers. Pursue degraded-visual-environment avionics retrofit opportunities for pre-1990 airframes lacking databus architecture for modern systems integration. For Investors and Strategic Acquirers: EASA CS-29 noise certification amendment announcements are the leading indicator that acoustic signature reduction capabilities will separate acquisition-worthy platform specialists from stranded legacy producers. Five-to-ten-year viability hinges on hybrid-electric R&D positioning ahead of EU Green Deal aviation decarbonization timelines. Target fly-by-wire engineering talent pools concentrated at legacy military rotorcraft houses as the scarce asset class commanding premium multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Propulsion Partnership | Megawatt-class electric motor integration with Siemens or Rolls-Royce secures 2035 regulatory pre-certification positioning for North Sea operators. |
| Sovereign Assembly Facility | Domestic production footprint in Connecticut or Pennsylvania satisfies USMC CH-53K component traceability requirements and Future Vertical Lift mandates. |
| Degraded-Visual-Environment Avionics Suite | Terrain-following radar fused with synthetic vision opens civilian SAR contracts previously restricted to military operators in Norwegian and Alpine markets. |
| Performance-Based Logistics Unbundling | Separating airframe procurement from power-by-the-hour maintenance arrangements captures margin from fragmented commercial operator demand. |
| Titanium Forging Capacity Lock-in | Long-term offtake agreements with specialty metals suppliers defend against aerospace-grade material allocation competition from commercial fixed-wing programs. |
Methodological Framework
FAA type certification databases, EASA CS-29 amendment filings, and US Department of Defense contract award records formed the secondary backbone, cross-referenced with primary interviews involving fleet managers at North Sea offshore operators, procurement officers at USMC aviation logistics commands, and engineering directors at legacy rotorcraft houses. Bottom-up and top-down triangulation validated segmentation assumptions across payload thresholds, certification requirements, and end-user procurement patterns.
Bottom-up modeling aggregated individual program data across CH-53K, CH-47F, and civilian super heavy-lift deliveries, while top-down analysis calibrated against defense budget appropriations and offshore energy capital expenditure disclosures across the projection horizon. Segmentation dimensions included payload capacity tiers, propulsion architecture types, application categories spanning oil and gas through search and rescue, and regional regulatory clusters defined by FAA, EASA, and CAAC harmonization status. CAGRs derived from fitted trend analysis of fleet renewal cycles and pre-digital airframe retirement schedules.
Caveats apply where FAA Part 29 implementation timelines, EU Green Deal aviation decarbonization enforcement intensity, or turboshaft engine supply disruptions could materially shift the outlook for replacement demand and hybrid propulsion investment returns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Supersonic Jet Market
Aircraft
Wireless in-Flight Entertainment Market
Aircraft
Europe Freighter Aircraft Market
Aircraft
Europe General Aviation Market
Aircraft
North America General Aviation Market
Aircraft
Aircraft Leasing Market
Aircraft
Europe Fighter Aircraft Market
Aircraft
Airplane Landing Gear Market
Aircraft
Commercial Aircraft Manufacturing Market
Aircraft
Middle-East and Africa Freighter Aircraft Market
Aircraft
Airship Market
Aircraft
Military Trainer Aircraft Market
Aircraft
Global Helicopter Market
Aircraft
Asia-Pacific Helicopters Market
Aircraft
Australia Aviation Market
Aircraft
Single-Seat Gyrocopter Market