
 Aircraft Exterior Mounts Market | 2026-2036
Aircraft Exterior Mounts Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Exterior Mounts Market Analysis
Polymer-matrix composites is rebalancing traditional aluminum mount economics across the Aircraft Exterior Mounts landscape. Hutchinson Aerospace and Industry leverages its European manufacturing footprint to supply vibration-isolation solutions for narrowbody programs. LORD Corporation anchors its position through proprietary elastomeric bonding technologies that reduce maintenance intervals. Parker Hannifin Corp extends its aerospace hydraulics expertise into integrated mount-actuator assemblies for next-generation wing systems.
Aircraft exterior mounts are structural-mechanical assemblies that secure engines, wings, and control surfaces to airframe hardpoints while isolating vibration and managing load transfer; typical specifications include elastomeric shear ratings from 40 to 70 Shore A and operating temperature ranges spanning minus 55 to plus 150 degrees Celsius. These components serve the essential commercial purpose of extending airframe fatigue life while maintaining aerodynamic surface alignment under dynamic flight loads. Engine mounts command the largest value share due to thrust-load complexity and mandatory replacement cycles, while composite material mounts represent the fastest-expanding category as OEMs pursue weight reduction targets. Wing mounts constitute a mature, high-volume segment where price competition intensifies among Tier-2 suppliers.
FAA airworthiness standards under Part 25.571 and EASA CS-25 damage-tolerance requirements mandate fatigue testing protocols that elevate R&D barriers for new mount entrants. EPA REACH compliance and EU Green Deal carbon-footprint disclosures are reshaping material selection decisions across European supply chains. Stakeholders must monitor emerging airworthiness directives on sustainable aviation fuel compatibility, as thermal and chemical exposure profiles from alternative fuels may redefine elastomer specification thresholds.
Market Dynamics
Fleet renewal programs at Boeing and Airbus are compressing qualification timelines for lightweight mount assemblies. Polymer-matrix composite adoption is forcing recalibration of traditional aluminum supply relationships across Tier-2 fabrication networks.
Growth Catalysts
- Commercial aviation fleet renewal:Narrowbody production rate increases at Boeing's Renton facility and Airbus Toulouse operations are pulling forward orders for vibration-isolation hardware. OEMs specify composite mounts for weight-critical wing hardpoints.
- FAA Part 25.571 damage-tolerance mandates:Fatigue-testing protocols for engine mounts are extending replacement-cycle predictability. Airlines prioritize certified suppliers with established airworthiness documentation.
- Sustainable aviation fuel compatibility requirements:Elastomer specification thresholds are broadening as operators test alternative fuel thermal profiles. Mount suppliers with fuel-resistant bonding formulations capture specification advantages.
Market Restraints
- Titanium and nickel alloy input volatility:Aerospace-grade metal pricing swings compress margin buffers for traditional aluminum-titanium hybrid mount producers. Smaller fabricators lack hedging infrastructure.
- European supply chain concentration:Vibration-isolation component manufacturing clusters in France and Germany create single-source vulnerabilities. EASA CS-25 certification timelines extend when primary suppliers face capacity constraints.
- Polymer-matrix composite technical limitations:Lightning-strike conductivity and repairability gaps restrict composite mount deployment on certain engine pylon configurations. Aluminum retains specification dominance in high-thrust applications.
Strategic Opportunities
- India defense aviation modernization:Indigenous fighter programs and helicopter fleet upgrades are creating import-substitution openings for mount suppliers with AS9100 certification. Local production partnerships bypass offset requirements.
- Urban air mobility hardpoint development:eVTOL airframe manufacturers require scaled-down vibration-isolation solutions. Electric propulsion systems demand mounts optimized for high-frequency, low-amplitude oscillation profiles.
- EU Green Deal carbon-footprint disclosure rules:Life-cycle assessment documentation is becoming a procurement differentiator. Suppliers with verified low-carbon material sourcing secure preferential supplier status with Airbus and Safran.
Industry Challenges
- Composite bonding technician scarcity:Elastomer-to-substrate adhesive application requires specialized certification. Training pipeline gaps extend production ramp timelines for new composite mount lines.
- FAA-EASA harmonization delays:Divergent interpretation of damage-tolerance testing protocols forces dual certification tracks. Smaller suppliers abandon transatlantic market entry rather than absorb duplicate qualification costs.
- Legacy fleet MRO integration complexity:New-generation lightweight mounts require adapter hardware for aging airframe hardpoints. Engineering change orders proliferate when retrofit compatibility fails.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Exterior Mounts Market |
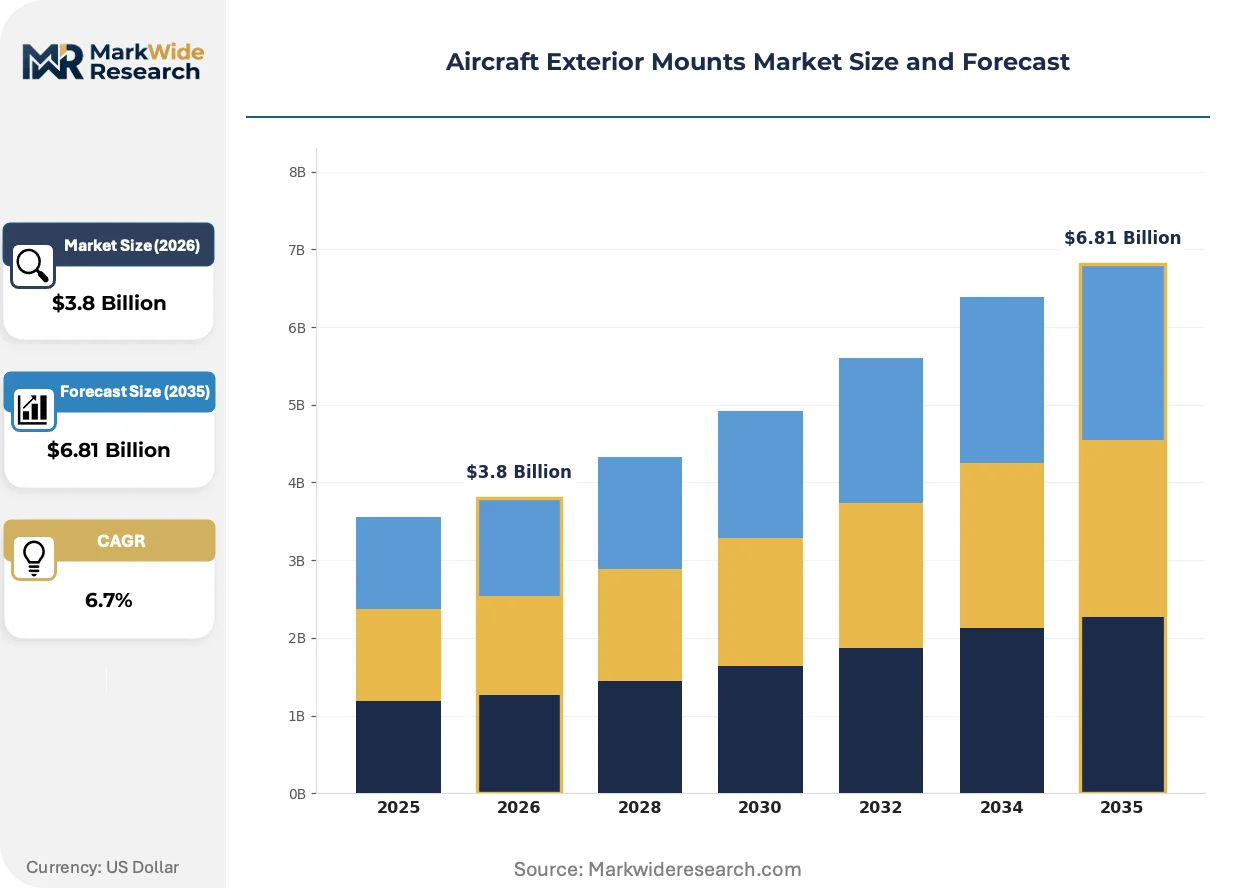
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wing Mounts, Fuselage Mounts, Tail Mounts, Engine Mounts Material: Aluminum, Steel, Composite, Titanium End User: Commercial Aviation, Military Aviation, Cargo Carriers, General Aviation Application: Passenger Aircraft, Cargo Aircraft, Private Jets, Helicopters |
| Companies Covered | Hutchinson Aerospace and Industry, Shock Tech, Inc., LORD Corporation, AirLoc Ltd., Cadence Aerospace, Trelleborg AB, Parker Hannifin Corp, Mayday Manufacturing, GMT Rubber-Metal-Technic Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Exterior Mounts Market Emerging Trajectories
Material substitution and regulatory harmonization pressures are compressing traditional product lifecycles across exterior mount categories. Suppliers are repositioning around integrated sensing capabilities and predictive maintenance interfaces.
Polymer-matrix composite shear web designs are overtaking aluminum forgings in wing-to-fuselage attachment applications. Boeing 787 and Airbus A350 programs specify carbon-fiber-reinforced mounts at primary load-bearing stations. The technology is overtaking metallurgical solutions in segments where 15-20% weight reduction justifies qualification investment.
EPA REACH substance restrictions are forcing reformulation of traditional nitrile and neoprene elastomer compounds. European mount suppliers face material requalification costs for vibration-dampening elements. The regulation most affects engine pylon isolators, where suppliers accelerate fluoroelastomer and hydrogenated nitrile alternatives through EASA validation.
Airline technical procurement teams are consolidating vendor panels around integrated hardware-software offerings. Traditional component-only suppliers lose specification access to competitors bundling mount assemblies with strain-monitoring sensors. This consolidation pattern concentrates in North American and Middle Eastern carrier fleets with centralized engineering procurement functions.
Aircraft Exterior Mounts Market Segmentation
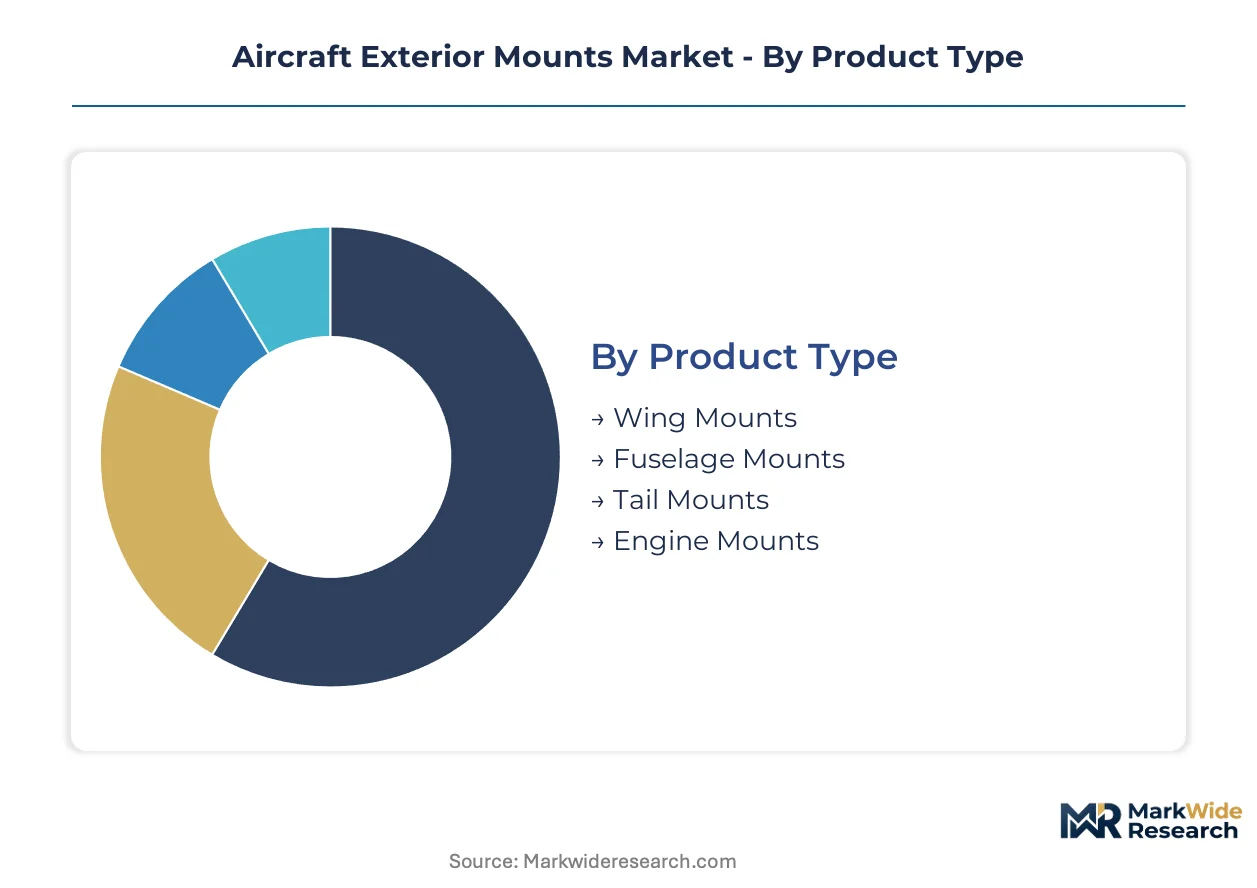
Segmentation in aircraft exterior mounts reflects divergent engineering requirements across airframe hardpoints, material performance envelopes, and operational duty cycles. Procurement specifications vary sharply between commercial fleet operators prioritizing weight reduction and military programs emphasizing damage tolerance.
Product Type:
Specification intensity correlates with load-bearing complexity and vibration-isolation demands across airframe attachment points.
- Engine Mounts:These assemblies manage thrust-vector loads and propulsion-system vibration isolation through elastomeric shear layers rated 40-70 Shore A. Demand concentrates in the United States at Boeing's Renton facility and Airbus Toulouse operations, where narrowbody production rate increases pull forward orders for certified vibration-isolation hardware. Airlines prioritize suppliers with established FAA Part 25.571 airworthiness documentation.
- Wing Mounts:High-volume structural attachments securing wing-to-fuselage load paths define this mature segment. Price competition intensifies among Tier-2 suppliers fabricating aluminum forgings and polymer-matrix composite shear webs for Boeing 787 and Airbus A350 primary load-bearing stations.
- Fuselage Mounts:These assemblies stabilize cabin pressurization cycles and equipment bay attachments. Specifications emphasize fatigue-life extension under cyclic loading profiles.
- Tail Mounts:Empennage hardpoint hardware manages control-surface actuation loads and stabilizer attachment. Applications span vertical and horizontal stabilizer mounting configurations.
Mature deployment sits with Wing Mounts. Newer deployment is concentrated in Engine Mounts.
Material:
Cost-to-performance tradeoffs and regulatory compliance burdens reshape sourcing decisions across fabrication networks.
- Composite:Carbon-fiber-reinforced polymer-matrix designs achieve 15-20% weight reduction over metallurgical alternatives. Boeing 787 and Airbus A350 programs specify these mounts at primary load-bearing stations, though lightning-strike conductivity gaps restrict deployment on certain engine pylon configurations.
- Aluminum:Traditional forged and machined aluminum alloys retain specification dominance in high-thrust engine applications. Established supply relationships and repairability protocols sustain procurement volumes despite composite displacement pressure.
- Titanium:Aerospace-grade titanium offers strength-to-weight advantages for critical hardpoints. Input price volatility compresses margin buffers for hybrid mount producers lacking hedging infrastructure.
- Steel:High-strength steel alloys serve legacy fleet MRO and cost-sensitive applications. Specifications emphasize durability over weight optimization.
Volume leadership belongs to Aluminum. Steepest expansion trajectory belongs to Composite.
End User:
Customer procurement patterns separate fleet-scale operators from fragmented specialty aviation demand.
- Commercial Aviation:Narrowbody and widebody fleet operators drive specification standards through centralized technical procurement. FAA and EASA damage-tolerance mandates elevate barriers for uncertified suppliers.
- Military Aviation:Defense programs prioritize damage tolerance and battle-hardiness over weight metrics. India's indigenous fighter programs and helicopter fleet upgrades create import-substitution openings for AS9100-certified suppliers.
- Cargo Carriers:Freighter conversion programs and dedicated cargo fleets sustain aftermarket demand for heavy-duty mount configurations.
- General Aviation:Business jet and regional turboprop operators generate fragmented, specification-diverse procurement.
Specification authority concentrates with Commercial Aviation. Procurement diversification is accelerating in Military Aviation.
Application:
Platform-specific duty cycles and certification pathways fragment addressable market architecture.
- Passenger Aircraft:Commercial airliners generate the largest absolute demand volume. Fleet renewal programs at Boeing and Airbus compress qualification timelines for lightweight mount assemblies.
- Helicopters:Rotary-wing platforms require specialized vibration-isolation solutions for main and tail rotor transmissions. High-frequency, low-amplitude oscillation profiles demand distinct elastomer formulations.
- Cargo Aircraft:Freighter operations emphasize structural durability under high-cycle loading. Converted passenger airframes require adapter hardware compatibility.
- Private Jets:Business aviation specifications balance performance with cabin comfort priorities. Fragmented OEM landscape limits volume concentration.
Volume scale sits with Passenger Aircraft. Technology differentiation is advancing fastest in Helicopters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial aviation procurement concentrates heavily in the United States, where Boeing's supply chain and aftermarket MRO networks sustain significant volumes. France and Germany anchor European specification authority through Airbus and Safran engineering centers. India's defense modernization and China's expanding fleet renewal programs are redistributing demand geography.
United States
Boeing's Renton facility and Airbus's Mobile assembly plant pull forward orders for vibration-isolation hardware. FAA Part 25.571 damage-tolerance mandates elevate certification barriers for mount suppliers. Wichita, Kansas hosts a dense cluster of Tier-2 fabricators serving both OEM and aftermarket channels.
France
Airbus Toulouse operations and Safran Landing Systems drive specification standards for composite mount assemblies. EASA CS-25 certification requirements and EU Green Deal carbon-footprint disclosures reshape material selection decisions. The Toulouse-Blagnac aerospace cluster concentrates vibration-isolation engineering expertise.
Germany
Airbus Hamburg final assembly and MTU Aero Engines sustain procurement volumes for engine mount hardware. REACH substance restrictions force reformulation of traditional elastomer compounds. The Munich-Stuttgart corridor hosts specialized suppliers with EASA validation capabilities.
India
Indigenous fighter programs and helicopter fleet upgrades create import-substitution openings for AS9100-certified suppliers. The Ministry of Defence's offset requirements push foreign mount manufacturers toward local production partnerships. Bengaluru and Hyderabad emerging as aerospace manufacturing hubs with growing MRO infrastructure.
China
COMAC C919 production ramp and expanding commercial fleet renewal compress qualification timelines for lightweight assemblies. MIIT aerospace standards and GB certification protocols create parallel regulatory tracks for domestic and export markets. The Shanghai-Tianjin corridor concentrates airframe integration capabilities.
Aircraft Exterior Mounts Market Vendor Landscape
Capacity expansion dominates the current landscape as suppliers add composite fabrication lines to meet Boeing and Airbus production rate increases. The vendor base organizes into three tiers: integrated aerospace conglomerates with proprietary elastomeric technologies, specialized vibration-isolation houses with EASA/FAA dual certification, and regional fabricators serving MRO aftermarket channels. Strategic archetypes include materials-science specialists competing on bonding formulation IP, and scale-driven manufacturers optimizing aluminum forging throughput. Geographic expansion and portfolio diversification represent the two dominant competitive moves, with suppliers establishing AS9100-certified facilities near emerging OEM assembly sites.
Among North American integrated suppliers, LORD Corporation and Parker Hannifin Corp exemplify the materials-science archetype through proprietary elastomeric and hydraulics expertise. Hutchinson Aerospace and Industry anchors the European specialist tier with its French manufacturing footprint. Trelleborg AB represents the Scandinavian engineering tradition in polymer-based vibration solutions. These three companies occupy positions across distinct geographic and technological vectors rather than competing head-to-head in identical specification segments.
| Leading Market Players |
|---|
| Hutchinson Aerospace and Industry |
| Shock Tech, Inc. |
| LORD Corporation |
| AirLoc Ltd. |
| Cadence Aerospace |
| Trelleborg AB |
| Parker Hannifin Corp |
| Mayday Manufacturing |
| GMT Rubber-Metal-Technic Ltd |
| Others |
Supply Flow & Price Mechanics
Elastomer compound costs cascade through three distinct pricing tiers before reaching airline technical procurement teams. Boeing and Airbus volume contracts anchor the premium segment, while Tier-2 fabricators serving MRO channels absorb margin compression from titanium and nickel alloy volatility. FAA Part 25.571 certification investments create fixed-cost barriers that stratify supplier economics across the value chain.
Pricing Analysis
High-volume narrowbody programs command contract-based long-term offtake structures with 15-20% discounts against spot procurement. Price differentiation separates FAA-EASA dual-certified suppliers from single-jurisdiction qualifiers, with composite material grades adding further stratification. Cost compression in the aluminum forging tier is intensifying because smaller fabricators lack hedging infrastructure against aerospace-grade metal swings. Cargo carriers and legacy fleet MRO operators exhibit the sharpest price sensitivity, whereas next-generation composite mounts for wing hardpoints face minimal elasticity due to weight-reduction mandates.
Supply Chain Analysis
Dual-sourcing requirements embedded in Boeing and Airbus supplier quality manuals mandate multi-facility qualification for all engine mount categories. Manufacturing gravity centers on the United States, France, and Germany, with specialized elastomer compounding concentrated in the Toulouse-Blagnac and Wichita clusters. Raw material dependencies draw from carbon fiber prepreg, aerospace-grade titanium billet, and fluoroelastomer formulations. Single-source vulnerability persists in EASA-certified vibration-isolation engineering talent. Distribution runs through OEM direct procurement for new aircraft, with aftermarket channels feeding from regional MRO hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where FAA Part 25.571 and EASA CS-25 damage-tolerance mandates erect formidable barrier-to-entry moats. Certification documentation investments exceeding typical Tier-2 capital thresholds protect incumbent positions against unqualified challengers.
For Market Incumbents: Deepen proprietary elastomeric bonding formulation IP to extend replacement-cycle predictability and lock in airline technical procurement panels. Expand captive supply of carbon fiber prepreg through backward integration into composite shear web production, neutralizing input volatility that compresses margin buffers for hybrid mount producers. Composite bonding technician scarcity represents the most acute operational threat requiring targeted training pipeline investments.
For New Entrants and Emerging Players: The mid-tier price gap between LORD Corporation's premium elastomeric solutions and regional aluminum forging houses creates specification access for AS9100-certified specialists with EASA validation capabilities. Target India's indigenous fighter programs and helicopter fleet upgrades where Ministry of Defence offset requirements push foreign manufacturers toward local production partnerships. Urban air mobility hardpoint development offers the most penetrable white-space, with eVTOL manufacturers requiring scaled-down vibration-isolation solutions absent entrenched supplier relationships.
For Investors and Strategic Acquirers: Airbus and Safran supplier panel consolidation around integrated hardware-software offerings is the leading indicator that materials-science specialists with strain-monitoring sensor bundling capabilities will command acquisition premiums. The five-to-ten year viability window favors targets with verified low-carbon material sourcing documentation aligned to EU Green Deal procurement differentiators. Watch for EASA airworthiness directives on sustainable aviation fuel compatibility as the inflection signal reshaping elastomer specification thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| Composite Fabrication Line Expansion | Adds capacity to meet Boeing Renton and Airbus Toulouse narrowbody rate increases. |
| Dual FAA-EASA Certification Investment | Opens specification access to transatlantic airline procurement panels. |
| Fluoroelastomer Formulation Development | Positions suppliers for REACH-compliant engine pylon isolator requalification. |
| India Local Production Partnership | Bypasses Ministry of Defence offset requirements for defense aviation programs. |
| Integrated Sensor Bundling Capability | Captures airline vendor panel consolidation toward predictive maintenance interfaces. |
Methodological Framework
Multi-period observation of Boeing and Airbus production rate schedules, FAA airworthiness directive issuance patterns, and elastomer compound pricing indices anchored the trend analysis, supplemented by interviews with airframe integration engineers, airline technical procurement directors, MRO aftermarket managers, and composite fabrication specialists. Secondary validation drew from FAA Part 25.571 certification databases, EASA CS-25 compliance filings, EU REACH substance restriction updates, and aerospace customs trade records. Bottom-up supplier capacity assessments and top-down fleet renewal demand projections were triangulated to cross-verify volume estimates.
Input-output matrix framing linked narrowbody and widebody delivery schedules through polymer-matrix composite adoption curves to exterior mount category demand across the projection horizon. Segmentation dimensions modeled include product type, material grade tier, end-user procurement pattern, and application platform duty cycle. CAGRs were derived from slope analysis of historical certification timelines against projected fleet replacement waves. Industry-specific forecast inputs incorporated sustainable aviation fuel thermal exposure profiles and lightning-strike conductivity thresholds for composite pylon configurations.
Underlying measurement precision varies by segment; engine mounts with mandatory replacement cycles carry tighter precision than emerging eVTOL hardpoint categories where specification standards remain fluid. Forecasts reflect assumptions regarding Boeing and Airbus production rate stability, EASA-FAA harmonization progress, and composite bonding technician pipeline development. Deviation in sustainable aviation fuel adoption velocity or REACH substance restriction enforcement timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Fiber-Optic Strain Sensing Systems for Composite Wing Structures Market
Aircraft
Aeronautic Propeller Market
Aircraft
Aircraft Radome Market
Aircraft
Aircraft Aerostructures Market
Aircraft
Firefighting Aircraft Market
Aircraft
Japan Aerospace and Defense Market
Aircraft
Commercial Helicopter Market
Aircraft
Active Air Deflector Market
Aircraft
Flight Management Systems Market
Aircraft
North America General Aviation Market
Aircraft
Commercial Aircraft Wing Market
Aircraft
Europe Aircraft Manufacturing Market
Aircraft
Aircraft Nacelle Systems Market
Aircraft
North America Aircraft Band Clamps Market
Aircraft
Aircraft Manufacturing Market
Aircraft
Single-Seat Gyrocopter Market