
 Europe Military Aviation Market | 2026-2036
Europe Military Aviation Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Military Aviation Market Foresight
The EU Green Deal's sustainable aviation fuel mandates are expanding the addressable market for low-emission military propulsion retrofits and new-build platforms. BAE Systems leverages its Tempest sixth-generation fighter partnership to anchor UK industrial participation in collaborative European programs. Airbus SE dominates the A400M transport and tanker segment, while Safran SA specializes in propulsion systems that comply with emerging EU defense carbon benchmarks.
Europe military aviation encompasses manned and unmanned aerial platforms, mission systems, and training infrastructure designed for state defense and security operations, typically integrating fly-by-wire controls, active electronically scanned array radar, and sovereign encrypted datalinks for contested electromagnetic environments. Fixed-wing aircraft and UAVs represent the largest product categories, with rotorcraft retaining mature replacement cycles in naval and utility roles. Combat operations and aerial surveillance applications attract the majority of technology investment, particularly in avionics and weapon systems where margin pools concentrate among integrated prime contractors.
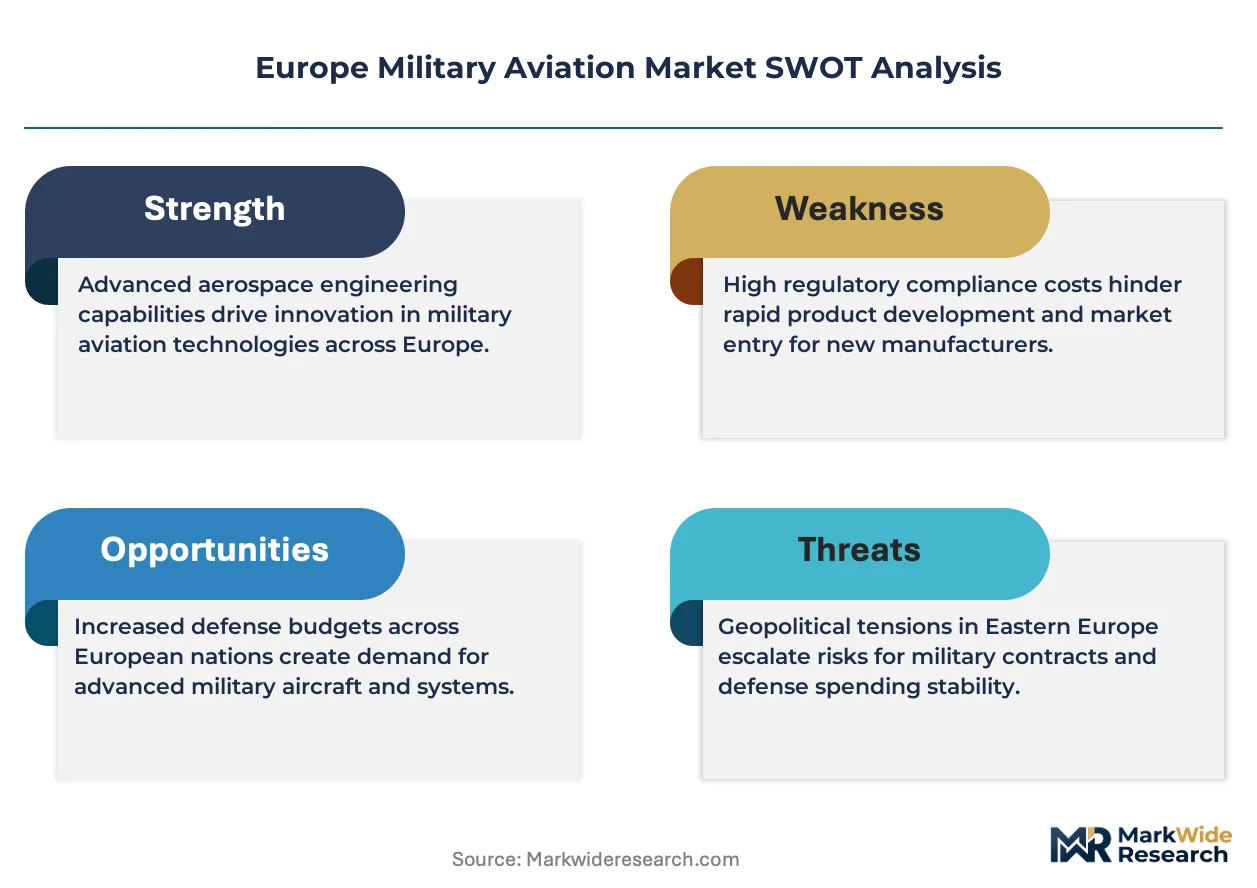
REACH chemical regulations and the EU AI Act constrain materials sourcing and autonomous system certification timelines for platforms operating across member states. EASA military certification frameworks and national aviation authorities in France, Germany, and Italy shape airworthiness standards that determine market access for new entrants. Stakeholders must monitor how the European Defence Fund and NATO capability targets realign national procurement schedules toward collaborative programs versus sovereign platforms.
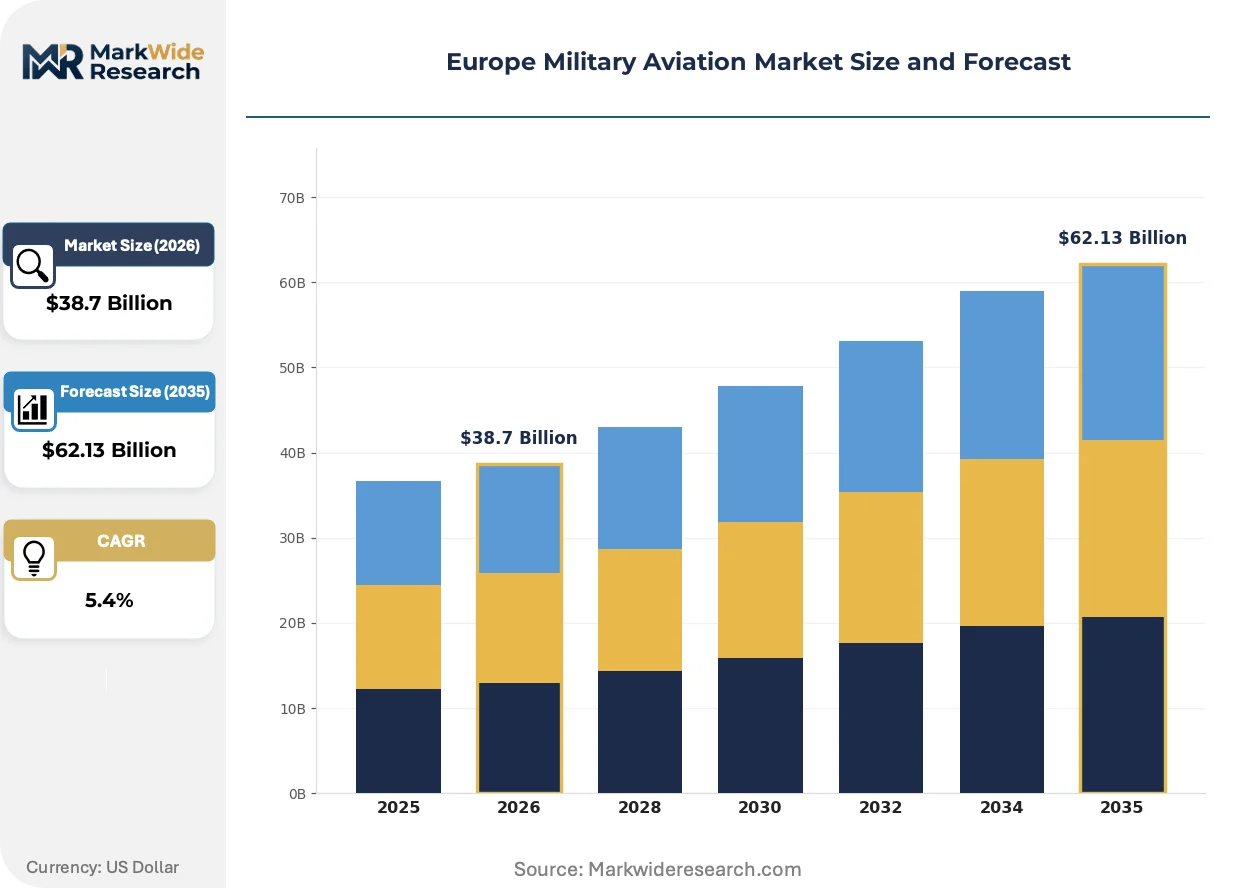
Market Dynamics
Collaborative defense procurement across EU member states is compressing national sovereign programs into multinational frameworks, forcing prime contractors to restructure industrial participation models around shared development costs and distributed manufacturing footprints.
Growth Catalysts
- NATO Capability Targets:Alliance-mandated interoperability standards are accelerating fleet modernization timelines across Eastern European air forces, particularly in tactical transport and intelligence-gathering platforms.
- EU Green Deal SAF Mandates:Binding sustainable aviation fuel quotas for military operators by 2030 are creating retrofit demand for propulsion systems compatible with synthetic and bio-derived fuels.
- Active Electronically Scanned Array Radar:AESA technology migration from combat aircraft to maritime patrol and transport platforms is expanding the addressable electronics market beyond traditional fighter primes.
Market Restraints
- Titanium and Nickel Superalloy Concentration:Russian-origin titanium sponge and vacuum arc remelt capacity disruption has exposed raw material dependencies in turbine blade supply chains.
- REACH Chemical Compliance:ECHA substance restrictions on hexavalent chromium coatings and legacy solvents are forcing reformulation of surface treatments with multi-year requalification timelines.
- Skilled Aerostructures Labor Scarcity:Composite layup and bonded assembly expertise concentrates in Toulouse, Hamburg, and Broughton, constraining surge capacity for new program ramp-ups.
Strategic Opportunities
- Poland and Baltic States:Frontline NATO members are accelerating unmanned combat air system procurement with offset requirements favoring local final assembly partnerships.
- Manned-Unmanned Teaming:Fighter-directed loyal wingman architectures are creating new subsystem categories in secure datalinks, autonomous decision aids, and modular mission computers.
- European Defence Fund Co-Development:EDF Pathfinder projects for next-generation effectors and electronic warfare suites are opening non-traditional supplier access to classified program tiers.
Industry Challenges
- EASA Military Certification Timelines:Harmonized airworthiness frameworks remain incomplete across France, Germany, and Italy, forcing redundant national qualification campaigns for cross-border operations.
- Legacy Platform Interoperability:Fourth-generation fighters with analog avionics architectures require costly middleware development to interface with fifth-generation sensor networks and battle management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Military Aviation Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $62.13 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing Aircraft, Rotorcraft, UAVs, Simulation Systems Application: Combat Operations, Aerial Surveillance, Reconnaissance, Training End User: Air Forces, Defense Contractors, Government Agencies, Private Security Technology: Avionics, Navigation Systems, Weapon Systems, Communication Equipment |
| Companies Covered | BAE Systems plc, Lockheed Martin Corporation, Airbus SE, Thales Group, Rheinmetall, Dassault Aviation, Boeing, Safran SA, Leonardo S.p.A, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Military Aviation Market Shifts & Advancements
Open systems architectures are dismantling proprietary avionics stacks, enabling modular upgrades that decouple airframe life cycles from mission system refresh rates and fragment traditional prime contractor control over platform sustainment.
Adaptive cycle propulsion is consolidating variable-cycle engine technology originally developed for sixth-generation fighter demonstrators into medium-altitude long-endurance unmanned platforms. Italian and Spanish drone programs are adopting these powerplants to extend endurance beyond 40 hours while maintaining dash speeds for contested airspace transit. The technology is consolidating thermal management and fuel efficiency gains previously segmented between combat and reconnaissance engine lineages.
EU AI Act conformity assessments for autonomous weapon systems are imposing documentation burdens on machine learning training pipelines and decision logic traceability. French and German national aviation authorities are interpreting Article 52 prohibitions on biometric categorization and social scoring to constrain target recognition algorithms in strike drones. Combat air system developers are responding by segregating training data provenance and establishing sovereign cloud infrastructure for sensitive model development.
Performance-based logistics contracts are displacing traditional spares-and-repair arrangements in Scandinavian and Benelux air forces. Contractors now assume availability risk for engine and radar subsystems, with payment tied to mission-capable rates rather than parts delivered. Sweden and Norway have pioneered these arrangements for Gripen and F-35 fleets, compressing supplier margins while transferring inventory risk upstream to primes and their tier-one partners.
Europe Military Aviation Market Segmentation
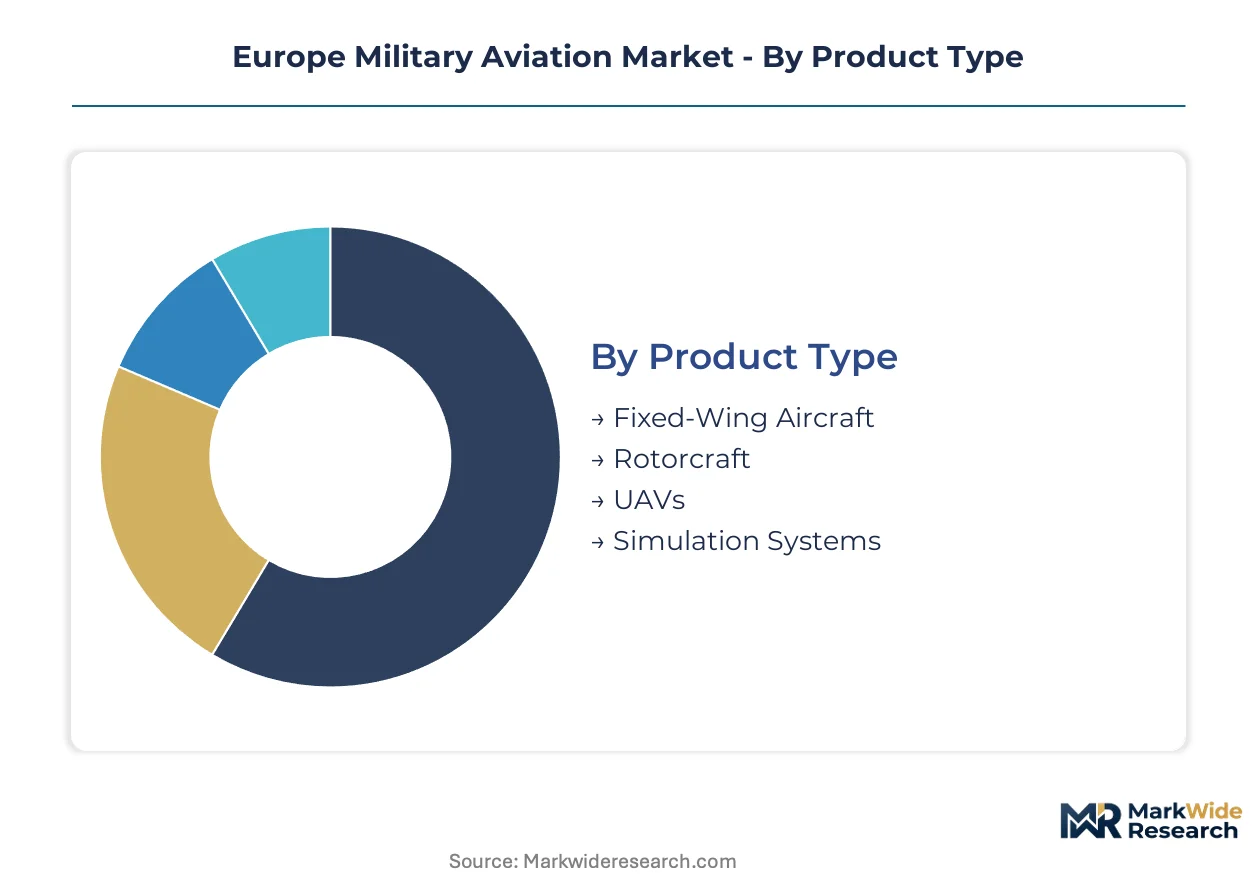
European military aviation procurement splits sharply between high-unit-cost combat platforms with decades-long service horizons and volume-driven unmanned systems requiring rapid refresh cycles. Understanding where technology investment concentrates versus where fleet mass accumulates shapes supplier positioning across NATO and EU defense frameworks.
Product Type:
Fixed-wing platforms absorb the majority of development capital while unmanned systems capture procurement volume growth across Eastern European air forces.
- Fixed-Wing Aircraft:Manned combat and transport platforms integrate active electronically scanned array radar and fly-by-wire flight controls. Demand concentrates in Germany, France, and the United Kingdom for sixth-generation fighter development under NATO capability targets, though titanium supply chain disruptions from Russian-origin sponge have extended engine blade procurement timelines.
- UAVs:Tactical and medium-altitude long-endurance systems carry sovereign encrypted datalinks and modular mission computers for contested electromagnetic environments. Poland and Baltic states are accelerating unmanned combat air system procurement with offset requirements favoring local final assembly partnerships.
- Rotorcraft:Naval and utility helicopters retain mature replacement cycles with composite rotor blade manufacturing concentrated in Toulouse and Hamburg industrial clusters.
- Simulation Systems:Synthetic training environments replicate sensor fusion and electronic warfare scenarios for pilot readiness without flight hour consumption.
Mature deployment sits with Fixed-Wing Aircraft. Newer deployment is concentrated in UAVs.
Application:
Combat missions drive avionics and weapon system margins while surveillance applications expand AESA technology into non-traditional platform categories.
- Combat Operations:Air-to-air and air-to-ground mission systems require integrated electronic warfare suites and precision-guided munitions carriage. French and German national aviation authorities are interpreting EU AI Act Article 52 constraints on target recognition algorithms, forcing segregation of training data provenance for strike drone development.
- Aerial Surveillance:Maritime patrol and ground surveillance platforms migrate AESA technology from fighter lineages to extend detection range against low-observable targets. Scandinavian air forces are pioneering performance-based logistics contracts tied to mission-capable rates rather than spares delivered.
- Reconnaissance:Signals intelligence and synthetic aperture radar payloads demand thermal management solutions for extended endurance missions.
- Training:Live-virtual-constructive architectures reduce operational conversion costs for fourth-to-fifth-generation fighter transitions.
Technology refresh concentrates in Combat Operations. Fleet expansion is climbing the fastest in Aerial Surveillance.
End User:
Air force procurement dominates capital allocation while defense contractors assume availability risk through outcome-based sustainment arrangements.
- Air Forces:National military aviation services across NATO's eastern flank are modernizing tactical transport and intelligence-gathering fleets. Sweden and Norway have pioneered performance-based logistics for Gripen and F-35 fleets, compressing supplier margins while transferring inventory risk upstream.
- Defense Contractors:Prime contractors and tier-one partners manage subsystem availability under long-term service contracts with payment tied to operational readiness metrics.
- Government Agencies:Border security and coast guard operators acquire modified military platforms for sovereign airspace patrol without full combat system integration.
- Private Security:Specialized contractors operate surveillance platforms under government contract for intelligence, surveillance, and reconnaissance tasking.
Platform ownership rests with Air Forces. Risk transfer is accelerating through Defense Contractors.
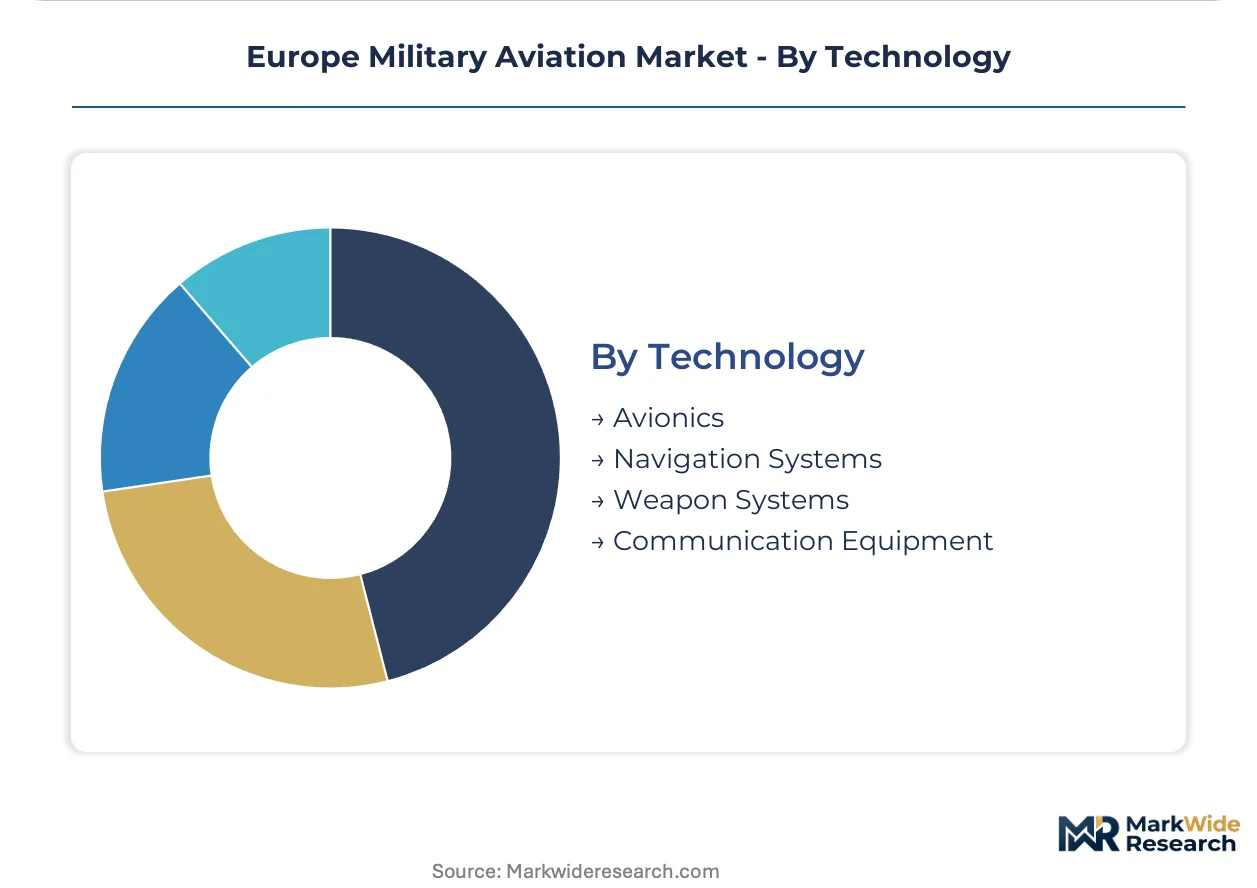
Technology:
Avionics integration determines platform upgrade economics while weapon system certification timelines constrain new entrant market access.
- Avionics:Open systems architectures dismantle proprietary mission computer stacks, enabling modular upgrades that decouple airframe life cycles from sensor refresh rates. EASA military certification frameworks remain incomplete across France, Germany, and Italy, forcing redundant national qualification campaigns.
- Weapon Systems:Hardpoint integration, stores management computers, and precision munitions interfaces require EDA Pathfinder co-development funding for next-generation effectors. REACH chemical regulations constrain hexavalent chromium coatings in launcher surface treatments with multi-year requalification timelines.
- Navigation Systems:GNSS-denied positioning using celestial and terrain reference updates ensures mission continuity in contested electromagnetic environments.
- Communication Equipment:Sovereign datalinks with NATO interoperability standards enable coalition operations while protecting classified waveform architectures.
Platform differentiation depends on Avionics. Mission effectiveness hinges on Weapon Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of military aviation platforms concentrates in Western European aerospace clusters, while consumption spreads across NATO's eastern flank where fleet modernization accelerates. The EU Green Deal and NATO capability targets are synchronizing procurement timelines across member states. Industrial participation requirements increasingly favor distributed manufacturing footprints over sovereign national programs.
Germany
FCAS sixth-generation fighter development and A400M transport fleet expansion drive procurement budgets. The EU AI Act constrains autonomous target recognition algorithms for strike drones, forcing segregation of training data provenance. Hamburg and Munich industrial clusters specialize in composite aerostructures and propulsion systems respectively.
France
Rafale export campaigns and nEUROn UCAV demonstrator programs anchor defense aerospace output. ANSM and DGAC interpret Article 52 prohibitions on biometric categorization for combat air systems. Toulouse and Bordeaux manufacturing concentrations handle final assembly and flight test operations for manned and unmanned platforms.
United Kingdom
Tempest fighter partnership and F-35 Lightning II procurement dominate capital allocation. Broughton and Warton industrial sites concentrate on wing fabrication and combat aircraft final assembly. UK national aviation authority frameworks shape airworthiness certification for collaborative European programs.
Poland
Frontline NATO positioning accelerates unmanned combat air system procurement with offset requirements favoring local final assembly. The European Defence Fund co-development pathways open access to classified electronic warfare programs. Warsaw and Rzeszow emerging clusters focus on drone integration and subsystem manufacturing partnerships.
Italy
Leonardo-led programs in M-346 trainer and Falco UAV families sustain aerospace employment. EASA military certification harmonization remains incomplete, forcing redundant national qualification campaigns. Turin and Brindisi facilities specialize in flight simulation systems and tactical unmanned platform assembly respectively.
Europe Military Aviation Market Competitive Landscape
The competitive structure tilts toward integrated prime contractors with established NATO supply chain access. National champion models persist in France, Germany, and the United Kingdom, though collaborative program structures are compressing sovereign platform development. Two strategic archetypes dominate: full-spectrum integrators controlling airframe-through-mission-system stacks, and subsystem specialists capturing propulsion and avionics niches. Competitive moves concentrate on industrial participation restructuring for multinational frameworks and performance-based logistics contract capture.
Among UK-based integrators, BAE Systems plc exemplifies the full-spectrum prime archetype through sixth-generation fighter partnerships. Airbus SE and Safran SA represent the continental European model: the former anchoring transport and tanker platform integration, the latter occupying propulsion specialization with EU Green Deal compliance positioning. These three entities illustrate how geographic origin and corporate structure map onto divergent strategic postures within NATO collaborative procurement frameworks.
| Leading Market Players |
|---|
| BAE Systems plc |
| Lockheed Martin Corporation |
| Airbus SE |
| Thales Group |
| Rheinmetall |
| Dassault Aviation |
| Boeing |
| Safran SA |
| Leonardo S.p.A |
| Others |
Supply & Pricing Matrix
NATO procurement offices and national defense ministries concentrate platform acquisition through multi-year framework contracts, anchoring contract-based long-term offtake pricing with payment schedules tied to development milestones and operational availability guarantees rather than unit delivery.
Pricing Analysis
Margin tightening in propulsion and avionics subsystems traces to REACH chemical compliance costs and titanium supply chain disruption, with prime contractors absorbing requalification expenses to maintain platform integration relationships. Pricing stratifies across certified military-grade, dual-use commercial-military, and developmental prototype tiers, with EU AI Act conformity assessments adding certification premiums for autonomous systems. Cost compression accelerates in rotorcraft and transport categories as performance-based logistics contracts transfer inventory risk upstream. Eastern European air forces exhibit highest price sensitivity due to accelerated fleet modernization timelines, while sixth-generation fighter programs demonstrate lowest sensitivity given sovereign industrial participation requirements.
Supply Chain Analysis
Regional distribution centers in Toulouse, Hamburg, and Broughton coordinate hub-and-spoke patterns for composite aerostructures and mission systems, with final assembly concentrating in France, Germany, and the United Kingdom. Raw material dependencies center on Russian-origin titanium sponge, nickel superalloys for turbine blades, and specialized composites from proprietary prepreg suppliers. Single-source vulnerability in vacuum arc remelt capacity exposes engine blade supply chains to geopolitical disruption. Distribution runs through national military logistics commands with NATO standardization agreements enabling cross-border spare pooling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Military Aviation Market operates as a cost-of-compliance arena where REACH chemical regulations and EU AI Act certification timelines erect barrier-to-entry moats favoring incumbent primes with established EASA military certification pathways.
For Market Incumbents: Anticipate titanium supply chain restructuring by securing alternative sponge sources from Japan and Kazakhstan while investing in additive manufacturing for turbine blade geometries to reduce forging dependencies. Performance-based logistics contract expansion in Scandinavian markets threatens traditional spares-margin pools, requiring predictive maintenance analytics capabilities to defend availability-guarantee profitability. For New Entrants and Emerging Players: Digital-channel routes through European Defence Fund Pathfinder project portals offer non-traditional supplier access to classified electronic warfare and autonomous effector development tiers. Poland and Baltic states unmanned combat air system procurement presents the most penetrable entry vector, with offset requirements favoring local final assembly partnerships over full platform development. Target subsystem niches in secure datalinks and modular mission computers where open systems architectures fragment traditional prime contractor control. For Investors and Strategic Acquirers: The window for entry favors propulsion and avionics specialists with EU Green Deal compliance positioning and established EASA certification relationships. Long-term viability hinges on capturing sustainment revenue streams under outcome-based contracts rather than development-phase margins. Monitor European Defence Fund allocation shifts toward collaborative programs versus sovereign platforms as the inflection indicator for industrial consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| EU Green Deal Propulsion Retrofit | Safran SA and Rolls-Royce capture synthetic fuel-compatible engine upgrade demand from A400M and Eurofighter operators. |
| Performance-Based Logistics Contract | Swedish and Norwegian Gripen and F-35 availability agreements compress supplier margins while transferring inventory risk to primes. |
| Manned-Unmanned Teaming Architecture | BAE Systems Tempest partnership develops loyal wingman datalink standards fragmenting proprietary avionics stacks. |
| REACH Chemical Compliance Investment | Surface treatment reformulation for hexavalent chromium alternatives forces multi-year requalification timelines favoring incumbents. |
| Eastern European Offset Partnership | Poland and Baltic states local final assembly requirements create manufacturing footprint expansion opportunities for drone integrators. |
Research Methodology
Independent corroboration across NATO capability target documentation, European Defence Fund project registries, and EASA military certification frameworks underwrites the qualitative findings presented in this analysis. Primary interviews with program managers at national aviation authorities, procurement officers at Eastern European air forces, and subsystem engineering directors at tier-one suppliers combined with secondary validation from customs trade data, SEC 10-K filings of listed primes, and EU official journal procurement notices. Bottom-up platform delivery forecasts and top-down defense budget allocation analysis triangulate market sizing across the projection horizon.
Comparable-period anchoring to historical NATO procurement cycles and EU defense spending patterns shaped the forecast window, with segmentation modeling across platform type, mission application, and technology tier throughout the forecast period. CAGRs derive from fitted trend extrapolation moderated by policy scenario weighting. Industry-specific inputs include titanium spot price volatility indices and EDF funding allocation trajectories for next-generation effector development.
The model holds under sustained NATO capability target adherence and EU Green Deal implementation timelines; deviation in transatlantic burden-sharing negotiations or titanium supply normalization would shift procurement volume and pricing assumptions. Periodic stress-testing of base assumptions against defense budget announcements and certification framework harmonization progress is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Europe Aerospace and Defense Market
Aircraft and Aerospace Components
Spain Rotor Blade Market
Aircraft and Aerospace Components
Aircraft Hose Fittings Market
Aircraft and Aerospace Components
North America Rotor Blade Market
Aircraft and Aerospace Components
Germany Aerospace and Defense Market
Aircraft and Aerospace Components
Advanced Composite Fuselage Panel Systems for Next-Gen Narrow-Bodies Market
Aircraft and Aerospace Components
Cold Gas Thrusters Market
Aircraft and Aerospace Components
Altimeter Market
Aircraft and Aerospace Components
Aviation Connector Market
Aircraft and Aerospace Components
Europe Drone Motor Market
Aircraft and Aerospace Components
Global Commercial Aircraft Airframe Materials Market
Aircraft and Aerospace Components
Aerostructures Market
Aircraft and Aerospace Components
Aircraft Nacelle Components Market
Aircraft and Aerospace Components
Global Aircraft Nacelle and Thrust Reverser Market
Aircraft and Aerospace Components
Composite Winglet and Sharklet Structures Market
Aircraft and Aerospace Components
Aerospace Pressure Bulkheads Market