
 Belly Fairing Modifications for Freighter and Combi Aircraft Market | 2026-2036
Belly Fairing Modifications for Freighter and Combi Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Belly Fairing Modifications for Freighter and Combi Aircraft Market Insights
E-commerce logistics operators is reorganizing demand patterns across the belly fairing modification landscape, pulling volume away from traditional cargo airlines toward parcel integrators with high-cycle utilization needs. Boeing leverages its OEM retrofit authority and factory engineering data to dominate structural modification programs for its own platforms. ST Engineering competes through third-party retrofit capabilities anchored in Singapore and expanding European MRO footprints. Elbe Flugzeugwerke specializes in narrowbody freighter conversions with integrated belly fairing reinforcement packages.
Belly fairing modifications encompass structural alterations to the lower fuselage aerodynamic panels of cargo-configured aircraft, typically involving aluminum or composite skin replacement, longeron reinforcement, and inspection port integration to accommodate increased landing cycles and ground handling equipment contact. These modifications extend airframe service life while maintaining fuel efficiency parameters within original type certificate limits. Reinforcement modifications lead the modification type segment due to mandatory compliance with fatigue-critical structure airworthiness directives. Third-party retrofit installations capture expanding share as independent conversion houses build FAA/EASA dual certification capabilities outside OEM channels.
FAA airworthiness directives and EASA certification memoranda jointly govern structural modification standards, with both agencies mandating damage tolerance analysis for converted freighters operating beyond original passenger-duty cycle profiles. The EU AI Act and emerging MEE emissions tracking requirements in China add compliance layers to modification documentation and material traceability protocols. Stakeholders must monitor regulatory divergence between FAA order 8110 and EASA Part 21J implementation timelines when planning multi-registry fleet conversion programs.
Market Dynamics
E-commerce logistics operators are pulling demand away from traditional cargo carriers toward parcel integrators with high-cycle utilization requirements, restructuring the entire modification services landscape around fleet conversion velocity rather than passenger-to-freighter feedstock availability.
Growth Catalysts
- FAA Airworthiness Directives on Fatigue-Critical Structures:Mandatory damage tolerance analysis for converted freighters operating beyond original passenger-duty cycles creates baseline demand for reinforcement modifications.
- Aluminum-Composite Hybrid Skin Technologies:Advanced material combinations reduce weight penalties while maintaining structural integrity under increased landing cycle profiles.
- Integrator Network Expansion in the United States:Parcel operators anchor conversion activity through dedicated MRO partnerships and captive modification scheduling.
Market Restraints
- Aerospace-Grade Aluminum Sheet Volatility:Input cost fluctuations compress modification house margins on fixed-price conversion contracts.
- OEM Engineering Data Access Concentration:Boeing and Airbus control factory structural drawings, limiting third-party retrofit design authority.
- Original Type Certificate Limitations:Service life extension modifications cannot exceed certified maximum zero-fuel weight thresholds without full recertification.
Strategic Opportunities
- China MEE Emissions Tracking Compliance:Material traceability documentation requirements favor modification houses with integrated supply chain digitization capabilities.
- Inspection Port Integration Services:Structural health monitoring sensor embedding represents emerging revenue layer beyond basic skin replacement.
- European EASA Part 21J Design Organization Approvals:Dual-certification capabilities unlock cross-registry fleet conversion programs for leasing companies.
Industry Challenges
- Damage Tolerance Engineering Talent Scarcity:Specialized fatigue analysis expertise concentrates at OEM engineering centers and select MRO clusters.
- FAA Order 8110 and EASA Implementation Timeline Divergence:Multi-registry certification programs face documentation reconciliation delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Belly Fairing Modifications for Freighter and Combi Aircraft Market |
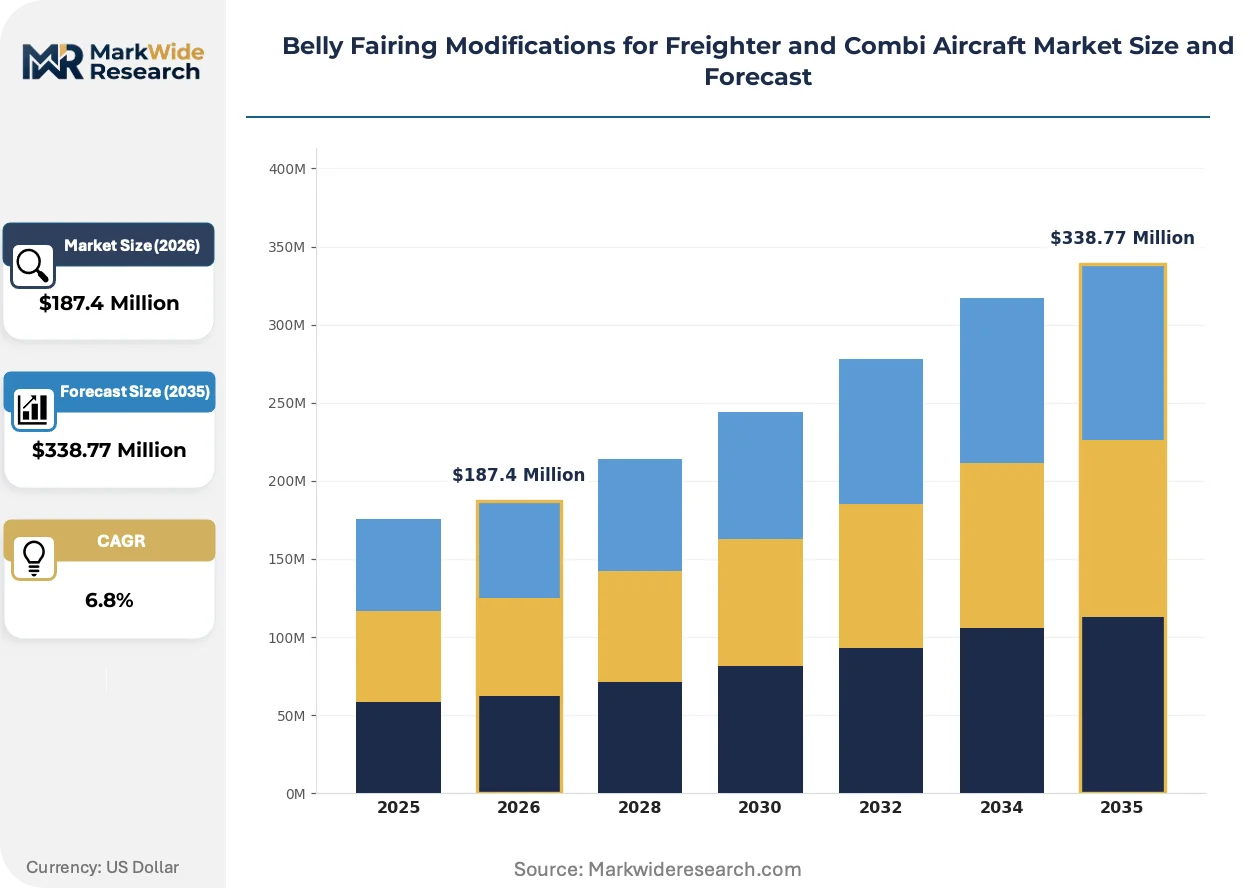
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Modification Type: Reinforcement, Extension, Inspection Port Addition, Aerodynamic Enhancement Aircraft Variant: Freighter, Combi, Converted Passenger, Specialized Cargo End User: Logistics Operators, Cargo Airlines, Charter Services, Aircraft Lessors Installation Method: OEM Retrofit, Third-Party Retrofit, In-Hangar Upgrade, Field Modification |
| Companies Covered | Boeing, Airbus, Elbe Flugzeugwerke, ST Engineering, HAECO Group, Precision Aircraft Solutions, Aeronautical Engineers, Israel Aerospace Industries, PEMCO Conversions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Belly Fairing Modifications for Freighter and Combi Aircraft Market Trends and Innovations
Modification technology is splitting along capability lines, separating OEM-authorized retrofit programs from independent conversion houses building alternative certification pathways through regulatory technology investments.
Composite reinforcement patches is bifurcating the structural modification market between quick-turn bonded repairs for aging narrowbody freighters and full skin replacement programs for widebody platforms. Express operators with 737-800SF fleets adopt bonded solutions for cycle-count extension. Third-party MROs capture volume that OEM channels cannot schedule, compressing lead times from eighteen to twelve weeks on standard reinforcement packages.
EASA Part 21J design organization requirements are tightening documentation standards for structural modification approvals. Independent conversion houses must demonstrate equivalent safety findings to OEM engineering data. Narrowbody freighter specialists in Central and Eastern Europe accelerate dual-certification investments to serve leasing company fleets registered across multiple jurisdictions.
Buyer concentration among parcel integrators is forcing modification houses toward dedicated capacity contracts rather than spot-market conversion slots. Traditional cargo airlines lose scheduling priority as Amazon Air, DHL Express, and FedEx anchor multi-year MRO agreements. This concentration is most visible in the United States, where integrator-owned feedstock dominates 737-800 and A321 conversion pipelines.
Belly Fairing Modifications for Freighter and Combi Aircraft Market Segmentation
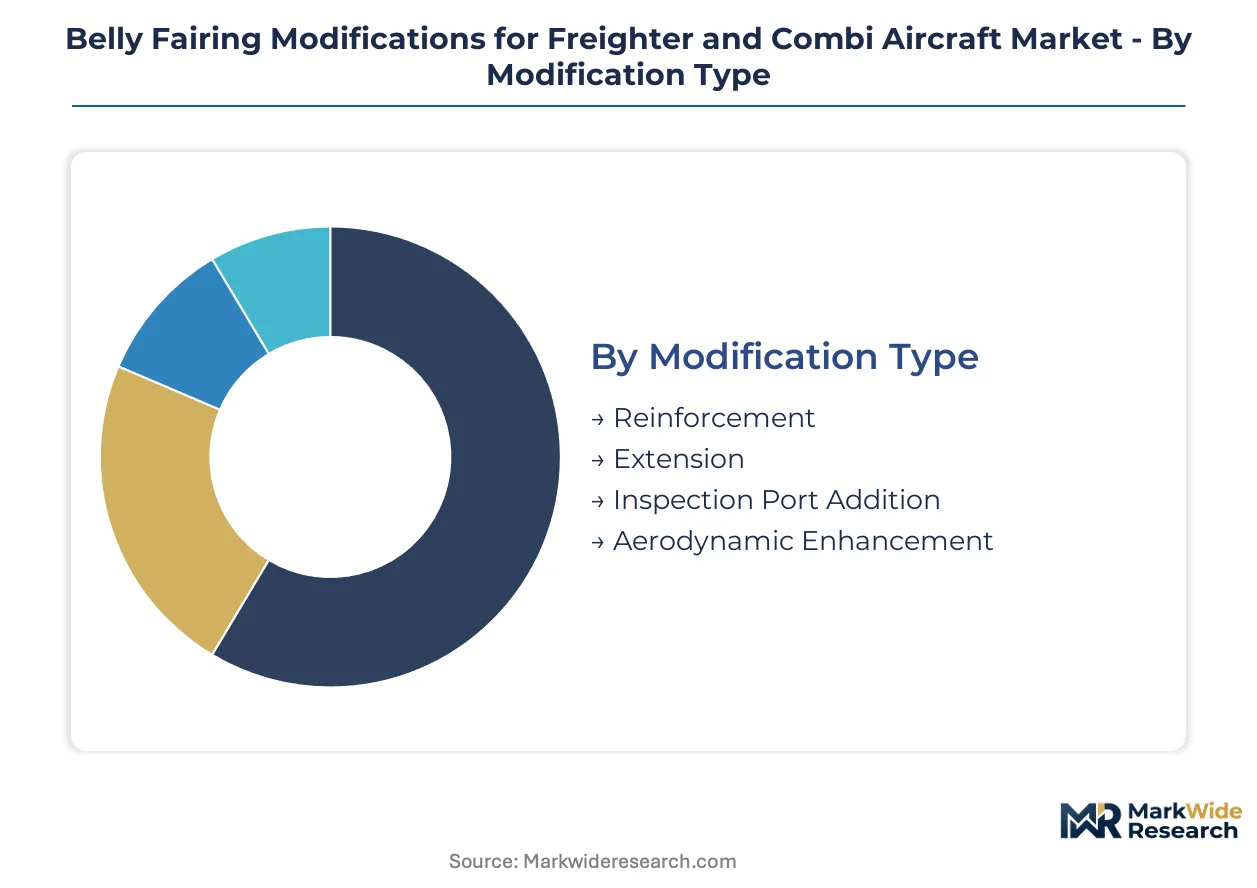
Belly fairing modifications fragment across technical specifications, aircraft configurations, and service delivery models. Each segmentation axis reveals distinct procurement patterns and margin structures that shape competitive positioning across the modification services landscape.
Modification Type:
Domestic demand concentrates in reinforcement and inspection port additions tied to FAA airworthiness directive compliance, while export-led segments like aerodynamic enhancement serve Middle East and Asia-Pacific cargo carriers seeking fuel efficiency gains on long-haul routes.
- Reinforcement:Structural strengthening of longerons and frame sections using aluminum-composite hybrid laminates to withstand elevated landing cycle stresses. Parcel integrators in the United States mandate this modification for converted narrowbody freighters operating six to eight daily cycles. Reinforcement modifications anchor baseline revenue for conversion houses with FAA Part 145 certification.
- Inspection Port Addition:Integration of access panels and structural health monitoring interfaces into lower fuselage skin assemblies. European cargo carriers under EASA jurisdiction drive specification evolution toward embedded sensor compatibility. This segment climbs fastest as predictive maintenance adoption spreads beyond integrator fleets to traditional cargo airlines.
- Extension:Lengthening of existing fairing structures to accommodate revised center-of-gravity envelopes on heavy-freight configurations.
- Aerodynamic Enhancement:Reshaping of lower fuselage contours to reduce form drag on high-utilization express networks.
Reinforcement modifications hold the largest share; momentum sits with inspection port addition as sensor integration requirements expand.
Aircraft Variant:
Cost tier segmentation separates factory-built freighters commanding premium modification pricing from converted passenger feedstock competing on turnaround speed and slot availability.
- Converted Passenger:Former narrowbody airliners reconfigured for cargo duty requiring comprehensive belly fairing reinforcement to address structural fatigue accumulation from prior high-cycle passenger operations. Demand clusters at conversion facilities in the United States and Singapore serving 737-800 and A321 platforms. Converted passenger variants generate highest modification revenue per airframe due to scope of structural remediation required.
- Freighter:Purpose-built cargo aircraft with original equipment manufacturer structural specifications optimized for ground handling equipment contact and reduced pressurization cycles. Factory freighters concentrate modification demand in heavy maintenance intervals rather than conversion events. This segment gains share fastest as e-commerce operators favor new-build feedstock with cleaner maintenance histories.
- Combi:Mixed passenger-cargo configurations requiring segmented fairing modifications preserving cabin pressurization integrity forward of the cargo partition.
- Specialized Cargo:Custom-configured platforms for temperature-controlled pharmaceuticals, live animals, or oversized freight with non-standard floor loading.
Converted passenger variants dominate current volume; factory freighters represent the steepest expansion trajectory as feedstock quality preferences shift.
End User:
Customer type segmentation distinguishes integrator procurement patterns—characterized by multi-year master service agreements and captive scheduling—from spot-market cargo airline demand.
- Logistics Operators:Parcel integrators and e-commerce fulfillment networks operating high-frequency hub-and-spoke systems with standardized fleet configurations. These buyers negotiate dedicated modification capacity at ST Engineering and Boeing facilities, compressing lead times through volume commitments. Logistics operators are displacing traditional cargo carriers as the primary demand source for narrowbody conversion programs.
- Cargo Airlines:Scheduled and charter freight carriers with mixed fleet ages and variable utilization profiles. These operators prioritize cost minimization over speed, sourcing modifications through competitive tender rather than strategic partnerships. Cargo airline demand concentrates in Asia-Pacific and European markets with aging widebody freighter fleets.
- Charter Services:On-demand cargo operators with irregular maintenance schedules and aircraft-specific modification requirements.
- Aircraft Lessors:Fleet owners seeking residual value preservation through proactive modification investment prior to lease placement.
Logistics operators hold the largest share; lessors are gaining share fastest as sale-leaseback structures proliferate in freighter financing.
Installation Method:
Supply concentration bifurcates between OEM-controlled channels with exclusive engineering data access and independent conversion houses building regulatory technology capabilities.
- Third-Party Retrofit:Independent MRO facilities and conversion specialists executing modifications under FAA Part 145 or EASA Part 145 certificates without original equipment manufacturer authorization. These providers capture volume that OEM channels cannot schedule, particularly for narrowbody platforms with standardized modification packages. Third-party retrofit is expanding most quickly as dual-certification investments unlock cross-registry fleet programs.
- OEM Retrofit:Boeing and Airbus factory modification programs leveraging proprietary structural drawings and damage tolerance analysis databases. OEM retrofit commands premium pricing for widebody platforms and complex fatigue-critical repairs. This segment concentrates in the United States and France with limited geographic replication.
- In-Hangar Upgrade:Modifications executed during scheduled maintenance events without dedicated conversion line allocation.
- Field Modification:Deployable teams performing structural repairs at operator bases for aircraft with restricted ferry permissions.
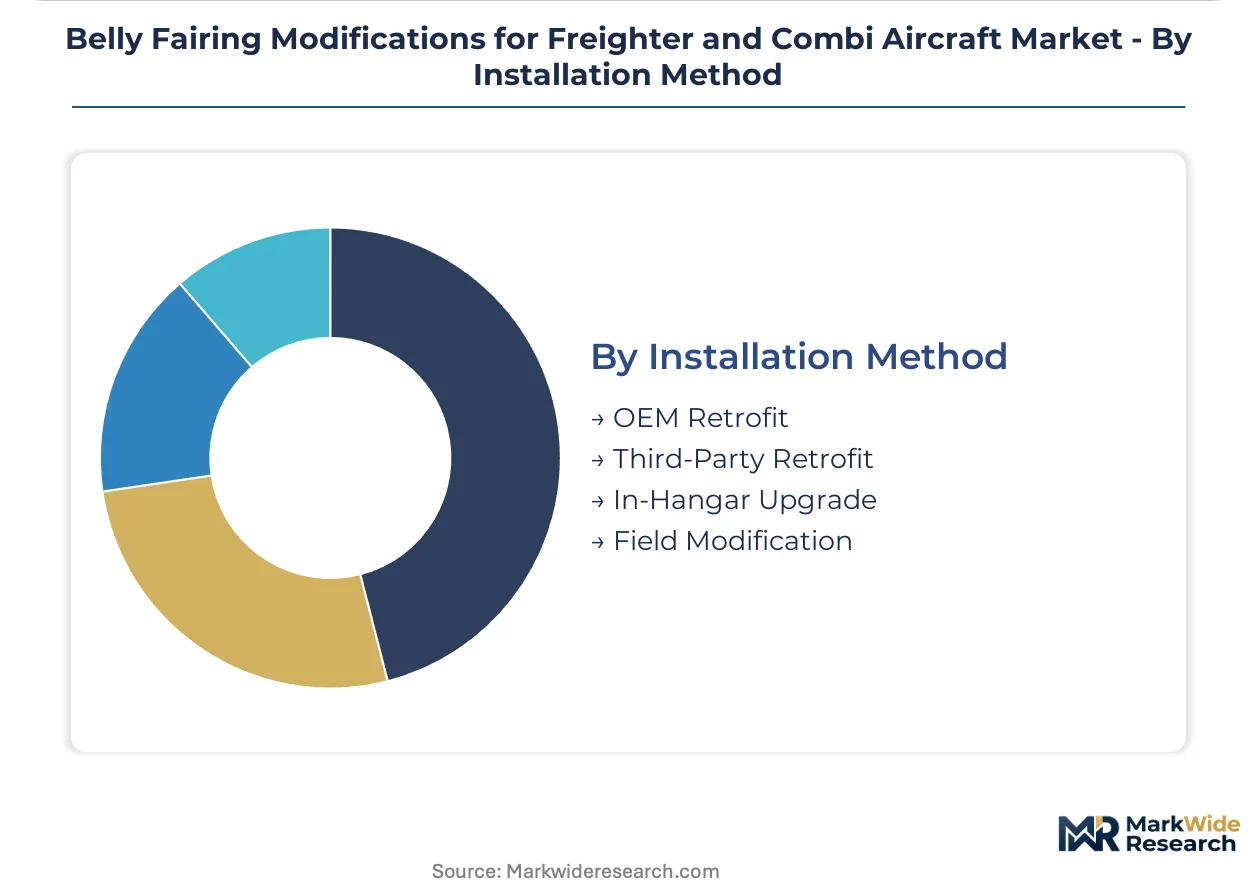
Third-party retrofit holds the largest share; OEM retrofit maintains pricing power on widebody platforms where engineering data access creates supply constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Modification demand flows from conversion centers in the United States toward integrator networks operating high-cycle narrowbody freighters across domestic hub-and-spoke systems. European facilities serve cross-registry leasing fleets requiring dual FAA-EASA certification. Asian conversion houses capture overflow volume from Boeing and Airbus engineering backlogs.
United States
Parcel integrators anchor conversion demand through dedicated MRO partnerships at facilities in Miami, Victorville, and Moses Lake. FAA airworthiness directives on fatigue-critical structures mandate damage tolerance analysis for converted 737-800 freighters. The Southeast cluster around Miami International Airport concentrates third-party retrofit capacity serving Amazon Air and FedEx Express fleets.
Germany
EASA Part 21J design organization approvals concentrate engineering authority at facilities in Dresden and Hamburg. Elbe Flugzeugwerke executes narrowbody conversions with integrated belly fairing reinforcement packages for European cargo operators. The Saxony region hosts specialized modification houses building dual-certification capabilities for cross-border leasing programs.
Singapore
ST Engineering operates third-party retrofit facilities serving Asia-Pacific integrators and traditional cargo carriers. The Seletar aerospace park anchors conversion activity for 737-800SF and A321P2F platforms. Singapore's Civil Aviation Authority maintains bilateral agreements with FAA and EASA that streamline multi-registry certification workflows.
China
Domestic e-commerce logistics operators drive freighter conversion demand at facilities in Guangzhou and Shanghai. MEE emissions tracking requirements impose material traceability documentation standards on modification houses. The Yangtze River Delta cluster develops integrated supply chain digitization capabilities to serve compliance mandates.
Israel
Israel Aerospace Industries maintains conversion engineering expertise at facilities near Tel Aviv serving military and civil freighter markets. The country's national aviation regulator enforces damage tolerance standards aligned with FAA Order 8110 protocols. Israeli modification specialists export engineering services to European and African cargo operators.
Belly Fairing Modifications for Freighter and Combi Aircraft Market Competitive Landscape
Player mix skews toward OEM-authorized retrofit channels with exclusive engineering data access, though third-party conversion houses capture expanding share through regulatory technology investments. Boeing and Airbus dominate widebody modification programs leveraging factory structural drawings. Two strategic archetypes define competitive positioning: OEM engineering centers commanding premium pricing, and independent MROs competing on scheduling flexibility. Dominant competitive moves include dual-certification investments for cross-registry fleet programs and dedicated capacity contracts with parcel integrators.
Within the OEM-authorized tier, Boeing and Airbus occupy positions as engineering data gatekeepers for their respective platforms. Among independent conversion specialists, Elbe Flugzeugwerke exemplifies narrowbody-focused operations, while ST Engineering represents the third-party MRO archetype building multi-jurisdiction certification capabilities. These three companies anchor the competitive structure, with Boeing and Airbus controlling factory retrofit channels and the independents capturing volume that OEM facilities cannot schedule.
| Leading Market Players |
|---|
| Boeing |
| Airbus |
| Elbe Flugzeugwerke |
| ST Engineering |
| HAECO Group |
| Precision Aircraft Solutions |
| Aeronautical Engineers |
| Israel Aerospace Industries |
| PEMCO Conversions |
| Others |
Pricing and Supply Chain Analysis
FAA Part 145 and EASA Part 145 certification requirements gate both supplier qualification and price differentiation simultaneously, concentrating modification authority in facilities with dual-approval capabilities while segmenting pricing across OEM-authorized and independent channels. The regulatory compliance burden creates tiered access that shapes how conversion houses compete on cost and scheduling flexibility.
Pricing Analysis
Current-generation aluminum-composite hybrid laminates command premium pricing over legacy aluminum sheet configurations, while next-generation embedded sensor packages sit at the top tier awaiting scale economics. Three-tier pricing structure across premium, standard, and economy levels separates OEM retrofit programs with factory engineering data from third-party Part 145 facilities and basic in-hangar upgrades. Cost compression in standard-tier reinforcement packages is intensifying because aerospace-grade aluminum sheet volatility squeezes fixed-price contract margins. Traditional cargo airlines exhibit highest price sensitivity, negotiating competitive tenders for spot-market slots, while parcel integrators with captive MRO agreements absorb premium pricing for dedicated capacity.
Supply Chain Analysis
Inbound logistics costs for aerospace-grade aluminum sheet and composite prepreg materials fluctuate with container availability on Asia-North America trade lanes, compressing procurement flexibility for modification houses operating on thin inventory buffers. Supply concentrates in the United States, Germany, and Singapore, where FAA and EASA dual-certification capabilities cluster around conversion engineering expertise. Raw material dependencies center on 2024-T3 aluminum alloy, carbon fiber epoxy systems, and titanium fastener hardware. Single-source vulnerability runs through OEM-controlled structural drawing databases, limiting third-party design authority. Distribution runs through dedicated MRO partnerships with parcel integrators rather than open-market procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
E-commerce logistics disruption and FAA-EASA regulatory divergence on damage tolerance analysis create high-growth conditions for modification services with cross-registry capabilities. The technological inflection sits with embedded structural health monitoring sensors transforming inspection port additions from compliance items into predictive maintenance platforms.
For Market Incumbents: Secure exclusive engineering data licensing from Boeing and Airbus to defend against independent conversion houses building alternative certification pathways through EASA Part 21J investments. Add dedicated modification capacity in the United States Southeast cluster to capture Amazon Air and FedEx Express volume commitments. OEM retrofit channels face margin pressure from third-party scheduling flexibility on narrowbody platforms. For New Entrants and Emerging Players: Differentiate on dual-certification speed for cross-registry leasing company fleets registered across FAA and EASA jurisdictions. Target Central and Eastern European facilities where EASA Part 21J design organization approvals remain underpenetrated relative to conversion demand. Build go-to-market positioning around twelve-week lead time guarantees for standard reinforcement packages, compressing the eighteen-week OEM benchmark. For Investors and Strategic Acquirers: EASA Part 21J implementation timeline divergence reshapes the acquisition landscape toward independent conversion houses with demonstrated equivalent safety findings capabilities. Long-term viability favors facilities with integrated supply chain digitization for China MEE emissions tracking compliance. Watch for FAA airworthiness directive expansion to additional fatigue-critical structures as the signal indicating baseline demand acceleration beyond current reinforcement modification volumes.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Investment | EASA Part 21J approval unlocks cross-registry fleet programs for leasing companies operating mixed-jurisdiction aircraft. |
| Embedded Sensor Integration | Structural health monitoring compatibility positions inspection port additions for predictive maintenance revenue expansion. |
| Aluminum-Composite Hybrid Adoption | Advanced material combinations reduce weight penalties while maintaining integrity under elevated landing cycle stresses. |
| Captive MRO Partnership | Dedicated capacity contracts with parcel integrators secure scheduling priority over spot-market cargo airline demand. |
| Supply Chain Digitization | Material traceability documentation capabilities satisfy China MEE emissions tracking mandates for modification houses. |
Research Methodology
Initial hypotheses were tested against primary input from conversion program managers, FAA Part 145 certification leads, MRO procurement officers, and aerospace materials specialists and refined through secondary validation. Sources included FAA airworthiness directive filings, EASA certification memoranda, customs trade data on aerospace-grade aluminum imports, and SEC 10-K disclosures from MRO operators. Bottom-up fleet conversion pipeline analysis triangulated against top-down e-commerce logistics capacity expansion estimates.
Variance decomposition across the projection horizon isolates drivers by modification type, aircraft variant, installation method, and end-user procurement pattern. Segmentation dimensions modeled include reinforcement versus inspection port specifications, converted passenger versus factory freighter feedstock, third-party retrofit versus OEM-authorized channels, and logistics operator versus cargo airline demand. CAGRs were derived from fleet age profiles, airworthiness directive compliance timelines, and integrator network expansion trajectories. Forecast inputs incorporate landing cycle utilization rates and damage tolerance engineering capacity constraints.
The analysis sits within stated boundaries; outcomes outside sustained e-commerce volume growth or harmonized FAA-EASA certification timelines would require recalibration. Forecasts reflect assumptions on regulatory implementation schedules and material cost trajectories. Specific risks include aerospace-grade aluminum price volatility, OEM engineering data access restrictions, and divergent multi-registry approval timelines. Recalibration cycles align with material shifts in airworthiness directive scope or integrator fleet conversion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aircraft Anchoring System Market
Aircraft
Global Aircraft Tugs Market
Aircraft
America Freighter Aircraft Market
Aircraft
Asia-Pacific General Aviation Market
Aircraft
Aircraft Control Surface Market
Aircraft
India Winglets Market
Aircraft
Fixed Wing Turbine Aircraft Market
Aircraft
Global Aircraft Heat Exchanger Market
Aircraft
Latin America Business Jet Market
Aircraft
US Business Jet Market
Aircraft
Aviation Market
Aircraft
Aircraft Jack Market
Aircraft
Latin America Commercial Aircraft Market
Aircraft
Cargo Compartment Latches Market
Aircraft
Aircraft Aerostructures Market
Aircraft
Aviation Crew Management System Market