
 Aircraft Band Clamps Market | 2026-2036
Aircraft Band Clamps Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Band Clamps Market Analysis
OEM-direct procurement is tilting toward long-term supply agreements with certified specialty fastener manufacturers. Teconnex leverages its vertical integration across material sourcing and precision forming to secure multi-year contracts with European airframers. TransDigm Group Inc. anchors its position through backward integration into proprietary alloy formulations and captive heat-treatment capacity. Eaton Corporation competes by extending its electromechanical systems portfolio to include integrated clamp-and-sensor assemblies for next-generation engine programs.
Aircraft band clamps are circumferential fastening devices engineered from corrosion-resistant alloys, typically stainless steel or titanium grades meeting AMS or MIL specifications, manufactured through precision roll-forming and welding to maintain uniform clamping force across temperature extremes from minus 65 to plus 450 degrees Fahrenheit. Their primary purpose is securing fluid lines, ducting, and wiring harnesses against vibration-induced fatigue in airframe and propulsion systems. Stainless steel variants dominate current production volumes due to established supply chains and cost predictability, while titanium segments capture premium margins on weight-critical platforms. The aftermarket services application channel generates the fastest order velocity as aging fleets require scheduled clamp replacement under corrosion-prevention mandates.
FAA airworthiness directives and EASA certification specifications dictate material traceability, fatigue testing protocols, and supplier quality accreditation for band clamp installations on type-certified aircraft. The EPA and REACH frameworks in the United States and Europe respectively constrain surface treatment chemistries, pushing manufacturers toward chrome-free coating technologies. Stakeholders must monitor evolving airframe OEM specifications for electric and hybrid propulsion architectures, as thermal management routing complexity will redefine clamp performance thresholds and qualification pathways.
Market Dynamics
Fleet modernization mandates and airworthiness directive backlogs are compressing replacement cycles for legacy fastening hardware, forcing MRO operators to accelerate corrosion-prevention clamp swaps while OEMs redesign thermal management routing for next-generation propulsion architectures.
Growth Catalysts
- FAA Airworthiness Directives:Mandated fastener integrity inspections on aging narrow-body fleets drive scheduled replacement volumes through certified aftermarket channels.
- Electric Propulsion Thermal Complexity:Hybrid-electric engine architectures multiply fluid line routing density, expanding clamp count per airframe by 15-25% versus conventional designs.
- China MRO Cluster Expansion:Tianjin and Guangzhou maintenance hubs add heavy-check capacity, concentrating demand for corrosion-resistant stainless steel clamp inventories.
Market Restraints
- Titanium Alloy Supply Concentration:Sponge production bottlenecks in Russia and Ukraine create input volatility for weight-critical aerospace grades.
- REACH Surface Treatment Constraints:Chrome-free coating qualification timelines extend 18-24 months, freezing supplier process certifications.
- Substitution by Adhesive Bonding:Structural epoxy advances in non-critical ducting applications displace mechanical fastening on select composite airframe sections.
Strategic Opportunities
- India Defense Aviation Modernization:Indigenous fighter and transport programs under the Ministry of Defence's Make in India initiative create localized qualification pathways for specialty fastener suppliers.
- Integrated Clamp-Sensor Assemblies:Convergence of mechanical fastening with IoT pressure-monitoring electronics opens premium positioning in predictive maintenance contracts.
- EU Green Deal Sustainable Manufacturing:Incentives for reduced-emission production processes favor suppliers with in-house heat-treatment and closed-loop coating systems.
Industry Challenges
- NADCAP Welding Certification Backlogs:Precision roll-forming and orbital welding qualifications for aerospace suppliers face 12-18 month auditor availability delays.
- Legacy Fleet Documentation Gaps:Incomplete clamp installation records on pre-1990 aircraft complicate traceability for AD-mandated replacement programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Band Clamps Market |
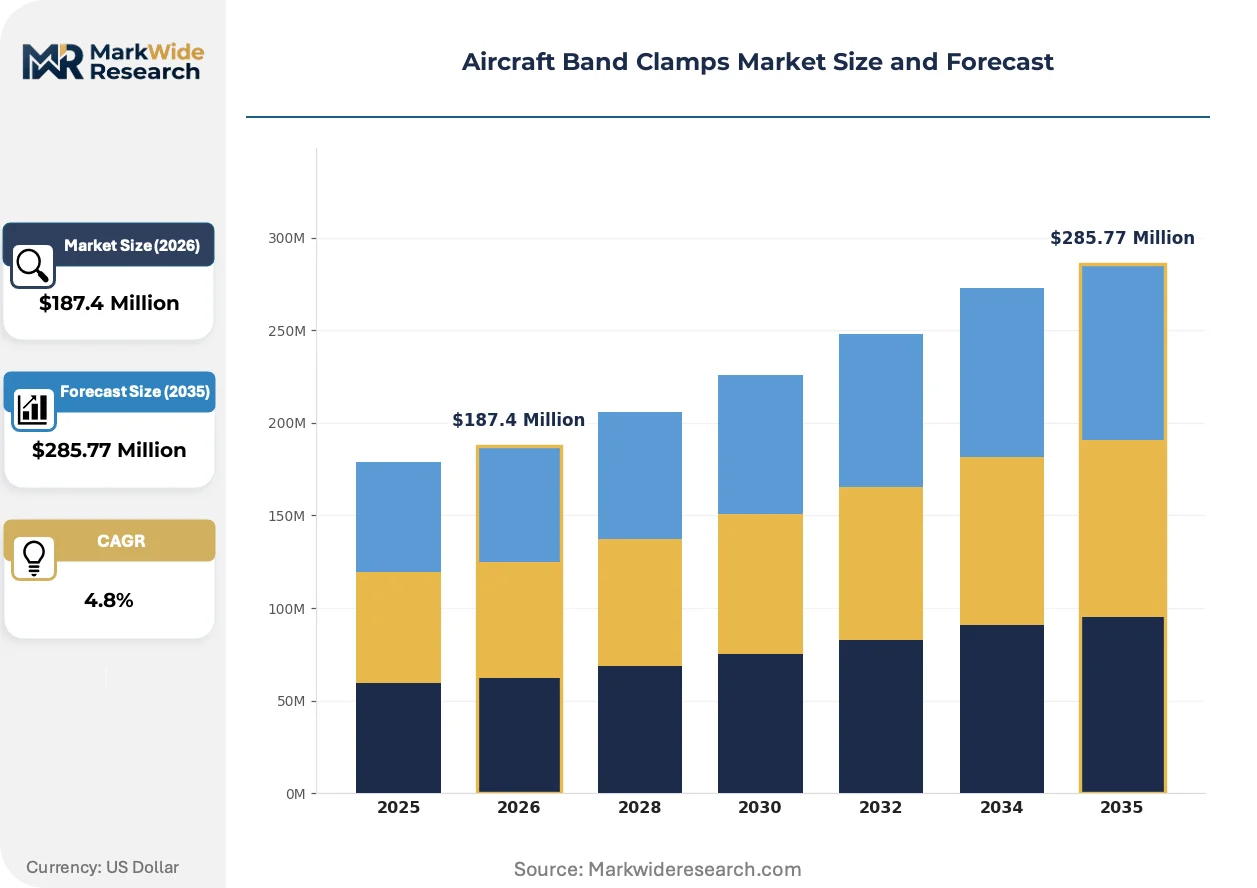
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stainless Steel, Titanium, Aluminum, Composite Application: Aerospace Manufacturing, Maintenance, Repair, Aftermarket Services End User: OEMs, Tier-1 Suppliers, Fleet Operators, Maintenance Providers Installation Type: Permanent, Removable, Adjustable, Custom |
| Companies Covered | Teconnex, J&M Products Inc., TransDigm Group Inc., Pacmet Aerospace, Clampco Products Inc., Eaton Corporation, Ho-Ho Kus Inc., UMPCO Inc., Caillau, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Band Clamps Market Emerging Trajectories
Material science advances and regulatory chemistry bans are rewriting manufacturing process requirements, while procurement centralization among mega-MROs alters how specifications flow from airframers to tier-three fastener vendors.
Additive manufacturing of titanium clamp brackets is migrating from prototyping labs to qualified production lines at select engine OEMs. GE Aviation and Rolls-Royce test laser powder bed fusion for complex bracket geometries previously machined from billet. This technology is migrating from developmental engine programs to narrow-body propulsion retrofits, compressing lead times for low-volume heritage fleet components.
REACH Annex XVII restrictions on hexavalent chromium surface treatments took full effect across EU-27 manufacturing in 2024. Chrome-free passivation and trivalent coating chemistries now dominate supplier qualification submissions to EASA-approved production facilities. German and French fastener specialists face 30-40% process revalidation costs, passing through to OEM contract renegotiations.
Consolidated buying by top-five global MRO networks now dictates specification flows previously controlled by airline engineering departments. Lufthansa Technik, ST Engineering, and AAR Corp centralize clamp procurement through multi-year framework agreements with certified specialty manufacturers. North American aftermarket channels show the strongest concentration effects, with three buyers controlling 60% of non-OEM stainless steel clamp volumes.
Aircraft Band Clamps Market Segmentation
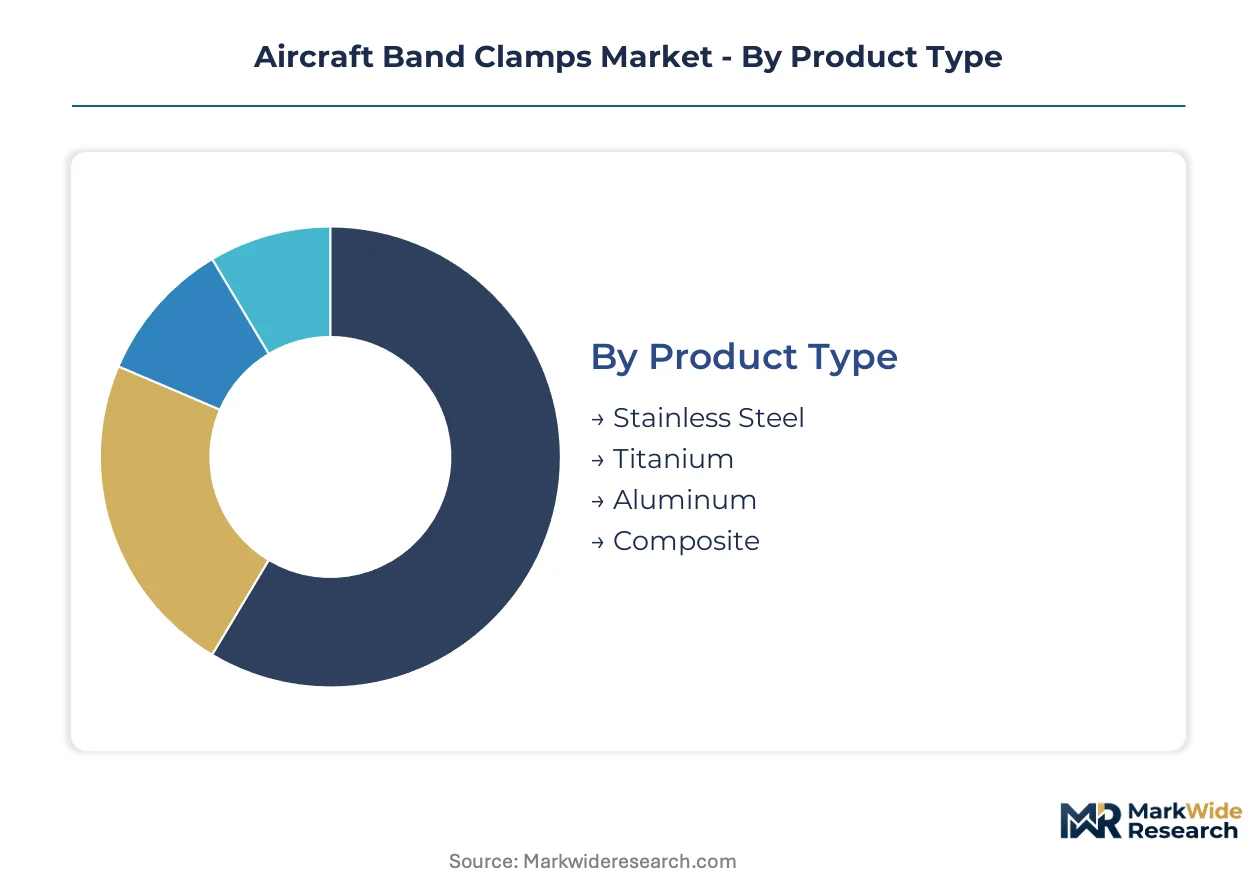
Segmentation in the aircraft band clamps market reflects divergent procurement logics between weight-critical new production and corrosion-driven aftermarket replacement. Material selection, installation permanence, and channel structure each reshape supplier qualification requirements and margin profiles across distinct customer workflows.
Product Type:
Cost tier differentiation separates commodity-grade stainless from premium titanium formulations, with aluminum and composite variants occupying emerging niches.
- Stainless Steel:Corrosion-resistant alloys meeting AMS or MIL specifications dominate current production volumes through established supply chains and cost predictability. Fleet operators in the United States and Germany source these clamps for scheduled corrosion-prevention replacements under FAA and EASA airworthiness directives.
- Titanium:Weight-critical formulations capture premium positioning on next-generation narrow-body and wide-body platforms where every kilogram reduction translates to fuel efficiency gains. Chinese airframe assembly clusters increasingly specify titanium grades for indigenous commercial programs targeting export certification.
- Aluminum:Intermediate density option gaining traction in secondary fluid line routing on regional turboprops.
- Composite:Emerging polymer-reinforced variants under qualification for non-structural harness securing on experimental electric propulsion testbeds.
Stainless steel commands the established base. The steepest expansion runs through titanium as weight reduction mandates intensify across OEM engineering specifications.
Application:
Volume concentration tilts toward aftermarket channels where regulatory replacement cycles compress order velocity versus lumpy new airframe procurement.
- Aerospace Manufacturing:New production clamp installations track airframe delivery schedules with multi-year visibility through OEM supply agreements. Boeing and Airbus final assembly lines in Washington state and Toulouse drive specification authority that cascades to tier-1 ducting suppliers.
- Maintenance:Corrosion-prevention mandates on aging narrow-body fleets generate predictable replacement demand through certified MRO channels. Lufthansa Technik and AAR Corp centralize procurement frameworks that lock in multi-year stainless steel clamp volumes.
- Repair:Unscheduled damage events require rapid-turn inventory availability at regional maintenance hubs.
- Aftermarket Services:Scheduled replacement programs under airworthiness directive backlogs create the fastest order velocity among all application channels.
Aftermarket services capture the highest growth trajectory. Manufacturing maintains the revenue concentration through long-term OEM contracting.
End User:
Customer type determines specification control, with OEMs dictating material standards that MROs later inherit for replacement compliance.
- OEMs:Airframe and engine manufacturers set baseline specifications that propagate through entire supply chains. Boeing, Airbus, and COMAC engineering departments qualify clamp suppliers through multi-year development programs before production authorization.
- Tier-1 Suppliers:Ducting and fluid system integrators absorb specification compliance costs while competing on logistics integration and inventory positioning.
- Fleet Operators:Airline engineering departments increasingly defer procurement authority to consolidated MRO networks.
- Maintenance Providers:Heavy-check facilities in Tianjin, Guangzhou, and Singapore concentrate demand for corrosion-resistant inventories.
OEMs retain specification authority. Maintenance providers are expanding their procurement influence fastest as fleet outsourcing accelerates.
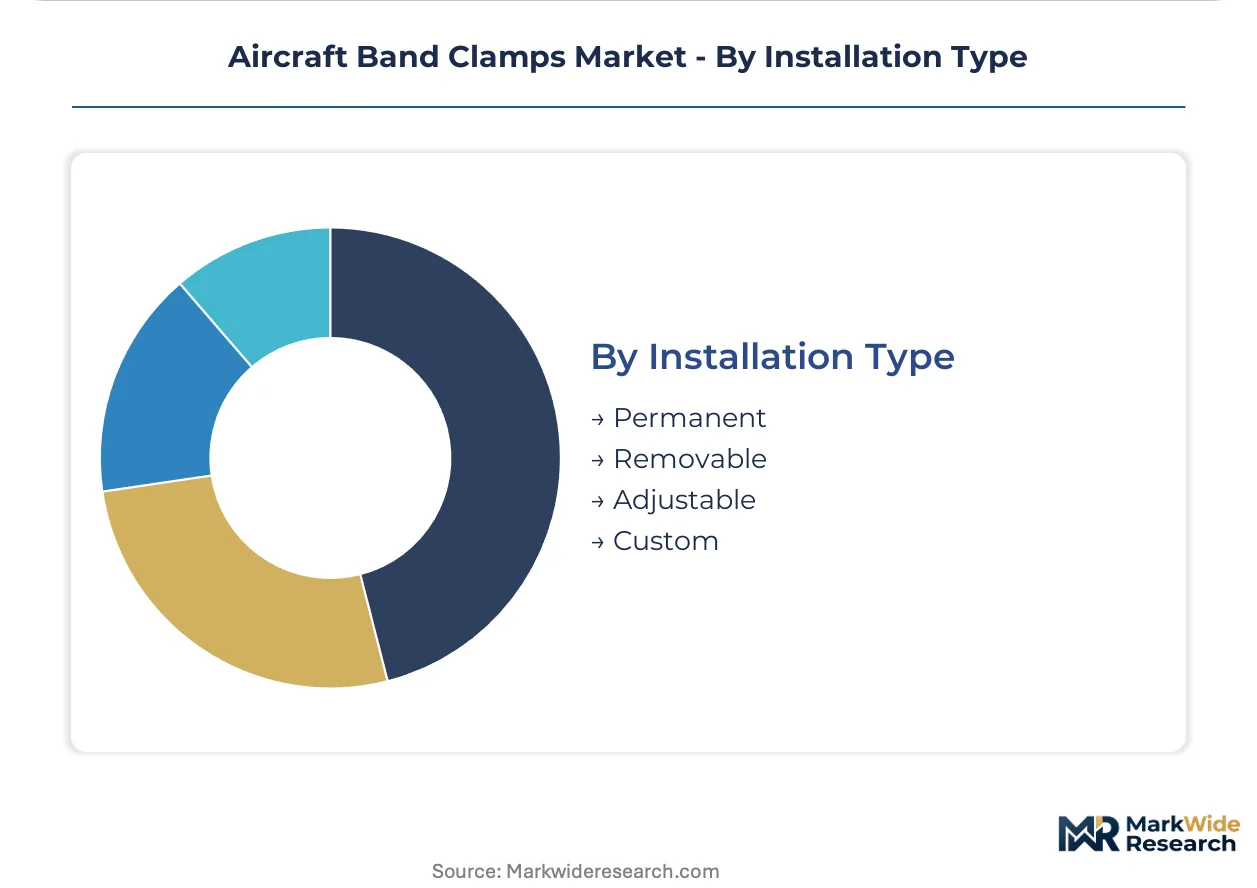
Installation Type:
Permanence requirements split between structural integrity demands and accessibility needs for inspection-intensive systems.
- Permanent:Welded or crimped installations for critical propulsion fluid lines where failure modes prohibit disassembly. FAA certification protocols mandate fatigue testing protocols that extend supplier qualification timelines.
- Removable:Quick-disconnect variants for inspection-accessible ducting on thermal management systems. These clamps dominate electric propulsion retrofit programs where routing configurations remain under iterative refinement.
- Adjustable:Tension-variable designs accommodating thermal expansion cycles in high-temperature engine zones.
- Custom:Application-specific geometries for heritage fleet components where original tooling no longer exists.
Permanent installations anchor safety-critical applications. Removable configurations are gaining share fastest as thermal management complexity multiplies access requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany where precision forming capabilities command premium contract terms, while Chinese suppliers compete on volume scale for regional turboprop programs. This asymmetry shapes procurement patterns across three continents.
United States
FAA airworthiness directives on aging narrow-body fleets drive scheduled clamp replacement through certified MRO channels. The EPA constrains surface treatment chemistries, pushing manufacturers toward chrome-free coating technologies. Boeing's final assembly lines in Washington state anchor specification authority that cascades to tier-1 ducting suppliers nationwide.
Germany
Lufthansa Technik's consolidated buying power centralizes stainless steel clamp procurement through multi-year framework agreements. REACH Annex XVII restrictions on hexavalent chromium took full effect in 2024, forcing 30-40% process revalidation costs onto fastener specialists. Hamburg and Munich maintenance clusters concentrate demand for corrosion-resistant inventories serving European fleet operators.
China
Indigenous commercial programs under COMAC target export certification, intensifying titanium grade specifications for weight-critical platforms. The Ministry of Ecology and Environment implements dual carbon goals that constrain heat-treatment energy intensity. Tianjin and Guangzhou heavy-check hubs add capacity, concentrating demand for stainless steel clamp inventories across the Asia-Pacific.
France
Airbus engineering departments in Toulouse qualify clamp suppliers through multi-year development programs before production authorization. EASA certification specifications dictate material traceability and fatigue testing protocols for type-certified installations. The Occitanie aerospace cluster hosts precision forming specialists serving both civil and defense aviation supply chains.
United Kingdom
Rolls-Royce tests laser powder bed fusion for complex titanium bracket geometries previously machined from billet. The Civil Aviation Authority enforces supplier quality accreditation standards aligned with EASA frameworks. Bristol and Derby engine manufacturing centers drive specification flows for next-generation propulsion architectures.
Aircraft Band Clamps Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream where precision forming and welding certifications create defensive moats. The vendor base organizes around three archetypes: vertically integrated aerospace conglomerates, captive fastener divisions of airframe OEMs, and independent specialty manufacturers with NADCAP welding qualifications. Consolidation pressure runs highest among mid-scale European fabricators facing REACH compliance cost burdens. Dominant competitive moves include backward integration into proprietary alloy supply and multi-year supply agreement lock-ins with mega-MRO networks.
Among UK-based precision forming specialists, Teconnex exemplifies the independent manufacturer archetype with its vertical integration across material sourcing. TransDigm Group Inc. anchors the aerospace conglomerate tier through its portfolio of proprietary component businesses. Eaton Corporation occupies the platform integrator position, extending electromechanical systems portfolios to include integrated fastening solutions for next-generation engine programs.
| Leading Market Players |
|---|
| Teconnex |
| J&M Products Inc. |
| TransDigm Group Inc. |
| Pacmet Aerospace |
| Clampco Products Inc. |
| Eaton Corporation |
| Ho-Ho Kus Inc. |
| UMPCO Inc. |
| Caillau |
| Others |
Supply Flow & Price Mechanics
Shanghai-to-Rotterdam container freight corridors transmit cost volatility from titanium sponge bottlenecks directly into European fastener contract renegotiations, amplifying price spreads between certified specialty manufacturers and commodity-grade stainless suppliers serving aftermarket channels.
Pricing Analysis
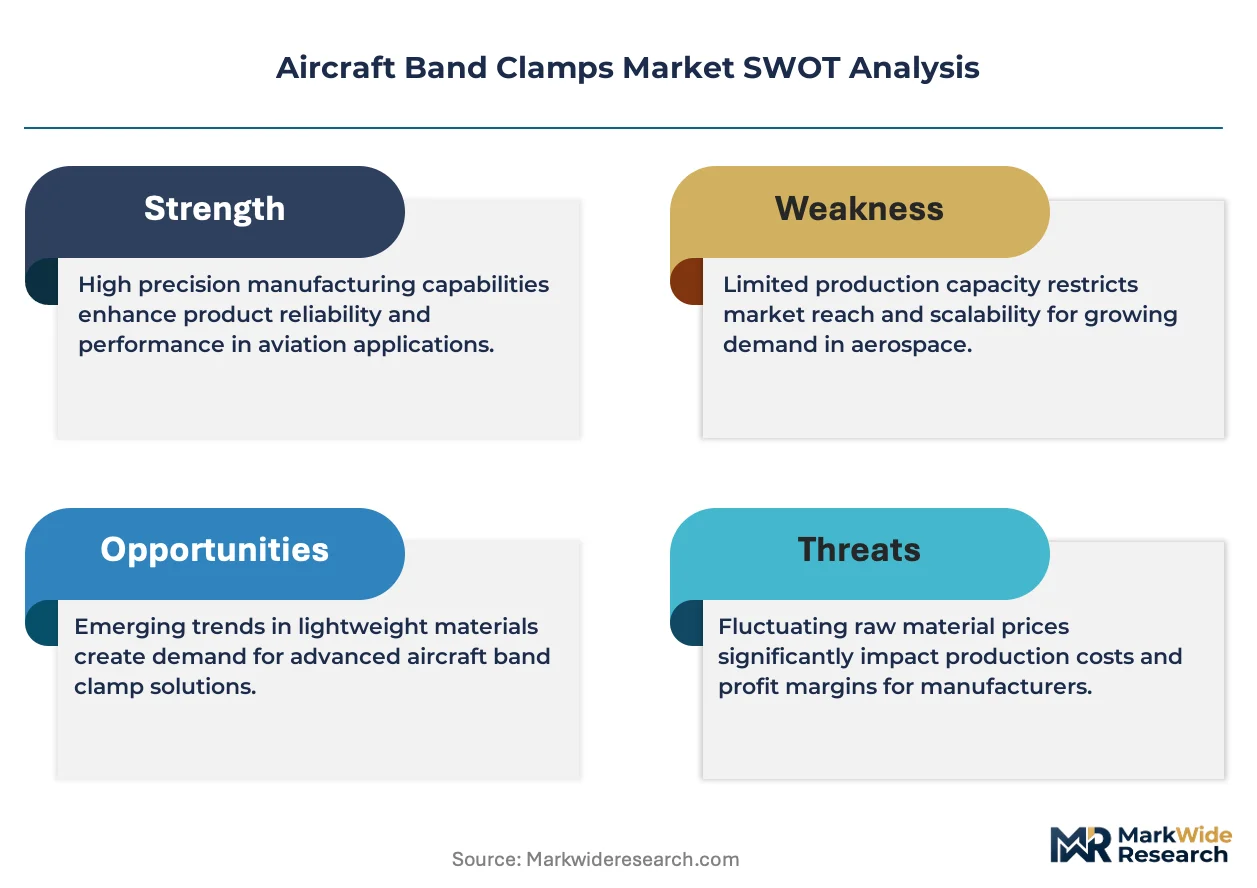
Configured-to-order pricing for titanium grades meeting AMS specifications commands 40-60% premiums over standard stainless steel catalog pricing, with certification grade and volume scale as primary differentiation drivers. Three-tier pricing structure across premium, standard, and economy levels stratifies procurement: premium tiers absorb REACH compliance costs for chrome-free surface treatments, while economy tiers face margin compression from consolidated mega-MRO buying power. Cost compression in standard stainless segments is intensifying because Lufthansa Technik and AAR Corp centralize multi-year framework agreements. Fleet operators represent the most price-sensitive buyer segment, deferring to MRO procurement consolidation, whereas OEM engineering departments demonstrate lowest sensitivity given airworthiness liability exposure.
Supply Chain Analysis
Precision roll-forming and orbital welding capacity concentrates among German, French, and UK specialty fabricators holding NADCAP heat-treatment accreditations. Raw material flows draw from Russian and Ukrainian titanium sponge sources, Japanese stainless steel mills, and domestic European alloy formulators. Single-source vulnerability runs through orbital welding equipment suppliers facing 12-18 month auditor backlogs. Distribution runs through tier-1 ducting integrators absorbing specification compliance costs while competing on logistics positioning for Boeing, Airbus, and COMAC final assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks commercial aviation fleet replacement cycles, with narrow-body re-engining programs and aging fleet corrosion mandates creating predictable demand troughs and peaks across the analysis window.
For Market Incumbents: Harden NADCAP welding certification moats through captive auditor pre-scheduling and cross-training programs, insulating against 12-18 month qualification backlogs that threaten delivery commitments. Deepen upstream control over proprietary titanium alloy formulations to offset Russian sponge supply volatility. Lock in multi-year supply agreements with ST Engineering and Lufthansa Technik before REACH process revalidation costs fully pass through to contract terms.
For New Entrants and Emerging Players: India's indigenous fighter and transport programs under the Ministry of Defence's Make in India initiative represent the most penetrable entry point for specialty fastener qualification without incumbent supply agreement encumbrances. Chrome-free coating technology gaps among mid-scale European fabricators create technology-licensing opportunities for qualified Asian suppliers. A go-to-market angle through integrated clamp-sensor assemblies for electric propulsion thermal management bypasses entrenched stainless steel commodity competition.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision forming specialists with in-house heat-treatment and closed-loop coating systems capable of absorbing REACH compliance cost shocks. Long-term viability across the 5-10 year horizon rests on qualification pathways for next-generation propulsion architectures rather than legacy fleet replacement alone. The signal to watch is COMAC export certification progress for indigenous Chinese airframes, which would validate titanium grade specification authority outside Boeing-Airbus duopoly control.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Proprietary Alloy Supply | Captive titanium sponge sourcing insulates TransDigm and Teconnex against Russian supply volatility. |
| Multi-Year Supply Agreement Lock-Ins | Lufthansa Technik's consolidated buying power forces mid-scale European fabricators into margin-compressed framework terms. |
| Chrome-Free Coating Process Revalidation | German and French specialists face 30-40% compliance costs that reshape competitive positioning across EU-27 manufacturing. |
| Integrated Clamp-Sensor Assembly Development | Eaton Corporation's electromechanical convergence opens predictive maintenance contract premiums in next-generation engine programs. |
| NADCAP Welding Certification Pre-Scheduling | Auditor availability bottlenecks create defensive moats for incumbents with advance qualification pipelines. |
Methodological Framework
Operator-level perspectives from MRO procurement directors, OEM fastener qualification engineers, tier-1 ducting integrators, and NADCAP facility auditors anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through FAA airworthiness directive databases, EASA certification specification filings, SEC 10-K disclosures from aerospace conglomerates, and customs trade data for titanium sponge and stainless steel mill product flows. Bottom-up segment sizing triangulated against top-down fleet projection models from airframe delivery schedules and MRO capacity expansion announcements.
Scenario-bracketing around fleet modernization pace, REACH enforcement stringency, and electric propulsion adoption curves bounded the projection range across the modeling period. Segmentation dimensions modeled include material grade tier, application channel, installation permanence type, and regional regulatory cluster. CAGRs derived from compound growth trajectory analysis of replacement cycle compression and new airframe content expansion. Industry-specific forecast inputs incorporated corrosion-prevention mandate backlogs and thermal management routing density multipliers for hybrid-electric architectures.
Practitioners should monitor titanium sponge supply diversification progress, COMAC export certification milestones, and chrome-free coating qualification completion rates for early signals of forecast revision triggers. Cross-checking against IATA fleet forecast updates and OEM delivery guidance revisions is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Global Aircraft Tugs Market
Aircraft
Drone Turbojet Engine Market
Aircraft
Global Commercial Aircraft Seat Actuation Market
Aircraft
Aeronautic Propeller Market
Aircraft
GCC General Aviation Market
Aircraft
Aircraft Inspection Covers Market
Aircraft
Aircraft Windshield Wiper and Washer System Market
Aircraft
Aircraft Ailerons Market
Aircraft
Middle-East and Africa Freighter Aircraft Market
Aircraft
India Aviation Market
Aircraft
Asia-Pacific General Aviation Market
Aircraft
Commercial Helicopter Market
Aircraft
Water Bomber Market
Aircraft
Aircraft Galley Systems Market
Aircraft
Global Commercial Aircraft Windows and Windshields Market
Aircraft
Aircraft Cargo Winches Market