
 Asia-Pacific Military Helicopters Market | 2026-2036
Asia-Pacific Military Helicopters Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Military Helicopters Market Outlook
AS9100D certification is unwinding supplier eligibility across the Asia-Pacific military helicopter supply base, forcing tier-two aerostructures firms to rebuild quality management systems or exit. Airbus Helicopters leverages its Tiger and H225M footprints to sustain naval attack and utility contracts with Australia and South Korea. Hindustan Aeronautics Limited anchors India's indigenous rotorcraft pipeline through the Prachand light combat helicopter and ongoing Dhruv derivatives. Lockheed Martin Corporation, via its Sikorsky lineage, competes on heavy-lift requirements with the CH-53K and Seahawk variants pitched to Japan and Australia.
Asia-Pacific military helicopters are rotary-wing aircraft designed for armed forces operations, typically featuring tandem or side-by-side crew seating, armor-protected airframes, and turboshaft powerplants rated between 1,500 and 3,000 shaft horsepower for hot-and-high performance. Their primary purpose spans tactical assault, vertical replenishment, anti-submarine warfare, and personnel recovery in contested littoral and mountain environments. Attack helicopters command premium engineering margins due to integrated targeting sensors and weapons management complexity, while transport helicopters absorb the largest unit volumes from army aviation modernization cycles across the region. Reconnaissance platforms incorporating synthetic aperture radar and signals intelligence packages represent the fastest-expanding technology insertion point.
Australia's Defence Aviation Safety Authority, Japan's Ministry of Defense acquisition standards, and India's Defence Research and Development Organisation collectively shape airworthiness, offset, and technology-transfer requirements for foreign OEMs. Australia's sovereign shipbuilding and aviation sustainment mandates now extend to rotorcraft deep maintenance, compelling primes to localize depot-level repair capacity. Japan's relaxed defense equipment export guidelines are altering subcontractor access rules for co-developed platforms. Stakeholders must monitor how India's PLI scheme for aerospace components interacts with HAL's monopoly on domestic final assembly, as this tension will determine whether private sector participation reshapes supplier economics or reinforces incumbent control.
Market Dynamics
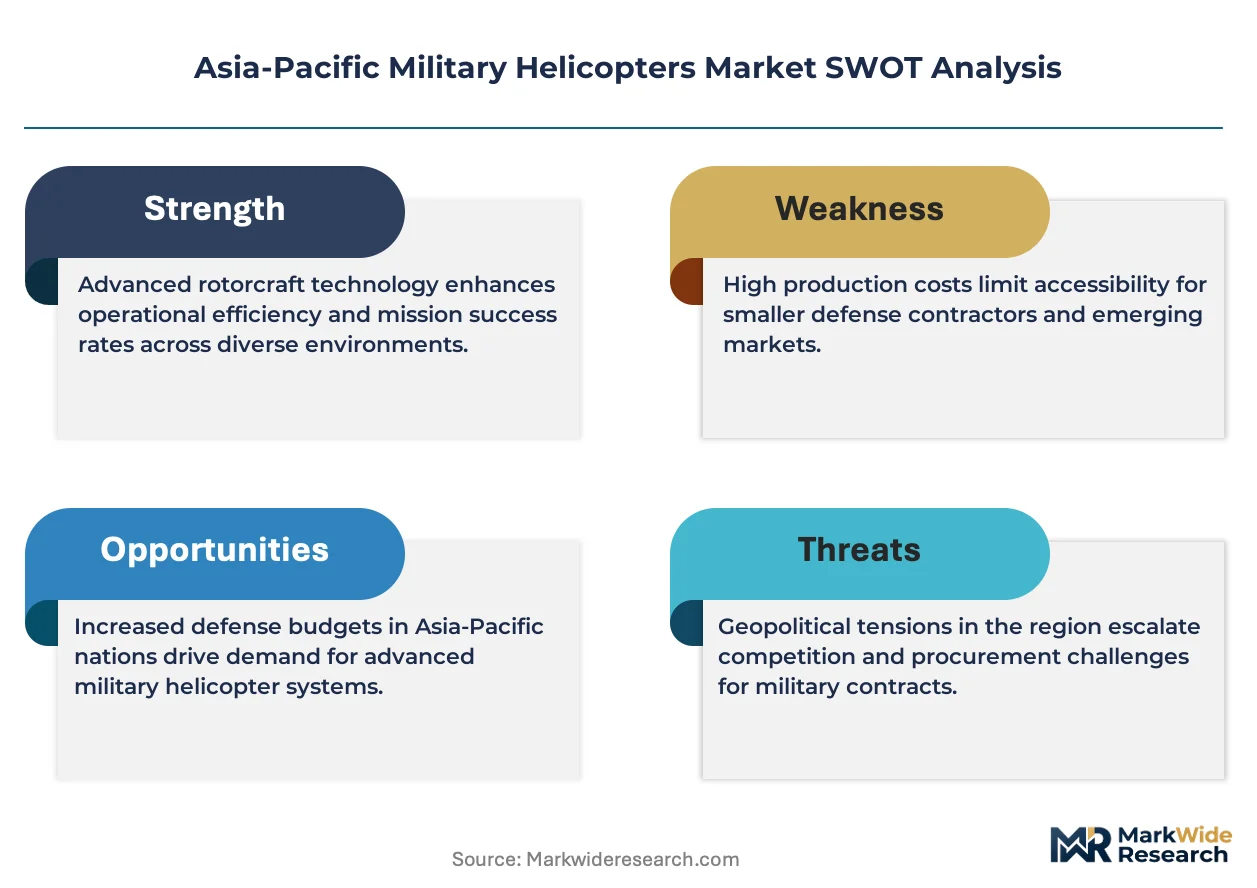
AS9100D quality certification mandates are forcing tier-two aerostructures suppliers across Asia-Pacific to rebuild management systems or exit the military helicopter supply base entirely.
Growth Catalysts
- Naval aviation procurement:Southeast Asian fleets are accelerating platform renewal for anti-submarine warfare and vertical replenishment missions.
- India's Defence Acquisition Procedure reforms:Streamlined indigenization mandates are pulling foreign OEMs into co-development partnerships with domestic rotorcraft suppliers.
- Sovereign industrial base expansion:Australia's Defence Aviation Safety Authority is mandating localized depot-level repair capacity for amphibious and littoral helicopter capabilities.
Market Restraints
- Turboshaft engine supply concentration:Hot-and-high performance powerplants rated above 2,000 shaft horsepower rely on a concentrated supplier base in North America and Europe.
- AS9100D compliance costs:Small-tier aerostructures firms face prohibitive quality management system rebuild expenses that compress margins below sustainable thresholds.
- Technology transfer restrictions:Japan's Ministry of Defense acquisition standards impose stringent offset requirements that slow foreign platform entry despite relaxed export guidelines.
Strategic Opportunities
- Reconnaissance platform expansion:Synthetic aperture radar and signals intelligence packages represent underpenetrated technology insertion points across regional attack helicopter fleets.
- India's PLI scheme for aerospace components:Production-linked incentives could reshape supplier economics if private sector participation penetrates HAL's domestic final assembly monopoly.
- Heavy-lift capability gaps:Australia's amphibious expansion creates white space for integrated logistics support and maintenance contracts tied to new heavy-lift acquisitions.
Industry Challenges
- AS9100D certification timeline compression:Tier-two suppliers face 18-24 month quality system rebuild cycles that conflict with program delivery schedules.
- Integrated targeting sensor integration:Attack helicopter programs require complex weapons management software validation that extends development timelines.
- Legacy fleet interoperability:New platforms must integrate with existing command-and-control architectures across heterogeneous national inventories.
Report Scope
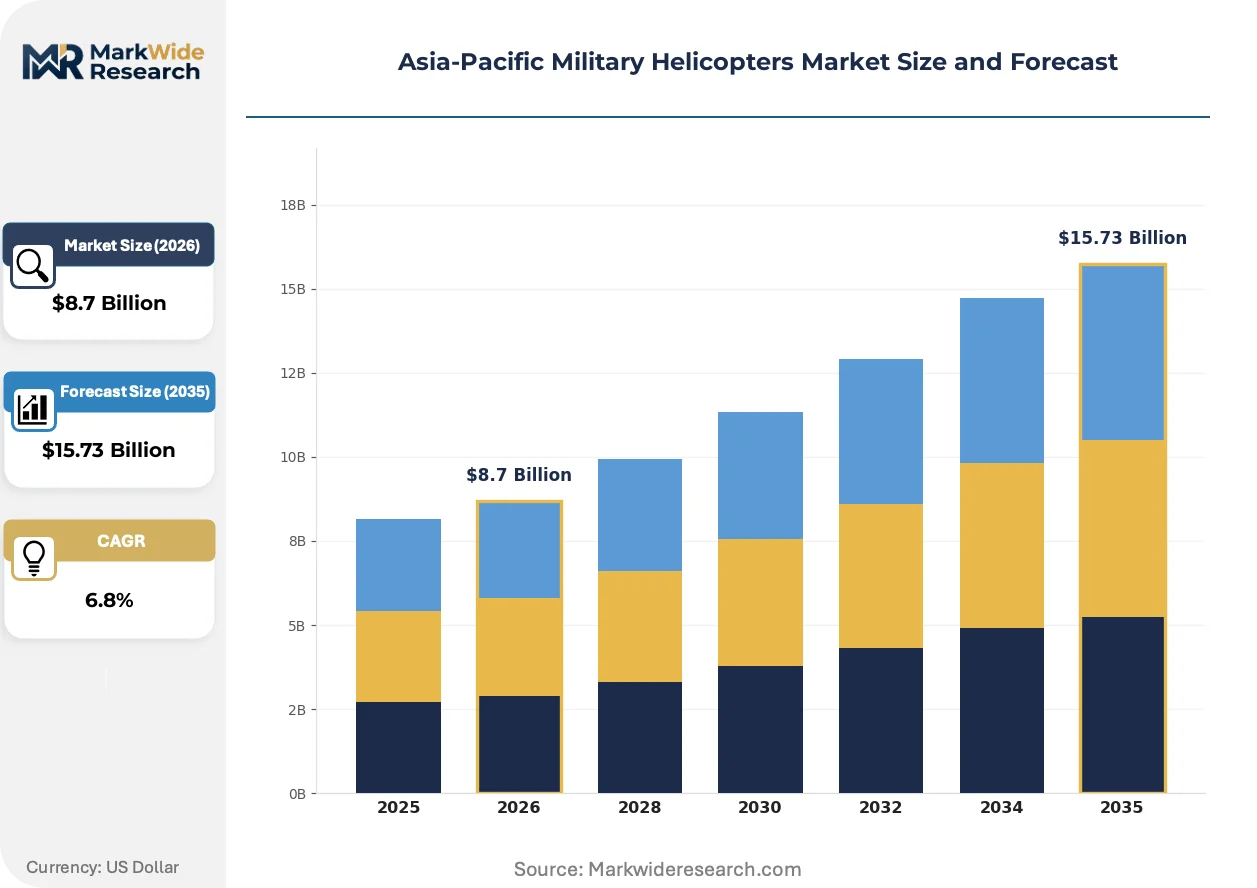
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Military Helicopters Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Attack Helicopters, Transport Helicopters, Reconnaissance Helicopters, Utility Helicopters Technology: Fly-by-Wire, Avionics Systems, Rotorcraft Technology, Navigation Systems Application: Military Operations, Search and Rescue, Medical Evacuation, Surveillance End User: Defense Forces, Government Agencies, Private Contractors, International Organizations |
| Companies Covered | Airbus Helicopters, Hindustan Aeronautics Limited, Lockheed Martin Corporation, Aviation Industry Corporation of China, Turkish Aerospace Industries, The Boeing Company, Leonardo S.p.A., Kawasaki Heavy Industries Ltd., Textron Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Military Helicopters Market Strategic Shifts
Digital engineering and modular mission systems are compressing development cycles for military rotorcraft while reshaping how regional defense forces specify platform requirements.
Fly-by-wire flight control architectures are decomposing traditional mechanical linkages in next-generation combat helicopters. The Indian Army and Republic of Korea Army are specifying digital flight control systems for new attack helicopter procurements. This shift is decomposing incumbent supplier relationships as avionics specialists capture engineering value previously held by mechanical systems houses.
Australia's Defence Aviation Safety Authority now mandates sovereign depot-level maintenance capacity for all new naval helicopter acquisitions. Foreign OEMs must establish local deep-repair facilities or partner with domestic aviation sustainment providers. Heavy-lift and utility segments face the steepest compliance burden as these platforms require the most extensive tooling and test equipment localization.
Outcome-based availability contracts are displacing traditional spares-and-repair purchasing across Asia-Pacific military helicopter fleets. The Australian Defence Force and Japan Maritime Self-Defense Force now specify fleet availability metrics rather than component quantities. South Korea's Defense Acquisition Program Administration is piloting similar performance-based logistics frameworks for its Marine Corps helicopter units.
Asia-Pacific Military Helicopters Market Segmentation
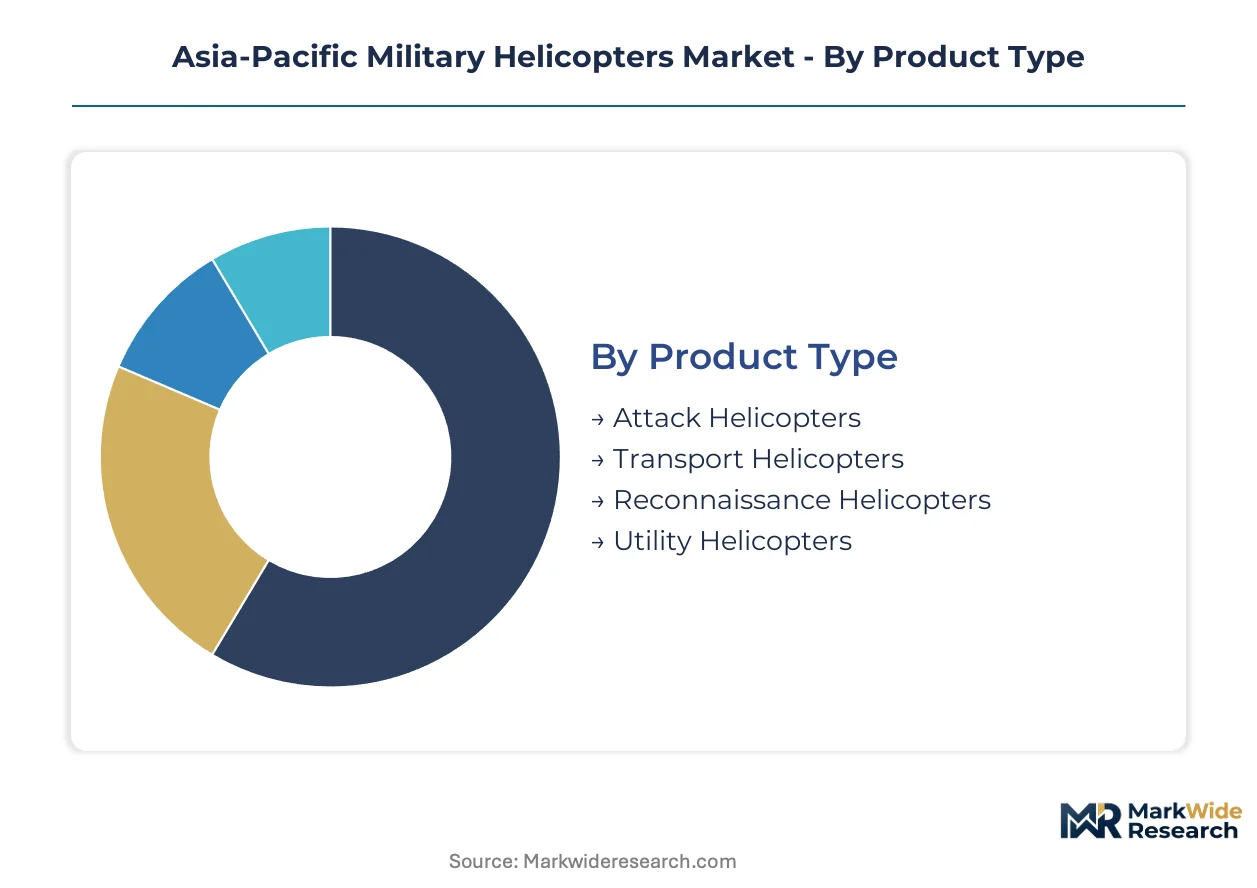
Segmentation of the Asia-Pacific military helicopter market reveals how procurement priorities diverge across national defense architectures. Regulatory frameworks in Australia, India, and Japan shape distinct specification requirements that fragment platform demand across product categories and technology tiers.
Product Type:
Australia's Defence Aviation Safety Authority mandates sovereign depot-level maintenance capacity that varies sharply by helicopter mission profile, creating regulatory differentiation across platform categories.
- Attack Helicopters:Tandem-crew configurations with integrated targeting sensors and weapons management systems rated for hot-and-high performance. India's Defence Acquisition Procedure reforms are accelerating indigenization partnerships for light combat helicopter production through Hindustan Aeronautics Limited.
- Transport Helicopters:Side-by-side crew seating with armor-protected airframes and turboshaft powerplants between 1,500 and 3,000 shaft horsepower. Australia's amphibious expansion is concentrating demand for heavy-lift capabilities with localized deep-repair infrastructure.
- Reconnaissance Helicopters:Platforms incorporating synthetic aperture radar and signals intelligence packages for contested littoral environments.
- Utility Helicopters:Multi-role configurations spanning vertical replenishment and personnel recovery missions across Southeast Asian naval fleets.
Established volume favors Transport Helicopters; emerging adoption favors Reconnaissance Helicopters.
Technology:
Cost tier differentiation separates legacy mechanical architectures from digital flight control premiums demanded by next-generation procurements.
- Fly-by-Wire:Digital flight control architectures decomposing traditional mechanical linkages. The Indian Army and Republic of Korea Army specify these systems for new attack helicopter procurements, displacing incumbent mechanical systems suppliers.
- Avionics Systems:Modular mission electronics compressing development cycles while expanding software validation requirements.
- Rotorcraft Technology:Main and tail rotor configurations optimized for maritime corrosion resistance and mountain altitude performance.
- Navigation Systems:GPS-denied positioning and encrypted datalinks for contested electromagnetic environments.
Defense forces prioritize Fly-by-Wire for new procurements; sustainment budgets sustain Rotorcraft Technology refresh cycles.
Application:
Customer type concentration varies by mission criticality, with sovereign defense forces dominating lethal applications while international organizations fund humanitarian configurations.
- Military Operations:Tactical assault and anti-submarine warfare missions requiring hardened airframes and integrated electronic warfare suites. Japan's Ministry of Defense acquisition standards impose stringent technology transfer restrictions despite relaxed export guidelines.
- Search and Rescue:All-weather hoist configurations with de-iced rotor systems for maritime and alpine environments.
- Medical Evacuation:Cabin configurations optimized for casualty transport with life support equipment integration.
- Surveillance:Persistent observation platforms with electro-optical and infrared sensor payloads.
Procurement concentration favors Military Operations; capability gaps favor Search and Rescue expansion.
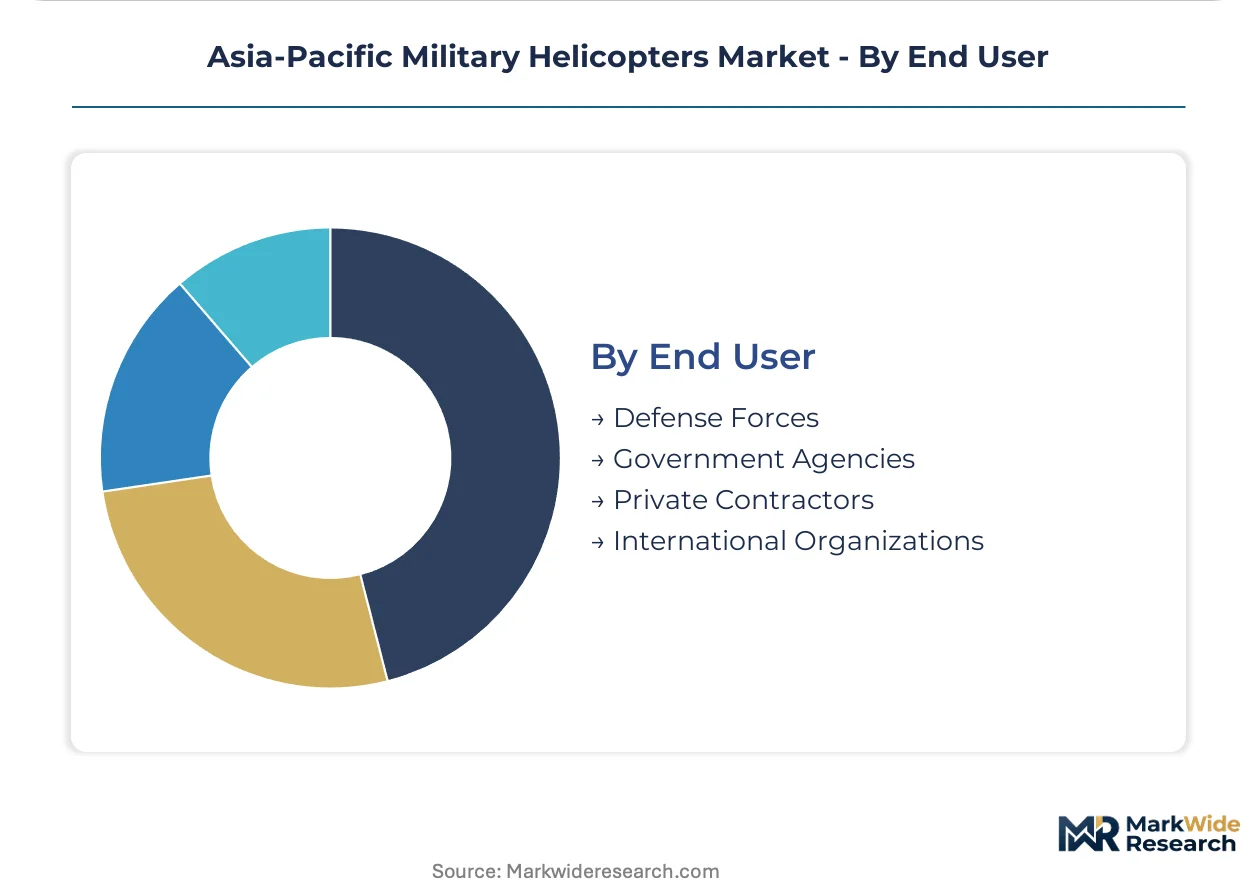
End User:
Supply concentration aligns with sovereign industrial base mandates, restricting foreign OEM access without domestic partnership structures.
- Defense Forces:Army, navy, and marine aviation units with fleet-wide standardization requirements. Australia's Defence Aviation Safety Authority mandates localized depot-level repair capacity for all new acquisitions.
- Government Agencies:Coast guard and paramilitary operators with dual-use platform specifications.
- Private Contractors:Logistics and training providers operating under government contract frameworks.
- International Organizations:Peacekeeping and humanitarian missions with pooled procurement mechanisms.
Contract volume concentrates with Defense Forces; emerging demand patterns favor Government Agencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Defence Acquisition Procedure reforms are accelerating indigenization mandates for rotorcraft suppliers. Australia's sovereign defense industrial base expansion is reshaping depot-level maintenance requirements for naval aviation.
India
Hindustan Aeronautics Limited anchors the indigenous rotorcraft pipeline through the Prachand light combat helicopter and Dhruv derivatives. The Defence Research and Development Organisation shapes airworthiness and technology-transfer requirements for foreign OEMs. Bengaluru's aerospace cluster concentrates final assembly and systems integration activity for domestic attack helicopter programs.
Australia
The Defence Aviation Safety Authority mandates localized depot-level repair capacity for all new amphibious and littoral helicopter acquisitions. Sovereign shipbuilding and aviation sustainment mandates now extend to rotorcraft deep maintenance requirements. Brisbane and Adelaide host the primary aviation sustainment infrastructure for naval helicopter fleet support.
Japan
The Ministry of Defense acquisition standards impose stringent offset requirements that slow foreign platform entry despite relaxed defense equipment export guidelines. Kawasaki Heavy Industries maintains domestic production capabilities for military rotorcraft. The Nagoya industrial corridor concentrates aerospace manufacturing and systems engineering for maritime patrol helicopter variants.
South Korea
The Defense Acquisition Program Administration pilots performance-based logistics frameworks for Marine Corps helicopter units. The Republic of Korea Army specifies digital flight control systems for new attack helicopter procurements. Sacheon and Seoul anchor the domestic aerospace industrial base for rotorcraft final assembly and avionics integration.
China
The Aviation Industry Corporation of China consolidates state-owned rotorcraft production across military and civil segments. MIIT standards govern domestic certification for turboshaft-powered platforms. Tianjin and Nanchang host the primary helicopter manufacturing complexes for attack and utility variants.
Asia-Pacific Military Helicopters Market Competitive Environment
Listed leaders compete with private specialists across sovereign industrial base mandates and technology-transfer frameworks. The market structure fragments across three tiers: state-owned enterprises with domestic monopoly positions, multinational primes with established regional footprints, and emerging national champions seeking export authorization. Two strategic archetypes dominate: integrated aerospace conglomerates with rotorcraft divisions, and helicopter specialists with platform-specific engineering depth. Competitive moves concentrate on co-development partnerships for indigenization compliance and localized maintenance facility establishment.
Within the state-owned tier, Hindustan Aeronautics Limited and Aviation Industry Corporation of China exemplify nationally anchored production structures. Airbus Helicopters occupies a position as the established European prime with Tiger and H225M footprints across Australia and South Korea. Lockheed Martin Corporation, through its Sikorsky lineage, represents the American heavy-lift specialist competing on integrated logistics support contracts.
| Leading Market Players |
|---|
| Airbus Helicopters |
| Hindustan Aeronautics Limited |
| Lockheed Martin Corporation |
| Aviation Industry Corporation of China |
| Turkish Aerospace Industries |
| The Boeing Company |
| Leonardo S.p.A. |
| Kawasaki Heavy Industries Ltd. |
| Textron Inc. |
| Others |
Value Chain & Pricing Dynamics
AS9100D certification regimes gate both supplier qualification and price differentiation across the Asia-Pacific military helicopter supply base, compressing margins for tier-two aerostructures firms while rewarding primes with established quality management systems. The certification burden creates a structural bifurcation where AS9100D-compliant suppliers command premium positioning for naval attack and heavy-lift platforms, while non-compliant firms face exclusion or forced exit.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with AS9100D-compliant suppliers capturing 40-60% engineering margin premiums on attack helicopter sensor integration contracts versus commodity aerostructures. Price differentiation also tracks fleet availability guarantees, with outcome-based contracts bundling spares, repair, and logistics into per-flight-hour rates that shift risk to OEMs. Cost compression in tier-two aerostructures is intensifying because 18-24 month quality system rebuild cycles compress sustainable margins below exit thresholds. Government defense forces exhibit lowest price sensitivity due to sovereign capability mandates, while private contractors face acute pressure on bid competitiveness.
Supply Chain Analysis
Inbound logistics costs through Singapore and Busan port corridors concentrate turboshaft engine and precision avionics flows into Australia, Japan, and South Korea assembly facilities. Hot-and-high performance powerplants rated above 2,000 shaft horsepower draw from concentrated North American and European supplier bases, while composite rotor blade materials and integrated targeting sensors rest on specialized Japanese and South Korean component manufacturers. Single-source vulnerability in engine supply creates fleet readiness exposure for Southeast Asian naval aviation procurement cycles. Distribution runs through sovereign depot-level maintenance networks mandated by Australia's Defence Aviation Safety Authority and Japan's Ministry of Defense acquisition standards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific military helicopter market operates as a defensive-moat structure where regulatory entrenchment through sovereign industrial base mandates creates durable incumbent advantages. Switching costs for defense forces escalate through fleet standardization requirements and localized maintenance infrastructure lock-in.
For Market Incumbents: Secure AS9100D certification moats by accelerating tier-two supplier consolidation before India's PLI scheme for aerospace components reshapes private sector access. Deepen sovereign depot partnerships in Brisbane and Adelaide to preempt Australia's amphibious expansion requirements. Counter emerging entrant pressure from Turkish Aerospace Industries by embedding integrated logistics support contracts with performance-based availability metrics that extend contract tenures. For New Entrants and Emerging Players: Differentiate on synthetic aperture radar and signals intelligence package integration for reconnaissance helicopter white space in South Korea and Southeast Asian naval fleets. Target India's private sector rotorcraft component manufacturing under PLI incentives as the most penetrable supply tier, given HAL's final assembly monopoly creates supplier-side entry points. Pursue co-development partnerships with Hindustan Aeronautics Limited for Dhruv derivative programs to bypass foreign OEM offset requirements. For Investors and Strategic Acquirers: Carve-out targets emerge from European aerostructures suppliers facing AS9100D compliance cost pressure and seeking Asia-Pacific defense revenue diversification. Long-term viability centers on platforms with embedded sovereign maintenance mandates that generate recurring service revenue streams. Monitor India's Defence Acquisition Procedure reform implementation velocity as the critical inflection signal for private sector participation scaling versus HAL incumbent reinforcement.| Strategic Initiative | Industry Significance |
|---|---|
| Co-Development Partnership | Foreign OEMs align with HAL to satisfy India's indigenization mandates for attack helicopter production. |
| Sovereign Depot Establishment | Primes localize deep-repair capacity in Brisbane to comply with Australia's Defence Aviation Safety Authority requirements. |
| Performance-Based Logistics Contract | Outcome-based availability frameworks displace spares purchasing across Japan Maritime Self-Defense Force fleets. |
| AS9100D Certification Investment | Tier-two aerostructures firms rebuild quality systems to retain eligibility for Southeast Asian naval procurement. |
| Reconnaissance Platform Integration | Specialist avionics suppliers capture value from synthetic aperture radar insertion in Korean Army attack helicopter programs. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with defense procurement officers, rotorcraft program managers, aviation sustainment directors, and tier-two aerostructures suppliers; and secondary validation through defense ministry acquisition disclosures, customs import records for turboshaft engines, AS9100D certification registries, and fleet availability contract announcements. Bottom-up triangulation across platform-level procurement volumes and top-down reconciliation against national defense budget allocations anchored value estimates.
Across the analysis window, the forecasting framework modeled demand trajectories by product type, technology tier, application mission profile, and end-user category, with additional segmentation by sovereign industrial base maturity. CAGRs derived from regression analysis of historical procurement cycles, fleet replacement timelines, and regulatory reform implementation schedules. Specific inputs included India's Defence Acquisition Procedure reform velocity, Australia's sovereign shipbuilding mandate expansion, and Japan's defense equipment export guideline relaxation.
The analysis sits within stated boundaries; outcomes outside sustained defense budget growth trajectories, stable technology transfer frameworks, and AS9100D certification regime continuity would require recalibration. Forecasts reflect assumptions regarding procurement cycle predictability and offset negotiation outcomes. Geopolitical disruption to engine supply corridors or abrupt regulatory reversal in India or Japan would necessitate model revision. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Airship Market
Aircraft
Aircraft Lavatory System Market
Aircraft
Electric VTOL (Evtol) Aircraft Market
Aircraft
Commercial Aircraft in-Seat Power System Market
Aircraft
Global Aircraft Design and Engineering Market
Aircraft
Commercial Aircraft Aerostructures Market
Aircraft
Europe Business Jet Market
Aircraft
Enhanced Flight Vision Systems ( EFVS) Market
Aircraft
North America Aircraft Band Clamps Market
Aircraft
Helicopter Lighting Market
Aircraft
America Freighter Aircraft Market
Aircraft
Anti Rolling Gyro (ARG) Market
Aircraft
Military Multirole Aircraft Market
Aircraft
Aircraft Pushback Tugs Market
Aircraft
Asia-Pacific Aircraft Manufacturing Market
Aircraft
Aircraft Inspection Covers Market