
 Global Commercial Aircraft Seat Actuation Market | 2026-2036
Global Commercial Aircraft Seat Actuation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Commercial Aircraft Seat Actuation Market Foresight
The EU's CSRD disclosure mandates is pivoting how seat actuator suppliers document supply chain emissions and material provenance. Crane Aerospace & Electronics leverages its integrated electromechanical portfolio to anchor long-term contracts with tier-one seat integrators. Moog Inc. dominates precision motion control for premium class seating configurations where multi-axis articulation commands higher unit values.
Commercial aircraft seat actuation encompasses electromechanical, hydraulic, and pneumatic drive systems that translate control inputs into precise seat positioning, typically operating at voltages between 28 VDC and 115 VAC with load ratings exceeding 200 lb per axis to satisfy dynamic crash load requirements. Electric actuators lead the product type landscape as airlines prioritize weight reduction and simplified maintenance intervals over legacy hydraulic alternatives. Premium class seating applications capture disproportionate margin pools because lie-flat mechanisms require synchronized multi-motor architectures with redundant position feedback.
FAA Part 25 crashworthiness standards, EASA CS-25 certification protocols, and China's CAAC CCAR-25 framework collectively dictate structural load paths, flammability thresholds, and electromagnetic compatibility benchmarks that actuator designs must satisfy before airworthiness approval. The EU's REACH chemical restrictions and evolving F-Gas Regulation further constrain seal materials and lubricant formulations used in pneumatic and hydraulic variants. Stakeholders must monitor how next-generation sustainable aviation fuel compatibility requirements and emerging thermal runaway protocols for lithium-powered electric actuators reshape qualification timelines and supplier qualification costs.
Market Dynamics
Airlines retrofitting wide-body fleets with lie-flat premium seating are expanding actuator procurement volumes, while FAA airworthiness directives on seat crashworthiness force hardware redesigns that compress supplier qualification timelines.
Growth Catalysts
- Wide-body fleet retrofit cycles:Legacy aircraft undergoing cabin reconfigurations require complete actuator replacement, generating sustained aftermarket demand from North American and European flag carriers.
- CSRD disclosure mandates:The EU's corporate sustainability reporting rules pivot how seat actuator suppliers document supply chain emissions and material provenance, creating competitive differentiation for compliant manufacturers.
- Multi-axis electromechanical architectures:Lie-flat premium seating configurations demand synchronized motor systems with redundant position feedback, elevating unit values and technical entry barriers.
Market Restraints
- Specialized seal material costs:REACH chemical restrictions and the EU F-Gas Regulation constrain elastomer and lubricant formulations, forcing pneumatic and hydraulic variant redesigns that extend development cycles.
- Precision motion control supplier concentration:A limited cohort of electromechanical specialists controls multi-axis articulation technology, creating single-source vulnerability for tier-one seat integrators.
- Electromagnetic compatibility thresholds:FAA Part 25 and EASA CS-25 certification protocols impose stringent EMC benchmarks that disqualify commodity actuator designs from airworthiness approval.
Strategic Opportunities
- China's MRO network expansion:The country's growing commercial aviation maintenance infrastructure creates localized actuator refurbishment and replacement demand independent of Western supply chains.
- CAAC CCAR-25 framework alignment:China's airworthiness certification convergence with FAA and EASA standards enables dual-qualified suppliers to capture retrofit contracts from Chinese-owned wide-body operators.
- Lithium-powered electric actuator protocols:Emerging thermal runaway standards for battery-integrated seat mechanisms create first-mover advantage for suppliers with certified fail-safe architectures.
Industry Challenges
- Multi-certification talent scarcity:Engineers capable of navigating simultaneous FAA, EASA, and CAAC approval pathways command premium compensation, constraining supplier scaling capacity.
- Crash load test facility access:Dynamic load validation exceeding 200 lb per axis requires specialized aerospace testing infrastructure with limited global availability, creating qualification bottlenecks.
- Legacy hydraulic system integration:Mixed-fleet operators demand actuator compatibility with existing 28 VDC and 115 VAC aircraft power architectures, complicating pure-electric product roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Commercial Aircraft Seat Actuation Market |
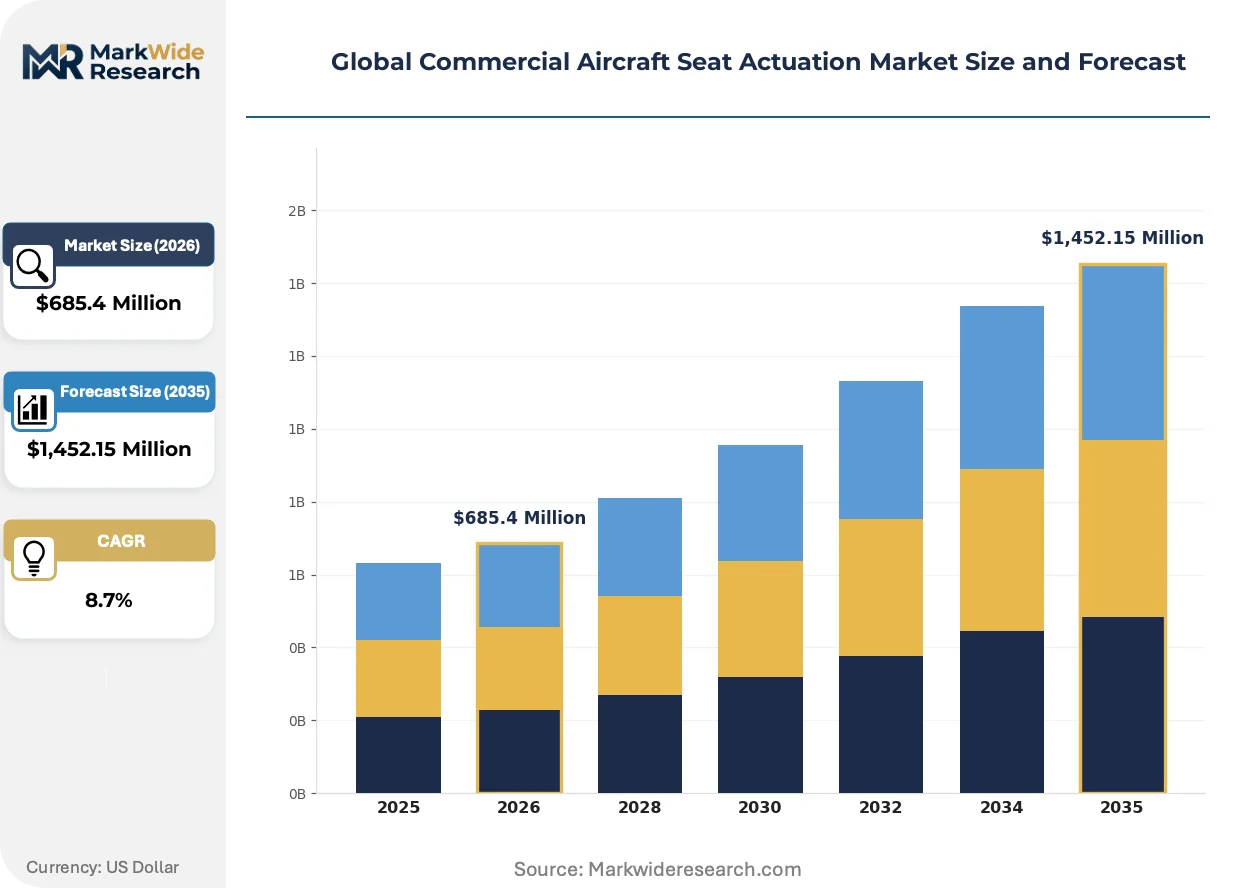
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Actuators, Hydraulic Actuators, Pneumatic Actuators, Mechanical Actuators Application: Passenger Seating, Crew Seating, Cargo Seating, Premium Class Seating End User: Airlines, Aircraft Manufacturers, Maintenance Providers, Leasing Companies Deployment: New Aircraft Installation, Retrofit Upgrades, Maintenance Replacement, Custom Modifications |
| Companies Covered | Bühler Motor GmbH, Crane Aerospace & Electronics, Moog Inc., Collins Aerospace, Astronics Corporation, Safran SA, ITT Inc., Zodiac Aerospace, Nook Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Commercial Aircraft Seat Actuation Market Shifts & Advancements
Electromechanical architectures are displacing legacy hydraulic and pneumatic systems across all aircraft classes, compressing maintenance intervals while introducing new power management and thermal control complexities.
Brushless DC motor systems with integrated motor controllers are unifying power conversion and position sensing into single-package actuators. Premium class seat integrators are specifying these units for new-build wide-body programs. This unification eliminates separate controller rack space, reducing wiring weight and simplifying fault isolation procedures.
REACH chemical restrictions and the EU F-Gas Regulation are forcing reformulation of hydraulic seal elastomers and pneumatic lubricant bases. Manufacturers serving European-registered aircraft must validate alternative compounds under accelerated aging protocols. Pneumatic actuator suppliers with German and French manufacturing footprints face the most compressed reformulation timelines.
Airlines are consolidating seat actuator procurement under airframe OEM direct-buy agreements rather than tier-one seat integrator pass-through contracts. This disintermediation transfers specification authority to Boeing and Airbus procurement teams. The shift is most visible in United States-based carrier fleets where aftermarket cost transparency drives sourcing centralization.
Global Commercial Aircraft Seat Actuation Market Segmentation
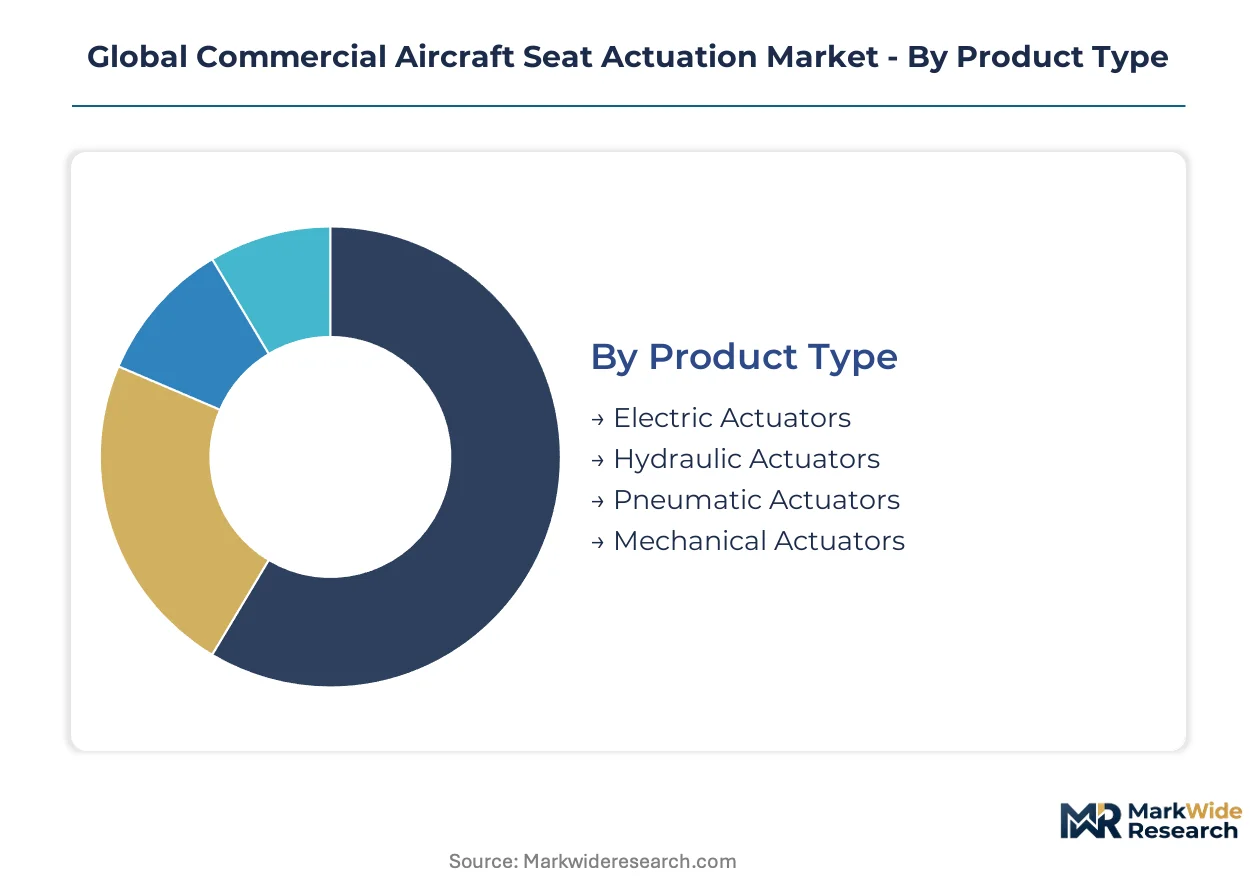
Segmentation in seat actuation reveals how capital deployment, regulatory exposure, and fleet replacement cycles concentrate value across distinct technology and customer categories. Understanding these divisions clarifies where suppliers must anchor qualification investments versus aftermarket service infrastructure.
Product Type:
Capital intensity varies sharply across drive system architectures, with electric platforms demanding the heaviest upfront motor-controller integration and certification spending.
- Electric Actuators:Brushless DC motor systems with integrated controllers convert 28 VDC or 115 VAC power into precise linear or rotary motion. Airlines retrofitting wide-body fleets with lie-flat seating in the United States and Germany specify these units for weight reduction and simplified maintenance intervals.
- Hydraulic Actuators:Fluid-power cylinders operating at pressures exceeding 3,000 PSI deliver high force density for heavy-duty cargo seating applications. Demand concentrates in legacy freighter conversions where operators prioritize load capacity over energy efficiency.
- Pneumatic Actuators:Compressed-air drives serve budget-constrained regional aircraft with limited electrical generation capacity.
- Mechanical Actuators:Manual screw-jack mechanisms persist in emergency exit rows and certain crew seating where electrical redundancy is prohibited.
Most installed capacity flows through Electric Actuators. Expansion is steepest in Pneumatic Actuators as Southeast Asian low-cost carriers expand turboprop fleets.
Application:
Margin capture diverges by cabin zone, with premium configurations requiring synchronized multi-axis architectures that multiply unit values.
- Premium Class Seating:Lie-flat mechanisms demand redundant motor systems with position feedback loops and crash-load-rated frames. Boeing and Airbus direct-buy agreements for new-build wide-bodies in China and the United States specify these actuators at the highest technical tier.
- Passenger Seating:Recline and leg-rest functions in economy and business cabins utilize single-motor electric drives with simplified control interfaces.
- Crew Seating:Flight deck and cabin crew stations require compact actuators with manual override capabilities for emergency egress compliance.
- Cargo Seating:Quick-change palletized seating for combi aircraft employs heavy-duty hydraulic or pneumatic drives rated for repeated reconfiguration cycles.
Premium Class Seating commands the highest per-unit engineering investment. Passenger Seating delivers the largest aggregate volume opportunity across fleet replacement programs.
End User:
Procurement authority is shifting from tier-one integrators toward direct OEM and airline relationships, altering supplier access patterns.
- Airlines:Flag carriers in Germany, the United States, and China now negotiate direct actuator specifications with Boeing and Airbus procurement teams, bypassing traditional seat manufacturer intermediaries for aftermarket transparency.
- Aircraft Manufacturers:Boeing, Airbus, and COMAC define technical requirements and qualification protocols for factory-installed seating on new production lines.
- Maintenance Providers:MRO networks in Singapore, the United Arab Emirates, and Germany handle refurbishment and crash-damage replacement under airworthiness directive compliance.
- Leasing Companies:Lessors in Ireland and the United States specify standardized actuator configurations to preserve residual value across multiple operator transitions.
Airlines drive the fastest specification changes. Aircraft Manufacturers lock in the longest contract horizons through platform development cycles.
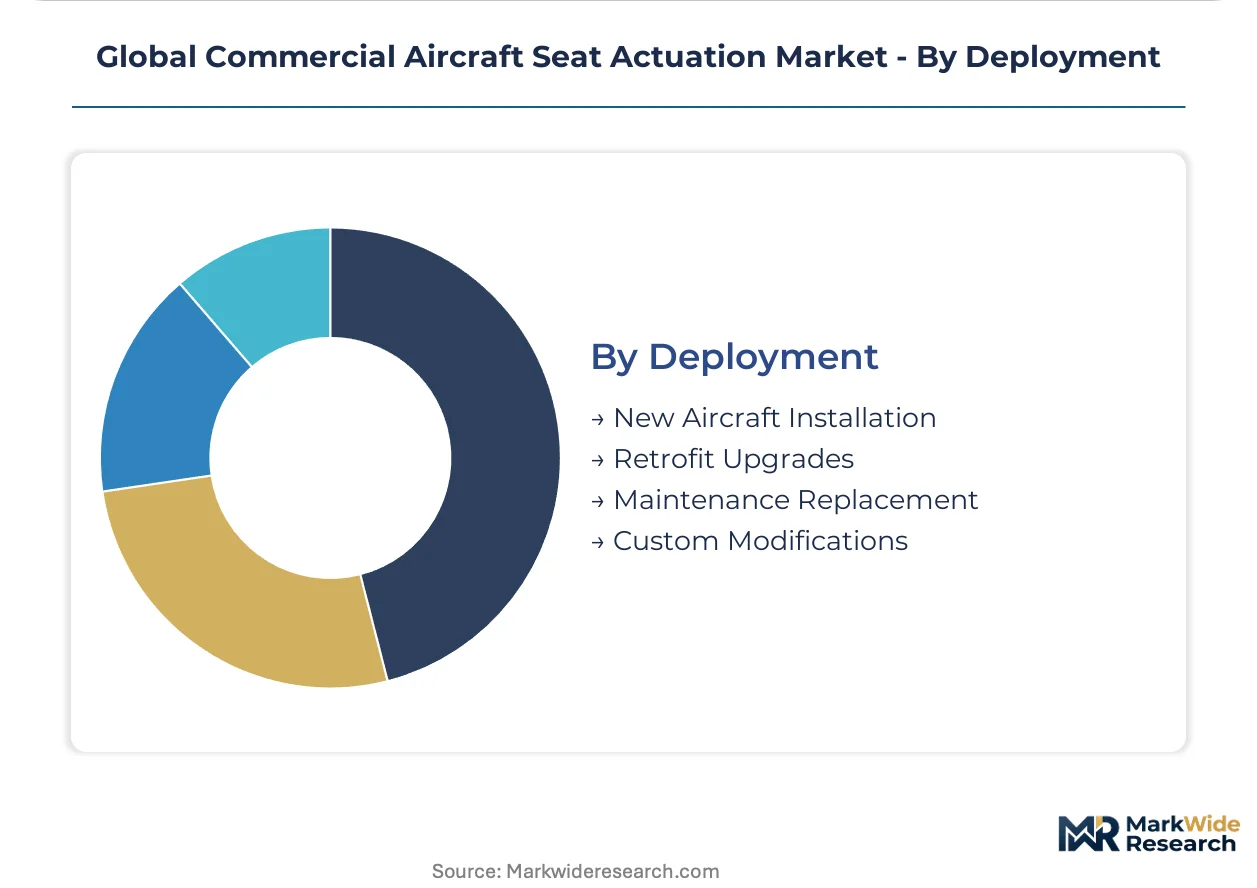
Deployment:
Revenue timing differs dramatically between new production attachment and aftermarket replacement, with retrofit cycles extending supplier cash conversion periods.
- New Aircraft Installation:Factory-fit actuators on Boeing 787, Airbus A350, and COMAC C919 production lines require simultaneous FAA, EASA, and CAAC qualification before first delivery.
- Retrofit Upgrades:Wide-body cabin reconfigurations for lie-flat seating generate complete actuator replacement demand from North American and European flag carriers modernizing legacy fleets.
- Maintenance Replacement:Crash-damage repairs and wear-item swaps follow scheduled C-check intervals at MRO facilities.
- Custom Modifications:VIP and head-of-state aircraft installations demand bespoke actuator architectures with non-standard stroke lengths and finish specifications.
New Aircraft Installation absorbs the greatest certification engineering resources. Retrofit Upgrades are climbing fastest as post-pandemic premium cabin competition intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The commercial aircraft seat actuation industry traces its commercial scale to post-war aerospace manufacturing clusters in Germany and the United States, where electromechanical precision engineering first merged with aviation certification requirements. These historical foundations established the regulatory and supplier networks that now define global actuator procurement patterns.
United States
Wide-body fleet retrofits by American, Delta, and United Airlines drive sustained aftermarket actuator demand for lie-flat premium cabin reconfigurations. FAA Part 25 crashworthiness standards and ongoing airworthiness directives force hardware redesigns that compress supplier qualification timelines. Seattle and Wichita host concentrated manufacturing ecosystems where Boeing procurement teams now negotiate direct actuator specifications, bypassing traditional seat integrator intermediaries.
Germany
Lufthansa Group's premium cabin modernization programs generate substantial factory-fit and retrofit actuator procurement volumes for Airbus A350 and Boeing 787 fleets. EASA CS-25 certification protocols and the EU's REACH chemical restrictions constrain seal materials and lubricant formulations, forcing pneumatic and hydraulic variant redesigns. Hamburg and Munich anchor specialized MRO networks handling refurbishment and crash-damage replacement under compressed regulatory timelines.
China
COMAC C919 production ramp-up and expanding wide-body fleets at Air China, China Eastern, and China Southern create localized actuator demand independent of Western supply chains. CAAC CCAR-25 framework alignment with FAA and EASA standards enables dual-qualified suppliers to capture factory-install contracts. Shanghai and Tianjin concentrate final assembly lines and growing MRO infrastructure that reduces import dependency for maintenance replacement cycles.
France
Airbus procurement teams in Toulouse define technical requirements for factory-installed seating on A320, A350, and A330 production lines, centralizing specification authority for European programs. The EU's CSRD disclosure mandates pivot how seat actuator suppliers document supply chain emissions and material provenance, creating competitive differentiation pressure. Toulouse-Blagnac and Nantes industrial clusters host precision electromechanical fabricators serving tier-one seat integrators with reduced certification friction.
Singapore
SIA Engineering and ST Engineering MRO facilities handle actuator refurbishment and replacement for Asia-Pacific carrier fleets under scheduled C-check intervals. The city-state's maintenance infrastructure serves as a regional hub for crash-damage repairs and wear-item swaps independent of European and North American service networks. Changi Aviation Park concentrates specialized testing capabilities for dynamic load validation exceeding regulatory thresholds.
Global Commercial Aircraft Seat Actuation Market Competitive Landscape
The competitive structure tilts toward electromechanical specialists with integrated motor-controller capabilities and established multi-certification track records. Three distinct archetypes populate the supplier base: diversified aerospace conglomerates with seat actuation as a vertical segment; pure-play precision motion control firms focused exclusively on aviation applications; and diversified industrial automation suppliers adapting commercial off-the-shelf architectures for airworthiness compliance. Competitive dynamics center on strategic partnerships with tier-one seat integrators and selective backward integration into motor manufacturing to secure supply continuity.
Within the diversified aerospace tier, Crane Aerospace & Electronics and Collins Aerospace occupy positions anchored by broad electromechanical portfolios and long-term OEM relationships. Moog Inc. exemplifies the precision motion control specialist archetype, with its company name signaling concentrated expertise in multi-axis articulation systems. Safran SA and ITT Inc. represent European and American industrial conglomerates respectively, each with aviation-qualified actuator divisions sitting within larger transportation and defense portfolios. Bühler Motor GmbH anchors the German precision manufacturing tradition, while Astronics Corporation and Nook Industries illustrate the mid-scale specialist segment serving retrofit and aftermarket channels with focused product lines.
| Leading Market Players |
|---|
| Bühler Motor GmbH |
| Crane Aerospace & Electronics |
| Moog Inc. |
| Collins Aerospace |
| Astronics Corporation |
| Safran SA |
| ITT Inc. |
| Zodiac Aerospace |
| Nook Industries |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between multi-axis electromechanical systems and commodity pneumatic drives manifests in both unit economics and supplier network topology. Premium lie-flat mechanisms command sustained margin pools through synchronized motor architectures with redundant position feedback, while budget regional aircraft specifications compress supplier margins through simplified compressed-air alternatives. FAA Part 25 and EASA CS-25 qualification timelines further stratify pricing power, with dual-certified manufacturers capturing factory-fit contracts from Boeing and Airbus procurement teams while single-certification suppliers remain tethered to aftermarket replacement cycles.
Pricing Analysis
The bundled-versus-unbundled service split separates long-term actuator procurement under airframe OEM direct-buy agreements from spot-market maintenance replacement. Three-tier pricing structure across premium, standard, and economy levels tracks certification complexity, with multi-axis electromechanical systems carrying the highest engineering amortization. Price differentiation rests on crash-load validation status and integrated motor-controller packaging density. Cost compression in pneumatic variants is intensifying because Southeast Asian low-cost carriers prioritize acquisition cost over lifecycle maintenance. Airlines negotiating direct specifications with Boeing and Airbus exhibit the lowest price sensitivity, while regional turboprop operators drive aggressive commodity bidding.
Supply Chain Analysis
CAAC domestic-content mandates for COMAC C919 production lines are reshaping sourcing patterns, forcing Western suppliers to establish joint-venture manufacturing in Shanghai and Tianjin. Component fabrication concentrates in Germany, the United States, and China, with precision motor winding and controller assembly anchored in Stuttgart and Wichita. Rare-earth magnet supply draws from Chinese processing facilities, while specialized seal elastomers feed from German chemical compounders. Single-source vulnerability runs through brushless DC motor controller chipsets. Distribution runs through tier-one seat integrator channels for new-build programs and MRO networks for aftermarket fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The commercial aircraft seat actuation market functions as a stable compounder, with wide-body fleet retrofit cycles generating sustained aftermarket demand independent of new aircraft delivery volatility. Regulatory harmonization across FAA, EASA, and CAAC frameworks creates durable competitive moats for qualified suppliers.
For Market Incumbents: Deploy backward integration into rare-earth magnet supply to insulate against Chinese export quota volatility. Consolidate testing infrastructure partnerships with Hamburg and Wichita crash-load facilities to compress qualification timelines for next-generation lie-flat architectures. Electromechanical specialists with captive motor production capabilities defend most effectively against emerging Asian challengers. For New Entrants and Emerging Players: CAAC CCAR-25 framework alignment with FAA and EASA standards opens a window for dual-qualified suppliers to capture retrofit contracts from Chinese-owned wide-body operators. Target lithium-powered electric actuator segments where thermal runaway certification gaps persist among established vendors. Pursue white-label manufacturing partnerships with COMAC C919 seat integrators as the lowest-friction entry vector. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-certification engineering talent scarcity constrains supplier scaling capacity. Mid-scale electromechanical specialists with established FAA-EASA track records represent optimal acquisition targets for platform roll-up strategies. Watch for inflection signals in CAAC approval timeline convergence, which would unlock factory-fit contract access for Western suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Certification Engineering Investment | Dual FAA-EASA-CAAC qualification unlocks Boeing 787 and Airbus A350 factory-fit contracts. |
| Brushless DC Motor Controller Integration | Unified power conversion and position sensing eliminates separate rack space and wiring weight. |
| China Joint-Venture Manufacturing | Local production satisfies COMAC C919 domestic-content requirements and reduces tariff exposure. |
| Thermal Runaway Certification Program | Fail-safe battery-integrated architectures capture first-mover advantage in emerging lithium actuator protocols. |
| MRO Network Partnership Expansion | Singapore and Dubai maintenance hubs provide Asia-Pacific aftermarket access independent of European channels. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with aircraft manufacturer procurement directors, tier-one seat integrator engineering leads, MRO facility maintenance planners, and electromechanical component suppliers with secondary validation against FAA airworthiness directive filings, EASA certification databases, COMAC supplier disclosure records, and customs trade data for actuator motor and controller imports. Bottom-up build-ups of installed fleet base and retrofit cycle timing were cross-checked against top-down aerospace OEM production forecasts.
Segment-weighting approaches distributed value across electric, hydraulic, pneumatic, and mechanical actuator product types, with further disaggregation by premium class seating, passenger seating, crew seating, and cargo seating applications. Deployment mode splits between new aircraft installation, retrofit upgrades, maintenance replacement, and custom modifications were modeled across the projection horizon. CAGRs were derived from fleet replacement schedules and regulatory-driven hardware redesign cycles, with specific inputs from lie-flat seating penetration rates in wide-body reconfigurations and REACH chemical restriction compliance timelines affecting seal material reformulation.
Revisions become necessary when CAAC certification pathway divergence, sustainable aviation fuel compatibility mandates, or lithium battery thermal runaway protocol finalizations materialize differently than modeled assumptions. Supply chain disruptions affecting rare-earth magnet availability or semiconductor controller fabrication could compress or extend supplier qualification timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Europe General Aviation Market
Aircraft
South Korea Aviation Market
Aircraft
Asia-Pacific General Aviation Market
Aircraft
Aircraft Cargo Container Market
Aircraft
Aircraft Cargo Winches Market
Aircraft
Aviation Crew Management System Market
Aircraft
Aircraft Flight Control Computers Market
Aircraft
Fighter Aircraft Market
Aircraft
Middle East and Africa Military Helicopters Market
Aircraft
North America Aircraft Manufacturing Market
Aircraft
Helicopter Lighting Market
Aircraft
Asia-Pacific Commercial Aircraft Market
Aircraft
Aircraft Strut Market
Aircraft
America Freighter Aircraft Market
Aircraft
Commercial Aircraft in-Seat Power System Market
Aircraft
Middle-East and Africa Business Jet Market