
 Steel Casting Market | 2026-2036
Steel Casting Market Size, Share, and Industry Trends Forecast 2026-2036
Steel Casting Market Analysis
Market Context
The split between premium aerospace-grade castings and commodity construction-grade output is realigning contract structures across the supply base. ArcelorMittal leverages its integrated European mill network to dominate high-specification alloy segments for energy and transport clients. Nucor Corporation anchors its position through electric arc furnace flexibility, allowing rapid grade switching between carbon and alloy orders. thyssenkrupp AG differentiates via precision finishing capabilities that command sustained margins in German automotive supply chains.
Technical Definition and Segment Structure
Steel casting involves pouring molten steel into molds to form complex geometries with tensile strengths typically exceeding 400 MPa, serving critical load-bearing functions in power generation, transportation, and heavy machinery. Carbon steel castings occupy the largest volume share across construction and general machinery applications where cost sensitivity overrides alloy performance requirements. Investment casting leads technology margins by enabling near-net-shape production for aerospace turbine blades and medical instruments, while sand casting sustains foundational capacity for marine propellers and industrial housings.
Regulatory Environment
EPA emissions rules and OSHA foundry safety standards in the United States compress operating margins but simultaneously filter marginal producers from the competitive set. REACH compliance in Europe and China's GB standards for industrial emissions impose divergent testing and certification burdens on exporters serving multiple jurisdictions. Stakeholders must monitor how carbon border adjustments and evolving scrap metal traceability rules reshape sourcing economics for integrated versus merchant foundry models.
Market Dynamics
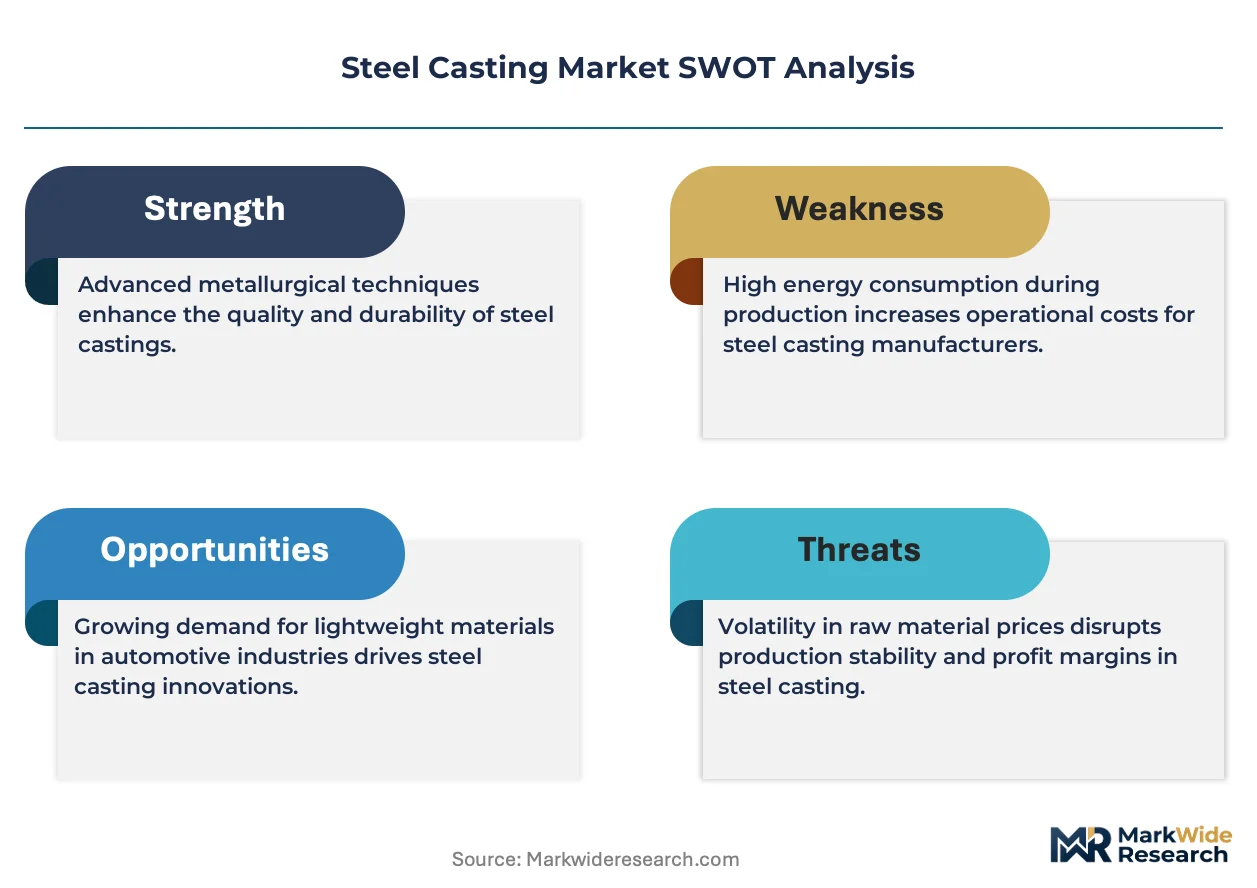
Automotive OEMs are forcing a recalibration of foundry economics as lightweighting mandates compress batch sizes while multiplying alloy grades, fragmenting production schedules across the supply base.
Growth Catalysts
- EPA emissions standards:The United States Environmental Protection Agency's tightening tailpipe rules are compelling powertrain redesigns that favor precision-cast steel components over forged alternatives in transmission housings.
- China's industrial machinery buildout:Domestic infrastructure investment and energy sector expansion are concentrating demand for heavy-section castings in foundries along the Yangtze River corridor.
- Investment casting automation:Robotics-assisted shell-building and digital pattern libraries are compressing lead times for aerospace turbine blade orders from twelve weeks to under six.
Market Restraints
- Scrap metal price volatility:Electric arc furnace operators face margin compression when shredded auto scrap spreads widen unpredictably against hot-rolled coil benchmarks.
- Graphite electrode supply concentration:Chinese producers control over seventy percent of ultra-high-power electrode manufacturing, exposing Western foundries to export restriction risk.
- Ceramic core substitution limits:Complex internal cooling geometries in industrial gas turbine blades remain unachievable with additive manufacturing, locking in investment casting dependence.
Strategic Opportunities
- India's defense indigenization:The country's PLI scheme for specialty steel is creating captive demand for tank hull and submarine valve castings previously sourced from European suppliers.
- Offshore wind monopile transition:Floating platform anchor systems require novel high-manganese steel grades that incumbent forging houses cannot economically produce at scale.
- Carbon border adjustment mechanics:The European Union's CBAM implementation is incentivizing integrated mill-casting combinations that can document Scope 3 emissions from ore to finished component.
Industry Challenges
- Non-destructive testing technician scarcity:Radiographic interpretation certification programs produce fewer qualified inspectors than ultrasonic and phased-array inspection protocols require for aerospace work.
- Legacy ERP-to-MES integration:Sand casting operations running twenty-year-old shop-floor systems face data architecture friction when connecting to customer digital thread requirements.
- Heat treatment furnace certification:Nadcap accreditation timelines for vacuum carburizing equipment stretch fourteen months, gating entry into medical implant casting supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steel Casting Market |
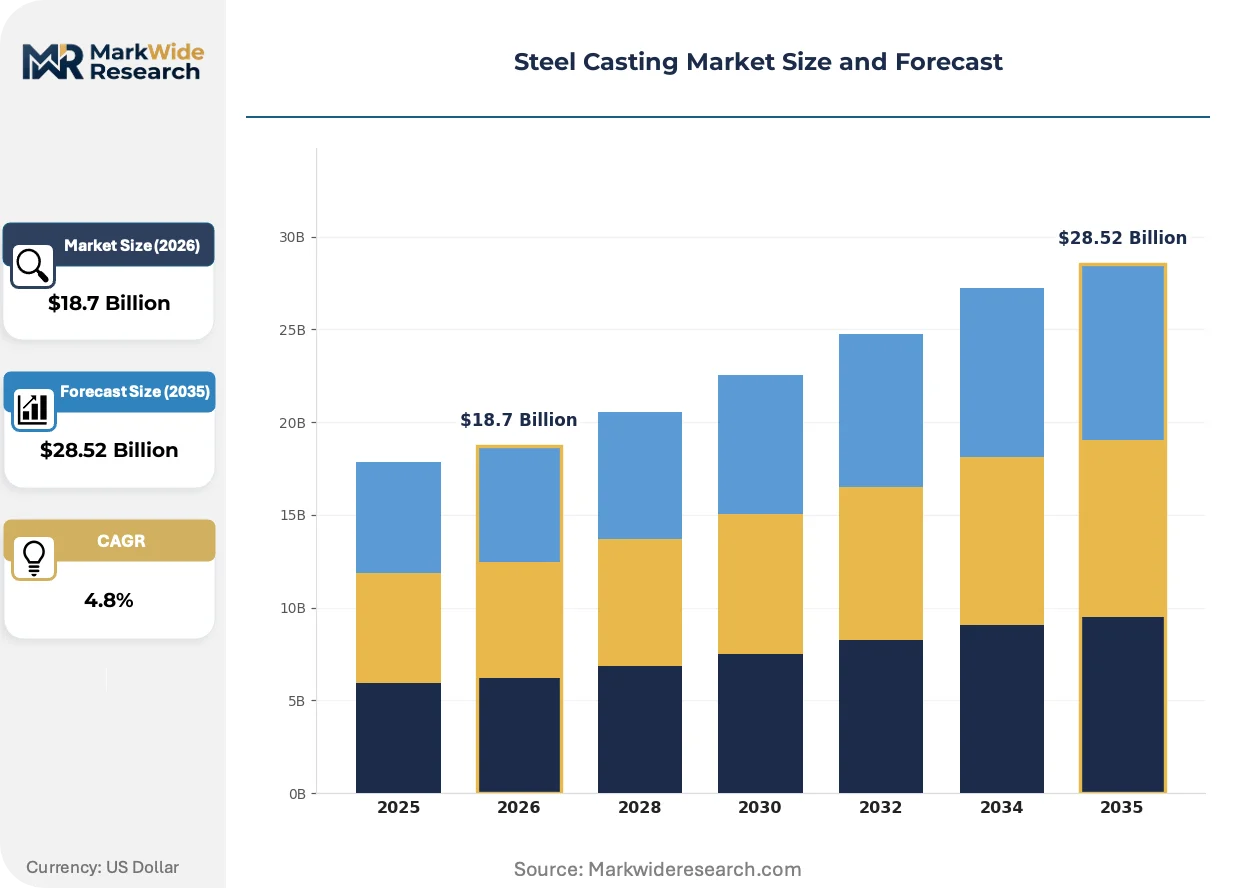
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Steel, Alloy Steel, Stainless Steel, Tool Steel Application: Aerospace, Automotive, Marine, Machinery End User: Manufacturers, OEMs, Foundries, Construction Technology: Investment Casting, Sand Casting, Die Casting, Centrifugal Casting |
| Companies Covered | Precision Castparts Corp., ArcelorMittal, Nemak S.A.B. de C.V., Nippon Steel Corporation, Doosan Corporation, Nucor Corporation, thyssenkrupp AG, Impro Precision Industries Ltd., GF Casting Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steel Casting Market Emerging Trajectories
Digital thread architectures are dissolving the traditional separation between design engineering and shop-floor metallurgy, enabling real-time chemistry adjustments that were previously impossible.
Real-time melt monitoring systems using laser-induced breakdown spectroscopy are absorbing quality control functions that once required post-pour laboratory analysis. Aerospace tier-one suppliers are deploying these sensors across vacuum induction melting lines to catch nitrogen excursions before pour. The technology is absorbing intermediate inspection steps and compressing certification documentation cycles from days to hours.
REACH authorization requirements for nickel compounds are forcing European foundries to reformulate austenitic stainless steel grades for marine applications. The European Chemicals Agency's sunset dates for unregistered substances are accelerating R&D spending on manganese-nitrogen replacements. German pump manufacturers are qualifying these alternatives ahead of 2026 deadlines to avoid supply interruption.
Consolidated procurement desks at wind turbine OEMs are displacing fragmented foundry relationships with single-source platform agreements covering cast, machined, and coated components. Vestas and Siemens Gamesa are bundling multi-year contracts that require suppliers to absorb inventory carrying costs. This concentration is most visible in Denmark and northern Germany, where casting houses are restructuring sales organizations around dedicated account teams.
Steel Casting Market Segmentation
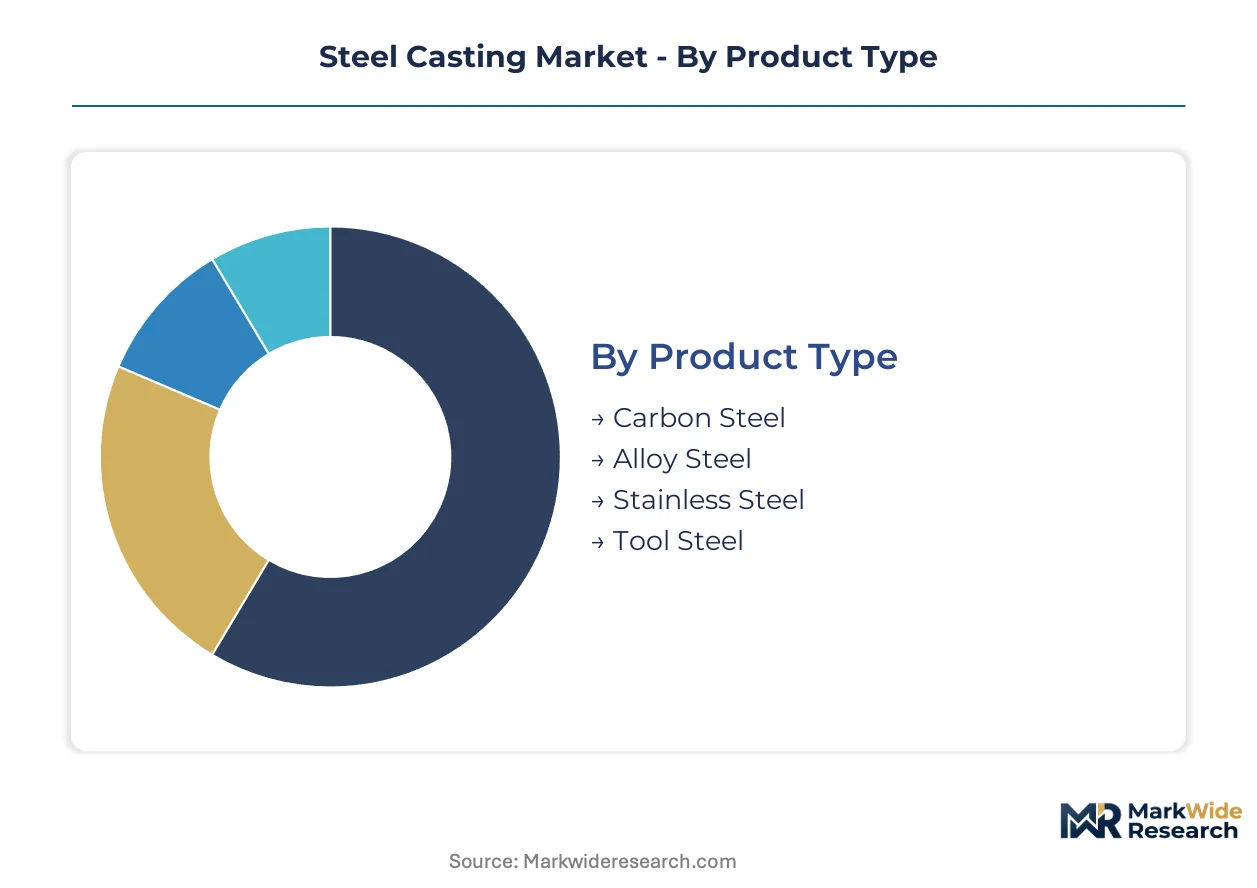
Steel casting segmentation reveals how specification tiers, process technologies, and end-use requirements fragment procurement patterns. Foundries must align capacity investments against these axes to capture margin pools rather than commodity volume.
Product Type:
Specification grade determines metallurgical complexity and pricing power across the supply base.
- Carbon Steel:Low-alloy compositions dominate construction brackets and general machinery housings where tensile requirements stay below 600 MPa. Demand concentrates in Chinese industrial machinery buildout along the Yangtze River corridor as domestic infrastructure investment accelerates.
- Alloy Steel:Chromium-molybdenum and nickel-bearing grades enable creep resistance in power generation turbine casings and pressure vessels. Procurement from German automotive OEMs is intensifying for transmission components facing lightweighting mandates.
- Stainless Steel:Austenitic and duplex grades serve marine propellers and chemical processing equipment requiring corrosion resistance. REACH authorization pressures on nickel compounds are forcing European foundries to reformulate manganese-nitrogen alternatives ahead of regulatory deadlines.
- Tool Steel:High-carbon, high-vanadium compositions deliver wear resistance for die-casting molds and metal-forming dies. Japanese tool-and-die manufacturers anchor specialized demand for vacuum-degassed premium grades.
Mature deployment sits with Carbon Steel. Newer deployment is concentrated in Alloy Steel.
Application:
End-use performance requirements dictate certification burden and batch economics.
- Aerospace:Vacuum investment casting of single-crystal turbine blades demands Nadcap-accredited heat treatment and radiographic inspection protocols. Lead times have compressed from twelve weeks to under six through robotics-assisted shell-building automation.
- Automotive:Powertrain lightweighting is fragmenting production schedules as OEMs multiply alloy grades while compressing batch sizes. EPA emissions standards are accelerating precision-cast steel adoption in transmission housings previously served by forged alternatives.
- Marine:Heavy-section propellers and stern frames sustain sand casting capacity at European and Japanese yards. Classification society rules from Lloyd's Register and DNV govern mechanical testing protocols for open-water reliability.
- Machinery:Industrial housings and gearboxes tolerate broader dimensional tolerances, prioritizing cost over metallurgical premium. Indian domestic foundries are scaling capacity to serve construction equipment and mining machinery demand.
Certification intensity peaks in Aerospace. Volume scale concentrates in Machinery.
End User:
Procurement sophistication varies dramatically across customer archetypes.
- Manufacturers:Tier-two and tier-three component suppliers purchase standard grades through spot-market arrangements with limited technical collaboration.
- OEMs:Automotive and aerospace original equipment manufacturers impose digital thread requirements and real-time quality data exchange, favoring foundries with modern MES integration.
- Foundries:Merchant casting houses source ingot and scrap feedstock, exposing them to graphite electrode supply concentration risks from Chinese producers.
- Construction:Infrastructure contractors prioritize delivered cost and availability over metallurgical traceability, accepting broader chemistry windows.
Technical integration runs deepest with OEMs. Price sensitivity dominates Construction procurement.
Technology:
Process selection locks in capital intensity, surface finish capability, and internal geometry complexity.
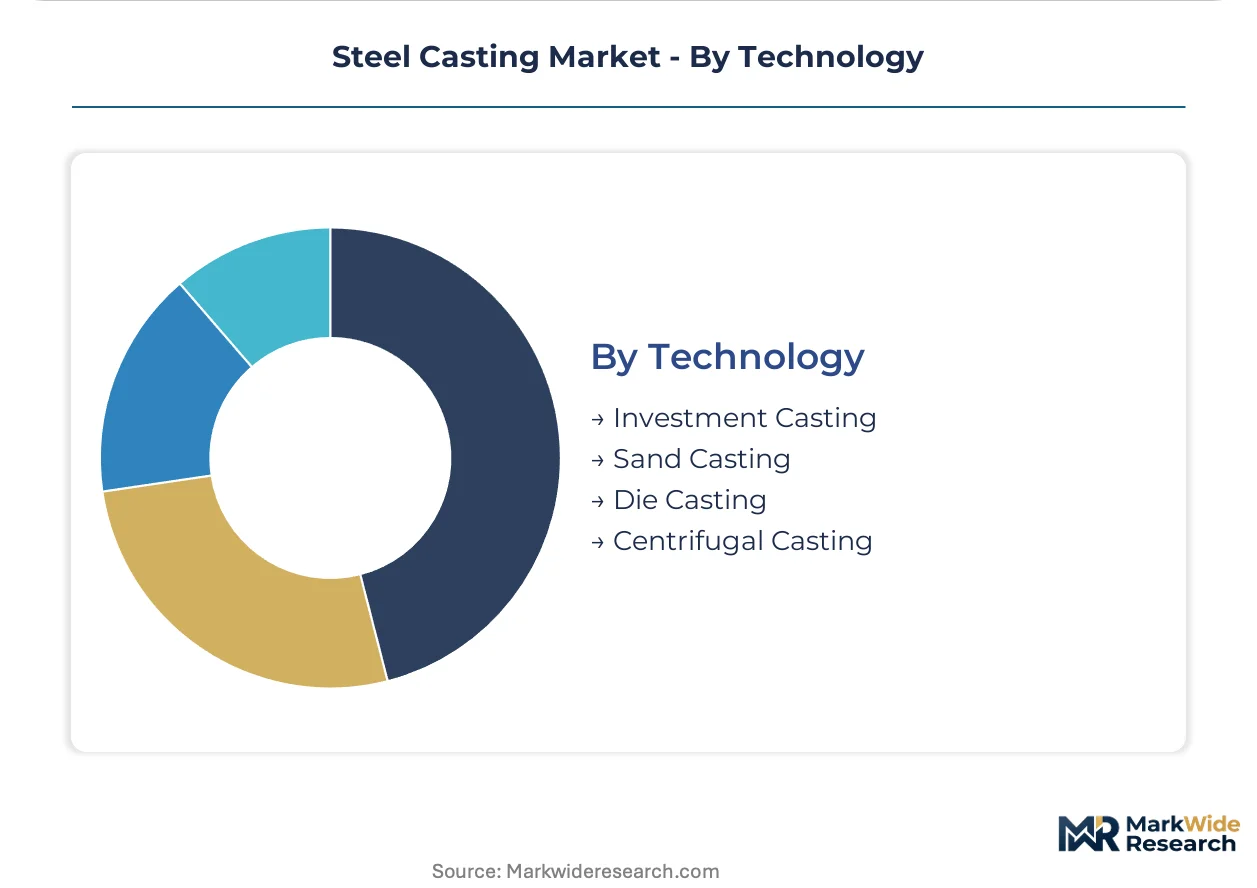
- Investment Casting:Ceramic shell processes achieve near-net-shape precision for turbine blades and medical instruments with surface finishes below 125 RMS. Laser-induced breakdown spectroscopy is absorbing post-pour laboratory analysis steps.
- Sand Casting:Green-sand and chemically bonded molds sustain foundational capacity for marine propellers and heavy machinery housings. Legacy ERP-to-MES integration friction is gating digital thread compliance for aerospace work.
- Die Casting:High-pressure metal injection suits thin-wall automotive brackets and small engine components requiring dimensional repeatability.
- Centrifugal Casting:Rotational force segregation produces radially graded properties ideal for pipe spools and bearing sleeves with dense outer surfaces.
Margin premiums concentrate in Investment Casting. Volume throughput peaks in Sand Casting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta anchors global steel casting capacity, with foundry clusters in Shanghai, Jiangsu, and Zhejiang provinces processing heavy-section components for domestic machinery and export markets. Production concentration here reflects proximity to steel mills, port infrastructure, and automotive OEM assembly plants.
China
Domestic infrastructure investment and energy sector expansion concentrate demand for industrial machinery castings along the Yangtze River corridor. GB standards for industrial emissions impose testing burdens on exporters serving multiple jurisdictions. Foundries in Jiangsu province scale capacity for wind turbine and power generation components.
United States
EPA emissions standards accelerate investment in precision casting processes for powertrain components. OSHA foundry safety standards compress operating margins while filtering marginal producers from the competitive set. Electric arc furnace operators in the Southeast face margin compression from shredded auto scrap price volatility.
Germany
Automotive OEM procurement for lightweight transmission housings intensifies demand for precision-cast alloy grades. REACH compliance requirements for nickel compounds force reformulation of austenitic stainless steel grades ahead of 2026 deadlines. Foundries in North Rhine-Westphalia maintain precision finishing capabilities for captive automotive supply chains.
India
The PLI scheme for specialty steel creates captive demand for tank hull and submarine valve castings previously sourced from European suppliers. Domestic foundries scale capacity to serve construction equipment and mining machinery demand. Industrial clusters in Maharashtra and Gujarat expand sand casting operations for general machinery applications.
Japan
Tool-and-die manufacturers anchor specialized demand for vacuum-degassed premium tool steel grades. METI industrial policy supports investment casting automation for aerospace turbine blade production. Nagoya-area foundries serve precision requirements for medical instrument and industrial gas turbine components.
Steel Casting Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across a tiered supply base where integrated mill networks face merchant foundries with electric arc furnace flexibility. The market structure fragments between premium aerospace-grade specialists and commodity construction-grade volume players. Three archetypes dominate: integrated steel mill-casting combinations, electric arc furnace-based flexible producers, and precision investment casting specialists. M&A activity concentrates among European automotive supply chain assets, while capacity expansion focuses on Yangtze River corridor heavy-section foundries.
Within the integrated mill tier, ArcelorMittal and Nucor Corporation exemplify divergent geographic and technological positioning. ArcelorMittal leverages its European network presence to serve high-specification alloy segments for energy and transport clients. Nucor Corporation anchors North American positioning through electric arc furnace operational flexibility that enables rapid grade switching between carbon and alloy orders. Among precision casting specialists, Precision Castparts Corp. occupies a position representing aerospace and medical instrument tier-one supplier relationships.
| Leading Market Players |
|---|
| Precision Castparts Corp. |
| ArcelorMittal |
| Nemak S.A.B. de C.V. |
| Nippon Steel Corporation |
| Doosan Corporation |
| Nucor Corporation |
| thyssenkrupp AG |
| Impro Precision Industries Ltd. |
| GF Casting Solutions |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap foundries across Germany and Japan anchor premium alloy segments through generational metallurgical expertise that resists commoditization pressure. Their concentrated ownership structures enable long-term customer contracts without quarterly earnings scrutiny, reinforcing pricing discipline even when scrap volatility compresses merchant foundry margins.
Pricing Analysis
Value-based pricing anchored to component uptime guarantees dominates aerospace and power generation procurement, with turbine blade suppliers capturing premiums tied to mean-time-between-failure performance. Certification grade and Nadcap heat-treatment accreditation drive price differentiation between aerospace-tier and general-machinery castings. Cost compression in carbon steel construction brackets intensifies as Chinese Yangtze River corridor capacity expands. Construction contractors exhibit highest price sensitivity, accepting broader chemistry windows, while medical implant OEMs prioritize metallurgical traceability over unit cost.
Supply Chain Analysis
Graphite electrode supply rests on Chinese producers controlling ultra-high-power manufacturing capacity, exposing Western electric arc furnace operators to export restriction risk. Raw material flows draw from shredded auto scrap yards in the United States, direct-reduced iron pellets from Middle Eastern gas-based plants, and high-grade ferroalloys from South African chromium and Kazakh ferromanganese operations. Single-source vulnerability concentrates in ceramic shell supply for investment casting. Distribution runs through consolidated procurement desks at wind turbine OEMs bundling cast, machined, and coated components under single-source platform agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained conditions in aerospace-grade vacuum investment casting prop pricing power, with Nadcap accreditation timelines stretching fourteen months and gating new competitor entry.
For Market Incumbents: Extend precision finishing capabilities into medical implant supply chains before REACH nickel compound sunset dates force grade reformulation. Consolidate sand casting assets in India's Maharashtra and Gujarat industrial corridors to capture PLI-scheme defense demand. Threat substitution from additive manufacturing in simple geometries demands counterinvestment in real-time melt monitoring systems that compress certification cycles. For New Entrants and Emerging Players: Laser-induced breakdown spectroscopy integration offers a technology-first wedge into aerospace tier-two supplier relationships currently frustrated by legacy foundry quality documentation delays. Target India's defense indigenization white space for tank hull and submarine valve castings previously sourced from European suppliers. Pursue joint qualification programs with German pump manufacturers ahead of manganese-nitrogen stainless steel reformulation deadlines. For Investors and Strategic Acquirers: Distressed-cycle entries favor electric arc furnace-based flexible producers in the United States Southeast with rapid carbon-to-alloy grade switching capability. Long-term viability hinges on integrated mill-casting combinations that can document Scope 3 emissions from ore to finished component under evolving carbon border adjustment mechanics. Watch graphite electrode export license volumes from Chinese customs as inflection indicator for Western foundry margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Scrap Sorting | Nucor Corporation's electric arc furnace flexibility hinges on shredded auto scrap quality control. |
| Nadcap Heat Treatment Accreditation | Fourteen-month vacuum carburizing certification timelines gate medical implant supply chain entry. |
| Robotics-Assisted Shell-Building Automation | Aerospace turbine blade lead times compress from twelve weeks to under six through digital pattern libraries. |
| Carbon Border Adjustment Documentation | European Union CBAM implementation favors integrated mill-casting combinations with ore-to-component emissions tracking. |
| Manganese-Nitrogen Stainless Reformulation | German pump manufacturers qualify REACH-compliant alternatives ahead of nickel compound sunset deadlines. |
Methodological Framework
Document review covered customs and trade flow databases, SEC 10-K filings from publicly traded steel producers, and foundry association capacity surveys, complemented by interviews with foundry operations managers, automotive OEM procurement leads, aerospace tier-one supplier quality directors, and graphite electrode distribution specialists. Secondary validation drew from EPA emissions compliance filings, REACH substance registration databases, and Indian PLI scheme administrative records. Bottom-up capacity modeling and top-down demand segmentation triangulated market sizing.
Segment-level projections across carbon steel, alloy steel, stainless steel, and tool steel grades were generated through the analysis window, with investment casting, sand casting, die casting, and centrifugal casting technology splits informing margin assumptions. Aerospace, automotive, marine, and machinery application demand curves were modeled against EPA tailpipe rules, China's industrial machinery buildout, and offshore wind monopile transition timelines. CAGRs were derived from production capacity expansion announcements and OEM contract visibility.
Forecast precision tightens around the base case; tail outcomes carry wider variance under graphite electrode export restriction scenarios or accelerated REACH authorization timelines. Forecasts reflect assumptions about scrap metal price correlation stability and Nadcap accreditation throughput capacity. A small set of triggers—including Chinese industrial emissions enforcement intensity and Indian defense procurement localization pace—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Iron Casting Market
Metals
Titanium Market
Metals
Aluminum Powders Pastes and Flakes Market
Metals
Global Tin Market
Metals
Weathering Steel Market
Metals
US Ferrochrome Market
Metals
Transition Metals Market
Metals
Global Mercury Market
Metals
Heat-Treated Steel Plates Market
Metals
Rubidium Market
Metals
Europe Aluminium Wire Rod Market
Metals
Galvanizing Market
Metals
Silver Cyanide Market
Metals
Titanium Sponge Market
Metals
Steel Drums Market
Metals
Monel Alloy Market