
 Yucca Extract Material Market | 2026-2036
Yucca Extract Material Market Size, Share, and Industry Trends Forecast 2026-2036
Yucca Extract Material Market Analysis
Asset-light contract extraction and toll manufacturing is tilting competitive dynamics toward smaller botanical specialists that lack captive farming operations. Desert King International leverages its integrated desert farming and extraction infrastructure to sustain cost advantages across powder and liquid grades. Ingredients by Nature LLC competes through specialized organic certification and kosher/halal positioning for dietary supplement clients. Baja Yucca Company anchors its presence in granule formats for animal feed compounders seeking flowability improvements.
Yucca extract material comprises steroidal saponins, polyphenols, and polysaccharides derived from Yucca schidigera and Yucca filamentosa species through aqueous or solvent extraction, typically standardized to 10-30% saponin content for commercial applications. The extract functions primarily as a natural surfactant, ammonia binder, and anti-inflammatory agent across food, feed, and cosmetic systems. Powder formulations lead volume due to superior shelf stability and ease of blending into dry premixes, while liquid extracts capture faster growth in personal care where cold-process emulsification demands aqueous compatibility. The dietary supplements application concentrates margin pools where standardized saponin claims support premium positioning, whereas animal feed operates at scale with thinner returns.
The FDA oversees GRAS determinations and New Dietary Ingredient notifications that gate yucca entry into functional foods and supplements, while the EPA evaluates pesticidal claims when extracts target ammonia reduction in livestock confinement. USDA organic certification and NOP compliance shape premium segment access, particularly for export-oriented suppliers. FSSAI registration requirements in India and EFSA Novel Food opinions in Europe add compliance layers for international expansion. Stakeholders must monitor evolving saponin threshold regulations in major import markets and calibrate extraction standardization investments accordingly.
Market Dynamics
The yucca extract material market is restructuring around asset-light contract extraction models that favor botanical specialists without captive farming operations, compressing margins for integrated players while opening entry points for niche organic and kosher-certified suppliers.
Growth Catalysts
- FDA GRAS self-affirmation pathway:The streamlined approval mechanism accelerates ingredient clearance for functional food applications, reducing time-to-market for yucca-derived surfactants and ammonia binders entering human and pet nutrition systems.
- Pet food manufacturer demand:Natural foaming and odor-control agents are displacing synthetic additives in premium kibble and wet food formulations, with contract compounders specifying yucca saponins for label-friendly positioning.
- Southwest US cultivation clusters:Desert-adapted Yucca schidigera farming concentrates in Arizona and New Mexico, providing feedstock proximity to toll extraction facilities and reducing inbound logistics costs for powder and liquid grade production.
Market Restraints
- Wild-harvest supply concentration:Dependence on mature Yucca schidigera populations in Mojave and Sonoran desert ecosystems creates volume constraints and price volatility when drought cycles reduce harvestable biomass.
- Solvent extraction cost structure:Organic ethanol and food-grade methanol inputs face agricultural commodity price swings, compressing margins for standard-grade saponin extracts during energy market disruptions.
- EFSA Novel Food opinion timelines:European market entry requires protracted safety assessments for yucca polysaccharide fractions, delaying revenue recognition for suppliers targeting EU functional food applications.
Strategic Opportunities
- Personal care cold-process emulsification:Liquid extract aqueous compatibility enables formulation in temperature-sensitive cosmetic systems, with indie beauty brands specifying yucca-derived natural surfactants for clean-label positioning.
- India FSSAI registration pathway:Formalized ingredient approval under India's food safety framework opens access to domestic nutraceutical compounders and Ayurveda-inspired supplement manufacturers seeking standardized saponin inputs.
- USDA Organic certification tailwind:NOP-compliant extraction processes command 15-30% price premiums in dietary supplement channels, rewarding suppliers that invest in certified organic solvent recovery and handling protocols.
Industry Challenges
- Analytical chemist talent scarcity:Standardized saponin quantification via HPLC-ELSD requires specialized phytochemical expertise that concentrates in university research labs and contract testing houses, constraining in-house quality control scaling.
- Multi-jurisdiction certification complexity:Simultaneous pursuit of kosher, halal, organic, and GRAS status demands parallel documentation streams and audit cycles, extending sales qualification timelines for multinational ingredient buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yucca Extract Material Market |
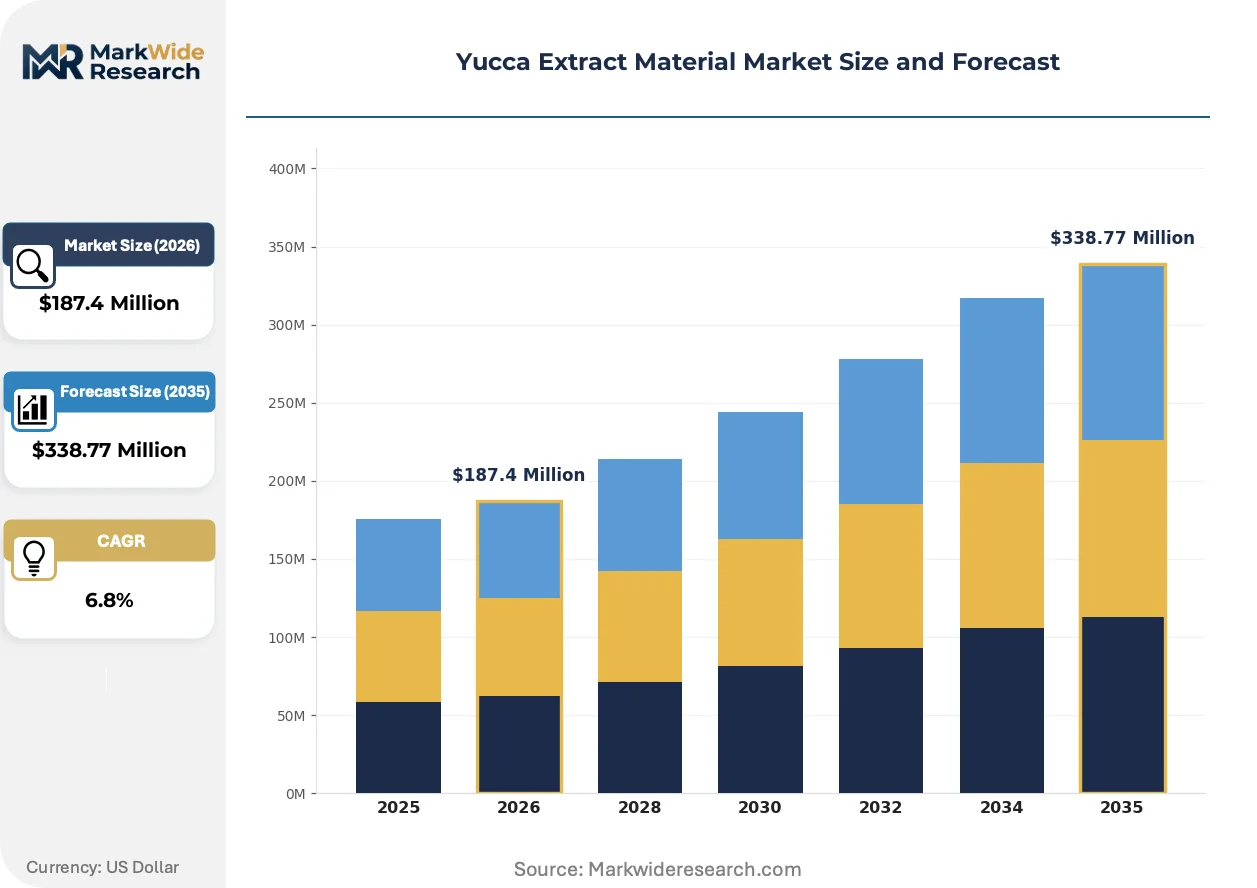
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Capsule, Granule End User: Food Industry, Cosmetics, Pharmaceuticals, Agriculture Application: Dietary Supplements, Animal Feed, Functional Foods, Personal Care Packaging Type: Bottles, Bags, Jars, Boxes |
| Companies Covered | Desert King International, Naturex Group, Baja Yucca Company, American Extracts, Ingredients by Nature LLC, Avitech Nutrition Pvt. Ltd, Nova Microbials, Garuda International Inc., Ultra Bio-Logics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yucca Extract Material Market Emerging Trajectories
Process analytical technology and extraction automation are compressing batch-to-batch variability while regulatory data infrastructure is digitizing compliance documentation across distributed supply chains.
Supercritical CO2 extraction systems with inline near-infrared monitoring are digitizing real-time saponin standardization, enabling continuous processing that reduces solvent waste and improves yield consistency. Mid-tier toll manufacturers in Texas and California are retrofitting batch aqueous lines with modular CO2 units to capture personal care contracts demanding residual-solvent-free extracts. The technology is digitizing quality assurance workflows, replacing offline HPLC verification with automated release decisions that compress turnaround times from days to hours.
REACH registration requirements for imported botanical extracts are tightening substance characterization obligations for yucca saponin mixtures entering EU cosmetic and feed additive channels. The regulation forces suppliers to generate full analytical profiles including genotoxicity data and environmental fate studies, raising entry costs for non-European exporters. Small-scale Indian and Mexican producers are responding by partnering with EU-based importers that maintain existing dossiers, effectively ceding margin to intermediaries with regulatory infrastructure.
Direct procurement from extraction facilities is displacing traditional distributor relationships among mid-size pet food compounders seeking traceability documentation for ESG reporting. Buyers now require blockchain-anchored batch records linking desert harvest coordinates to finished extract certificates, bypassing ingredient brokers that cannot provide field-level provenance. This pattern concentrates in North American premium pet nutrition, where B Corp certification and carbon accounting disclosures pressure supply chain transparency.
Yucca Extract Material Market Segmentation
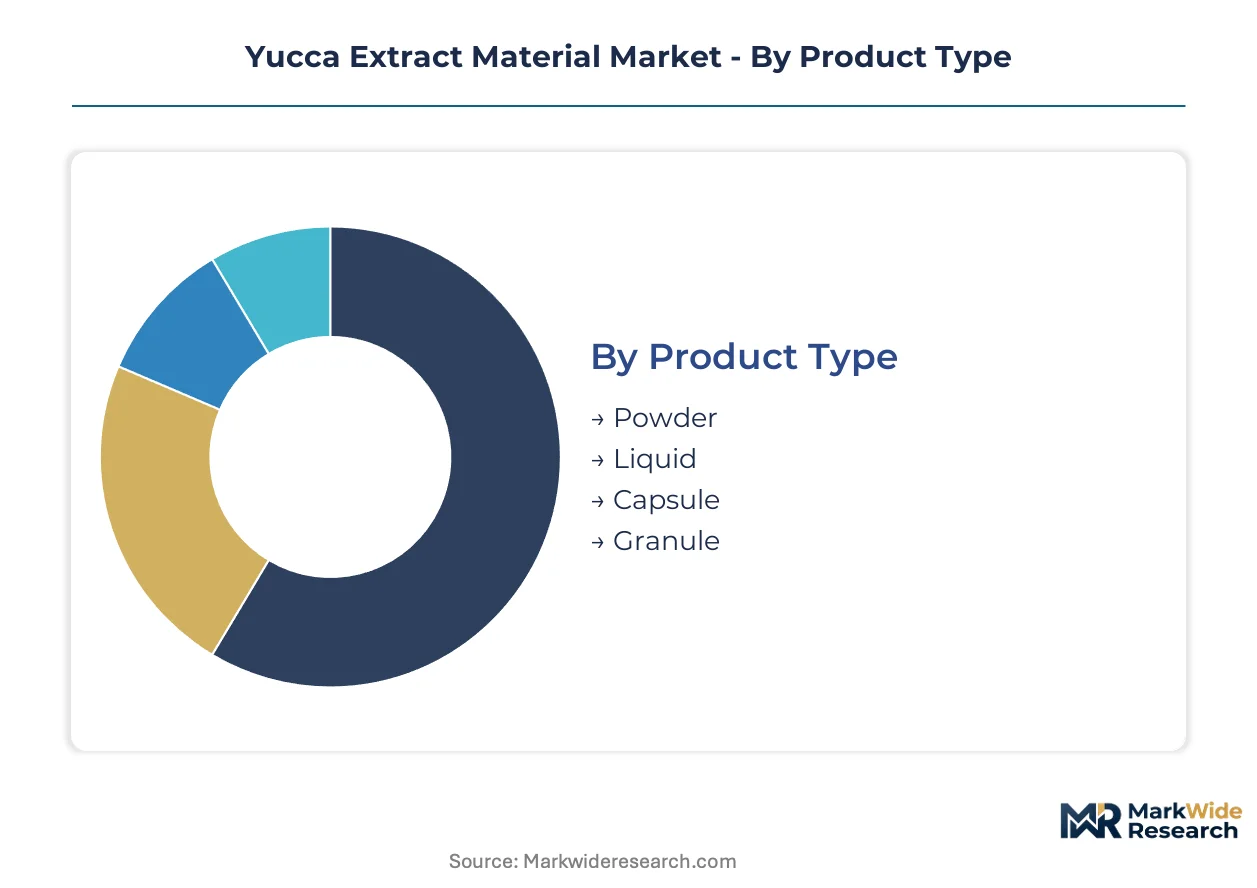
Yucca extract material segments by physical form, end-use industry, functional application, and packaging configuration. Each dimension carries distinct margin profiles and regulatory pathways that shape supplier investment priorities.
Product Type:
Inventory velocity varies sharply across physical formats, with liquid extracts turning over fastest due to shorter shelf lives and just-in-time cosmetic manufacturing schedules.
- Powder:Spray-dried or freeze-dried saponin concentrates at 10-60% standardization, offering superior stability in dry premix systems. Pet food compounders in the United States specify powder grades for kibble surface applications where flowability and caking resistance prove critical.
- Liquid:Aqueous or hydro-alcoholic solutions with immediate solubility, prized for cold-process cosmetic emulsification where heat-sensitive actives demand aqueous incorporation. Indie beauty brands specify liquid yucca surfactants for clean-label shampoo and cleanser formulations.
- Capsule:Pre-measured gelatin or vegetable cellulose shells containing standardized saponin powder, targeting direct-to-consumer supplement channels with dosing convenience.
- Granule:Agglomerated particles engineered for bulk feed handling, reducing dust generation during pneumatic conveying at animal feed mills.
Powder anchors the volume base while liquid gains share at the steepest rate.
End User:
Margin concentration follows regulatory complexity, with pharmaceutical and cosmetic channels commanding premium pricing against commoditized agricultural applications.
- Food Industry:GRAS-affirmed yucca extracts function as natural foaming agents in beverage systems and ammonia binders in protein processing, with FDA self-affirmation pathways accelerating ingredient approvals for functional food developers.
- Cosmetics:Formulators leverage yucca saponins as biosurfactants in sulfate-free personal care, with ECHA REACH registration requirements tightening substance characterization for EU market access.
- Pharmaceuticals:Standardized steroidal saponin fractions undergo USP monograph compliance for anti-inflammatory and cholesterol-management indications, though clinical validation timelines extend commercialization horizons.
- Agriculture:Livestock confinement operators deploy yucca extracts for ammonia binding in poultry and swine housing, with EPA pesticidal claim evaluations governing efficacy marketing.
Agriculture generates the highest tonnage throughput while cosmetics delivers the steepest margin expansion trajectory.
Application:
Customer technical requirements diverge by use case, with dietary supplements demanding certificate-backed standardization and animal feed prioritizing cost-efficient bulk supply.
- Dietary Supplements:Capsule and tablet formats with HPLC-verified saponin content support structure-function claims, with USP verification programs enabling premium positioning in practitioner channels.
- Animal Feed:Bulk powder and granule incorporation into premix systems targets odor control and digestive efficiency in monogastric livestock, with FAMI-QS certification governing European compounder procurement.
- Functional Foods:Beverage emulsification and protein texturization applications exploit yucca surfactant properties, with clean-label positioning driving replacement of synthetic polysorbates.
- Personal Care:Shampoo, body wash, and facial cleanser formulations specify yucca-derived foaming agents for sulfate-free and naturally positioned product lines.
Animal feed commands the volume base while personal care climbs the fastest.
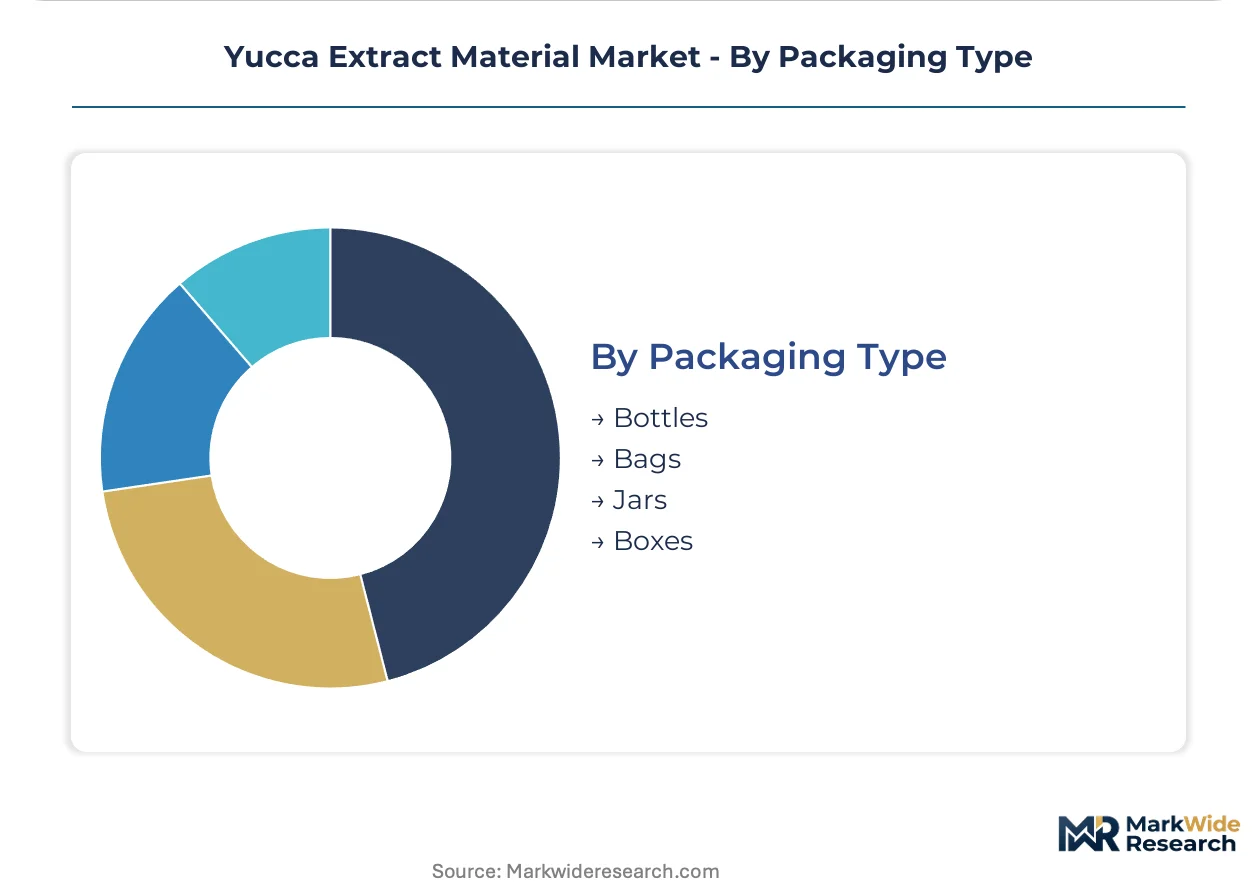
Packaging Type:
Handling economics and shelf-life requirements dictate format selection, with bulk bags dominating industrial procurement and unit-dose bottles capturing retail supplement channels.
- Bottles:Amber glass or HDPE containers with desiccant closures protect liquid extracts from oxidation, serving cosmetic laboratories and small-batch supplement manufacturers.
- Bags:Multi-wall paper or woven polypropylene bulk packaging enables pneumatic discharge at feed mills and food processing facilities, with FIBC formats for 500-1000kg agricultural shipments.
- Jars:Wide-mouth polyethylene containers facilitate scoop-based powder dosing in consumer supplement and cosmetic DIY segments.
- Boxes:Folding carton secondary packaging with blister inserts serves retail pharmaceutical and premium cosmetic channels requiring shelf-ready presentation.
Bags dominate industrial procurement while bottles expand most quickly in direct-to-consumer channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA GRAS self-affirmation pathways and USDA organic certification programs accelerate yucca extract commercialization in North America, while REACH registration requirements and FSSAI formalization reshape competitive access in Europe and India respectively.
United States
Premium pet food manufacturers in Kansas and Missouri drive powder-grade procurement for odor-control applications in kibble formulations. FDA GRAS determinations govern entry into functional food and supplement channels, with self-affirmation pathways compressing approval timelines. Yucca cultivation clusters concentrate in Arizona and New Mexico desert zones, supplying toll extraction facilities in Texas with reduced inbound logistics costs.
Germany
Cosmetic formulators in Hamburg and Düsseldorf specify liquid yucca extracts for sulfate-free personal care lines targeting clean-label positioning. ECHA REACH registration requirements tighten substance characterization obligations for saponin mixtures entering EU cosmetic channels. Bavarian botanical distributors maintain regulatory dossiers that enable Asian and Latin American suppliers to access German compounders without direct compliance investment.
India
Domestic nutraceutical manufacturers in Maharashtra and Karnataka seek standardized saponin inputs for Ayurveda-inspired supplement formulations. FSSAI registration requirements formalize ingredient approval pathways, opening contract supply relationships with export-oriented extractors. Gujarat-based feed compounders evaluate yucca granules for ammonia binding in poultry operations, though adoption remains nascent relative to synthetic alternatives.
Canada
Health Canada oversight of Natural Health Product licensing shapes yucca extract entry into dietary supplement channels, with site licensing requirements for domestic repackagers. Prairie livestock operations in Alberta and Saskatchewan trial ammonia-binding applications in confined swine and poultry housing. Toronto-area cosmetic laboratories import liquid grades for indie beauty brand formulations emphasizing biosurfactant positioning.
Australia
TGA regulation of complementary medicines governs yucca extract inclusion in practitioner-channel supplements, with strict evidence requirements for structure-function claims. Queensland and New South Wales feed mills evaluate granule formats for export-oriented beef feedlot operations targeting Middle Eastern markets. Sydney-based natural cosmetic formulators source liquid extracts for domestic sulfate-free hair care lines.
Yucca Extract Material Market Vendor Landscape
On the supply side, the industry is bifurcating between integrated desert farming operations and asset-light toll manufacturers, creating a tiered structure where captive cultivation confers feedstock security against spot-market volatility. Three archetypes dominate: vertically integrated cultivator-extractors with Southwest US land positions; contract-focused botanical specialists leveraging third-party organic certification; and regional granule processors serving agricultural feed channels. Competitive moves concentrate on extraction automation investments and multi-jurisdiction certification stacking to qualify for multinational ingredient procurement.
Within the integrated cultivation tier, Desert King International anchors supply security through captive desert farming and extraction infrastructure spanning powder and liquid grades. Ingredients by Nature LLC occupies a specialized position emphasizing organic certification and kosher/halal compliance for dietary supplement channel access. Baja Yucca Company represents the agricultural-format specialization vector, concentrating granule production for animal feed compounders prioritizing handling flowability. These three entities exemplify divergent strategic postures: upstream control versus certification-driven differentiation versus format-specific scale.
| Leading Market Players |
|---|
| Desert King International |
| Naturex Group |
| Baja Yucca Company |
| American Extracts |
| Ingredients by Nature LLC |
| Avitech Nutrition Pvt. Ltd |
| Nova Microbials |
| Garuda International Inc. |
| Ultra Bio-Logics Inc. |
| Others |
Supply Flow & Price Mechanics
Undercapacity at Arizona and New Mexico toll extraction facilities drives supplier pricing power while forcing buyers into longer contract terms, compressing margins for pet food compounders locked into synthetic additive substitution timelines.
Pricing Analysis
Certification level creates the primary spread between USDA Organic NOP-compliant extracts and conventional grades, with kosher and halal accreditations layering additional premiums. Three-tier pricing structure across premium, standard, and economy levels reflects saponin standardization thresholds and solvent recovery protocols. Cost compression in standard powder grades is intensifying because organic ethanol input costs track agricultural commodity volatility. Animal feed compounders exhibit highest price sensitivity due to thin margins in bulk premix operations, while dietary supplement channels absorb premiums for HPLC-verified standardization.
Supply Chain Analysis
Contract manufacturing concentrates at Desert King International's integrated Arizona facilities and Texas-based toll processors serving mid-tier botanical specialists. Feedstock draws from domestic Southwest cultivation clusters and limited Mexican wild-harvest operations, with solvent inputs resting on North American ethanol supply chains. Single-source vulnerability concentrates in mature Yucca schidigera stands facing drought-induced harvest variability. Distribution runs through ingredient brokers for smaller compounders and direct procurement relationships for premium pet nutrition manufacturers requiring blockchain-anchored provenance documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic surfactant and ammonia-binding chemistry poses a persistent substitution threat that yucca extract incumbents must neutralize through certification stacking and formulation performance validation.
For Market Incumbents: Build regulatory moats through simultaneous GRAS self-affirmation, USDA Organic certification, and FSSAI registration to disqualify smaller competitors from multinational procurement. Deepen upstream control over Arizona cultivation leases to secure feedstock against drought-cycle volatility. Accelerate supercritical CO2 extraction automation to compress batch-to-batch variability and defend against synthetic additive price competition.
For New Entrants and Emerging Players: India's Maharashtra and Karnataka nutraceutical corridors offer underpenetrated white-space for Ayurveda-positioned saponin suppliers with FSSAI-registered inputs. European cosmetic channels present secondary entry points through REACH-registered liquid extracts for sulfate-free personal care. Pursue kosher and halal certification as the primary go-to-market angle to differentiate from commodity-grade competitors in dietary supplement distribution.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across toll manufacturing sub-segments as modular CO2 extraction units reduce scale thresholds. Long-term viability favors vertically integrated cultivator-extractors with captive desert land positions and multi-jurisdiction regulatory dossiers. Acquisition targets should demonstrate existing organic certification infrastructure and established relationships with premium pet food compounders. Watch for FDA enforcement actions on GRAS self-affirmation documentation as an inflection signal for compliance-cost escalation.
| Strategic Initiative | Industry Significance |
|---|---|
| USDA Organic Certification Investment | NOP-compliant extraction processes command 15-30% price premiums in supplement channels. |
| Supercritical CO2 Extraction Scale-Up | Inline near-infrared monitoring reduces solvent waste and compresses quality assurance turnaround times. |
| FSSAI Registration Pathway Completion | Formalized approval opens contract supply with Maharashtra nutraceutical manufacturers. |
| Blockchain Provenance Infrastructure | Field-level harvest coordinates satisfy ESG reporting requirements from B Corp-certified pet food brands. |
| Multi-Jurisdiction Dossier Expansion | REACH registration enables EU cosmetic channel access without ceding margin to regulatory intermediaries. |
Methodological Framework
Cross-validation between primary interviews with extraction facility operators, pet food procurement directors, and cosmetic formulators and secondary validation through FDA GRAS notifications, USDA Organic Integrity Database records, and FSSAI registered ingredient listings anchors the qualitative findings. Customs data on yucca extract import volumes and SEC filings from publicly traded pet nutrition companies provided demand-side calibration. Bottom-up segmentation modeling and top-down market sizing triangulated volume and value estimates.
Calibration against historical saponin price indices and extraction capacity utilization rates informed the analytical framework across the projection horizon. Segmentation dimensions modeled include physical form, end-use industry, functional application, and packaging configuration, with saponin standardization tier as an industry-specific dimension. CAGRs were derived from regression analysis of adoption curves in pet food and cosmetic channels, incorporating solvent cost trajectories and regulatory approval timelines as forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by integrated cultivator-extractors or breakthrough synthetic surfactant cost reductions would shift outcomes. Quarterly review of Arizona drought indices, organic ethanol commodity prices, and FDA GRAS enforcement patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Irish Moss Market
Extracts
Ovalbumin Powder Market
Extracts
Helichrysum Oil Market
Extracts
Nootkatone Market
Extracts
Global Azadirachtin Market
Extracts
Black Fungus Extract Market
Extracts
Botanicals Market
Extracts
Global Magnolia Bark Extract Market
Extracts
Extracts and Distillates Market
Extracts
White Willow Bark Extract Market
Extracts
Solid Phase Extraction Market
Extracts
Functional Extract Market
Extracts
Global Aphrodisiac Powder Market
Extracts
CO2 Extract Market
Extracts
Bromelain Market
Extracts
Passion Flower Extracts Market