
 Aluminum Casting Market | 2026-2036
Aluminum Casting Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Casting Market Analysis
IATF 16949 certification is reorganizing supplier hierarchies in automotive aluminum casting, pushing sub-tier foundries toward unified quality management systems or exit. Nemak S.A.B. de C.V. anchors North American light-vehicle cylinder head supply through dedicated high-pressure die casting campuses. Georg Fischer Ltd. dominates gravity casting for commercial vehicle chassis nodes across European OEM networks. Ryobi Limited specializes in thin-walled transmission cases, leveraging its Japan-based R&D footprint for thermal management innovations.
Aluminum casting is a metal-forming process wherein molten aluminum alloys—typically A380, A383, or Silafont-36 grades—are poured into molds to produce near-net-shape components with wall thicknesses ranging from 0.5 mm in vacuum die casting to 50 mm in sand casting. The process serves primarily to reduce mass in transportation and energy systems while maintaining structural integrity under cyclic loading. Die casting captures the dominant share of automotive volume, though permanent mold casting commands superior margins in aerospace structural brackets where porosity tolerances tighten to ASTM E505 Grade A. Sand casting retains cost leadership for prototype runs and legacy engine blocks where tooling amortization spans decades.
The US EPA enforces National Ambient Air Quality Standards that limit particulate emissions from foundry cupolas, while REACH in Europe restricts hexavalent chromium in surface treatment chemistries used on cast housings. China's MEE implements dual carbon targets that cap energy intensity per ton of cast output, reshaping plant location decisions. Stakeholders must monitor how carbon border adjustment mechanisms redefine landed cost competitiveness between Asian export foundries and regional European suppliers.
Market Dynamics
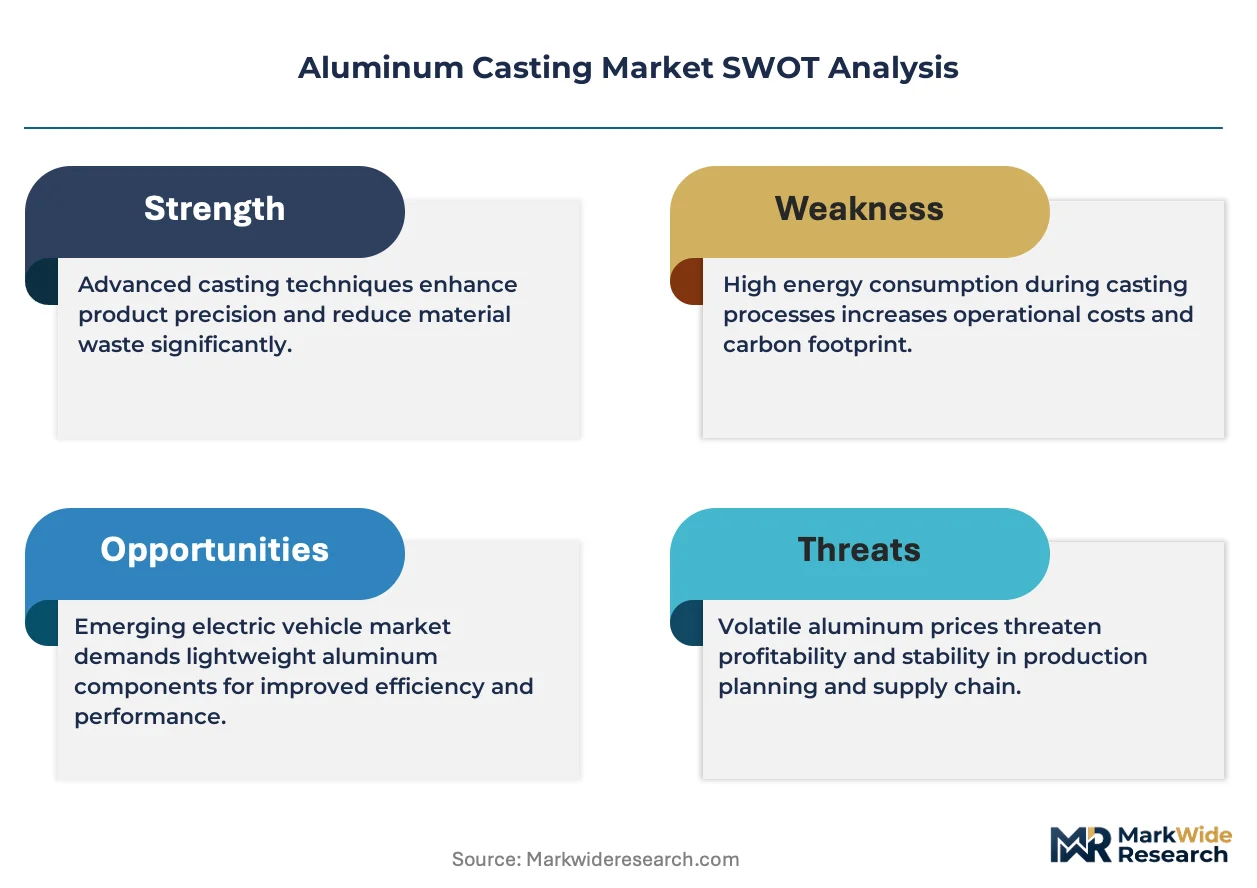
The aluminum casting sector confronts a structural squeeze between OEM lightweighting mandates and foundry energy-intensity caps, forcing simultaneous process reinvention and carbon footprint reduction.
Growth Catalysts
- EU F-Gas Regulation:Phase-down of hydrofluorocarbon coolants in automotive climate systems accelerates aluminum heat exchanger casting demand for lighter, more efficient thermal management architectures.
- EV platform proliferation:Battery enclosure and motor housing castings command thicker walls and tighter tolerances than internal-combustion equivalents, expanding addressable tonnage per vehicle.
- Silafont-36 alloy adoption:High-ductility die-cast grades enable single-piece body-in-white nodes that eliminate multi-part welding assemblies, compressing Bill of Materials for structural engineers.
Market Restraints
- Primary aluminum ingot volatility:LME price swings transmit directly to foundry margins within 30-60 day contract windows, compressing EBITDA for non-integrated operators.
- Scrap availability concentration:Automotive shredded scrap recovery clusters in Germany, China, and the United States, straining secondary alloy supply security for peripheral geographies.
- Silicon carbide substitution:Ceramic matrix composites displace aluminum in high-turbocharger housings above 180°C continuous operating temperatures.
Strategic Opportunities
- India commercial vehicle casting:Bharat Stage VI emission standards and domestic OEM localization mandates create greenfield demand for cylinder block and head foundries.
- Semi-solid rheocasting convergence:Thixomolding and new rheocasting process hybrids reduce porosity below ASTM E505 Grade B thresholds, opening aerospace bracket applications previously reserved for forgings.
- Carbon border adjustment arbitrage:EU CBAM implementation incentivizes low-carbon primary aluminum sourcing from hydro-powered smelters in Canada and Norway for European automotive Tier-1 contracts.
Industry Challenges
- IATF 16949 auditor scarcity:Certified lead auditors for automotive quality management systems command 40% fee premiums, extending certification timelines for sub-tier foundries by 4-6 months.
- Legacy ERP integration friction:Foundry-specific production planning modules resist seamless data handoff to OEM supplier portals, forcing middleware investments that strain sub-$50M revenue operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Casting Market |
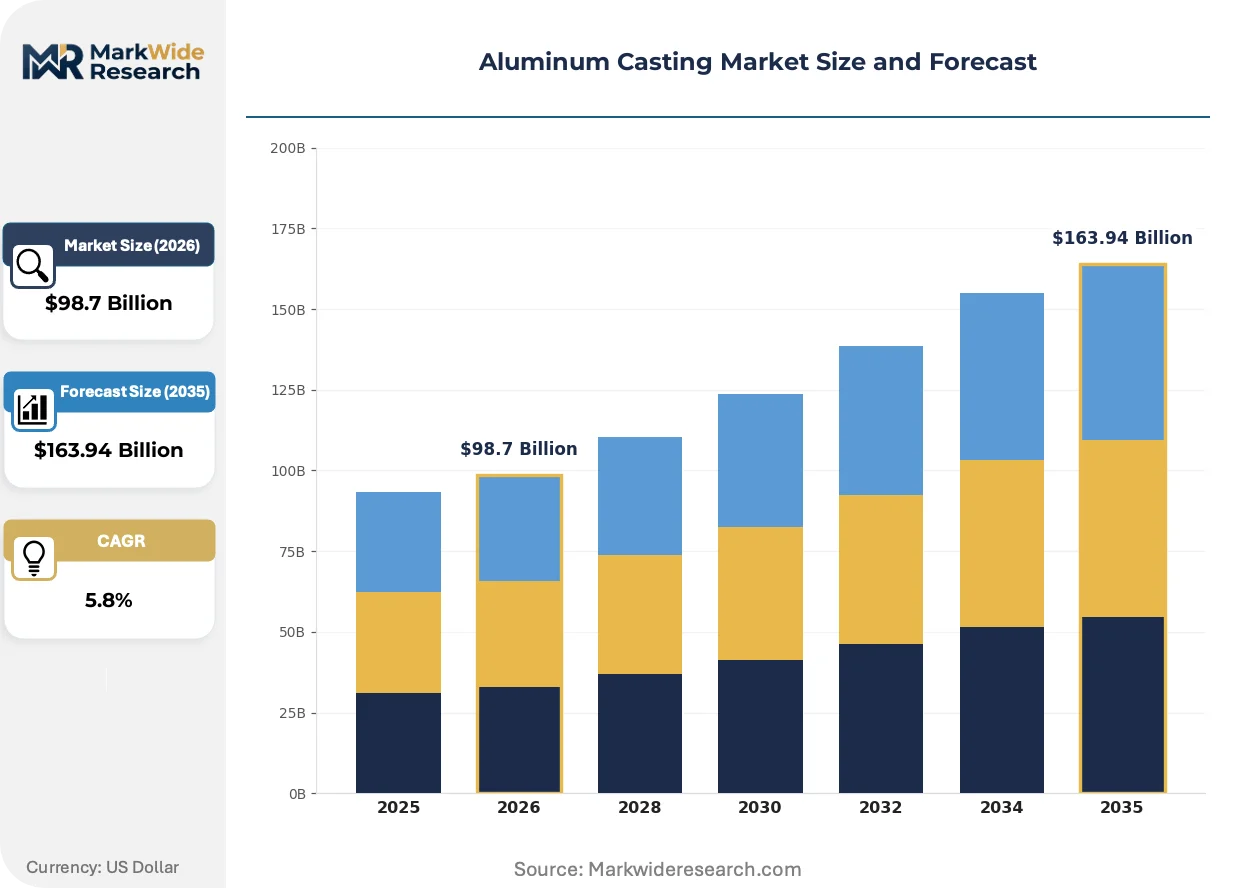
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $163.94 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Die Casting, Sand Casting, Permanent Mold Casting, Investment Casting Technology: High Pressure, Low Pressure, Gravity, Non-Ferrous Melting End User: Aerospace, Automotive, Electrical, Construction Application: Engine Components, Structural Parts, Housing, Heat Exchangers |
| Companies Covered | Alcoa Corporation, Ryobi Limited, Dynacast International, Georg Fischer Ltd., Nemak S.A.B. de C.V., Gibbs Die Casting Corp., Endurance Technologies Limited, Arconic Inc., Consolidated Metco Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Casting Market Emerging Trajectories
Process digitization and alloy formulation advances are compressing development cycles while regulatory carbon accounting forces material provenance transparency through the value chain.
Vacuum-assisted high-pressure die casting is bifurcating the structural component market. OEMs specify this process for Class A body panels and crash-critical nodes requiring sub-2% porosity. Tier-1 suppliers in Germany and Japan dominate installed capacity. The technology is bifurcating sourcing strategies between premium vacuum-capable foundries and commodity air-casting suppliers serving non-structural brackets.
China's MEE dual carbon enforcement tightens energy-intensity benchmarks for smelter-integrated foundries. Plants exceeding 13,500 kWh per ton of cast output face production curtailments during grid stress periods. Export-oriented operators in Shandong and Guangdong provinces are retrofitting regenerative thermal oxidizers and induction melting to maintain shipment schedules to European automotive customers.
Automotive OEMs now mandate cradle-to-gate carbon declarations for aluminum castings in RFQ packages. Procurement teams weight embodied CO2 at 15-20% of total evaluated price for battery tray and motor housing contracts. This preference shift is most visible in German and Swedish OEM supplier selections, where low-carbon primary aluminum commands 8-12% price premiums over regional benchmark ingot.
Aluminum Casting Market Segmentation
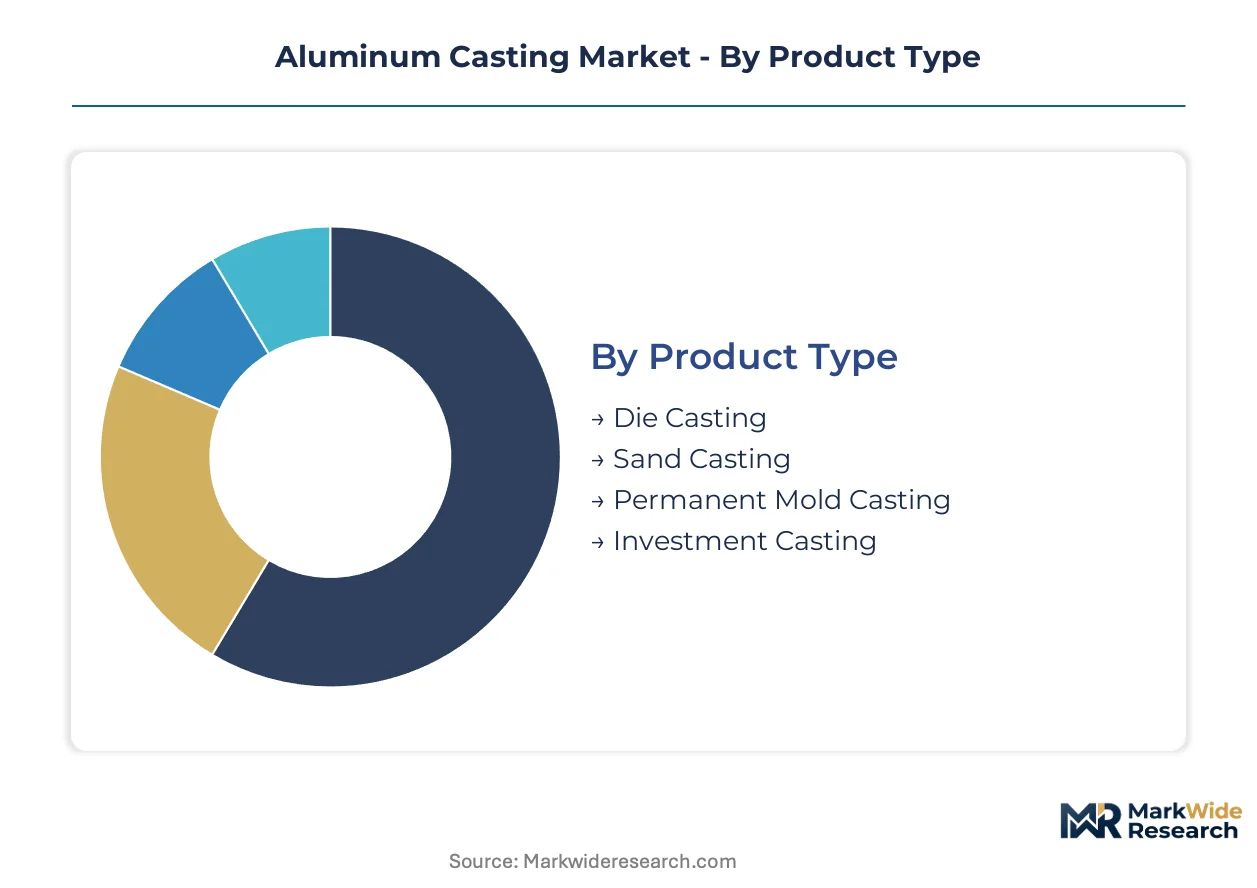
Process selection and end-use specifications in aluminum casting create sharply divergent margin profiles and capital requirements. Segmentation reveals where technology premiums concentrate versus where volume commoditization dominates competitive dynamics.
Product Type:
Die casting facilities cluster near OEM assembly plants in Germany, China, and the United States to minimize logistics costs for just-in-sequence delivery. Sand and investment casting maintain more dispersed footprints serving export markets and prototype development centers.
- Die Casting:High-pressure injection of molten aluminum into hardened steel dies produces thin-walled components with surface finishes suitable for Class A automotive panels. Demand concentrates in cylinder heads, transmission cases, and EV battery enclosures where porosity tolerances tighten to sub-2% specifications. OEM lightweighting mandates are accelerating conversion of multi-part welded assemblies to single-piece die-cast nodes.
- Sand Casting:Green sand or chemically bonded molds accommodate prototype runs and legacy engine blocks where tooling amortization spans decades. Cost leadership for low-volume production and design flexibility retains foundry demand in commercial vehicle powertrain components and industrial machinery housings.
- Permanent Mold Casting:Gravity-fed metal molds deliver superior dimensional repeatability for aerospace structural brackets requiring ASTM E505 Grade A porosity standards.
- Investment Casting:Ceramic shell processes enable complex internal geometries for turbine blades and precision aerospace components where net-shape capability eliminates machining operations.
Die casting commands the established base. The steepest expansion runs through permanent mold casting as aerospace structural demand tightens quality thresholds.
Technology:
Capital intensity stratifies across process technologies, with high-pressure systems requiring 3-5x the equipment investment of gravity-based alternatives. Technology selection locks foundries into specific customer tiers and margin structures.
- High Pressure:Clamping forces exceeding 4,000 tons inject molten aluminum at velocities above 50 m/s, enabling 0.5 mm wall thicknesses in vacuum-assisted configurations. German and Japanese Tier-1 suppliers dominate installed capacity for structural automotive nodes requiring crash-energy absorption certification.
- Low Pressure:Controlled metal rise from pressurized crucibles yields superior internal integrity for wheels and suspension components subject to cyclic fatigue loading. Automotive OEMs specify this process for safety-critical chassis elements where X-ray inspection protocols apply.
- Gravity:Simple pouring mechanics minimize capital barriers for entry-level foundries serving construction hardware and general industrial castings.
- Non-Ferrous Melting:Induction and reverberatory furnace technologies govern energy efficiency and alloy chemistry control across all casting processes.
High pressure technology anchors mass-market automotive supply. Low pressure systems are climbing the fastest as EV suspension architectures multiply control-arm specifications per vehicle.
End User:
Customer concentration patterns split between localized just-in-time supply for automotive and distributed global sourcing for aerospace tier-one networks.
- Automotive:OEM lightweighting programs across powertrain and structural assemblies consume the dominant volume share. EV platform proliferation is expanding addressable tonnage per vehicle through battery enclosures and motor housings with thicker walls than internal-combustion equivalents.
- Aerospace:Structural bracket and landing gear component demand concentrates in precision-grade permanent mold and investment casting segments where NADCAP certification filters supplier eligibility.
- Electrical:Motor housings and heat sink applications require thermal conductivity optimization through specific alloy selection and controlled solidification rates.
- Construction:Façade systems, window frames, and infrastructure hardware utilize gravity and sand casting for architectural metalwork with lower mechanical performance requirements.
Automotive end-use commands the established base. Aerospace applications are gaining share fastest as airframe OEMs reshore critical component supply.
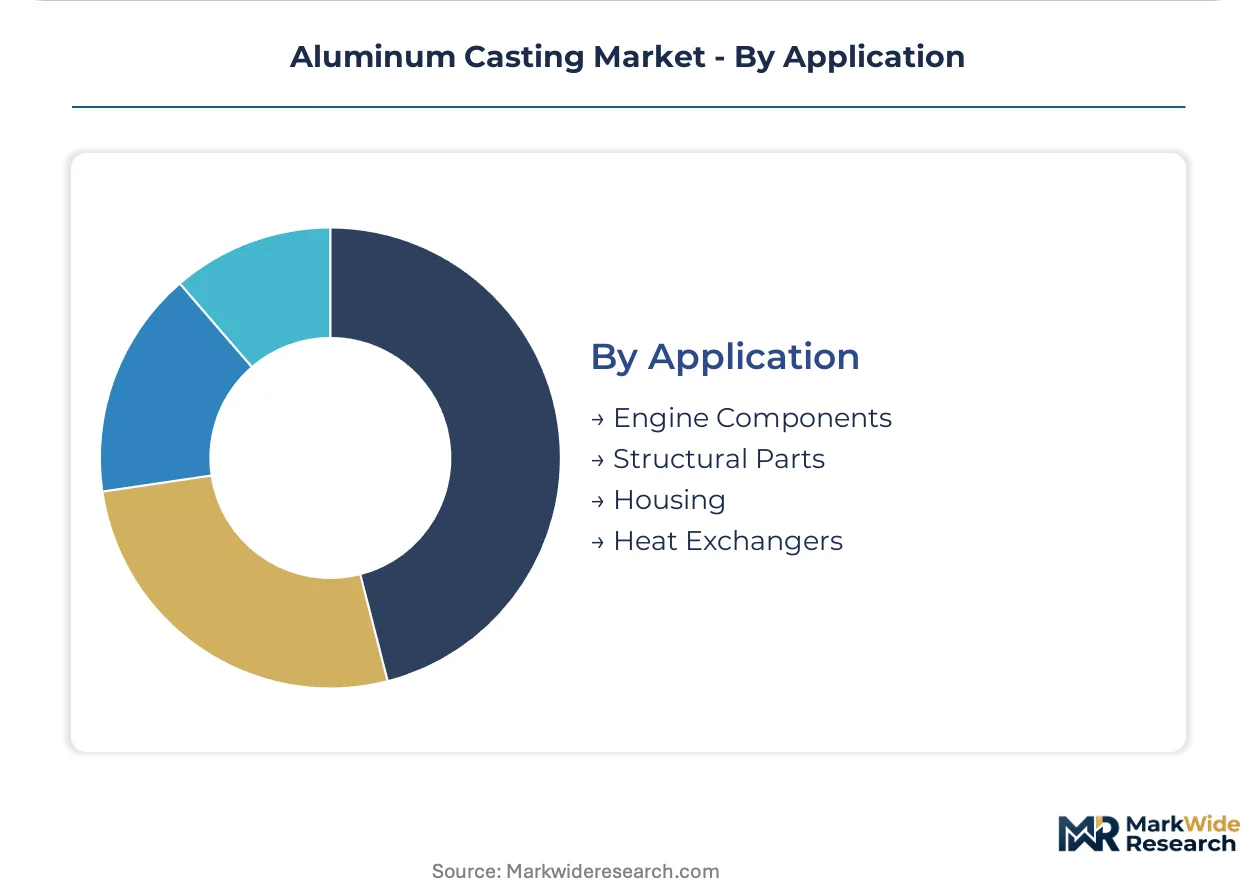
Application:
Functional performance requirements determine process selection and alloy grade, with thermal and structural applications commanding premium specifications over containment functions.
- Engine Components:Cylinder blocks, heads, and pistons require elevated temperature resistance and wear characteristics delivered through hypereutectic aluminum-silicon alloys. Foundries serving this segment maintain dedicated high-volume die casting campuses with integrated machining operations.
- Structural Parts:Body-in-white nodes, subframes, and crash management systems are converting to Silafont-36 high-ductility grades that enable single-piece casting of previously welded multi-part assemblies.
- Housing:Transmission cases, pump bodies, and electronic enclosures prioritize pressure tightness and dimensional stability over mechanical loading capacity.
- Heat Exchangers:F-Gas Regulation phase-down of hydrofluorocarbon coolants is accelerating demand for aluminum heat exchanger castings in lighter, more efficient thermal management architectures.
Engine components command the established base. Structural parts are expanding most quickly as OEMs compress Bill of Materials through casting consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's EU F-Gas Regulation enforcement and China's MEE dual carbon targets are redirecting foundry investment toward low-carbon smelter corridors in Canada and Norway, reshaping regional competitive positioning for automotive Tier-1 contracts.
Germany
Automotive OEM lightweighting mandates for EV battery enclosures and structural nodes concentrate demand in Bavaria and Baden-Württemberg. The EU F-Gas Regulation accelerates aluminum heat exchanger casting specifications for climate system architectures. Foundry clusters around Stuttgart and Munich are retrofitting vacuum-assisted high-pressure die casting capacity for Class A body panel contracts.
China
EV platform proliferation across BYD, NIO, and Xpeng supply chains expands addressable tonnage per vehicle through motor housings and battery trays. MEE dual carbon enforcement caps energy intensity at 13,500 kWh per ton of cast output, forcing Shandong and Guangdong export foundries to install regenerative thermal oxidizers. Yangtze River Delta smelter-integrated campuses are securing long-term European automotive contracts through carbon border adjustment arbitrage.
United States
Domestic OEM reshoring of critical component supply and Inflation Reduction Act clean energy incentives are attracting low-carbon primary aluminum sourcing. EPA National Ambient Air Quality Standards limit particulate emissions from foundry cupolas, compressing margins for non-integrated operators. Michigan and Ohio-based Tier-1 suppliers are expanding dedicated high-pressure die casting campuses for cylinder head and transmission case programs.
India
Bharat Stage VI emission standards and domestic OEM localization mandates from Tata Motors and Mahindra are creating greenfield demand for commercial vehicle cylinder blocks and heads. The central government's PLI scheme for automotive components subsidizes foundry capacity expansion in Maharashtra and Tamil Nadu. Pune and Chennai industrial corridors are attracting Japanese and Korean joint ventures for powertrain casting operations.
Japan
Thin-walled transmission case specifications for hybrid powertrains leverage domestic R&D footprints in thermal management innovation. METI carbon neutrality roadmaps pressure foundries to transition from cupola to induction melting. Toyota City and Nagoya-based supplier networks are consolidating Silafont-36 alloy development for single-piece body-in-white nodes.
Aluminum Casting Market Vendor Landscape
Player mix skews toward integrated Tier-1 automotive suppliers with captive smelter linkages and specialized aerospace-grade permanent mold operators. The structure bifurcates between premium vacuum-capable foundries serving structural automotive nodes and commodity air-casting suppliers filling non-structural bracket demand. Three archetypes dominate: smelter-integrated mass producers, precision aerospace specialists, and regional commercial vehicle suppliers. Competitive moves concentrate on backward integration into low-carbon primary aluminum sourcing and technology licensing for semi-solid rheocasting processes.
Within the integrated Tier-1 tier, Nemak S.A.B. de C.V. and Georg Fischer Ltd. exemplify divergent geographic and process specializations. Ryobi Limited occupies a position among precision die-cast specialists with Japan-based R&D anchoring. Alcoa Corporation represents the smelter-integrated archetype with upstream control over low-carbon primary metal supply chains. Gibbs Die Casting Corp. and Consolidated Metco Inc. sit within the North American commercial vehicle supplier cluster serving legacy powertrain programs.
| Leading Market Players |
|---|
| Alcoa Corporation |
| Ryobi Limited |
| Dynacast International |
| Georg Fischer Ltd. |
| Nemak S.A.B. de C.V. |
| Gibbs Die Casting Corp. |
| Endurance Technologies Limited |
| Arconic Inc. |
| Consolidated Metco Inc. |
| Others |
Supply Flow & Price Mechanics
Silafont-36 alloy substitution for welded steel assemblies is redrawing procurement geography toward hydro-powered smelter corridors in Canada and Norway while compressing foundry margins through elevated scrap recovery premiums. This material transition simultaneously elevates carbon-adjusted landed costs for Asian export foundries and rewards European Tier-1 suppliers with captive low-carbon primary aluminum sourcing.
Pricing Analysis
Certification level (IATF 16949 vs. legacy QS-9000) creates the primary spread between premium vacuum-capable structural foundries and commodity air-casting suppliers. Contract structures favor long-term offtake agreements with LME-linked escalators for primary ingot, while secondary alloy premiums reflect shredded scrap availability concentration in Germany, China, and the United States. Pricing pressure stems from OEM procurement teams weighting embodied CO2 at 15-20% of evaluated price for battery tray contracts. Volume-scale buyers in German automotive OEM networks exhibit lowest price sensitivity, while sub-$50M revenue operators in peripheral geographies face acute margin compression.
Supply Chain Analysis
Just-in-sequence inventory strategies dominate automotive die casting, with foundry campuses clustering within 150 kilometers of OEM assembly plants in Germany, China, and the United States. Raw material supply draws from hydro-powered primary aluminum in Canada and Norway, automotive shredded scrap recovery networks, and silicon carbide ceramic precursors for high-temperature applications. Single-source vulnerability concentrates in vacuum-assisted high-pressure die casting equipment, where German and Japanese Tier-1 suppliers control installed capacity for structural node certification. Distribution runs through dedicated supplier portals with embedded carbon accounting modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EV platform proliferation represents a structural inflection, with battery enclosure castings commanding thicker walls and tighter tolerances than internal-combustion equivalents, expanding addressable tonnage per vehicle while forcing simultaneous process reinvention and carbon footprint reduction.
For Market Incumbents: Shield core cylinder head and transmission case programs through backward integration into low-carbon primary aluminum sourcing from hydro-powered smelters. Certify additional vacuum-assisted high-pressure die casting capacity to capture Class A body panel contracts as OEM lightweighting mandates intensify. Defensive consolidation should prioritize IATF 16949 auditor training pipelines to compress certification timelines for sub-tier acquisitions. For New Entrants and Emerging Players: Anchor in India's commercial vehicle casting corridor, where Bharat Stage VI emission standards and PLI scheme subsidies create greenfield demand for cylinder block and head foundries. Target semi-solid rheocasting process licensing for aerospace bracket applications previously reserved for forgings. A technical partnership with established Japanese or German equipment suppliers accelerates NADCAP certification pathways. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive Tier-1 suppliers lacking captive smelter linkages and facing carbon border adjustment exposure. Five-to-ten year viability hinges on securing long-term offtake from hydro-powered primary aluminum producers. Monitor EU CBAM implementation timelines as the decisive inflection indicator for portfolio rebalancing toward low-carbon foundry assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Low-Carbon Primary Aluminum | Captures EU CBAM arbitrage for European automotive Tier-1 contracts. |
| Vacuum-Assisted High-Pressure Die Casting Capacity Expansion | Qualifies suppliers for Class A body panel and crash-critical node specifications. |
| Semi-Solid Rheocasting Process Licensing | Opens aerospace bracket applications with porosity below ASTM E505 Grade B thresholds. |
| IATF 16949 Certification Pipeline Investment | Compresses supplier onboarding timelines amid auditor scarcity premiums. |
| Regenerative Thermal Oxidizer Retrofit | Maintains shipment schedules to European customers under MEE dual carbon enforcement. |
Methodological Framework
Operator-level perspectives from foundry plant managers, OEM platform engineers, Tier-1 supplier procurement leads, and aftermarket service heads anchored the qualitative base. Primary fieldwork combined with secondary validation from SEC 10-K filings, customs and trade data, vehicle production databases, and IHS Markit registration data. Bottom-up capacity and utilization modeling triangulated against top-down demand segmentation across process technology, end-use industry, and regional production cluster dimensions.
Sensitivity analysis tested forecast robustness across primary aluminum price volatility scenarios, EV platform adoption curves, and regulatory enforcement intensity variations. Segmentation dimensions modeled included casting process type, alloy grade tier, propulsion architecture, content per vehicle, and OEM supplier tier. CAGRs derived from regression analysis of historical production data against projected vehicle build rates and lightweighting content trajectories. Industry-specific inputs incorporated smelter energy intensity benchmarks and carbon border adjustment mechanism phase-in schedules.
Material uncertainties — LME price swings, silicon carbide substitution rates in high-temperature applications, and IATF 16949 auditor availability — sit outside the modeled envelope. Forecasts reflect assumptions regarding dual carbon enforcement continuity and EV platform proliferation timelines. Revision becomes warranted when carbon border adjustment mechanism coverage expands beyond pilot phases or when semi-solid rheocasting process yields cross commercial viability thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Zinc Ingots Market
Metals
Global Mercury Market
Metals
Aluminum Powders Pastes and Flakes Market
Metals
Silver Cyanide Market
Metals
Global Copper Market
Metals
Rare Earth Metals Market
Metals
Tin Chloride Market
Metals
Carbon Steel Market
Metals
Global High Purity Titanium Powder Market
Metals
Aluminium Powder Market
Metals
Rubidium Market
Metals
Titanium Powder Market
Metals
Merchant Bar Quality (MBQ) Steel Market
Metals
High Purity Tungsten Market
Metals
Ferrosilicon Magnesium Market
Metals
High Purity Lead Market