
 Global Superconducting Wire Market | 2026-2036
Global Superconducting Wire Market Size, Share, and Industry Trends Forecast 2026-2036
Global Superconducting Wire Market Intelligence
Second-generation rare-earth barium copper oxide manufacturing is rewriting the cost-performance calculus for high-field magnet systems. Bruker Corporation leverages its cryogenic instrumentation heritage to dominate MRI-grade wire supply chains. Sumitomo Electric Industries anchors Asia-Pacific production through integrated niobium-titanium and REBCO tape capabilities. American Superconductor competes in grid-scale deployment with its Amperium HTS cable architecture.
Superconducting wire comprises electrically zero-resistance conductors, typically niobium-titanium alloys operating below 9.2 K or REBCO coated conductors requiring liquid nitrogen cooling at 77 K, engineered to carry kiloampere currents without resistive loss for high-field magnets and power infrastructure. Low Temperature Superconductors occupy the mature revenue base through decades of MRI magnet provenance, while High Temperature Superconductors capture the fastest expansion trajectory as cooling costs decline and power utility pilot projects validate grid reliability. Rare-Earth Barium Copper Oxide concentrates margin pools in the deployment segment where energy utilities and scientific laboratories commission bespoke cable installations.
FDA medical device regulations govern MRI system certification, directly conditioning wire purity and field stability requirements for equipment manufacturers. China's SAMR enforces GB standards on grid-connected superconducting apparatus, shaping market access for imported coated conductors. The EU Green Deal and F-Gas Regulation constrain cryogenic refrigerant selection, pressuring cooling system redesigns. Stakeholders must monitor which regulatory jurisdiction certifies first-quantum computing cryogenic interconnects, as that standard will propagate through allied national frameworks.
Market Dynamics
REBCO coated conductor manufacturing is compressing cooling costs and expanding addressable applications beyond liquid helium dependence, while China's dual carbon mandates pull grid-scale deployment forward faster than Western utility procurement cycles.
Growth Catalysts
- Healthcare infrastructure modernization:MRI system upgrades across aging hospital networks in Germany, Japan, and the United States are accelerating niobium-titanium wire replacement cycles and expanding high-field magnet installations.
- F-Gas Regulation:The EU's phasedown of hydrofluorocarbon refrigerants is forcing cryogenic system redesigns that favor liquid nitrogen-cooled REBCO architectures over conventional helium-based cooling loops.
- China's clean energy mandates:State Grid Corporation pilot projects in Beijing, Shanghai, and Shenzhen are validating superconducting fault current limiters and power cables for urban load centers.
Market Restraints
- Helium supply concentration:Qatar, Russia, and the United States control over 80% of global helium extraction, exposing MRI magnet maintenance costs to geopolitical supply disruptions and price volatility.
- REBCO substrate scarcity:High-purity nickel-tungsten tape and Hastelloy substrate production concentrates in Japanese and German metallurgical facilities, creating single-source dependencies for coated conductor manufacturers.
- Cryogenic infrastructure gap:Liquid nitrogen distribution networks remain underdeveloped outside East Asian industrial corridors, limiting HTS cable deployment to sites with captive liquefaction capacity.
Strategic Opportunities
- Fusion energy pilot programs:Commonwealth Fusion Systems and tokamak projects in Massachusetts, Oxfordshire, and Cadarache are commissioning kilometer-length REBCO magnet systems for plasma confinement.
- India grid modernization:The Central Electricity Authority's smart city initiatives and renewable integration targets create first-mover positioning for HTS fault current limiters in Mumbai, Delhi, and Bangalore substations.
- Quantum computing interconnects:Dilution refrigerator manufacturers in Finland, the Netherlands, and Colorado are specifying low-thermal-leakage superconducting ribbon for qubit control wiring.
Industry Challenges
- Cryogenic engineering talent scarcity:Universities in the United States, Germany, and Japan produce fewer than 200 specialized refrigeration engineers annually, constraining field service expansion for deployed systems.
- REBCO certification timelines:IEC 61788 standardization for coated conductor mechanical and electrical properties remains incomplete, delaying utility procurement approvals by 18-24 months.
- Legacy LTS integration friction:Niobium-titanium magnet retrofits require vacuum vessel redesigns incompatible with existing MRI gantry footprints, complicating hospital upgrade economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Superconducting Wire Market |
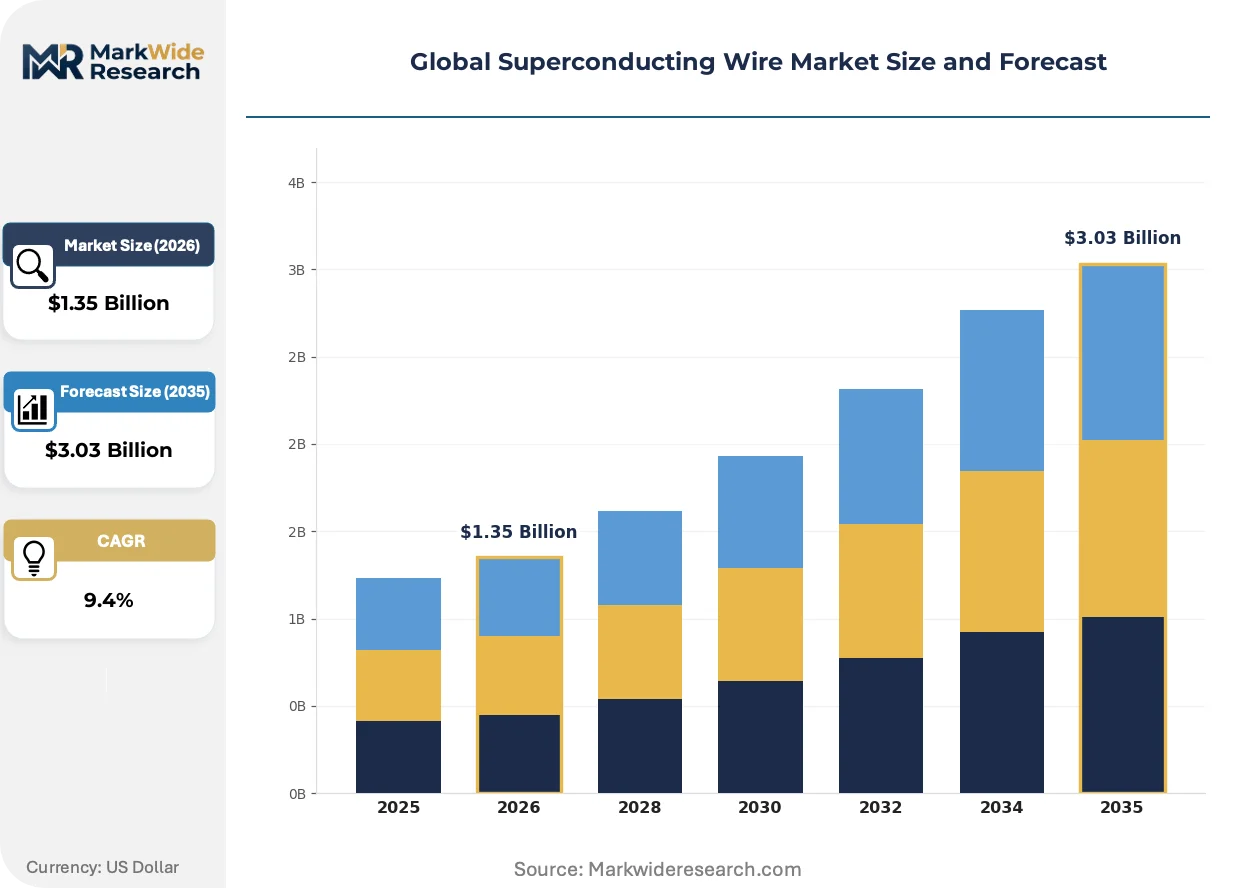
| Market Size in 2026 | $1.35 Billion |
| Market Size in 2035 | $3.03 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Temperature Superconductors, High Temperature Superconductors, Magnesium Diboride, Iron-Based Superconductors, Rare-Earth Barium Copper Oxide Application: Magnetic Resonance Imaging, Particle Accelerators, Power Transmission, Fault Current Limiters, Electromagnetic Propulsion Deployment: Manufacturing Plants, Research Laboratories, Energy Utilities, Transportation Systems, Defense Installations End User: Medical Equipment Manufacturers, Scientific Research Institutions, Power Grid Operators, Rail Network Providers, Aerospace Engineering Firms |
| Companies Covered | Bruker Corporation, Nexans, Sumitomo Electric Industries, Japan Superconductor Technology, LS Cable & System, Fujikura Ltd., American Superconductor, SuperPower Inc., Furukawa Electric Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Superconducting Wire Market Strategic Shifts & Innovations
Novel buffer layer deposition techniques and reel-to-reel manufacturing are collapsing REBCO production costs while expanding tape lengths, fundamentally altering competitive positioning between low-temperature and high-temperature superconductor architectures.
REBCO coated conductors employing metal-organic chemical vapor deposition for barium-copper-oxide epitaxy are achieving critical current densities exceeding 500 A/mm-width at 77 K. Scientific laboratories in Switzerland, the United States, and Japan are specifying these tapes for 20+ tesla insert magnets. The technology is rendering obsolete niobium-titanium dominance in fields above 12 tesla where helium cooling economics fail.
The EU F-Gas Regulation's 2030 phase-down targets for hydrofluorocarbon refrigerants are eliminating R-404A and R-507A from cryogenic cooling systems. Magnet manufacturers in France, Germany, and Italy are redesigning cryocooler architectures around helium recovery loops and liquid nitrogen pre-cooling stages. HTS cable projects in Amsterdam, Essen, and Milan are accelerating procurement to secure regulatory-compliant cooling infrastructure before 2027 compliance deadlines.
Utility procurement committees are unbundling superconducting cable installation from 20-year maintenance contracts, forcing wire suppliers to compete on capital cost alone rather than lifecycle performance. State Grid Corporation and Korea Electric Power Corporation tenders now separate cable supply from cryogenic system operation. This shift is most visible in East Asian urban grid reinforcement projects where municipal ownership of infrastructure creates complex multi-vendor coordination requirements.
Global Superconducting Wire Market Segmentation
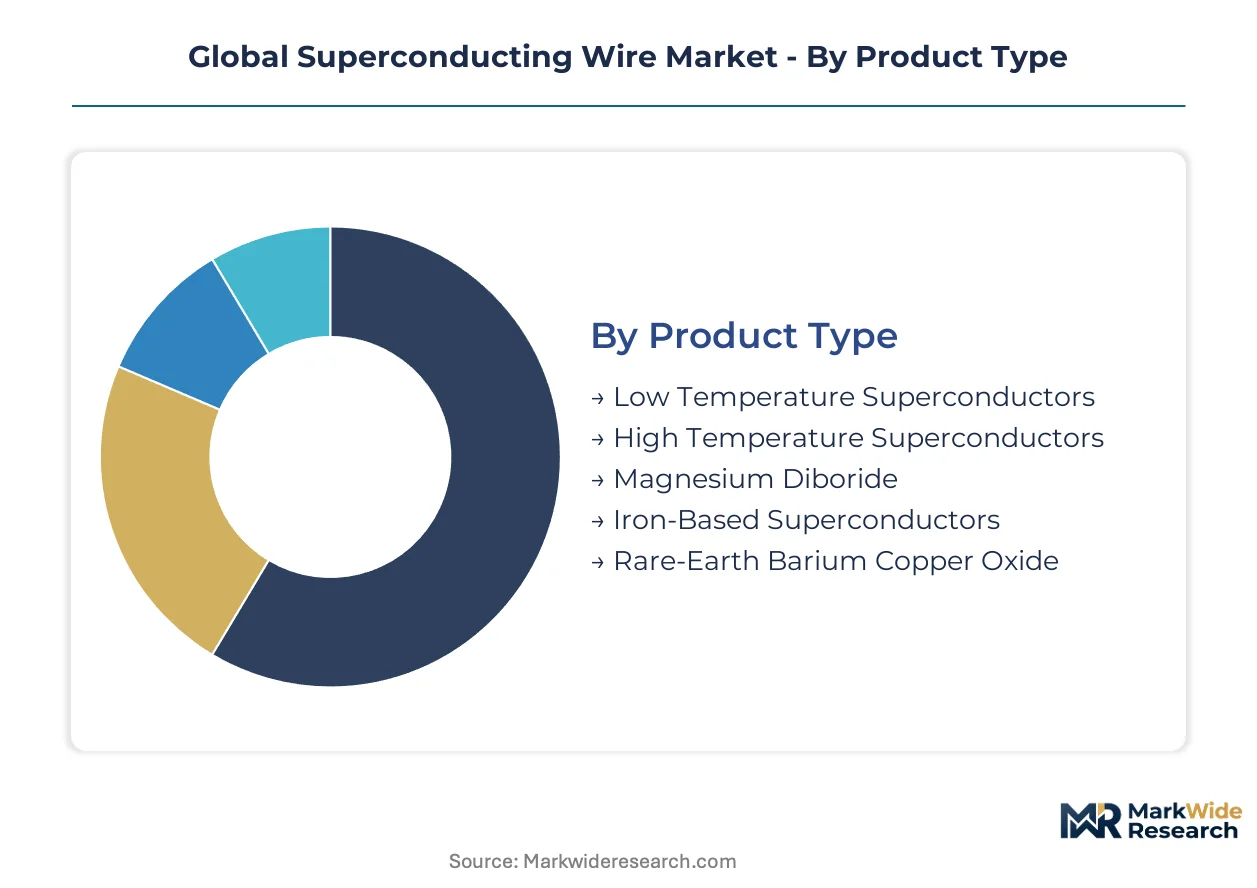
Superconducting wire segmentation reveals how cooling economics and field strength requirements partition demand across incompatible technical architectures. Each dimension—product chemistry, application physics, deployment environment, and end-user procurement—creates distinct margin pools and supplier qualification barriers.
Product Type:
Mature niobium-titanium alloys dominate installed base maintenance while emerging coated conductors capture expansion capital.
- Low Temperature Superconductors:Niobium-titanium alloys operating below 9.2 K with decades of MRI magnet provenance anchor replacement demand across German, Japanese, and American hospital networks. FDA device regulations govern wire purity specifications, conditioning supplier qualification timelines.
- High Temperature Superconductors:Rare-earth barium copper oxide and bismuth-based tapes cooled by liquid nitrogen at 77 K are eliminating helium dependence for grid-scale power infrastructure. China's State Grid Corporation pilot projects in Beijing and Shanghai validate fault current limiter reliability.
- Magnesium Diboride:Intermediate 39 K transition temperature suits compact cryocooler applications in scientific instrumentation.
- Iron-Based Superconductors:Emerging material class with favorable upper critical field properties under active development at Japanese national laboratories.
- Rare-Earth Barium Copper Oxide:Second-generation coated conductor architecture specified for 20+ tesla insert magnets and fusion energy confinement systems.
Low Temperature Superconductors handle the majority of throughput; High Temperature Superconductors are climbing the fastest on share.
Application:
Clinical imaging volume contrasts with scientific and infrastructure projects on procurement cycle length and technical specification rigor.
- Magnetic Resonance Imaging:High-field magnet systems for diagnostic imaging constitute the largest installed base, with niobium-titanium wire replacement cycles accelerating across aging European and North American hospital infrastructure. Equipment manufacturers specify exacting field stability tolerances.
- Particle Accelerators:Synchrotron and collider projects at CERN, DESY, and Brookhaven National Laboratory commission kilometer-scale magnet windings with customized current density profiles. Procurement committees unbundle cable supply from cryogenic system operation.
- Power Transmission:Urban grid reinforcement projects in Amsterdam, Essen, and Milan deploy HTS cables for high-density load centers.
- Fault Current Limiters:Grid protection devices commissioned by Korea Electric Power Corporation and India's Central Electricity Authority.
- Electromagnetic Propulsion:Naval and rail applications requiring pulsed field performance.
Magnetic Resonance Imaging commands the largest revenue pool; Particle Accelerators show steepest expansion trajectory on project commissioning activity.
Deployment:
Facility ownership structures determine whether wire suppliers compete on capital cost alone or lifecycle performance contracting.
- Manufacturing Plants:Industrial magnet applications for magnetic separation and materials processing.
- Research Laboratories:Scientific facilities in Switzerland, the United States, and Japan specify bespoke 20+ tesla insert magnets.
- Energy Utilities:State Grid Corporation and Korea Electric Power Corporation tenders now separate cable supply from cryogenic system operation, forcing pure capital cost competition.
- Transportation Systems:Rail network electrification and naval propulsion programs.
- Defense Installations:Classified electromagnetic applications with specialized security clearance requirements.
Energy Utilities concentrate the fastest-growing procurement volume; Research Laboratories maintain the most demanding technical specifications.
End User:
Procurement sophistication varies from regulated medical device manufacturers to fragmented scientific research institutions.
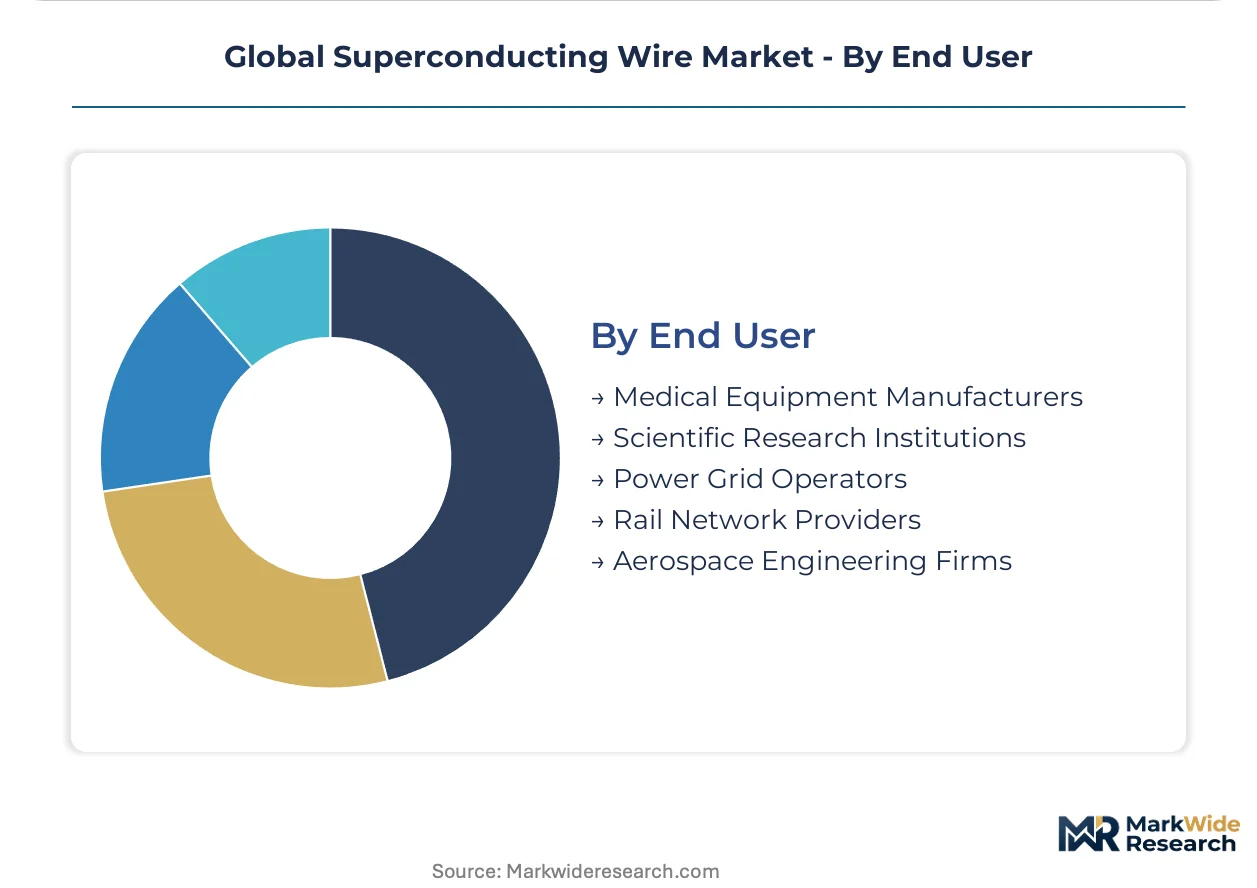
- Medical Equipment Manufacturers:Siemens Healthineers, GE HealthCare, and Philips specify MRI-grade wire under FDA and PMDA jurisdiction, with field stability requirements directly conditioning supplier selection.
- Scientific Research Institutions:CERN, RIKEN, and Argonne National Laboratory commission customized magnet systems with extended qualification protocols.
- Power Grid Operators:Municipal ownership in East Asian urban centers creates complex multi-vendor coordination for HTS cable projects.
- Rail Network Providers:Electromagnetic propulsion system operators in Japan and Germany.
- Aerospace Engineering Firms:Specialized contractors for defense and space applications.
Medical Equipment Manufacturers sustain the largest order flow; Power Grid Operators are gaining share fastest on clean energy mandate deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan exports niobium-titanium and REBCO tape to Germany's MRI manufacturers and China's State Grid Corporation, while South Korean cable fabricators supply HTS infrastructure across East Asian urban load centers.
United States
Fusion energy pilot programs in Massachusetts and Colorado commission kilometer-length REBCO magnet systems. The FDA governs MRI-grade wire purity specifications for equipment manufacturers. Greater Boston anchors quantum computing interconnect development with dilution refrigerator manufacturers specifying low-thermal-leakage ribbon.
Germany
Aging hospital networks in Bavaria and North Rhine-Westphalia accelerate niobium-titanium wire replacement cycles. The EU F-Gas Regulation phases down hydrofluorocarbon refrigerants by 2030, forcing cryocooler redesigns. Essen hosts HTS cable deployment for urban grid reinforcement with regulatory-compliant cooling infrastructure.
China
State Grid Corporation validates superconducting fault current limiters in Beijing, Shanghai, and Shenzhen substations. SAMR enforces GB standards on grid-connected superconducting apparatus. Coastal provinces concentrate cryogenic engineering capabilities and REBCO manufacturing investment.
Japan
High-purity nickel-tungsten tape production for REBCO substrates concentrates in metallurgical facilities. METI funding supports national laboratory development of iron-based superconductors. Osaka and Tokyo industrial clusters integrate niobium-titanium and coated conductor capabilities.
India
The Central Electricity Authority targets smart city initiatives and renewable integration for HTS fault current limiters. CEA procurement frameworks shape utility adoption timelines. Mumbai, Delhi, and Bangalore substations represent first-mover positioning for grid protection devices.
Global Superconducting Wire Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented supply tiers. The vendor base separates into cryogenic instrumentation heritage firms, integrated cable manufacturers, and coated conductor pure-plays. Three archetypes dominate: MRI-grade wire specialists, grid-scale HTS system integrators, and substrate-dependent tape fabricators. Capacity expansion and strategic partnerships constitute the dominant competitive moves as firms secure cryogenic engineering talent and REBCO substrate supply.
Among diversified industrial conglomerates, Sumitomo Electric Industries and Furukawa Electric Co. exemplify integrated production spanning niobium-titanium alloys through coated conductor architectures. Bruker Corporation occupies a position within the cryogenic instrumentation heritage tier, leveraging magnetic resonance expertise into wire supply chain participation. These three entities represent distinct strategic positions: materials-integrated Japanese manufacturers versus instrumentation-rooted Western specialists.
| Leading Market Players |
|---|
| Bruker Corporation |
| Nexans |
| Sumitomo Electric Industries |
| Japan Superconductor Technology |
| LS Cable & System |
| Fujikura Ltd. |
| American Superconductor |
| SuperPower Inc. |
| Furukawa Electric Co. |
| Others |
Cost & Logistics Intelligence
The Yokohama-Hamburg maritime corridor's container rate volatility feeds directly into REBCO tape landed costs, amplifying price spreads between Japanese substrate suppliers and European magnet manufacturers while compressing margins for non-integrated wire fabricators.
Pricing Analysis
Second-generation REBCO coated conductors command substantial premiums over first-generation bismuth-based tapes and mature niobium-titanium alloys. Three-tier pricing structure across premium, standard, and economy levels reflects critical current density certification tiers and helium-free cooling compatibility. Cost compression in standard-grade MRI wire is intensifying because Korean cable manufacturers are expanding niobium-titanium drawing capacity. Hospital procurement committees demonstrate highest price sensitivity, whereas fusion energy project developers prioritize field stability over unit economics.
Supply Chain Analysis
Tokyo Electron and Shin-Etsu Chemical hold captive capacity for high-purity nickel-tungsten substrate production, constraining coated conductor expansion for non-integrated competitors. Manufacturing concentrates in Japan, Germany, and coastal Chinese provinces where cryogenic engineering infrastructure has accumulated. Raw material flows draw from Qatari helium extraction, Australian rare-earth concentrate, and German metallurgical processing. Single-source vulnerability pervades Hastelloy substrate supply. Distribution runs through medical equipment OEMs for MRI-grade wire and state utility tenders for grid-scale cable.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Superconducting wire markets are approaching a platform-economics inflection as IEC 61788 standardization creates interoperability layers between magnet systems and cryogenic cooling architectures, enabling modular procurement unbundling.
For Market Incumbents: Harden substrate supply positions through backward integration into nickel-tungsten tape production or long-term offtake agreements with Japanese metallurgical facilities. Lock in cryogenic engineering talent pipelines with Swiss and German technical universities before fusion energy projects absorb available specialists. Defend against emerging Chinese coated conductor pure-plays by accelerating FDA certification timelines for next-generation REBCO architectures. For New Entrants and Emerging Players: Pursue fault current limiter deployment opportunities in Indian smart city substations where CEA procurement frameworks favor first-mover qualification over established brand preference. Target quantum computing interconnect supply to Finnish and Dutch dilution refrigerator manufacturers seeking low-thermal-leakage ribbon alternatives. Anchor go-to-market strategy around liquid nitrogen cooling system integration rather than competing on wire specifications alone. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates where superconducting wire divisions represent non-core revenue pools within broader cable or materials portfolios. Five-to-ten year viability hinges on REBCO cost curves intersecting with utility procurement thresholds for grid-scale deployment. Monitor IEC standardization completion as the critical inflection signal enabling utility procurement committee approvals.| Strategic Initiative | Industry Significance |
|---|---|
| REBCO Substrate Backward Integration | Captive nickel-tungsten supply from Japanese metallurgical facilities eliminates single-source vulnerability for coated conductor expansion. |
| Helium Recovery Loop Deployment | EU F-Gas Regulation compliance in German and Italian cryocooler redesigns preserves MRI magnet maintenance economics. |
| Quantum Computing Interconnect Qualification | Finnish dilution refrigerator specifications establish early-mover positioning for low-thermal-leakage ribbon standards. |
| India Grid Protection Pilot Execution | CEA smart city tenders in Mumbai and Delhi validate fault current limiter reliability for utility procurement committees. |
| Fusion Energy Magnet System Commissioning | Commonwealth Fusion Systems and tokamak projects in Massachusetts and Oxfordshire absorb kilometer-length REBCO capacity. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with cryogenic system engineers, utility procurement officers, MRI equipment manufacturers, and REBCO tape metallurgists; and secondary validation against IEC standardization drafts, FDA 510(k) filings for MRI magnets, State Grid Corporation tender announcements, and EU F-Gas Regulation implementation guidance. Bottom-up volume modeling triangulated against top-down market sizing from superconducting material consumption metrics.
Forecast inputs span product chemistry segmentation across LTS and HTS architectures, application physics from diagnostic imaging through plasma confinement, deployment environment ownership structures, and end-user procurement sophistication tiers. CAGRs were derived from elasticity modeling against clean energy mandate enforcement timelines and healthcare infrastructure replacement cycles. Fusion energy project commissioning schedules and quantum computing dilution refrigerator deployment curves provided industry-specific demand anchors.
Macroeconomic conditions sit as an overlay; deviation in rare-earth concentrate pricing, helium supply disruptions from Qatari or Russian sources, or IEC standardization delays would shift the trajectory. Quarterly review of utility tender award patterns, FDA certification completion rates, and cryogenic engineering graduate program enrollment is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Arc Ferrite Magnet Market
Metals
Palladium Market
Metals
Barium Market
Metals
Copper and Brass Flat Products Market
Metals
Silver Powder and Flakes Market
Metals
Silver Enamel Market
Metals
Global Mercury Market
Metals
Refined Nickel Market
Metals
Monel Alloy Market
Metals
Huntite Market
Metals
Ultrafine Tungsten Wire for Medical Applications Market
Metals
Osmium Market
Metals
High-End Copper Foil Market
Metals
Brazil Aluminum Market
Metals
Medical Metal Tubing Market
Metals
Copper Foil Market