
 Metal Molds Market | 2026-2036
Metal Molds Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Molds Market Intelligence
Chinese die-casting capacity is rebalancing toward integrated aluminum structural mold packages for electric vehicle platforms. Engel Austria GmbH leverages its Austrian engineering base to sustain premium positioning in multi-cavity injection systems. Wayken Rapid Manufacturing Limited differentiates through rapid tooling services bridging prototype-to-production gaps for North American industrial clients.
Metal molds are precision-engineered tooling systems, typically fabricated from hardened tool steels or aluminum alloys with tolerances measured in micrometers, designed to shape molten or softened materials into repeatable geometries through thermal cycling. CNC Machining and EDM dominate current fabrication workflows, though 3D Printing is displacing conventional methods for conformal cooling channel geometries that reduce cycle times. Injection Molds anchor the product mix due to polymer throughput volumes across consumer goods and electronics assembly, while Blow Molds occupy stable demand lanes in packaging solutions for beverage and personal care sectors.
EPA emissions frameworks and OSHA workplace exposure limits govern US mold shop operations, while REACH substance restrictions in Europe constrain coating chemistries and release agent formulations. China's GB standards and MIIT industrial upgrading mandates enforce energy efficiency benchmarks for domestic mold fabrication equipment. Stakeholders must monitor how dual carbon goals in China and EU Green Deal carbon border adjustments reshape sourcing decisions for steel feedstock and heat treatment services.
Market Dynamics
Automotive electrification is compressing mold design cycles as OEMs demand aluminum structural tooling for battery platform architectures. Chinese die-casting clusters and German precision engineering bases now compete directly for multi-cavity injection contracts previously segmented by geography.
Growth Catalysts
- EV Battery Housing Demand:Electric vehicle manufacturers in China and Germany require large-format aluminum molds for thermal management enclosures. MIIT industrial upgrading mandates accelerate domestic tooling capacity expansion.
- REACH Surface Treatment Compliance:European mold shops are retrofitting coating lines to meet ECHA substance restrictions on hexavalent chromium. This drives replacement demand for compliant hard-coating equipment.
- Conformal Cooling Adoption:Additive manufacturing of tool steel inserts with optimized channel geometries reduces cycle times for high-volume polymer components. Automotive Tier 1 suppliers lead implementation.
Market Restraints
- Tool Steel Price Volatility:H13 and P20 grade steel feedstock costs fluctuate with nickel and chromium spot markets. Japanese and Austrian specialty steel mills concentrate global supply.
- Heat Treatment Bottlenecks:Vacuum hardening and nitriding capacity concentrates in Germany, Japan, and select Chinese industrial zones. Lead times extend during peak automotive program launches.
- Polymer Substitution Threat:Advanced composites and carbon fiber reinforced plastics displace metal molds in aerospace structural applications. Boeing and Airbus qualification programs favor thermoset tooling.
Strategic Opportunities
- Mexico Nearshoring Expansion:Automotive OEMs relocate stamping and casting operations to Monterrey and Querétaro. Local mold fabrication capacity lags demand, creating import substitution potential.
- EU Green Deal Carbon Border Adjustments:Steel-intensive mold imports face embedded emissions tariffs. Austrian and Italian toolmakers with electric arc furnace feedstock gain cost positioning.
- Hybrid Manufacturing Convergence:CNC machining centers integrate in-situ laser cladding for localized surface hardening. Mold repair and modification services capture value from extended asset lifecycles.
Industry Challenges
- Multi-Axis Programming Shortage:Five-axis CNC and simultaneous EDM path generation require specialized CAM expertise. German and Swiss technical institutes produce insufficient graduates for current demand.
- ISO 9001 and IATF 16949 Certification Timelines:Automotive supplier qualification audits extend 12-18 months for new mold shops. Documentation burden favors incumbent certified facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Molds Market |
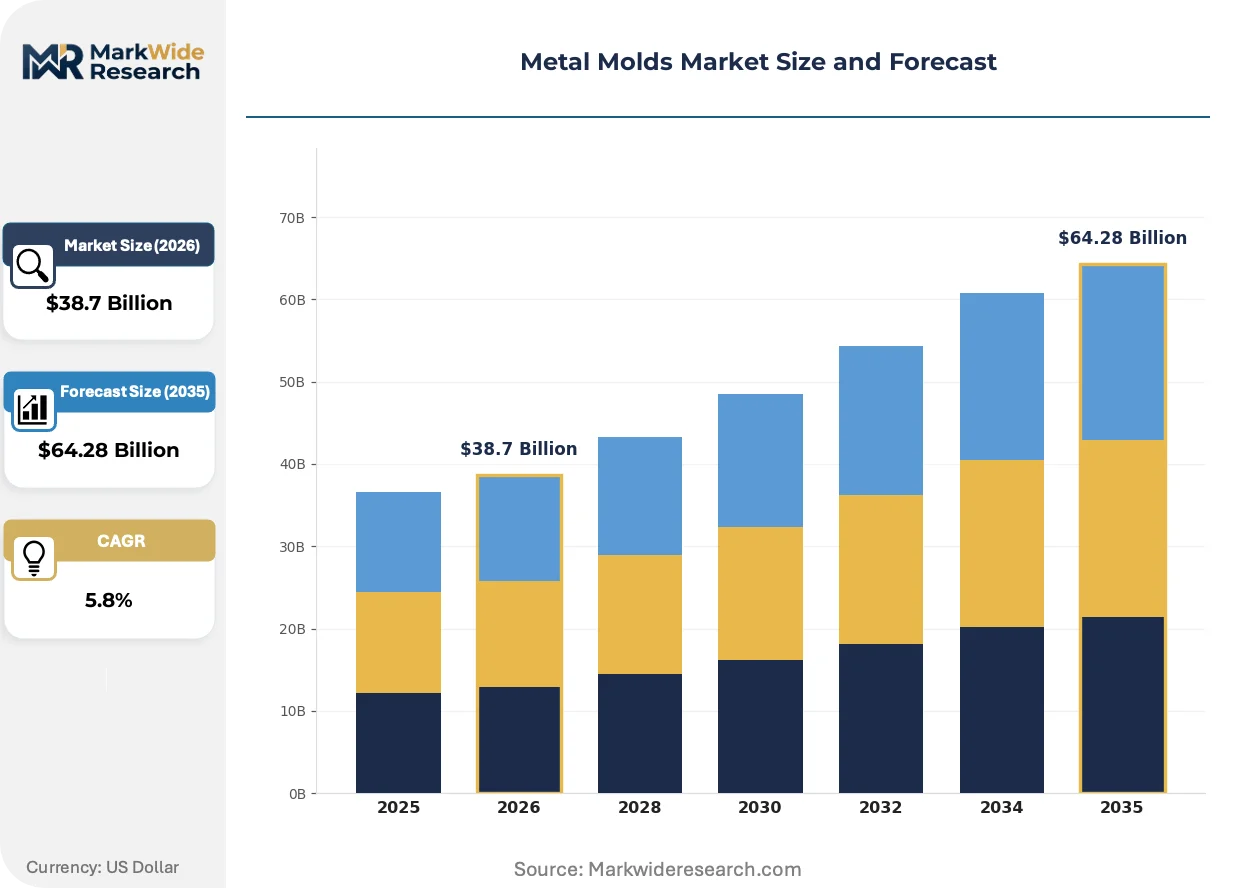
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection Molds, Die Casting Molds, Blow Molds, Compression Molds, Transfer Molds Technology: CNC Machining, EDM, 3D Printing, Laser Cutting, Water Jet Cutting Application: Consumer Goods, Electronics Assembly, Aerospace Components, Packaging Solutions, Automotive Supply Chain End User: Tooling Manufacturers, Tier-1 Suppliers, Vehicle Assemblers, Industrial Equipment Makers, Mold Design Firms |
| Companies Covered | Bunty LLC, JBJ Technologies Ltd., Engel Austria GmbH, GENSINI S.R.L., Wayken Rapid Manufacturing Limited, The Rodon Group, Colonial Machine, Enko AS, Bericap GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Molds Market Strategic Shifts & Innovations
Digital thread integration connects mold design, simulation, and shop floor execution. Real-time thermal monitoring and predictive maintenance are compressing unplanned downtime in high-volume production environments.
Metal additive manufacturing is absorbing conformal cooling channel fabrication that conventional drilling cannot achieve. Automotive lighting and consumer electronics molders adopt laser powder bed fusion for complex core inserts. The technology is absorbing cycle time reductions of 15-30 percent in thin-wall applications where thermal uniformity governs part quality.
REACH authorization requirements for nickel compounds and certain release agents tighten quarterly. Mold shops in Germany and Italy reformulate surface treatments to maintain export eligibility. Battery housing manufacturers face the steepest compliance costs as anodizing and passivation chemistries require substitution.
Buyer consolidation among automotive Tier 1 suppliers concentrates mold procurement decisions. Magna, Bosch, and Continental now operate centralized tooling boards that bypass traditional distributor networks. German and Chinese industrial clusters witness direct OEM-to-fabricator contracting that disintermediates regional trading houses.
Metal Molds Market Segmentation
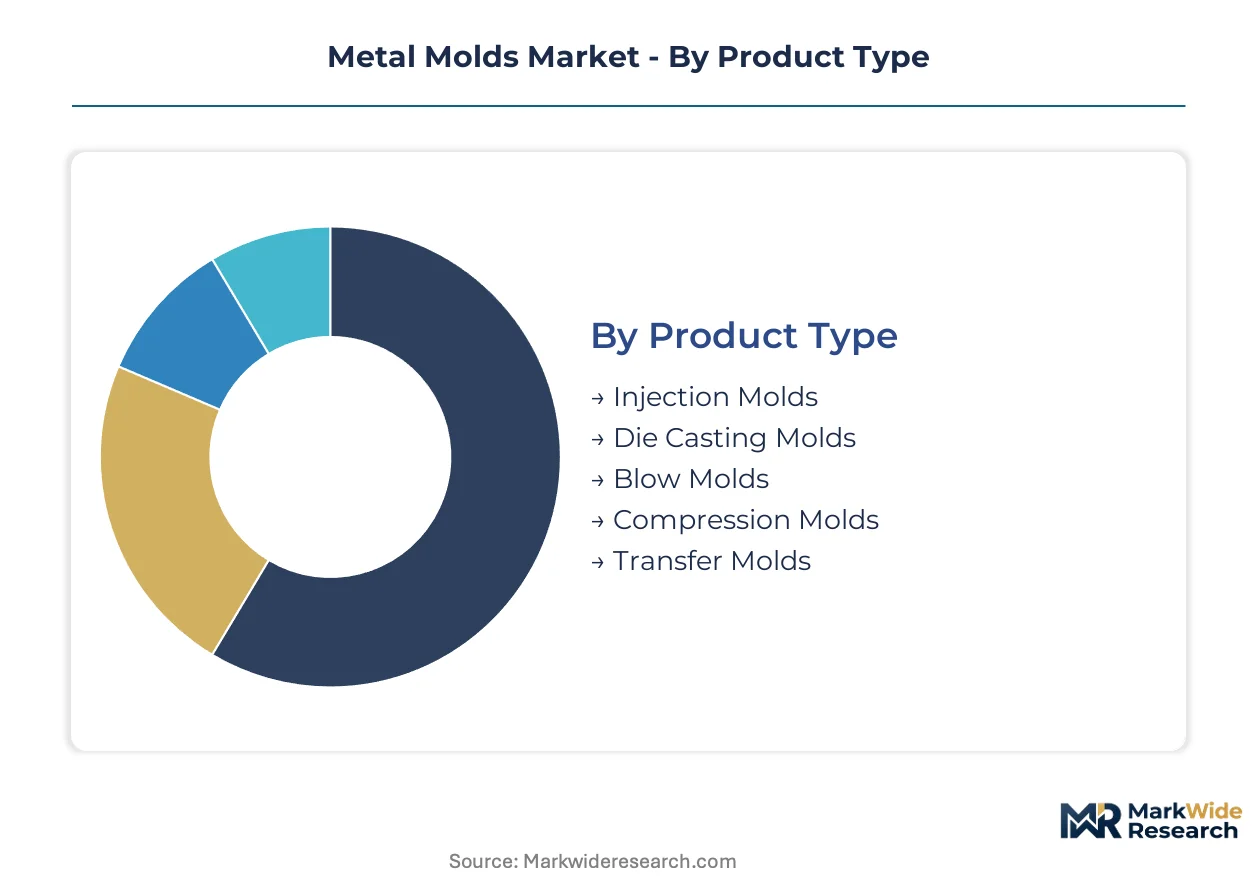
Metal mold procurement decisions cluster around thermal cycling demands, geometric complexity, and volume economics. Each segmentation dimension reveals distinct upgrade cycles and supplier capability requirements that reshape competitive positioning across fabrication workflows.
Product Type:
Replacement cycles vary dramatically by thermal load and mechanical wear patterns, with high-pressure aluminum tooling requiring more frequent refurbishment than polymer-focused systems.
- Injection Molds:These precision steel cavities handle thermoplastic and thermoset polymers under sustained thermal cycling. Automotive lighting manufacturers in Germany and consumer electronics assemblers in China dominate order books, driven by thin-wall component geometries that demand multi-cavity tooling.
- Die Casting Molds:Hardened tool steel inserts withstand molten aluminum and magnesium pressures exceeding 1,000 bar. Battery housing programs for electric vehicle platforms in China and Germany are compressing design-to-delivery timelines for large-format structural molds.
- Blow Molds:Aluminum and steel tooling shapes hollow containers through controlled air pressure expansion. Beverage packaging lines in Mexico and personal care manufacturers in Italy sustain steady demand for high-cavitation PET bottle molds.
- Compression Molds:Vertical clamping systems process thermoset composites and rubber compounds under heat and pressure. Aerospace seal manufacturers and electrical insulator producers specify these for fiber-reinforced geometries.
- Transfer Molds:Intermediate systems move preheated material into closed cavities for precision rubber and silicone parts. Medical device manufacturers and industrial gasket producers favor these for flash-free finishing requirements.
Injection Molds sits at the top of the volume ranking, with Die Casting Molds climbing the fastest.
Technology:
Capital intensity and skill thresholds separate premium fabrication methods from commoditized cutting operations, with additive systems commanding margins that conventional machining cannot match.
- CNC Machining:Five-axis milling centers remove material from hardened steel blocks with micrometer precision. German and Japanese machine tool builders dominate the installed base, though Chinese equipment makers are gaining share in mid-tier accuracy segments.
- EDM:Electrical discharge machining erodes complex geometries and fine details that cutting tools cannot access. Wire and sinker variants handle hardened steels without thermal distortion, serving mold repair shops and precision cavity fabrication.
- 3D Printing:Laser powder bed fusion builds conformal cooling channels and lattice structures impossible through conventional methods. Tool steel and copper alloy printing reduces cycle times for automotive lighting and electronics housings.
- Laser Cutting:High-power fiber lasers slice through thick steel plates for mold base preparation and rough shaping operations. Speed advantages favor large-format automotive tooling where geometric precision requirements are relaxed.
- Water Jet Cutting:Abrasive water streams cut heat-sensitive materials without thermal damage. Mold base manufacturers and prototype shops employ these for aluminum alloy preparation and stack plate fabrication.
CNC Machining commands the largest installed base, while 3D Printing is expanding most quickly in conformal cooling applications.
Application:
End-use durability requirements and regulatory exposure determine material specifications and surface treatment investments across customer segments.
- Consumer Goods:High-cavitation molds for household appliances, personal care items, and toys prioritize cycle time optimization over extreme durability. Chinese mold shops dominate volume production for global brand owners.
- Electronics Assembly:Miniaturized connectors, housings, and thermal management components demand sub-micron tolerances. Smartphone and laptop manufacturers in Taiwan and South Korea drive precision tooling specifications.
- Aerospace Components:Titanium and Inconel tooling for composite curing and metal forming must withstand autoclave pressures and thermal cycling. Boeing and Airbus qualification programs impose extensive certification documentation.
- Packaging Solutions:Beverage, food, and pharmaceutical containers require FDA-compliant surface finishes and rapid changeover capabilities. Italian and German specialists lead thin-wall PET and barrier film tooling.
- Automotive Supply Chain:Interior trim, lighting, powertrain, and structural components span the widest mold size and complexity range. Tier-1 suppliers consolidate procurement through centralized tooling boards.
Automotive Supply Chain generates the highest absolute tooling spend, with Electronics Assembly gaining share fastest on miniaturization trends.
End User:
Technical sophistication and in-house capability determine whether customers specify complete mold packages or component-level procurement.
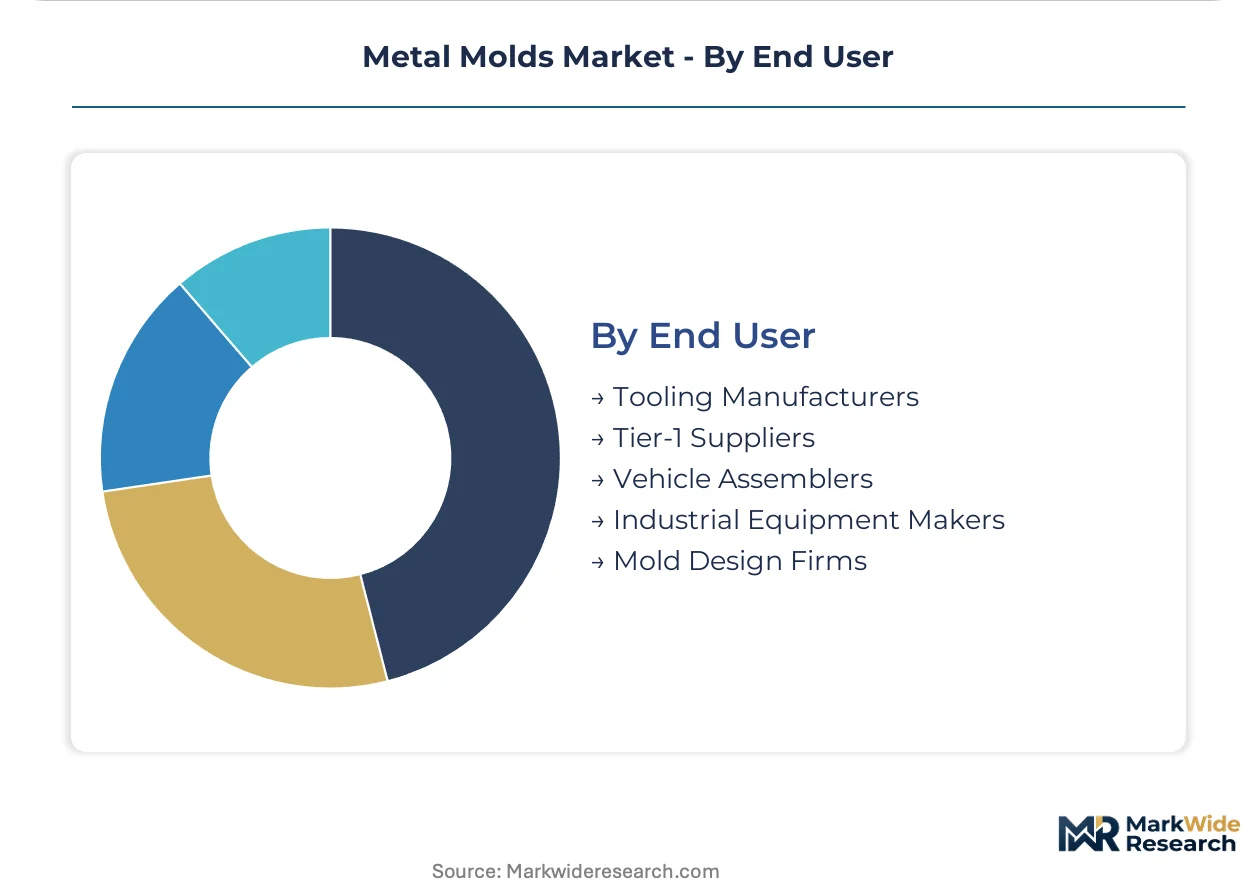
- Tooling Manufacturers:Specialized mold builders serve as intermediaries, integrating design, fabrication, and tryout services for end customers. German and Austrian firms maintain premium positioning through engineering-intensive project execution.
- Tier-1 Suppliers:Magna, Bosch, and Continental operate captive tooling divisions and external procurement boards. These customers demand IATF 16949 certification and real-time production visibility.
- Vehicle Assemblers:OEMs including Volkswagen, Toyota, and BYD source directly for strategic platform tooling. Battery housing and structural aluminum programs bypass traditional supplier tiers.
- Industrial Equipment Makers:Construction machinery, agricultural equipment, and material handling producers order medium-tonnage tooling with extended lifecycle requirements.
- Mold Design Firms:Engineering consultancies specify and source fabrication for customers lacking in-house technical resources. These intermediaries concentrate in industrial clusters around Detroit, Stuttgart, and Shanghai.
Tier-1 Suppliers represent the largest addressable customer base, with Vehicle Assemblers expanding direct procurement fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are redistributing mold fabrication capacity toward jurisdictions with lower compliance costs for surface treatment and emissions control. Chinese producers leverage MIIT industrial upgrading subsidies to capture battery housing contracts, while European shops absorb REACH-driven retrofit expenses. Mexican nearshoring clusters attract automotive programs seeking tariff-advantaged supply routes.
China
MIIT mandates accelerate domestic tooling capacity for electric vehicle battery platforms. GB standards enforcement tightens energy efficiency benchmarks for heat treatment equipment. Yangtze River Delta die-casting clusters expand integrated aluminum structural mold packages for BYD and Tesla supplier networks.
Germany
ECHA substance restrictions on hexavalent chromium force coating line retrofits across Baden-Württemberg mold shops. KBA automotive regulations extend qualification timelines for battery housing tooling. Stuttgart industrial corridor maintains premium positioning in multi-cavity injection systems through IATF 16949-certified fabricators.
United States
EPA emissions frameworks and OSHA workplace exposure limits govern mold shop operations in Michigan and Ohio automotive corridors. NHTSA vehicle safety standards propagate design requirements into tooling specifications. Detroit-area tooling boards consolidate procurement for Tier-1 suppliers seeking real-time production visibility.
Mexico
Automotive OEMs relocate stamping and casting operations to Monterrey and Querétaro under USMCA tariff advantages. Federal environmental regulations lag European stringency, reducing surface treatment compliance costs. Northern border states develop mold fabrication capacity to capture import substitution demand from relocated supply chains.
Japan
METI industrial policy supports precision tooling exports through JIS standards harmonization. PMDA medical device regulations propagate into mold qualification protocols for pharmaceutical packaging. Nagoya industrial zone concentrates vacuum hardening capacity serving automotive and aerospace tooling programs.
Metal Molds Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue additive manufacturing and rapid tooling services. The vendor base stratifies across Austrian engineering-intensive specialists, Chinese volume-driven fabricators, and North American prototype-to-production intermediaries. Strategic archetypes include precision multi-cavity system builders, conformal cooling technology integrators, and nearshoring-enabled regional suppliers. Competitive moves center on hybrid manufacturing convergence and geographic expansion into Mexican automotive corridors.
Among Austrian-based precision engineers, Engel Austria GmbH exemplifies the premium-tier archetype through its engineering-intensive positioning in multi-cavity injection systems. Wayken Rapid Manufacturing Limited represents the rapid tooling specialist segment bridging prototype-to-production gaps for industrial clients. GENSINI S.R.L. anchors the Italian precision fabrication cluster serving packaging and automotive surface treatment requirements.
| Leading Market Players |
|---|
| Bunty LLC |
| JBJ Technologies Ltd. |
| Engel Austria GmbH |
| GENSINI S.R.L. |
| Wayken Rapid Manufacturing Limited |
| The Rodon Group |
| Colonial Machine |
| Enko AS |
| Bericap GmbH & Co. KG |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between IATF 16949-certified automotive tooling and general-purpose industrial molds manifests in pricing spreads exceeding three-to-one, with Austrian and German fabricators commanding premium positioning through captive heat treatment networks while Chinese volume producers compete on raw steel conversion economics.
Pricing Analysis
Distributor margins of 15-25 percent persist in European and North American channels serving mid-tier automotive Tier 1 suppliers, though direct OEM contracting in China and Germany compresses intermediary layers. Three-tier pricing structure across premium, standard, and economy levels correlates with vacuum hardening certification, multi-axis CNC capability, and conformal cooling integration. Cost compression in standard-grade P20 tooling intensifies because Chinese equipment makers expand five-axis machining share. Automotive battery housing manufacturers exhibit lowest price sensitivity due to thermal management performance requirements, while consumer goods molders prioritize unit economics over surface treatment specifications.
Supply Chain Analysis
Five-axis CAM programming shortages in Stuttgart, Nagoya, and Detroit industrial corridors constrain capacity expansion regardless of capital availability. Tool steel feedstock concentrates in Austrian, Japanese, and select Yangtze River Delta specialty mills. Vacuum hardening and nitriding services draw from German, Japanese, and Chinese industrial zone clusters. Single-source vulnerability concentrates in H13 and P20 grade steel supply from Nippon Steel and voestalpine. Distribution runs through regional tooling boards operated by Magna, Bosch, and Continental that disintermediate traditional trading houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH compliance cost differentials between European coating line retrofits and Mexican environmental regulatory lag create geographic-arbitrage opportunities for battery housing tooling procurement.
For Market Incumbents: Lock in heat treatment capacity through long-term offtake agreements with Nagoya and Baden-Württemberg vacuum hardening specialists before automotive program launches compress availability. Secure IATF 16949 recertification ahead of KBA battery housing qualification timelines to defend against Chinese die-casting cluster expansion. Vertical integration into conformal cooling channel additive manufacturing preserves margin positioning as laser powder bed fusion commoditizes. For New Entrants and Emerging Players: USMCA tariff advantages in Monterrey and Querétaro open a window for nearshoring-enabled mold fabrication serving relocated automotive stamping operations. Target electronics assembly miniaturization demand in Taiwan and South Korea where sub-micron tolerance requirements outpace incumbent capacity expansion. Pursue rapid tooling service positioning bridging prototype-to-production gaps for North American industrial clients lacking in-house five-axis programming expertise. For Investors and Strategic Acquirers: Consolidation pressure builds where heat treatment bottlenecks and CAM programming shortages constrain independent mold shop viability. Mid-cap Austrian and Italian precision fabricators with established OEM relationships represent acquisition targets with durable revenue visibility. Watch for MIIT industrial upgrading mandate acceleration as signal of Chinese domestic capacity displacement of European battery housing tooling imports.| Strategic Initiative | Industry Significance |
|---|---|
| Conformal Cooling Integration | Additive manufacturing of tool steel inserts reduces cycle times 15-30 percent for automotive lighting molds. |
| Nearshoring Capacity Expansion | Monterrey fabrication facilities capture import substitution demand from USMCA-relocated automotive supply chains. |
| REACH Compliance Retrofit | Hard-coating line upgrades maintain ECHA export eligibility for German and Italian surface treatment specialists. |
| Direct OEM Contracting | Bypassing Tier 1 tooling boards secures strategic platform relationships with BYD and Tesla supplier networks. |
| Hybrid Manufacturing Convergence | CNC-laser cladding integration enables localized surface hardening for extended mold asset lifecycles. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with mold design engineers, Tier 1 supplier procurement directors, heat treatment facility operators, and automotive platform engineering leads with secondary validation against SEC filings, customs trade databases, MIIT industrial policy directives, and ECHA substance restriction updates. Bottom-up fabrication capacity modeling and top-down automotive production program analysis provided triangulation checks across the analysis window.
Segment-weighting approaches distributed value and volume across injection mold, die casting mold, blow mold, compression mold, and transfer mold categories, with technology splits across CNC machining, EDM, 3D printing, laser cutting, and water jet cutting. Application modeling incorporated consumer goods, electronics assembly, aerospace components, packaging solutions, and automotive supply chain demand patterns. CAGRs derived from production program pipelines, industrial equipment investment cycles, and regulatory compliance timelines. Forecast inputs included electric vehicle platform launch schedules and REACH authorization requirement phase-ins.
Revisions become necessary when MIIT mandate acceleration, ECHA substance restriction expansion, or USMCA tariff renegotiation materialize beyond baseline assumptions. Forecasts reflect documented projections contingent on tool steel price stability and vacuum hardening capacity expansion. Material deviation in automotive electrification timelines or REACH enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Global Cenospheres Market
Industrial Materials
Polyurethane Insulation Board Market
Industrial Materials
Mineral Wool Market
Industrial Materials
United States Graphite Electrodes Market
Industrial Materials
Atomizing Metal Powder Market
Industrial Materials
Battery Separator Materials Market
Industrial Materials
Bamboo Products Market
Industrial Materials
Soil Stabilization Materials Market
Industrial Materials
Plastic Injection Mold Market
Industrial Materials
Diamond Wire Market
Industrial Materials
Injection Molding Market
Industrial Materials
Asia-Pacific Wood Based Panel Market
Industrial Materials
Industrial Strainers Market
Industrial Materials
Industrial Films Market
Industrial Materials
Wood Protein Market
Industrial Materials
Foam Insulation Market