
 Phenolic Board Market | 2026-2036
Phenolic Board Market Size, Share, and Industry Trends Forecast 2026-2036
Phenolic Board Market Analytics
The gap between premium-certified phenolic boards and commodity-grade alternatives is expanding as fire performance ratings, thermal conductivity coefficients, and environmental product declarations become mandatory specification filters across major construction procurement frameworks. Kingspan Group leverages its integrated insulation manufacturing network to sustain specification relationships with tier-one contractors across multiple continents. Asahi Kasei Corporation anchors its position through specialized electrical-grade phenolic laminates serving aerospace and electronics OEMs. Fiberesin Industries differentiates via controlled-density boards for transportation interior applications where smoke toxicity standards dominate procurement criteria.
Phenolic board denotes a rigid panel manufactured from phenol-formaldehyde resin impregnated into cellulose fiber, glass fiber, or synthetic substrates, then cured under heat and pressure to achieve densities ranging from 40 to 200 kg/m³ depending on end-use requirements; the material delivers inherent flame resistance, low thermal conductivity near 0.018 W/m·K, and dimensional stability across temperature extremes from -180°C to +180°C, serving primarily as thermal insulation, electrical isolation, and structural substrate in fire-critical installations. Thermal insulation commands the largest volume pool within construction applications, though electrical insulation generates superior margin density through aerospace and automotive certification requirements. Laminated board segments face maturity in North American furniture manufacturing but retain growth vectors in Asian railway interior refurbishment programs. Decorative surface applications remain niche, concentrated in healthcare and laboratory environments where chemical resistance and cleanability override cost sensitivity.
Construction Products Regulation fire classification requirements in the European Union, EPA formaldehyde emission standards under TSCA Title VI in the United States, and BIS IS 12436 certification for thermal insulation materials in India collectively elevate compliance costs while restricting market access for uncertified producers. ECHA REACH restrictions on phenol and formaldehyde precursors are forcing reformulation investments across European manufacturing bases, with downstream effects on raw material sourcing strategies. Stakeholders must monitor evolving fire safety test protocols and precursor chemical regulations as these standards increasingly determine competitive viability in specification-driven procurement channels.
Market Dynamics
Fire safety code convergence across major economies is compressing specification windows for uncertified phenolic board producers while concentrating procurement authority among tier-one contractors with documented compliance histories.
Growth Catalysts
- EU Construction Products Regulation:Mandatory fire classification requirements under CPR are redirecting commercial building specifications toward certified phenolic systems with proven reaction-to-fire performance.
- Retrofit programs:Germany's building energy renovation initiatives are expanding specification volumes for high-performance thermal insulation boards in existing commercial portfolios.
- Cellulose fiber substrates:Advances in resin impregnation chemistry are improving bond strength and reducing thermal conductivity coefficients in construction-grade boards.
Market Restraints
- Formaldehyde precursor volatility:Phenol and formaldehyde feedstock prices fluctuate with petrochemical cycles, compressing margin stability for non-integrated manufacturers.
- Mineral wool substitution:Stone wool and glass wool insulation systems compete aggressively on installed cost in non-fire-critical building envelopes.
- ECHA REACH compliance burden:Registration, evaluation and authorization requirements for phenol derivatives elevate fixed costs for European manufacturing bases.
Strategic Opportunities
- Indian thermal insulation certification:BIS IS 12436 compliance requirements are creating first-mover advantages for certified producers in commercial construction procurement channels.
- Aerospace electrical laminates:Specialized phenolic prepregs serving avionics OEMs command premium pricing through FAA certification pathways.
- Railway interior refurbishment:Asian mass transit operators are adopting controlled-density phenolic panels meeting smoke toxicity standards for passenger compartment refurbishment.
Industry Challenges
- Reformulation chemistry expertise:ECHA restrictions on formaldehyde emissions are forcing investments in low-emission resin systems that few technical teams have mastered at scale.
- Multi-jurisdiction certification timelines:Simultaneous pursuit of EPA TSCA Title VI, EU CE marking, and BIS approvals extends product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phenolic Board Market |
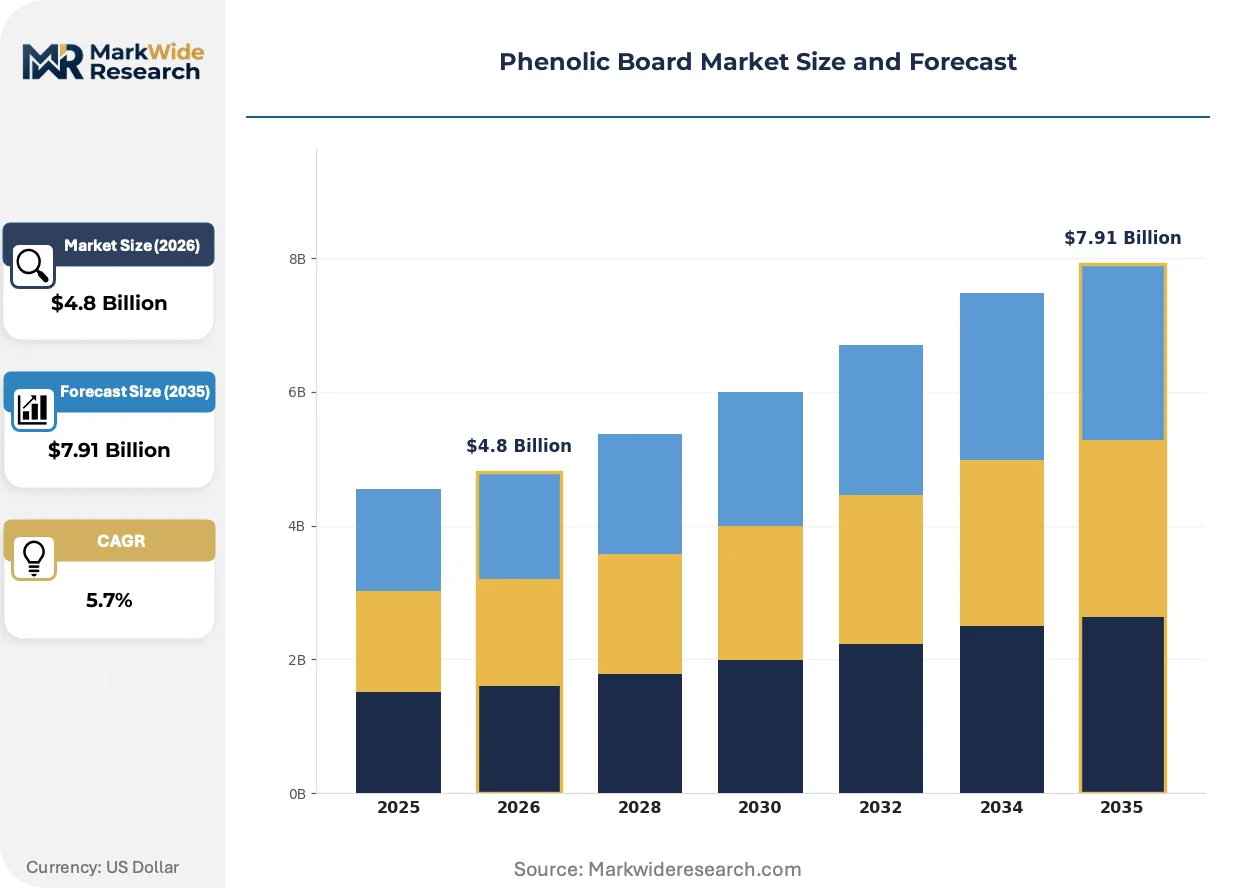
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Insulation, Electrical Insulation, Laminated Board, Decorative Surface End User: Construction, Furniture, Aerospace, Automotive Application: Wall Panels, Ceiling Tiles, Flooring, Electrical Components Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Kingspan Group, Asahi Kasei Corporation, Spigo Group, Jialifu Panel Industry (Guangzhou) Co., Ltd., Fiberesin Industries, SEKISUI CHEMICAL CO., LTD., Unilin Group, Wilsonart LLC, Phenolam India Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phenolic Board Market Evolving Landscape
Material science advances and procurement digitization are compressing traditional specification cycles while elevating performance transparency as a competitive differentiator in fire-critical applications.
Hybrid resin systems combining phenol-formaldehyde with bio-based modifiers are unifying thermal performance and reduced emission profiles in a single substrate. Tier-one contractors in Germany and France are specifying these boards for healthcare and educational facilities where indoor air quality standards intersect with fire safety mandates. This convergence is unifying previously separate procurement streams for insulation and emissions compliance into single-source contracts.
EPA formaldehyde emission standards under TSCA Title VI are tightening test protocols for composite wood products imported into the United States. Certified testing laboratory capacity constraints are creating bottlenecks for Asian producers seeking market access. North American distributors are responding by consolidating supplier relationships around domestic manufacturers with established third-party certification histories.
Building information modeling integration is compressing specification decision timelines from months to weeks as architects embed thermal and fire performance data directly into digital twins. Tier-one engineering firms are displacing traditional material submittal processes with automated compliance verification against project-specific performance criteria. This behavioral shift is most visible in German commercial construction where energy efficiency modeling and fire safety simulation now run in parallel workflows.
Phenolic Board Market Segmentation
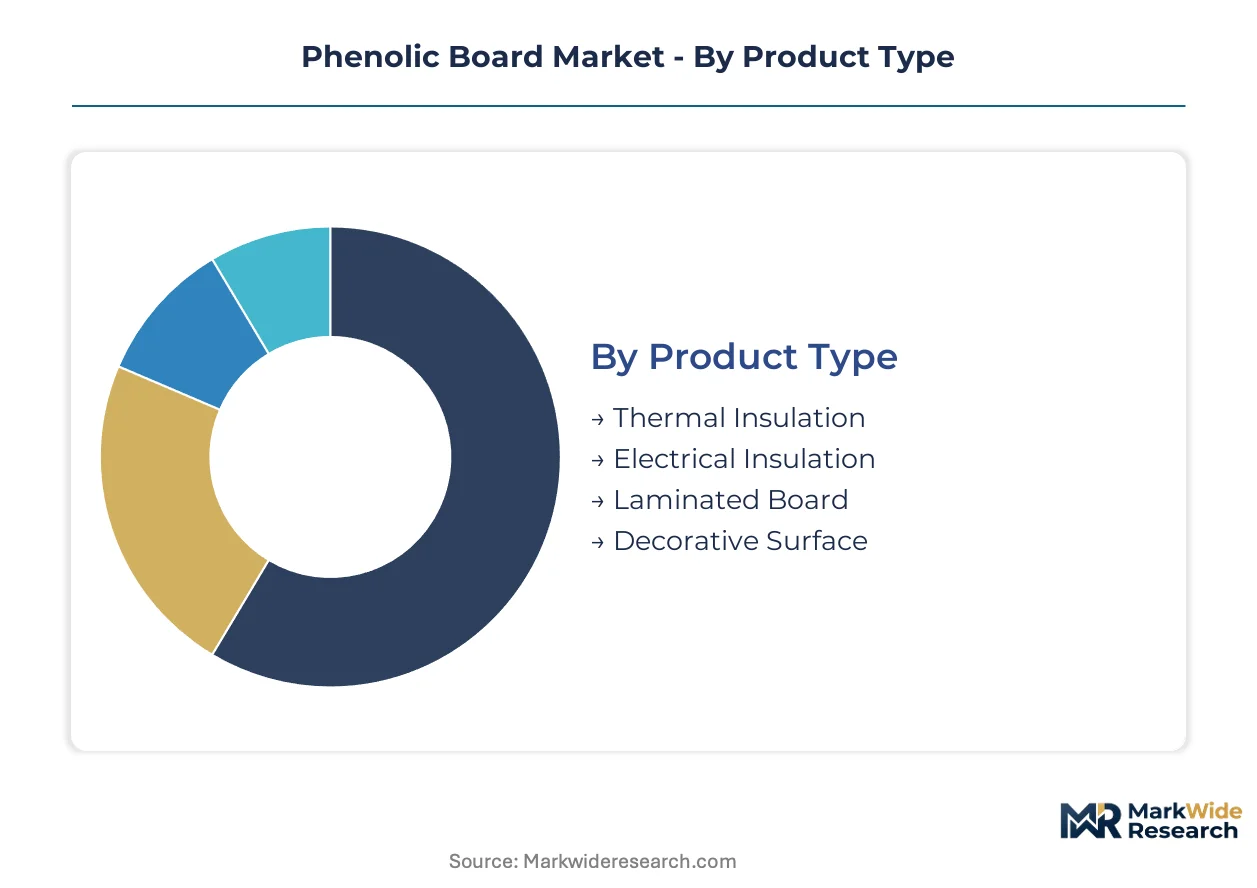
Phenolic board procurement hinges on certification alignment across product categories, with thermal performance ratings and fire safety classifications filtering specification decisions before cost considerations enter negotiation. Segmentation reveals how regulatory burden concentrates demand within certified supply channels while marginalizing uncertified alternatives.
Product Type:
Certification requirements fragment sharply across product types, with thermal insulation boards facing multi-jurisdiction fire classification mandates while electrical grades navigate aerospace OEM qualification protocols.
- Thermal Insulation:Rigid panels manufactured from phenol-formaldehyde resin impregnated into cellulose or glass fiber substrates, achieving densities of 40-120 kg/m³ with thermal conductivity near 0.018 W/m·K. Demand concentrates in German commercial retrofit programs where EU Construction Products Regulation fire classifications redirect procurement toward certified systems with documented reaction-to-fire performance.
- Electrical Insulation:High-density laminates serving avionics and power distribution applications, requiring FAA certification pathways for aerospace OEM qualification. Premium pricing persists through specialized prepreg formulations meeting dielectric strength and thermal endurance specifications for electrical isolation in fire-critical installations.
- Laminated Board:Multi-layer constructions bonded under heat and pressure for structural substrate applications in furniture and transportation interiors.
- Decorative Surface:Chemically resistant facing materials specified in healthcare and laboratory environments where cleanability overrides cost sensitivity.
Leading the category by volume: Thermal Insulation. Growing fastest: Electrical Insulation.
End User:
End-user concentration determines margin structure, with construction procurement driving volume through tier-one contractor relationships while aerospace and automotive segments extract premium pricing through qualification barriers.
- Construction:Commercial building portfolios across Germany, France, and retrofit-heavy EU markets specify phenolic boards for fire-resistant cladding and high-performance insulation envelopes. EU Construction Products Regulation compliance filters uncertified producers from specification channels.
- Furniture:North American furniture manufacturing represents mature demand, though Asian railway interior refurbishment programs are reviving laminated board specifications for controlled-density panels.
- Aerospace:Specialized phenolic prepregs serving avionics OEMs command premium positioning through FAA certification and dielectric performance requirements.
- Automotive:Electrical-grade laminates for powertrain and battery isolation applications, with qualification protocols extending product launch cycles.
Construction dominates procurement volume. Aerospace delivers steepest margin expansion trajectory.
Application:
Application segmentation tracks fire safety criticality, with wall and ceiling specifications facing the most stringent reaction-to-fire testing while flooring and electrical components navigate load-bearing and dielectric requirements.
- Wall Panels:Fire-resistant cladding systems for commercial building envelopes, with EU CPR classification requirements compressing specification windows toward certified phenolic systems.
- Ceiling Tiles:Suspended ceiling applications in healthcare and educational facilities where smoke toxicity standards intersect with indoor air quality mandates.
- Flooring:Structural substrate applications requiring dimensional stability across temperature extremes.
- Electrical Components:Isolation barriers and terminal boards in power distribution equipment.
Wall panels anchor construction demand. Ceiling tiles are expanding most quickly through healthcare specification.
Distribution Channel:
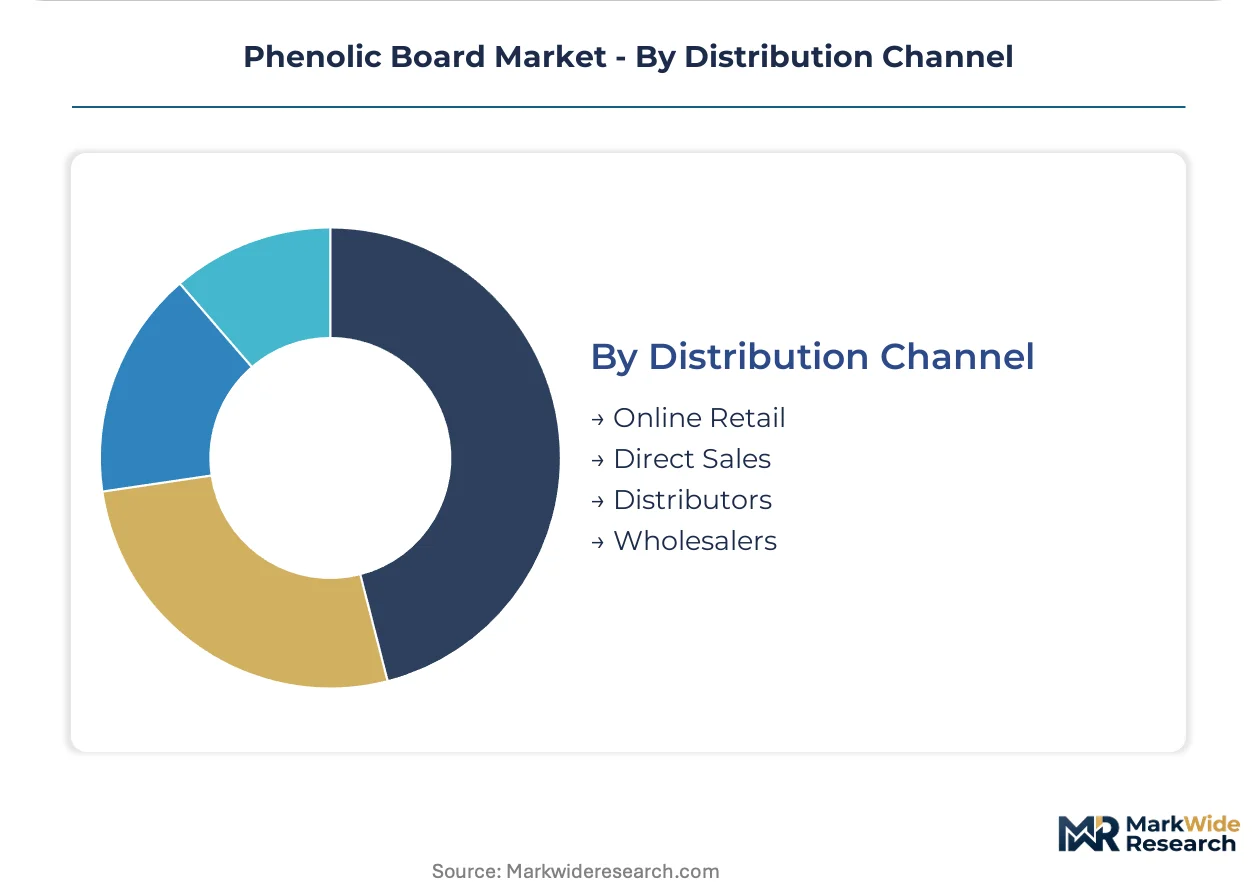
Channel structure reflects certification documentation requirements, with direct sales and distributor networks dominating specification-driven procurement while online retail serves commoditized replacement demand.
- Direct Sales:Tier-one contractor relationships sustained through integrated manufacturing networks and documented compliance histories across EPA TSCA Title VI, EU CE marking, and BIS IS 12436 certifications.
- Distributors:Regional stocking partners consolidating supplier relationships around domestic manufacturers with established third-party certification, particularly in North America where testing laboratory capacity constraints bottleneck Asian producer access.
- Online Retail:Standard-grade thermal insulation boards for residential and light commercial replacement markets.
- Wholesalers:Volume aggregation for secondary contractors and maintenance procurement.
Direct sales command specification authority. Distributors are gaining share fastest through certification consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Düsseldorf anchors European phenolic board specification activity through its concentration of engineering consultancies and tier-one contractor headquarters serving commercial retrofit programs across the Rhine-Ruhr industrial corridor.
Germany
Building energy renovation initiatives in North Rhine-Westphalia and Bavaria are expanding specification volumes for high-performance thermal insulation boards. The federal government's KfW funding programs for commercial building retrofits mandate EU Construction Products Regulation fire classifications. Cologne and Munich engineering clusters are embedding phenolic systems into digital twin workflows for healthcare and educational facilities.
United States
Commercial building portfolios in Texas and California are specifying fire-resistant cladding systems following high-profile facade fire incidents. EPA formaldehyde emission standards under TSCA Title VI are redirecting procurement toward domestic manufacturers with established third-party certification histories. The Pacific Northwest construction corridor is consolidating distributor relationships around certified supply channels.
India
Mumbai and Delhi-NCR commercial construction is accelerating specification of certified thermal insulation materials. BIS IS 12436 certification requirements are creating first-mover advantages for compliant producers in public infrastructure procurement. Gujarat industrial zones are emerging as manufacturing locations serving domestic demand and export markets.
China
Yangtze River Delta megacity construction is absorbing controlled-density phenolic panels for mass transit interior refurbishment programs. GB standards for building fire safety are tightening specification windows for reaction-to-fire performance. Shanghai engineering firms are integrating thermal performance data into building information modeling platforms.
Japan
Tokyo-Osaka industrial corridors are demanding specialized electrical-grade phenolic laminates for automotive powertrain and battery isolation applications. METI energy efficiency directives are elevating thermal conductivity coefficients as procurement filters. Chubu region aerospace suppliers are qualifying phenolic prepregs through JIS certification pathways.
Phenolic Board Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and specification relationship intensity. The vendor base clusters around three strategic archetypes: integrated insulation manufacturers with multi-continent production networks, specialized laminate producers serving aerospace and electronics OEMs, and regional fabricators concentrating on transportation interior applications. Competitive moves center on backward integration into resin chemistry and consolidation of distributor relationships around documented compliance histories.
Among Ireland-based integrated manufacturers, Kingspan Group exemplifies the scale-driven archetype through its multi-continent insulation manufacturing footprint. Asahi Kasei Corporation anchors the specialized laminate tier, representing Japanese chemical conglomerates with aerospace qualification capabilities. Fiberesin Industries occupies a position within the controlled-density board segment, illustrating North American fabrication expertise for smoke-critical transportation applications.
| Leading Market Players |
|---|
| Kingspan Group |
| Asahi Kasei Corporation |
| Spigo Group |
| Jialifu Panel Industry (Guangzhou) Co., Ltd. |
| Fiberesin Industries |
| SEKISUI CHEMICAL CO., LTD. |
| Unilin Group |
| Wilsonart LLC |
| Phenolam India Pvt. Ltd. |
| Others |
Value Network & Pricing Analysis
Phenol-formaldehyde resin feedstock costs cascade through three distinct pricing tiers as integrated manufacturers in Germany and Ireland capture margin through captive precursor production while commodity-grade importers absorb volatility from spot petrochemical markets. Certification depth separates these tiers, with EU CE-marked and EPA TSCA Title VI-compliant boards commanding structural premiums over uncertified alternatives excluded from tier-one contractor procurement channels.
Pricing Analysis
Fire-performance certification anchors value-based pricing, with reaction-to-fire ratings under EU Construction Products Regulation and BIS IS 12436 compliance in India filtering buyers before cost negotiation begins. Three-tier pricing structure across premium-certified, standard-compliant, and economy-grade levels reflects differentiation by thermal conductivity coefficients, environmental product declarations, and documented formaldehyde emission profiles. Pricing pressure stems from mineral wool substitution in non-fire-critical building envelopes, compressing margins in construction-grade thermal insulation. Residential replacement buyers exhibit highest price sensitivity, while aerospace electrical laminate procurement prioritizes FAA qualification over unit cost.
Supply Chain Analysis
Regional distribution centers in Düsseldorf, Cologne, and Munich aggregate certified inventory for German commercial retrofit programs, with hub-and-spoke patterns extending into France and Benelux markets. Manufacturing concentrates in Germany, Ireland, and Japan, drawing from phenol and formaldehyde precursor supply anchored in petrochemical complexes along the Rhine-Ruhr corridor and Gulf Coast USA. Single-source vulnerability runs through cellulose fiber substrate suppliers facing ECHA REACH authorization delays. Distribution runs through direct sales to tier-one contractors and consolidating distributor networks in North America where testing laboratory capacity constraints bottleneck Asian producer market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hybrid resin systems incorporating bio-based modifiers are displacing legacy phenol-formaldehyde formulations as EU indoor air quality standards converge with fire safety mandates in healthcare and educational facility procurement.
For Market Incumbents: Anchor specification relationships through backward integration into low-emission resin chemistry, defending against mineral wool substitution by embedding thermal and fire performance data into building information modeling workflows for German engineering consultancies. Prioritize certification maintenance across EPA TSCA Title VI, EU CE marking, and BIS IS 12436 as multi-jurisdiction compliance timelines extend competitive moats. For New Entrants and Emerging Players: E-commerce platforms serving residential replacement markets offer lowest barrier to entry, with online retail of standard-grade thermal insulation boards bypassing distributor certification consolidation. Target Indian commercial construction through BIS IS 12436 first-mover positioning in Mumbai and Delhi-NCR infrastructure procurement. Pursue Asian railway interior refurbishment segments where smoke toxicity standards create specification openings for controlled-density panel specialists. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized laminate producers with aerospace OEM qualification pathways in Japan and Germany, where METI energy efficiency directives and EU fire safety convergence sustain long-term demand visibility. Monitor ECHA formaldehyde restriction implementation timelines as inflection indicator for reformulation chemistry capability scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Chemistry | Captive phenol-formaldehyde production insulates margin from petrochemical volatility in German manufacturing bases. |
| Multi-Jurisdiction Certification Investment | Simultaneous EPA TSCA Title VI, EU CE marking, and BIS IS 12436 approvals unlock tier-one contractor procurement channels across three continents. |
| Building Information Modeling Integration | Embedded thermal performance data in digital twin workflows compresses specification cycles for Cologne and Munich engineering clusters. |
| Hybrid Bio-Modified Resin Development | Unified fire safety and low-emission profiles capture healthcare and educational facility procurement in France and Germany. |
| Regional Distribution Center Expansion | Hub-and-spoke inventory positioning in Düsseldorf, Cologne, and Munich reduces lead times for German commercial retrofit programs. |
Research Methodology
Independent corroboration across technical directors at phenolic board manufacturers, procurement leads at German tier-one construction contractors, and regulatory affairs specialists at ECHA and EPA underwrites the qualitative findings in this analysis. Primary interviews with plant managers in the Rhine-Ruhr industrial corridor, distribution channel partners consolidating around certified domestic producers, and R&D directors developing low-emission resin formulations combined with secondary validation from customs trade data, SEC 10-K filings of integrated insulation manufacturers, and BIS certification registries. Bottom-up volume estimates triangulated against top-down construction spend allocations across commercial building retrofit programs.
Rate-of-change decomposition across the analysis window segments growth by product type, end-user concentration, application fire-safety criticality, and distribution channel certification requirements. Modeled dimensions include thermal insulation versus electrical insulation grade tiers, construction versus aerospace end-use industries, and direct sales versus distributor channel structures. CAGRs derived from regression analysis against German KfW funding program allocations, Indian commercial construction permit data, and Asian mass transit refurbishment procurement cycles. Forecast inputs incorporate ECHA REACH authorization timelines and EPA formaldehyde emission standard enforcement intensity.
The model holds under stable regulatory enforcement trajectories and continued petrochemical feedstock availability; deviation in ECHA restriction scope or cellulose fiber substrate supply disruptions would shift volume and value outputs. Forecasts reflect documented assumptions regarding certification adoption rates and contractor procurement digitization velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Organic Binders Market
Organic Chemicals
North America Biphenyl Market
Organic Chemicals
Bio-Acetic Acid Market
Organic Chemicals
Anisole Derivatives Market
Organic Chemicals
North America Phenol Market
Organic Chemicals
2-Fluorobenzotrifluoride Market
Organic Chemicals
North America Organic Acid Market
Organic Chemicals
Aliphatic Amines Market
Organic Chemicals
Global Ketones Market
Organic Chemicals
Chlorocyclopentane Market
Organic Chemicals
Global Carboxylic Acid Market
Organic Chemicals
2-Methylbutanoic Acid Market
Organic Chemicals
1,3-Dioxolane Market
Organic Chemicals
Organic Acids Market
Organic Chemicals
Organic Matting Agent Market
Organic Chemicals
2-Iodophenol Market