
 Positron Emission Tomography Devices (PET) Market | 2026-2036
Positron Emission Tomography Devices (PET) Market Size, Share, and Industry Trends Forecast 2026-2036
Positron Emission Tomography Devices (PET) Market Analytics
Lutetium-based scintillator crystals are repositioning detector economics away from traditional bismuth germanate assemblies, trimming unit costs while sharpening spatial resolution. Siemens Healthineers leverages in-house crystal growth capacity to dominate premium system supply. GE Healthcare anchors its installed base through proprietary reconstruction algorithms and dense service networks. United Imaging Healthcare competes aggressively on digital PET/CT price points across Asia-Pacific hospital tenders.
Positron Emission Tomography Devices detect gamma ray pairs from positron-electron annihilation, reconstructing three-dimensional metabolic activity maps with spatial resolution typically below 5 millimeters; these systems enable clinicians to identify malignant tissue, quantify myocardial perfusion, and localize epileptic foci before structural changes appear on anatomical imaging. PET/CT hybrids command the dominant revenue share by fusing metabolic and anatomical datasets into single-session protocols that streamline oncology staging workflows. Digital detector technology represents the fastest-expanding segment, replacing analog signal chains with solid-state readouts that improve timing resolution and enable simultaneous multi-parametric imaging.
FDA premarket notification requirements for new PET systems enforce clinical validation standards that lengthen development cycles but protect incumbent manufacturers with established 510(k) portfolios. The EPA and NRC jointly regulate radiopharmaceutical production and waste handling, constraining site licensing for cyclotron-equipped facilities and shaping regional supply patterns for fluorodeoxyglucose tracers. Stakeholders must monitor CMS reimbursement rate adjustments for PET-directed biopsies and NCCN guideline expansions that directly influence hospital capital allocation cycles.
Market Dynamics
Digital detector architectures are compressing scan protocols from forty minutes to under fifteen, forcing incumbent manufacturers to retool production lines and service infrastructures around solid-state silicon photomultiplier arrays.
Growth Catalysts
- FDG tracer protocol standardization:CMS reimbursement codes for cancer staging now cover PET-directed biopsies across lung, lymphoma, and colorectal pathways, expanding hospital capital allocation toward hybrid PET/CT suites.
- Lutetium-based scintillator economics:Crystal growth automation trims detector assembly costs while sharpening spatial resolution below four millimeters, accelerating replacement cycles for aging bismuth germanate systems.
- Germany's dense hospital network:Tertiary oncology centers in Munich, Heidelberg, and Berlin maintain cyclotron-equipped radiopharmacy facilities that sustain high-throughput PET utilization rates.
Market Restraints
- Fluorine-18 supply concentration:Regional cyclotron capacity clusters in the United States, China, and Germany create radiopharmaceutical deserts where FDG logistics costs exceed scanner depreciation.
- NRC licensing friction:Radioactive waste handling permits and cyclotron siting approvals stretch facility commissioning timelines to eighteen months in constrained metropolitan markets.
- Total cost of ownership:Annual service contracts, shielding upgrades, and radiochemist staffing consume forty percent of lifetime system expenditure beyond initial hardware procurement.
Strategic Opportunities
- Cardiac amyloidosis imaging:PiB-derived tracers for TTR amyloid detection open neurology and cardiology departments beyond traditional oncology staging workflows.
- India's hospital infrastructure buildout:PLI scheme incentives for medical device manufacturing attract PET system assembly investments serving South Asian price sensitivity.
- Total-body dynamic PET:Simultaneous multi-organ parametric imaging converges pharmacokinetic modeling with therapeutic monitoring, enabling single-scan drug response assessment.
Industry Challenges
- Digital detector retrofit complexity:Analog-to-solid-state conversion demands gantry reconstruction and software revalidation that disrupts installed base service revenue streams.
- Radiochemist workforce scarcity:Cyclotron operation and tracer synthesis require specialized certification pathways that lag scanner deployment timelines in expansion markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Positron Emission Tomography Devices (PET) Market |
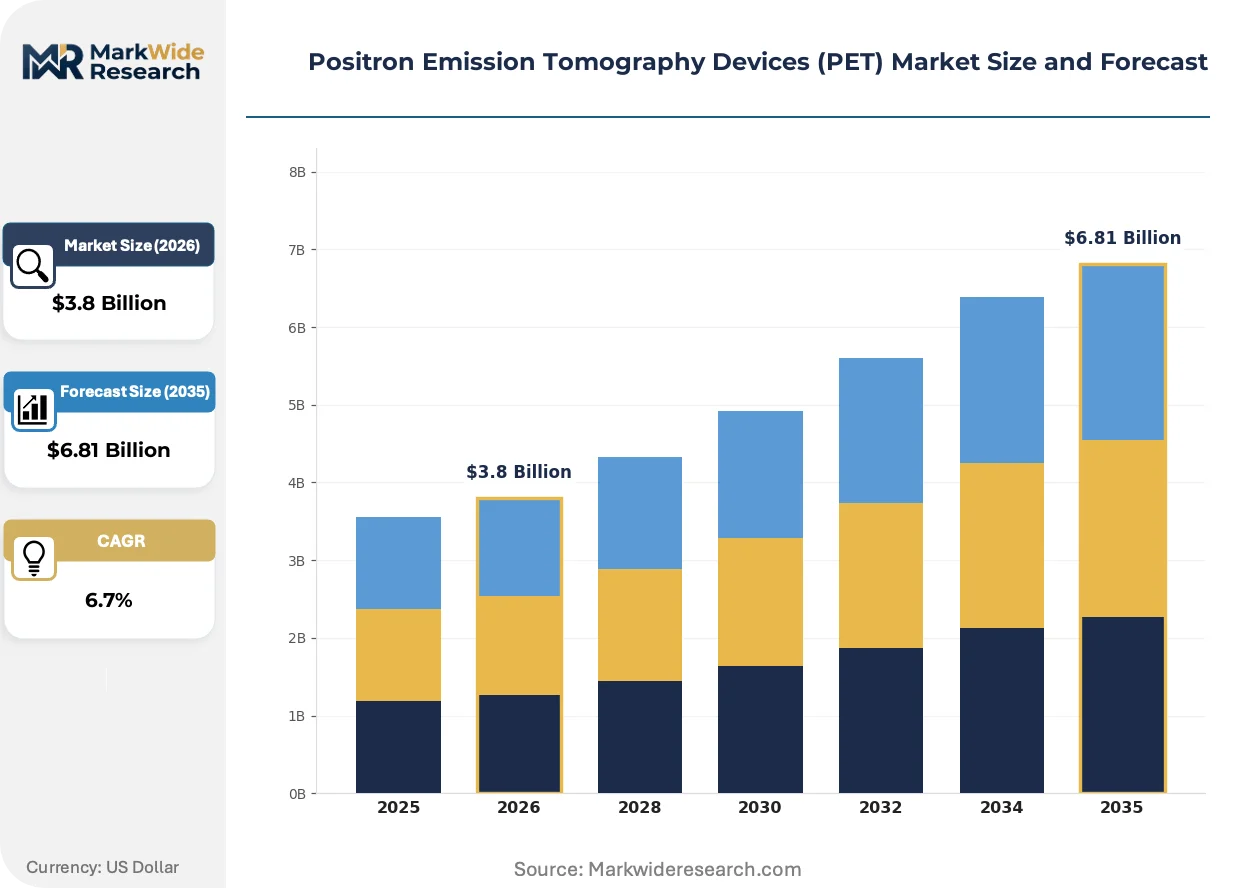
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone PET, PET/CT, PET/MRI, Mobile PET End User: Hospitals, Diagnostic Centers, Research Institutions, Home Care Technology: Analog, Digital, Hybrid, Advanced Imaging Application: Oncology, Cardiology, Neurology, Others |
| Companies Covered | Canon, Mediso, Siemens Healthineers, Bruker, Hitachi, GE Healthcare, United Imaging Healthcare, Neusoft Medical Systems, Koninklijke Philips, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Positron Emission Tomography Devices (PET) Market Evolving Landscape
Solid-state detector arrays are collapsing the trade-off between image quality and patient throughput, while regulatory frameworks tighten around artificial intelligence-enabled reconstruction algorithms.
Silicon photomultiplier sensors replace vacuum-tube photomultiplier tubes in detector stacks, converting scintillation light directly into digital signals with nanosecond timing resolution. Academic medical centers in the United States and university hospitals in Germany are adopting these architectures for simultaneous multi-tracer protocols. Digital PET/CT is overtaking analog platforms in new system tenders, compressing the viable service life of installed base equipment.
EMA's Medical Device Regulation now mandates clinical validation datasets for AI-based image reconstruction software, extending 510(k) equivalence pathways for algorithm updates. Siemens Healthineers and GE Healthcare are submitting supplemental premarket notifications for deep learning reconstruction modules. European notified bodies are prioritizing reviews for systems with embedded quality assurance automation.
Hospital purchasing consortia in China are unbundling service contracts from hardware acquisition, forcing manufacturers to compete on transparent parts pricing and remote diagnostics capabilities. Provincial tender documents in Jiangsu and Guangdong now specify minimum ten-year spare parts availability. United Imaging Healthcare and Neusoft Medical are capturing share through localized service networks and government-backed financing instruments.
Positron Emission Tomography Devices (PET) Market Segmentation
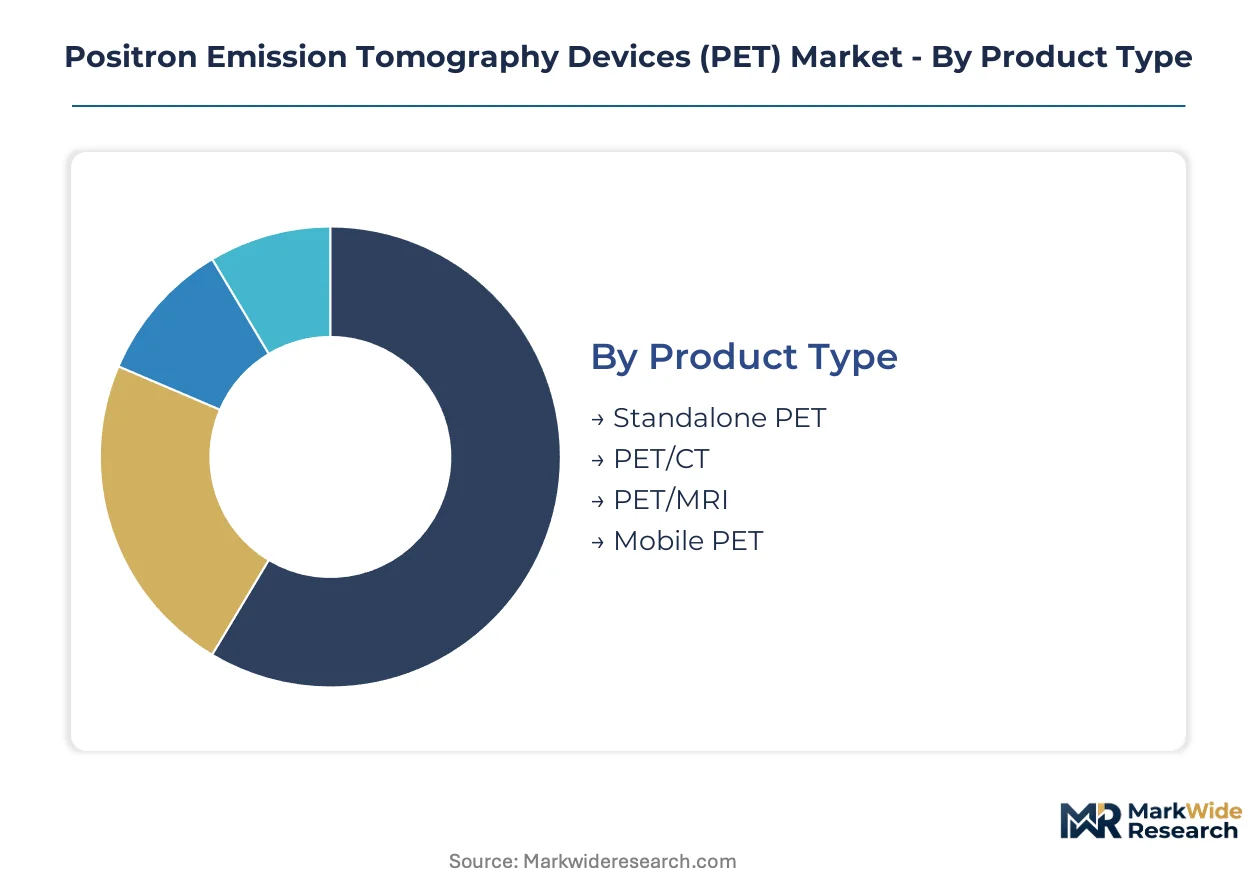
PET device segmentation reveals distinct regulatory pathways and capital intensity profiles across product architectures. Hospital procurement committees weight reimbursement alignment against detector technology roadmaps when allocating budgets across these categories.
Product Type:
FDA 510(k) clearance timelines vary sharply across these architectures, with hybrid systems demanding dual-modality validation datasets that extend premarket review cycles by eight to fourteen months.
- PET/CT:Fused metabolic-anatomical imaging dominates oncology staging protocols across tertiary hospitals in the United States, Germany, and China. CMS reimbursement codes for lung, lymphoma, and colorectal cancer staging sustain replacement cycles for aging analog-equipped suites.
- Standalone PET:Dedicated metabolic imaging without CT attenuation correction occupies niche applications in cardiac viability assessment and research protocols. Demand concentrates in budget-constrained diagnostic centers and academic institutions where CT availability already exists.
- PET/MRI:Simultaneous acquisition of metabolic and soft-tissue contrast enables pediatric neurology and prostate imaging without ionizing radiation exposure from CT. Siemens Healthineers and GE Healthcare hold established 510(k) portfolios for integrated gantry designs.
- Mobile PET:Trailer-mounted cyclotron and scanner configurations serve rural markets and temporary capacity surges. NRC licensing for radioactive materials transport constrains operational radius and service scheduling flexibility.
Leading the category by volume: PET/CT. Growing fastest: PET/MRI.
End User:
Capital allocation patterns diverge across facility types, with hospitals prioritizing throughput metrics while research institutions emphasize tracer development flexibility.
- Hospitals:Tertiary oncology centers in Munich, Heidelberg, and Berlin maintain cyclotron-equipped radiopharmacy facilities that sustain high-throughput utilization. FDG protocol standardization drives hybrid suite procurement across lung and lymphoma service lines.
- Diagnostic Centers:Specialized imaging chains compete on appointment availability and price transparency for self-pay oncology staging. United Imaging Healthcare and Neusoft Medical capture share through localized service networks and government-backed financing instruments.
- Research Institutions:Academic medical centers adopt solid-state detector architectures for simultaneous multi-tracer protocols. EMA Medical Device Regulation clinical validation requirements shape algorithm development roadmaps.
- Home Care:Portable coincidence detection systems for amyloid imaging remain experimental, constrained by radiopharmaceutical handling protocols and shielding requirements.
Hospitals command the largest installed base. Research institutions show the steepest expansion trajectory for digital platform adoption.
Technology:
Detector architecture selection determines timing resolution, dose efficiency, and service infrastructure requirements across the installed base.
- Digital:Silicon photomultiplier sensors convert scintillation light directly into digital signals with nanosecond timing resolution. Solid-state readouts compress scan protocols from forty minutes to under fifteen while lowering patient dose exposure.
- Analog:Vacuum-tube photomultiplier tube architectures dominate legacy installed base equipment. Replacement cycles accelerate as lutetium-based scintillator economics sharpen spatial resolution below four millimeters.
- Hybrid:Mixed-signal detector stacks bridge analog-to-digital transition for cost-sensitive tenders. Provincial documents in Jiangsu and Guangdong specify minimum ten-year spare parts availability for hybrid configurations.
- Advanced Imaging:Deep learning reconstruction modules require supplemental premarket notifications under FDA and EMA frameworks. Siemens Healthineers and GE Healthcare submit clinical validation datasets for AI-enabled image quality enhancement.
Digital platforms are displacing analog systems fastest. Hybrid configurations retain share in price-sensitive Asia-Pacific tenders.
Application:
Clinical indication drives tracer selection, reimbursement coding, and scanner specification requirements.
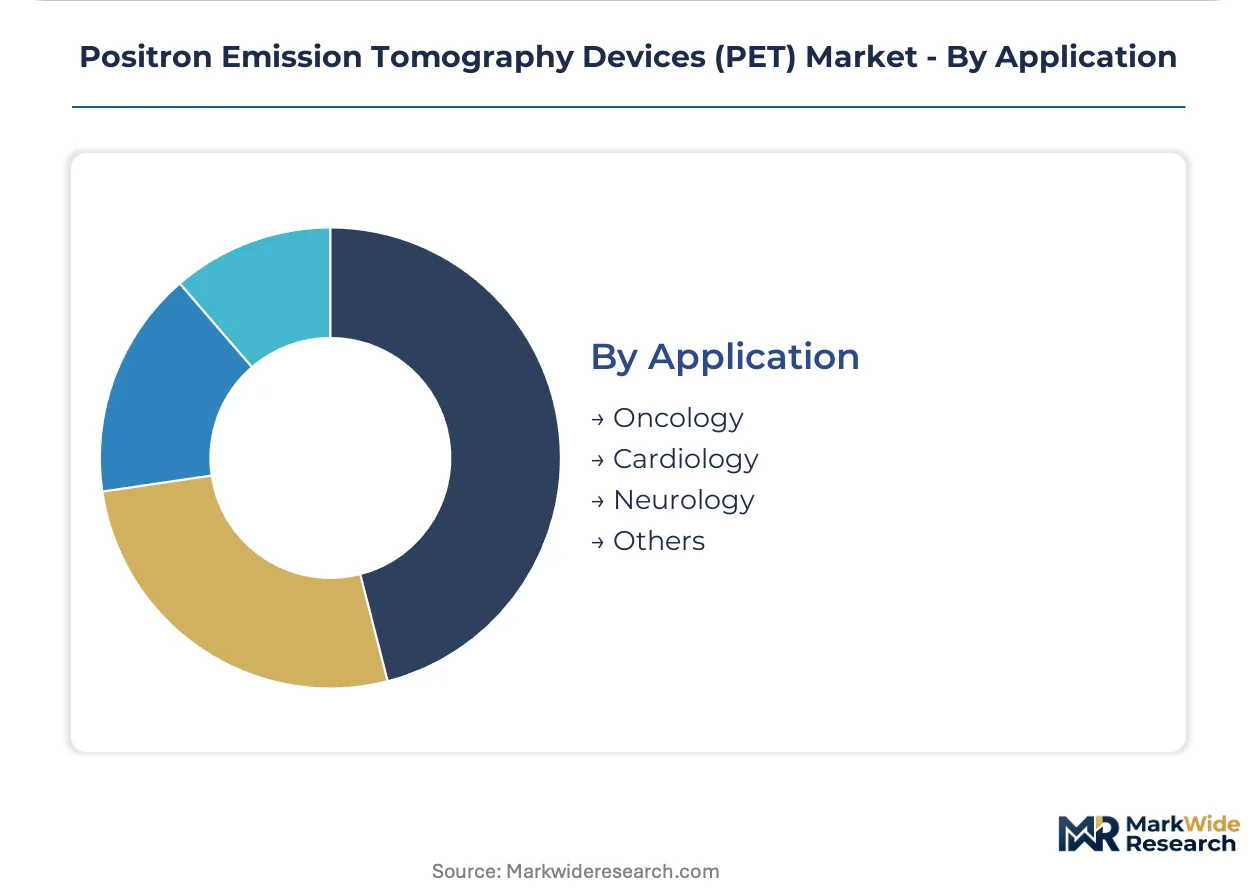
- Oncology:FDG-directed cancer staging generates the dominant procedure volume across lung, lymphoma, and colorectal pathways. CMS reimbursement rate adjustments directly influence hospital capital allocation cycles.
- Cardiology:Myocardial perfusion and viability assessment utilizes rubidium-82 and ammonia-13 tracers from on-site cyclotron or generator systems. PiB-derived tracers for TTR amyloid detection expand addressable indications beyond oncology.
- Neurology:Amyloid and tau imaging for Alzheimer's disease staging requires specialized tracer synthesis capabilities. Academic medical centers in the United States and Germany lead protocol development.
- Others:Infection imaging with gallium-68 labeled peptides and epilepsy focus localization occupy emerging application niches. Radiochemist workforce scarcity constrains tracer availability in expansion markets.
Oncology generates the highest procedure volume. Cardiology amyloid imaging shows the fastest indication expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Shanghai and Shenzhen concentrate PET device manufacturing capacity through VAT rebate programs and streamlined customs clearance for scintillator crystal imports.
United States
CMS reimbursement codes for lung and lymphoma cancer staging sustain hospital capital allocation toward hybrid PET/CT suites. FDA 510(k) premarket notification requirements enforce clinical validation standards that protect incumbent manufacturers with established portfolios. Tertiary oncology centers in Houston, Boston, and Cleveland maintain cyclotron-equipped radiopharmacy facilities that sustain high-throughput utilization rates.
Germany
EMA Medical Device Regulation clinical validation requirements shape algorithm development roadmaps for AI-enabled reconstruction software. Germany's dense hospital network in Munich, Heidelberg, and Berlin anchors premium system demand through established FDG protocol standardization. Siemens Healthineers leverages in-house crystal growth capacity to dominate supply chains serving Western European markets.
China
Provincial tender documents in Jiangsu and Guangdong specify minimum ten-year spare parts availability, forcing manufacturers to compete on transparent pricing. NMPA regulatory pathways for new PET systems align with international standards while prioritizing domestic innovation. United Imaging Healthcare and Neusoft Medical capture share through localized service networks and government-backed financing instruments.
Japan
PMDA approval timelines for digital detector architectures accelerate adoption of solid-state silicon photomultiplier arrays in academic medical centers. METI industrial policy supports domestic manufacturing of lutetium-based scintillator components to reduce import dependency. University hospitals in Tokyo and Osaka lead protocol development for simultaneous multi-tracer imaging applications.
India
PLI scheme incentives for medical device manufacturing attract PET system assembly investments serving South Asian price sensitivity. CDSCO regulatory harmonization with international standards streamlines import pathways for premium hybrid systems. Diagnostic center chains in Mumbai and Delhi compete on appointment availability for self-pay oncology staging procedures.
Positron Emission Tomography Devices (PET) Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated imaging conglomerates commanding premium pricing through proprietary reconstruction algorithms and dense service networks. The vendor base clusters around three strategic archetypes: diversified healthcare conglomerates with captive crystal growth capacity, mid-scale regional specialists competing on price points, and research-oriented firms serving academic protocols. Dominant competitive moves include gantry technology licensing agreements and backward integration into scintillator crystal production.
Among diversified healthcare conglomerates, Siemens Healthineers and GE Healthcare exemplify archetypes built on proprietary algorithm portfolios and established 510(k) clearance pathways. United Imaging Healthcare represents the regional specialist model, anchoring Asia-Pacific hospital tenders through localized service networks and government-backed financing structures.
| Leading Market Players |
|---|
| Canon |
| Mediso |
| Siemens Healthineers |
| Bruker |
| Hitachi |
| GE Healthcare |
| United Imaging Healthcare |
| Neusoft Medical Systems |
| Koninklijke Philips |
| Others |
Value Network & Pricing Analysis
Hospital purchasing consortia in China and Germany anchor PET system procurement through sovereign-backed financing instruments and multi-year service bundling, compressing margins for manufacturers without captive crystal growth capacity while rewarding vendors with localized radiopharmacy networks.
Pricing Analysis
Lead-time-driven pricing stratification separates premium digital PET/CT configurations with sub-six-month delivery windows from discounted analog-equipped spot inventory liquidated by retiring cyclotron facilities. Three-tier pricing structure across premium, standard, and economy levels reflects detector architecture grade, FDA 510(k) clearance status, and bundled radiopharmacy service contracts. Cost compression in economy-tier analog systems is intensifying because provincial tender documents in Jiangsu and Guangdong mandate transparent parts pricing. Diagnostic center chains exhibit highest price sensitivity due to self-pay oncology staging competition, while tertiary hospitals with established FDG protocols prioritize throughput metrics over acquisition cost.
Supply Chain Analysis
Dual-sourcing requirements for lutetium-based scintillator crystals now appear in Siemens Healthineers and GE Healthcare procurement specifications, mandating qualification of at least two crystal growth suppliers to mitigate single-source vulnerability. Geographic supply concentration centers on China for silicon photomultiplier sensor fabrication, Japan for lutetium oxyorthosilicate crystal production, and Germany for precision gantry assembly. Raw material dependencies span rare-earth lutetium compounds, high-purity silicon wafers, and lead shielding alloys. Distribution runs through hospital purchasing consortia in China, GPO contracts in the United States, and direct tender participation in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state silicon photomultiplier arrays are displacing vacuum-tube photomultiplier architectures across the installed base, compressing viable service life for legacy analog systems and forcing retooling decisions.
For Market Incumbents: Cement installed base loyalty through backward integration into lutetium-based scintillator production and proprietary AI reconstruction algorithm roadmaps. Siemens Healthineers leverages in-house crystal growth capacity to defend premium positioning against United Imaging Healthcare's price aggression in Asia-Pacific tenders. Capacity addition in cyclotron-equipped radiopharmacy networks protects recurring service revenue streams from digital detector retrofit disruption. For New Entrants and Emerging Players: Enter via cardiac amyloidosis imaging protocols using PiB-derived tracers, where TTR detection workflows remain underdeveloped relative to saturated oncology staging markets. India's PLI scheme incentives for medical device manufacturing represent the most penetrable geography given South Asian price sensitivity and nascent cyclotron infrastructure. Target diagnostic center chains with transparent parts pricing and remote diagnostics capabilities as the primary go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale regional specialists with localized service networks in constrained metropolitan markets where NRC licensing friction stretches facility commissioning timelines. Long-term viability hinges on radiopharmaceutical supply chain control across the analysis window. Watch CMS reimbursement rate adjustments for PET-directed biopsies as the inflection indicator for hospital capital allocation cycles. Deviation in fluorine-18 cyclotron capacity concentration would shift the outlook materially.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Detector Platform Transition | Solid-state silicon photomultiplier arrays compress scan protocols from forty minutes to under fifteen, forcing incumbent retooling. |
| Cyclotron-Equipped Radiopharmacy Expansion | On-site FDG production capacity in Houston, Boston, and Cleveland sustains high-throughput utilization rates for tertiary oncology centers. |
| AI Reconstruction Algorithm Development | Deep learning modules require supplemental FDA 510(k) notifications, extending equivalence pathways for Siemens Healthineers and GE Healthcare. |
| Localized Service Network Buildout | United Imaging Healthcare captures Asia-Pacific share through government-backed financing instruments and transparent parts pricing. |
| Cardiac Amyloidosis Tracer Protocol | PiB-derived TTR detection opens neurology and cardiology departments beyond traditional oncology staging workflows. |
Research Methodology
FDA 510(k) premarket notification databases, CMS reimbursement code filings, and EMA Medical Device Regulation submission records formed the secondary backbone, cross-referenced against primary interviews with hospital purchasing committee members, biomedical engineers, cyclotron facility radiochemists, and GPO contracts managers. Bottom-up and top-down triangulation validated unit shipment estimates against installed base replacement cycles and provincial tender award disclosures in Jiangsu and Guangdong.
Bottom-up modeling segmented volume and value outputs across detector architecture, application indication, and end-user facility type, with CAGRs derived from fitted trend extrapolation moderated by cyclotron capacity expansion timelines and reimbursement policy trajectories. Industry-specific forecast inputs incorporated NRC licensing approval durations for radioactive materials handling and lutetium-based scintillator crystal cost curves from academic medical center procurement data.
Revisions become necessary when fluorine-18 supply concentration shifts, NRC siting approval timelines extend beyond current metropolitan market constraints, or CMS reimbursement codes exclude PET-directed biopsy pathways for emerging cancer indications. Deviation in digital detector adoption rates across the installed base would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global Ultrasound Imaging Devices Market
Medical Imaging
Dental Digital X Ray Market
Medical Imaging
Ultrasound Consoles and Transducers Market
Medical Imaging
United States Computed Tomography Market
Medical Imaging
Intravascular Imaging Market
Medical Imaging
Radiography-Fluoroscopy Combo System Market
Medical Imaging
US Gadolinium-Based Contrast Media Market
Medical Imaging
South America Nuclear Imaging Market
Medical Imaging
India Computed Tomography Market
Medical Imaging
South America Portable X Ray Devices Market
Medical Imaging
Global Confocal Microscope Market
Medical Imaging
Mammography Market
Medical Imaging
South Korea Diagnostic Imaging Equipment Market
Medical Imaging
Portable Ultrasound Bladder Scanner Market
Medical Imaging
Global MRI Scanner Market
Medical Imaging
Mexico Nuclear Imaging Market