
 Open Magnetic Resonance Imaging System Market | 2026-2036
Open Magnetic Resonance Imaging System Market Size, Share, and Industry Trends Forecast 2026-2036
Open Magnetic Resonance Imaging System Market Insights
ISO 13485 certification for medical device quality management is rotating the competitive set as smaller manufacturers face extended audit cycles. Siemens Healthineers leverages its superconducting magnet foundry in Erlangen to control upstream component supply. GE Healthcare anchors North American service networks through captive field engineering teams. Esaote SpA specializes in dedicated extremity MRI systems for orthopedic clinics, occupying a defensible niche below whole-body scanner price points.
An open magnetic resonance imaging system employs permanent magnet or resistive electromagnet architectures with vertical or horizontal patient gaps exceeding 60 centimeters, enabling claustrophobic or bariatric patient positioning without enclosed tunnel geometry. These systems operate at field strengths typically ranging from 0.2 to 1.0 Tesla, prioritizing patient comfort over peak signal-to-noise ratio for musculoskeletal and cardiac screening protocols. Permanent magnet MRI technology leads installed base volumes due to lower cryogen dependency and siting costs, while superconducting MRI captures premium pricing in hospital radiology departments seeking diagnostic equivalence with closed systems. Among end users, diagnostic centers represent the fastest-growing channel as outpatient imaging chains expand ambulatory access in suburban markets.
FDA 510(k) premarket notification requirements govern US commercialization pathways, while the EU Medical Device Regulation mandates notified body conformity assessment for CE marking access across European member states. Japan's PMDA enforces Good Quality Management System Practice standards that extend approval timelines for foreign manufacturers. Stakeholders must monitor evolving helium conservation mandates from the US Department of Energy and corresponding magnet redesign roadmaps as supply chain constraints intensify.
Market Dynamics
Helium supply constraints are forcing magnet redesign roadmaps across the installed base, as cryogen dependency collides with conservation mandates from the US Department of Energy and export restrictions from major helium-producing nations.
Growth Catalysts
- Claustrophobia-tolerant protocols:Aging patient populations in Japan and Germany reject enclosed tunnel geometries, accelerating hospital procurement of vertical-gap architectures for cardiac and musculoskeletal screening.
- ISO 13485 certification rotation:Extended audit cycles for smaller manufacturers create procurement windows for established suppliers with mature quality management systems in place.
- Ambulatory imaging chain expansion:Outpatient diagnostic centers in suburban US markets deploy compact permanent-magnet systems to capture referral volume outside hospital radiology departments.
Market Restraints
- Superconducting magnet concentration:Foundry capacity for niobium-titanium wire and helium-cooled cryostats clusters in Germany and the United States, creating single-source vulnerability for high-field open systems.
- Signal-to-noise ratio ceiling:Permanent magnet architectures top out below 1.0 Tesla, excluding open systems from brain and abdominal protocols that demand diagnostic equivalence with 1.5 Tesla closed tunnels.
- FDA 510(k) timeline friction:Premarket notification requirements for predicate device comparison extend clearance durations for novel magnet geometries, delaying competitive entry.
Strategic Opportunities
- India outpatient penetration:Diagnostic chains in Mumbai and Bangalore lack MRI saturation, creating first-mover positioning for compact siting configurations that bypass construction-intensive shielding requirements.
- Helium-free superconducting convergence:Cryogen-free magnet technology from cryocooler manufacturers enables open-architecture systems to approach 1.5 Tesla without supply chain exposure to noble gas volatility.
- EU Medical Device Regulation tailwind:MDR Article 10 quality system requirements favor manufacturers with notified body relationships, consolidating procurement decisions toward CE-marked suppliers with established technical documentation.
Industry Challenges
- Field service engineer scarcity:Superconducting system maintenance demands cryogen handling certification and magnet quench recovery protocols that exceed training capacity at independent service organizations.
- Shielding specification fragmentation:Fringe field containment requirements vary across hospital construction codes in the United States, Germany, and Japan, preventing standardized site preparation templates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Open Magnetic Resonance Imaging System Market |
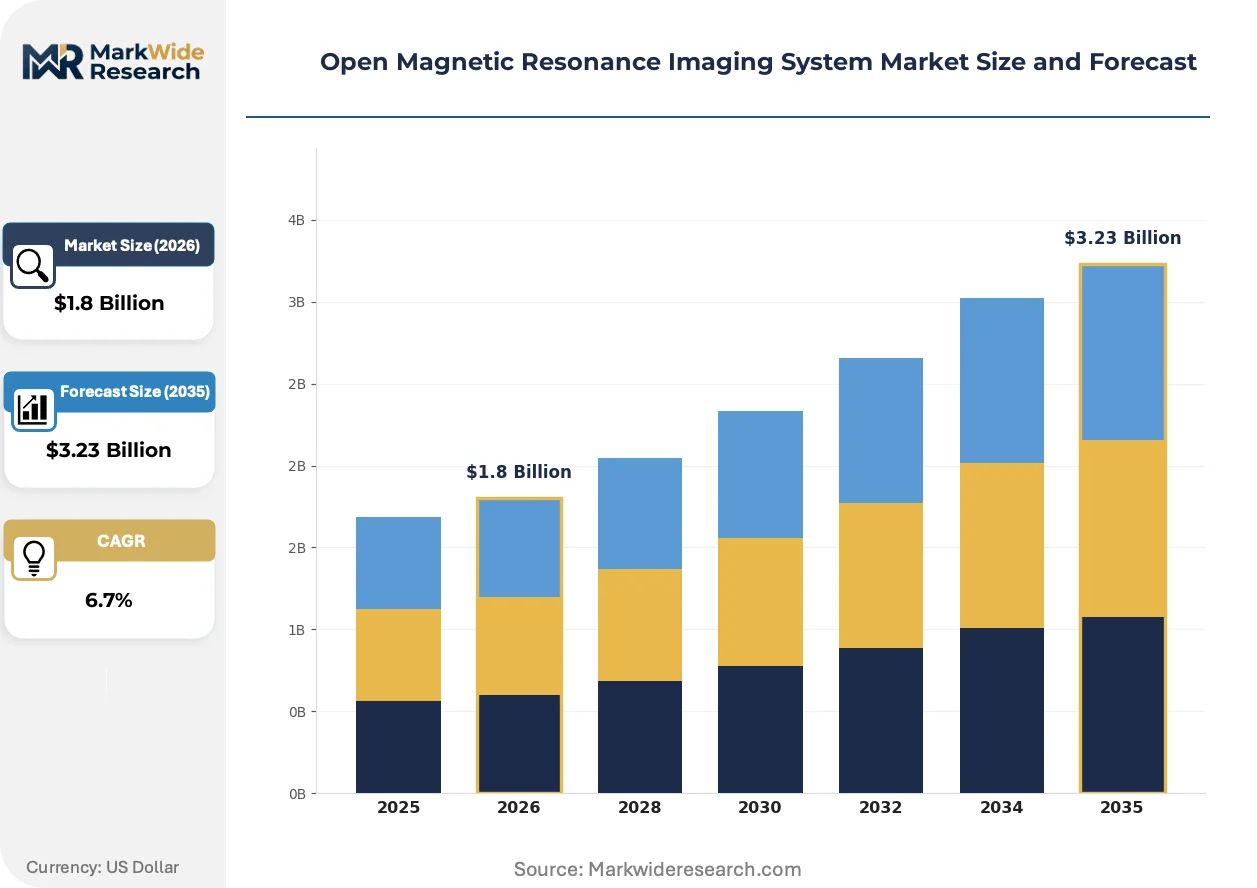
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed MRI, Open MRI, Extremity MRI, Functional MRI End User: Hospitals, Diagnostic Centers, Research Institutes, Imaging Facilities Technology: Superconducting MRI, Permanent Magnet MRI, Radiofrequency MRI, Contrast-Enhanced MRI Application: Neurology, Orthopedics, Cardiology, Oncology |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips N.V., Canon Medical Systems Corporation, Hitachi Ltd., Esaote SpA, FUJIFILM Holdings Corporation, Neusoft Corporation, Alltech Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Open Magnetic Resonance Imaging System Market Trends and Innovations
Permanent magnet architectures are capturing share from resistive electromagnets as siting flexibility and operating cost advantages outweigh field strength trade-offs in screening-heavy workflows.
Permanent magnet arrays with rare-earth neodymium-iron-boron configurations are displacing conventional iron-yoke designs in orthopedic clinic deployments across the United States. These systems eliminate persistent electrical consumption for magnet excitation while reducing thermal management infrastructure. The shift compresses total cost of ownership for extremity-focused installations that never require whole-body coverage.
Japan's PMDA has tightened Good Quality Management System Practice standards for foreign manufacturers, extending approval timelines by demanding on-site audits of production facilities. Domestic distributors now demand exclusive representation agreements to justify regulatory investment. European manufacturers with Tokyo-based regulatory affairs teams are capturing share from competitors managing Japan through regional headquarters in Singapore.
Hospital procurement committees are unbundling service contracts from equipment financing, forcing OEM field engineering networks to compete with independent service organizations on response time metrics. Diagnostic centers in suburban German markets now specify guaranteed uptime percentages rather than OEM brand preference in tender documents. This behavior compresses margin structures for manufacturers that historically subsidized equipment pricing through captive service revenue.
Open Magnetic Resonance Imaging System Market Segmentation
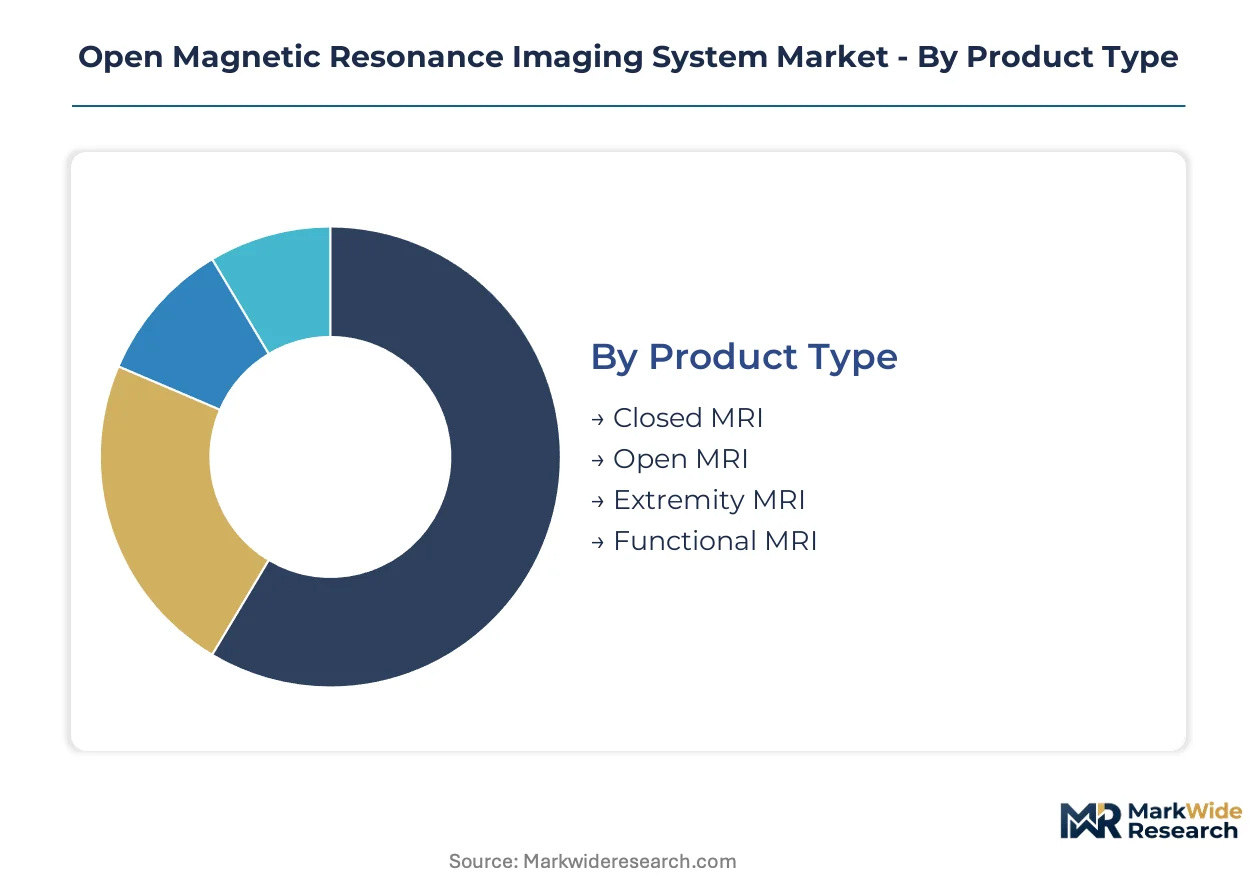
Segmentation in the Open Magnetic Resonance Imaging System Market reveals divergent procurement patterns across clinical settings and magnet technologies. Hospital radiology departments prioritize field strength and throughput, while outpatient chains optimize for siting flexibility and operating economics. Understanding these segment-specific trade-offs informs equipment positioning and service contract design.
Product Type:
Domestic procurement dominates closed MRI installations in Germany and Japan, where hospital infrastructure supports cryogen-dependent superconducting systems. Export-led demand concentrates in open and extremity configurations shipped to diagnostic chains in India and suburban United States markets lacking construction-intensive shielding capacity.
- Closed MRI:Tunnel geometries with superconducting magnets achieve 1.5 to 3.0 Tesla field strength for brain and abdominal protocols. Siemens Healthineers and GE Healthcare anchor installed base concentration in German and US hospital radiology departments where diagnostic equivalence with academic medical centers drives procurement specifications.
- Open MRI:Vertical or horizontal patient gaps exceeding 60 centimeters employ permanent magnet or resistive electromagnet architectures operating at 0.2 to 1.0 Tesla. Aging patient populations in Japan and Germany reject enclosed tunnel geometries, accelerating hospital procurement for claustrophobia-tolerant cardiac and musculoskeletal screening protocols.
- Extremity MRI:Compact dedicated systems target orthopedic clinics with lower siting costs and screening-focused workflows.
- Functional MRI:Blood-oxygen-level-dependent imaging for neurosurgical planning and research applications.
Closed MRI commands the established base. The steepest expansion runs through Open MRI.
End User:
Cost tier stratification separates capital-intensive hospital procurement from lean diagnostic center deployments. Research institutes occupy premium pricing bands with customized magnet configurations, while imaging facilities compete on throughput metrics.
- Hospitals:Radiology departments demand diagnostic equivalence with academic medical centers, specifying superconducting systems with comprehensive service contracts. German hospital procurement committees unbundle financing from maintenance agreements, forcing OEM field engineering networks to compete on guaranteed uptime percentages rather than brand preference.
- Diagnostic Centers:Outpatient imaging chains in suburban US markets and Indian metropolitan areas deploy compact permanent-magnet systems to capture referral volume outside hospital radiology departments. These operators prioritize siting flexibility and operating cost compression over peak field strength.
- Research Institutes:Functional neuroimaging and spectroscopy applications require customized gradient coil configurations.
- Imaging Facilities:Independent operators focus on throughput optimization and rapid patient turnover.
Hospitals anchor revenue concentration. Diagnostic centers are gaining share fastest.
Technology:
Supply concentration in superconducting wire foundries shapes competitive access, while permanent magnet arrays displace resistive electromagnets in volume-led segments.
- Superconducting MRI:Niobium-titanium wire wound into solenoid configurations achieves field strengths exceeding 1.0 Tesla with cryogen-cooled cryostats. Foundry capacity clusters in Germany and the United States, creating single-source vulnerability for high-field open systems as helium supply constraints intensify.
- Permanent Magnet MRI:Rare-earth neodymium-iron-boron arrays eliminate persistent electrical consumption and cryogen dependency. Orthopedic clinic deployments across the United States favor these systems for extremity-focused installations that never require whole-body coverage, compressing total cost of ownership.
- Radiofrequency MRI:Specialized coil configurations for targeted anatomical imaging.
- Contrast-Enhanced MRI:Gadolinium-based agent protocols for vascular and oncological assessment.
Superconducting MRI commands the established base. Permanent Magnet MRI is climbing the fastest.
Application:
Clinical protocol requirements dictate magnet specification, with neurology and cardiology demanding highest field strength and orthopedic screening tolerating lower Tesla configurations.
- Neurology:Brain parenchyma imaging and functional mapping protocols demand 1.5 Tesla minimum for diagnostic confidence. Open systems exclude themselves from this segment due to signal-to-noise ratio ceilings below closed tunnel equivalence.
- Orthopedics:Musculoskeletal screening of knees, shoulders, and spines tolerates lower field strength in exchange for patient positioning flexibility. Extremity-dedicated permanent magnet systems from Esaote SpA capture this segment with compact siting configurations.
- Cardiology:Stress perfusion and viability imaging requires cardiac gating compatibility.
- Oncology:Whole-body staging and treatment response assessment protocols.
Orthopedics commands the established base. Cardiology shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Frankfurt Rhine-Main logistics corridor underwrites Germany's central role in European MRI distribution, connecting superconducting magnet foundries to hospital networks across the continent.
Germany
Siemens Healthineers anchors domestic manufacturing through its Erlangen superconducting magnet foundry, supplying niobium-titanium wire configurations to hospital radiology departments nationwide. The EU Medical Device Regulation mandates notified body conformity assessment for CE marking access, extending technical documentation requirements for foreign entrants. Bavaria's medical technology cluster concentrates procurement committees that unbundle service contracts from equipment financing.
United States
Outpatient imaging chains in suburban markets deploy compact permanent-magnet systems to capture referral volume outside hospital radiology departments. FDA 510(k) premarket notification requirements govern commercialization pathways, with predicate device comparisons extending clearance timelines for novel magnet geometries. The Department of Energy's helium conservation mandates are forcing magnet redesign roadmaps across the installed base in Texas and California medical centers.
Japan
Aging patient populations reject enclosed tunnel geometries, accelerating hospital procurement of vertical-gap architectures for cardiac and musculoskeletal screening in Tokyo and Osaka metropolitan areas. The PMDA enforces Good Quality Management System Practice standards that extend approval timelines through on-site production facility audits. Kanto region distributors now demand exclusive representation agreements to justify regulatory investment.
India
Diagnostic chains in Mumbai and Bangalore lack MRI saturation, creating first-mover positioning for compact siting configurations that bypass construction-intensive shielding requirements. The Central Drugs Standard Control Organization regulates medical device imports through registration and licensing pathways. Maharashtra's outpatient imaging expansion concentrates in suburban corridors where permanent-magnet systems compress total cost of ownership.
China
Neusoft Corporation anchors domestic manufacturing capacity for resistive electromagnet configurations serving tier-two hospital procurement. The National Medical Products Administration enforces Good Quality Management System standards for domestic and imported devices. Yangtze River Delta medical device clusters in Shanghai and Suzhou concentrate regional distribution networks for open-architecture scanners.
Open Magnetic Resonance Imaging System Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and regulatory certification dimensions. The vendor base clusters around three tiers: diversified healthcare conglomerates with captive magnet foundries, dedicated imaging specialists with orthopedic niche positioning, and emerging Asian manufacturers with cost-optimized permanent-magnet platforms. Strategic moves concentrate on helium-free superconducting convergence and unbundled service contract competition.
Among diversified healthcare conglomerates, Siemens Healthineers and GE Healthcare exemplify the integrated-manufacturer archetype with upstream control over superconducting wire supply chains. Esaote SpA occupies a distinct position within the dedicated-specialist tier, anchoring the extremity-MRI segment with compact configurations for orthopedic clinic deployments. These three entities represent divergent competitive vectors: scale-driven foundry economics versus defensible niche positioning below whole-body scanner price points.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips N.V. |
| Canon Medical Systems Corporation |
| Hitachi Ltd. |
| Esaote SpA |
| FUJIFILM Holdings Corporation |
| Neusoft Corporation |
| Alltech Medical Systems |
| Others |
Pricing and Supply Chain Analysis
Permanent magnet substitution for helium-cooled superconducting architectures is redrawing procurement geography and compressing pricing power at the mid-market tier, as rare-earth neodymium-iron-boron arrays from Chinese and Australian mining operations displace niobium-titanium wire dependency while slashing siting costs for orthopedic clinic deployments.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with FDA 510(k) cleared systems and CE-marked MDR-compliant units commanding substantial premiums over uncertified configurations in hospital procurement. Three-tier pricing structure across premium superconducting, standard permanent-magnet, and economy resistive-electromagnet levels stratifies buyer segments, with diagnostic centers exhibiting acute price sensitivity while academic medical centers prioritize diagnostic equivalence regardless of cost. Pricing pressure stems from unbundled service contracts in German and US suburban markets, where guaranteed uptime specifications now override brand premiums in tender documents.
Supply Chain Analysis
Helium refining capacity in Qatar and Algeria constitutes a critical chokepoint for superconducting magnet production, with cryogen dependency tethering high-field open systems to volatile noble gas markets. Niobium-titanium wire foundries cluster in Germany and the United States, while rare-earth magnet processing concentrates in Chinese separation facilities, creating dual-source exposure for permanent-magnet arrays. Single-source vulnerability intensifies as export restrictions from major helium-producing nations collide with US Department of Energy conservation mandates. Distribution runs through captive OEM field engineering networks competing with independent service organizations on response time metrics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits within a regulatory entrenchment moat, where ISO 13485 certification timelines and FDA 510(k) predicate requirements erect structural barriers that compound incumbent advantages through switching costs embedded in hospital radiology department procurement workflows.
For Market Incumbents: Compound defensive positioning through upstream magnet foundry capacity additions in Erlangen and Milwaukee, while extending ISO 13485 certification coverage to preempt audit cycle windows that smaller competitors cannot sustain. Helium-free superconducting convergence from cryocooler manufacturers threatens traditional cryostat architectures, demanding accelerated R&D investment in cryogen-free platforms. Channel control through exclusive field service engineer networks in suburban US markets preserves margin structures against independent service organization price competition. For New Entrants and Emerging Players: Lead with compact permanent-magnet configurations targeting Mumbai and Bangalore diagnostic chains, where MRI saturation gaps and construction-intensive shielding limitations favor siting-flexible extremity systems. Orthopedic clinic penetration in the United States offers the most penetrable white-space, with Esaote SpA's niche dominance proving defensible positioning below whole-body scanner price points. Pursue distributor exclusive representation agreements in Japan's Kanto region, where PMDA on-site audit requirements justify regulatory investment through concentrated market access. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated manufacturers with captive superconducting wire supply and mature notified body relationships for EU MDR compliance. Long-term viability centers on helium-free technology convergence and unbundled service contract economics across the projection horizon. Acquisition targets should demonstrate established CE marking pathways and Tokyo-based regulatory affairs teams. Monitor helium spot price volatility and US Department of Energy conservation mandate enforcement as primary inflection indicators for magnet redesign roadmap acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Helium-Free Superconducting Magnet Development | Cryocooler manufacturer partnerships enable 1.5 Tesla open architectures without noble gas supply chain exposure. |
| ISO 13485 Certification Extension | Extended audit cycle coverage preempts procurement windows from smaller manufacturers facing quality system gaps. |
| Diagnostic Center Service Contract Unbundling | Guaranteed uptime specifications in German suburban tenders compress OEM margin structures toward competitive response metrics. |
| India Outpatient Distribution Partnership | Mumbai and Bangalore diagnostic chain relationships bypass construction-intensive shielding requirements through compact siting configurations. |
| Japan PMDA Regulatory Affairs Localization | Tokyo-based technical documentation teams capture share from competitors managing through Singapore regional headquarters. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and diagnostic center operations directors; and secondary validation against FDA 510(k) premarket notification databases, EU MDR notified body conformity assessments, hospital procurement records, and helium trade flow customs data. Bottom-up triangulation across magnet foundry capacity disclosures and top-down reconciliation with installed base estimates anchored volume and value outputs.
Across the analysis window, the forecasting framework modeled product type segmentation between closed, open, extremity, and functional MRI configurations; technology tiers spanning superconducting, permanent magnet, and resistive electromagnet architectures; and end-user channels distinguishing hospital radiology departments from diagnostic centers and research institutes. CAGRs derived from weighted average replacement cycles and ambulatory imaging chain expansion trajectories incorporated helium supply constraint scenarios and PMDA approval timeline extensions as sensitivity inputs.
Underlying assumptions cover stable regulatory enforcement of FDA 510(k) and EU MDR requirements, with deviation risk concentrated in helium export restriction escalations and accelerated cryogen-free magnet technology adoption. Practitioners should keep alternative scenarios live as conservation mandate implementation and rare-earth processing capacity expansion evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global Artificial Intelligence in MRI Market
Medical Imaging
Medical Hyperspectral Imaging Market
Medical Imaging
United Kingdom Computed Tomography Market
Medical Imaging
Medical Image Analysis Software Market
Medical Imaging
Medical Imaging Market
Medical Imaging
Mexico Computed Tomography Market
Medical Imaging
X-Ray Devices Market
Medical Imaging
Global Veterinary Diagnostic Imaging Market
Medical Imaging
North America Digital Pathology Market
Medical Imaging
Small Animal Imaging (in-Vivo) Market
Medical Imaging
Medical X-Ray Equipment and Imaging Software Market
Medical Imaging
Global Dental Radiology and Dental Imaging Devices Market
Medical Imaging
Breast Imaging Equipment Market
Medical Imaging
Cone Beam CT Scanner Market
Medical Imaging
North America Digital X-Ray Market
Medical Imaging
Middle East and Africa Mammography Market