
 Italy Diagnostic Imaging Equipment Market | 2026-2036
Italy Diagnostic Imaging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Diagnostic Imaging Equipment Market Foresight
Market Context
Italian medical device manufacturing is pivoting toward higher-value imaging systems as domestic producers respond to post-pandemic healthcare modernization budgets. Siemens Healthineers anchors its southern European operations through extensive service networks covering Italian hospitals. Esaote specializes in ultrasound and dedicated MRI systems for musculoskeletal applications, leveraging its Genoa headquarters for regional distribution control. Canon Medical Systems competes on advanced CT reconstruction algorithms while maintaining manufacturing partnerships that sustain local employment in the sector.
Technical Definition and Structural Segments
Diagnostic imaging equipment encompasses electromechanical systems that generate visual representations of internal body structures for clinical diagnosis, utilizing radiation doses, magnetic field strengths, or acoustic frequencies calibrated to specific tissue contrasts. CT scanners and MRI machines command the highest capital investment among product types, with CT systems leading installed base expansion in Italian emergency departments while MRI faces longer replacement cycles due to shielding infrastructure costs. Digital imaging technology dominates new procurement across hospitals and diagnostic centers, displacing analog systems as radiology departments prioritize DICOM-compliant workflow integration and teleradiology readiness.
Regulatory Framework and Outlook
Italy's national pharmaceutical regulator, the Agenzia Italiana del Farmaco, enforces EU MDR compliance timelines for imaging device registrations, while CE marking requirements under EU regulation shape product design standards for electromagnetic compatibility and patient safety. The Ministry of Health coordinates regional procurement frameworks that influence capital allocation across Italy's twenty healthcare districts. Stakeholders must monitor how evolving EU AI Act provisions classify machine-learning diagnostic algorithms embedded in next-generation imaging platforms.
Market Dynamics
Italy's diagnostic imaging equipment sector confronts a structural squeeze between EU MDR compliance deadlines and aging hospital infrastructure requiring wholesale replacement cycles. The Agenzia Italiana del Farmaco's enforcement timelines are compressing product registration windows while regional health authorities accelerate capital deployment toward digital-ready systems.
Growth Catalysts
- EU Medical Device Regulation:The MDR's stricter conformity assessment protocols are filtering out lower-tier competitors, concentrating procurement among certified suppliers capable of sustained technical documentation.
- Chronic disease prevalence:Italy's aging demographic profile drives sustained demand for oncology and cardiology imaging workflows across Lombardy and Emilia-Romagna hospital networks.
- Magnetic field strength escalation:3 Tesla MRI systems are displacing 1.5 Tesla platforms in academic medical centers, triggering replacement cascades through shielding infrastructure upgrades.
Market Restraints
- Helium supply concentration:MRI superconducting magnet cooling depends on helium sourcing concentrated in Qatar and the United States, exposing Italian operators to price volatility and allocation risk.
- Shielding infrastructure costs:RF-shielded installation requirements for MRI systems impose fixed costs exceeding equipment purchase prices in historic hospital buildings common across central Italian provinces.
- EU AI Act classification uncertainty:Pending algorithmic risk-tier determinations for machine-learning diagnostic tools are freezing R&D roadmaps and delaying product launches.
Strategic Opportunities
- Point-of-care ultrasound expansion:Emergency departments and rural clinics across Sicily and Calabria remain underpenetrated by portable systems capable of triage-grade cardiac and abdominal imaging.
- Interventional radiology convergence:Hybrid operating suites combining CT guidance with minimally invasive procedures represent white space in Italian private hospital expansion plans.
- Teleradiology infrastructure mandates:Regional healthcare district digitization requirements are creating bundled procurement opportunities for DICOM-compliant hardware-software packages.
Industry Challenges
- Clinical engineer scarcity:Specialized service technicians capable of superconducting magnet maintenance and gradient coil repair are concentrated in northern industrial corridors, limiting national coverage.
- Legacy PACS integration friction:New imaging platforms must interface with decades-old picture archiving systems prevalent in public hospitals, extending deployment timelines and inflating customization costs.
Report Scope
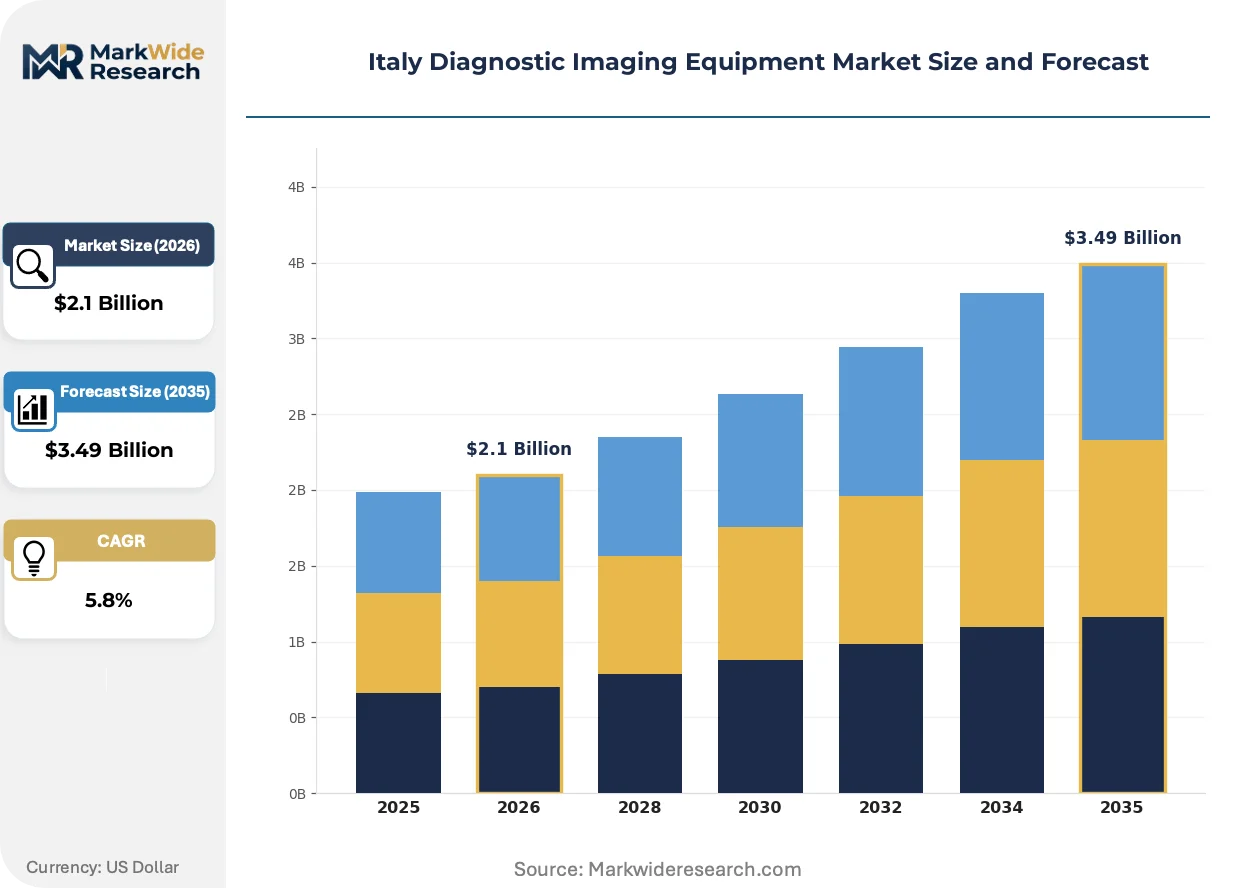
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Diagnostic Imaging Equipment Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CT Scanners, MRI Machines, Ultrasound Devices, X-Ray Systems End User: Hospitals, Diagnostic Centers, Outpatient Clinics, Research Labs Technology: Digital Imaging, Analog Imaging, 3D Imaging, Ultrasonography Service Type: Maintenance, Installation, Consulting, Training |
| Companies Covered | Canon Medical Systems, Esaote, Siemens Healthineers, Gilardoni SpA, Italray, GE Healthcare, FUJIFILM, Hologic, Koninklijke Philips, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Diagnostic Imaging Equipment Market Shifts & Advancements
Artificial intelligence integration and hardware miniaturization are restructuring competitive advantage in Italian diagnostic imaging, compressing the gap between premium and mid-tier system capabilities while opening new deployment contexts previously unreachable by conventional platforms.
Computed tomography detector technology is modularizing through photon-counting architectures that replace energy-integrating sensors with cadmium telluride or cadmium zinc telluride layers. Academic medical centers in Milan and Bologna are piloting these systems for spectral imaging protocols. This modularity is compressing the upgrade cycle from full gantry replacement to detector subsystem swaps, altering capital planning and service contract structures.
The EU AI Act's risk-based classification framework for machine-learning medical devices is reshaping product development priorities across imaging software vendors. High-risk algorithmic diagnostic tools now face conformity assessment requirements comparable to hardware devices, extending time-to-market for computer-aided detection systems. Radiology departments are responding by demanding vendor documentation of training data provenance and performance validation across Italian patient populations.
Service unbundling from equipment purchase is restructuring how Italian hospitals acquire imaging capability. Public procurement frameworks in Piedmont and Veneto are separating hardware acquisition from maintenance and software subscriptions, enabling multi-vendor service ecosystems. This fragmentation is most visible among mid-sized diagnostic centers seeking specialized teleradiology connectivity without full vendor lock-in.
Italy Diagnostic Imaging Equipment Market Segmentation
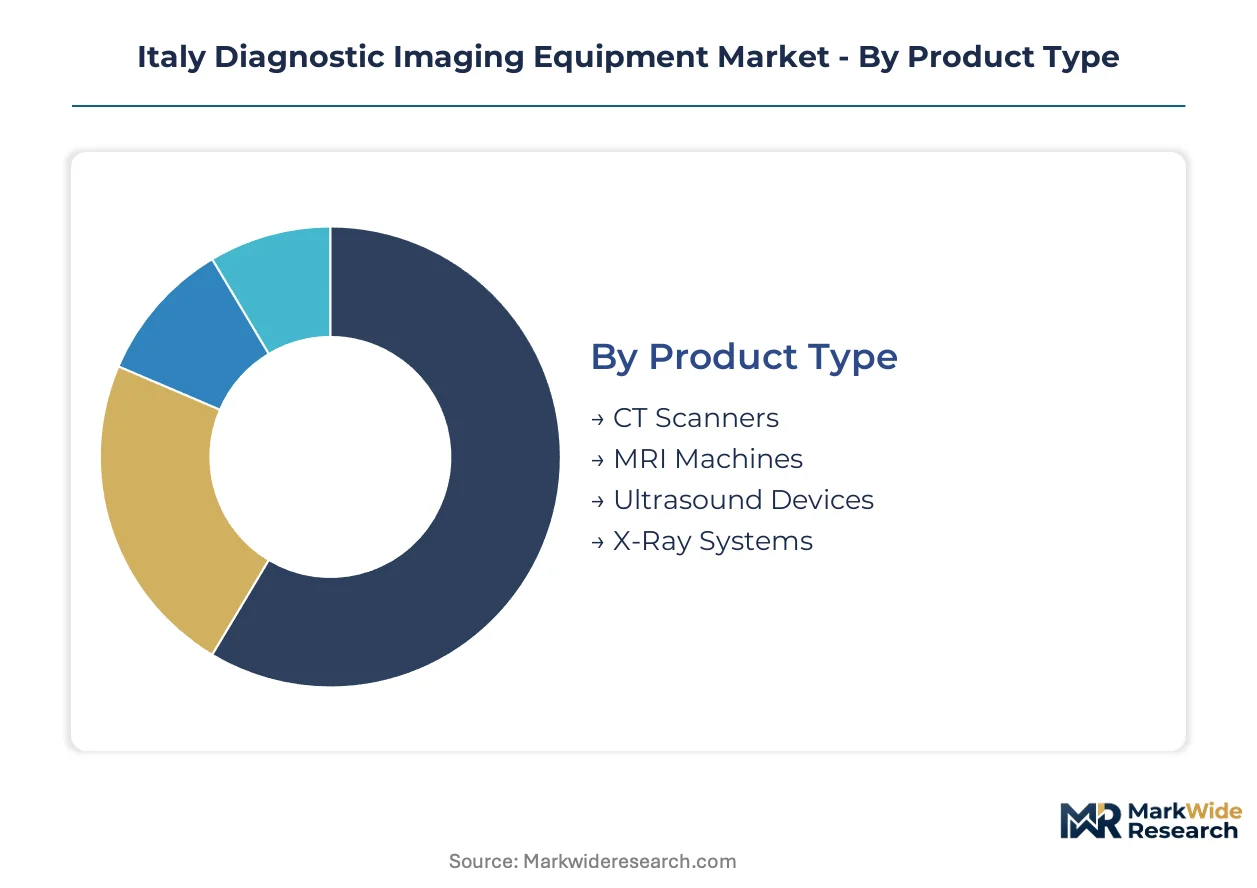
Segmentation reveals how procurement priorities diverge across Italian healthcare infrastructure. Northern hospital networks concentrate capital spending on premium modalities while southern regions prioritize accessible point-of-care systems. Understanding these splits enables targeted positioning against regional budget cycles and facility upgrade timelines.
Product Type:
Volume deployment favors workhorse systems with proven reimbursement pathways, while premium positioning concentrates on advanced magnetic field and detector architectures that command higher procedure yields.
- CT Scanners:Energy-integrating detector arrays dominate installed bases, though photon-counting architectures are penetrating Milan and Bologna academic centers. Emergency departments across Lombardy drive replacement demand for dual-source systems capable of cardiac gating without breath-hold protocols.
- MRI Machines:Superconducting systems with 1.5 Tesla field strength anchor standard-of-care diagnostics in regional hospitals. 3 Tesla platforms are displacing legacy installations in Turin and Genoa research hospitals where neurovascular and musculoskeletal protocols generate higher throughput economics.
- Ultrasound Devices:Cart-based systems with harmonic imaging and elastography functions serve cardiology and hepatology departments.
- X-Ray Systems:Digital radiography panels with wireless connectivity are replacing computed radiography cassettes in high-volume screening programs.
Mature deployment sits with X-Ray Systems. Newer deployment is concentrated in MRI Machines.
End User:
Capital allocation authority determines procurement sophistication, with centralized purchasing entities favoring bundled service contracts over discrete hardware transactions.
- Hospitals:Public acute-care facilities operate under regional health authority budgets that mandate DICOM compliance and teleradiology readiness. Procurement concentrates in Lombardy, Emilia-Romagna, and Veneto where dense referral networks justify high-throughput scanner configurations.
- Diagnostic Centers:Private imaging chains compete on appointment availability and subspecialty radiologist access. These facilities favor refurbished premium systems and flexible financing to manage utilization risk across competitive catchment areas.
- Outpatient Clinics:Limited floor space and lower procedure volumes drive demand for compact ultrasound and portable X-ray configurations.
- Research Labs:Preclinical imaging for pharmaceutical studies requires specialized small-bore MRI and micro-CT systems with custom coil geometries.
Equipment density peaks in Hospitals. Steepest expansion trajectory belongs to Diagnostic Centers.
Technology:
Workflow integration requirements are filtering procurement toward interoperable platforms, with legacy compatibility determining upgrade sequencing.
- Digital Imaging:PACS-native acquisition systems with automated dose tracking and structured reporting dominate new procurement. Italian regional health authorities mandate digital readiness as a condition of capital funding approval.
- Analog Imaging:Film-based systems persist in remote mountain clinics and aging facilities where electrical infrastructure cannot support digital detector power requirements.
- 3D Imaging:Cone-beam CT and tomosynthesis reconstruction algorithms are penetrating dental and breast imaging segments.
- Ultrasonography:Shear-wave elastography and contrast-enhanced protocols are expanding liver and renal diagnostic capabilities beyond traditional B-mode imaging.
Regulatory compliance is accelerating Digital Imaging adoption. Analog Imaging remains concentrated in infrastructure-constrained settings.
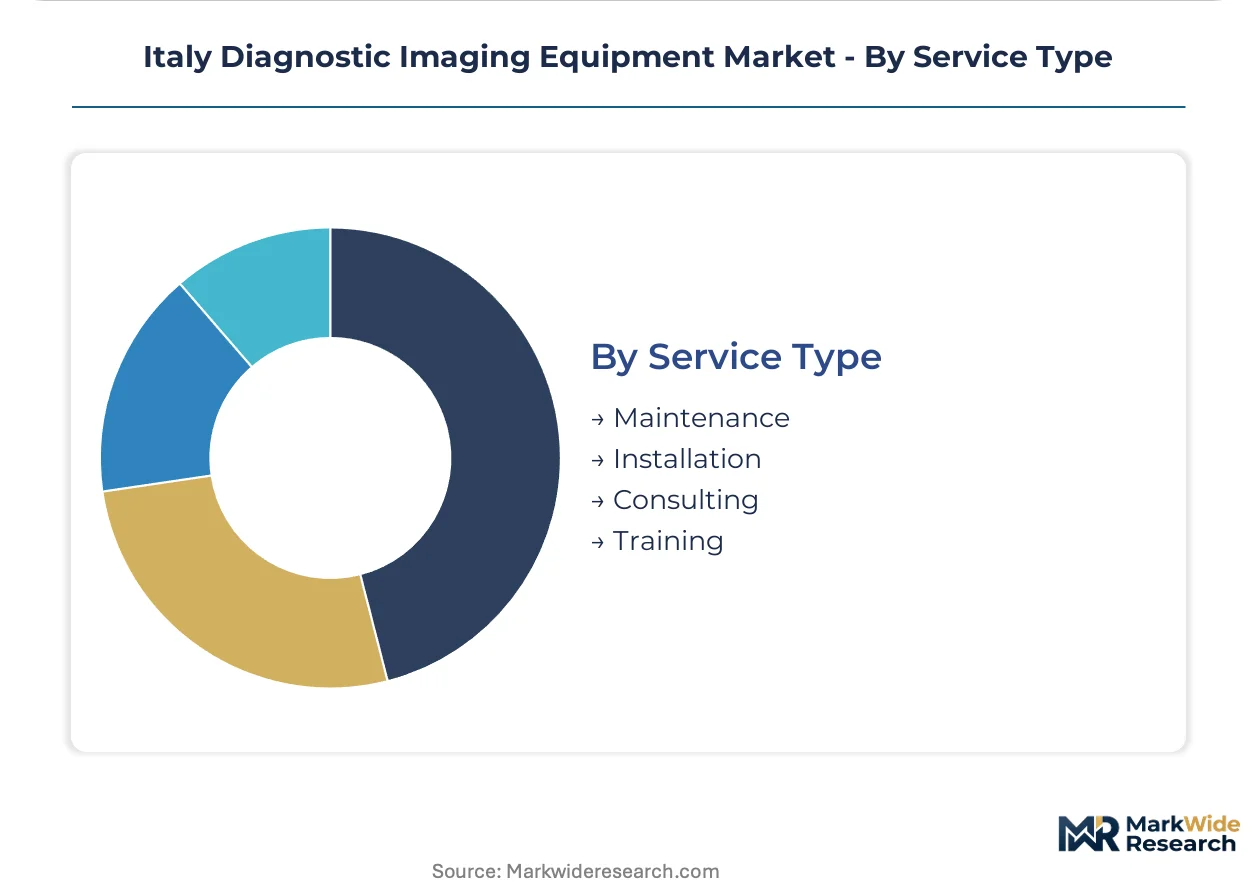
Service Type:
Procurement unbundling is separating hardware acquisition from lifecycle support, enabling multi-vendor service ecosystems and specialized technical partnerships.
- Maintenance:Comprehensive service contracts covering magnet cryogen management, gradient coil calibration, and detector replacement dominate premium system ownership. Superconducting magnet maintenance requires specialized technicians concentrated in northern industrial corridors.
- Installation:RF shielding construction, vibration isolation, and electrical conditioning for MRI systems often exceed equipment purchase costs in historic hospital buildings.
- Consulting:Workflow optimization and teleradiology infrastructure planning support digital transformation mandates from regional health authorities.
- Training:Technologist certification for advanced sequences and AI-assisted interpretation tools addresses skill gaps in underpenetrated provinces.
Recurring revenue concentrates in Maintenance. Fastest-growing engagement model is Consulting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Helium supply routes from Qatar and the United States feed superconducting magnet cooling across Italian MRI installations, anchoring procurement geography to liquefaction port infrastructure at Genoa and Trieste.
Lombardy
Milan's Policlinico and Humanitas Research Hospital drive 3 Tesla MRI adoption for neurovascular protocols. The Agenzia Italiana del Farmaco coordinates regional CE marking enforcement timelines for new device registrations. Dense hospital networks across Bergamo and Brescia concentrate procurement authority for high-throughput CT configurations.
Piedmont
Turin's Molinette Hospital anchors academic imaging research with advanced cardiac MRI capabilities. Regional health authority budgets mandate DICOM compliance as a condition of capital funding approval. The metropolitan corridor linking Turin to Novara sustains service technician clusters for superconducting magnet maintenance.
Emilia-Romagna
Bologna's Sant'Orsola-Malpighi Hospital leads spectral CT pilot programs for oncology staging. EU MDR conformity assessment protocols filter procurement toward certified suppliers with sustained technical documentation capabilities. The biomedical manufacturing belt around Modena and Parma hosts imaging component subcontractors.
Veneto
Padua's university hospital network drives interventional radiology hybrid suite expansion. Regional digitization mandates create bundled procurement opportunities for PACS-native acquisition systems. The industrial corridor between Verona and Vicenza concentrates diagnostic center chains competing on subspecialty radiologist access.
Lazio
Rome's Policlinico Universitario Agostino Gemelli manages high-volume emergency CT throughput for central Italy referral networks. Ministry of Health procurement frameworks influence capital allocation across public acute-care facilities. Aging infrastructure in historic hospital buildings inflates RF shielding installation costs beyond equipment purchase prices.
Italy Diagnostic Imaging Equipment Market Competitive Landscape
Global majors compete with regional champions across service network density and regulatory compliance capabilities. Siemens Healthineers and GE Healthcare anchor premium-tier procurement through extensive southern European service infrastructure, while Esaote and Gilardoni SpA occupy specialized positions in musculoskeletal MRI and domestic manufacturing. Three archetypes define competitive positioning: integrated multinationals with full-modality portfolios, regional specialists leveraging geographic proximity for service response times, and component fabricators supplying detector subsystems and RF coils. M&A activity concentrates on teleradiology software capabilities, while strategic partnerships address EU AI Act documentation requirements for machine-learning diagnostic tools.
Among Italy-based enterprises, Esaote exemplifies the regional specialist archetype through its Genoa headquarters and dedicated MRI systems for musculoskeletal applications. Gilardoni SpA and Italray occupy positions within the domestic component fabrication tier, supplying imaging hardware elements and maintenance services to public hospital networks. Siemens Healthineers represents the integrated multinational archetype, anchoring southern European operations through service networks covering Italian hospitals. These three enterprises illustrate how competitive positioning stratifies across global scale, regional specialization, and domestic manufacturing proximity.
| Leading Market Players |
|---|
| Canon Medical Systems |
| Esaote |
| Siemens Healthineers |
| Gilardoni SpA |
| Italray |
| GE Healthcare |
| FUJIFILM |
| Hologic |
| Koninklijke Philips |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap specialists like Esaote and Gilardoni SpA anchor Italy's domestic manufacturing tier, their concentrated ownership structures enabling long-term service contract pricing discipline while insulating procurement negotiations from quarterly earnings pressure. This ownership pattern reinforces supply stability across superconducting magnet maintenance networks and RF coil fabrication, concentrating pricing power in northern industrial corridors where technical labor clusters.
Pricing Analysis
Warranty and service bundling separates premium-tier procurement from unbundled hardware transactions now penetrating Piedmont and Veneto public tenders. Three-tier pricing structure across premium, standard, and economy levels stratifies by magnetic field strength and detector architecture, with 3 Tesla MRI systems commanding substantial premiums over 1.5 Tesla platforms. Cost compression in mid-tier CT configurations is intensifying because regional health authorities mandate DICOM compliance as a funding condition. Diagnostic center chains exhibit highest price sensitivity, while academic medical centers prioritize throughput economics over capital expenditure minimization.
Supply Chain Analysis
Direct-to-hospital channels handle premium system deployments, while distributor networks serve mid-sized diagnostic centers and outpatient clinics across southern provinces. Superconducting magnet fabrication draws from Germany, the United States, and Japan, with helium liquefaction tethered to Qatar and US sourcing through Genoa and Trieste port infrastructure. Cadmium telluride detector substrates and gradient coil windings represent critical component dependencies. Single-source vulnerability in helium supply exposes Italian operators to allocation risk during global shortages. Distribution runs through authorized service partnerships for maintenance and cryogen management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into superconducting magnet servicing and AI algorithm development is accelerating as manufacturers seek captive control over lifecycle revenue streams and regulatory documentation. Incumbents and challengers alike are pursuing downstream service unbundling to capture recurring revenue independent of hardware replacement cycles.
For Market Incumbents: Hedge against EU AI Act compliance cost escalation by consolidating technical documentation capabilities and acquiring teleradiology software specialists. Backward integration into helium recycling infrastructure addresses supply concentration risk from Qatar and US sourcing. Certification investment in MDR Class III documentation creates defensive moats against lower-tier competitors lacking sustained regulatory affairs capacity. For New Entrants and Emerging Players: Cloud-based teleradiology platforms offer the lowest-friction entry vector for penetrating underprovisioned provinces in Sicily and Calabria. Point-of-care ultrasound for emergency department triage represents the most penetrable white space, with rural clinic networks seeking cardiac and abdominal imaging without capital-intensive MRI infrastructure. Subscription-based service models align with regional health authority digitization mandates. For Investors and Strategic Acquirers: Agenzia Italiana del Farmaco enforcement timeline acceleration is the leading indicator that MDR compliance capabilities will concentrate procurement among certified suppliers. Long-term viability favors enterprises with integrated hardware-software portfolios and established service technician networks. Acquisition targets should demonstrate documented training data provenance for machine-learning diagnostic tools and established CE marking pathways.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR Class III documentation accelerates market access for certified suppliers ahead of enforcement deadlines. |
| Hospital System Partnership | Bundled procurement with Lombardy and Emilia-Romagna networks secures high-throughput installation commitments. |
| Software Companion Development | AI-assisted reconstruction algorithms embedded in CT platforms differentiate spectral imaging offerings. |
| Backward Integration into Servicing | Cryogen management and gradient coil maintenance capture recurring revenue independent of hardware sales. |
| Reimbursement Strategy | Alignment with regional health authority procedure codes ensures sustainable utilization economics for diagnostic centers. |
Research Methodology
Independent corroboration across hospital purchasing committee interviews, biomedical engineer consultations, and GPO contracts managers underwrites the qualitative findings on procurement prioritization and vendor selection criteria. Secondary validation draws from Agenzia Italiana del Farmaco registration databases, EU MDR technical documentation filings, and regional health authority capital expenditure disclosures. Bottom-up demand modeling from installed base replacement cycles and top-down market sizing from equipment shipment tracking were reconciled to establish segmentation splits.
Comparable historical reference periods anchored the projection horizon to post-pandemic healthcare modernization budget cycles and EU regulatory transition timelines. The analytical framework models product type, end user facility class, technology generation, and service unbundling status as core segmentation dimensions. CAGRs were derived from weighted average replacement rates and regional budget growth trajectories. Forecast inputs incorporate superconducting magnet shipment data and helium price volatility indices.
The model holds under stable EU MDR enforcement timelines and continued regional health authority digitization mandates; deviation in AI Act classification determinations or helium supply disruptions would shift equipment procurement pacing and vendor competitive positioning. Periodic stress-testing of base assumptions against Agenzia Italiana del Farmaco policy updates and Ministry of Health procurement framework revisions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Digital Radiography Detectors Market
Medical Imaging
Small Animal Imaging (in-Vivo) Market
Medical Imaging
Global CT Scanners Market
Medical Imaging
Germany Nuclear Imaging Market
Medical Imaging
Diagnostic Imaging Market
Medical Imaging
Latin America Medical Imaging Software Market
Medical Imaging
North America Nuclear Medicine Market
Medical Imaging
AI-Assisted Radiology Market
Medical Imaging
Chile Diagnostic Imaging Equipment Market
Medical Imaging
Stationary Anode CT X-Ray Tube Market
Medical Imaging
Breast Imaging Technologies Market
Medical Imaging
Image Guided Therapy Market
Medical Imaging
Japan Diagnostic Imaging Equipment Market
Medical Imaging
Angiography Imaging Systems Market
Medical Imaging
Remanufactured Medical Imaging Devices Market
Medical Imaging
United Kingdom Diagnostic Imaging Equipment Market