
 Portable X-Ray Devices Market | 2026-2036
Portable X-Ray Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Portable X-Ray Devices Market Outlook
Leasing and pay-per-scan financing is fragmenting the competitive landscape for portable imaging systems. GE HealthCare leverages its installed base of hospital equipment to anchor long-term service contracts. Siemens Healthineers AG differentiates through integrated digital workflow platforms that extend beyond hardware sales. Koninklijke Philips N.V. competes on compact system design that occupies premium ambulance and field-hospital segments.
Portable X-ray devices are self-contained radiographic systems typically operating at 5-40 kV with battery-powered generators and flat-panel digital detectors, designed to capture diagnostic images outside fixed radiology departments. Mobile and handheld product types are capturing disproportionate investment as health systems prioritize bedside and field-deployable imaging over fixed installations. Digital X-ray technology leads volume while computed radiography retains share in budget-constrained clinics where retrofit economics dominate upgrade decisions.
FDA 510(k) premarket notification and EU MDR conformity assessment shape product development timelines and commercial access across North America and Europe. Japan's PMDA and METI standards govern detector sensitivity and radiation dose thresholds that manufacturers must satisfy for market entry. Stakeholders must weigh regulatory compliance costs against the margin compression from financing-driven procurement models that favor asset-light vendors.
Market Dynamics
Hospital decentralization policies across Germany are accelerating point-of-care imaging deployment outside fixed radiology departments, compressing capital allocation toward mobile systems and fragmenting traditional equipment procurement hierarchies.
Growth Catalysts
- EU MDR Conformity Assessment:Streamlined device certification pathways in Europe are shortening product development cycles for digital imaging systems, enabling faster commercialization of next-generation portable units.
- Emergency Care Centers:United States trauma facilities are expanding mobile radiography capacity to reduce patient transport risks and accelerate triage decisions in critical care settings.
- Amorphous Selenium Detectors:Direct-conversion flat-panel technology is improving image quality at lower radiation doses, expanding clinical applications beyond skeletal imaging into soft-tissue diagnostics.
Market Restraints
- Lithium-Ion Battery Supply Concentration:Dependence on East Asian cell manufacturers creates input cost volatility and geopolitical exposure for battery-powered generator systems.
- FDA 510(k) Substantial Equivalence:Predicate device requirements for digital imaging systems create regulatory friction that delays market entry for novel detector architectures.
- Computed Radiography Retrofit Economics:Budget-constrained clinics in rural United States markets prolong equipment lifecycles through phosphor plate upgrades rather than full digital replacement.
Strategic Opportunities
- Japan PMDA Detector Sensitivity Standards:Stringent national requirements for radiation dose thresholds create premium positioning opportunities for manufacturers exceeding baseline compliance.
- Pay-per-Scan Financing Models:Asset-light procurement structures are opening hospital networks previously inaccessible to capital-intensive equipment vendors, particularly in German outpatient clinics.
- Telemedicine Integration:Cloud-native diagnostic workflows converging with 5G field connectivity are enabling real-time radiologist consultation for ambulance and disaster-response deployments.
Industry Challenges
- Medical Physics Specialist Shortage:Qualified personnel for equipment calibration and radiation safety compliance are scarce in United States rural health systems, constraining deployment velocity.
- Legacy PACS Integration Complexity:Hospital information systems built on decade-old architectures require costly middleware development to accommodate wireless digital detector protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable X-Ray Devices Market |
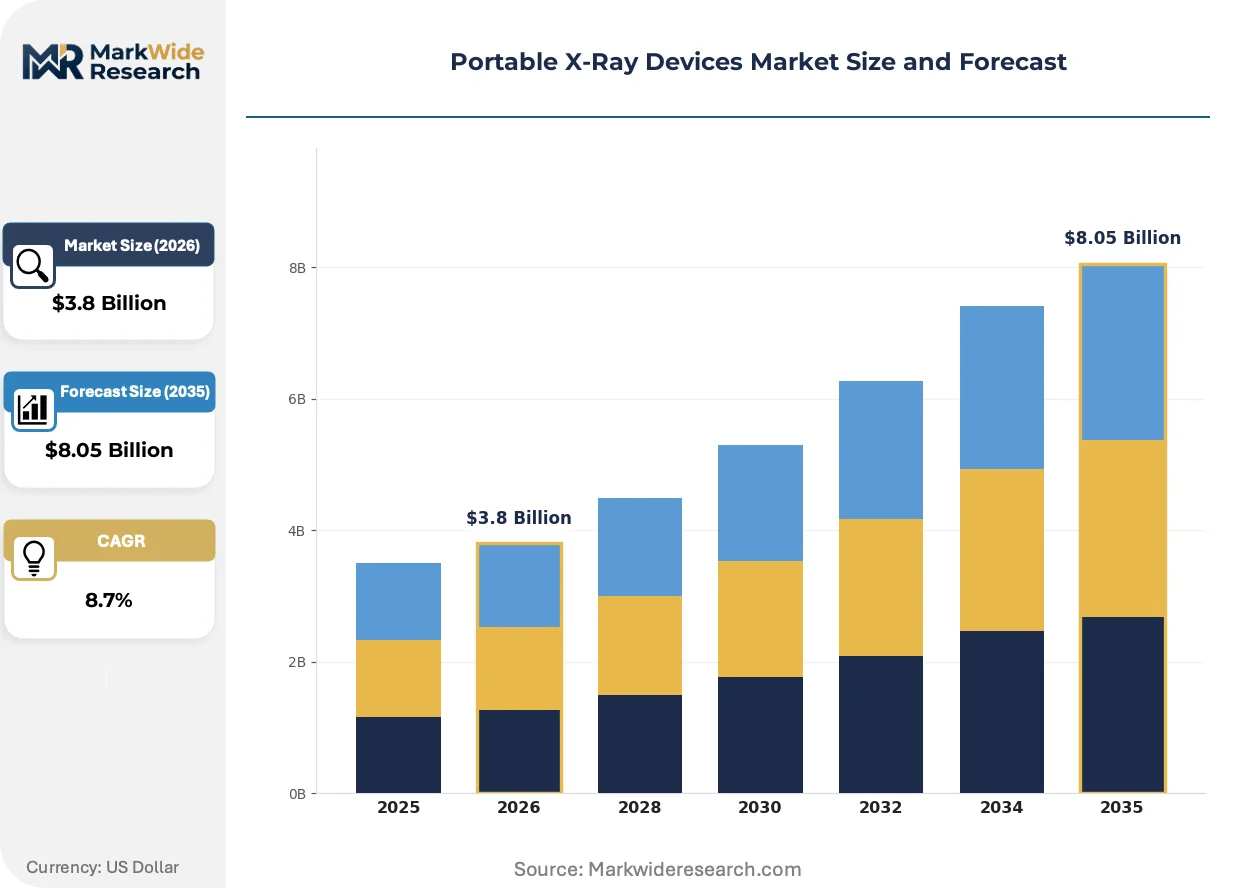
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
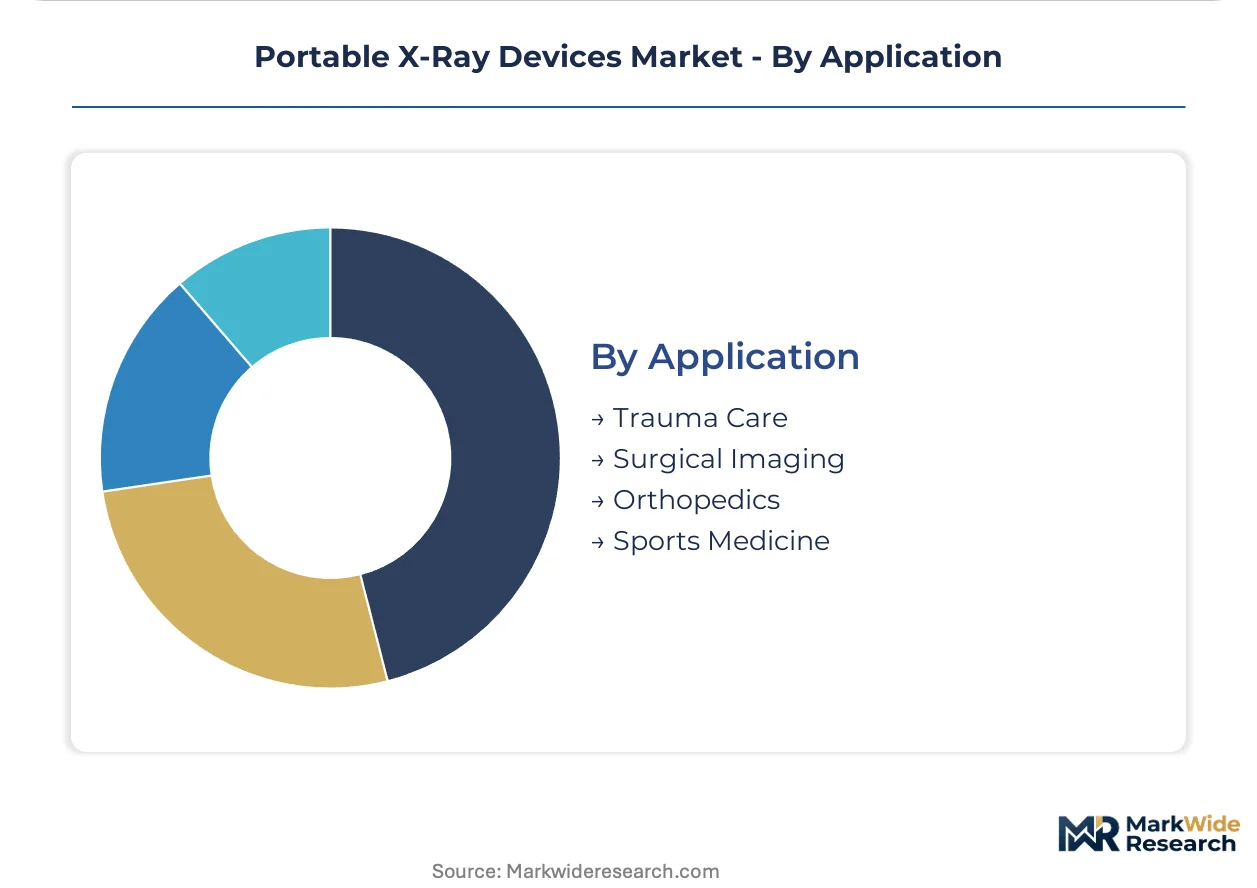
| Segmentation | Product Type: Handheld, Mobile, Fixed, Wireless Technology: Digital X-Ray, Computed Radiography, Traditional Radiography, Portable Ultrasound End User: Hospitals, Emergency Care Centers, Clinics, Home Healthcare Application: Trauma Care, Surgical Imaging, Orthopedics, Sports Medicine |
| Companies Covered | Koninklijke Philips N.V., Carestream Health, GE HealthCare, Ziehm Imaging, Shimadzu Corporation, Siemens Healthineers AG, Fujifilm Holdings Corporation, Konica Minolta, Inc., Canon Medical Systems Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable X-Ray Devices Market Strategic Shifts
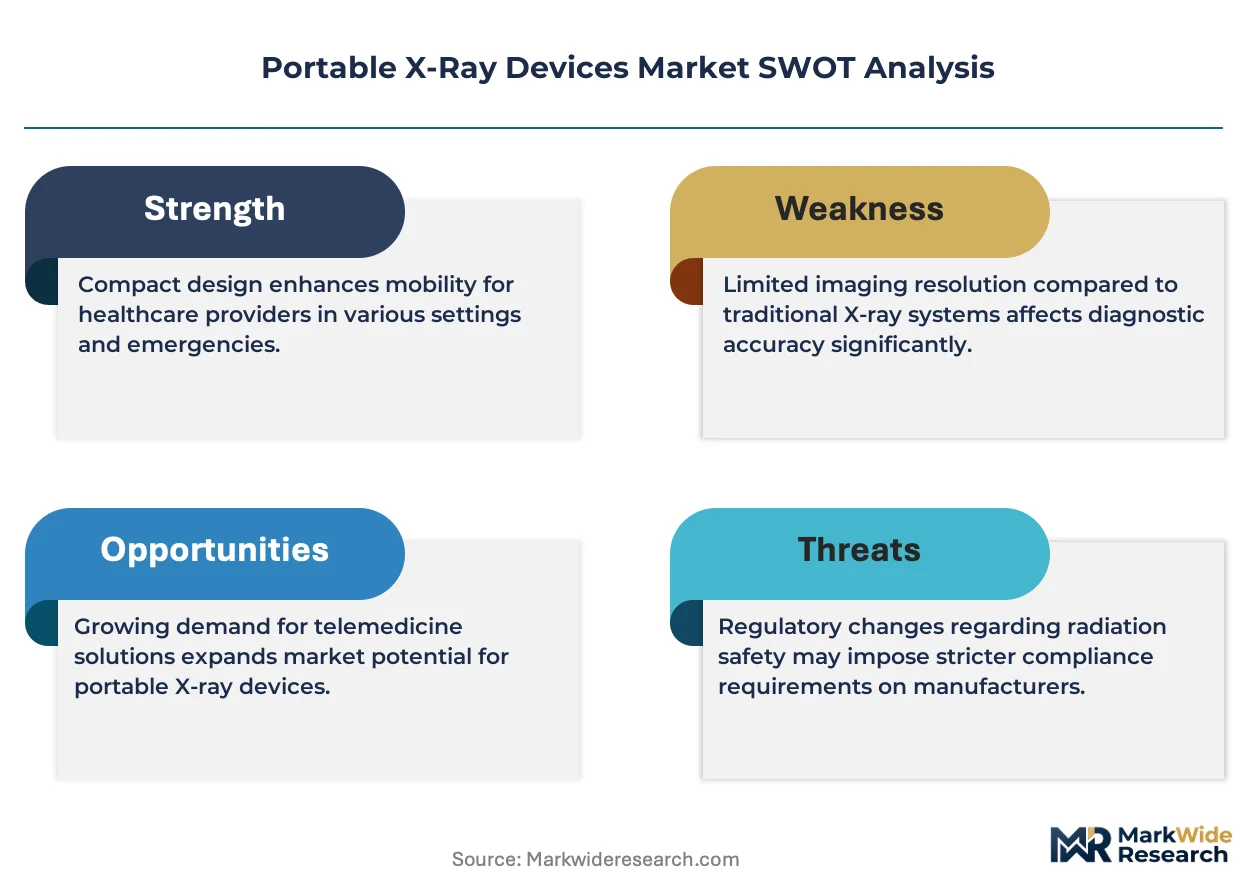
Portable X-ray technology is undergoing rapid capability convergence as detector sensitivity improvements, battery energy density gains, and wireless data transmission standards simultaneously mature, collapsing the performance gap between mobile and fixed-room systems.
Digital flat-panel detector technology is migrating from amorphous silicon photodiode arrays toward direct-conversion selenium and cadmium-zinc-telluride architectures that eliminate intermediate scintillation layers. United States hospital systems with high patient throughput are adopting these detectors to reduce exposure times and improve workflow efficiency. The shift is migrating from niche orthopedic applications toward mainstream chest and abdominal imaging, compressing the addressable market for legacy computed radiography retrofit solutions.
EU MDR Article 10 technical documentation requirements are mandating enhanced clinical evidence for digital imaging systems, forcing manufacturers to maintain more rigorous post-market surveillance. This regulatory tightening is elevating compliance costs for smaller vendors while creating competitive moats for established players with dedicated regulatory affairs infrastructure. German notified bodies are experiencing backlog congestion, delaying CE marking timelines and compressing product launch windows across European markets.
Asset-light procurement models are displacing traditional capital purchase structures in United States health systems facing margin pressure from reimbursement compression. Hospital networks are unbundling equipment ownership from service contracts, favoring vendors offering operational expenditure-based financing. This behavioral shift is most visible in emergency department expansions across Texas and Florida, where administrators prioritize cash-flow flexibility over balance-sheet asset accumulation.
Portable X-Ray Devices Market Segmentation
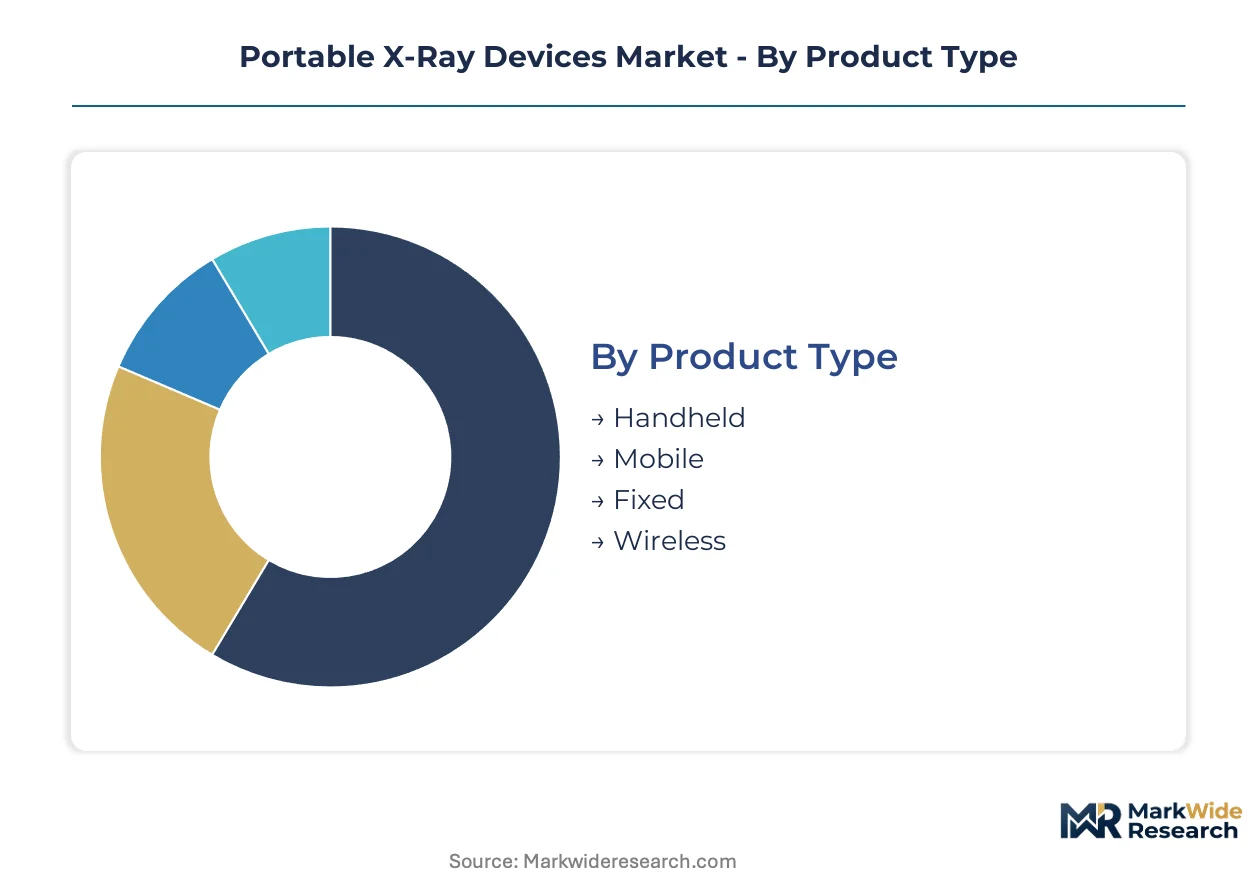
Portable X-ray segmentation reveals divergent equipment lifecycles across product architectures, with battery-powered mobile units turning over every 4-6 years versus 10-15 year depreciation schedules for fixed installations. Technology choices further stratify procurement patterns, separating health systems prioritizing workflow integration from budget-constrained facilities extending legacy phosphor plate systems.
Product Type:
Replacement velocity varies dramatically across form factors, with handheld systems cycling fastest due to battery degradation and detector fragility, while wireless retrofit kits extend existing mobile chassis lifespans.
- Handheld:Compact battery-powered units weighing under 5 kg integrate flat-panel detectors with onboard image processing. German outpatient clinics favor these for house-call radiography under decentralized care mandates. Battery chemistry limitations drive 4-6 year replacement cycles regardless of mechanical condition.
- Mobile:Motorized radiography systems with telescoping columns and integrated generators serve bedside imaging in United States emergency departments. Hospital networks in Texas and Florida prioritize these for patient transport risk reduction. These units anchor manufacturer service contract revenues through decade-long depreciation schedules.
- Fixed:Ceiling-suspended or floor-mounted systems in dedicated radiology suites retain longest operational lifespans. Rural United States clinics maintain these through phosphor plate retrofits rather than full digital conversion.
- Wireless:Detector-only upgrades convert existing mobile chassis to cable-free operation. United States health systems facing reimbursement compression favor this capital-light pathway over full system replacement.
Mobile systems anchor the volume base while handheld configurations gain share at the steepest rate.
Technology:
Cost tier separation distinguishes premium direct-conversion architectures from economy phosphor plate systems, with mid-market amorphous silicon arrays capturing hospital procurement.
- Digital X-Ray:Direct-conversion selenium and cadmium-zinc-telluride detectors eliminate scintillation layers for improved dose efficiency. United States trauma centers adopt these for high-throughput chest imaging. FDA 510(k) clearance pathways favor predicate-based submissions for iterative detector improvements.
- Computed Radiography:Photostimulable phosphor plate systems with laser scanning digitization dominate budget-constrained rural United States clinics. Retrofit economics prolong equipment lifecycles through plate replacement rather than detector upgrade. Reimbursement compression reinforces reliance on depreciated capital assets.
- Traditional Radiography:Analog film-screen combinations persist in select developing markets and veterinary applications. Regulatory pressure for dose documentation accelerates obsolescence outside niche segments.
- Portable Ultrasound:Complementary point-of-care imaging modality with overlapping clinical indications in emergency and sports medicine settings. Battery-powered cart-based and handheld configurations compete for capital allocation against radiographic alternatives.
Computed Radiography retains installed base dominance while Digital X-Ray climbs fastest in new procurement.
End User:
Customer type determines financing structure preferences, separating capital-rich hospital networks from cash-constrained independent practices seeking operational expenditure models.
- Hospitals:Integrated delivery networks with dedicated radiology departments and in-house medical physics support. German hospital decentralization policies fragment procurement authority toward individual department managers.
- Emergency Care Centers:United States trauma facilities expanding mobile radiography capacity for triage acceleration. Texas and Florida lead emergency department imaging infrastructure investment.
- Clinics:Outpatient settings in Germany favor pay-per-scan financing under decentralized diagnostic mandates. Asset-light procurement opens vendor access previously blocked by capital purchase requirements.
- Home Healthcare:Emerging deployment segment for palliative care and post-surgical monitoring in patient residences. Reimbursement coding limitations constrain commercial scale.
Hospitals command procurement volume leadership while Emergency Care Centers demonstrate the steepest expansion trajectory.
Application:
Clinical use case determines detector specification requirements, with trauma and surgical applications demanding rapid image availability versus orthopedic tolerance for longer exposure protocols.
- Trauma Care:Time-critical imaging for fracture identification and internal injury assessment in United States emergency departments. Mobile radiography reduces patient transport risks during initial stabilization.
- Surgical Imaging:Intraoperative verification of implant placement and anatomical alignment. C-arm compatibility requirements influence detector form factor selection.
- Orthopedics:Skeletal imaging with tolerance for longer positioning and exposure times. Direct-conversion detectors penetrate this segment from established extremity imaging applications.
- Sports Medicine:Field-side and training facility deployment for immediate injury assessment. Compact handheld units serve professional and collegiate athletic programs.
Trauma Care anchors clinical volume while Sports Medicine gains share most rapidly through field-deployable system adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement officers in Germany, emergency department administrators in Texas, and decentralized clinic operators in Japan drive distinct purchasing behaviors across portable X-ray markets. These buyer archetypes concentrate demand in specific national regulatory environments that shape product specification and financing structure preferences.
United States
Emergency care centers in Texas and Florida expand mobile radiography capacity to reduce patient transport risks during trauma triage. FDA 510(k) premarket notification requirements compress product development cycles for iterative detector improvements. The Greater Houston medical corridor anchors hospital network procurement consolidation, with administrators prioritizing operational expenditure financing over capital purchase structures.
Germany
Hospital decentralization policies fragment procurement authority toward individual department managers in outpatient clinics. EU MDR conformity assessment and Article 10 technical documentation requirements elevate compliance costs for digital imaging systems. The Rhine-Ruhr metropolitan region concentrates notified body activity, though backlog congestion delays CE marking timelines for manufacturers seeking market entry.
Japan
Trauma centers in Tokyo and Osaka adopt direct-conversion detectors for high-throughput chest imaging applications. PMDA and METI standards govern detector sensitivity and radiation dose thresholds that manufacturers must satisfy for commercial access. The Kanto region surrounding Tokyo anchors domestic medical device distribution networks, with metropolitan hospitals leading adoption of compact field-deployable systems.
United Kingdom
NHS procurement frameworks favor asset-light leasing models that unbundle equipment ownership from long-term service contracts. MHRA post-Brexit regulatory alignment with EU MDR technical standards maintains continuity in device certification pathways. The Cambridge-Oxford-London triangle concentrates medical physics specialist talent, enabling faster deployment velocity for wireless detector protocol integration.
China
Tier-2 city hospitals accelerate digital flat-panel detector adoption as NMPA streamlines innovative device review pathways for domestic manufacturers. National reimbursement reform compresses capital allocation timelines toward mobile systems in provincial medical centers. The Yangtze River Delta manufacturing corridor supplies battery-powered generator components, though lithium-ion cell concentration in East Asia creates input cost volatility.
Portable X-Ray Devices Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented procurement hierarchies. The vendor base stratifies between diversified imaging conglomerates with installed base leverage and focused detector technology developers. Three archetypes dominate: hospital network service contract anchors, workflow-integrated platform providers, and compact form factor specialists. M&A activity concentrates on digital detector technology acquisitions, while strategic partnerships target telemedicine integration capabilities.
Within the diversified imaging systems tier, Koninklijke Philips N.V., GE HealthCare, and Siemens Healthineers AG represent distinct geographic and structural positioning. The Dutch-originated entity exemplifies compact system design specialization for premium ambulance segments. The US-based conglomerate anchors long-term service contract revenues through hospital equipment installed base leverage. The German AG structure occupies integrated digital workflow platform positioning that extends beyond hardware transaction economics.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Carestream Health |
| GE HealthCare |
| Ziehm Imaging |
| Shimadzu Corporation |
| Siemens Healthineers AG |
| Fujifilm Holdings Corporation |
| Konica Minolta, Inc. |
| Canon Medical Systems Corporation |
| Others |
Value Chain & Pricing Dynamics
The Yangtze River Delta freight corridor carries selenium wafer and lithium-ion cell shipments whose cost volatility feeds directly into detector manufacturing economics, concentrating pricing power with East Asian component suppliers while forcing Western OEMs to differentiate through service bundling and financing structures.
Pricing Analysis
Cost-plus contracts with lithium carbonate indexation dominate battery procurement for mobile generator systems. Three-tier pricing structure across premium direct-conversion, standard amorphous silicon, and economy computed radiography levels separates FDA-cleared trauma systems from rural clinic retrofit kits. Pricing pressure stems from pay-per-scan financing adoption in German outpatient clinics. Emergency care centers in Texas demonstrate lowest price sensitivity due to patient transport risk reduction value, while rural United States clinics face acute budget constraints.
Supply Chain Analysis
Upstream feedstock for amorphous selenium detectors draws from specialized chemical refiners in Japan and Germany, with lithium-ion cells sourcing predominantly from South Korea and China. Critical dependencies include high-purity selenium, cadmium-zinc-telluride substrates, and medical-grade battery management systems. Single-source vulnerability concentrates in East Asian cell manufacturers facing geopolitical friction. Distribution runs through hospital GPO contracts in the United States and direct manufacturer relationships in decentralized German procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Portable X-ray incumbents must defend against point-of-care ultrasound substitution in emergency triage applications, where compact sonography systems compete for capital allocation in ambulance and field-hospital deployments.
For Market Incumbents: Pre-empt detector commoditization by anchoring long-term service contracts through wireless workflow platform integration. Defend against handheld ultrasound erosion by embedding AI-assisted image interpretation that accelerates radiologist throughput. Backward integration into battery pack assembly mitigates East Asian cell supply concentration.
For New Entrants and Emerging Players: Build out pay-per-scan financing infrastructure to access German outpatient clinics previously blocked by capital purchase barriers. Target home healthcare palliative imaging where reimbursement coding gaps create incumbent hesitation. Lead with cloud-native PACS integration that bypasses legacy hospital information system middleware costs.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified imaging conglomerates seeking to divest non-core detector manufacturing units. Long-term viability hinges on software-defined workflow platforms rather than hardware transaction economics. Watch FDA 510(k) clearance velocity for novel direct-conversion architectures as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Article 10 Compliance Investment | CE marking backlog at German notified bodies creates first-mover advantage for prepared manufacturers. |
| Telemedicine Platform Partnership | 5G-enabled real-time radiologist consultation unlocks ambulance and disaster-response deployment segments. |
| Amorphous Selenium Detector Scale-Up | Direct-conversion technology migration from orthopedic niche toward chest imaging expands addressable market. |
| Pay-per-Scan Financing Infrastructure | Asset-light procurement opens hospital networks previously inaccessible to capital-intensive equipment vendors. |
| Wireless PACS Protocol Development | Legacy hospital information system integration complexity creates competitive moat for cloud-native entrants. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital biomedical engineers, emergency department administrators, GPO contracts managers, and portable imaging OEM product directors. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR Article 10 technical documentation, hospital procurement contract filings, and CMS Medicare reimbursement schedules. Bottom-up equipment shipment estimates triangulated against top-down health system capital expenditure surveys.
Calibration against historical replacement cycle data and regulatory approval timelines anchored volume projections across the analysis window. Segmentation dimensions modeled include product form factor, detector technology architecture, end-user financing structure, and clinical application intensity. CAGRs derived from equipment lifecycle velocity and technology transition elasticity, with specific inputs for battery degradation curves and EU MDR notified body processing rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by handheld ultrasound specialists or cloud-native imaging platforms would shift outcomes. Cross-checking against hospital capital expenditure survey benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Mexico Diagnostic Imaging Equipment Market
Medical Imaging
Surgical Imaging Robots Market
Medical Imaging
Quantitative Pathology Imaging Market
Medical Imaging
South Africa Computed Tomography Market
Medical Imaging
China Diagnostic Imaging Equipment Market
Medical Imaging
Japan Nuclear Imaging Market
Medical Imaging
China Computed Tomography Market
Medical Imaging
Medical X-Ray Films Market
Medical Imaging
Computed Tomography (CT) Scanners Market
Medical Imaging
Mammography Workstation Market
Medical Imaging
North America MRI (Magnetic Resonance Imaging) Market
Medical Imaging
Global Surgical Imaging Arms Market
Medical Imaging
Digital Pathology Market
Medical Imaging
Transesophageal Echocardiography (TEE) Market
Medical Imaging
Functional Brain Imaging Systems Market
Medical Imaging
X-Ray Devices Market