
 South America Nuclear Imaging Market | 2026-2036
South America Nuclear Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
South America Nuclear Imaging Market Analytics
Aftermarket service revenue is tilting toward hybrid imaging system maintenance contracts as installed PET-CT and SPECT-CT bases mature across South America. Siemens Healthineers leverages its regional service hubs in São Paulo to sustain long-term equipment uptime agreements. GE HealthCare anchors its position through radiopharmaceutical distribution partnerships with local cyclotron facilities. Koninklijke Philips differentiates via digital detector upgrade pathways that extend legacy gamma camera operational life.
Nuclear imaging deploys radiolabeled tracers detected by gamma cameras, PET scanners, or SPECT systems to visualize metabolic and functional processes, with spatial resolution for PET typically reaching 4-6 millimeters and radiopharmaceutical half-lives ranging from minutes to days depending on the isotope. Positron Emission Tomography equipment commands the dominant share of capital expenditure as hybrid PET-CT configurations become standard for oncology staging in tertiary hospitals. Software Analytics represents the fastest-expanding technology segment as AI-assisted quantification tools reduce interpretation variability and accelerate reporting workflows across Diagnostic Centers.
ANVISA governs radiopharmaceutical registration and manufacturing facility inspections in Brazil, while Argentina's national pharmaceutical regulator enforces import licensing for technetium generators and fluorodeoxyglucose kits. These frameworks shape market access timelines and cold-chain logistics requirements for tracer suppliers. Stakeholders must monitor pending harmonization initiatives between Mercosur member states that could unify nuclear medicine device approval pathways.
Market Dynamics
Hybrid PET-CT configuration mandates from Brazil's largest hospital networks are compressing capital equipment replacement cycles while elevating software analytics procurement priority. ANVISA's streamlined radiopharmaceutical import pathways are simultaneously shortening product registration timelines and intensifying competition among tracer suppliers.
Growth Catalysts
- Oncology Staging Protocols:Hospital networks across Brazil and Argentina are expanding molecular imaging programs for cancer diagnosis and treatment monitoring. Tertiary care centers in São Paulo now require PET-CT capability as standard equipment.
- ANVISA Regulatory Modernization:Updated radiopharmaceutical import guidelines are reducing product registration timelines from 18 months to under 12 months. Cold-chain logistics requirements are being harmonized with international standards.
- AI-Assisted Quantification Tools:Diagnostic centers are deploying machine learning algorithms to reduce interpretation variability and accelerate reporting workflows. Software analytics now represents the fastest-expanding technology segment.
Market Restraints
- Isotope Supply Concentration:Technetium-99m and fluorodeoxyglucose production concentrates in a limited number of cyclotron facilities across the continent. Generator supply disruptions in Argentina directly impact Brazilian diagnostic center operations.
- Radiopharmaceutical Cold-Chain Costs:Tracer half-lives ranging from minutes to days impose specialized logistics requirements. Temperature-controlled transport infrastructure remains underdeveloped in northern Brazil and Paraguay.
- Capital Equipment Intensity:PET-CT systems require substantial upfront investment and dedicated shielded facility construction. SPECT-CT configurations offer lower resolution alternatives that constrain diagnostic confidence in certain oncology applications.
Strategic Opportunities
- Digital Detector Upgrade Pathways:Legacy gamma camera installed bases across Colombia and Chile present retrofit opportunities. Solid-state detector replacements extend operational life without full system replacement.
- Service Contract Unbundling:Aftermarket revenue is tilting toward discrete maintenance agreements rather than bundled equipment-service packages. Independent service organizations are capturing hybrid imaging system maintenance contracts.
- Mercosur Harmonization Initiatives:Pending regulatory alignment between member states could unify nuclear medicine device approval pathways. Unified standards would reduce redundant registration costs for multi-country operators.
Industry Challenges
- Nuclear Medicine Physician Scarcity:Interpretation of PET and SPECT studies requires specialized training that outpaces regional educational program output. São Paulo and Buenos Aires concentrate available expertise while interior regions face diagnostic reporting delays.
- Cyclotron Facility Certification Timelines:Good Manufacturing Practice compliance for radiopharmaceutical production requires extensive facility validation. Argentina's national pharmaceutical regulator enforces inspection protocols that extend commissioning schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Nuclear Imaging Market |
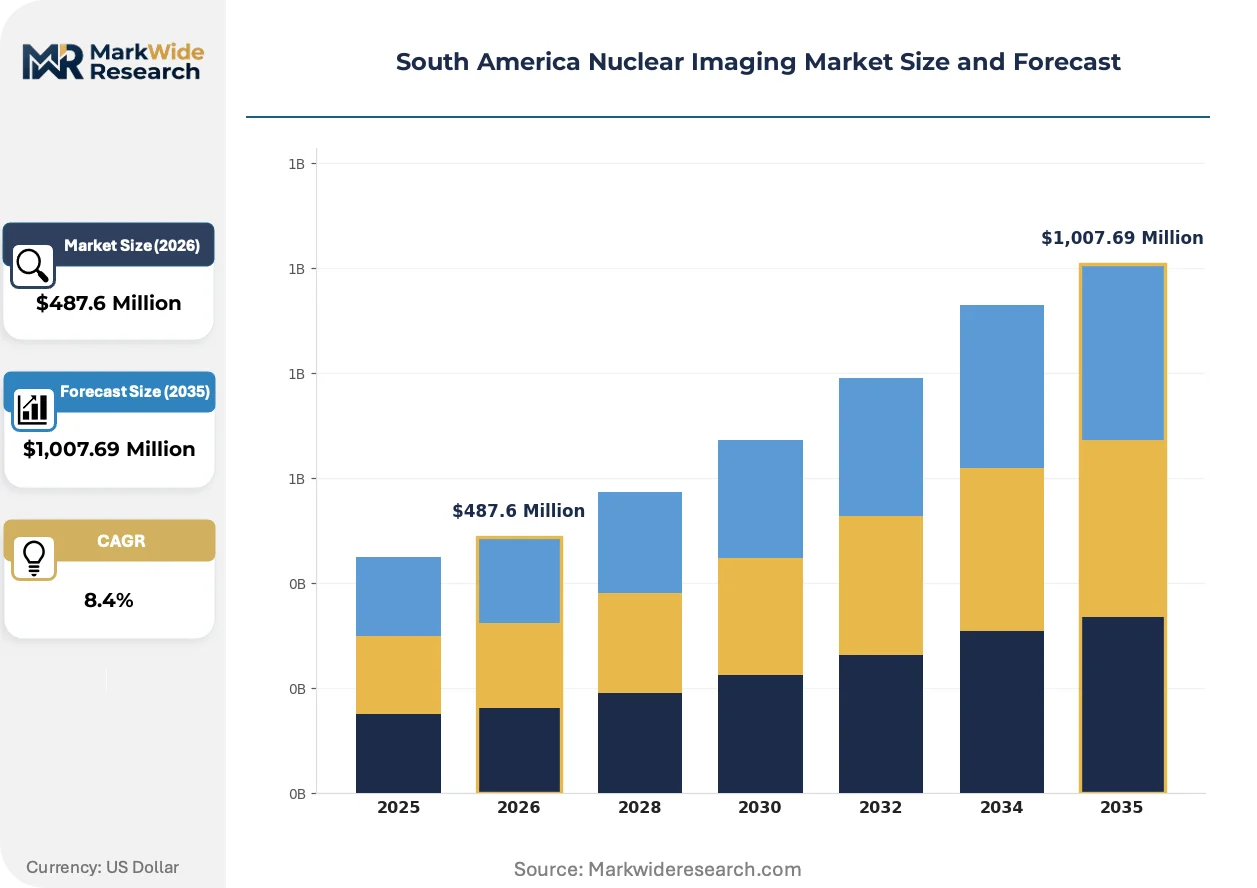
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,007.69 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Photon Emission Computed Tomography, Positron Emission Tomography, Gamma Cameras, Radiopharmaceuticals End User: Hospitals, Diagnostic Centers, Research Institutions, Ambulatory Surgical Centers Application: Oncology, Cardiology, Neurology, Thyroid Imaging Technology: Hybrid Imaging, 3D Imaging, Digital Detectors, Software Analytics |
| Companies Covered | GE HealthCare, Siemens Healthineers, Koninklijke Philips, Canon Medical Systems, Mallinckrodt, Hitachi Medical, Lantheus Medical Imaging, Cardinal Health, Bayer, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Nuclear Imaging Market Evolving Landscape
Artificial intelligence integration is compressing diagnostic reporting timelines while digital detector materials are extending legacy equipment operational life. Regulatory pathway simplification and procurement model evolution are simultaneously reshaping competitive positioning.
Silicon photomultiplier (SiPM) digital detectors are replacing photomultiplier tubes in gamma camera and PET system configurations. Diagnostic centers in Brazil's Southeast region are adopting SiPM-equipped systems to reduce maintenance requirements and improve energy resolution. The technology is migrating from premium-tier installations to mid-market hospital segments, compressing price differentiation between equipment tiers.
ANVISA's updated radiopharmaceutical registration framework is eliminating redundant documentation requirements for imported tracer kits. Manufacturing facility inspection protocols now accept third-party certification from recognized international bodies. Brazilian diagnostic centers are responding by diversifying supplier relationships beyond traditional single-source dependencies.
Equipment procurement through operational lease structures is displacing outright capital purchase in mid-sized diagnostic center expansion. São Paulo-based hospital networks are negotiating multi-year uptime agreements that bundle hardware, software, and maintenance into per-scan pricing. This shift is most visible in oncology staging departments where patient volume predictability supports outcome-based contracting models.
South America Nuclear Imaging Market Segmentation
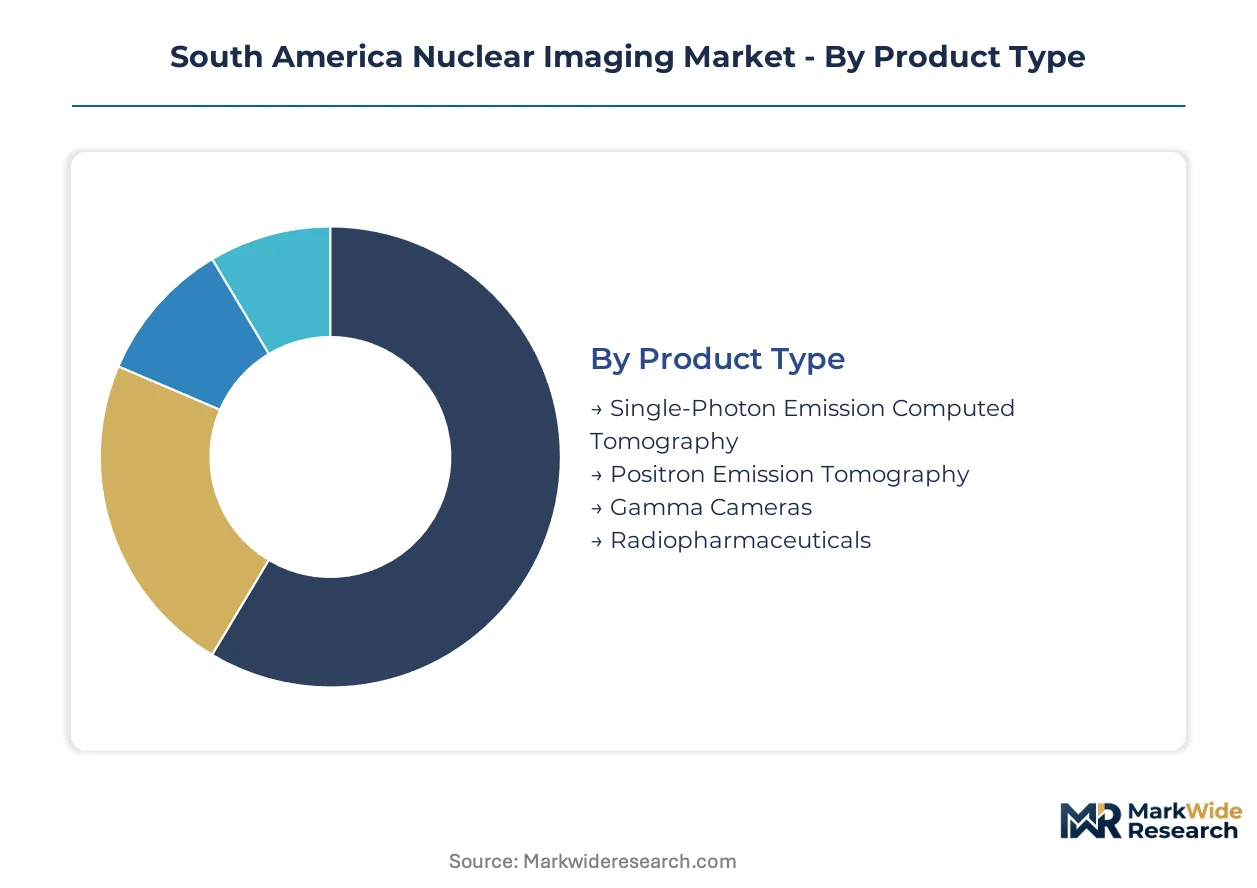
Nuclear imaging segmentation in South America reflects capital intensity gradients across product tiers, end-user scale disparities, and technology maturity curves. Category boundaries determine procurement pathways, regulatory exposure, and service contract structures.
Product Type:
Cost tier stratification separates premium hybrid configurations from legacy standalone systems and consumable tracer dependencies.
- Positron Emission Tomography:Hybrid PET-CT systems dominate capital expenditure with 4-6 millimeter spatial resolution capability. São Paulo's tertiary hospital networks mandate this configuration as standard equipment for oncology staging protocols.
- Radiopharmaceuticals:Technetium-99m generators and fluorodeoxyglucose kits require cold-chain logistics with half-lives ranging from minutes to days. ANVISA's streamlined import guidelines are shortening registration timelines for Brazilian diagnostic centers.
- Single-Photon Emission Computed Tomography:SPECT systems offer lower-resolution functional imaging at reduced capital thresholds. Interior regions of Brazil and Paraguay deploy these where PET-CT infrastructure remains economically prohibitive.
- Gamma Cameras:Legacy planar imaging systems persist in smaller diagnostic centers across Colombia and Chile. Solid-state detector retrofits extend operational life without full system replacement.
PET systems anchor installed capacity. Radiopharmaceuticals are climbing the fastest as tracer diversification accelerates.
End User:
Customer type determines procurement sophistication, with volume scale dictating lease-versus-buy structures and bundled service terms.
- Hospitals:Brazil's largest hospital networks negotiate multi-year uptime agreements bundling hardware, software, and maintenance into per-scan pricing. Southeast region facilities in São Paulo and Rio de Janeiro concentrate molecular imaging program expansion.
- Diagnostic Centers:Independent imaging chains deploy AI-assisted quantification tools to reduce interpretation variability and accelerate reporting workflows. Software analytics procurement priority is elevating rapidly in this segment.
- Research Institutions:Academic medical centers in Buenos Aires pursue clinical trial imaging protocols requiring specialized tracer synthesis capabilities. Cyclotron facility partnerships support investigational radiopharmaceutical access.
- Ambulatory Surgical Centers:Limited nuclear imaging deployment concentrates in thyroid uptake procedures and sentinel lymph node mapping. Capital constraints restrict PET-CT adoption in this setting.
Hospitals retain dominant installed base. Diagnostic centers are expanding most quickly through operational lease structures.
Application:
Clinical utility concentration varies by disease burden demographics and reimbursement pathway maturity across South American healthcare systems.
- Oncology:PET-CT staging for lung, colorectal, and lymphoma malignancies drives procedure volume. Hospital network procurement mandates in Brazil's Southeast region prioritize hybrid imaging capability for cancer treatment monitoring.
- Cardiology:Myocardial perfusion imaging using SPECT remains the workhorse application. Stress-rest protocols with technetium-99m sestamibi dominate where PET rubidium-82 availability is limited.
- Neurology:Amyloid-beta PET imaging for Alzheimer's disease evaluation is emerging in specialized centers. Reimbursement pathways remain underdeveloped outside Argentina's private insurance networks.
- Thyroid Imaging:Iodine-131 whole-body scanning and uptake quantification persist as standard-of-care. Gamma camera sufficiency for this application limits PET-CT penetration in thyroid-specific diagnostic centers.
Oncology commands procedure volume concentration. Neurology is gaining share fastest as dementia care infrastructure matures.
Technology:
Technology maturity curves separate established hybrid configurations from emerging digital detector materials and algorithmic interpretation tools.
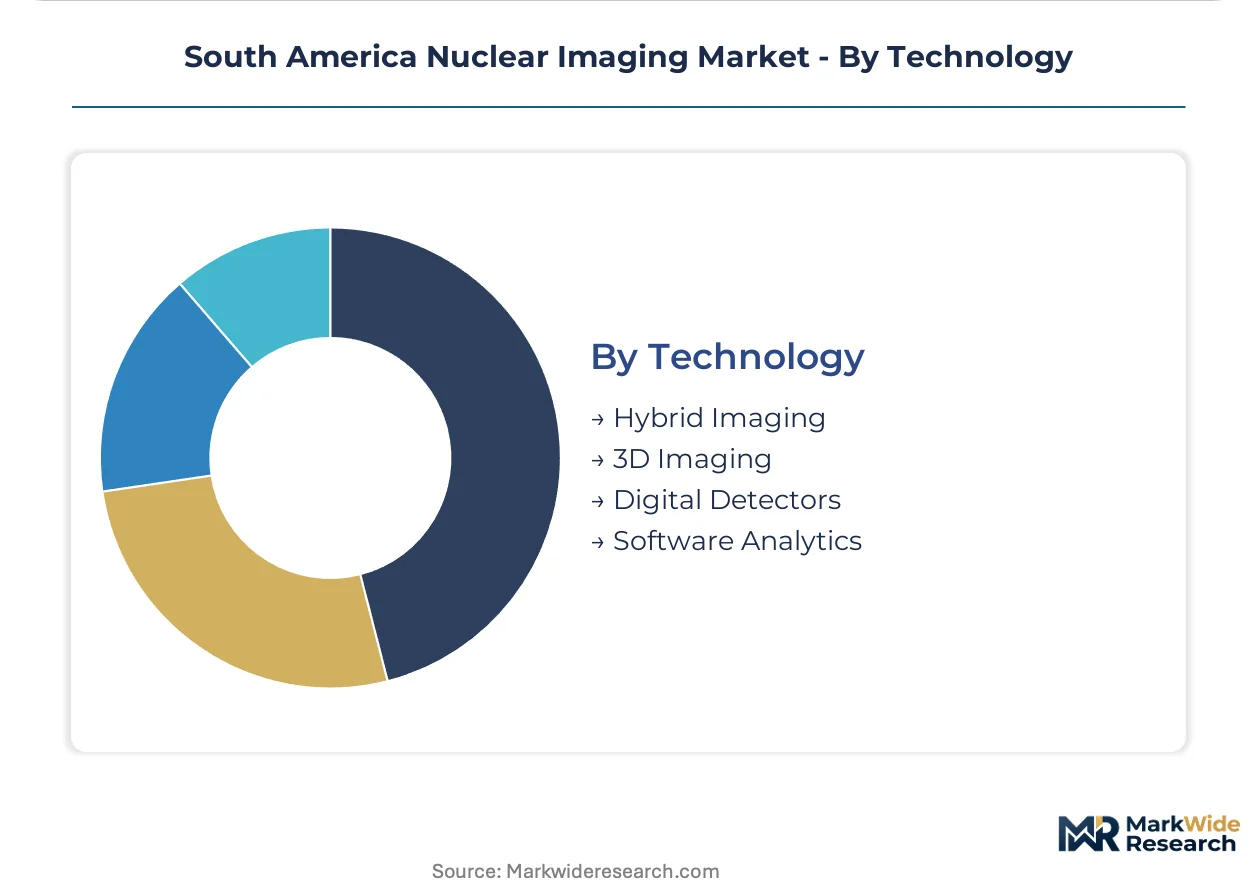
- Hybrid Imaging:PET-CT and SPECT-CT fusion systems deliver anatomical-functional correlation that standalone modalities cannot match. Brazil's tertiary care accreditation standards increasingly require hybrid capability.
- Software Analytics:Machine learning algorithms for automated lesion detection and standardized uptake value quantification are compressing reporting timelines. This segment shows the steepest expansion trajectory as diagnostic centers prioritize workflow efficiency.
- Digital Detectors:Silicon photomultiplier technology is replacing photomultiplier tubes in gamma camera and PET configurations. Southeast Brazil's mid-market hospital segments are adopting SiPM-equipped systems to reduce maintenance requirements.
- 3D Imaging:Iterative reconstruction algorithms enable reduced-dose protocols while maintaining diagnostic confidence. Regulatory acceptance of 3D SPECT quantification methods varies across ANVISA and Argentina's national pharmaceutical regulator jurisdictions.
Hybrid imaging holds installed capacity. Software analytics is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic centers in Paraguay and northern Brazil exhibit acute price sensitivity to radiopharmaceutical cold-chain costs, while São Paulo's tertiary hospitals absorb premium PET-CT procurement without volume constraints. This elasticity gradient shapes equipment financing structures and service contract terms across the continent.
Brazil
Southeast region hospital networks in São Paulo and Rio de Janeiro anchor molecular imaging program expansion for oncology staging protocols. ANVISA's streamlined radiopharmaceutical import guidelines compress product registration timelines from 18 months to under 12 months. São Paulo's diagnostic imaging infrastructure investment concentrates hybrid PET-CT deployment in tertiary care accreditation standards.
Argentina
Buenos Aires academic medical centers pursue clinical trial imaging protocols requiring specialized tracer synthesis capabilities. The national pharmaceutical regulator enforces import licensing for technetium generators and fluorodeoxyglucose kits with extended Good Manufacturing Practice inspection protocols. Cyclotron facility partnerships in Greater Buenos Aires support investigational radiopharmaceutical access for research institutions.
Chile
Santiago's private insurance networks drive amyloid-beta PET imaging adoption for Alzheimer's disease evaluation where reimbursement pathways mature faster than neighboring markets. The country's national pharmaceutical regulator maintains harmonized cold-chain logistics requirements with international standards. Diagnostic centers in the Santiago Metropolitan Region deploy solid-state detector retrofits to extend legacy gamma camera operational life.
Colombia
Bogotá-based hospital networks negotiate operational lease structures for mid-market nuclear imaging expansion as capital constraints restrict outright PET-CT purchase. Regional regulatory frameworks for radiopharmaceutical device approval remain pending Mercosur harmonization initiatives. The Andean region's interior diagnostic centers concentrate SPECT deployment where PET-CT infrastructure proves economically prohibitive.
Paraguay
Asunción's limited cyclotron facility access creates generator supply dependencies on Argentine and Brazilian tracer production networks. Temperature-controlled transport infrastructure underdevelopment imposes specialized logistics cost burdens on diagnostic center operations. The country's nuclear medicine physician scarcity concentrates available expertise in the capital while interior regions face diagnostic reporting delays.
South America Nuclear Imaging Market Competitive Landscape
Capability concentration sits with integrated hybrid imaging system manufacturers; scale advantage sits with radiopharmaceutical distribution networks spanning multiple national jurisdictions. The vendor structure organizes around three archetypes: full-stack equipment-service integrators, tracer supply specialists with cyclotron partnerships, and digital detector technology licensors. Competitive positioning hardens through multi-year uptime agreements bundling hardware, software, and maintenance into per-scan pricing, alongside operational lease structures displacing capital purchase in mid-sized diagnostic center expansion.
Among diversified health technology conglomerates, GE HealthCare, Siemens Healthineers, and Koninklijke Philips occupy positions exemplifying full-stack integration archetypes. GE HealthCare anchors its regional presence through radiopharmaceutical distribution partnerships with local cyclotron facilities. Siemens Healthineers leverages regional service hubs in São Paulo to sustain long-term equipment uptime agreements. Koninklijke Philips differentiates via digital detector upgrade pathways that extend legacy gamma camera operational life across Colombia and Chile.
| Leading Market Players |
|---|
| GE HealthCare |
| Siemens Healthineers |
| Koninklijke Philips |
| Canon Medical Systems |
| Mallinckrodt |
| Hitachi Medical |
| Lantheus Medical Imaging |
| Cardinal Health |
| Bayer |
| Others |
Value Network & Pricing Analysis
Single-source isotope dependency on Argentine and Brazilian cyclotron facilities compresses pricing power for technetium-99m generators while simultaneously dictating cold-chain logistics investment priorities across the continent's diagnostic networks. This structural concentration elevates service contract bundling as the primary margin defense mechanism for equipment vendors while forcing tracer suppliers to absorb temperature-controlled transport cost volatility.
Pricing Analysis
Aftermarket service revenue tiers now dominate lifetime value capture, with multi-year uptime agreements bundling hardware, software, and maintenance into per-scan pricing displacing transactional equipment sales across Brazil's Southeast region. Three-tier pricing structure across premium, standard, and economy levels separates São Paulo's tertiary hospitals from mid-market diagnostic centers and interior SPECT-only facilities. Cost compression in the economy tier is intensifying because Paraguayan and northern Brazilian operators face acute cold-chain cost absorption limits. Diagnostic centers in Asunción exhibit highest price sensitivity due to generator supply dependencies, while São Paulo's hospital networks absorb premium procurement without volume constraints.
Supply Chain Analysis
Upstream feedstock concentration in molybdenum-99 production centers on Argentina, Brazil, and limited North American reactor sources that feed regional technetium generator manufacturing. Radiopharmaceutical supply draws from cyclotron-produced fluorodeoxyglucose in Greater Buenos Aires and São Paulo, plus imported iodine-131 and gallium-68 precursor shipments. Single-source vulnerability concentrates in Argentina's national pharmaceutical regulator enforcement of extended Good Manufacturing Practice inspection protocols that delay facility commissioning. Distribution runs through temperature-controlled courier networks with specialized handling requirements for half-life-constrained tracers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America nuclear imaging market sits at a regulatory modernization inflection where ANVISA's streamlined import pathways are compressing product registration timelines and intensifying competitive entry velocity.
For Market Incumbents: Harden defensive positioning through captive cyclotron facility partnerships that secure isotope supply continuity against Argentine generator disruption risks. Expand São Paulo service hub capacity to capture independent diagnostic center maintenance contracts as bundled equipment-service packages unbundle. Prioritize silicon photomultiplier detector upgrade pathways for Colombia and Chile legacy gamma camera installed bases. For New Entrants and Emerging Players: Pursue digital detector retrofit opportunities in Chile and Colombia where solid-state replacements extend operational life without full system replacement capital requirements. Target Paraguay's interior regions through mobile gamma camera deployment with simplified SPECT protocols that bypass PET-CT infrastructure gaps. Lead with AI-assisted quantification software licensing to diagnostic centers seeking workflow efficiency without hardware procurement. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors radiopharmaceutical distribution specialists with multi-jurisdictional cyclotron partnerships. Long-term viability hinges on Mercosur harmonization completion that would reduce redundant registration costs for multi-country operators. Monitor ANVISA's pending Good Manufacturing Practice reciprocity agreements with international bodies as the signal to watch for supply chain restructuring inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Cyclotron Facility Partnership | Secures isotope supply continuity against Argentine production disruption risks. |
| AI Software Licensing | Captures diagnostic center workflow efficiency demand without hardware capital barriers. |
| Digital Detector Retrofit Program | Extends legacy gamma camera life across Colombia and Chile mid-market segments. |
| Per-Scan Pricing Contract | Aligns vendor revenue with patient volume predictability in oncology staging departments. |
| Mercosur Regulatory Harmonization | Reduces redundant registration costs for multi-country radiopharmaceutical operators. |
Research Methodology
Operator-level perspectives from nuclear medicine physicians, hospital procurement committees, cyclotron facility managers, ANVISA regulatory affairs specialists, and diagnostic center operations directors anchored the qualitative base. Primary interview findings triangulated against ANVISA registration databases, Argentina's national pharmaceutical regulator import licensing records, hospital procurement contract registries, and GPO equipment lease disclosures. Secondary validation incorporated customs radiopharmaceutical shipment data, tertiary hospital accreditation standards, and cyclotron facility certification timelines. Bottom-up procedure volume estimates across oncology, cardiology, neurology, and thyroid imaging applications combined with top-down capital expenditure flows from major hospital networks.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation modeling spanning product type, end user scale tier, clinical application, and technology maturity curve. CAGRs derived from equipment replacement cycle compression, radiopharmaceutical import registration acceleration, and software analytics procurement trajectory analysis. Forecast inputs incorporated ANVISA guideline revision implementation pace, Mercosur harmonization initiative progress, and silicon photomultiplier adoption migration from premium to mid-market hospital segments.
Sensitivities concentrate around Argentine cyclotron facility certification delays, northern Brazil cold-chain infrastructure development gaps, and nuclear medicine physician training program output shortfalls. Forecasts reflect documented assumptions regarding regulatory pathway simplification and hybrid imaging accreditation mandate expansion. Cross-checking against ANVISA's published radiopharmaceutical registration approval statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
China Mammography Market
Medical Imaging
Global MRI Scanner Market
Medical Imaging
South Africa Computed Tomography Market
Medical Imaging
South Korea Magnetic Resonance Imaging Market
Medical Imaging
Global Veterinary Radiography System Market
Medical Imaging
United Kingdom Magnetic Resonance Imaging Market
Medical Imaging
Dental X-Ray Market
Medical Imaging
South America Mammography Market
Medical Imaging
US Magnetic Resonance Imaging Coils Market
Medical Imaging
Japan Diagnostic Imaging Market
Medical Imaging
Spain Nuclear Imaging Market
Medical Imaging
Brazil Computed Tomography Market
Medical Imaging
Nuclear Medicine Software Market
Medical Imaging
Teleradiology Market
Medical Imaging
Global Mammography Systems Market
Medical Imaging
Germany Digital Radiology Market