
 South Africa Respiratory Devices Market | 2026-2036
South Africa Respiratory Devices Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Respiratory Devices Market Analytics
Market Context
SAHPRA's Medical Device Regulatory Unit is expanding registration compliance requirements for imported respiratory equipment, elevating the cost-of-entry calculus for foreign manufacturers seeking South African market access. Drägerwerk AG & Co. KGaA leverages its established Johannesburg service infrastructure to sustain technical support capabilities that satisfy local regulatory presence mandates. Koninklijke Philips NV anchors its competitive position through deep channel control across private hospital procurement networks in Gauteng and the Western Cape. ResMed specializes in sleep apnea therapy systems, occupying a differentiated niche within the homecare segment where patient self-management protocols are gaining traction.
Technical Definition and Segment Structure
South Africa respiratory devices encompass mechanically or pneumatically actuated apparatus engineered to deliver therapeutic gases, aerosolized pharmaceuticals, or positive airway pressure to patients with compromised pulmonary function, typically operating at flow rates between 2-60 liters per minute depending on clinical indication. These systems serve primarily to maintain adequate gas exchange, reduce work of breathing, and administer bronchodilator or corticosteroid therapy across acute hospital, sub-acute clinic, and domiciliary care environments. CPAP machines command substantial margin pools within the product type dimension due to recurring consumables revenue streams and private medical scheme reimbursement alignment. Homecare represents the fastest-expanding end user category as South African insurers extend coverage for nocturnal oxygen therapy and domiciliary ventilator weaning programs. Electronic technology variants are displacing manual alternatives in hospital settings where waveform monitoring and data connectivity integrate with electronic health record systems.
Regulatory Framework and Outlook
SAHPRA governs medical device registration and post-market surveillance, while the South African Bureau of Standards enforces electrical safety and electromagnetic compatibility specifications for powered respiratory equipment. The National Department of Health's Essential Medicines List Committee influences public sector procurement priorities, directly shaping demand volumes for nebulizers and oxygen concentrators distributed through provincial health departments. Stakeholders must monitor SAHPRA's progression toward harmonization with International Medical Device Regulators Forum guidelines, as this alignment will determine whether existing registrations require technical file resubmission or additional clinical evidence.
Market Dynamics
SAHPRA's technical support infrastructure mandates are compressing market access for foreign manufacturers while rewarding distributors with established Johannesburg service capabilities, fundamentally restructuring competitive positioning around regulatory compliance rather than price alone.
Growth Catalysts
- Chronic respiratory patient expansion:Public hospitals in Gauteng and KwaZulu-Natal are scaling ventilator and oxygen concentrator procurement for COPD and tuberculosis cohorts, creating sustained institutional demand.
- Private medical scheme reimbursement extension:South African insurers are expanding coverage for nocturnal oxygen therapy and domiciliary ventilator weaning, accelerating homecare segment penetration.
- Electronic health record integration:Waveform monitoring and data connectivity capabilities in electronic respiratory devices are displacing manual alternatives across hospital procurement networks.
Market Restraints
- Import dependency for critical components:Pneumatic valves and pressure sensors concentrate in German and Chinese supply bases, exposing South African assemblers to currency volatility and shipping delays.
- SAHPRA registration timeline friction:Technical file resubmission requirements under evolving IMDRF harmonization protocols extend product approval cycles beyond 18 months for novel device categories.
- Bi-level PAP substitution pressure:Adaptive servo-ventilation systems are capturing share from fixed-pressure CPAP in complex sleep-disordered breathing indications, compressing margins on legacy product lines.
Strategic Opportunities
- Eastern Cape and Limpopo provincial expansion:Underpenetrated public health infrastructure in these provinces offers first-mover positioning for oxygen concentrator distributors establishing rural service networks.
- Remote patient monitoring convergence:Integration of cellular connectivity with cloud-based adherence tracking creates subscription revenue models aligned with medical scheme preventive care incentives.
- Local technical support infrastructure mandates:SAHPRA's in-country service requirements create defensive moats for distributors investing in Johannesburg-based biomedical engineering capabilities.
Industry Challenges
- Biomedical engineering talent scarcity:Ventilator maintenance and calibration expertise concentrates in Gauteng and Western Cape urban centers, constraining service expansion into secondary cities.
- SAHPRA clinical evidence requirements:Novel positive airway pressure algorithms require local patient cohort data, extending time-to-market for next-generation flow generators.
- Legacy device integration complexity:Hospital information systems in provincial health departments operate on fragmented software architectures, complicating electronic respiratory device connectivity deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Respiratory Devices Market |
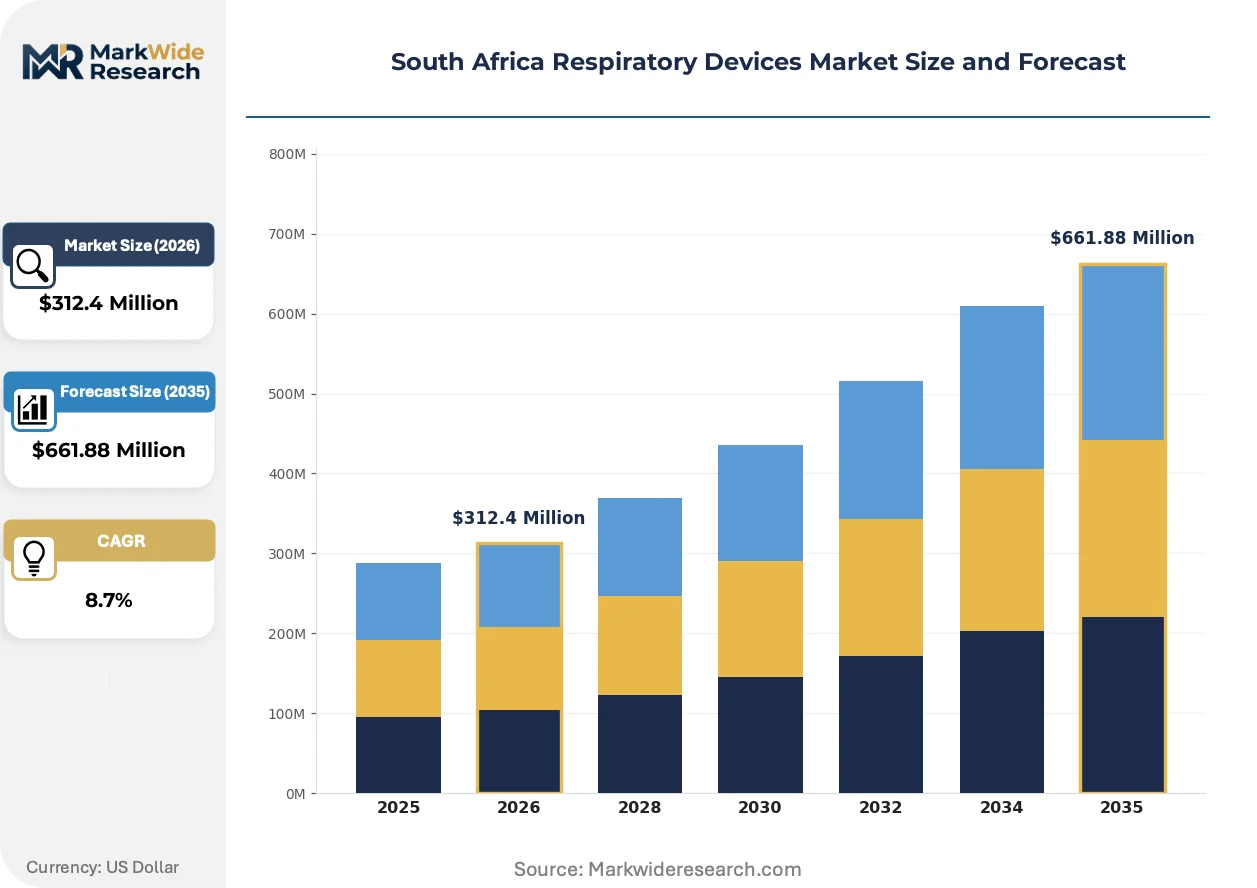
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inhalers, Nebulizers, Oxygen Concentrators, CPAP Machines End User: Hospitals, Homecare, Clinics, Rehabilitation Centers Technology: Electronic, Manual, Portable, Fixed Application: Asthma Management, COPD Treatment, Sleep Apnea Therapy, Acute Respiratory Distress |
| Companies Covered | Akacia Medical & Healthcare Group, Drägerwerk AG & Co. KGaA, Koninklijke Philips NV, Hamilton Bonaduz AG, Teleflex Incorporated, ResMed, GE Healthcare, Medtronic, Fisher & Paykel Healthcare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Respiratory Devices Market Evolving Landscape
Digital connectivity architectures and algorithm-driven pressure modulation are reshaping product development priorities, while procurement centralization among private hospital groups is compressing vendor margins and elevating service bundling requirements.
Cloud-connected CPAP platforms with integrated adherence monitoring are overtaking standalone devices in private medical scheme channels, with Discovery Health and Bonitas driving preferential reimbursement for cellular-enabled units that transmit compliance data to prescribing physicians, compressing reimbursement risk for insurers while locking patients into manufacturer ecosystems through proprietary data formats.
SAHPRA's progression toward International Medical Device Regulators Forum technical documentation standards is elevating clinical evidence requirements for imported positive airway pressure systems, compelling manufacturers to submit South African patient cohort data or accept extended review timelines, with homecare segment entrants most exposed to registration delays.
Private hospital groups including Netcare and Life Healthcare are consolidating respiratory device procurement through centralized tender processes, displacing fragmented purchasing across individual facilities and elevating technical service response time guarantees as competitive differentiators over unit pricing alone, with metropolitan Johannesburg corridors exhibiting the most concentrated buyer power.
South Africa Respiratory Devices Market Segmentation
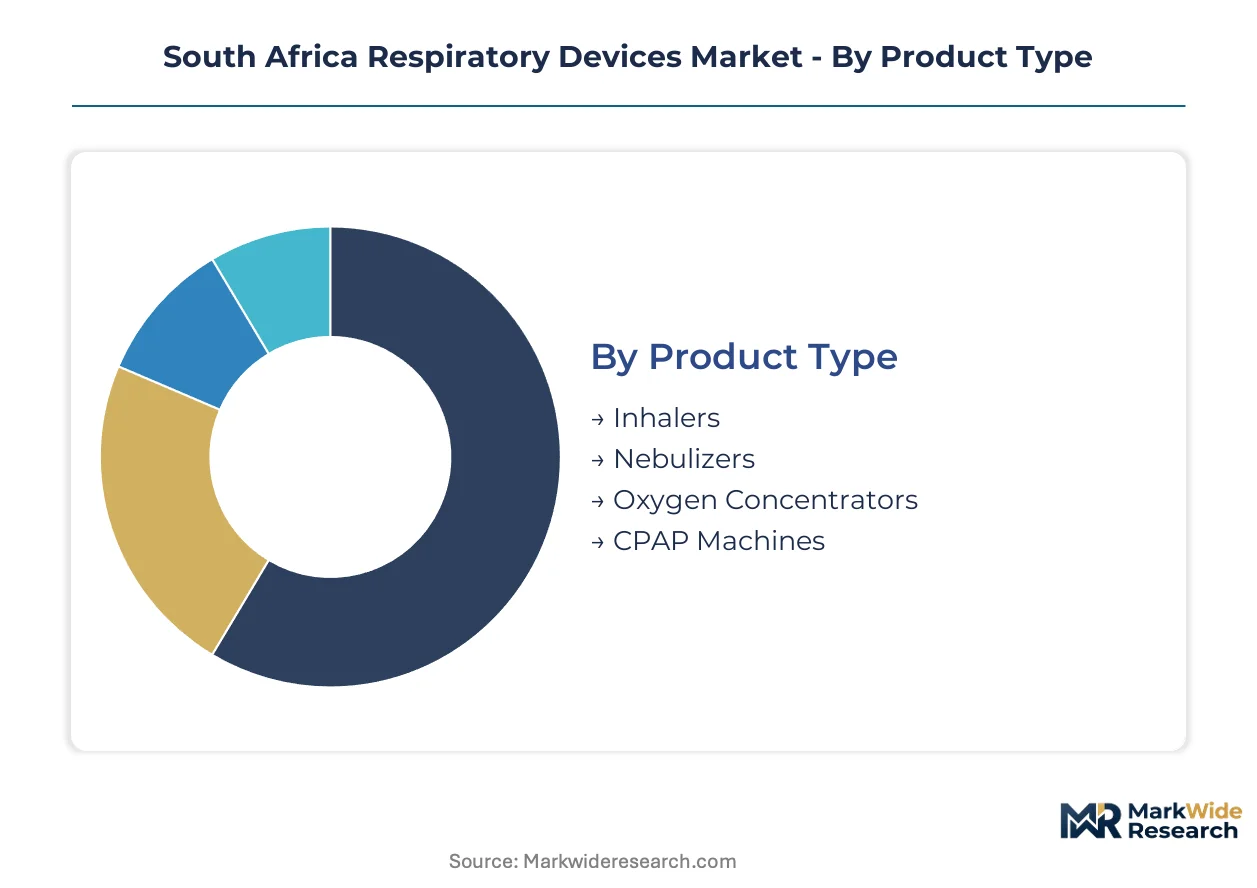
Respiratory device procurement in South Africa fragments across clinical settings, reimbursement pathways, and technology tiers. Understanding these divides reveals where margin pools concentrate and which specifications determine competitive viability.
Product Type:
Flow generation mechanisms and drug delivery modalities define performance benchmarks and service revenue potential.
- CPAP Machines:Positive airway pressure systems with heated humidification and expiratory pressure relief dominate private medical scheme channels. Discovery Health and Bonitas drive preferential reimbursement for cellular-enabled units that transmit compliance data, locking patients into manufacturer ecosystems through proprietary data formats.
- Oxygen Concentrators:Pressure swing adsorption systems producing medical-grade oxygen at 2-10 liters per minute anchor public hospital procurement in Gauteng and KwaZulu-Natal. Provincial health departments prioritize units with molecular sieve durability exceeding 20,000 hours to minimize replacement cycles.
- Inhalers:Pressurized metered-dose and dry powder devices for bronchodilator delivery.
- Nebulizers:Jet and ultrasonic aerosol generators for corticosteroid administration in acute settings.
CPAP machines lead on scale through recurring consumables revenue; oxygen concentrators lead on momentum through public sector expansion.
End User:
Reimbursement architecture and patient acuity determine device specifications and service intensity.
- Homecare:Domiciliary oxygen therapy and nocturnal ventilation programs expand fastest as insurers extend coverage for remote patient monitoring. Cellular-connected adherence tracking creates subscription revenue models aligned with preventive care incentives.
- Hospitals:Acute care facilities in Johannesburg, Cape Town, and Durban corridors demand electronic respiratory devices with waveform monitoring and electronic health record integration. Netcare and Life Healthcare consolidate procurement through centralized tender processes.
- Clinics:Sub-acute facilities managing stable COPD and asthma patients.
- Rehabilitation Centers:Post-acute weaning facilities for ventilator-dependent patients.
Hospitals lead on scale through concentrated procurement volumes; homecare leads on momentum through reimbursement extension.
Technology:
Power source and mobility specifications determine regulatory classification and distribution channel access.
- Electronic:Microprocessor-controlled flow modulation with data connectivity displaces manual alternatives in hospital settings. SAHPRA mandates electromagnetic compatibility certification to South African Bureau of Standards specifications.
- Portable:Battery-powered oxygen concentrators and travel CPAP units serve mobile patient populations. Lightweight designs under 2.5 kilograms penetrate private medical scheme channels where patient lifestyle flexibility drives selection.
- Manual:Hand-operated resuscitation bags and mechanical spirometers for resource-constrained settings.
- Fixed:Stationary installations for continuous domiciliary oxygen delivery.
Electronic systems lead on scale through hospital procurement; portable configurations lead on momentum through patient mobility demands.
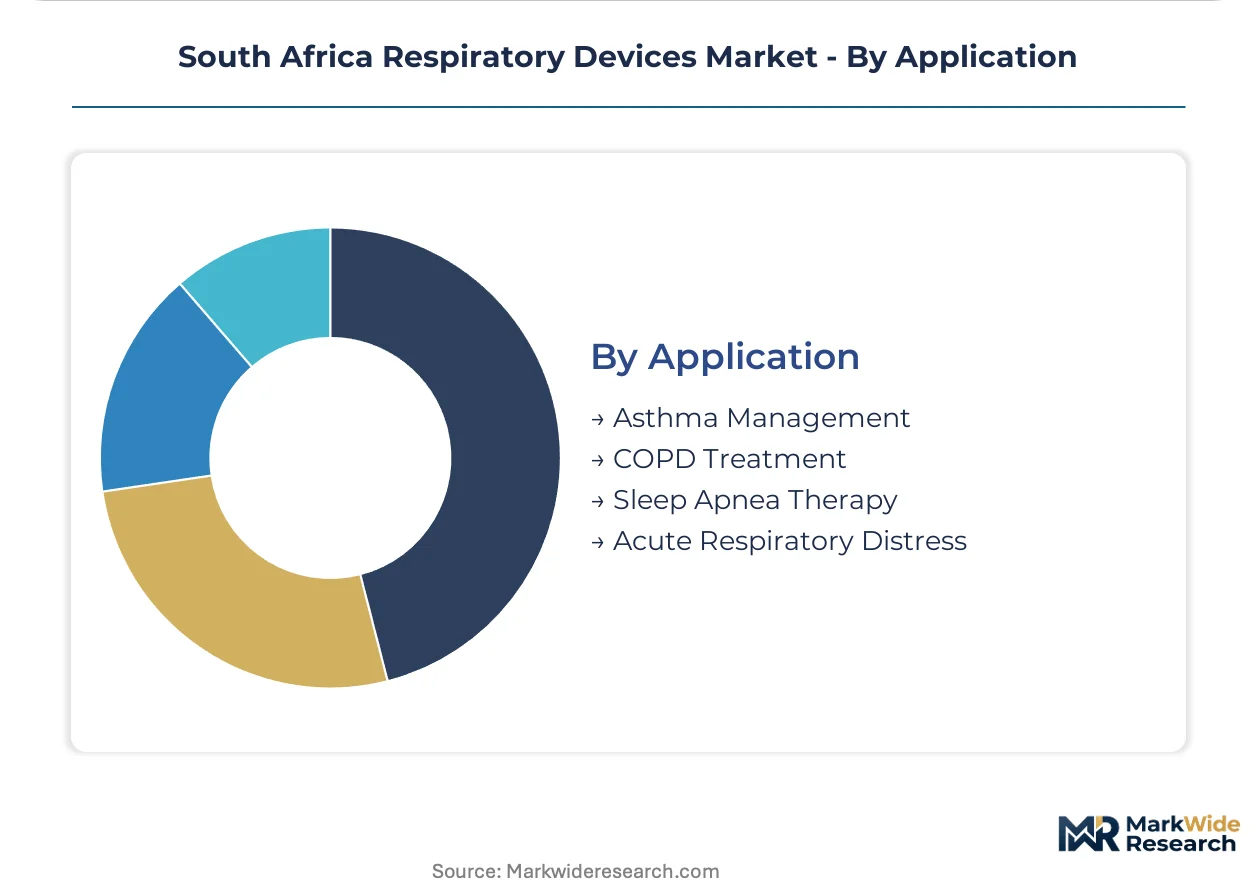
Application:
Clinical indication determines pressure profiles, flow rates, and monitoring requirements.
- Sleep Apnea Therapy:Auto-titrating positive airway pressure with algorithmic event detection dominates private sector volume. Adaptive servo-ventilation systems capture share from fixed-pressure CPAP in complex sleep-disordered breathing indications.
- COPD Treatment:Long-term oxygen therapy and non-invasive ventilation for chronic hypercapnic respiratory failure. Public hospitals in Gauteng scale ventilator procurement for weaning programs.
- Asthma Management:Bronchodilator delivery and peak flow monitoring for reversible airway obstruction.
- Acute Respiratory Distress:High-flow nasal cannula and invasive mechanical ventilation for critical care.
COPD treatment leads on scale through institutional procurement; sleep apnea therapy leads on momentum through homecare penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biomedical engineering talent clusters in Gauteng and the Western Cape anchor South Africa's respiratory device service infrastructure, with provincial health departments driving procurement volumes through centralized tender processes.
Gauteng
Public hospitals in Johannesburg and Pretoria corridors scale ventilator procurement for COPD and tuberculosis weaning programs, creating sustained institutional demand for oxygen concentrators and non-invasive ventilation systems. SAHPRA's technical support infrastructure mandates compel distributors to maintain Johannesburg-based biomedical engineering capabilities. The metropolitan corridor concentrates private hospital procurement through Netcare and Life Healthcare centralized tenders.
Western Cape
Discovery Health and Bonitas medical schemes drive preferential reimbursement for cellular-enabled CPAP units with adherence monitoring, accelerating homecare segment penetration in Cape Town metropolitan areas. The South African Bureau of Standards enforces electromagnetic compatibility certification for powered respiratory equipment entering this market. Private hospital procurement concentrates in Cape Town's medical corridor with technical service response guarantees as competitive differentiators.
KwaZulu-Natal
Provincial health departments in Durban and Pietermaritzburg expand oxygen concentrator procurement for chronic respiratory patient cohorts, prioritizing molecular sieve durability exceeding 20,000 hours. The National Department of Health's Essential Medicines List Committee influences public sector procurement priorities for nebulizers distributed through provincial channels. Durban's private hospital networks demand electronic respiratory devices with electronic health record integration capabilities.
Eastern Cape
Underpenetrated public health infrastructure creates first-mover positioning opportunities for oxygen concentrator distributors establishing rural service networks beyond Port Elizabeth and East London. SAHPRA registration timeline friction extends product approval cycles for novel device categories entering this province. Biomedical engineering talent scarcity constrains service expansion into secondary cities and district hospitals.
Limpopo
Rural health districts drive demand for portable oxygen concentrators serving mobile patient populations in areas lacking continuous power infrastructure. Provincial procurement prioritizes lightweight designs under 2.5 kilograms for patient lifestyle flexibility in remote settings. Polokwane and Tzaneen medical hubs concentrate limited technical support capabilities for device maintenance and calibration.
South Africa Respiratory Devices Market Competitive Landscape
The competitive structure tilts toward multinational medical technology conglomerates with established service infrastructure. Three to five foreign manufacturers control premium-tier hospital procurement through Johannesburg-based technical support capabilities that satisfy SAHPRA regulatory presence mandates. Two strategic archetypes dominate: diversified medical technology conglomerates leveraging global R&D scale, and respiratory-focused specialists occupying differentiated niches in sleep therapy and homecare segments. Competitive moves concentrate on regulatory compliance infrastructure investments and private medical scheme reimbursement alignment rather than price competition alone.
Among Germany-based conglomerates, Drägerwerk AG & Co. KGaA exemplifies the diversified medical technology archetype with established Johannesburg service infrastructure. Koninklijke Philips NV and ResMed occupy positions within the respiratory-focused specialist tier, with the former anchoring channel control across private hospital procurement networks and the latter representing the sleep apnea therapy specialization. These three companies illustrate how regulatory compliance capabilities and reimbursement alignment determine competitive viability more than manufacturing scale alone.
| Leading Market Players |
|---|
| Akacia Medical & Healthcare Group |
| Drägerwerk AG & Co. KGaA |
| Koninklijke Philips NV |
| Hamilton Bonaduz AG |
| Teleflex Incorporated |
| ResMed |
| GE Healthcare |
| Medtronic |
| Fisher & Paykel Healthcare |
| Others |
Value Network & Pricing Analysis
Netcare and Life Healthcare's centralized procurement consolidation across Johannesburg metropolitan corridors is forcing distributors to unbundle equipment pricing from technical service contracts, compressing upfront margins while elevating recurring revenue attachment rates for biomedical engineering support.
Pricing Analysis
Service bundling versus unbunded equipment sales defines competitive positioning across private hospital and homecare channels. Three-tier pricing structure across premium, standard, and economy levels separates SAHPRA-registered units with Johannesburg-based technical support from gray-market imports and refurbished alternatives. Cost compression in the economy tier is intensifying because provincial health departments prioritize molecular sieve durability specifications over brand premium. Public sector procurement committees exhibit highest price sensitivity, while Discovery Health-aligned private medical scheme channels accept premium positioning for cellular-enabled adherence monitoring capabilities.
Supply Chain Analysis
Regional distribution centers in Johannesburg anchor hub-and-spoke patterns radiating to Durban, Cape Town, and secondary cities. Pneumatic valve manufacturing concentrates in Germany, pressure sensor production centers on China, and molecular sieve materials draw from Japan and the United States. Single-source vulnerability in German precision valve supply exposes South African assemblers to extended lead times. Distribution runs through authorized distributor networks with SAHPRA-mandated technical service capabilities rather than direct manufacturer-to-hospital relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's respiratory device market represents a late-cycle quality story where SAHPRA's tightening technical support infrastructure mandates are filtering out price-only competitors and rewarding distributors with certified biomedical engineering capabilities.
For Market Incumbents: To counter adaptive servo-ventilation systems capturing share from fixed-pressure CPAP in complex sleep-disordered breathing indications, incumbents must deepen backward integration into cloud-based adherence tracking software and lock in exclusive procurement contracts with Netcare and Life Healthcare through guaranteed four-hour technical response time commitments in Gauteng and Western Cape corridors. For New Entrants and Emerging Players: SAHPRA's progression toward International Medical Device Regulators Forum technical documentation standards opens a window for respiratory-focused specialists to establish first-mover positioning in Eastern Cape and Limpopo rural districts where biomedical engineering talent scarcity has constrained incumbent service expansion, leveraging lightweight portable oxygen concentrator designs under 2.5 kilograms and partnerships with provincial procurement offices for district hospital tenders. For Investors and Strategic Acquirers: Asymmetric upside sits with distributors possessing established Johannesburg technical service infrastructure that satisfies SAHPRA regulatory presence mandates without requiring manufacturer direct investment. Over the medium-term horizon, acquisition targets should demonstrate exclusive relationships with at least two of the three major private hospital groups and cellular-enabled product portfolios aligned with Discovery Health reimbursement criteria. The signal to watch is SAHPRA publication of final IMDRF harmonization implementation dates, which will trigger registration resubmission costs and consolidation pressure on undercapitalized distributors.| Strategic Initiative | Industry Significance |
|---|---|
| SAHPRA Registration Pathway Investment | Accelerates market access for novel positive airway pressure algorithms requiring local clinical evidence. |
| Hospital System Partnership | Locks in procurement volume through Netcare and Life Healthcare centralized tender participation. |
| Software Companion Development | Enables cellular-connected adherence tracking aligned with Discovery Health preventive care incentives. |
| Biomedical Engineering Capability Buildout | Satisfies SAHPRA technical support infrastructure mandates for in-country service presence. |
| Reimbursement Strategy Alignment | Positions cellular-enabled CPAP units for preferential coverage under Bonitas and Discovery Health schemes. |
Research Methodology
Coverage spans Gauteng, Western Cape, KwaZulu-Natal, Eastern Cape, and Limpopo provinces, with primary inputs from each region combined with secondary validation. Interviews with hospital purchasing committee members, biomedical engineering directors at private hospital groups, provincial health department procurement officers, and SAHPRA regulatory affairs specialists informed demand-side dynamics. Secondary sources included SAHPRA medical device registration databases, National Department of Health Essential Medicines List Committee procurement guidelines, South African Bureau of Standards electromagnetic compatibility certification records, and private medical scheme formulary documentation. Bottom-up provincial procurement volume estimates triangulated against top-down manufacturer shipment data.
Product type, end user, technology tier, and clinical application dimensions were modeled at the provincial level across the analysis window. CAGRs derived from logistic curve fitting to historical procurement trajectories adjusted for SAHPRA regulatory timeline assumptions and medical scheme reimbursement expansion schedules. Forecast inputs incorporated COPD and tuberculosis prevalence projections from the National Department of Health, private hospital bed expansion plans from listed healthcare groups, and molecular sieve replacement cycle assumptions for oxygen concentrator installed base.
Revisions become necessary when SAHPRA accelerates IMDRF harmonization timelines, when provincial health departments shift procurement authority to national tender structures, or when private medical schemes alter reimbursement criteria for homecare respiratory therapy. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
APAC AMH Market
Medical Devices
United States Small Bone and Joint Devices Market
Medical Devices
Global Breast Implants Market
Medical Devices
Large Volume Nebulizers Market
Medical Devices
Contact and Intraocular Lenses Market
Medical Devices
Europe Cardiac Rhythm Management Devices Market
Medical Devices
Intravenous Access Devices Market
Medical Devices
Female Pelvic Implants Market
Medical Devices
Global Canes and Crutches Market
Medical Devices
Europe Organ-On-Chip Market
Medical Devices
Self-Sampling Blood Collection and Storage Devices Market
Medical Devices
Feeding Tubes Market
Medical Devices
Steam Inhaler Devices Market
Medical Devices
Supraglottic Airway Devices Market
Medical Devices
Medical Pendant Market
Medical Devices
Global Scleral Lens Market