
 Middle East and Africa Clinical Trial Imaging Market | 2026-2036
Middle East and Africa Clinical Trial Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Clinical Trial Imaging Market Foresight
Modular service bundling is expanding across the Middle East and Africa Clinical Trial Imaging Market, allowing sponsors to purchase imaging core lab services, radiologist adjudication, and regulatory submission support as integrated packages rather than discrete contracts. IQVIA leverages its established CRO footprint across the Gulf states to anchor large-scale oncology trials requiring centralized image analysis. Clario competes through specialized endpoint adjudication platforms that sustain repeat engagements from multinational sponsors. Resonance Health Analytical Services dominates niche iron overload quantification in liver imaging, a capability that differentiates its offering in hematology trials across the region.
Clinical trial imaging encompasses the acquisition, quality control, analysis, and regulatory submission of medical images used as endpoints or safety assessments in drug and device development, requiring DICOM-compliant formats, standardized acquisition protocols, and blinded independent central review to ensure data integrity. The primary purpose is to generate objective, reproducible biomarker evidence that regulators accept for efficacy and safety determinations. CT Scan and MRI modalities lead current revenue contribution across the region, reflecting their entrenched role in solid tumor and neurological trial designs. 3D Imaging technology captures the fastest expansion trajectory, driven by its capacity to reduce reader variability and enable volumetric tumor assessment that 2D methods cannot replicate. Contract Research Organizations represent a concentrated demand channel, as these intermediaries consolidate imaging procurement across sponsor portfolios and negotiate preferred provider arrangements.
South Africa's Health Products Regulatory Authority, Saudi Arabia's SFDA, and Egypt's national pharmaceutical regulator enforce varying imaging protocol standards that shape trial design complexity and vendor qualification requirements across jurisdictions. The EU AI Act's extraterritorial influence on multinational sponsors operating in the region is accelerating algorithm validation requirements for AI-assisted image analysis tools deployed in trials. Stakeholders must monitor regulatory divergence between Gulf harmonization initiatives and sub-Saharan national frameworks when selecting imaging partners and technology platforms.
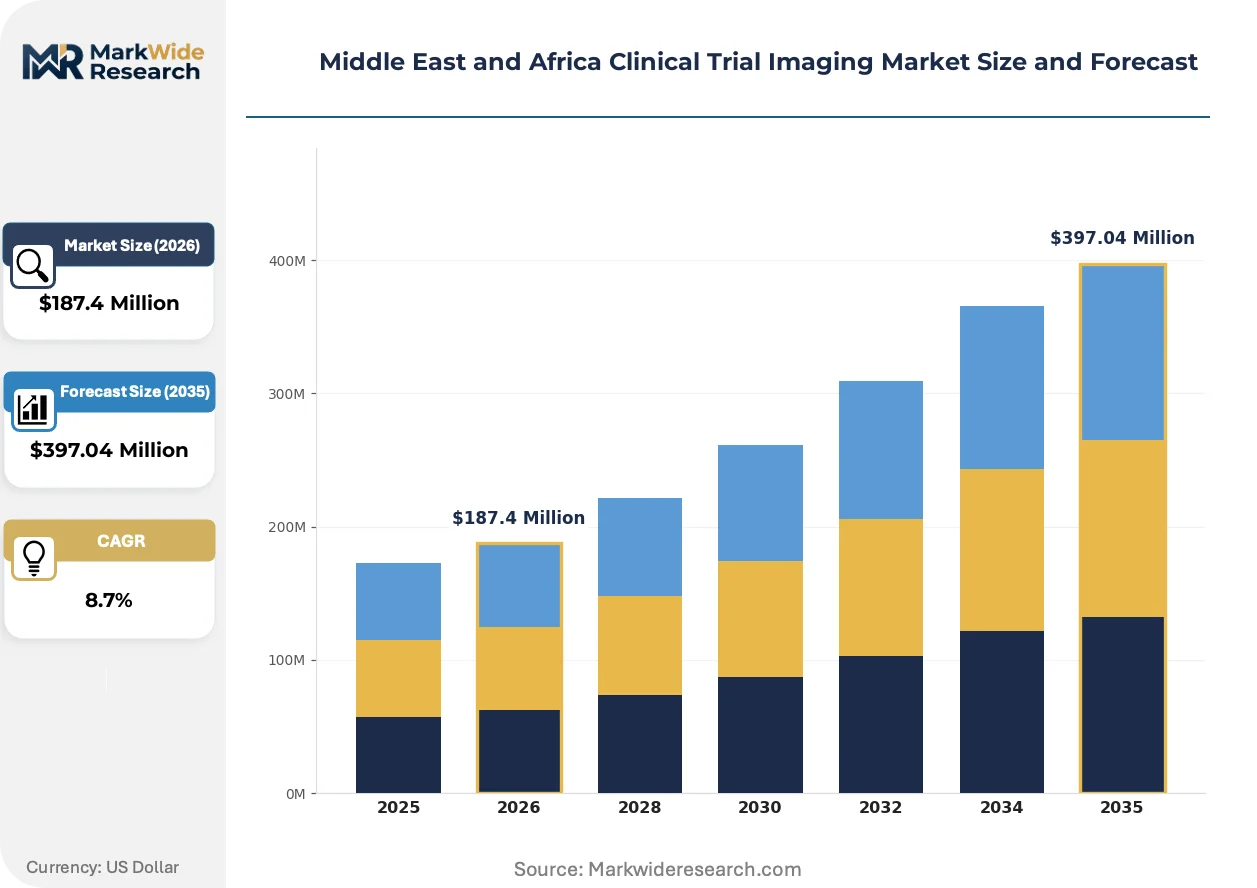
Market Dynamics
Centralized image review infrastructure is consolidating trial execution across the Middle East and Africa, compressing site-to-site variability and forcing sponsors to qualify vendors against divergent national regulatory frameworks rather than unified standards.
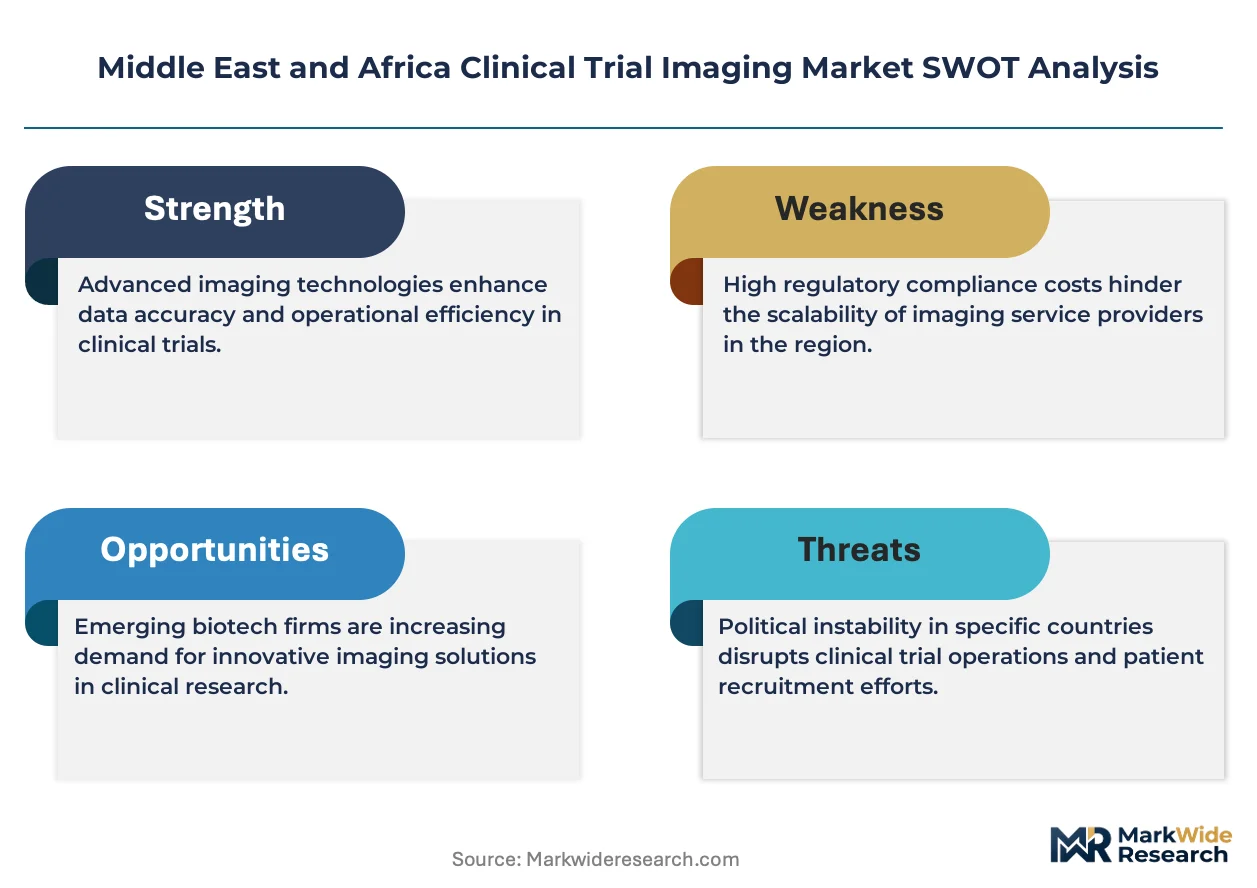
Growth Catalysts
- SFDA Protocol Harmonization:Saudi Arabia's sovereign health funds are building dedicated clinical imaging infrastructure that standardizes acquisition parameters across multi-site oncology trials.
- Oncology Trial Volume:Pharmaceutical sponsors across Gulf Cooperation Council states are expanding adoption of blinded independent central review for solid tumor studies.
- 3D Volumetric Assessment:Volumetric tumor measurement protocols are displacing 2D RECIST methods, reducing reader variability and accelerating endpoint adjudication timelines.
Market Restraints
- Qualified Radiologist Supply:Sub-Saharan Africa faces acute scarcity of DICOM-certified imaging specialists capable of executing blinded reads for regulatory submission.
- Equipment Import Duties:MRI and CT scanner procurement costs in Egypt and Nigeria inflate trial startup capital requirements beyond sponsor risk thresholds.
- Protocol Divergence:South Africa's Health Products Regulatory Authority maintains imaging standards that conflict with Gulf harmonization initiatives, forcing duplicate validation studies.
Strategic Opportunities
- AI-Assisted Adjudication:Algorithm validation frameworks under the EU AI Act's extraterritorial reach are creating first-mover advantages for vendors deploying machine learning readers in Saudi trials.
- Iron Overload Quantification:Specialized liver imaging biomarkers remain underpenetrated across hematology trials in North Africa, offering niche service differentiation.
- Modular Service Bundling:Sponsors are consolidating imaging core lab services, radiologist adjudication, and regulatory submission support into single-contract arrangements that reduce procurement friction.
Industry Challenges
- Blinded Reader Training:Maintaining reader independence across centralized review platforms requires continuous certification cycles that strain operational bandwidth.
- Legacy PACS Integration:Site-level picture archiving systems in older Egyptian and South African hospitals resist seamless data transmission to centralized core labs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Clinical Trial Imaging Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CT Scan, MRI, PET Scan, Ultrasound Technology: 2D Imaging, 3D Imaging, Digital Radiography, Fusion Imaging End User: Pharmaceutical Companies, Research Institutions, Contract Research Organizations, Hospitals Application: Oncology, Neurology, Cardiovascular, Infectious Diseases |
| Companies Covered | Resonance Health Analytical Services, IXICO plc, IQVIA, WIRB-Copernicus Group, Clario, Paraxel International Corporation, BioTelemetry (Philips Company), Invicro LLC, ICON plc, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Clinical Trial Imaging Market Shifts & Advancements
Digital pathology convergence with radiology workflows is dissolving traditional modality silos, creating unified diagnostic platforms that sponsors must navigate when designing composite endpoints.
Cloud-native image management platforms are unifying acquisition, quality control, and regulatory submission workflows into single-architecture systems. Contract research organizations across the Gulf states are adopting these platforms at accelerating pace to compress trial timelines. This unification is collapsing the vendor landscape by eliminating point-solution providers that cannot deliver end-to-end DICOM compliance.
The EU AI Act's algorithmic transparency requirements are reshaping validation protocols for AI-assisted image analysis tools deployed in multinational trials. Industrial consequence includes mandatory documentation of training data provenance and performance benchmarking against human readers. Oncology segmentation algorithms face the steepest compliance burden, with sponsors accelerating vendor qualification timelines to secure regulatory acceptance.
Site-level procurement of imaging services is fragmenting as hospital networks in Saudi Arabia and South Africa establish preferred provider arrangements directly with core labs. Traditional contract research organization intermediation is thinning in these concentrated demand pockets, with sponsors accepting unbundled service contracts to secure site access. This channel compression is most visible in Riyadh and Johannesburg, where sovereign health system consolidation has created single-buyer leverage.
Middle East and Africa Clinical Trial Imaging Market Segmentation
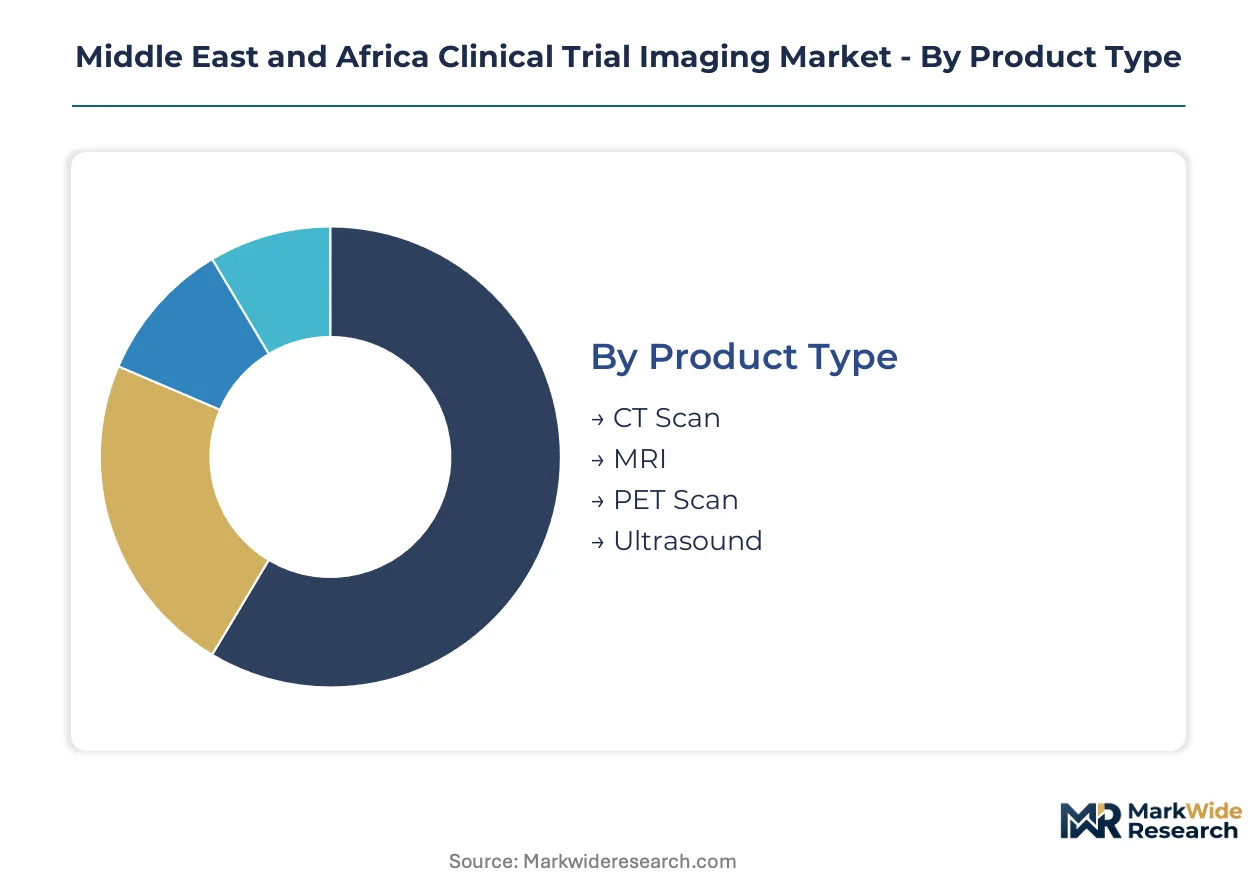
Imaging modality selection in Middle East and Africa clinical trials hinges on regulatory acceptance thresholds, with each product type carrying distinct validation burdens across Saudi SFDA, South African Health Products Regulatory Authority, and Egyptian national frameworks. Sponsors must map segment-specific certification requirements to trial design complexity when qualifying vendors.
Product Type:
CT Scan and MRI modalities require SFDA pre-qualification for oncology endpoints, while PET Scan and Ultrasound face variable acceptance across Gulf harmonization initiatives versus sub-Saharan national protocols.
- CT Scan:Computed tomography delivers cross-sectional anatomical resolution essential for RECIST-based tumor assessment. Demand concentrates in Saudi Arabia's sovereign-funded oncology infrastructure, where standardized acquisition parameters compress site-to-site variability. Regulatory submission requires DICOM-compliant formats validated against SFDA imaging protocol standards.
- MRI:Magnetic resonance imaging provides soft-tissue contrast without ionizing radiation, enabling neurological and hepatic iron overload quantification. South African Health Products Regulatory Authority maintains distinct MRI protocol standards that conflict with Gulf harmonization, forcing duplicate validation studies for multi-regional trials.
- PET Scan:Positron emission tomography enables metabolic activity assessment through radiotracer uptake measurement.
- Ultrasound:Sonographic imaging supports cardiac function and abdominal assessment with lower capital requirements.
Leading the category by volume: CT Scan. Growing fastest: MRI.
Technology:
Technology tier selection determines reader variability exposure and endpoint adjudication speed, with 3D volumetric methods commanding premium positioning over legacy 2D approaches.
- 3D Imaging:Volumetric reconstruction algorithms enable precise tumor boundary delineation and longitudinal volume tracking. Saudi Arabia's centralized imaging infrastructure accelerates 3D protocol adoption, displacing 2D RECIST methods in solid tumor trials. Cloud-native platforms unify acquisition and quality control workflows.
- 2D Imaging:Planar radiographic methods remain entrenched in infectious disease and cardiovascular trial designs with lower biomarker complexity. Egyptian and Nigerian sites favor 2D protocols to avoid MRI and CT scanner import duty inflation.
- Digital Radiography:DR systems replace film-based capture with immediate electronic image distribution.
- Fusion Imaging:Hybrid modality registration combines anatomical and functional data streams.
Expanding most quickly: 3D Imaging. Dominating current revenue: 2D Imaging.
End User:
Customer type shapes procurement channel structure, with Contract Research Organizations consolidating demand and hospital networks establishing direct core lab relationships.
- Contract Research Organizations:CRO intermediaries aggregate imaging procurement across sponsor portfolios and negotiate preferred provider arrangements. IQVIA leverages Gulf state footprints to anchor large-scale oncology trials requiring centralized analysis.
- Pharmaceutical Companies:Sponsor direct engagement concentrates in Saudi Arabia and South Africa where sovereign health system consolidation creates single-buyer leverage.
- Research Institutions:Academic medical centers execute investigator-initiated studies with limited commercial imaging budgets.
- Hospitals:Site-level procurement fragments as Riyadh and Johannesburg hospital networks establish preferred provider arrangements directly with core labs.
Highest volume concentration: Contract Research Organizations. Fastest channel shift: Hospitals.
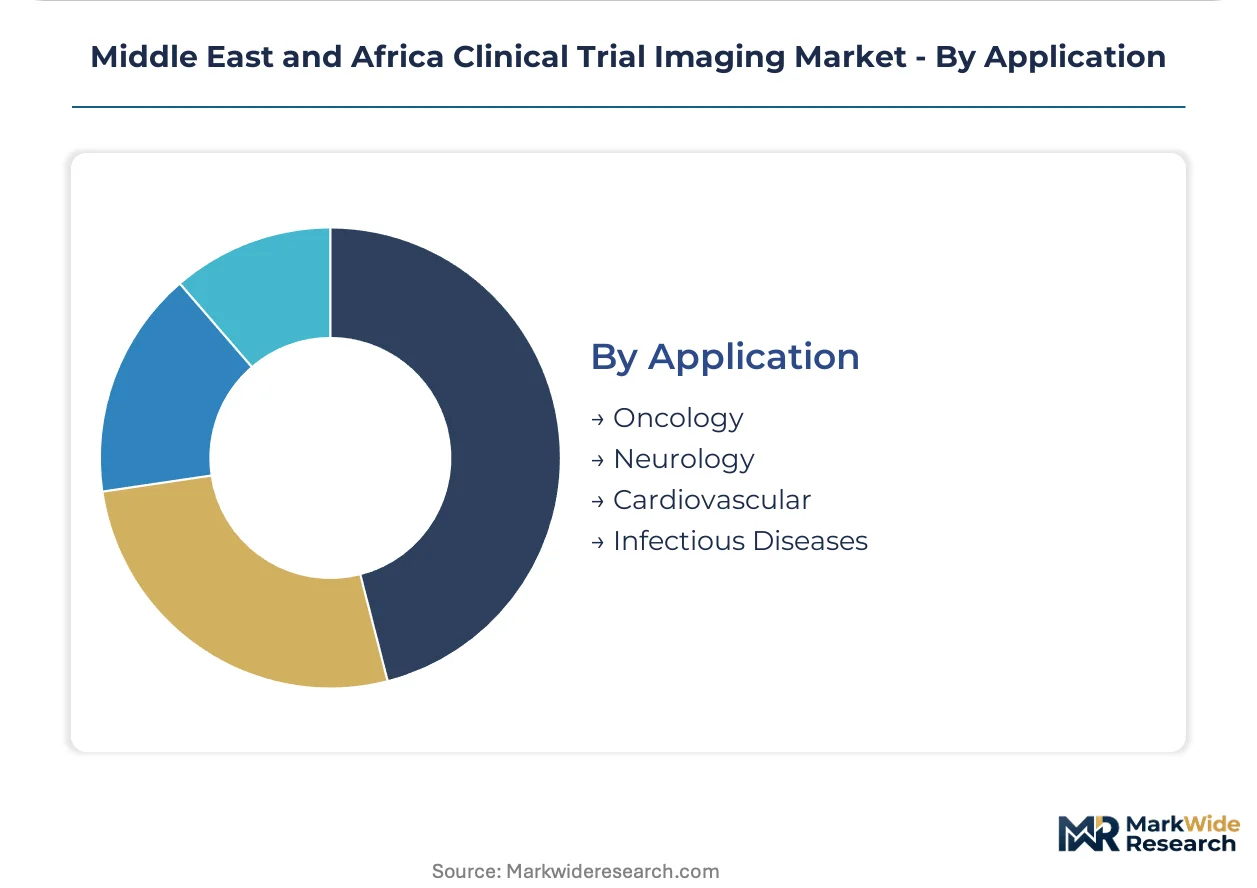
Application:
Therapeutic area drives modality mix and regulatory scrutiny intensity, with oncology commanding the most rigorous blinded independent central review requirements.
- Oncology:Solid tumor trials mandate DICOM-compliant imaging with blinded independent central review for regulatory submission. SFDA protocol harmonization standardizes acquisition parameters across multi-site studies. AI-assisted segmentation algorithms face steep EU AI Act compliance burdens.
- Neurology:Central nervous system studies rely on MRI for lesion detection and progression monitoring. South African Health Products Regulatory Authority tightened imaging protocol standards specifically for neurodegenerative drug trials.
- Cardiovascular:Cardiac imaging endpoints span CT angiography, MRI ventricular function, and ultrasound ejection fraction assessment.
- Infectious Diseases:Tuberculosis and tropical disease trials employ chest radiography and abdominal ultrasound with lighter regulatory validation requirements.
Leading therapeutic segment: Oncology. Gaining share fastest: Neurology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
King Abdullah Economic City anchors imaging infrastructure concentration through sovereign-backed healthcare zones that compress site qualification timelines for multinational sponsors. Special economic privileges within these zones exempt MRI and CT equipment from standard import duties, lowering trial startup capital thresholds.
Saudi Arabia
Sovereign health funds are building dedicated clinical imaging infrastructure across Riyadh and the Eastern Province. SFDA protocol harmonization standardizes acquisition parameters for multi-site oncology trials, reducing site-to-site variability. King Faisal Specialist Hospital anchors centralized image review capacity for solid tumor studies.
South Africa
Johannesburg hospital networks establish preferred provider arrangements directly with core labs, fragmenting traditional CRO intermediation. The Health Products Regulatory Authority tightened imaging protocol standards specifically for neurodegenerative drug trials. Cape Town academic medical centers concentrate neurological imaging expertise for multi-regional studies.
Egypt
National pharmaceutical regulators enforce imaging standards that diverge from Gulf harmonization initiatives, forcing duplicate validation studies. Cairo-based hospital networks favor 2D protocols to avoid MRI and CT scanner import duty inflation. Legacy PACS systems in older institutions resist seamless data transmission to centralized core labs.
United Arab Emirates
Dubai Healthcare City free zone attracts imaging core labs through regulatory fast-track mechanisms for trial approval. MOHAP maintains distinct imaging certification requirements that sponsors must map against Saudi SFDA standards for multi-jurisdictional studies. Abu Dhabi sovereign wealth vehicles fund dedicated oncology imaging infrastructure.
Middle East and Africa Clinical Trial Imaging Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across service bundling and endpoint adjudication capabilities. Contract research organizations consolidate imaging procurement across sponsor portfolios, while specialized core labs defend position through proprietary algorithm platforms. Three archetypes dominate: full-service CROs with embedded imaging divisions, independent imaging core labs with regulatory submission expertise, and technology vendors supplying AI-assisted segmentation tools. Geographic expansion and modular service packaging represent the dominant competitive vectors.
Within the specialized core lab tier, Resonance Health Analytical Services exemplifies niche differentiation through liver iron quantification capabilities. IQVIA and Clario occupy positions at opposite ends of the service integration spectrum: the former anchors large-scale oncology trials through established Gulf state footprints, while the latter competes through endpoint adjudication platforms that sustain repeat sponsor engagements. These three entities collectively represent the competitive tension between geographic scale and technical specialization.
| Leading Market Players |
|---|
| Resonance Health Analytical Services |
| IXICO plc |
| IQVIA |
| WIRB-Copernicus Group |
| Clario |
| Paraxel International Corporation |
| BioTelemetry (Philips Company) |
| Invicro LLC |
| ICON plc |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between SFDA-validated imaging core labs and non-accredited regional providers manifests in both procurement premiums and supply chain sourcing patterns across the Middle East and Africa Clinical Trial Imaging Market. Saudi sovereign health funds pay substantial markups for DICOM-compliant vendors with centralized review infrastructure while Egyptian and Nigerian sites absorb equipment import duties that compress margins for 2D protocol providers.
Pricing Analysis
Expedited lead-time premiums dominate contract negotiations, with sponsors paying 25-40% markups for core labs guaranteeing blinded reader turnaround under 72 hours versus standard 10-day adjudication cycles. Project-based pricing structures predominate across oncology trials, where volume scale and regulatory submission bundling drive differentiation. Cost compression in the 2D imaging tier intensifies because Egyptian hospital networks favor legacy radiography to avoid MRI and CT scanner import duties. Contract Research Organizations exhibit highest price sensitivity due to sponsor portfolio consolidation pressures, while pharmaceutical companies with sovereign health system direct access show least sensitivity.
Supply Chain Analysis
Saudi Arabia's local-content mandates for healthcare infrastructure spending are reshaping vendor qualification requirements, forcing core labs to establish domestic radiologist pools and DICOM-compliant data centers within the Kingdom. Equipment supply concentrates in Germany, Japan, and the United States for MRI and CT scanner manufacturing, while cloud-native software platforms draw from Irish and Indian development centers. Single-source vulnerability pervades the AI-assisted segmentation algorithm tier, where EU AI Act validation requirements tether sponsors to a narrow vendor set. Distribution runs through CRO intermediaries in fragmented markets and direct hospital network contracts in Riyadh and Johannesburg corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa Clinical Trial Imaging Market functions as a vertical-integration race where control over blinded reader certification cycles and cloud-native platform architecture determines pricing power and client retention longevity.
For Market Incumbents: Deepen radiologist adjudication capacity within Saudi Arabia's sovereign health zones to defend against emerging pure-play AI segmentation vendors. Anchor long-term contracts with King Faisal Specialist Hospital and parallel institutions across the Eastern Province. Invest in backward integration into DICOM-compliant data center infrastructure to reduce third-party cloud dependency and accelerate quality control workflows. For New Entrants and Emerging Players: Academic medical centers in North Africa represent an underserved buyer archetype with limited commercial imaging budgets and unmet iron overload quantification needs. Penetrate Egypt's hematology trial segment through specialized liver imaging biomarker services that incumbent CROs overlook. Pursue investigator-initiated study partnerships as a go-to-market angle that bypasses consolidated CRO procurement channels. For Investors and Strategic Acquirers: Re-rating potential sits with niche core labs possessing proprietary algorithm platforms given EU AI Act compliance burdens that favor validated incumbents. Long-term viability over a multi-year horizon hinges on regulatory submission expertise rather than geographic footprint scale. Target acquisition archetypes include specialized liver imaging biomarker providers and cloud-native quality control platform developers. Monitor SFDA protocol harmonization announcements as the critical inflection signal for vendor consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Certification Investment | Validates imaging protocols for multi-site oncology trials across Saudi sovereign health infrastructure. |
| Cloud-Native Platform Migration | Unifies acquisition, quality control, and regulatory submission workflows for CRO portfolio consolidation. |
| AI Algorithm Validation Program | Secures EU AI Act compliance for machine learning readers deployed in multinational trials. |
| Radiologist Training Center Establishment | Addresses acute DICOM-certified specialist scarcity across Sub-Saharan Africa trial sites. |
| Direct Hospital Network Contracting | Bypasses CRO intermediation in Riyadh and Johannesburg concentrated demand pockets. |
Research Methodology
Independent corroboration across regulatory affairs directors at imaging core labs, clinical operations leads at Contract Research Organizations, and procurement managers at Saudi sovereign health funds underwrites the qualitative findings in this study. Primary interviews with SFDA compliance officers and South African Health Products Regulatory Authority imaging protocol specialists combined with secondary validation from ClinicalTrials.gov registry entries, SFDA medical device filings, and EMA submission documentation established the evidentiary base. Bottom-up trial volume modeling and top-down healthcare infrastructure spending analysis provided cross-verification.
Comparable-period anchoring to historical oncology trial initiation patterns across the analysis window informed the projection framework. Segmentation dimensions modeled include imaging modality, technology tier, end-user channel structure, and therapeutic application area, with regional regulatory cluster differentiation as an additional industry-specific layer. CAGRs were derived through exponential smoothing of annualized trial volume growth rates, incorporating AI-assisted adjudication adoption curves and 3D volumetric protocol displacement timelines as forecast inputs.
Revisions become necessary when SFDA protocol harmonization initiatives diverge from Egyptian or South African national frameworks, when EU AI Act enforcement intensity shifts, or when sovereign health fund allocation priorities redirect. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Nuclear Medicine Market
Medical Imaging
Non-Invasive & Minimally Invasive Medical Imaging and Visualization Systems Market
Medical Imaging
Global Artificial Intelligence in MRI Market
Medical Imaging
Global Medical Imaging Phantoms Market
Medical Imaging
Medical Digital Imaging Systems Market
Medical Imaging
Contrast Media/Contrast Agents Market
Medical Imaging
Japan Magnetic Resonance Imaging Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Equipment Market
Medical Imaging
Europe Open System MRI Market
Medical Imaging
Global Medical Image Management Market
Medical Imaging
India Diagnostic Imaging Equipment Market
Medical Imaging
Portable X-Ray Devices Market
Medical Imaging
Asia-Pacific Intraoperative Imaging Market
Medical Imaging
France Digital X-Ray Devices Market
Medical Imaging
Industrial Radiography Market
Medical Imaging
Global Colposcopy Market