
 Canada Diagnostic Imaging Equipment Market | 2026-2036
Canada Diagnostic Imaging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Diagnostic Imaging Equipment Market Outlook
Outpatient imaging centers is unwinding the traditional hospital-centric procurement pattern that has long dominated Canadian capital equipment budgets. GE Healthcare leverages its installed base of CT and MRI platforms across provincial health systems to sustain recurring service revenue streams. Siemens Healthineers anchors its position through advanced molecular imaging R&D partnerships with Canadian academic medical centers. Philips Healthcare differentiates via integrated diagnostic informatics that connect cardiology and radiology workflows.
Diagnostic imaging equipment encompasses systems that generate visual representations of internal body structures for clinical diagnosis, utilizing ionizing radiation, magnetic fields, or acoustic energy with spatial resolution parameters measured in millimeters and slice thickness. These technologies serve the primary commercial purpose of enabling non-invasive disease detection, treatment planning, and therapeutic monitoring across hospital and ambulatory settings. CT scan systems occupy the largest revenue pool within the product type dimension, reflecting sustained provincial investment in trauma and oncology staging capabilities. Digital technology leads the technology category as provinces retire analog film-based systems under quality improvement mandates. Cardiology applications within the application dimension are expanding fastest, driven by echocardiography and cardiac CT protocols for coronary artery assessment.
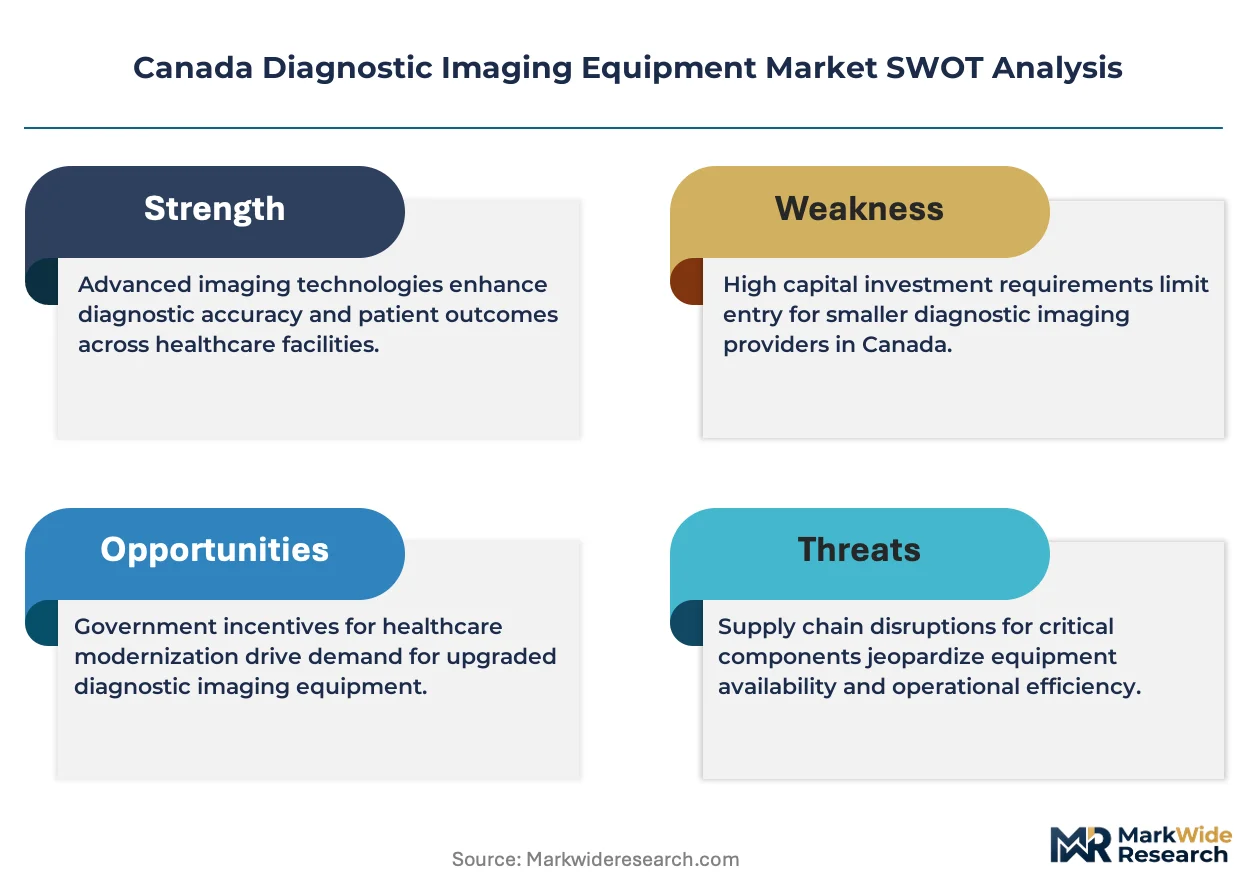
Health Canada regulates device licensing under the Medical Devices Regulations, while provincial health technology assessment bodies evaluate imaging modalities for public formulary inclusion. The Canadian Standards Association maintains electrical safety and electromagnetic compatibility standards that manufacturers must satisfy for market authorization. Procurement consolidation through shared service organizations in Ontario and Quebec is reshaping vendor contracting dynamics. Stakeholders must monitor how provincial budget allocations to diagnostic imaging balance equipment modernization against staffing and infrastructure priorities.
Market Dynamics
Provincial shared-service organizations in Ontario and Quebec are consolidating imaging procurement authority, compressing vendor negotiation cycles and favoring integrated system suppliers over standalone equipment vendors.
Growth Catalysts
- Health Canada Medical Devices Regulations:Mandatory licensing renewals and safety updates accelerate equipment replacement timelines across hospital networks.
- Outpatient imaging centers:These facilities expand capital budgets for digital radiography and portable ultrasound systems outside traditional hospital procurement channels.
- DICOM-3 compliance mandates:Provincial health authorities require PACS network interoperability, forcing analog-to-digital conversions.
Market Restraints
- Specialized isotope supply:Reliance on foreign reactors for medical isotopes creates vulnerability in PET-CT and SPECT system utilization rates.
- Technical limitation:Magnetic field homogeneity requirements in 3T MRI systems restrict installation sites to purpose-built shielded suites with substantial infrastructure costs.
- Regulatory friction:Health Canada's device licensing timelines extend commercialization pathways for novel imaging modalities compared to FDA-cleared equivalents.
Strategic Opportunities
- Remote and northern territories:Underpenetrated regions lack fixed imaging infrastructure, creating demand for mobile CT and teleradiology-linked ultrasound deployments.
- Artificial intelligence integration:Convergence of deep learning algorithms with CT and MRI reconstruction workflows enables faster scan protocols and reduced radiologist reading burden.
- Cardiac CT angiography:Emerging coronary artery assessment protocols displace diagnostic catheterization in stable chest pain pathways, expanding scanner throughput requirements.
Industry Challenges
- Specialized technologist shortage:MRI and nuclear medicine technologist training programs produce insufficient graduates to staff expanded provincial imaging networks.
- Legacy PACS integration:Hospital information system vendors maintain proprietary data formats that obstruct seamless interoperability with third-party diagnostic equipment.
- Equipment obsolescence cycles:Accelerated refresh mandates from provincial quality improvement programs strain capital allocation against competing infrastructure priorities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Diagnostic Imaging Equipment Market |
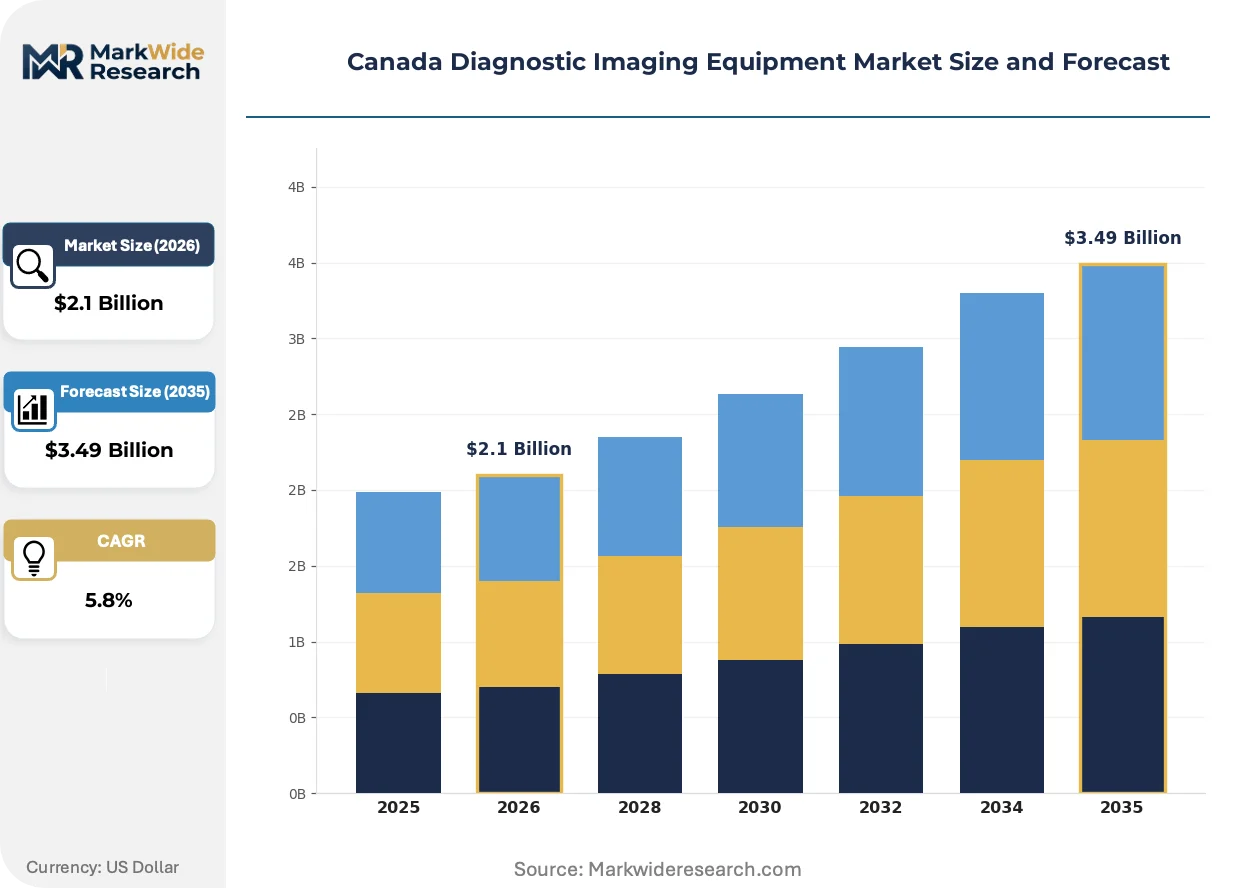
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-ray, MRI, CT Scan, Ultrasound Application: Radiology, Oncology, Cardiology, Neurology Technology: Analog, Digital, Hybrid, 3D Imaging End User: Hospitals, Clinics, Research Facilities, Outpatient Centers |
| Companies Covered | GE Healthcare, Siemens Healthineers, Philips Healthcare, Canon Medical Systems Corporation, FUJIFILM Holdings Corporation, Carestream Health, Esaote SpA, Mindray Medical International Limited, Hitachi Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Diagnostic Imaging Equipment Market Strategic Shifts
Digital detector technology and computational reconstruction methods are compressing examination times while expanding point-of-care deployment possibilities across Canadian healthcare settings.
Portable ultrasound systems with semiconductor-based transducer arrays is miniaturizing traditional cart-based platforms into handheld devices. Community hospitals and rural clinics adopt these systems for bedside cardiac and abdominal assessments. The form factor reduction is enabling imaging capabilities in ambulances and remote nursing stations previously unreachable by conventional equipment.
Health Canada's transition toward risk-based device classification aligns licensing requirements with international Medical Device Single Audit Program standards. Manufacturers face streamlined quality system audits but heightened post-market surveillance obligations. Class III imaging devices encounter accelerated review timelines while maintaining equivalent safety thresholds.
Provincial health authorities bundle diagnostic equipment procurement with multi-year service and informatics contracts. Shared-service organizations in Ontario consolidate CT and MRI purchasing across hospital clusters, displacing individual institutional negotiations. Quebec's integrated university health networks apply similar centralized contracting for molecular imaging systems.
Canada Diagnostic Imaging Equipment Market Segmentation
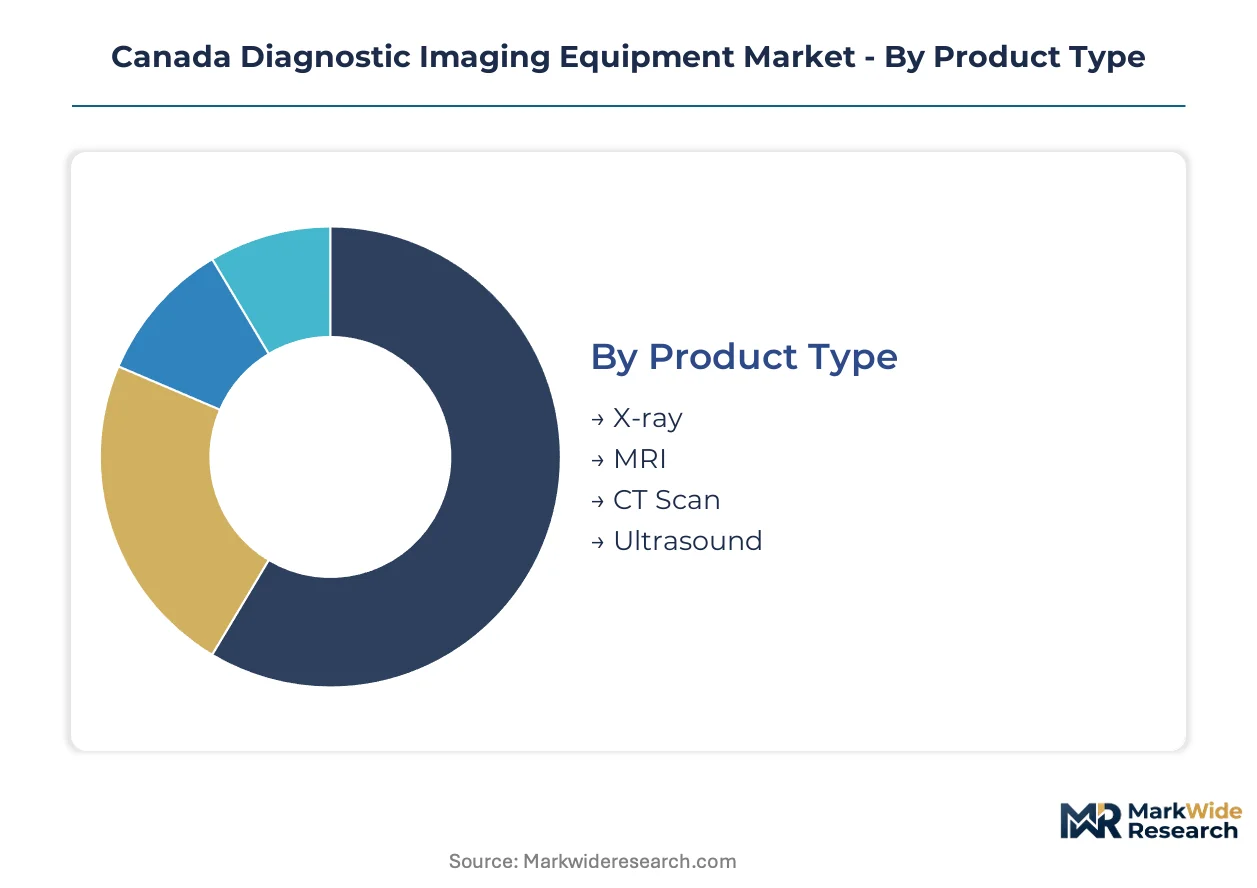
Segmentation reveals how Health Canada's device classification tiers and provincial procurement consolidation reshape vendor targeting strategies across distinct customer and technology clusters. Understanding these divides clarifies where capital allocation concentrates and which modalities face accelerated replacement cycles.
Product Type:
Health Canada applies Class II and III licensing thresholds that segment capital requirements and clinical validation burdens unevenly across modalities.
- CT Scan:Multi-detector systems with 64-slice and above configurations dominate provincial trauma and oncology staging investments. Ontario's shared-service organizations bundle CT procurement with multi-year service contracts, compressing vendor margins while locking in installed base loyalty.
- Ultrasound:Semiconductor-based transducer arrays now enable handheld form factors that penetrate ambulances and remote nursing stations previously unreachable by cart-based platforms. Quebec's outpatient imaging centers prioritize portable systems for point-of-care cardiac and abdominal assessments.
- X-ray:Digital radiography detectors replace analog film under provincial quality mandates.
- MRI:3T systems require purpose-built shielded suites that restrict installation to major academic centers.
CT Scan handles the majority of throughput; Ultrasound is the fastest mover on share.
Application:
Clinical workflow integration demands vary sharply by specialty, with cardiology and oncology commanding distinct informatics architectures.
- Cardiology:Echocardiography and cardiac CT protocols for coronary artery assessment displace diagnostic catheterization in stable chest pain pathways. Ontario health networks expand scanner throughput requirements to accommodate non-invasive cardiac imaging volume growth.
- Radiology:General diagnostic workflows anchor PACS network investments and DICOM-3 compliance mandates across provincial systems.
- Oncology:PET-CT and molecular imaging dependence on foreign isotope supply creates utilization vulnerability.
- Neurology:Functional MRI and diffusion tensor applications concentrate at university-affiliated centers.
Radiology maintains the deepest installed base; Cardiology is climbing the fastest on procedure volume.
Technology:
Cost tier differentiation separates legacy analog maintenance from digital refresh investments and emerging 3D reconstruction capabilities.
- Digital:Flat-panel detectors and computational reconstruction methods compress examination times while enabling teleradiology-linked deployments. Provincial health authorities mandate digital conversion as condition of PACS network participation.
- 3D Imaging:Cone-beam CT and tomosynthesis reconstruction algorithms expand diagnostic specificity in orthopedic and breast imaging applications.
- Hybrid:PET-CT and SPECT-CT fusion systems combine functional and anatomical data.
- Analog:Film-based systems persist in underfunded rural facilities facing capital constraints.
Digital captures the dominant replacement cycle; 3D Imaging shows the steepest expansion trajectory on emerging protocol adoption.
End User:
Procurement authority concentration through shared-service organizations privileges integrated suppliers capable of spanning hospital and ambulatory settings.
- Hospitals:Academic medical centers and community hospitals anchor CT and MRI procurement through Ontario's hospital cluster purchasing and Quebec's integrated university health networks. Multi-year service and informatics bundling displaces standalone equipment negotiations.
- Outpatient Centers:Independent imaging facilities expand capital budgets for digital radiography and portable ultrasound outside traditional hospital procurement channels, unwinding legacy hospital-centric patterns.
- Clinics:Primary care and specialty clinics adopt handheld ultrasound for limited bedside applications.
- Research Facilities:Preclinical imaging and advanced molecular imaging R&D partnerships concentrate at Canadian academic medical centers.
Hospitals command the largest capital pool; Outpatient Centers are gaining share fastest on volume migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and US manufacturers export diagnostic imaging systems through established distribution corridors into Canadian provincial health networks, with Ontario and Quebec serving as primary entry points for capital equipment procurement.
Ontario
Toronto's hospital clusters and shared-service organizations consolidate CT and MRI purchasing authority, compressing vendor negotiation cycles. Health Canada's Medical Devices Regulations govern licensing renewals for equipment deployed across the province's integrated imaging networks. The Greater Toronto Area anchors molecular imaging R&D partnerships between academic medical centers and equipment suppliers.
Quebec
Montreal's integrated university health networks apply centralized contracting for PET-CT and SPECT systems, displacing individual institutional negotiations. The province's health technology assessment bodies evaluate imaging modalities for public formulary inclusion alongside federal regulatory requirements. Quebec City and Montreal house the country's densest concentration of nuclear medicine infrastructure.
Alberta
Calgary and Edmonton health authorities expand cardiac CT angiography protocols for coronary artery assessment, driving scanner throughput requirements. Provincial quality improvement mandates accelerate analog-to-digital conversions in community hospitals. The Edmonton zone consolidates procurement for rural and northern territory mobile imaging deployments.
British Columbia
Vancouver Coastal Health and Fraser Health authorities bundle diagnostic equipment procurement with multi-year informatics contracts. Health Canada's transition toward risk-based device classification streamlines quality system audits for manufacturers supplying the province. Vancouver's academic medical centers concentrate functional MRI and diffusion tensor research applications.
Atlantic Canada
Underpenetrated rural regions in Nova Scotia and New Brunswick create demand for teleradiology-linked ultrasound and mobile CT deployments. Provincial health authorities mandate DICOM-3 compliance as a condition of PACS network participation. Halifax anchors the region's limited fixed imaging infrastructure while serving as a hub for remote nursing station equipment allocation.
Canada Diagnostic Imaging Equipment Market Competitive Environment
Listed leaders compete with private specialists across procurement channel consolidation, with multinational conglomerates facing independent equipment vendors for provincial shared-service contracts. The vendor base stratifies into three tiers: integrated system suppliers capable of spanning hospital and ambulatory settings; standalone modality manufacturers competing on price; and regional service specialists maintaining legacy installed bases. Dominant competitive moves include multi-year service contract bundling and AI-enabled workflow software integration.
Among diversified healthcare conglomerates, GE Healthcare, Siemens Healthineers, and Philips Healthcare exemplify the integrated supplier archetype that provincial shared-service organizations favor for consolidated CT and MRI procurement. These entities anchor positions through recurring service revenue streams and diagnostic informatics platforms rather than standalone equipment transactions. Their scale enables compliance with Health Canada's Medical Devices Regulations while supporting the multi-year contracting horizons that Ontario and Quebec procurement authorities require.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Philips Healthcare |
| Canon Medical Systems Corporation |
| FUJIFILM Holdings Corporation |
| Carestream Health |
| Esaote SpA |
| Mindray Medical International Limited |
| Hitachi Ltd |
| Others |
Value Chain & Pricing Dynamics
Health Canada's Medical Devices Regulations gate both supplier qualification and price differentiation simultaneously, mandating Class II and III licensing tiers that stratify capital requirements while provincial shared-service organizations compress vendor margins through bundled contracting.
Pricing Analysis
Current-generation 3T MRI and 64-slice CT systems command premium positioning against prior-generation 1.5T MRI and 16-slice CT platforms, while next-generation photon-counting CT and 7T MRI remain pre-commercial. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service bundling and DICOM-3 compliance certification. Cost compression in standard-tier digital radiography intensifies because outpatient imaging centers bypass hospital procurement channels. Community hospitals exhibit highest price sensitivity; academic medical centers prioritize performance specifications over unit economics.
Supply Chain Analysis
Specialized isotope supply from foreign reactors in Belgium and the Netherlands underwrites PET-CT and SPECT system utilization, creating single-source vulnerability for molecular imaging modalities. Semiconductor-based transducer arrays draw from Taiwan and South Korea fabrication facilities, while superconducting magnet wire rests on Japanese and German metallurgy. Tariff exposure on Chinese-sourced flat-panel detectors threatens digital radiography cost structures. Distribution runs through provincial shared-service organizations in Ontario and Quebec, displacing direct hospital vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Provincial procurement consolidation fragments vendor opportunity structures, as outpatient imaging center expansion and remote territory underpenetration create addressable niches outside integrated hospital networks.
For Market Incumbents: Compound installed base loyalty through multi-year service contract extensions and AI-enabled workflow software integration. Defend against standalone portable ultrasound vendors by anchoring diagnostic informatics platforms that connect cardiology and radiology workflows. Prioritize certification investment in Health Canada's risk-based device classification transition. For New Entrants and Emerging Players: Differentiate on teleradiology-linked ultrasound deployments for northern territories and remote nursing stations. Target underpenetrated Atlantic Canada rural regions with mobile CT platforms. Pursue hospital system partnership strategies that bundle equipment with radiologist staffing solutions. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed outpatient imaging center rollups consolidating across Ontario and Quebec. Five-to-ten year viability hinges on provincial budget allocation stability for diagnostic imaging modernization. Watch Health Canada post-market surveillance obligation intensification as inflection indicator for compliance cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Health Canada Class III Licensing Pathway | Accelerates commercialization timelines for novel imaging modalities against FDA-cleared equivalents. |
| Provincial Shared-Service Organization Partnership | Locks in multi-year CT and MRI procurement across Ontario hospital clusters. |
| AI-Enabled Reconstruction Software Development | Reduces scan protocols and radiologist reading burden in academic medical centers. |
| Mobile Imaging Deployment for Northern Territories | Addresses infrastructure gaps in underpenetrated regions lacking fixed CT installations. |
| DICOM-3 Compliant PACS Integration | Mandatory condition for provincial health authority network participation. |
Study Parameters
Initial hypotheses were tested against primary input from hospital purchasing committee chairs, biomedical engineering directors, GPO contracts managers, and provincial health technology assessment officers and refined through secondary validation against Health Canada device licensing databases, hospital procurement records, and provincial budget allocation documents. Bottom-up equipment shipment data triangulated with top-down provincial health expenditure models.
Variance-decomposition across product type, application, technology tier, and end-user segments shaped the analytical framework over the projection horizon. CAGRs derived from equipment replacement cycle analysis, provincial capital budget trajectories, and technology adoption S-curves. Forecast inputs incorporated DICOM-3 compliance mandate timelines and shared-service organization procurement consolidation patterns.
Decision-makers should treat outputs as directional under stable provincial health expenditure assumptions; material deviation in federal transfer payment structures would warrant model refresh. Practitioners should keep alternative scenarios live as Health Canada post-market surveillance obligations and foreign isotope supply reliability evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
3D Imaging Surgical Solution Market
Medical Imaging
Global Technetium-99M Market
Medical Imaging
Retinal Imaging Devices Market
Medical Imaging
China Digital X-Ray Market
Medical Imaging
US Magnetic Resonance Imaging Market
Medical Imaging
Breast Imaging Market
Medical Imaging
Fluoroscopy and Mobile C-Arms Market
Medical Imaging
Medical Videoscope Market
Medical Imaging
Orthopedic Imaging Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Equipment Market
Medical Imaging
Veterinary Computed Tomography Scanner Market
Medical Imaging
United Kingdom Diagnostic Imaging Equipment Market
Medical Imaging
South Africa Magnetic Resonance Imaging Market
Medical Imaging
France Computed Tomography Market
Medical Imaging
Brazil Nuclear Imaging Market
Medical Imaging
Canada Nuclear Imaging Market