
 United Kingdom Neurology Devices Market | 2026-2036
United Kingdom Neurology Devices Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Neurology Devices Market Analytics
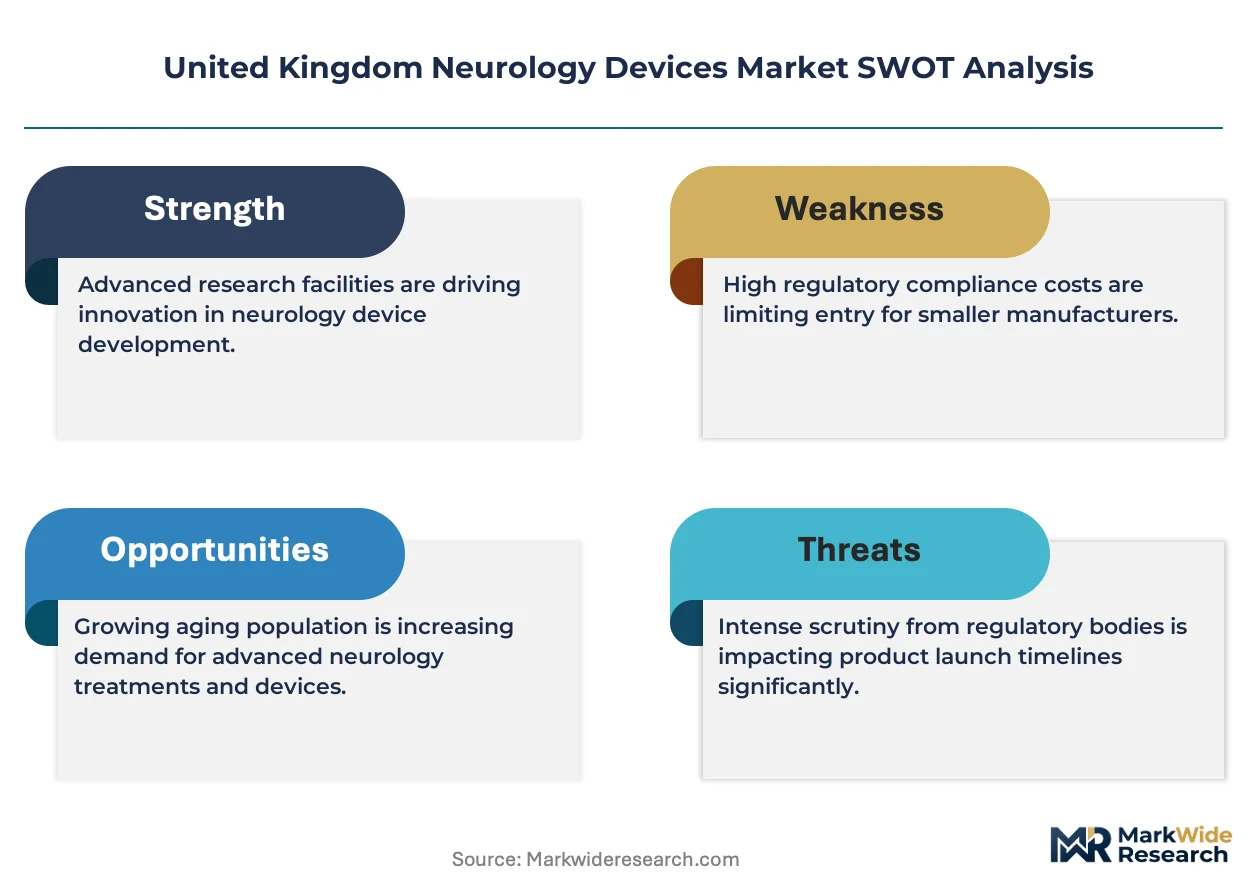
A shortage of trained neurointerventional radiologists is collapsing wait times for deep brain stimulation and endovascular procedures across NHS England. Medtronic PLC leverages its integrated neuromodulation portfolio to sustain service contracts with major teaching hospitals. Boston Scientific Corporation anchors its competitive position through specialized catheter-based platforms for stroke intervention. Abbott Laboratories differentiates via its neuromodulation division's focus on chronic pain and movement disorders.
Neurology devices encompass instruments, implants, and systems engineered to diagnose, monitor, or treat disorders of the central and peripheral nervous systems, typically operating through electrical signal modulation, mechanical intervention, or advanced imaging with spatial resolution below one millimetre for precise anatomical targeting. Their primary purpose is to restore neurological function, halt disease progression, or enable real-time intraoperative decision-making in conditions ranging from epilepsy to acute ischaemic stroke. Neurostimulation devices occupy the largest revenue pool as implantable pulse generators command premium pricing and recurring battery replacement cycles. EEG devices represent the fastest-expanding segment among diagnostics, driven by ambulatory monitoring demand and wireless delivery mode integration. MRI systems remain structurally mature, with replacement demand rather than first-time installation propelling capital expenditure.
MHRA now operates independent of EMA centralized procedures, creating a dual-track approval environment where UKCA marking requirements diverge from CE standards for active implantable devices. NHS England's MedTech Funding Mandate selectively accelerates reimbursement for technologies demonstrating measurable patient pathway efficiencies, directly shaping manufacturer commercialisation priorities. The Care Quality Commission's inspection regime for neurosurgical units further constrains site certification, filtering market access. Stakeholders must monitor how MHRA alignment negotiations with FDA and TGA evolve, as mutual recognition agreements could compress regulatory lag for novel neurology devices.
Market Dynamics
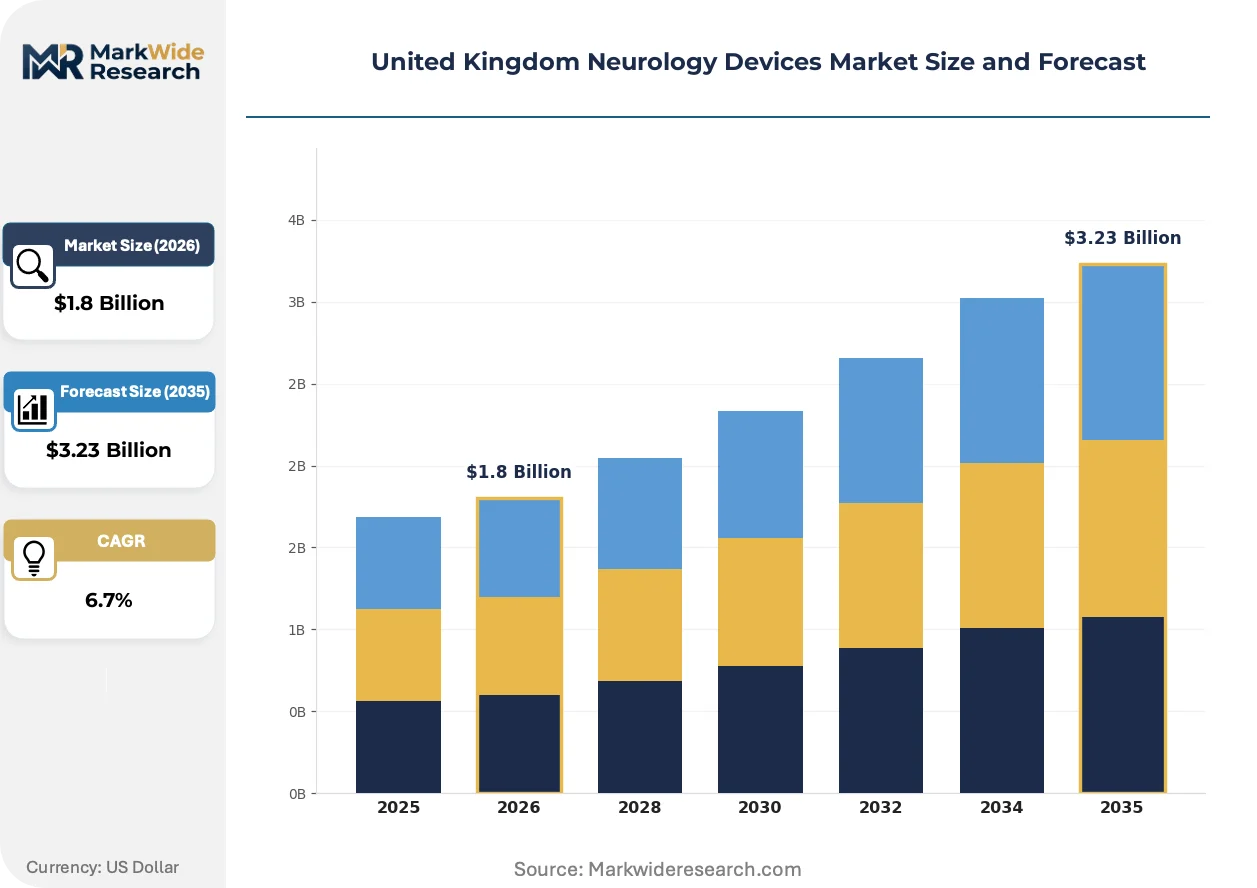
MHRA's post-Brexit regulatory autonomy is fragmenting approval pathways, forcing manufacturers to maintain parallel UKCA and CE certification streams while NHS England's MedTech Funding Mandate selectively fast-tracks reimbursement for pathway-efficient technologies.
Growth Catalysts
- NHS MedTech Funding Mandate:Reimbursement acceleration for stroke thrombectomy and deep brain stimulation technologies compresses adoption timelines across specialist neuroscience centres.
- Ambulatory EEG monitoring:Wireless delivery mode integration enables home-based epilepsy diagnostics, expanding addressable patient populations beyond hospital-confined testing.
- Greater London cluster concentration:Specialist neuroscience centre density in the South East generates referral gravity that pulls complex cases from peripheral regions.
Market Restraints
- Neurointerventional radiologist shortage:NHS England training pipeline constraints collapse wait times for endovascular thrombectomy and DBS procedures.
- Dual-track certification costs:MHRA UKCA marking divergence from CE MDR standards forces redundant technical documentation and conformity assessment expenditure.
- Implantable pulse generator battery replacement cycles:Recurring surgical intervention requirements limit patient eligibility in frail populations and constrain volume scalability.
Strategic Opportunities
- Telemedicine-integrated neurostimulation programming:Remote device adjustment capabilities reduce specialist clinic burden and expand rural patient access.
- NHS England Long Term Plan stroke pathway redesign:Thrombectomy capacity expansion mandates create procurement windows for catheter-based intervention platforms.
- Wales and Northern England underpenetration:Peripheral region specialist centre scarcity presents first-mover advantage for hub-and-spoke service model deployment.
Industry Challenges
- Care Quality Commission neurosurgical unit certification:Inspection regime stringency filters site-level market access and constrains eligible implanting centres.
- Legacy MRI system incompatibility:Neurostimulation device electromagnetic interference limitations restrict patient eligibility for concurrent diagnostic imaging.
- MHRA-FDA mutual recognition negotiation uncertainty:Transatlantic alignment timeline ambiguity delays novel device launch sequencing decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Neurology Devices Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Neurostimulation Devices, EEG Devices, MRI Systems, Invasive Monitoring Systems End User: Hospitals, Neurology Clinics, Research Laboratories, Rehabilitation Centers Delivery Mode: Wireless, Portable, Implantable, Desktop Technology: Robotic Assistance, Signal Processing, Biosensors, 3D Imaging |
| Companies Covered | Medtronic PLC, Boston Scientific Corporation, Abbott Laboratories, LivaNova PLC, Stryker Corporation, B. Braun Melsungen AG, Johnson and Johnson Services Inc., Penumbra Inc., Nihon Kohden Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Neurology Devices Market Evolving Landscape
Neurology device development is pivoting toward closed-loop adaptive systems and decentralized care delivery models that compress specialist dependency while MHRA regulatory evolution reshapes commercialisation sequencing.
Closed-loop neurostimulation is bifurcating therapeutic response through real-time biomarker-driven feedback adjustment. NHS teaching hospitals in Greater London and Oxford are piloting responsive DBS systems for Parkinson's disease at accelerated procurement cadences. This capability is bifurcating market structure into premium adaptive platforms and conventional open-loop alternatives with diverging reimbursement negotiation leverage.
MHRA's independent post-Brexit framework diverges from EMA centralized procedures for active implantable devices. UKCA marking timelines currently exceed CE MDR parallels by four to eight months for novel neuromodulation systems. Stroke intervention catheter platforms face the most pronounced approval lag, compressing manufacturer UK launch prioritisation relative to continental European sequencing.
After-sales service unbundling is fragmenting traditional device-vendor relationships. NHS procurement teams are separating implant hardware from long-term programming and battery replacement service contracts. This disintermediation is most visible in Greater Manchester and West Midlands trusts, where neurostimulation service tendering now runs independently from capital equipment frameworks.
United Kingdom Neurology Devices Market Segmentation
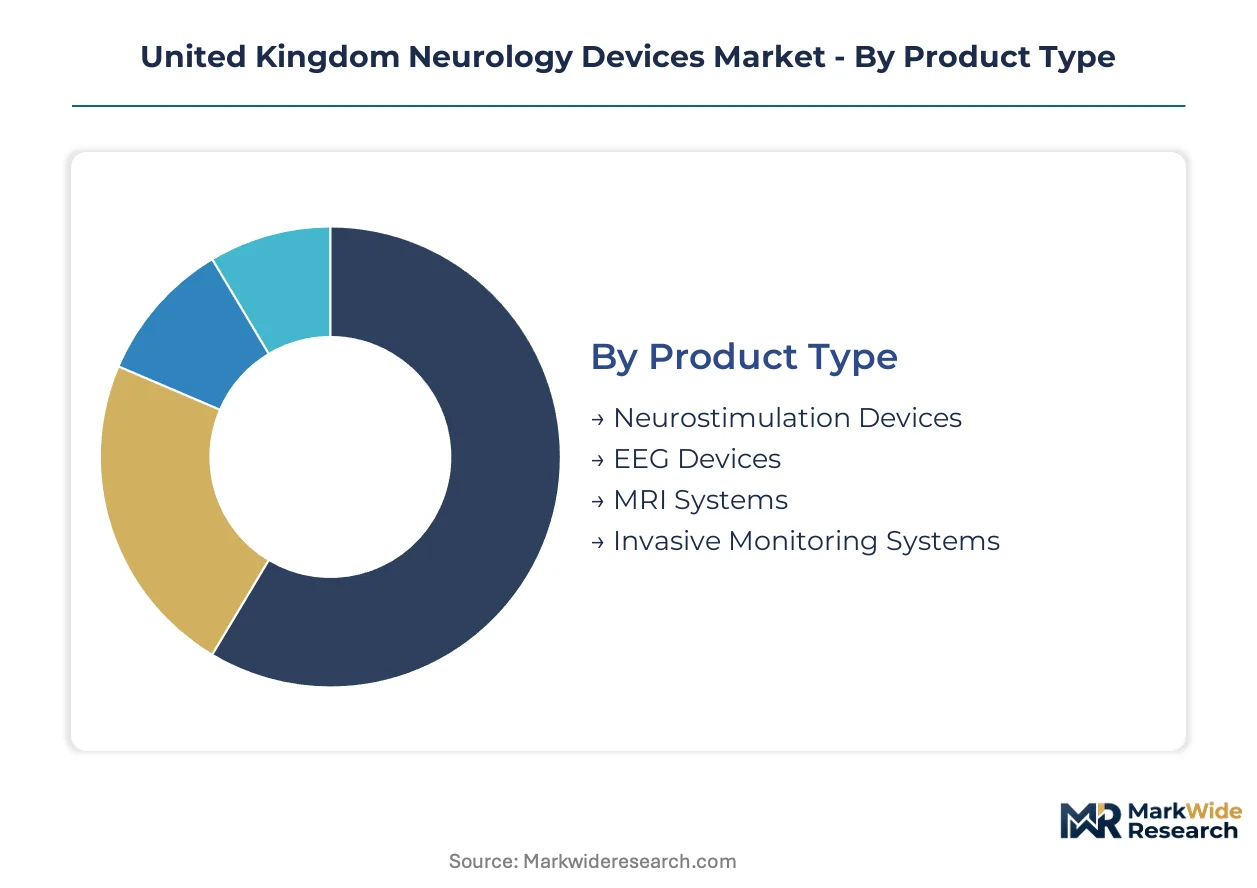
Neurology device segmentation in the United Kingdom reveals divergent margin architectures across hardware, service delivery, and site-of-care dimensions. Manufacturers calibrate portfolio investments against NHS procurement patterns and MHRA certification requirements that vary by product complexity.
Product Type:
Margin pools concentrate in implantable systems with recurring service revenue streams rather than capital-intensive diagnostic platforms.
- Neurostimulation Devices:Implantable pulse generators with battery replacement cycles generate sustained aftermarket revenue. Greater London teaching hospitals command premium pricing for deep brain stimulation systems through concentrated specialist referral networks.
- EEG Devices:Wireless ambulatory monitoring platforms enable home-based epilepsy diagnostics outside hospital confines. NHS England's MedTech Funding Mandate accelerates procurement for pathway-efficient technologies that reduce specialist clinic burden.
- MRI Systems:Replacement demand dominates capital expenditure as first-time installation saturates.
- Invasive Monitoring Systems:Intracranial pressure and electrocorticography platforms serve neurocritical care units.
Neurostimulation devices hold installed capacity. EEG devices are rotating up the share rankings.
End User:
Procurement authority and reimbursement complexity fragment demand across institutional tiers with divergent capital allocation flexibility.
- Hospitals:NHS foundation trusts and specialist neuroscience centres concentrate complex intervention volumes. MHRA UKCA marking requirements for active implantable devices filter eligible suppliers at major teaching hospitals in Oxford and Manchester.
- Neurology Clinics:Outpatient diagnostic and programming services expand patient access beyond acute settings. Wireless neurostimulation adjustment capabilities reduce specialist clinic burden across Greater London peripheral networks.
- Research Laboratories:Academic medical centres drive early adoption of closed-loop adaptive systems.
- Rehabilitation Centers:Post-stroke and movement disorder recovery programs generate demand for non-invasive neuromodulation.
Hospitals dominate current procurement volumes. Neurology clinics are gaining share fastest through decentralized care models.
Delivery Mode:
Patient mobility requirements and surgical risk tolerance stratify technology selection across frail and ambulatory populations.
- Wireless:Bluetooth-enabled ambulatory EEG and remote neurostimulation programming eliminate tethered constraints. South East specialist centre density pulls complex cases from peripheral regions through referral gravity.
- Implantable:Pulse generators and invasive monitoring hardware require surgical intervention with electromagnetic interference limitations.
- Portable:Mobile diagnostic units serve underpenetrated Wales and Northern England markets.
- Desktop:Fixed-station EEG and programming systems retain hospital-confined deployment.
Implantable systems anchor revenue stability. Wireless platforms are climbing the fastest as home-based monitoring expands addressable populations.
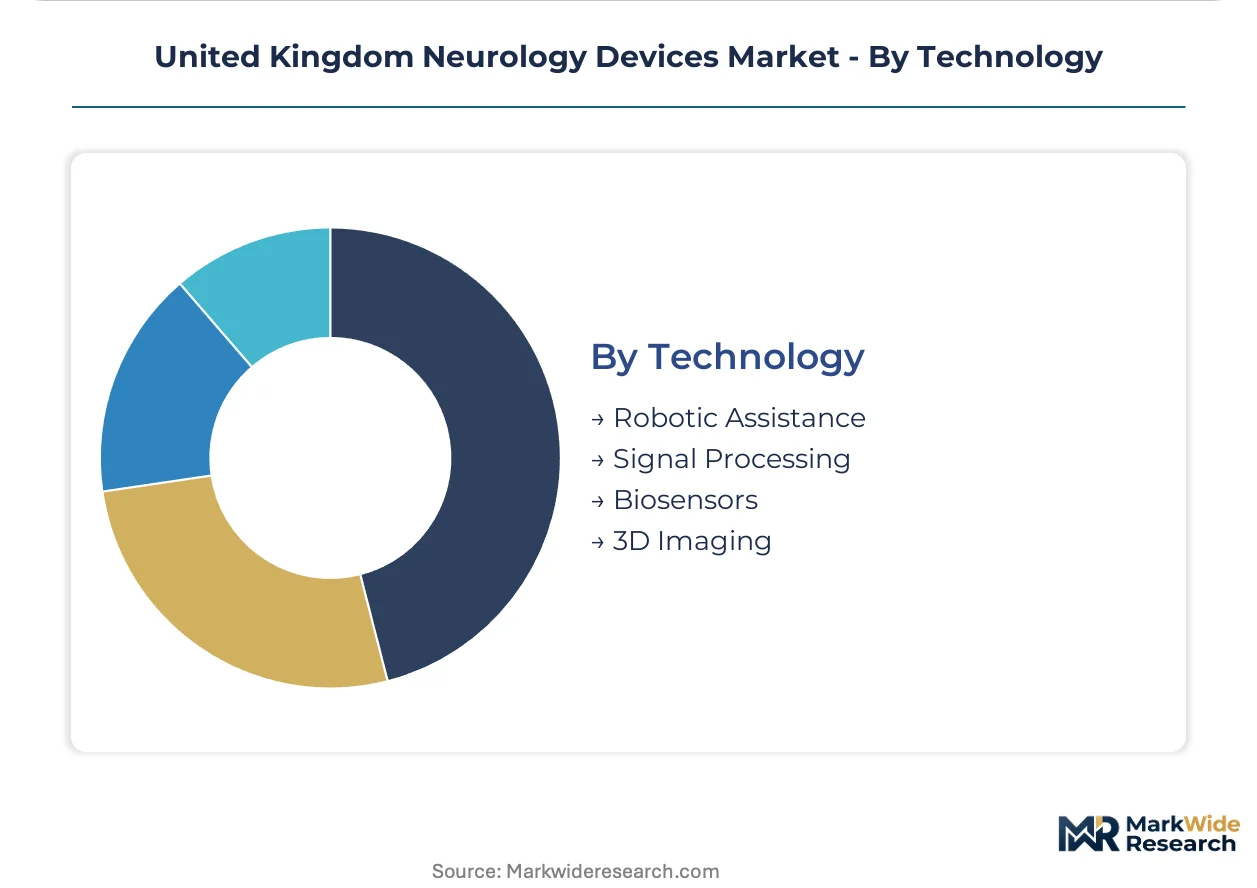
Technology:
Precision requirements and automation intensity differentiate platform architectures across intervention and diagnostic applications.
- Robotic Assistance:Stereotactic navigation and catheter guidance systems reduce operator dependency for deep brain stimulation and endovascular thrombectomy. NHS England training pipeline constraints for neurointerventional radiologists accelerate automation adoption.
- Signal Processing:Real-time biomarker analysis enables closed-loop therapeutic adjustment in responsive neurostimulation.
- Biosensors:Chronic implantable electrodes and wearable platforms capture neural and physiological data streams.
- 3D Imaging:Intraoperative navigation and preoperative planning integrate multimodal anatomical visualization.
Signal processing capabilities hold embedded value. Robotic assistance is rotating up the share rankings as workforce constraints intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neurology device consumption across the United Kingdom concentrates in Greater London and the South East, where specialist neuroscience centres cluster around teaching hospitals, while Wales and Northern England remain structurally underpenetrated with patients travelling significant distances for complex interventions.
Greater London and South East
Deep brain stimulation and endovascular thrombectomy volumes concentrate at National Hospital for Neurology and Neurosurgery, King's College Hospital, and Oxford University Hospitals. NHS England's MedTech Funding Mandate accelerates procurement for pathway-efficient technologies across these trusts. The cluster generates referral gravity that pulls complex cases from peripheral regions, sustaining premium pricing for implantable pulse generators.
Midlands
Queen Elizabeth Hospital Birmingham and University Hospitals of Leicester anchor neurointerventional capacity in England's central corridor. The Care Quality Commission's inspection regime filters eligible implanting centres, constraining site-level market access. Service contract unbundling is most visible in Greater Manchester and West Midlands trusts, where neurostimulation programming tenders run independently from capital equipment frameworks.
North England
Walton Centre in Liverpool and Salford Royal Hospital maintain specialist neuroscience units amid broader regional scarcity. MHRA UKCA marking requirements for active implantable devices filter supplier eligibility at major teaching hospitals in Manchester. Peripheral region specialist centre scarcity presents first-mover advantage for hub-and-spoke service model deployment.
Scotland
NHS Scotland operates through territorial health boards with neurosurgical concentration at Edinburgh's Western General Hospital and Glasgow's Queen Elizabeth University Hospital. The Scottish Government's health technology assessment processes parallel NHS England reimbursement pathways with distinct timelines. Edinburgh's bioelectronics research cluster feeds early adoption of closed-loop adaptive neurostimulation systems.
Wales
Cardiff and Vale University Health Board hosts the sole comprehensive neuroscience centre serving a population of over three million. Portable diagnostic units and mobile EEG services address geographic access barriers across rural North Wales and West Wales. Welsh Government procurement frameworks diverge from NHS England's MedTech Funding Mandate, creating distinct commercialisation sequencing for manufacturers.
United Kingdom Neurology Devices Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the United Kingdom neurology devices market. Medtronic PLC, Boston Scientific Corporation, and Abbott Laboratories anchor the upper tier through comprehensive neuromodulation portfolios and established NHS service contracts. Beneath them, catheter-based stroke intervention specialists and regional diagnostic equipment fabricators occupy narrower competitive positions. The dominant competitive moves include strategic partnerships with teaching hospitals for pilot programmes and portfolio diversification into closed-loop adaptive systems.
Within the integrated multinational tier, Medtronic PLC and Boston Scientific Corporation exemplify the service-contract-dependent archetype that sustains long-term NHS relationships. Abbott Laboratories occupies a position emphasising chronic pain and movement disorder specialisation. Among catheter-based intervention specialists, Penumbra Inc. and Stryker Corporation represent the stroke-thrombectomy-focused segment where NHS England pathway redesign is accelerating procurement windows. These three company groupings illustrate how competitive positioning diverges between comprehensive neuromodulation platforms and targeted intervention technologies.
| Leading Market Players |
|---|
| Medtronic PLC |
| Boston Scientific Corporation |
| Abbott Laboratories |
| LivaNova PLC |
| Stryker Corporation |
| B. Braun Melsungen AG |
| Johnson and Johnson Services Inc. |
| Penumbra Inc. |
| Nihon Kohden Corporation |
| Others |
Value Network & Pricing Analysis
Capacity utilization at NHS specialist neuroscience centres concentrates procurement leverage among a handful of foundation trusts, compressing price floors for implantable pulse generators while elevating service-attach premiums for programming and battery replacement cycles.
Pricing Analysis
Long-term service contracts dominate neurostimulation procurement, with hardware purchase prices decoupled from multi-year programming and maintenance agreements. Price differentiation hinges on MHRA UKCA certification tier and after-sales service bundling depth. Cost compression in standard-tier EEG devices is intensifying because NHS procurement frameworks favor pathway-efficient technologies with measurable wait-time reductions. Academic medical centres exhibit lowest price sensitivity due to research funding insulation, while peripheral NHS trusts in Wales and Northern England face acute budget constraints.
Supply Chain Analysis
Inventory buffers for implantable pulse generators stretch six to nine months due to MHRA batch-release testing requirements, elongating lead times for active implantable devices relative to diagnostic platforms. Manufacturing concentrates in Ireland, Germany, and the United States for neurostimulation hardware, with sterile packaging and electrode arrays sourcing from Switzerland and the Netherlands. Single-source vulnerability sits with specialized catheter-based stroke intervention platforms where Penumbra and Stryker maintain concentrated production. Distribution runs through NHS Supply Chain central procurement with direct-to-hospital logistics for emergency stroke thrombectomy devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Neurology device monetization is pivoting toward recurring-revenue service layers, with remote neurostimulation programming and battery replacement cycles expanding faster than capital hardware sales across NHS England trusts.
For Market Incumbents: Secure exclusive service contracts with Greater London teaching hospitals before procurement unbundling spreads to Oxford and Manchester clusters. Deepen backward integration into electrode manufacturing to offset raw material cost volatility from platinum-iridium suppliers. The priority defensive move is locking in closed-loop adaptive system pilot programmes before Boston Scientific and Abbott expand their responsive DBS footprints. For New Entrants and Emerging Players: Anchor in Wales and Northern England hub-and-spoke service models where specialist centre scarcity creates procurement windows for portable diagnostic platforms. Target ambulatory EEG monitoring for home-based epilepsy diagnostics, the fastest-climbing segment by delivery mode. A direct go-to-market angle partners with NHS Supply Chain for framework inclusion rather than competing for individual trust tenders. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among neurostimulation service specialists with captive programming relationships across multiple NHS trusts. Long-term viability over a five-to-ten year horizon favors acquisition targets with MHRA UKCA certification momentum and established battery replacement patient cohorts. The signal to watch is MHRA-FDA mutual recognition agreement progress, which would compress regulatory lag and accelerate novel device launch sequencing for UK-first entrants.| Strategic Initiative | Industry Significance |
|---|---|
| MHRA UKCA Certification Pathway | Independent post-Brexit marking requirements diverge from CE MDR standards for active implantable devices. |
| Hospital System Partnership | Teaching hospital pilot programmes for closed-loop DBS systems generate procurement precedence across NHS England. |
| Software Companion Development | Remote neurostimulation programming platforms reduce specialist clinic burden and expand rural patient access. |
| Reimbursement Strategy | NHS England MedTech Funding Mandate selectively accelerates procurement for pathway-efficient stroke and movement disorder technologies. |
| CE Marking Parallel Track | Dual certification maintenance preserves continental European market access while satisfying UKCA divergence requirements. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the United Kingdom neurology devices landscape, including neurointerventional radiologists, NHS foundation trust procurement directors, biomedical engineering leads, and MHRA regulatory affairs specialists. Secondary validation drew from NHS Supply Chain procurement databases, MHRA device registration filings, Care Quality Commission inspection reports, and hospital trust board papers. Bottom-up demand modeling triangulated against top-down market sizing from capital expenditure disclosures and service contract values.
Across the projection horizon, the analytical framework segmented volume and value outputs by product type, end user institution tier, delivery mode mobility class, and technology automation intensity. CAGRs were derived from installed base growth rates, replacement cycle frequencies, and NHS England procurement pipeline visibility. Forecast inputs incorporated neurointerventional radiologist training pipeline constraints, MHRA approval timeline divergences from EMA parallels, and MedTech Funding Mandate inclusion criteria evolution.
Decision-makers should treat outputs as directional under assumptions of stable NHS capital allocation and MHRA regulatory autonomy; material deviation in training pipeline expansion or transatlantic mutual recognition progress would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
India Neurology Devices Market
Neurology
Hydrocephalus Market
Neurology
Brain Aneurysm Treatment Market
Neurology
Argentina Neurology Devices Market
Neurology
Frontotemporal Disorders Treatment Market
Neurology
South Korea Neurology Devices Market
Neurology
North America Neurology Devices Market
Neurology
Idiopathic Intracranial Hypertension Therapeutics Market
Neurology
Ulnar Nerve Treatment Market
Neurology
Saudi Arabia Neurology Devices Market
Neurology
CNS Lymphoma Market
Neurology
Bell Palsy Treatment Market
Neurology
Multiple Sclerosis Treatment Market
Neurology
Cognitive Neuroscience Market
Neurology
Nerve Repair Market
Neurology
Brain Tumor Diagnosis and Treatments Market