
 Europe Lung Cancer Diagnostics Market | 2026-2036
Europe Lung Cancer Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Lung Cancer Diagnostics Market Foresight
Software-defined biomarker analysis is consolidating how lung cancer diagnostic platforms generate recurring revenue across European hospital networks. Thermo Fisher Scientific leverages its ion semiconductor sequencing architecture to anchor molecular diagnostic workflows in major oncology centers. Illumina Inc competes through next-generation sequencing panel standardization that extends reagent pull-through contracts. Qiagen differentiates with sample-to-insight automation that controls pre-analytical processing in high-throughput laboratories.
Lung cancer diagnostics encompasses tissue-based histopathology, circulating biomarker detection, and radiological imaging modalities employed to classify tumor subtype, stage disease progression, and guide targeted therapy selection. CT-guided transthoracic needle biopsy remains the gold standard for obtaining adequate tissue for EGFR, ALK, and PD-L1 testing, with specimen quality directly determining downstream molecular profiling success. Biomarker testing commands premium positioning due to companion diagnostic requirements for tyrosine kinase inhibitors and checkpoint inhibitors, while imaging tests retain volume leadership through screening program expansion. Molecular imaging via PET-CT with radiolabeled tracers represents the fastest-growing technology segment as European centers adopt theranostic pathways linking diagnostic localization to radionuclide therapy.
The European Medicines Agency (EMA) mandates companion diagnostic co-development for novel oncology approvals, while the In Vitro Diagnostic Regulation (IVDR) imposes stricter clinical evidence and post-market surveillance obligations on test manufacturers. EMA oncology designations and IVDR notified body capacity constraints collectively shape market access timelines and commercial launch sequencing across member states. Stakeholders must monitor IVDR transition deadlines and national reimbursement negotiations to align product registration investments with predictable revenue pathways.
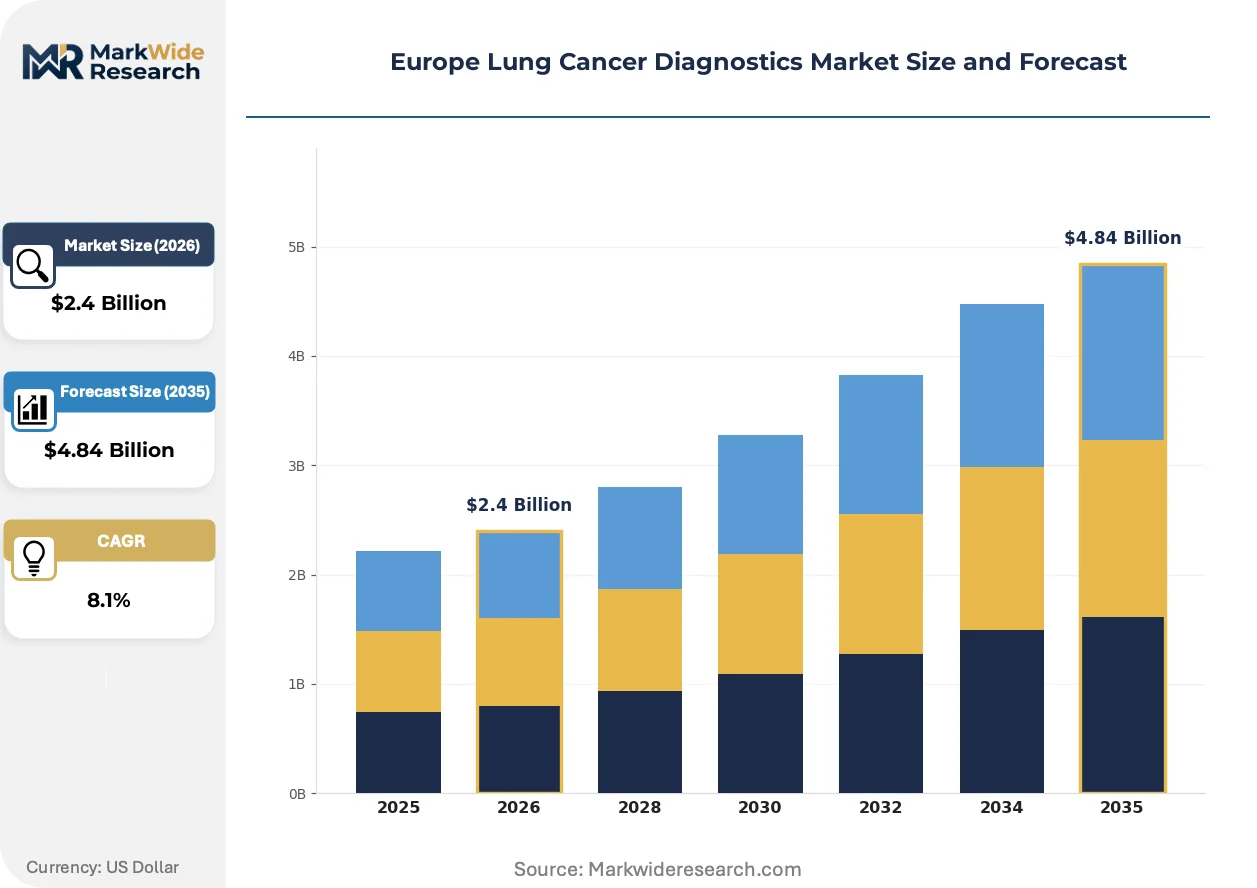
Market Dynamics
The EU In Vitro Diagnostic Regulation is compressing commercialization timelines for biomarker test developers while hospital procurement consolidation across Western Europe concentrates purchasing power into centralized reference laboratory networks.
Growth Catalysts
- Companion diagnostic mandates:EMA requirements for co-development with oncology therapeutics lock in testing demand alongside novel drug approvals, creating predictable revenue streams for molecular assay providers.
- Germany:Academic medical centers and university hospital networks drive centralized EGFR and PD-L1 testing volumes through integrated care pathways that standardize molecular profiling protocols.
- Liquid biopsy advancement:Cell-free DNA analysis from plasma samples is expanding reimbursable testing access where tissue acquisition fails, particularly in elderly patients with poor surgical candidacy.
Market Restraints
- IVDR notified body capacity:Limited certification infrastructure under the new regulation extends technical documentation review timelines to 18-24 months, delaying product launches.
- Reagent supply concentration:Dependence on single-source polymerase chain reaction master mixes from US suppliers exposes European laboratories to transatlantic shipping disruptions and customs processing delays.
- Histopathology workforce constraints:Pathologist shortages in France and Italy create specimen processing bottlenecks that limit molecular diagnostic throughput regardless of instrument capacity.
Strategic Opportunities
- Poland and Eastern Europe:Underdeveloped molecular diagnostic infrastructure presents first-mover advantages for automated NGS platform placement in emerging oncology centers.
- Theranostic pathway integration:PET-CT with radiolabeled tracers linking diagnostic localization to lutetium-177 therapy creates bundled reimbursement opportunities in radionuclide therapy centers.
- EU Green Deal procurement criteria:Sustainability requirements in public hospital tenders favor vendors with reduced plastic consumable footprints and energy-efficient sequencing chemistries.
Industry Challenges
- Bioinformatics specialist scarcity:Variant interpretation expertise for complex genomic signatures remains concentrated in Copenhagen, Heidelberg, and London, limiting decentralized test deployment.
- Laboratory information system integration:Legacy hospital IT architectures require expensive middleware development to connect new molecular platforms with electronic health record workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Lung Cancer Diagnostics Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.84 Billion |
| CAGR (2026 – 2036) | 8.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biopsy, Imaging Tests, Blood Tests, Biomarker Testing Technology: CT Scan, MRI, PET Scan, Molecular Imaging End User: Hospitals, Diagnostic Laboratories, Outpatient Clinics, Research Institutions Delivery Mode: Direct Mail, Point-of-Care, Online, In-Hospital |
| Companies Covered | F. Hoffmann-La Roche Ltd, Thermo Fisher Scientific, Illumina Inc, Agilent Technologies, Qiagen, Abbott Laboratories, bioMérieux, AstraZeneca plc, Siemens Healthineers AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Lung Cancer Diagnostics Market Shifts & Advancements
Automation architectures and regulatory data requirements are restructuring how diagnostic platforms capture value across European hospital procurement cycles, with three developments commanding strategic attention.
Next-generation sequencing panel design is modularizing around minimal gene sets required for reimbursement, with vendors stripping non-reimbursable biomarkers to reduce per-test costs. Medium-sized oncology centers in Spain and the Netherlands are adopting these slimmed panels at accelerated pace. This compression is fragmenting the market between comprehensive academic profiles and lean community hospital offerings.
EMA's tightened evidentiary standards for companion diagnostic claims are extending clinical validation study requirements, with post-market surveillance obligations now mandating real-world outcome tracking. Manufacturers must maintain patient registries linking test results to therapy response. High-complexity laboratories in Germany and Scandinavia are absorbing these compliance costs through integrated health system budgets.
Hospital procurement committees are consolidating molecular diagnostic contracts into multi-year sole-source agreements that bundle instruments, reagents, and bioinformatics support. France's hospital federation and England's NHS Supply Chain are driving this consolidation. The shift disadvantages smaller assay developers lacking capital to finance placement deals.
Europe Lung Cancer Diagnostics Market Segmentation
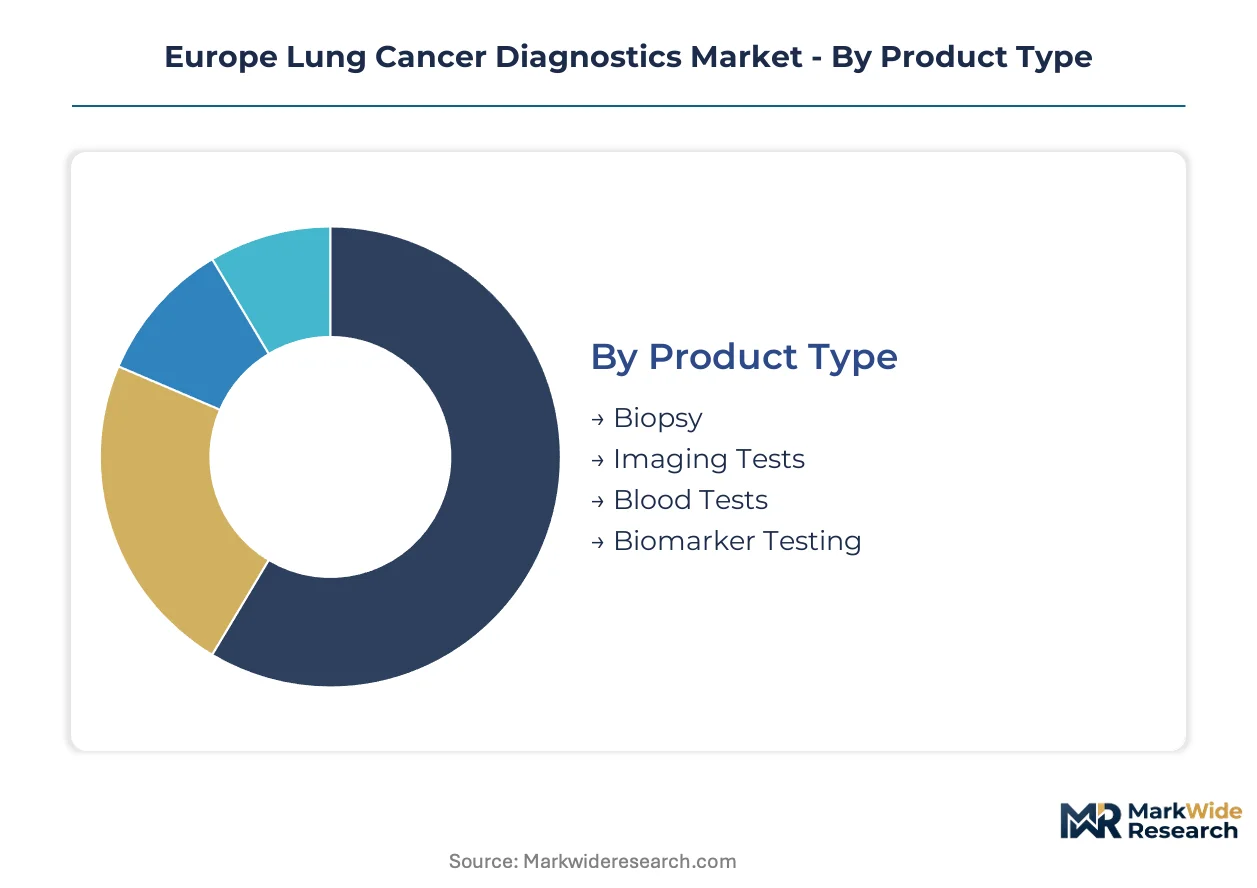
Segmentation in lung cancer diagnostics reveals how IVDR certification burdens and reimbursement pathways concentrate value capture across distinct product categories and delivery channels. Each segment carries differentiated regulatory timelines and capital requirements that shape competitive positioning.
Product Type:
IVDR Class C certification mandates apply unevenly across product types, with invasive tissue-based tests facing stricter clinical evidence requirements than non-invasive alternatives.
- Biopsy:CT-guided transthoracic needle biopsy extracts tissue specimens for histopathological examination and downstream molecular profiling. German academic medical centers and university hospital networks in Heidelberg and Munich drive centralized testing volumes through integrated care pathways that standardize specimen acquisition protocols.
- Biomarker Testing:Molecular assays detect EGFR, ALK, ROS1, and PD-L1 alterations to guide targeted therapy selection. EMA companion diagnostic mandates lock in testing demand alongside novel oncology drug approvals, creating predictable revenue streams for assay providers serving reference laboratory networks in France and Scandinavia.
- Imaging Tests:Radiological modalities stage disease progression and monitor treatment response across European hospital networks.
- Blood Tests:Liquid biopsy platforms analyze circulating tumor DNA from plasma samples where tissue acquisition fails.
Imaging Tests sits at the top of the volume ranking, with Biomarker Testing climbing the fastest.
Technology:
Capital intensity and consumable pull-through economics vary sharply across imaging modalities, with PET-CT systems requiring radionuclide production infrastructure that limits deployment to major oncology centers.
- PET Scan:Positron emission tomography with radiolabeled tracers enables metabolic characterization of pulmonary lesions and metastatic staging. Theranostic pathway integration linking diagnostic localization to lutetium-177 therapy creates bundled reimbursement opportunities in radionuclide therapy centers across Germany and Switzerland.
- Molecular Imaging:PET-CT with prostate-specific membrane antigen and somatostatin receptor ligands extends diagnostic utility into rare lung neuroendocrine subtypes. French and Belgian centers lead adoption of theranostic protocols that combine diagnostic tracer administration with subsequent radionuclide therapy.
- CT Scan:Computed tomography remains the workhorse modality for initial nodule detection and biopsy guidance.
- MRI:Magnetic resonance imaging provides soft-tissue contrast for superior sulcus tumors and brain metastasis evaluation.
CT Scan commands the highest installed base, while Molecular Imaging gains share fastest through theranostic integration.
End User:
Procurement consolidation across Western Europe concentrates purchasing power into centralized reference laboratory networks that favor multi-year sole-source agreements.
- Hospitals:Academic medical centers and university hospital networks in Germany, France, and England operate high-complexity molecular diagnostic laboratories with integrated pathology and oncology departments. NHS Supply Chain and France's hospital federation drive contract consolidation that bundles instruments, reagents, and bioinformatics support.
- Diagnostic Laboratories:Centralized reference networks in Bavaria, Lombardy, and the Netherlands process specimens from multiple hospital systems. IVDR notified body capacity constraints extend technical documentation review timelines, delaying product launches for smaller assay developers lacking capital to finance placement deals.
- Outpatient Clinics:Community oncology practices refer specimens to centralized laboratories for molecular profiling.
- Research Institutions:Translational research programs in Copenhagen, Heidelberg, and London concentrate bioinformatics expertise for complex genomic signature interpretation.
Hospitals dominate current spending, with Diagnostic Laboratories expanding most quickly through network consolidation.
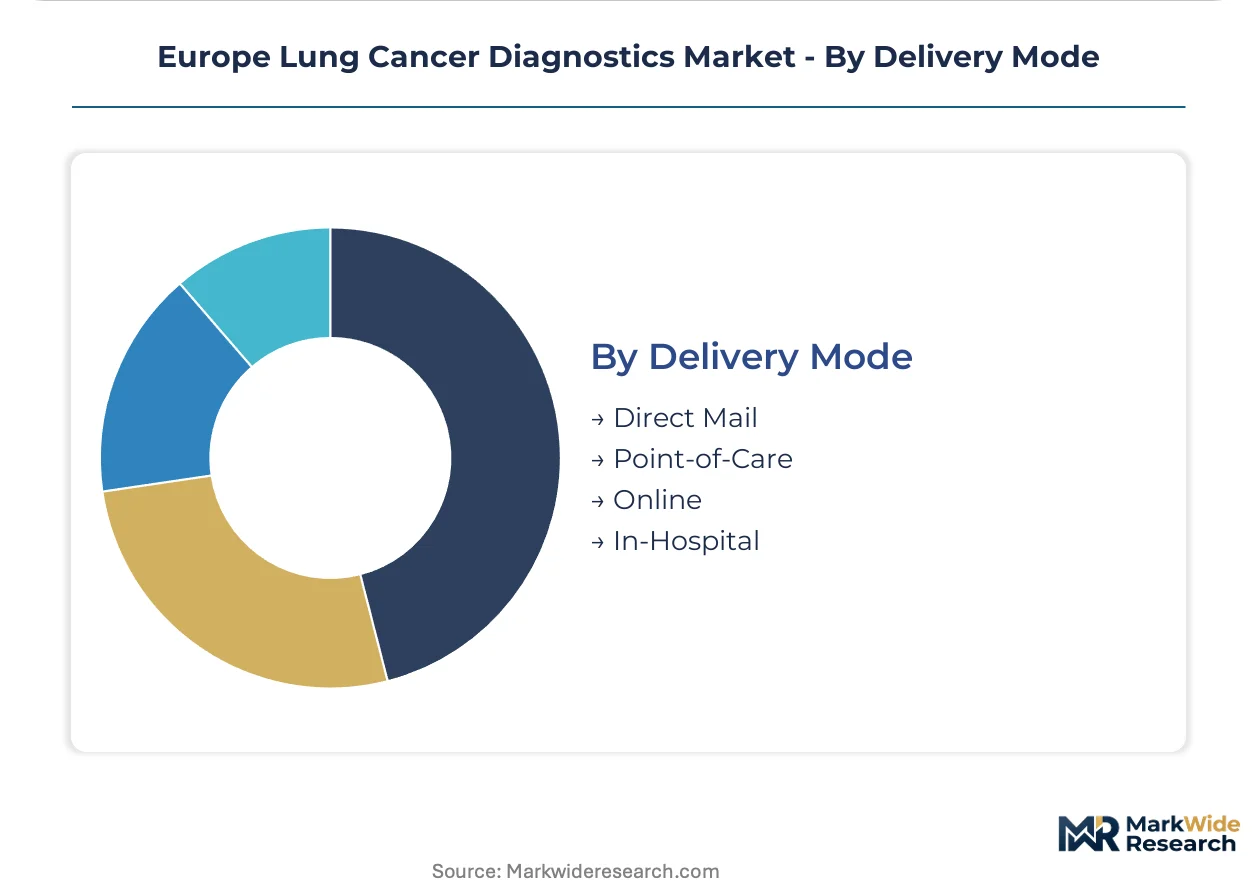
Delivery Mode:
Channel economics reflect specimen stability requirements and reimbursement pathway complexity, with direct hospital-based processing capturing premium positioning.
- In-Hospital:On-site molecular diagnostic programs within oncology centers control pre-analytical processing and reduce specimen transport degradation. Automated NGS platform placement in major European hospitals locks in reagent pull-through contracts through multi-year service agreements.
- Point-of-Care:Rapid molecular testing at community oncology sites expands access where centralized laboratory turnaround times delay therapy initiation. Poland and Eastern European markets present first-mover advantages for automated platform deployment in emerging oncology centers.
- Direct Mail:Specimen transport from peripheral hospitals to reference laboratories requires cold-chain logistics.
- Online:Digital pathology and remote consultation platforms support decentralized expert review.
In-Hospital retains the largest revenue share, with Point-of-Care demonstrating the steepest expansion trajectory through community clinic penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA companion diagnostic mandates and IVDR compliance cost differentials are redirecting molecular diagnostic platform investments toward jurisdictions with faster regulatory pathways and consolidated procurement channels. German reference laboratory networks and French hospital federations absorb certification delays through integrated health system budgets, while Eastern European markets attract first-mover automated platform placement.
Germany
Academic medical centers in Heidelberg and Munich drive centralized EGFR and PD-L1 testing volumes through standardized molecular profiling protocols. The country's hospital procurement consolidation under the Hospital Structures Act favors multi-year sole-source agreements bundling instruments, reagents, and bioinformatics support. Bavarian reference laboratory networks process specimens from multiple hospital systems across southern Germany.
France
ANSM post-market surveillance requirements align with IVDR clinical evidence obligations for biomarker test manufacturers. The hospital federation's national tendering framework concentrates purchasing power into centralized contracts that disadvantage smaller assay developers. Paris and Lyon oncology centers lead theranostic pathway adoption linking PET-CT diagnostic localization to lutetium-177 radionuclide therapy.
United Kingdom
NHS Supply Chain procurement consolidation bundles molecular diagnostic contracts across England's integrated care systems. NICE technology appraisals determine reimbursement eligibility for liquid biopsy platforms analyzing circulating tumor DNA. London and Cambridge bioinformatics clusters concentrate variant interpretation expertise for complex genomic signatures.
Netherlands
Dutch healthcare procurement laws mandate sustainability criteria under EU Green Deal implementation, favoring vendors with reduced plastic consumable footprints. University medical centers in Amsterdam and Rotterdam operate high-complexity molecular diagnostic laboratories with integrated pathology departments. The country's centralized health technology assessment process accelerates companion diagnostic reimbursement decisions.
Poland
Underdeveloped molecular diagnostic infrastructure in Warsaw and Kraków oncology centers presents first-mover advantages for automated NGS platform placement. The national health fund's emerging reimbursement pathways for liquid biopsy expand testing access where tissue acquisition fails. EU structural funds support laboratory modernization in emerging regional hospitals.
Europe Lung Cancer Diagnostics Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated purchasing power in Western European hospital networks favoring scale-driven incumbents over niche assay developers. The vendor base organizes around three archetypes: diversified life science conglomerates with reagent pull-through ecosystems, precision oncology pure-plays with companion diagnostic co-development capabilities, and imaging modality specialists integrating theranostic pathways. M&A activity concentrates on bioinformatics capabilities and automated sample-to-insight platforms, while strategic partnerships lock in multi-year service agreements with centralized reference laboratory networks.
Among diversified diagnostic conglomerates, F. Hoffmann-La Roche Ltd and Thermo Fisher Scientific exemplify the integrated reagent-instrument-bioinformatics archetype that dominates procurement committee evaluations. Illumina Inc occupies a distinct position anchoring next-generation sequencing standardization efforts across European oncology centers. These three entities collectively represent the scale threshold required to finance IVDR certification costs and placement deal structures that smaller competitors cannot match.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Thermo Fisher Scientific |
| Illumina Inc |
| Agilent Technologies |
| Qiagen |
| Abbott Laboratories |
| bioMérieux |
| AstraZeneca plc |
| Siemens Healthineers AG |
| Others |
Supply & Pricing Matrix
Reference laboratory networks in Germany and France concentrate purchasing power into multi-year sole-source agreements that compress price floors for molecular diagnostic platforms. IVDR certification costs and placement deal financing requirements lock smaller assay developers out of premium contracting tiers.
Pricing Analysis
Capacity additions in Eastern European oncology centers are reshaping price floors for automated NGS platforms as vendors compete for first-mover placement. Three-tier pricing structure across premium, standard, and economy levels separates IVDR-certified companion diagnostic assays from research-use-only panels and liquid biopsy alternatives. Pricing pressure stems from NHS Supply Chain and France's hospital federation bundling instruments, reagents, and bioinformatics into consolidated tenders. Community hospitals in Spain and the Netherlands exhibit highest price sensitivity, while German academic medical centers prioritize throughput and integration over per-test cost.
Supply Chain Analysis
Dual-sourcing requirements from European hospital procurement committees mandate qualified backup suppliers for PCR master mixes and sequencing reagents to mitigate transatlantic shipping disruptions. Manufacturing concentration in the United States, Germany, and China anchors consumable production for polymerase chain reaction and next-generation sequencing chemistries. Raw material dependencies include fluorophore-labeled oligonucleotides, semiconductor sequencing chips, and radionuclide precursors for PET-CT tracers. Single-source vulnerability for ion semiconductor sequencing consumables exposes laboratories to customs processing delays. Distribution runs through centralized reference laboratory networks in Bavaria, Lombardy, and the Netherlands that aggregate specimens from multiple hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European lung cancer diagnostics represents a late-cycle quality story where IVDR compliance burdens and companion diagnostic evidentiary standards favor scaled incumbents with integrated reagent-instrument-bioinformatics ecosystems. Demand is shifting toward premium specifications as EMA mandates tie novel oncology approvals to validated molecular profiling protocols.
For Market Incumbents: Anticipate consolidation pressure from NHS Supply Chain and France's hospital federation by deepening automated sample-to-insight platform penetration in German academic medical centers. Lock in multi-year reagent pull-through contracts before IVDR certification delays allow emerging competitors to capture Eastern European greenfield placements. Defend against liquid biopsy pure-plays by integrating cell-free DNA analysis into existing tissue-based workflow automation. For New Entrants and Emerging Players: IVDR notified body capacity constraints in Germany and France open a window for automated NGS platform placement in Poland and Czech Republic oncology centers where molecular diagnostic infrastructure remains underdeveloped. Target community hospital networks in Spain and the Netherlands adopting slimmed gene panels for reimbursable biomarker testing. Pursue theranostic pathway partnerships with radionuclide therapy centers in Switzerland and Belgium as a differentiated go-to-market angle. For Investors and Strategic Acquirers: Diversified life science conglomerates are the most active acquirer in this space, seeking bioinformatics capabilities and automated pre-analytical processing platforms to complete integrated diagnostic ecosystems. Long-term viability hinges on capturing recurring reagent revenue through instrument placement deals rather than one-time assay sales. Watch for IVDR transition deadline acceleration as the signal indicating regulatory capacity relief and compressed product launch timelines.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Certification Pathway | EMA companion diagnostic mandates lock in testing demand alongside novel drug approvals. |
| Hospital System Partnership | Bavarian reference laboratory networks aggregate specimens from multiple German hospital systems. |
| Software Companion Development | Integrated bioinformatics pipelines control variant interpretation in Copenhagen and Heidelberg clusters. |
| Reimbursement Strategy | NICE technology appraisals determine liquid biopsy eligibility across England's integrated care systems. |
| Geographic Expansion | EU structural funds support laboratory modernization in emerging Polish regional hospitals. |
Research Methodology
Multiple input streams — regulatory filing analysis, hospital procurement database review, and manufacturer technical documentation assessment — were reconciled against primary interviews with molecular diagnostic laboratory directors, IVDR notified body representatives, and hospital purchasing committee members. Secondary validation drew from EMA oncology designation records, IVDR technical documentation summaries, and national health technology assessment reports. Bottom-up instrument placement and reagent consumption estimates were triangulated against top-down market sizing from health system procurement disclosures.
Data-stream reconciliation across product type, technology platform, end-user channel, and delivery mode dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segmented volume and value trajectory modeling incorporating IVDR transition timeline assumptions, companion diagnostic approval pipeline density, and hospital procurement consolidation patterns. Forecast inputs included reference laboratory network expansion rates in Germany and France, liquid biopsy reimbursement pathway development in England and the Netherlands, and automated platform placement economics in Eastern European greenfield markets.
Revisions become necessary when IVDR notified body capacity constraints extend beyond modeled timelines or when EMA companion diagnostic evidentiary standards tighten further. Deviation in national reimbursement negotiations for liquid biopsy platforms would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
HIV/HBV/HCV Test Kits Market
Diagnostics
Sexually Transmitted Diseases Diagnostics Market
Diagnostics
Asia-Pacific Antinuclear Antibody Test Market
Diagnostics
Global Non-Small Cell Lung Cancer Diagnostics Market
Diagnostics
Global Oral Cancer Rapid Test Kit Market
Diagnostics
US in Vitro Diagnostics Market
Diagnostics
Global Comprehensive Metabolic Panel Market
Diagnostics
Global Yersiniosis Diagnostics and Treatment Market
Diagnostics
China in Vitro Diagnostics Market
Diagnostics
North America Breast Cancer Screening Tests Market
Diagnostics
India in-Vitro Diagnostics Market
Diagnostics
GCC in-Vitro Diagnostic Devices Market
Diagnostics
Syndromic Multiplex Diagnostic Market
Diagnostics
Global Chlamydia Infection Diagnostics Market
Diagnostics
Body Fluid Collection and Diagnostics Market
Diagnostics
Global Serological Testing Market