
 Asia-Pacific Antinuclear Antibody Test Market | 2026-2036
Asia-Pacific Antinuclear Antibody Test Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Antinuclear Antibody Test Market Analytics
Recombinant antigen substrates are shifting the cost structure of ANA test manufacturing away from traditional HEp-2 cell preparations. Thermo Fisher Scientific leverages its immunoassay portfolio to anchor high-throughput screening workflows across Japanese reference laboratories. Bio-Rad Laboratories specializes in quality control materials that sustain standardization across indirect immunofluorescence protocols. Abbott Laboratories competes through point-of-care testing platforms that extend diagnostic access into outpatient rheumatology clinics.
Antinuclear antibody testing detects autoantibodies directed against cellular nuclear components using indirect immunofluorescence on HEp-2 cell substrates, enzyme-linked immunosorbent assay, or line immunoassay formats, with titers reported at serum dilutions from 1:40 to 1:5120 to quantify antibody concentration for autoimmune disease screening and monitoring. The immunoassay technology segment dominates current volume owing to established automation infrastructure, while molecular diagnostics represents the fastest-expanding category as multiplexed nucleic acid detection converges with serological screening in integrated autoimmune workups. Diagnostic laboratories command the largest end-user margin pool due to centralized batch processing economics, though hospital-based point-of-care testing is capturing incremental share through reduced turnaround time for urgent rheumatology consultations.
Japan's PMDA enforces stringent analytical validation standards for in-vitro diagnostic reagents under the revised Pharmaceutical and Medical Device Act, elevating compliance costs for market entrants while reinforcing incumbent kit manufacturers. India's CDSCO mandates import licensing and local clinical performance data for foreign-sourced ANA assays, creating structural barriers that favor domestic assembly partnerships or regional manufacturing investments. China's NMPA accelerates innovative diagnostic approvals through priority review channels for autoimmune disease panels, reshaping product registration timelines for multinational suppliers. Stakeholders must monitor evolving convergence between immunoassay and molecular platform technologies as laboratory consolidation across Australia, South Korea, and Southeast Asia redefines procurement criteria toward integrated system contracts rather than discrete reagent purchasing.
Market Dynamics
Diagnostic laboratories across Asia-Pacific are consolidating procurement around integrated immunoassay platforms, compressing vendor margins while elevating analytical validation standards that favor incumbent kit manufacturers with established regulatory dossiers.
Growth Catalysts
- Automated HEp-2 substrate production:Recombinant antigen manufacturing is displacing manual cell culture workflows, reducing batch-to-batch variability for high-throughput screening in Chinese tier-one hospital networks.
- PMDA's streamlined priority review:Japan's revised Pharmaceutical and Medical Device Act accelerates approval timelines for multiplexed autoimmune panels, incentivizing kit manufacturers to submit expanded indication claims.
- Rheumatology clinic expansion:South Korea's national health insurance reimbursement for systemic lupus erythematosus screening is extending diagnostic access beyond tertiary referral centers into provincial hospital systems.
Market Restraints
- Import licensing friction:India's CDSCO mandates local clinical performance data for foreign-sourced ANA assays, creating structural barriers that delay market entry by 18-24 months for non-domestic suppliers.
- Fluorophore supply concentration:Specialist dye chemistries for indirect immunofluorescence remain concentrated among European and Japanese chemical suppliers, exposing kit manufacturers to input cost volatility and currency risk.
- Technician skill scarcity:Pattern interpretation for HEp-2 cell staining requires specialized cytology training that remains underdeveloped in Southeast Asian diagnostic workforces, constraining test quality standardization.
Strategic Opportunities
- Point-of-care platform penetration:Outpatient rheumatology clinics in Australian metropolitan centers present underexploited demand for rapid ANA screening with same-day result turnaround.
- Molecular-immunoassay convergence:Multiplexed nucleic acid detection is expanding into serological screening workflows, enabling integrated autoimmune workups that reduce reflex testing costs.
- Domestic assembly partnerships:CDSCO's local manufacturing incentives create white space for foreign kit manufacturers to establish regional production facilities serving Indian and Bangladeshi hospital networks.
Industry Challenges
- Inter-platform standardization gaps:Discordance between indirect immunofluorescence titers and enzyme-linked immunosorbent assay quantitative outputs complicates longitudinal patient monitoring across laboratory networks.
- Reference material scarcity:Certified control sera for autoimmune antibody quantification remain limited to single-source suppliers, constraining quality assurance program scalability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Antinuclear Antibody Test Market |
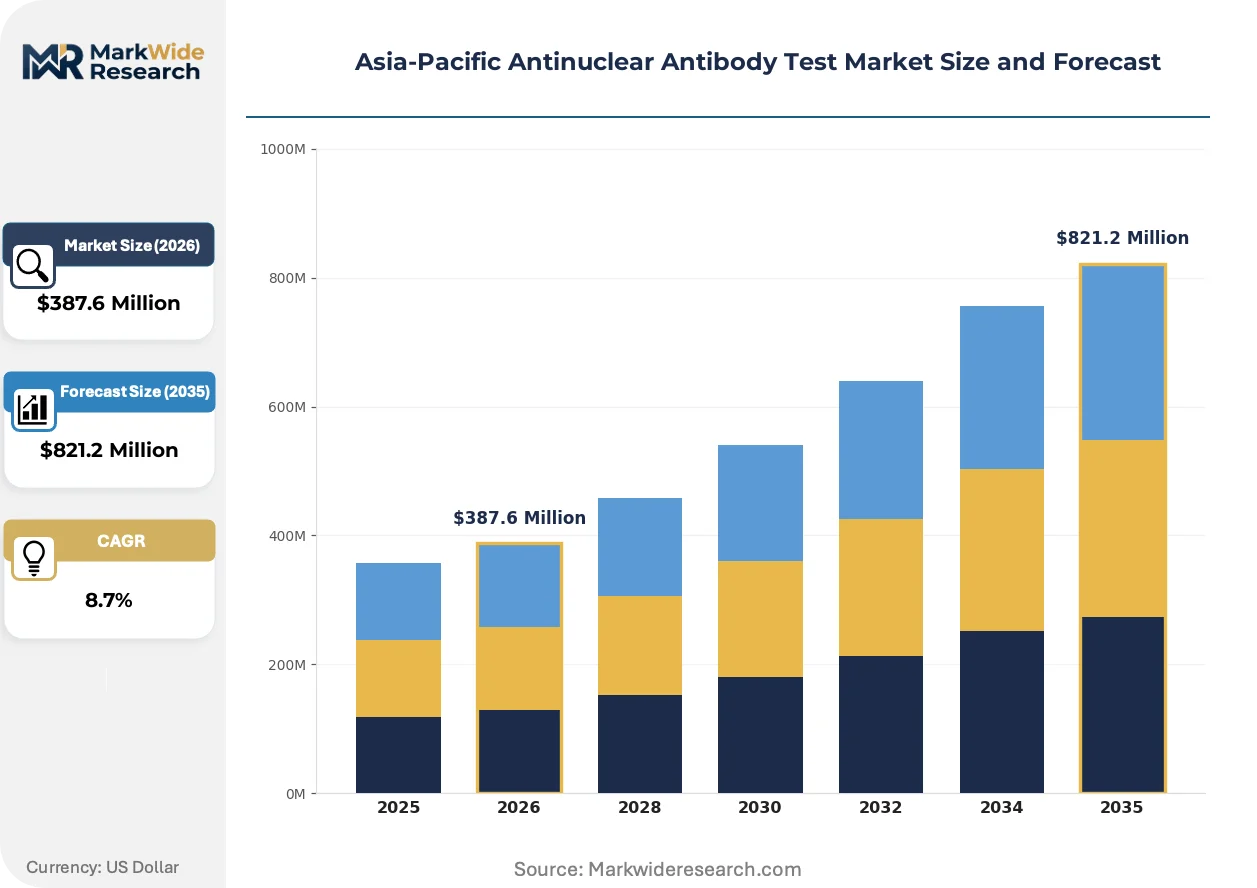
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: ELISA, Indirect Immunofluorescence, Line Immunoassays, Supplementary Tests End User: Diagnostic Laboratories, Hospitals, Research Institutions, Clinics Application: Autoimmune Disorders, Rheumatic Diseases, Infectious Diseases, Cancer Technology: Immunoassays, Molecular Diagnostics, Point-of-Care Testing, High-Throughput Screening |
| Companies Covered | Thermo Fisher Scientific, Abbott Laboratories, Bio-Rad Laboratories, Roche Diagnostics, Euroimmun Medizinische Labordiagnostika AG, Trinity Biotech, Inova Diagnostics, Siemens Healthineers, Fujirebio, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Antinuclear Antibody Test Market Evolving Landscape
Recombinant substrate engineering and regulatory pathway convergence are compressing product development cycles while reshaping how laboratories validate and deploy autoimmune screening technologies across heterogeneous healthcare systems.
Multiplexed line immunoassay formats are expanding into high-volume screening workflows by enabling simultaneous detection of multiple autoantibody specificities on a single test strip. Japanese reference laboratories are adopting these platforms at accelerated pace to reduce technologist interpretation burden. The technology is expanding into cost-sensitive hospital segments previously served by manual indirect immunofluorescence protocols.
China's NMPA has established priority review channels for innovative diagnostic panels targeting autoimmune disease differentiation, compressing registration timelines from 24 months to 12 months for qualifying submissions. This regulatory acceleration is redirecting multinational product development resources toward indication expansion rather than geographic line extensions. Domestic Chinese manufacturers are responding by accelerating multiplexed assay development to capture priority review benefits before multinational competitors adapt.
Laboratory procurement committees are consolidating reagent purchasing around integrated system contracts that bundle instrumentation, consumables, and service agreements into multi-year commitments. Distributor networks across South Korea and Australia are restructuring commission structures to favor total contract value over discrete reagent margins. This behavioral shift is most visible in Southeast Asian hospital group purchasing organizations that now require vendor participation in centralized tender processes rather than site-by-site negotiations.
Asia-Pacific Antinuclear Antibody Test Market Segmentation
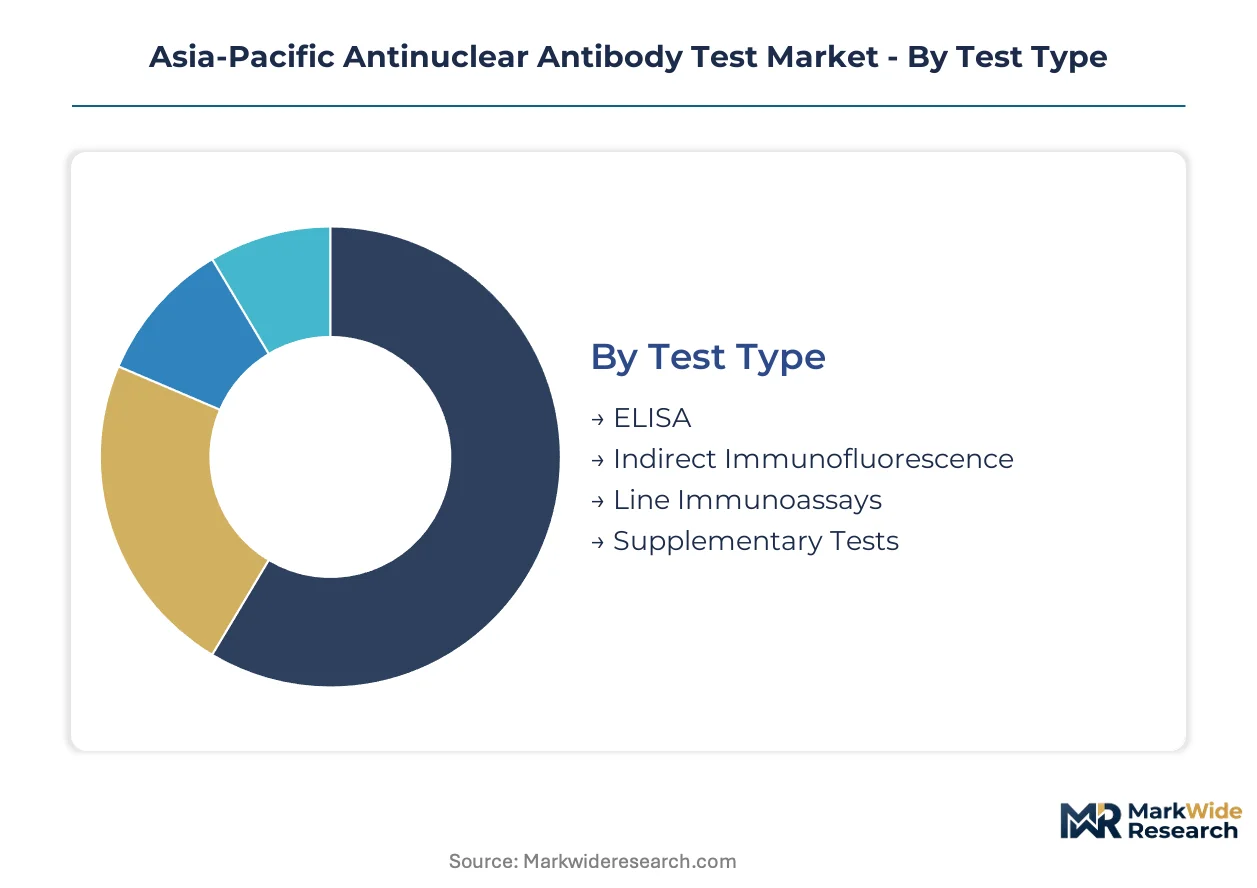
Segmentation in the Asia-Pacific antinuclear antibody test market reveals distinct procurement patterns across technology platforms and care settings. Laboratory infrastructure maturity and regulatory pathway complexity determine where specific test formats gain commercial traction.
Test Type:
Technical specification and automation readiness separate high-volume screening formats from specialized confirmatory assays.
- Indirect Immunofluorescence:HEp-2 cell-based detection remains the clinical reference standard for antinuclear antibody pattern classification. Japanese reference laboratories and South Korean hospital networks anchor demand for standardized substrate preparations that reduce inter-observer interpretation variance.
- ELISA:Enzyme-linked immunosorbent assay formats deliver quantitative antibody titers through automated microplate processing. China's tier-one hospital procurement committees favor ELISA platforms for their integration with existing immunoassay infrastructure and reduced technician training requirements.
- Line Immunoassays:Multiplexed strip formats enable simultaneous detection of multiple autoantibody specificities in a single workflow. These platforms are expanding into cost-sensitive hospital segments across Southeast Asia.
- Supplementary Tests:Confirmatory assays including immunoblot and immunodiffusion methods address reflex testing requirements. Demand concentrates in tertiary referral centers managing complex autoimmune differential diagnoses.
Indirect immunofluorescence leads on scale; line immunoassays lead on momentum.
End User:
Procurement authority and batch processing economics determine margin capture across the care continuum.
- Diagnostic Laboratories:Centralized reference laboratories command the largest reagent volume through multi-year system contracts. Australia's primary pathology networks and South Korea's commercial laboratory chains leverage consolidated purchasing power to compress per-test costs.
- Hospitals:Inpatient and emergency rheumatology departments require rapid turnaround for acute autoimmune presentations. China's provincial hospital systems are expanding automated screening capacity to reduce external send-out dependency.
- Research Institutions:Academic medical centers and translational research programs drive demand for novel biomarker discovery panels. These end-users prioritize analytical sensitivity over throughput metrics.
- Clinics:Outpatient rheumatology and primary care settings present underpenetrated demand for point-of-care screening formats. Australian metropolitan clinics are piloting rapid ANA testing to enable same-day consultation completion.
Diagnostic laboratories dominate current procurement value; clinics represent the steepest expansion trajectory.
Application:
Disease prevalence and reimbursement alignment shape test volume allocation across clinical indications.
- Autoimmune Disorders:Systemic lupus erythematosus and mixed connective tissue disease screening constitute the primary clinical utility for ANA testing. South Korea's national health insurance expansion for SLE screening is extending diagnostic access into provincial hospital networks.
- Rheumatic Diseases:Rheumatoid arthritis and Sjögren's syndrome monitoring drives repeat testing volume in established patient cohorts. Japanese rheumatology societies have published updated ANA interpretation guidelines that standardize clinical action thresholds.
- Infectious Diseases:Viral-induced autoantibody detection addresses post-infectious autoimmune sequelae. This application remains concentrated in research and tertiary referral settings.
- Cancer:Paraneoplastic syndrome screening represents an emerging indication with limited current reimbursement coverage. Clinical validation studies are ongoing across Chinese oncology centers.
Autoimmune disorders anchor current test volume; rheumatic diseases are gaining share fastest through monitoring protocols.
Technology:
Platform integration capabilities and regulatory validation status determine laboratory adoption sequencing.
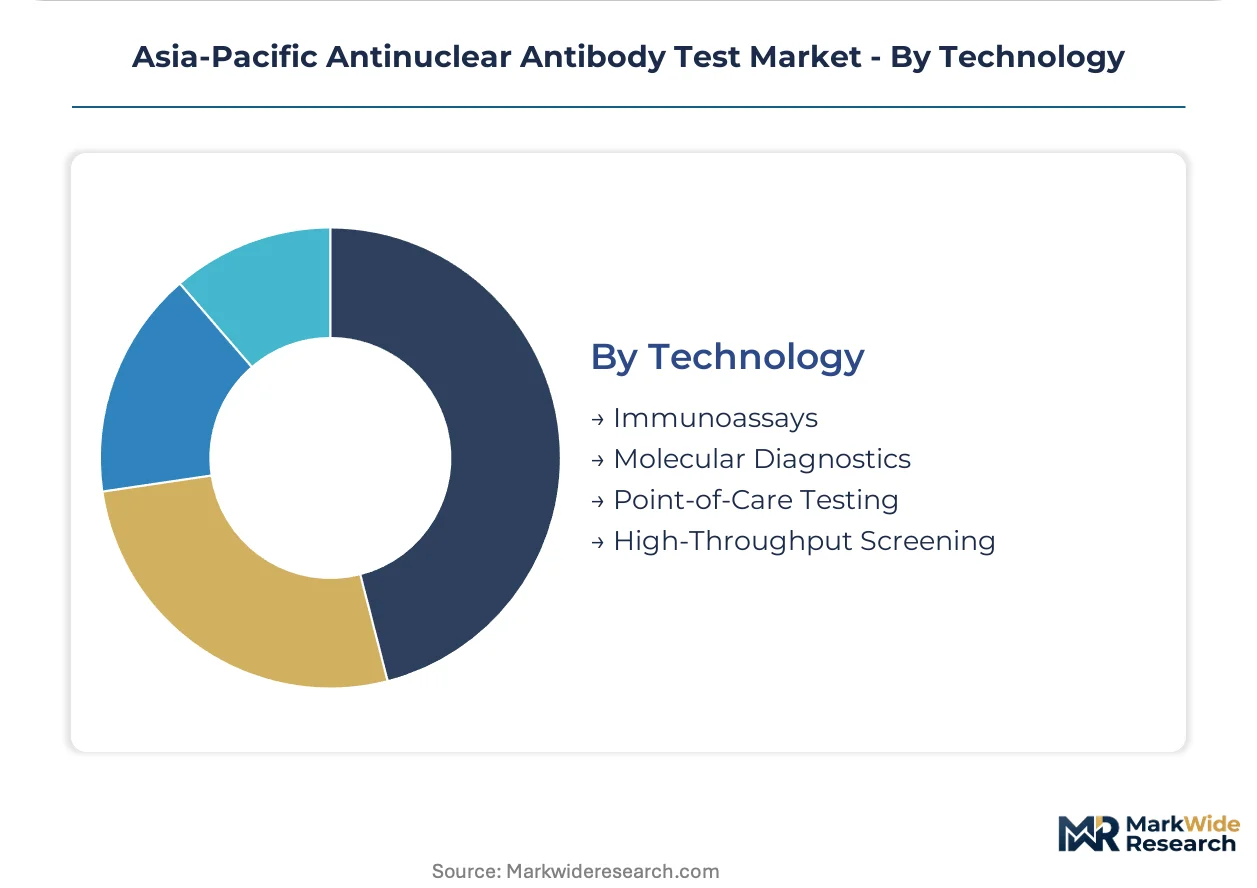
- Immunoassays:Established chemiluminescence and enzyme immunoassay platforms dominate installed base across Asia-Pacific reference laboratories. These technologies benefit from extensive automation infrastructure and standardized quality control programs.
- Molecular Diagnostics:Multiplexed nucleic acid detection is converging with serological screening in integrated autoimmune workups. China's NMPA priority review channels are accelerating approval timelines for molecular-immunoassay hybrid platforms.
- Point-of-Care Testing:Rapid cartridge-based formats enable decentralized screening in outpatient settings. PMDA's streamlined device approval pathways are reducing time-to-market for Japanese point-of-care ANA assays.
- High-Throughput Screening:Automated sample processing systems address population-scale screening requirements in China's national health initiatives. These installations require substantial capital commitment and long-term service contracts.
Immunoassays maintain installed base leadership; molecular diagnostics shows the strongest technology momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's tier-one hospital networks anchor procurement volume for automated immunoassay platforms, while regulatory acceleration across Tokyo, Seoul, and Mumbai reshapes competitive entry dynamics for kit manufacturers.
China
Beijing-Tianjin-Hebei hospital clusters drive demand for high-throughput screening systems as provincial health bureaus expand SLE screening coverage. NMPA's priority review channels compress autoimmune panel approvals from 24 months to 12 months. Yangtze River Delta reference laboratories are consolidating procurement around integrated system contracts that bundle instrumentation with multi-year service agreements.
Japan
Kansai region reference laboratories anchor demand for standardized HEp-2 substrate preparations that reduce interpretation variance across technologist shifts. PMDA enforces stringent analytical validation standards under the revised Pharmaceutical and Medical Device Act. Tokyo metropolitan rheumatology clinics are piloting point-of-care cartridge formats to enable same-day consultation completion.
India
Maharashtra's tertiary referral centers generate concentrated demand for confirmatory immunoblot assays in complex autoimmune differentials. CDSCO mandates import licensing and local clinical performance data for foreign-sourced ANA assays. Gujarat-based diagnostic chains are establishing domestic assembly partnerships to circumvent 18-24 month entry delays for non-domestic suppliers.
South Korea
Seoul Capital Area commercial laboratory chains leverage consolidated purchasing power to compress per-test reagent costs through multi-year vendor commitments. National health insurance reimbursement expansion for SLE screening extends diagnostic access into provincial hospital systems. Busan-Ulsan reference networks are adopting multiplexed line immunoassay platforms to reduce technologist interpretation burden.
Australia
New South Wales primary pathology networks command the largest reagent volume through centralized procurement committees that favor total contract value over discrete margins. TGA maintains alignment with international standards for in-vitro diagnostic validation. Victorian metropolitan rheumatology clinics present underexploited demand for rapid ANA screening with reduced turnaround times.
Asia-Pacific Antinuclear Antibody Test Market Competitive Landscape
Global majors compete with regional champions across regulatory dossier depth and automation platform integration, creating a tiered structure where incumbents with established validation histories capture premium pricing. The vendor base separates into three archetypes: diversified life science conglomerates with immunoassay portfolios, specialized autoimmune diagnostics firms with pattern interpretation expertise, and regional manufacturers leveraging domestic regulatory pathways. Consolidation pressure is accelerating through laboratory procurement centralization and multi-year system contract bundling.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Abbott Laboratories exemplify scale-driven positioning through automated platform dominance. Bio-Rad Laboratories occupies a specialist position anchored in quality control materials and standardization protocols. These three entities collectively represent the competitive tension between throughput-optimized instrumentation and interpretive accuracy requirements that defines procurement criteria across Asia-Pacific reference networks.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Abbott Laboratories |
| Bio-Rad Laboratories |
| Roche Diagnostics |
| Euroimmun Medizinische Labordiagnostika AG |
| Trinity Biotech |
| Inova Diagnostics |
| Siemens Healthineers |
| Fujirebio |
| Others |
Value Network & Pricing Analysis
Regulatory certification tiers bifurcate the Asia-Pacific ANA test market into premium validated kits and economy-grade alternatives, with PMDA-compliant Japanese substrates commanding threefold margins over CDSCO-registered Indian assemblies while supply chains reorganize around these quality thresholds.
Pricing Analysis
Fluorophore and recombinant antigen input costs pass through to kit manufacturers with 6-9 month lag structures, compressing margins on economy-grade ELISA formats while premium HEp-2 cell substrates absorb volatility through long-term service contracts. Three-tier pricing structure across premium, standard, and economy levels aligns with NMPA priority review status, PMDA analytical validation tier, and CDSCO import licensing requirements respectively. Pricing pressure stems from Chinese tier-one hospital procurement committees consolidating around integrated system contracts. Diagnostic laboratories exhibit highest price sensitivity; reference laboratories with captive validation programs show lowest.
Supply Chain Analysis
Specialist dye logistics and cold-chain freight costs from European and Japanese chemical suppliers add 12-18% landed cost premiums for Southeast Asian kit assemblers. Manufacturing concentrates in China for high-throughput screening systems, Japan for standardized HEp-2 substrates, and India for domestic assembly partnerships. Raw material dependencies include fluorescent dye chemistries, recombinant antigen substrates, and certified control sera. Single-source vulnerability concentrates in European fluorophore suppliers. Distribution runs through distributor networks restructuring toward total contract value commission models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific ANA test market compounds steadily as autoimmune disease screening expands into national health insurance coverage across South Korea and provincial Chinese hospital networks.
For Market Incumbents: Extend pattern interpretation software capabilities to defend against molecular diagnostics convergence, while deepening backward integration into recombinant antigen production to secure substrate supply against European dye supplier concentration. Anchor multi-year system contracts with Australian and South Korean laboratory chains before procurement centralization completes. For New Entrants and Emerging Players: The price-point gap between PMDA-validated Japanese kits and CDSCO-registered Indian alternatives creates entry space for mid-tier manufacturers offering NMPA priority review status at 40-60% discount to premium incumbents. Target China's provincial hospital systems expanding automated screening capacity. Pursue domestic assembly partnerships in Gujarat to circumvent CDSCO import licensing delays. For Investors and Strategic Acquirers: Consolidation pressure builds where laboratory procurement centralization eliminates site-by-site vendor relationships. The market reads as a 5-10 year compounder anchored by irreversible autoimmune disease prevalence growth. Target acquisition archetype: regional manufacturers with established regulatory dossiers in India or Southeast Asia lacking automation platform integration. Watch NMPA priority review queue depth as inflection signal for competitive intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Recombinant Antigen Manufacturing Scale-Up | Reduces batch-to-batch variability for Chinese tier-one hospital networks. |
| NMPA Priority Review Pathway Navigation | Compresses autoimmune panel approvals from 24 months to 12 months. |
| Point-of-Care Platform Development | Captures Australian metropolitan clinic demand for same-day turnaround. |
| Domestic Assembly Partnership Formation | Circumvents CDSCO 18-24 month entry delays in Indian market. |
| Integrated System Contract Bundling | Aligns with South Korean laboratory chain procurement centralization. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with diagnostic laboratory directors, rheumatology clinic administrators, biomedical procurement managers, and regulatory affairs specialists at kit manufacturers with secondary validation against NMPA and PMDA filing databases, hospital procurement contract registries, and national health insurance reimbursement schedules. Bottom-up test volume modeling triangulated against top-down market sizing across immunoassay, molecular diagnostics, and point-of-care technology platforms.
Segment-weighting approaches distributed value and volume across test type, end user, application, and technology dimensions, with regional coefficients applied for China, Japan, India, South Korea, and Australia. CAGRs derived from regression analysis of historical autoimmune disease prevalence, laboratory automation adoption curves, and regulatory approval velocity. Forecast inputs included PMDA analytical validation standard evolution and CDSCO import licensing procedural timelines.
The model assumes a particular technology adoption path; alternative pathways for molecular-immunoassay hybrid platforms would alter the outlook if NMPA accelerates approval timelines beyond current priority review channels. Forecasts reflect assumptions about regulatory pathway stability and laboratory consolidation velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
North America Autoimmune Disease Diagnostics Market
Diagnostics
IVD Antibody Market
Diagnostics
Middle East and Africa in-Vitro Diagnostics Market
Diagnostics
Treponema Pallidum Tests Market
Diagnostics
Diabetes Testing System Market
Diagnostics
North America Molecular Diagnostics Market
Diagnostics
Global Yersinia Diagnostics Market
Diagnostics
Global Women's Health Diagnostics Market
Diagnostics
Paper Based Diagnostic Test Kits Market
Diagnostics
Asia-Pacific Syndromic Multiplex Diagnostic Market
Diagnostics
Biochips Based in-Vitro Diagnostics Market
Diagnostics
Global Hemoglobin A1c Testing Devices Market
Diagnostics
Alanine Aminotransferase Reagent Market
Diagnostics
Global Autoimmune Disease Diagnostics Market
Diagnostics
Professional Diagnostics Market
Diagnostics
Cancer Tissue Diagnostics Market