
 Syndromic Multiplex Diagnostic Market | 2026-2036
Syndromic Multiplex Diagnostic Market Size, Share, and Industry Trends Forecast 2026-2036
Syndromic Multiplex Diagnostic Market Analytics
Hospital procurement channels are rewriting how syndromic multiplex diagnostic platforms reach end users. Becton, Dickinson and Company leverages direct institutional contracts to sustain placement momentum in high-throughput laboratories. Danaher (Cepheid) anchors its position through integrated cartridge-instrument systems that lock in consumable pull-through. Abbott Laboratories differentiates via compact point-of-care architectures that extend testing beyond centralized labs.
Syndromic multiplex diagnostics simultaneously detect multiple pathogens or biomarkers from a single patient sample using nucleic acid amplification, hybridization, or sequencing-based detection chemistries, with typical panels covering viral, bacterial, and fungal targets in under two hours to guide clinical decision-making. Reagents capture the dominant margin pool due to recurring consumption tied to installed instrument bases, while PCR technology leads in commercial penetration though NGS-based approaches are gaining traction in research institutions for expanded pathogen discovery. Point-of-care facilities represent the fastest-growing end-user channel as decentralized testing architectures reduce turnaround time for infectious disease applications.
FDA premarket notification pathways and EMA CE-IVD frameworks shape product development timelines and market access requirements for multiplex assay developers. NMPA registration in China adds a distinct compliance layer that manufacturers must navigate for commercial entry. Stakeholders should monitor evolving reimbursement codes for multiplex panels as payer coverage decisions will determine adoption velocity across hospital and outpatient settings.
Market Dynamics
Hospital laboratory consolidation is compressing procurement timelines for syndromic multiplex platforms, forcing manufacturers to restructure go-to-market strategies around integrated system contracts rather than standalone instrument sales.
Growth Catalysts
- Reimbursement code expansion:CMS and private payers in the United States are establishing dedicated billing codes for multiplex respiratory panels, removing prior authorization friction that previously delayed adoption.
- Antimicrobial stewardship mandates:Joint Commission accreditation requirements now compel hospitals to deploy rapid pathogen identification technologies to optimize antibiotic prescribing decisions.
- Cartridge-based automation:Closed-system chemistries are reducing hands-on time requirements, enabling laboratory directors to reallocate technical staff toward higher-complexity testing workflows.
Market Restraints
- Polymerase supply concentration:Thermostable DNA polymerase production clusters in a handful of contract manufacturers, exposing assay producers to input bottlenecks during demand surges.
- CE-IVD technical documentation burden:EMA's expanded performance evaluation requirements for multiplex claims are extending time-to-market for European launches by twelve to eighteen months.
- Culture-based confirmation protocols:Many hospital infection control committees still require traditional microbiological confirmation before acting on multiplex results, limiting clinical utility.
Strategic Opportunities
- Outpatient surgery center penetration:Ambulatory surgical facilities in Germany remain underpenetrated for pre-operative infectious disease screening, presenting a greenfield installation base.
- Sequencing-NGS convergence:Hybrid platforms combining real-time PCR with targeted next-generation sequencing are opening expanded pathogen discovery applications in academic medical centers.
- China NMPA fast-track pathway:The agency's priority review designation for infectious disease diagnostics is compressing regulatory timelines for manufacturers willing to localize clinical trials.
Industry Challenges
- Bioinformatics specialist scarcity:Multiplex panel interpretation requires computational biology expertise that hospital laboratories struggle to recruit and retain at competitive compensation levels.
- LIS integration complexity:Middleware connectivity with legacy laboratory information systems demands customized HL7 interface development, inflating implementation costs and extending project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Syndromic Multiplex Diagnostic Market |
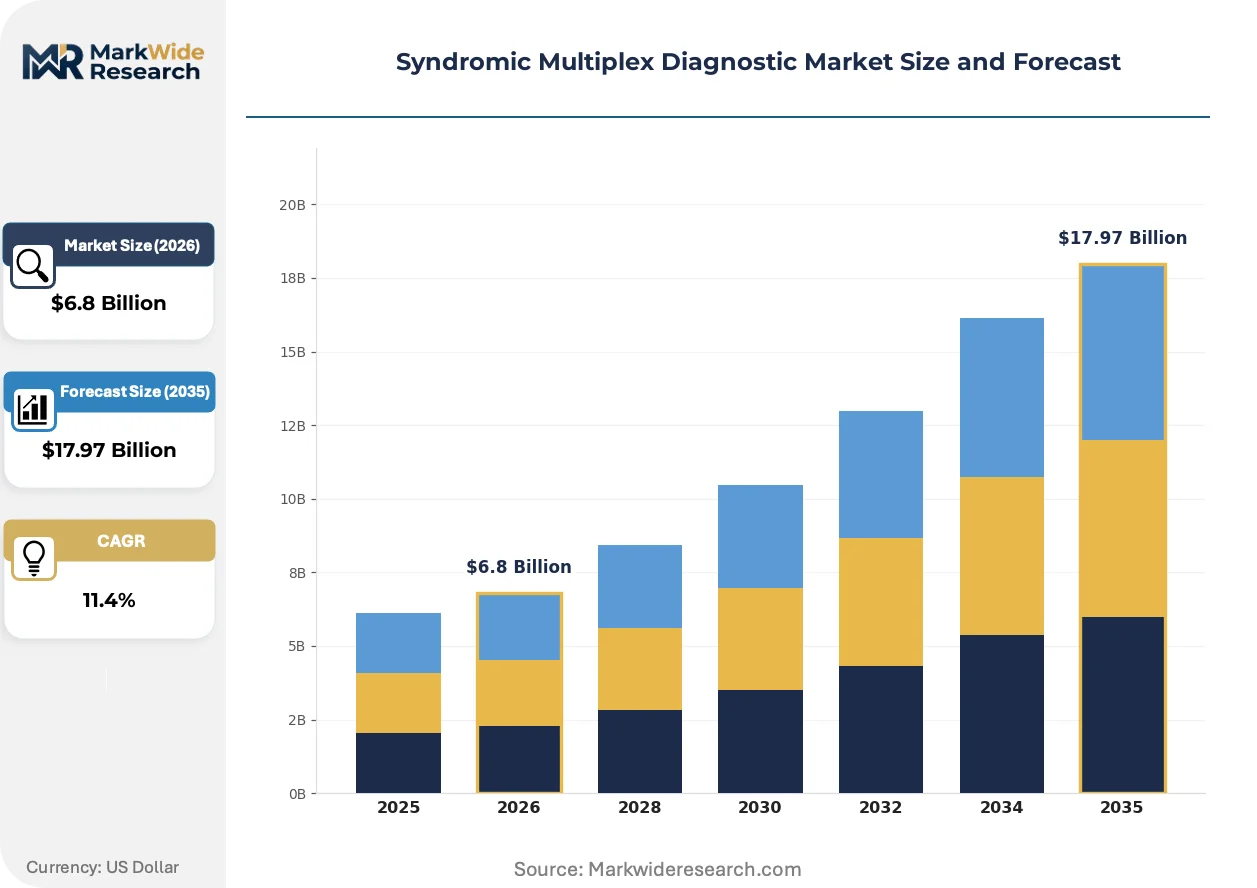
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Consumables, Software End User: Hospitals, Clinical Laboratories, Research Institutions, Point-of-Care Facilities Technology: PCR, Microarray, NGS, Mass Spectrometry Application: Infectious Diseases, Genetic Disorders, Cancer, Autoimmune Disorders |
| Companies Covered | Becton, Dickinson and Company, Danaher (Cepheid), Abbott Laboratories, Qiagen, DiaSorin S.p.A, bioMérieux, Thermo Fisher Scientific, Inc., Siemens Healthineers, F. Hoffmann-La Roche Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Syndromic Multiplex Diagnostic Market Evolving Landscape
Digital PCR chemistries are rewriting sensitivity benchmarks for syndromic detection, while cloud-based result interpretation tools are extending platform utility beyond raw pathogen identification toward clinical decision support.
Sample-to-answer automation is collapsing the distinction between centralized laboratory and near-patient testing architectures. Hospital systems in the United States are deploying these integrated workstations in satellite laboratories closer to emergency departments, compressing turnaround time from hours to minutes without sacrificing menu breadth. This capability expansion is enabling infectious disease specialists to initiate targeted therapy during the initial patient encounter.
EMA's In Vitro Diagnostic Medical Devices Regulation is forcing manufacturers to revalidate existing CE-marked assays under stricter clinical evidence standards. The transition deadline pressures smaller developers to either absorb substantial regulatory consulting costs or exit the European market entirely. Multiplex respiratory panel producers with established notified body relationships are capturing shelf space as competitors delay relaunch timelines.
Direct-to-hospital contracting is displacing traditional distribution intermediaries for high-volume multiplex platform placements. Integrated delivery networks in the United States are consolidating purchasing authority at the system level, negotiating enterprise-wide pricing agreements that bundle instruments, consumables, and service contracts. This concentration rewards manufacturers with scalable manufacturing footprints and penalizes niche players dependent on regional distributor relationships.
Syndromic Multiplex Diagnostic Market Segmentation
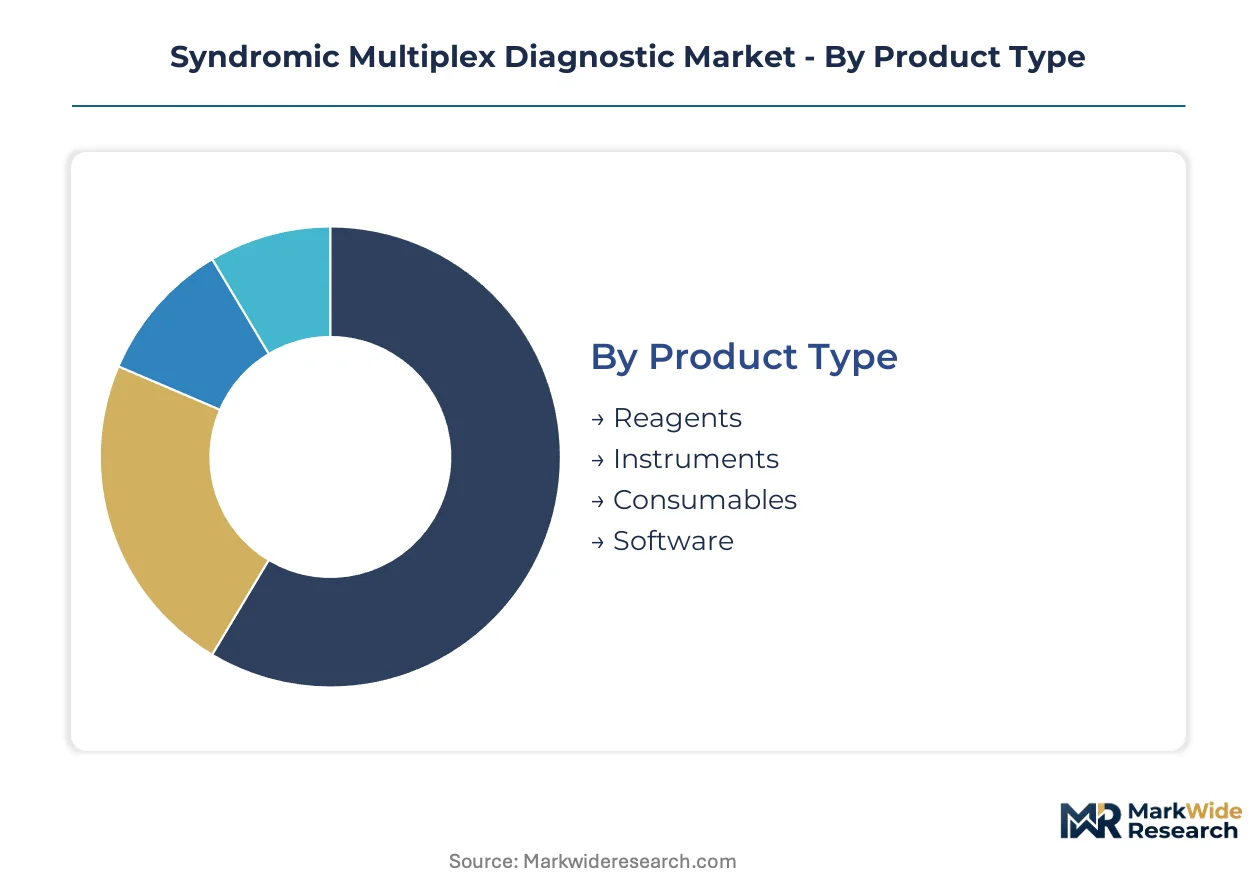
Segmentation in syndromic multiplex diagnostics reveals divergent margin structures and procurement patterns across product categories. Manufacturers optimize portfolio mix based on recurring revenue potential versus capital equipment cycles.
Product Type:
Cost tier differentiation separates consumable-dependent revenue streams from capital-intensive instrument placements.
- Reagents:Enzyme mixes, primers, and probe chemistries constitute the recurring consumable layer tied to installed instrument bases. Hospital laboratories in the United States generate concentrated pull-through as integrated delivery networks negotiate multi-year reagent supply contracts.
- Instruments:Thermal cyclers, hybridization stations, and sample-to-answer workstations represent the capital equipment foundation. Procurement committees in Germany prioritize CE-IVD certified platforms with validated LIS connectivity over unvalidated research-use-only alternatives.
- Consumables:Cartridges, microfluidic chips, and single-use reaction vessels enable closed-system workflows. These items capture standard pricing in high-throughput clinical laboratories.
- Software:Bioinformatics pipelines and cloud-based interpretation modules extend platform utility toward clinical decision support. Research institutions in China adopt these tools for expanded pathogen discovery applications.
Reagents command the established base. The steepest expansion runs through software modules.
End User:
Customer type determines throughput requirements and regulatory compliance thresholds.
- Hospitals:Acute care facilities deploy multiplex panels in microbiology laboratories to guide antimicrobial stewardship decisions. FDA-cleared respiratory panels anchor procurement budgets in United States health systems.
- Clinical Laboratories:Independent reference laboratories process high sample volumes across regional networks. These facilities in Germany emphasize automated sample-to-answer systems to reduce technical staffing costs.
- Research Institutions:Academic medical centers utilize expanded pathogen discovery panels for epidemiological surveillance. NGS-based approaches gain traction in these settings for untargeted detection capabilities.
- Point-of-Care Facilities:Emergency departments and urgent care clinics prioritize sub-one-hour turnaround times. Compact cartridge-based systems are climbing the fastest in this channel as decentralized architectures reduce time-to-treatment.
Hospitals retain the volume anchor. Point-of-Care Facilities are expanding most quickly.
Technology:
Maturity curves separate established amplification methods from emerging detection chemistries.
- PCR:Real-time and digital PCR chemistries deliver quantitative pathogen detection with established regulatory pathways. Commercial penetration concentrates in hospital laboratories seeking FDA 510(k) cleared respiratory panels.
- Microarray:Solid-phase hybridization enables medium-plex detection of viral and bacterial targets. Research institutions in China adopt these platforms for cost-effective screening of defined pathogen menus.
- NGS:Targeted next-generation sequencing expands detection scope beyond predefined panels. Academic medical centers leverage hybrid PCR-NGS workflows for novel pathogen identification.
- Mass Spectrometry:MALDI-TOF and PCR-electrospray ionization methods provide orthogonal confirmation of multiplex results. Clinical laboratories integrate these systems for culture-free species identification.
PCR holds the installed base anchor. NGS is gaining share fastest.
Application:
Disease area focus shapes panel design priorities and reimbursement eligibility.
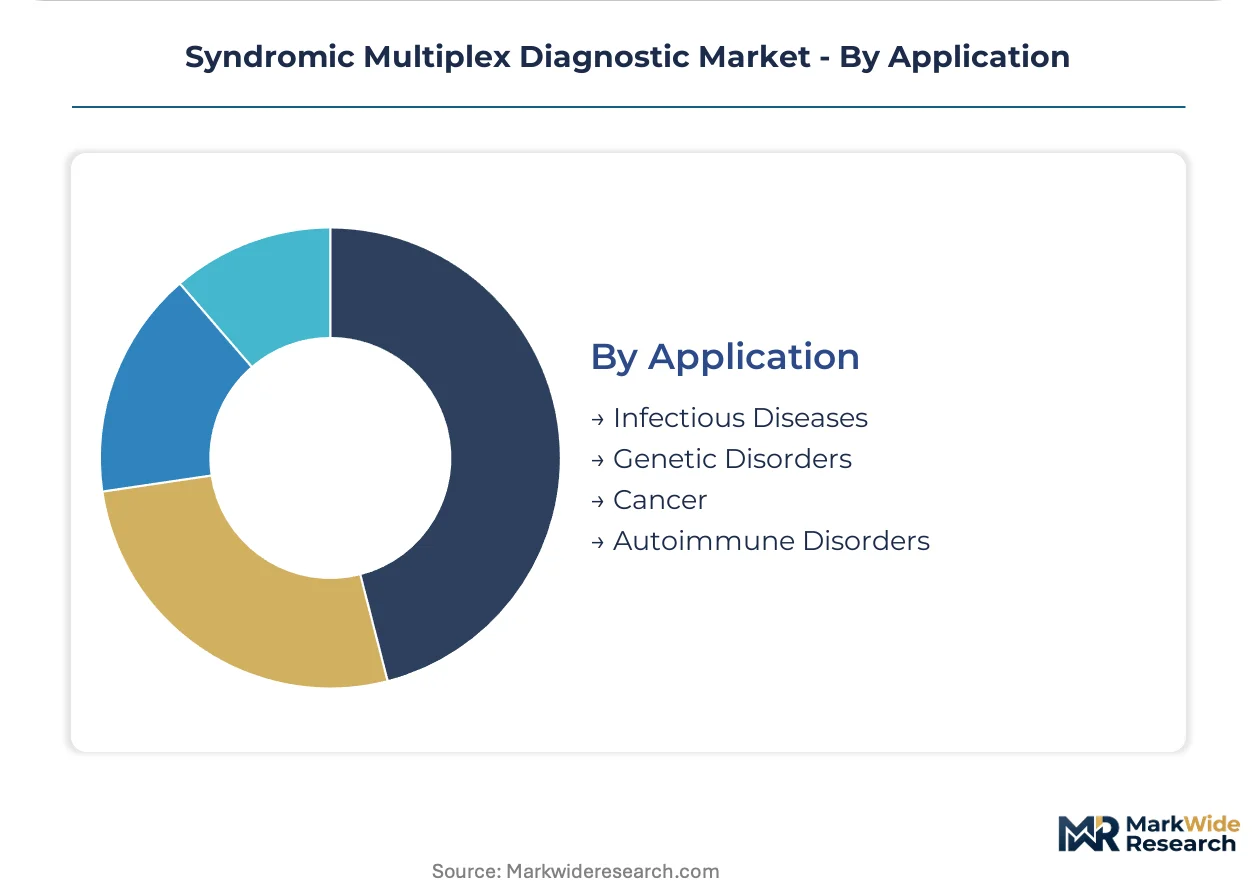
- Infectious Diseases:Respiratory, bloodstream, and gastrointestinal panels dominate commercial activity. CMS-established billing codes in the United States remove prior authorization barriers for multiplex respiratory testing.
- Genetic Disorders:Carrier screening and newborn diagnostic applications utilize expanded multiplex panels. Clinical laboratories process these samples under CAP proficiency testing requirements.
- Cancer:Liquid biopsy and minimal residual disease monitoring employ multiplex mutation detection. Research institutions develop oncology panels for precision therapy selection.
- Autoimmune Disorders:Cytokine and autoantibody multiplexing supports differential diagnosis. These applications remain concentrated in specialized reference laboratories.
Infectious Diseases anchors current revenue. Cancer applications show the steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam anchors European diagnostic logistics, while the Shanghai Yangshan deep-water port enables Chinese manufacturers to import precision reagents at scale. These infrastructure nodes underpin regional distribution networks for syndromic multiplex platforms.
United States
Integrated delivery networks in Texas and Florida are consolidating laboratory procurement authority at the system level. FDA's 510(k) premarket notification pathway shapes product development timelines for respiratory panel developers. The Boston-Cambridge cluster concentrates NGS-based assay innovation as academic medical centers deploy hybrid PCR-sequencing workflows.
Germany
Hospital laboratory consolidation across Bavaria and North Rhine-Westphalia is compressing procurement timelines for automated sample-to-answer systems. EMA's In Vitro Diagnostic Medical Devices Regulation forces manufacturers to revalidate existing CE-marked assays under stricter clinical evidence standards. The Rhine-Main metropolitan region anchors reference laboratory capacity for multiplex respiratory testing.
China
Domestic instrument manufacturers in the Yangtze River Delta are localizing thermal cycler production to reduce import dependency. NMPA's priority review designation for infectious disease diagnostics compresses regulatory timelines for manufacturers willing to conduct localized clinical trials. Shenzhen's biotech corridor concentrates cartridge-based platform development for point-of-care deployment.
Japan
Academic medical centers in Tokyo and Osaka are adopting expanded pathogen discovery panels for antimicrobial stewardship programs. PMDA's streamlined review pathway for infectious disease diagnostics accelerates market entry for multiplex respiratory assays. The Kansai region hosts specialized reference laboratories processing high-complexity syndromic testing.
United Kingdom
NHS England's centralized procurement frameworks are reshaping how syndromic platforms reach hospital laboratories. MHRA's post-Brexit regulatory autonomy enables tailored approval pathways for CE-IVD transitioning products. The Cambridge-Oxford-London golden triangle concentrates molecular diagnostic R&D for respiratory panel expansion.
Syndromic Multiplex Diagnostic Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in reagent and enzyme supply. The vendor base concentrates around multinational conglomerates with diversified life sciences portfolios, while mid-scale developers occupy niche application segments. Three archetypes dominate: integrated diagnostic conglomerates with cartridge-instrument lock-in strategies; point-of-care specialists with compact workflow architectures; and research-use panel providers expanding toward clinical validation. Competitive moves center on direct-to-hospital contracting displacement of traditional distribution, and regulatory consulting investments to navigate EMA MDR transition deadlines.
Among integrated system providers, Becton, Dickinson and Company and Danaher (Cepheid) exemplify the platform-anchored archetype with recurring consumable revenue models. Abbott Laboratories occupies a distinct position in near-patient testing architectures. These three entities represent contrasting geographic and application positioning within the consolidated top tier.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Danaher (Cepheid) |
| Abbott Laboratories |
| Qiagen |
| DiaSorin S.p.A |
| bioMérieux |
| Thermo Fisher Scientific, Inc. |
| Siemens Healthineers |
| F. Hoffmann-La Roche Ltd |
| Others |
Value Network & Pricing Analysis
The Port of Rotterdam's intermodal freight corridors transmit cost volatility from concentrated polymerase manufacturing through to downstream cartridge pricing, enabling integrated diagnostic conglomerates to enforce volume-discount tiering while regional distributors absorb margin compression from legacy inventory positions.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations between integrated delivery networks and platform manufacturers. Three-tier pricing separates FDA-cleared respiratory panels from CE-IVD certified systems and research-use-only alternatives, with certification grade and annual test volume as the primary differentiation levers. Cost compression in the standard tier is intensifying because hospital consolidation demands enterprise-wide pricing concessions. Independent reference laboratories exhibit the highest price sensitivity, while academic medical centers prioritize menu breadth over per-test economics.
Supply Chain Analysis
Thermostable DNA polymerase feedstock production draws from contract manufacturing clusters in the United States, Germany, and China, with enzyme mixes, primers, and probe chemistries as the critical input dependencies. Single-source vulnerability concentrates in specialized oligonucleotide synthesis capacity, exposing assay producers to allocation constraints during respiratory season demand surges. Distribution runs through direct-to-hospital contracting channels that displace traditional medical device distributors for high-throughput platform placements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent diagnostic platform manufacturers face sustained substitution pressure from sequencing-NGS convergence, requiring defensive repositioning to protect installed base revenues against hybrid workflow displacement.
For Market Incumbents: Entrench cartridge-instrument lock-in through multi-year consumable supply contracts that penalize switching costs. Accelerate backward integration into thermostable polymerase production to neutralize input bottlenecks during demand surges. Counter the sequencing-NGS threat by embedding targeted next-generation sequencing modules within existing PCR workstation architectures.
For New Entrants and Emerging Players: Build out software companion modules that extend platform utility toward clinical decision support, targeting the bioinformatics interpretation gap that hospital laboratories struggle to staff internally. Prioritize NMPA fast-track pathway submissions for infectious disease panels, leveraging China's compressed regulatory timelines against entrenched competitors delayed by EMA MDR revalidation requirements.
For Investors and Strategic Acquirers: Point-of-care specialists with compact cartridge-based architectures represent the most attractive acquisition target archetype, given their exposure to the fastest-growing end-user channel and limited regulatory consulting capacity to navigate EMA transition deadlines independently. Monitor NMPA priority review designation awards as the inflection signal indicating which domestic Chinese manufacturers are securing accelerated market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | CMS billing code expansion removes prior authorization friction for respiratory panel adoption. |
| CE Marking Pathway | EMA MDR revalidation requirements extend time-to-market for European launches by notified body bottlenecks. |
| Hospital System Partnership | Integrated delivery network contracting consolidates purchasing authority at enterprise level for volume leverage. |
| Software Companion Development | Cloud-based interpretation modules address bioinformatics specialist scarcity in hospital laboratory staffing. |
| Backward Integration | In-house polymerase production neutralizes supply concentration risk from contract manufacturing clusters. |
Research Methodology
Desk research of FDA 510(k) premarket notification databases, EMA CE-IVD technical documentation filings, and CMS reimbursement code determinations preceded structured interviews with hospital laboratory directors, GPO contracts managers, biomedical engineers, and regulatory affairs leads at multiplex assay developers. Secondary validation drew from hospital procurement databases, GPO contract repositories, and instrument placement tracking services. Bottom-up test volume estimates by facility type and top-down market sizing by manufacturer revenue were triangulated to constrain forecast variance.
Assumptions regarding regulatory pathway timelines, reimbursement coverage expansion velocity, and antimicrobial stewardship mandate enforcement intensity were held fixed across baseline scenarios while polymerase supply elasticity and hospital consolidation pace were varied in sensitivity testing. Segmentation dimensions modeled included product type tier, end-user channel, detection technology maturity curve, and infectious disease application area. CAGRs were derived from logistic diffusion curves fitted to historical instrument placement trajectories and consumable pull-through ratios.
Stress conditions across FDA review backlog duration, EMA notified body capacity constraints, and NMPA clinical trial localization requirements were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions regarding regulatory throughput and payer behavior. Material shifts in CMS reimbursement code coverage decisions or EMA MDR enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Canada in-Vitro Diagnostics Market
Diagnostics
Asia-Pacific Molecular Diagnostics Market
Diagnostics
Diabetes Testing System Market
Diagnostics
Vibrio Diagnostics Market
Diagnostics
Animal Diagnostics Market
Diagnostics
Animal Auto-Immune Disease Diagnostics Market
Diagnostics
Diagnostic Reagents Market
Diagnostics
In-Vitro Diagnostics (IVD) Packaging Market
Diagnostics
In Vitro Diagnostic Substrate Market
Diagnostics
Viral Disease Diagnosis Market
Diagnostics
Blood Grouping Reagents Market
Diagnostics
Middle East and Africa Lung Cancer Diagnostics Market
Diagnostics
Infectious Disease Point-Of-Care (POC) Diagnostics Market
Diagnostics
Melanoma Cancer Diagnostics Market
Diagnostics
Prenatal Diagnostics Market
Diagnostics
Global Serological Testing Market