
 Global Serological Testing Market | 2026-2036
Global Serological Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Serological Testing Market Foresight
Aftermarket service revenue is fragmenting across instrument calibration contracts, reagent supply agreements, and remote diagnostic platforms. Abbott Laboratories leverages its installed base of automated analyzers to sustain recurring consumable sales. Roche Diagnostics anchors its position through integrated workflow solutions that span pre-analytical to post-analytical stages. Thermo Fisher Scientific competes by extending its channel control into research-use-only reagents that bridge clinical and pharmaceutical endpoints.
Serological testing encompasses laboratory methods that detect antibodies, antigens, or other immune markers in blood serum, typically employing enzyme-linked immunosorbent assay (ELISA) protocols with sensitivity thresholds reaching picogram-per-milliliter concentrations for precise pathogen exposure confirmation. These assays serve primary commercial purposes in infectious disease surveillance, transfusion safety verification, and autoimmune condition characterization across healthcare systems. The product type landscape reveals chemiluminescence immunoassays capturing premium margin pools through higher throughput and lower detection limits, while rapid test kits occupy expanding point-of-care deployment channels where turnaround time supersedes analytical sensitivity. Application segmentation shows infectious disease detection retaining volume leadership, though autoimmune disorder diagnosis represents the fastest-growing category as rheumatology panels broaden.
The FDA's Quality System Regulation and Clinical Laboratory Improvement Amendments shape test kit commercialization pathways and laboratory accreditation requirements in the United States, while the EMA's In Vitro Diagnostic Regulation (IVDR) in Europe imposes stricter performance evaluation and post-market surveillance obligations on manufacturers seeking CE marking. Japan's PMDA enforces pharmaceutical and medical device Act standards that govern importation and clinical evidence thresholds for serological platforms. Stakeholders must monitor evolving IVDR transition timelines and PMDA harmonization efforts to align product development investments with shifting compliance burdens across major commercial jurisdictions.
Market Dynamics
The IVDR transition timeline is compressing commercialization windows for serological test manufacturers, forcing simultaneous compliance investments across multiple jurisdictions while diagnostic laboratories accelerate platform consolidation to secure supply continuity.
Growth Catalysts
- CLIA-waived rapid test expansion:The FDA's Clinical Laboratory Improvement Amendments waiver pathway enables point-of-care deployment in physician offices and urgent care clinics, bypassing centralized laboratory bottlenecks for infectious disease screening.
- Autoimmune panel proliferation:Rheumatology practices are adopting expanded antibody profiling for early lupus and rheumatoid arthritis detection, driving reagent consumption in specialty reference laboratories.
- Transfusion safety mandates:Blood banking facilities in Germany and Japan enforce nucleic acid testing supplementation with serological confirmation protocols, sustaining dual-methodology demand for donor screening programs.
Market Restraints
- Reagent supply concentration:Chemiluminescence immunoassay substrates depend on single-source suppliers in Switzerland and South Korea, creating vulnerability to geopolitical trade restrictions.
- IVDR performance evaluation costs:The European Medicines Agency's expanded clinical evidence requirements for Class C and D devices impose documentation burdens exceeding prior CE marking expenditures by substantial multiples.
- Point-of-care sensitivity gaps:Lateral flow serological assays fail to match ELISA detection thresholds for early infection windows, limiting deployment in high-acuity diagnostic settings.
Strategic Opportunities
- India's CDSCO streamlined pathways:The national pharmaceutical regulator's phased manufacturing incentives for in vitro diagnostics attract contract manufacturing investment for export-oriented reagent production.
- Multiplexed antigen-antibody convergence:Simultaneous detection platforms combining serological markers with molecular targets enable single-sample infectious disease characterization, reducing laboratory workflow steps.
- Home-based self-collection channels:Direct-to-consumer fingerstick sampling with mail-back laboratory processing circumvents clinic capacity constraints in United States metropolitan markets.
Industry Challenges
- IVDR technical documentation expertise:Manufacturers face scarcity of regulatory affairs specialists capable of compiling performance evaluation reports meeting EMA's common specifications for serological assays.
- Legacy analyzer integration friction:Pre-analytical automation systems from prior instrument generations require middleware customization to interface with cloud-based result reporting platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Serological Testing Market |
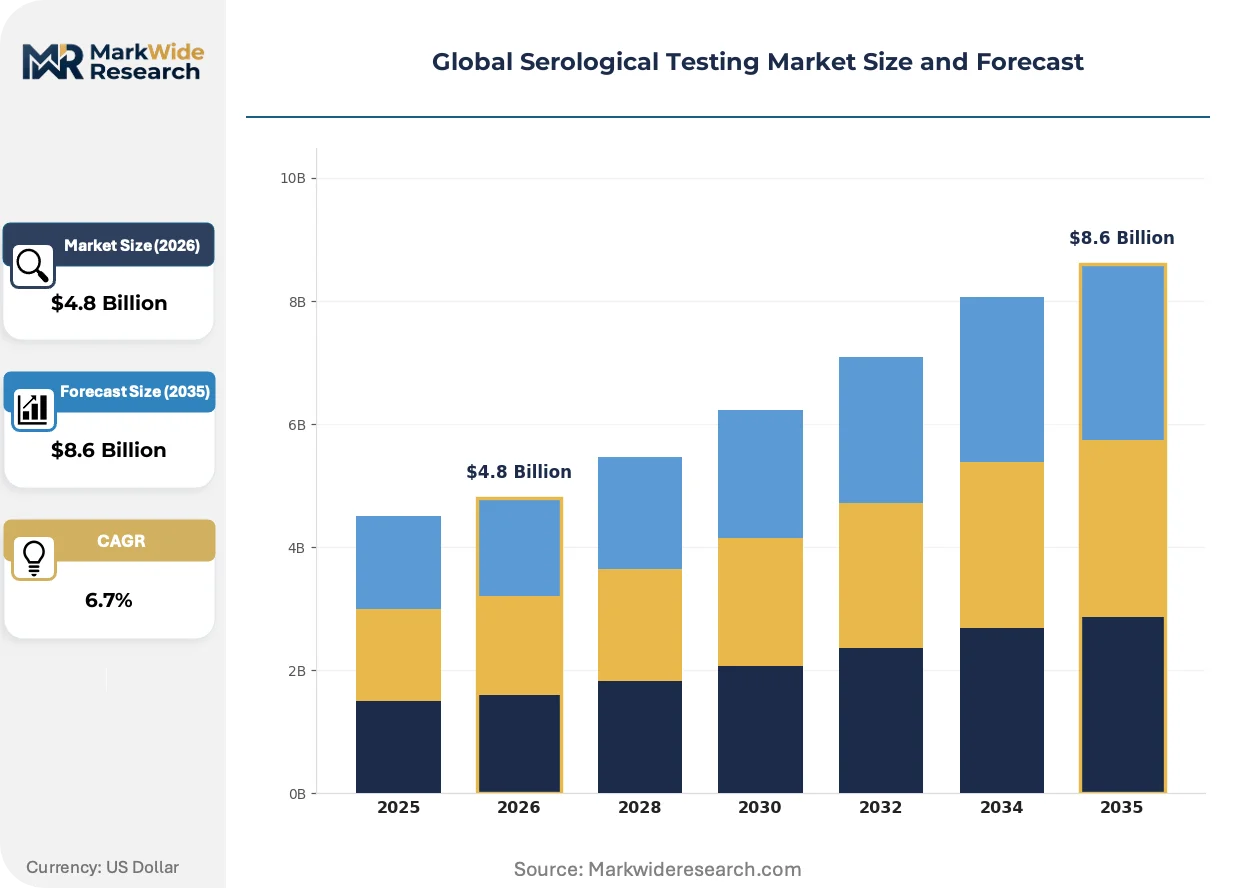
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rapid Test Kits, ELISA Kits, Western Blot, Immunofluorescence Assays, Chemiluminescence Immunoassays Application: Infectious Disease Detection, Blood Screening, Autoimmune Disorder Diagnosis, Allergy Testing, Vaccine Development End User: Diagnostic Laboratories, Blood Banks, Research Institutes, Point-of-Care Centers, Pharmaceutical Companies Deployment: Hospital Laboratories, Independent Laboratories, Mobile Testing Units, Community Health Centers, Academic Institutions |
| Companies Covered | Abbott Laboratories, Roche Diagnostics, Thermo Fisher Scientific, Becton Dickinson, Eurofins Scientific, Randox Laboratories, ELITechGroup, Bio-Rad Laboratories, Chembio Diagnostics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Serological Testing Market Shifts & Advancements
Serological testing platforms are converging with digital health infrastructure, creating data-rich diagnostic workflows that extend beyond analytical output to encompass predictive risk stratification and population surveillance capabilities.
Multiplexed bead-based immunoassays are hybridizing flow cytometry detection with traditional ELISA workflows, enabling simultaneous quantification of dozens of antibodies from minimal serum volumes. Large reference laboratories in the United States are adopting these platforms for autoimmune and infectious disease panels, compressing turnaround times while expanding test menus without proportional staffing increases.
EMA's In Vitro Diagnostic Regulation is mandating post-market performance monitoring through periodic safety update reports, compelling manufacturers to establish real-world evidence collection systems. This surveillance obligation disproportionately affects small-to-medium enterprises lacking established pharmacovigilance infrastructure, accelerating consolidation toward integrated diagnostic conglomerates with dedicated compliance functions.
Hospital procurement committees are unbundling instrument placement contracts from exclusive reagent supply agreements, favoring open-system architectures that permit third-party assay sourcing. This disintermediation is most pronounced in German university hospital networks, where centralized purchasing cooperatives negotiate reagent pricing independently from capital equipment vendors, compressing margin capture for integrated platform suppliers.
Global Serological Testing Market Segmentation
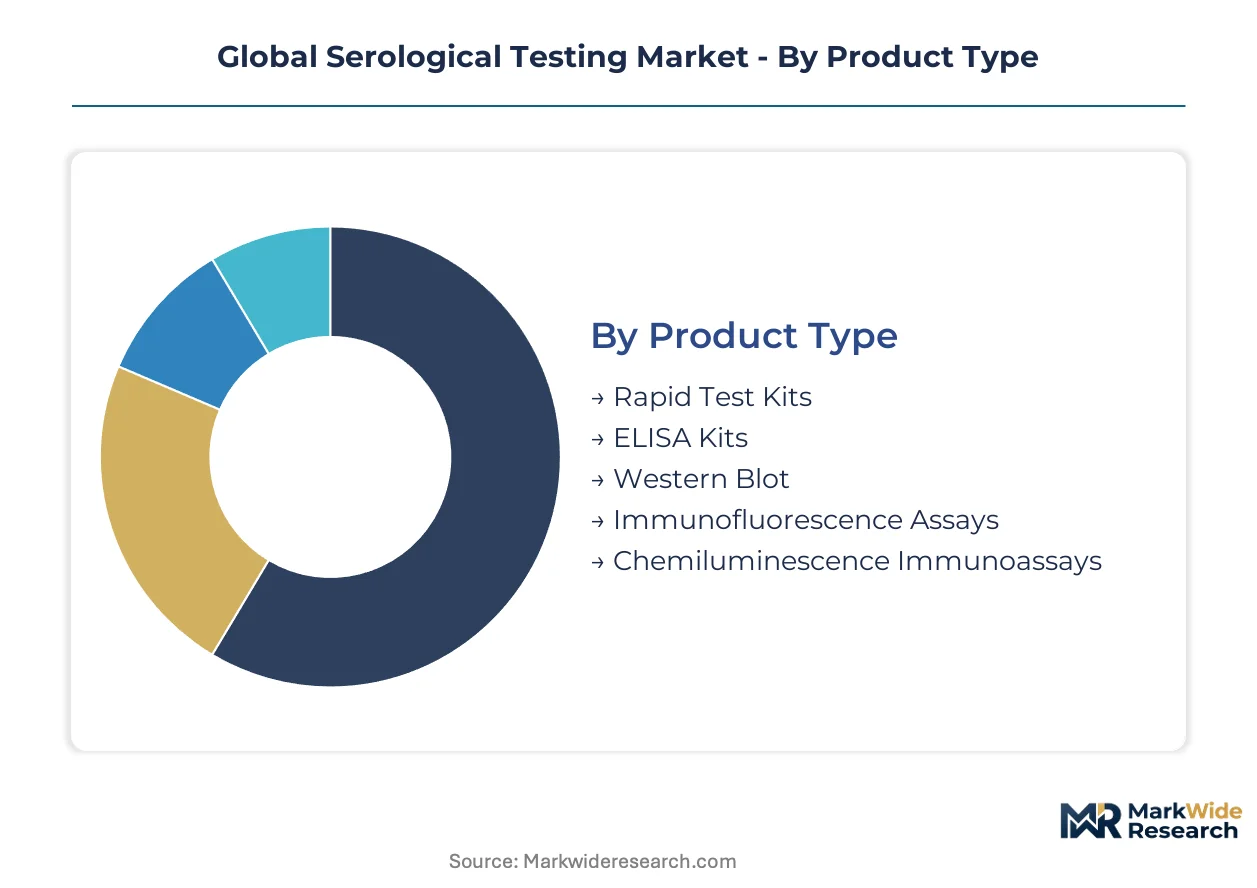
Serological testing segmentation reflects divergent performance requirements across clinical throughput, analytical sensitivity, and regulatory complexity. Product architecture choices cascade into deployment economics and end-user procurement patterns, creating distinct competitive arenas within each dimension.
Product Type:
Cost tier stratification separates premium high-throughput platforms from economy rapid formats, with mid-range ELISA occupying the contested middle ground.
- Chemiluminescence Immunoassays:These systems employ acridinium or luminol-based signal amplification achieving sub-picogram detection limits. Blood banking facilities in Japan and Germany anchor demand for donor screening applications where false-negative tolerance approaches zero. IVDR Class C certification requirements favor established manufacturers with dedicated regulatory affairs infrastructure.
- ELISA Kits:Enzyme-linked protocols using horseradish peroxidase or alkaline phosphatase conjugates dominate reference laboratory menus through proven standardization. Diagnostic laboratories in the United States sustain volume leadership for infectious disease panels despite longer incubation protocols. Open-system compatibility preserves third-party reagent sourcing flexibility.
- Rapid Test Kits:Lateral flow immunochromatography enables CLIA-waived point-of-care deployment with 15-minute turnaround times.
- Western Blot:Electrophoretic confirmation assays retain regulatory-mandated status for HIV and Lyme disease definitive diagnosis.
- Immunofluorescence Assays:Microscopy-based detection sustains autoimmune antibody pattern recognition in rheumatology reference settings.
Chemiluminescence Immunoassays holds installed capacity. Rapid Test Kits is rotating up the share rankings.
Application:
Volume concentration varies sharply across acute infectious screening versus chronic condition monitoring, with divergent reimbursement and test frequency profiles.
- Infectious Disease Detection:Serological confirmation of HIV, hepatitis, and syphilis exposure employs paired screening and supplemental algorithms. Blood banks in Germany enforce dual-methodology protocols combining nucleic acid testing with antibody detection. Regulatory mandates sustain baseline demand regardless of epidemiological fluctuation.
- Autoimmune Disorder Diagnosis:Expanded antibody panels for lupus, rheumatoid arthritis, and celiac disease are expanding most quickly among specialty reference laboratories. Rheumatology practices in the United States are adopting comprehensive profiling for early intervention protocols. Reagent consumption per patient exceeds infectious disease screening by substantial multiples.
- Blood Screening:Transfusion safety verification combines serological and molecular methods for comprehensive donor characterization.
- Allergy Testing:Specific IgE quantification serves allergist-immunologist practices with seasonal testing patterns.
- Vaccine Development:Immunogenicity assessment supports pharmaceutical clinical trials through neutralization and binding antibody quantification.
Infectious Disease Detection anchors current throughput. Autoimmune Disorder Diagnosis is climbing the fastest among revenue-generating categories.
End User:
Customer type fragmentation creates distinct procurement channels with divergent price sensitivity, technical support requirements, and contract structures.
- Diagnostic Laboratories:High-volume central facilities process thousands of serological samples daily with automated track-based workflows. Independent laboratories in the United States are consolidating through regional networks to negotiate reagent pricing leverage. Instrument placement contracts increasingly unbundle from exclusive supply agreements.
- Blood Banks:National transfusion services in Japan and Germany operate under ministerial mandates specifying dual-methodology screening protocols. Procurement runs through centralized tenders with multi-year performance guarantees. Quality system audits exceed standard clinical laboratory requirements.
- Point-of-Care Centers:Physician offices and urgent care clinics prioritize CLIA-waived rapid formats with minimal operator training.
- Research Institutes:Academic medical centers employ research-use-only reagents for biomarker discovery bridging clinical and pharmaceutical endpoints.
- Pharmaceutical Companies:Vaccine developers require GMP-compliant immunogenicity testing for regulatory submission packages.
Diagnostic Laboratories commands the largest installed instrument base. Point-of-Care Centers is gaining share fastest through CLIA waiver expansion.
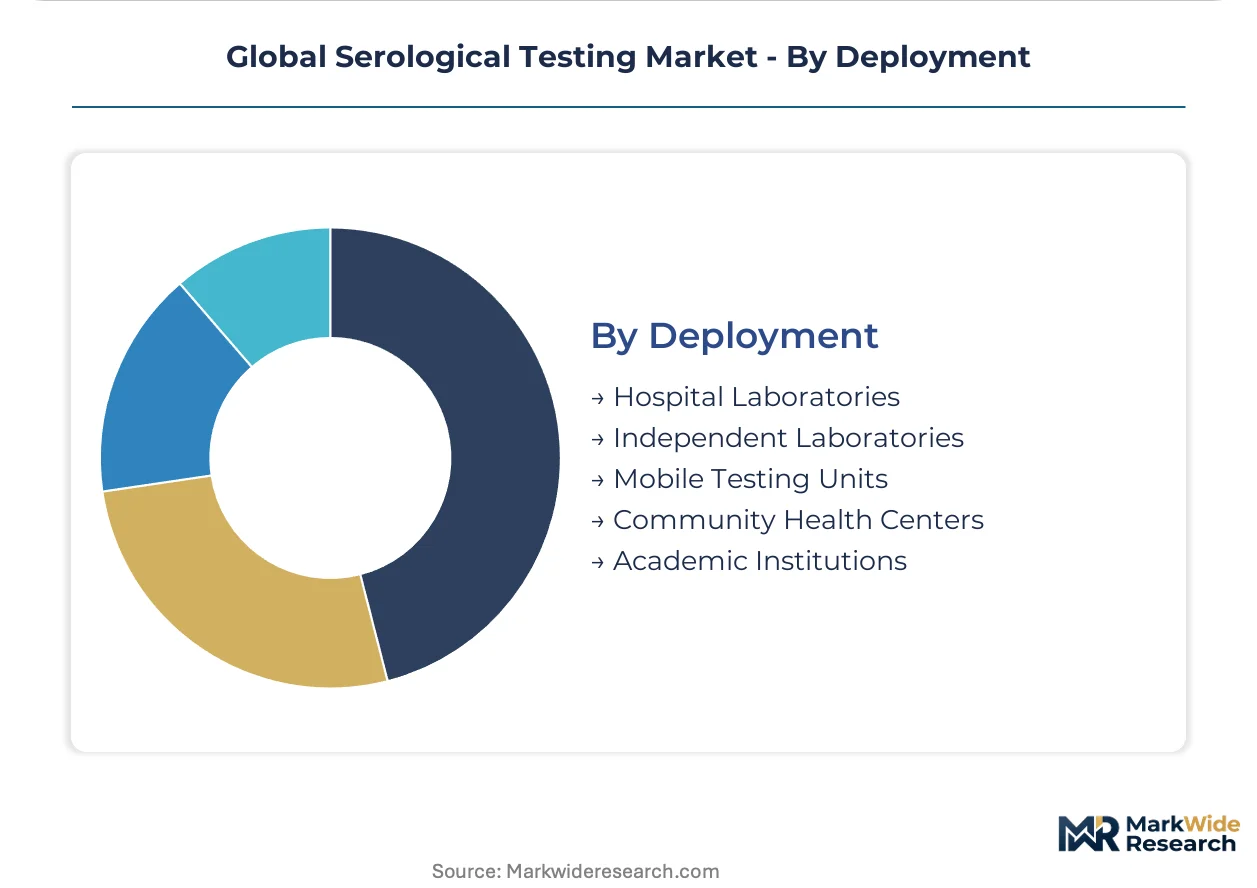
Deployment:
Physical infrastructure configuration determines pre-analytical handling, turnaround time guarantees, and regulatory accreditation scope.
- Hospital Laboratories:Integrated health system facilities leverage electronic medical record connectivity for seamless result routing. German university hospital networks are pioneering open-system architectures permitting third-party assay sourcing. Middleware customization requirements create integration friction with legacy automation.
- Independent Laboratories:Commercial reference facilities compete through specialized test menus and expedited turnaround commitments. National chains in the United States are deploying multiplexed bead-based platforms for autoimmune and infectious panel consolidation. Volume aggregation enables favorable reagent pricing.
- Mobile Testing Units:Deployable laboratories serve rural and disaster-response settings with containerized equipment configurations.
- Community Health Centers:Federally qualified health centers in the United States employ CLIA-waived rapid testing for infectious disease screening.
- Academic Institutions:Teaching hospital laboratories combine clinical service with research training missions.
Hospital Laboratories maintains the deepest analyzer installed base. Independent Laboratories is rotating up the share rankings through consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. Blood banks in Germany and Japan absorb premium pricing for zero-false-negative screening protocols. Point-of-care clinics in India and community health centers in the United States prioritize CLIA-waived rapid formats where unit cost trumps analytical sensitivity.
United States
Diagnostic laboratories sustain the deepest installed base of automated serological analyzers. FDA's CLIA waiver pathway accelerates point-of-care deployment in urgent care chains and physician offices. The Greater Boston corridor anchors reference laboratory consolidation, with national chains deploying multiplexed bead-based platforms for autoimmune panel consolidation.
Germany
Blood banking facilities enforce dual-methodology donor screening combining nucleic acid testing with antibody confirmation. EMA's IVDR mandates expanded performance evaluation documentation for Class C device commercialization. The Rhine-Ruhr metropolitan region concentrates university hospital networks pioneering open-system architectures that unbundle instrument contracts from reagent supply agreements.
Japan
PMDA enforces pharmaceutical-grade clinical evidence thresholds for serological platform importation. National transfusion services operate under ministerial mandates specifying chemiluminescence immunoassay confirmation protocols. The Kanto region around Tokyo hosts the densest concentration of automated track-based workflows processing thousands of daily samples.
India
CDSCO's phased manufacturing incentives attract contract reagent production for export-oriented diagnostics. Price-sensitive procurement in government health programs favors economy ELISA formats over premium chemiluminescence systems. The Mumbai-Pune corridor in Maharashtra anchors independent laboratory networks expanding into tier-two cities.
Switzerland
Single-source suppliers of chemiluminescence substrates create supply vulnerability for manufacturers dependent on acridinium ester derivatives. Swissmedic maintains alignment with EMA regulatory standards while preserving national notification requirements for IVD placement. The Basel-Zurich corridor concentrates precision reagent manufacturing for global diagnostic kit producers.
Global Serological Testing Market Competitive Landscape
Capability concentration sits with integrated diagnostic conglomerates possessing dedicated regulatory affairs infrastructure; scale advantage sits with diversified life science conglomerates leveraging cross-divisional manufacturing. The vendor base separates into three tiers: multinational platform suppliers with installed instrument bases, mid-cap reagent specialists with open-system compatibility, and regional rapid test manufacturers with CLIA-waived portfolios. Consolidation pressure intensifies as IVDR documentation burdens disproportionately burden small-to-medium enterprises lacking pharmacovigilance functions. Strategic moves center on unbundling instrument placement from exclusive reagent contracts, and on backward integration into substrate manufacturing to reduce single-source dependency.
Among diversified laboratory conglomerates, Abbott Laboratories and Roche Diagnostics exemplify the integrated platform archetype, each leveraging installed analyzer bases to sustain recurring consumable revenue streams. Thermo Fisher Scientific occupies a position bridging clinical diagnostics with research-use-only reagents that serve pharmaceutical immunogenicity testing. These three entities represent the capability-heavy tier where regulatory infrastructure and multi-jurisdictional compliance systems create defensive moats against mid-cap competitors.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Roche Diagnostics |
| Thermo Fisher Scientific |
| Becton Dickinson |
| Eurofins Scientific |
| Randox Laboratories |
| ELITechGroup |
| Bio-Rad Laboratories |
| Chembio Diagnostics |
| Others |
Supply & Pricing Matrix
Swiss suppliers of acridinium ester chemiluminescence substrates command disproportionate margin capture downstream, concentrating pricing power in the hands of substrate manufacturers while diagnostic kit assemblers face cost pass-through vulnerability. Blood banking facilities in Japan and Germany absorb premium pricing for zero-false-negative screening protocols, whereas point-of-care clinics in India and community health centers in the United States prioritize economy formats where unit cost supersedes analytical sensitivity.
Pricing Analysis
Reagent supply agreements and extended instrument service contracts generate the dominant lifetime value streams, shifting revenue concentration from capital equipment toward recurring consumable consumption. Three-tier pricing structure across premium chemiluminescence, standard ELISA, and economy rapid test levels reflects certification grade differentiation and throughput scale. Cost compression in the mid-range ELISA tier is intensifying because hospital procurement committees are unbundling instrument placement from exclusive reagent contracts. Point-of-care centers exhibit highest price sensitivity; blood banks demonstrate lowest sensitivity due to regulatory mandate rigidity.
Supply Chain Analysis
Tariff exposure between Switzerland and South Korea for chemiluminescence substrates dominates supply risk assessment for manufacturers dependent on acridinium derivative sourcing. Manufacturing concentration rests on Switzerland, South Korea, and the United States for precision substrate production, with India emerging as contract reagent assembly for export markets. Raw material dependencies include acridinium esters, enzyme conjugates, and nitrocellulose membranes. Single-source vulnerability for Class C device substrates creates procurement fragility. Distribution runs through centralized tenders for blood banking facilities and GPO-negotiated contracts for hospital laboratory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
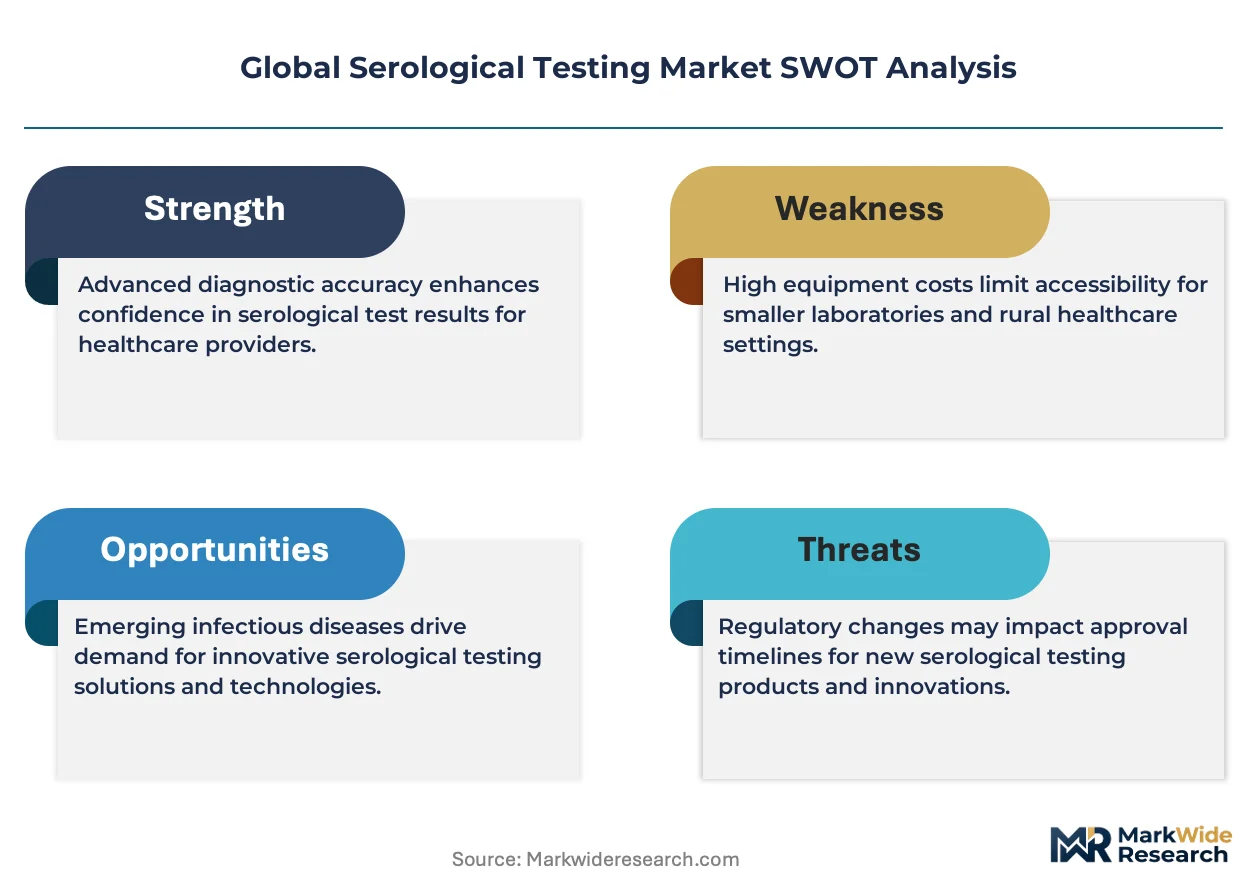
IVDR technical documentation expertise scarcity is concentrating competitive advantage among integrated diagnostic conglomerates with dedicated regulatory affairs infrastructure, leaving mid-cap reagent specialists exposed to compliance burden asymmetry. The capability gap in pharmacovigilance systems for post-market surveillance is reshaping acquisition attractiveness profiles.
For Market Incumbents: Entrench installed base loyalty through backward integration into substrate manufacturing to reduce Swiss supplier dependency, while expanding cloud-based remote diagnostic platforms that deepen switching costs for diagnostic laboratories. The IVDR documentation burden threatens mid-cap competitors lacking dedicated regulatory infrastructure. Channel control through open-system architecture partnerships with German university hospital networks preserves reagent pricing leverage against procurement committee unbundling. For New Entrants and Emerging Players: India's CDSCO streamlined manufacturing incentives offer the most penetrable geographic entry point for export-oriented reagent production targeting price-sensitive government health programs. The white-space opportunity concentrates in CLIA-waived rapid test formats for United States urgent care clinic expansion and multiplexed bead-based platforms for autoimmune panel consolidation in specialty reference laboratories. A contract manufacturing go-to-market angle bypasses direct regulatory certification burdens while building volume credibility. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap reagent specialists possessing open-system compatibility and established CE marking, positioned for IVDR compliance acquisition by integrated platform conglomerates seeking regulatory infrastructure augmentation. Long-term viability favors entities with hybrid clinical-research revenue streams bridging pharmaceutical immunogenicity testing. The signal to watch is CDSCO manufacturing incentive utilization rates as inflection indicator for contract production migration momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Manufacturing | Captive supply of acridinium esters reduces Swiss supplier concentration risk for chemiluminescence platforms. |
| IVDR Technical Documentation Investment | EMA Class C device compliance infrastructure creates defensive moats against mid-cap competitors lacking pharmacovigilance systems. |
| CLIA-Waived Rapid Test Portfolio Expansion | FDA waiver pathway access unlocks point-of-care deployment in United States urgent care chains and physician offices. |
| Open-System Architecture Partnerships | German university hospital network procurement committee alignment preserves reagent pricing leverage against contract unbundling. |
| Multiplexed Bead-Based Platform Adoption | Flow cytometry hybridization enables autoimmune and infectious panel consolidation without proportional staffing increases. |
Research Methodology
Cross-validation between primary interviews with diagnostic laboratory directors, regulatory affairs specialists at IVD manufacturers, hospital procurement committee members, and blood bank quality officers anchors the qualitative findings against secondary validation from FDA 510(k) filings, EMA IVDR submission databases, CDSCO manufacturing incentive disclosures, and hospital GPO contract repositories. Bottom-up instrument installation tracking and top-down reagent consumption modeling triangulate market sizing across the analysis window.
Calibration against historical instrument placement cycles and reagent pull-through rates validates growth trajectory assumptions throughout the forecast period. Segmentation dimensions span product type tier, application category, end-user procurement channel, and deployment configuration. CAGRs derive from regression analysis of installed base expansion correlated with reagent consumption intensity, incorporating IVDR transition timeline impacts and CLIA waiver pathway acceleration as industry-specific forecast inputs.
Practitioners should monitor IVDR technical documentation approval bottlenecks, CDSCO contract manufacturing incentive uptake velocity, and hospital procurement committee unbundling prevalence for early signals of competitive positioning shifts. Forecasts reflect documented assumptions regarding regulatory transition timelines and substrate supply continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Chlamydia Diagnostics Market
Diagnostics
Global Lyme Disease Diagnostic Market
Diagnostics
Digital Companion Diagnostics Market
Diagnostics
Diagnostic Reagents Market
Diagnostics
Pathogen Detection Market
Diagnostics
United States Melanoma Diagnostics & Therapeutics Market
Diagnostics
Elisa Tests Market
Diagnostics
Blood Urea Nitrogen Diagnostics Market
Diagnostics
Global Saliva Collection and Diagnosis Market
Diagnostics
Poultry Diagnostics Market
Diagnostics
Alzheimer's Disease Diagnostics and Therapeutics Market
Diagnostics
United Kingdom in-Vitro Diagnostics Market
Diagnostics
Preterm Birth Diagnostic Test Kits Market
Diagnostics
Global Hemostasis Diagnostics Market
Diagnostics
DNA Probes - Based Diagnostics Market
Diagnostics
Semen Analysis Market