
 Early-Stage Lung Cancer Diagnostics Market | 2026-2036
Early-Stage Lung Cancer Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Early-Stage Lung Cancer Diagnostics Market Analytics
Next-generation sequencing is consolidating its position as the preferred molecular backbone for early-stage lung cancer diagnostics, displacing single-gene PCR panels in academic medical centers. Illumina Inc. leverages its installed base of sequencing instruments to anchor clinical workflows in major oncology networks. Guardant Health competes through specialized blood-based assays that simplify patient access. Danaher Corporation sustains diversified revenue across imaging and molecular platforms.
Early-stage lung cancer diagnostics encompasses non-invasive and minimally invasive detection methods applied to Stage I and Stage II malignancies before symptomatic progression, typically involving sample volumes below 10 mL for liquid biopsy protocols and spatial resolution thresholds of 1-2 mm for CT-based nodule characterization. Imaging modalities, particularly CT scan deployments, dominate procedure volume while biomarker analysis captures expanding margin pools as companion diagnostic linkages deepen. Liquid biopsy segments show the fastest structural expansion as blood-draw collection replaces tissue acquisition in surveillance settings, though biopsy retains primacy in initial histological confirmation.
FDA premarket approval pathways and Medicare national coverage determinations shape commercial timelines and reimbursement access for novel diagnostic platforms in the United States, while China's NMPA accelerates review channels for innovative oncology devices under priority review frameworks. Stakeholders must monitor evolving regulatory convergence between CDx approval and drug label expansion as the central strategic variable for platform commitment decisions.
Market Dynamics
Medicare's national coverage determination for low-dose CT screening has triggered a structural demand inflection, pulling molecular diagnostics into standardized lung cancer surveillance protocols across United States hospital systems.
Growth Catalysts
- CMS Reimbursement Expansion:Medicare's coverage decision for annual low-dose CT in high-risk populations has normalized reimbursement for screening programs, accelerating hospital procurement of integrated imaging-to-biomarker workflows.
- Liquid Biopsy Protocol Adoption:Blood-draw collection methods are displacing tissue acquisition in recurrence monitoring settings, reducing patient attrition in longitudinal surveillance programs.
- China's NMPA Priority Review:Accelerated approval channels for innovative oncology diagnostics are compressing commercialization timelines for domestic and multinational assay developers targeting the Chinese market.
Market Restraints
- Sequencing Reagent Supply Concentration:Dependence on a limited supplier base for next-generation sequencing consumables creates vulnerability in assay production continuity for molecular diagnostic laboratories.
- False-Positive Burden:High benign nodule detection rates from CT screening generate downstream cost inflation and patient anxiety, constraining program expansion in budget-constrained health systems.
- Histopathology Bottleneck:Shortage of trained thoracic pathologists limits throughput for tissue-based molecular profiling, creating diagnostic delays in academic medical centers.
Strategic Opportunities
- Germany's National Cancer Plan:Federal screening initiative expansion creates procurement windows for integrated diagnostic platforms in statutory health insurance networks.
- AI-Augmented Nodule Characterization:Machine learning integration with CT imaging workflows is compressing radiologist interpretation time while standardizing malignancy risk scoring.
- Community Oncology Penetration:Underdeveloped molecular testing infrastructure in United States community hospital settings represents addressable white space for decentralized assay deployment.
Industry Challenges
- Companion Diagnostic Synchronization:Misalignment between FDA CDx approval timelines and oncology drug label expansions creates commercial uncertainty for platform developers.
- Interoperability Friction:Integration of multi-omic data streams with legacy electronic health record systems requires substantial health information technology investment and specialized informatics talent.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Early-Stage Lung Cancer Diagnostics Market |
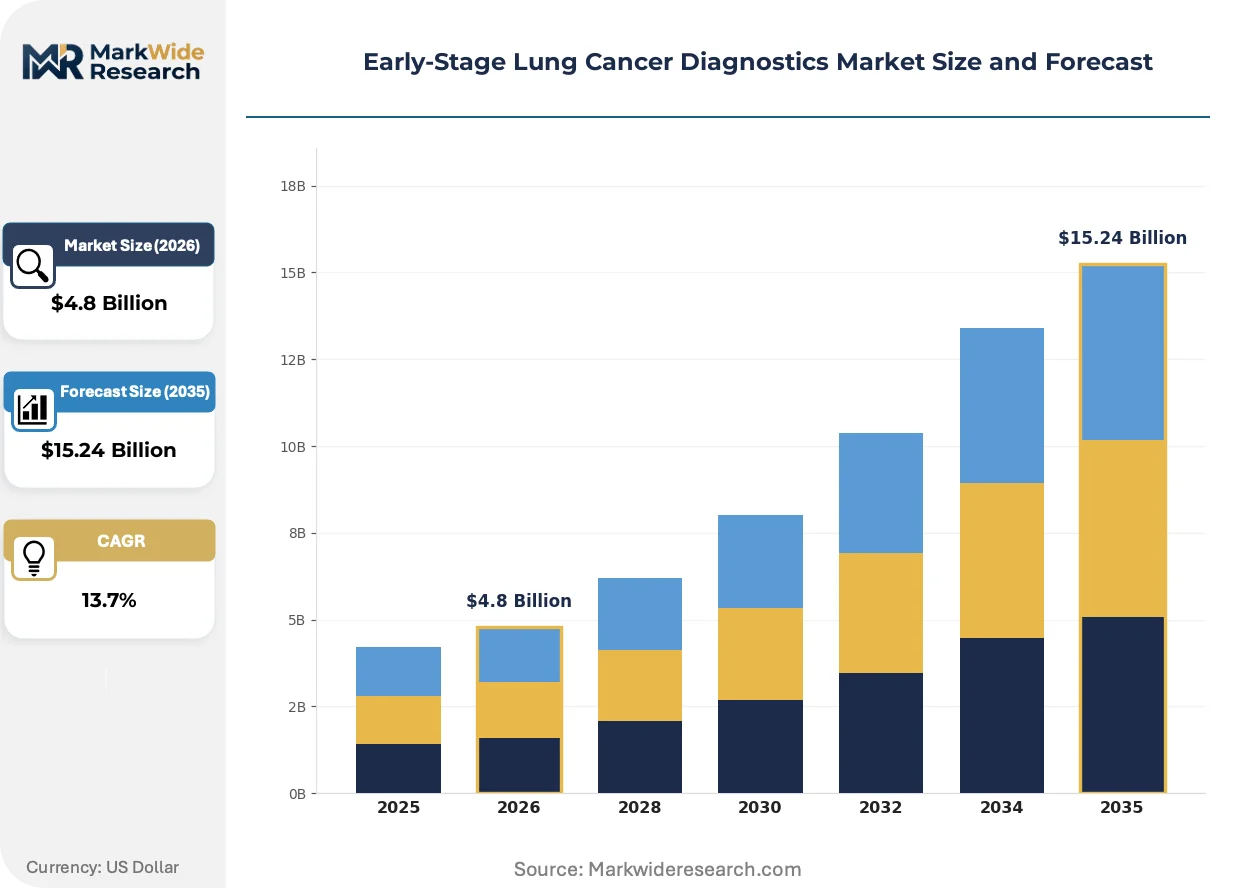
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging, Biopsy, Biomarkers, Liquid Biopsy Technology: CT Scan, MRI, PET Scan, Endobronchial Ultrasound End User: Hospitals, Diagnostic Laboratories, Oncology Centers, Academic Institutions Delivery Mode: In-person, Telehealth, Mobile Clinics, Home Care |
| Companies Covered | Abbott Laboratories, Danaher Corporation, Thermo Fisher Scientific, QIAGEN N.V, Illumina Inc., Quest Diagnostics Incorporated, NanoString Technologies, NeoGenomics Laboratories, Guardant Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Early-Stage Lung Cancer Diagnostics Market Evolving Landscape
Multimodal diagnostic architectures are consolidating imaging, circulating biomarker, and artificial intelligence layers into unified clinical decision support systems for lung cancer screening programs.
Multi-cancer early detection panels are unifying previously distinct single-organ assays into comprehensive blood-based screening protocols. Academic medical centers in the United States are piloting these platforms for high-risk cohorts ahead of prospective reimbursement decisions. This unification is compressing the addressable market for standalone lung-specific liquid biopsy assays while expanding total screening population eligibility.
FDA's evolving premarket approval framework for artificial intelligence-enabled radiology devices is formalizing validation requirements for algorithmic nodule characterization tools. Device manufacturers must now demonstrate clinical utility across diverse patient demographics and scanner modalities. United States academic medical centers are responding by establishing internal algorithm governance committees to evaluate deployment readiness.
Hospital procurement committees are consolidating vendor relationships through integrated platform contracts spanning imaging hardware, molecular assays, and data analytics subscriptions. This concentration is displacing point-solution purchasing patterns that dominated the previous decade. Germany and China exhibit the most pronounced consolidation, with hospital networks negotiating enterprise-wide diagnostic partnerships.
Early-Stage Lung Cancer Diagnostics Market Segmentation
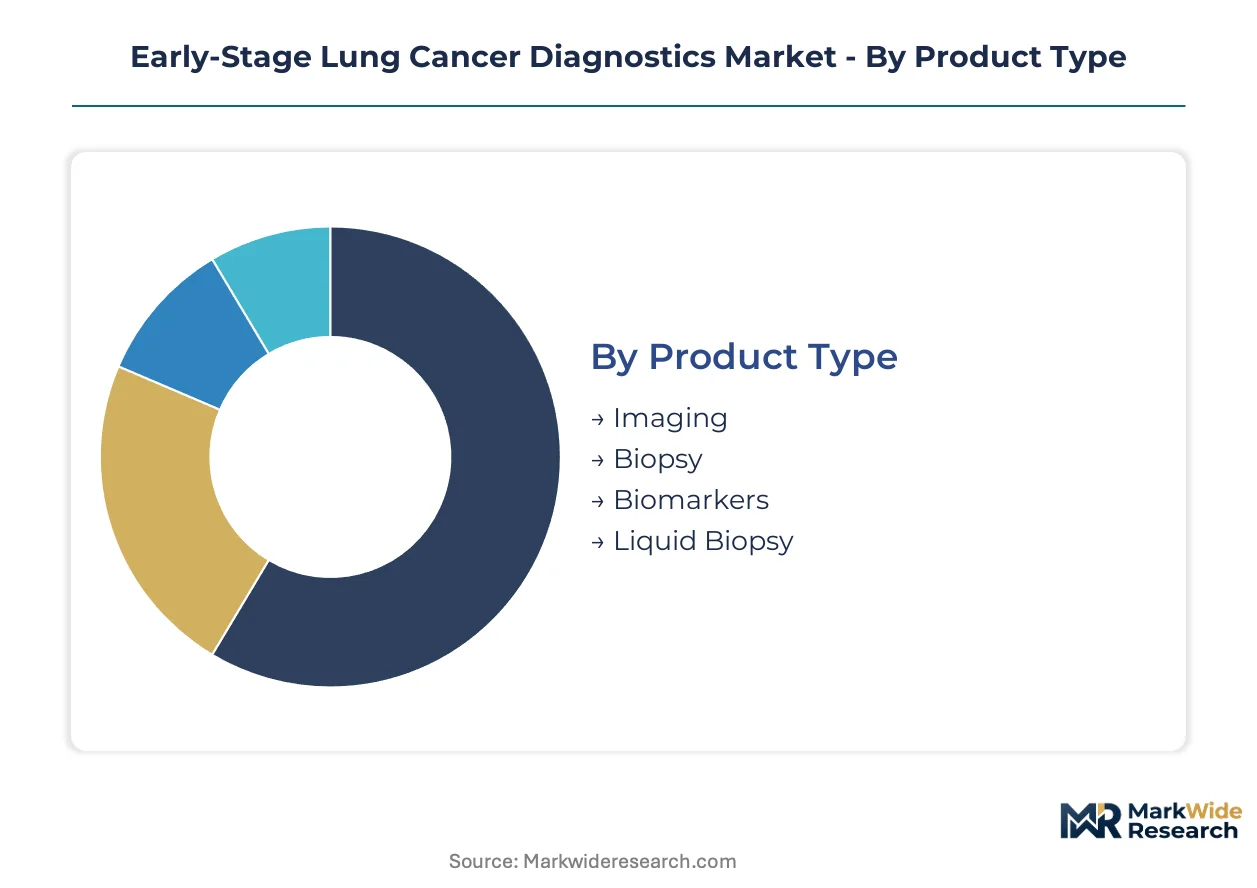
Segmentation reveals how diagnostic workflows fragment across technical modalities, care settings, and patient access channels. Understanding these divides exposes where procurement budgets concentrate and which platforms face displacement pressure.
Product Type:
Replacement cycles vary sharply across product categories, with imaging hardware requiring decade-long capital commitments while molecular assays refresh on 18-24 month innovation timelines.
- Imaging:Low-dose CT systems anchor screening infrastructure with 7-10 year depreciation schedules. United States hospital systems prioritize scanner replacements that integrate AI-enabled nodule detection, pulling demand toward vendors with embedded algorithm suites.
- Liquid Biopsy:Blood-draw collection platforms eliminate tissue acquisition barriers in surveillance protocols. China's NMPA priority review channels accelerate commercialization for domestic assay developers targeting recurrence monitoring.
- Biopsy:Tissue acquisition retains primacy for initial histological confirmation despite patient attrition risks.
- Biomarkers:Protein and metabolite panels complement genomic profiling in academic medical center workflows.
Volume placements concentrate in Imaging; the faster expansion belongs to Liquid Biopsy.
Technology:
Cost tiering separates premium-resolution modalities from standardized screening workhorses, with reimbursement differentials driving hospital procurement priorities.
- CT Scan:Low-dose protocols dominate procedure volume in lung cancer screening programs. Medicare's national coverage determination for annual screening in high-risk populations has normalized reimbursement, accelerating installed base expansion across United States community hospital networks.
- PET Scan:Metabolic imaging commands premium pricing for nodule characterization and staging confirmation. Germany's statutory health insurance networks limit PET utilization to specific diagnostic pathways, constraining volume relative to CT deployments.
- MRI:Magnetic resonance applications remain niche for patients with iodinated contrast contraindications.
- Endobronchial Ultrasound:Minimally invasive tissue sampling integrates with bronchoscopy suites for peripheral lesion access.
CT Scan captures the dominant placement volume; PET Scan claims the steepest expansion trajectory among advanced characterization modalities.
End User:
Customer type segmentation exposes a structural divide between integrated health systems with captive laboratory capacity and independent reference laboratories serving distributed oncology practices.
- Hospitals:Integrated delivery networks consolidate imaging and molecular testing under single procurement frameworks. Academic medical centers in the United States anchor next-generation sequencing adoption, displacing single-gene PCR panels through enterprise assay standardization.
- Diagnostic Laboratories:Independent reference labs compete on turnaround time and panel breadth for community oncology accounts. China's domestic laboratory networks expand molecular testing access beyond tier-one cities through regional hub-and-spoke configurations.
- Oncology Centers:Specialized cancer facilities demand rapid biomarker turnaround for treatment selection.
- Academic Institutions:Research-affiliated centers pilot multi-cancer early detection panels ahead of reimbursement decisions.
Hospital systems command the largest procurement volumes; Diagnostic Laboratories are gaining share fastest through decentralized community penetration.
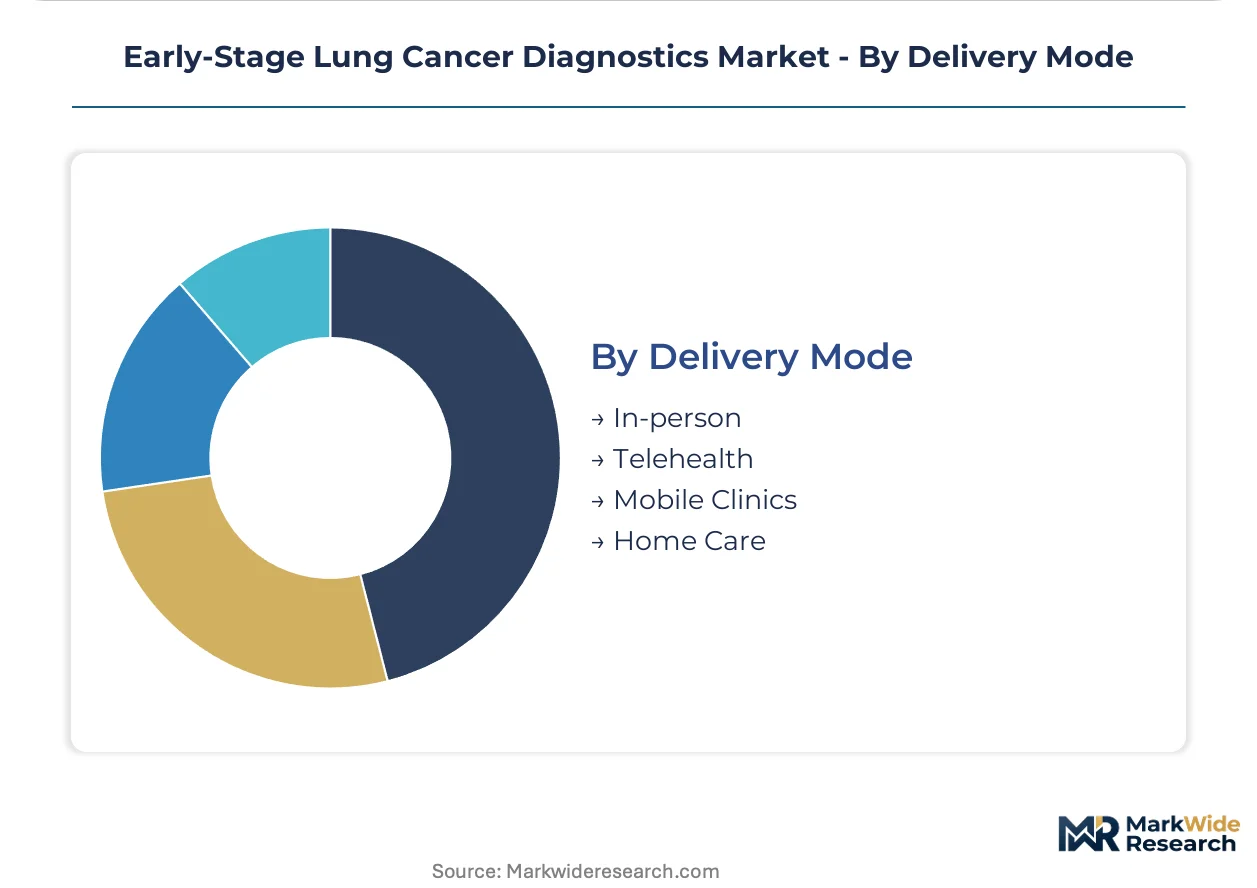
Delivery Mode:
Patient access channel segmentation tracks a shift from facility-centered testing toward distributed collection models that reduce geographic barriers to screening participation.
- In-person:Facility-based testing retains primacy for imaging-dependent diagnosis and tissue acquisition. United States lung cancer screening programs concentrate in hospital-affiliated radiology departments with dedicated low-dose CT protocols.
- Mobile Clinics:Deployable screening units extend CT access to underserved rural populations. Germany's National Cancer Plan incorporates mobile screening infrastructure to reach statutory insurance beneficiaries outside metropolitan clusters.
- Telehealth:Remote consultation platforms coordinate follow-up care for screen-detected nodules.
- Home Care:Blood-draw collection for liquid biopsy surveillance minimizes patient travel burden in longitudinal monitoring.
In-person delivery anchors current volume; Mobile Clinics are expanding most quickly as national screening programs prioritize access equity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized oncology zones in Massachusetts and California concentrate venture deployment for diagnostic platforms. Germany's statutory health insurance networks anchor European procurement volumes. China's NMPA priority review channels compress commercialization timelines for domestic assay developers.
United States
Medicare's national coverage determination for annual low-dose CT screening has normalized reimbursement across hospital systems. FDA premarket approval pathways shape commercial timelines for novel diagnostic platforms. Academic medical centers in Boston and Houston anchor next-generation sequencing adoption through enterprise assay standardization.
China
Domestic laboratory networks expand molecular testing access beyond tier-one cities through regional hub-and-spoke configurations. NMPA accelerates review channels for innovative oncology devices under priority review frameworks. Shanghai and Beijing clusters concentrate installed bases for imaging-to-biomarker integrated workflows.
Germany
Federal screening initiative expansion under the National Cancer Plan creates procurement windows for integrated diagnostic platforms. Statutory health insurance networks limit PET utilization to specific diagnostic pathways, constraining volume relative to CT deployments. Munich and Heidelberg anchor university hospital networks piloting multi-cancer early detection panels.
Japan
PMDA regulatory frameworks govern approval timelines for liquid biopsy assays entering the Japanese market. METI industrial policy supports domestic diagnostic platform development through targeted R&D subsidies. Tokyo-Osaka corridor concentrates hospital procurement committees consolidating vendor relationships through integrated platform contracts.
Early-Stage Lung Cancer Diagnostics Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with imaging hardware vendors commanding consolidated procurement relationships while molecular assay developers face fragmented reference laboratory competition. The vendor base organizes into three strategic archetypes: diversified life science conglomerates with sequencing instrument installed bases, specialized blood-based assay developers, and independent reference laboratories competing on turnaround time. Dominant competitive moves include strategic partnerships between imaging hardware vendors and AI algorithm developers, plus geographic expansion through mobile clinic deployment networks.
Among diversified platform developers, Danaher Corporation and Thermo Fisher Scientific occupy positions spanning imaging and molecular segments, while Guardant Health exemplifies the specialized blood-based assay archetype. Illumina Inc. anchors the sequencing infrastructure tier through instrument installed base leverage in academic medical centers. Abbott Laboratories and QIAGEN N.V sit within the diagnostic reagent and companion diagnostic development tier, with Quest Diagnostics Incorporated representing the independent reference laboratory model competing for community oncology accounts.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Danaher Corporation |
| Thermo Fisher Scientific |
| QIAGEN N.V |
| Illumina Inc. |
| Quest Diagnostics Incorporated |
| NanoString Technologies |
| NeoGenomics Laboratories |
| Guardant Health |
| Others |
Value Network & Pricing Analysis
Hospital procurement committee consolidation in the United States is forcing molecular diagnostic vendors toward bundled platform contracts that span imaging hardware, sequencing instruments, and assay subscriptions. This buyer-side concentration compresses pricing power for point-solution developers while rewarding diversified suppliers capable of anchoring enterprise-wide diagnostic partnerships.
Pricing Analysis
Lead-time premiums dominate contract negotiations for next-generation sequencing reagents, with academic medical centers paying marked-up rates for expedited consumable delivery to maintain assay continuity. The market operates on a hybrid pricing model combining capital equipment depreciation schedules for CT scanners with per-test transactional fees for liquid biopsy assays. Price differentiation hinges on FDA premarket approval tier and companion diagnostic linkage depth, with CDx-validated panels commanding substantial premiums over laboratory-developed tests. Pricing pressure stems from Medicare reimbursement compression for screening programs, squeezing margins on standardized low-dose CT protocols. Community hospital networks exhibit the highest price sensitivity, while integrated delivery networks prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Sequencing reagent supply rests on a concentrated base of specialty chemical producers in the United States, Germany, and China, with Illumina's proprietary flow cell chemistry creating captive demand channels for its installed instrument base. Critical inputs include fluorophore-labeled nucleotides, polymerase enzymes, and microfluidic cartridge substrates sourced from life science chemical suppliers. Single-source vulnerability concentrates in flow cell manufacturing, where supplier qualification timelines extend across multiple quarters and regulatory change notification requirements create switching friction. Distribution runs through authorized distributor networks for capital equipment and direct-to-laboratory fulfillment for high-velocity consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The early-stage lung cancer diagnostics market is becoming a vertical-integration race, with platform developers pursuing captive control over sequencing reagent supply and AI algorithm development to defend margin pools against modular competitors.
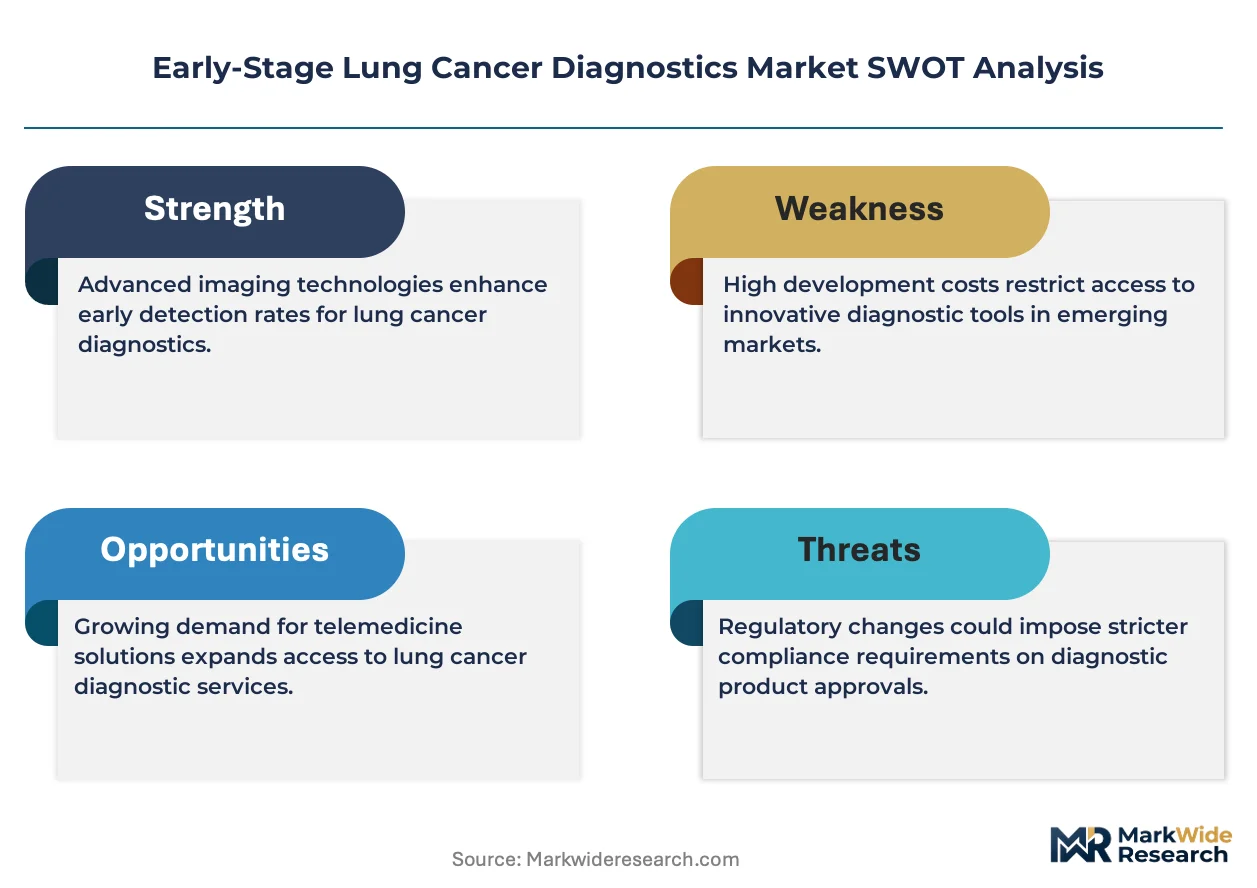
For Market Incumbents: Deploy enterprise assay standardization programs to lock academic medical centers into comprehensive sequencing workflows, displacing point-solution competitors. Deepen backward integration into flow cell chemistry manufacturing to reduce reagent cost exposure and supply disruption risk. Guard against blood-based assay specialists like Guardant Health by accelerating companion diagnostic synchronization with oncology drug developers. For New Entrants and Emerging Players: Capture community oncology penetration white space in United States hospital networks outside major metropolitan clusters, where molecular testing infrastructure remains underdeveloped. Target China's tier-two and tier-three cities through regional hub-and-spoke laboratory configurations enabled by NMPA priority review pathways. Lead with simplified blood-draw collection protocols that minimize patient attrition versus tissue acquisition competitors. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated diagnostic platform developers given Medicare reimbursement expansion and companion diagnostic label synchronization catalysts. Long-term viability favors suppliers with anchored instrument installed bases and recurring consumable revenue streams. Watch FDA premarket approval timelines for multi-cancer early detection panels as the inflection signal for liquid biopsy market restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enabled Nodule Detection Integration | FDA validation requirements for algorithmic radiology tools are compressing radiologist interpretation time across United States hospital systems. |
| Companion Diagnostic Synchronization | Alignment between CDx approval timelines and oncology drug label expansions determines platform commercialization velocity for molecular assay developers. |
| Mobile Screening Infrastructure Deployment | Germany's National Cancer Plan incorporates deployable CT units to extend statutory insurance beneficiary access beyond metropolitan clusters. |
| Multi-Cancer Early Detection Panel Development | Academic medical center pilots for unified blood-based screening protocols are compressing addressable market for standalone lung-specific assays. |
| Enterprise Platform Contract Consolidation | Hospital procurement committees in China and Germany are displacing point-solution purchasing through integrated diagnostic vendor relationships. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with hospital procurement managers, molecular laboratory directors, regulatory affairs specialists at diagnostic platform developers, and GPO contracts administrators. CMS Medicare coverage determinations, FDA premarket approval databases, and NMPA priority review disclosures provided reimbursement and regulatory trajectory validation. Bottom-up segmentation modeling triangulated against top-down market sizing from installed base estimates and procedure volume projections.
Granularity-level modeling addressed product type, technology modality, end-user setting, and delivery mode dimensions across the analysis window, with additional segmentation by companion diagnostic linkage status and reimbursement tier. CAGRs were derived from trend-line extrapolation of procedure volume growth, pricing trajectory assumptions, and technology substitution elasticities. Forecast inputs incorporated Medicare screening program expansion parameters, NMPA review timeline compression factors, and AI algorithm adoption curves in radiology workflows.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to companion diagnostic approval synchronization, sequencing reagent supply disruption events, and multi-cancer early detection panel reimbursement decisions. Forecasts reflect documented assumptions regarding Medicare coverage stability, regulatory pathway predictability, and hospital capital expenditure continuity. A small set of named triggers—FDA AI device validation requirements, NMPA priority review queue depth, and Germany's National Cancer Plan procurement timing—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology Diagnostics
Oncology Blood Testing Market
Oncology Diagnostics
Brain Tumor Diagnostics Market
Oncology Diagnostics
Asia-Pacific Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Middle East and Africa Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Global Hemato Oncology Testing Market
Oncology Diagnostics
Europe Non-Small Cell Lung Cancer Diagnostics Market
Oncology Diagnostics
Global Clinical Oncology NGS Market
Oncology Diagnostics
AI in Cancer Diagnostics Market
Oncology Diagnostics
Global Oncology Molecular Diagnostics Market
Oncology Diagnostics
Oncology Imaging Software Market
Oncology Diagnostics
North America Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Cancer Biopsy Market
Oncology Diagnostics
Middle East and Africa Colorectal Cancer Diagnostics Market
Oncology Diagnostics
Asia-Pacific Lung Cancer Diagnostics Market
Oncology Diagnostics
South America Ovarian Cancer Diagnostics and Therapeutics Market
Oncology Diagnostics
Global Bladder Cancer Therapeutics and Diagnostics Market