
 HIV/HBV/HCV Test Kits Market | 2026-2036
HIV/HBV/HCV Test Kits Market Size, Share, and Industry Trends Forecast 2026-2036
HIV/HBV/HCV Test Kits Market Foresight
China is tilting toward domestic manufacturing of molecular diagnostic consumables, with state-backed biotech parks in Suzhou and Chengdu adding cleanroom capacity for nucleic acid test kit production. Abbott Laboratories leverages its established channel presence across Asia-Pacific to sustain instrument-agnostic reagent sales. bioMérieux SA anchors its competitive position through integrated blood-culture and viral-load platforms that reduce laboratory turnaround times.
HIV/HBV/HCV test kits comprise in vitro diagnostic devices designed to detect viral antigens, antibodies, or nucleic acids in human serum, plasma, or whole blood specimens, typically achieving sensitivity thresholds below 50 copies per milliliter for RNA-based assays. Their primary commercial purpose is enabling clinical screening, blood-supply safety verification, and patient monitoring across acute and chronic infection stages. Rapid test kits occupy the largest volume share where point-of-care deployment limits infrastructure requirements, while polymerase chain reaction segments command premium pricing due to quantitative viral-load precision. Diagnostic laboratories represent the most concentrated end-user margin pool because high-throughput automation amortizes per-test costs across large sample volumes.
FDA enforces Class II medical device controls with 510(k) premarket notification for novel assay platforms, while the EU MDR requires notified-body conformity assessment for CE-marked IVDs entering European distribution channels. WHO prequalification shapes access for low-income country procurement through unified performance standards that align with PEPFAR and Global Fund tender requirements. Stakeholders must monitor evolving regulatory divergence between FDA's proposed LDT oversight framework and EMA's ongoing IVD regulation implementation timelines.
Market Dynamics
Decentralization of infectious disease testing to primary care networks is compressing the traditional laboratory-centric supply chain, forcing manufacturers to reconfigure kit formats for ambient-temperature stability and minimal operator training.
Growth Catalysts
- WHO Prequalification Programme:Unified performance benchmarks for dual-pathogen detection assays are harmonizing procurement standards across PEPFAR and Global Fund tenders, expanding addressable volume in low-income health systems.
- India's Public Health Expansion:Decentralization of screening to primary health centres under the National AIDS Control Programme is generating instrument placement demand at sub-district facilities previously served only by reference laboratories.
- Molecular Assay Sensitivity Thresholds:RNA-based platforms achieving detection below 50 copies per milliliter are displacing serological screening in acute infection windows, opening reimbursement pathways for quantitative viral load monitoring.
Market Restraints
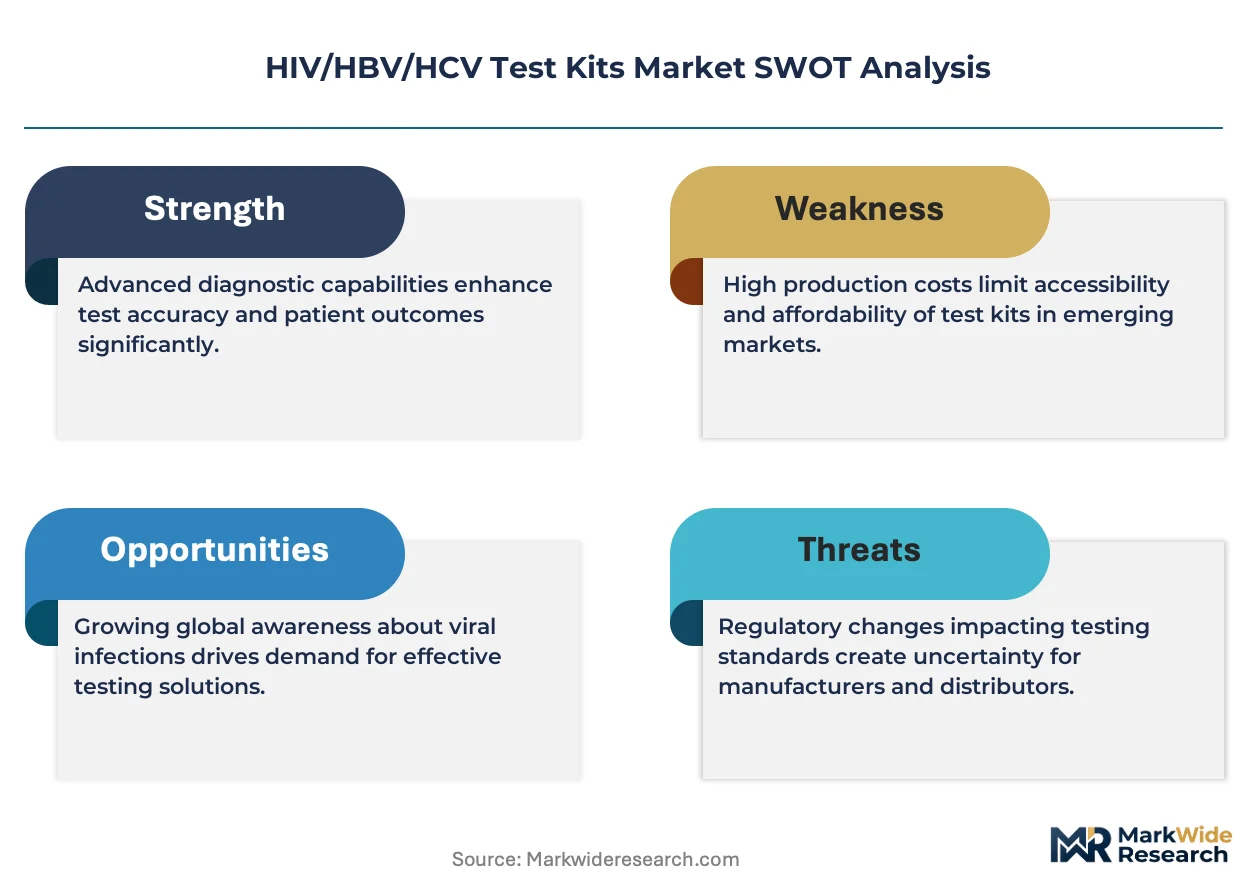
- Cold Chain Dependency:Nucleic acid test kits require continuous 2-8°C distribution infrastructure, limiting penetration in regions with unreliable electricity grids and fragmenting addressable geography.
- Regulatory Divergence:FDA's proposed laboratory-developed test oversight framework is creating compliance friction against EMA's MDR implementation timelines, forcing dual-track validation expenditures for multinational manufacturers.
- Reagent Instability:Enzyme-based rapid test kits exhibit lot-to-lot variability under tropical humidity conditions, elevating quality control costs and field failure rates in equatorial deployment zones.
Strategic Opportunities
- Point-of-Care Viral Load:Integration of microfluidic cartridge systems with smartphone-connected readers addresses the WHO target product profile for decentralized HIV monitoring, unlocking community-based antiretroviral therapy adherence programs.
- Blood Bank Automation:High-throughput nucleic acid testing platforms with sample-to-answer robotics reduce laboratory turnaround times, capturing margin concentration in centralized transfusion service networks.
- Dual-Pathogen Assay Development:Tightening performance benchmarks for HIV/HBV and HIV/HCV combination detection align with blood safety verification protocols, creating premium positioning for multiplex chemistry innovations.
Industry Challenges
- Bioinformatics Talent Scarcity:Interpretation of quantitative viral load data and assay calibration requires specialized molecular diagnostics expertise that outpaces training pipeline capacity in emerging market field operations.
- Legacy System Interoperability:Laboratory information management systems at district hospitals operate on fragmented software architectures, complicating data transmission from novel instrument platforms to national surveillance databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HIV/HBV/HCV Test Kits Market |
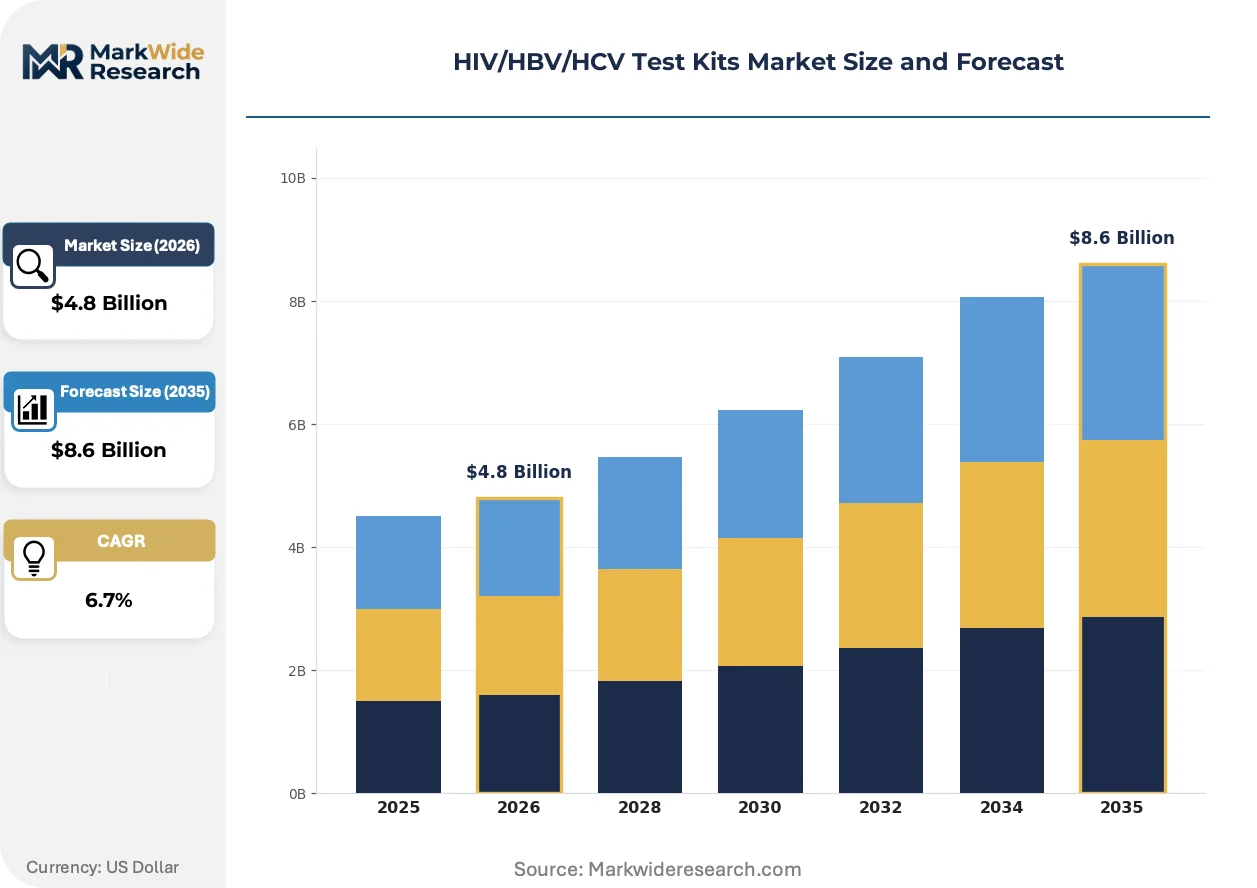
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rapid Test Kits, Enzyme-Linked Immunosorbent Assay, Polymerase Chain Reaction, Antigen Test Kits End User: Hospitals, Diagnostic Laboratories, Blood Banks, Home Care Providers Distribution Channel: Online Stores, Retail Pharmacies, Medical Supply Distributors, Direct Sales Technology: Immunochromatographic Assays, Continuous Flow Systems, Microfluidics, Lateral Flow Tests |
| Companies Covered | F. Hoffmann-La Roche Ltd, Abbott Laboratories, Siemens Healthineers, Bio-Rad Laboratories Inc, bioMérieux SA, QIAGEN, Hologic Inc, Meridian Bioscience Inc, Becton Dickinson and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HIV/HBV/HCV Test Kits Market Shifts & Advancements
Digital connectivity and miniaturized chemistry are collapsing the distance between specimen collection and diagnostic result, redefining where viral load monitoring can occur within patient care pathways.
Lyophilized reagent technology is virtualizing cold chain requirements for molecular assays. Manufacturers are embedding stabilized nucleic acid extraction chemistry directly into cartridge housings. District hospitals in sub-Saharan Africa and Southeast Asia are adopting these platforms at replacement cycle points previously reserved for laboratory-based systems. The technology is virtualizing the infrastructure barrier that historically confined quantitative testing to centralized reference laboratories.
EMA's MDR conformity assessment timelines are compressing product registration windows for novel IVD platforms. Notified-body bottlenecks in Germany and the Netherlands are extending time-to-market for CE-marked assays by 8-14 months against pre-2021 baselines. Manufacturers are responding with parallel FDA 510(k) submissions and early-stage WHO prequalification engagement to diversify regulatory risk.
Hospital procurement committees are consolidating viral hepatitis and HIV testing contracts under single-source framework agreements, displacing fragmented reagent purchasing across departmental silos. Integrated device-and-consumable vendors with established service infrastructure are capturing these consolidated awards. This concentration is most visible in India's corporate hospital chains and Brazil's public oncology networks.
HIV/HBV/HCV Test Kits Market Segmentation
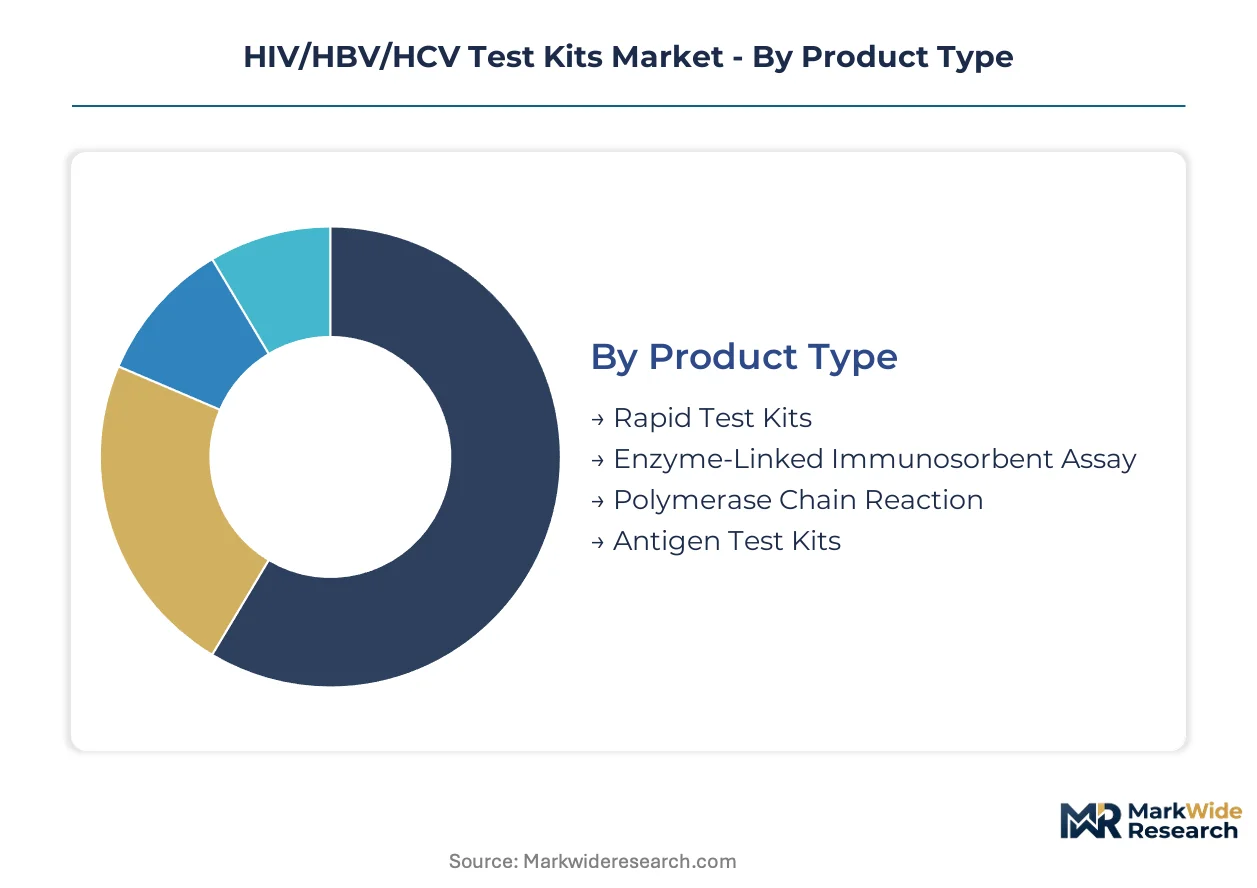
Test kit segmentation reveals divergent margin structures across detection chemistry, procurement authority, and care setting infrastructure. Each dimension carries distinct cold chain requirements, regulatory pathways, and operator training thresholds that reshape competitive positioning.
Product Type:
Cost tier stratification separates commodity serology from premium molecular platforms with divergent reimbursement and capital intensity profiles.
- Rapid Test Kits:Immunochromatographic strips detect antibodies or antigens within 20 minutes without instrumentation. Demand concentrates at primary health centres in India where the National AIDS Control Programme decentralizes screening to sub-district facilities lacking laboratory infrastructure.
- Polymerase Chain Reaction:Quantitative nucleic acid amplification achieves sensitivity below 50 copies per milliliter for viral load monitoring. Blood banks in Brazil and Thailand deploy high-throughput platforms to compress turnaround times for transfusion safety verification.
- Enzyme-Linked Immunosorbent Assay:Microplate-based antibody detection offers batch processing economies for reference laboratory networks.
- Antigen Test Kits:Direct viral protein detection bridges serology and molecular sensitivity for acute infection windows.
Rapid Test Kits hold installed capacity. Polymerase Chain Reaction is rotating up the share rankings.
End User:
Customer type determines purchasing authority complexity, with consolidated procurement committees displacing fragmented departmental buying.
- Diagnostic Laboratories:High-throughput automation amortizes per-test costs across large sample volumes, capturing concentrated margin pools. Centralized networks in São Paulo and Mumbai consolidate HIV, HBV, and HCV contracts under single-source framework agreements.
- Blood Banks:Nucleic acid testing mandates for transfusion safety drive instrument placement at national reference centres. Screening protocol expansions to cover emerging viral variants elevate sensitivity requirements for donor pool verification.
- Hospitals:Corporate hospital chains in India integrate viral hepatitis and HIV testing under unified reagent purchasing.
- Home Care Providers:Self-testing authorizations in select markets create direct-to-patient distribution channels.
Diagnostic Laboratories command purchasing volume concentration. Blood Banks are expanding fastest on regulatory mandate intensity.
Distribution Channel:
Supply concentration shapes route-to-market economics, with direct sales capturing institutional tenders and intermediaries serving fragmented retail.
- Medical Supply Distributors:Regional warehousing networks manage 2-8°C cold chain integrity for enzyme-based reagents. Distributor consolidation in Southeast Asia reduces fragmentation for nucleic acid test kit penetration.
- Direct Sales:Manufacturers deploy dedicated account teams for blood bank automation tenders and national laboratory framework agreements. Abbott Laboratories leverages this channel across Asia-Pacific for instrument-agnostic reagent contracts.
- Retail Pharmacies:Over-the-counter rapid test availability expands in markets with self-testing regulatory clarity.
- Online Stores:E-commerce platforms serve research institutions and smaller clinics with non-refrigerated consumables.
Medical Supply Distributors hold refrigerated infrastructure. Direct Sales is climbing fastest on tender consolidation.
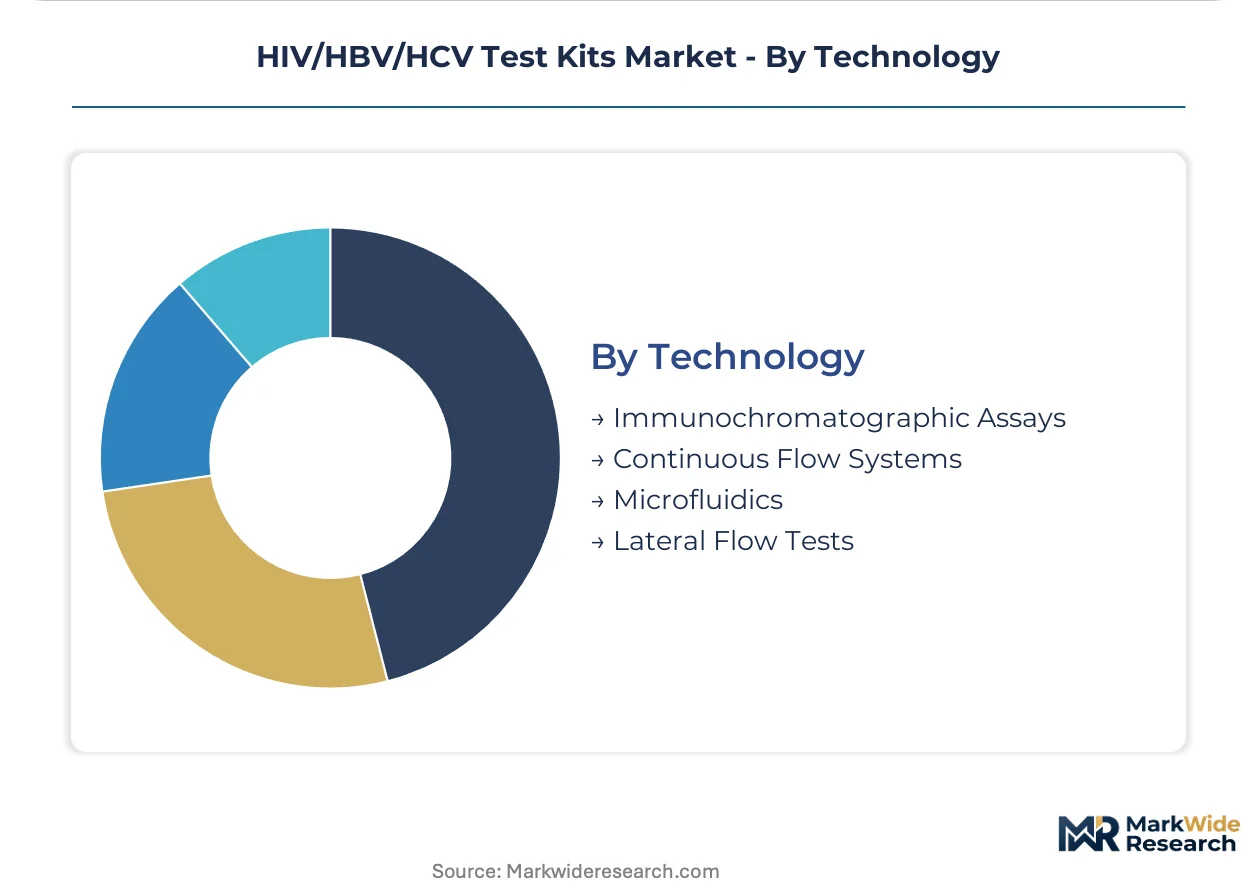
Technology:
Maturity gradients separate established immunochromatography from emerging microfluidic platforms with divergent intellectual property intensity.
- Microfluidics:Cartridge-based systems integrate nucleic acid extraction and amplification into single-use disposables. Smartphone-connected readers address WHO target product profiles for decentralized HIV monitoring in community-based antiretroviral adherence programs.
- Lateral Flow Tests:Nitrocellulose membrane chemistry dominates point-of-care deployment for antibody detection. Lot-to-lot variability under tropical humidity elevates quality control costs in equatorial zones.
- Immunochromatographic Assays:Colloidal gold conjugate visualization remains the cost baseline for rapid screening.
- Continuous Flow Systems:Automated sample-to-answer robotics reduce laboratory technician handling for high-volume blood bank networks.
Lateral Flow Tests hold manufacturing scale. Microfluidics is gaining share fastest on connectivity integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Test kit manufacturing clusters concentrate in Germany, Switzerland, and the United States, where precision instrumentation and diagnostic chemistry capabilities anchor supply. India and Brazil drive demand expansion through public health decentralization programs. Regulatory divergence between FDA and EMA compliance pathways shapes regional market access strategies.
United States
Blood bank automation tenders and high-throughput laboratory networks sustain instrument placement demand. FDA's Class II medical device controls and 510(k) premarket notification govern novel assay platform entry. Abbott Laboratories leverages established channel presence for instrument-agnostic reagent sales across reference laboratory networks.
Germany
Notified-body conformity assessment bottlenecks extend CE-marked IVD time-to-market by 8-14 months against pre-2021 baselines. EMA's MDR implementation timelines compress product registration windows for molecular diagnostic platforms. Siemens Healthineers anchors its position through integrated blood-culture and viral-load systems serving centralized transfusion services.
India
The National AIDS Control Programme decentralizes screening to primary health centres previously served only by reference laboratories. CDSCO regulatory pathways align with WHO prequalification standards for PEPFAR and Global Fund tender eligibility. Maharashtra and Karnataka host corporate hospital chains consolidating HIV, HBV, and HCV testing contracts under unified reagent purchasing.
Brazil
Blood banks deploy high-throughput nucleic acid testing platforms to compress turnaround times for transfusion safety verification. ANVISA conformity assessment shapes market access for imported diagnostic platforms. São Paulo's centralized laboratory networks consolidate procurement authority under single-source framework agreements.
China
State-backed biotech parks in Suzhou and Chengdu add cleanroom capacity for nucleic acid test kit production. NMPA regulatory oversight tightens performance benchmarks for domestic molecular diagnostic consumables. Yangtze River Delta manufacturing clusters tilt toward import substitution for previously foreign-sourced reagent chemistry.
HIV/HBV/HCV Test Kits Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in reagent chemistry and consumables. The vendor base stratifies across multinational conglomerates with blood bank automation portfolios and mid-scale manufacturers of point-of-care rapid tests. Two archetypes dominate: integrated device-and-consumable vendors capturing consolidated hospital procurement, and instrument-agnostic reagent suppliers leveraging established distribution channels. Competitive moves center on parallel regulatory submissions to diversify FDA and EMA compliance risk, and lyophilized reagent technology investments to virtualize cold chain infrastructure.
Among Swiss and German precision diagnostic groups, F. Hoffmann-La Roche Ltd and Siemens Healthineers exemplify platform-integrated archetypes with blood-culture and viral-load automation portfolios. Abbott Laboratories, a US-based healthcare conglomerate, occupies a position bridging instrument-agnostic reagent supply and point-of-care rapid test deployment. These three anchors represent divergent strategic postures: Roche and Siemens anchor the high-throughput laboratory tier, while Abbott spans channel presence across Asia-Pacific primary health networks.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Abbott Laboratories |
| Siemens Healthineers |
| Bio-Rad Laboratories Inc |
| bioMérieux SA |
| QIAGEN |
| Hologic Inc |
| Meridian Bioscience Inc |
| Becton Dickinson and Company |
| Others |
Supply & Pricing Matrix
Suzhou's state-backed biotech parks anchor nucleic acid test kit production capacity, with cleanroom expansion dynamics directly translating to downstream pricing leverage for domestic manufacturers against import-dependent competitors. CDSCO-aligned procurement in India and NMPA certification tiers in China fragment pricing power across regulatory jurisdictions, forcing multinational suppliers to maintain parallel cost structures.
Pricing Analysis
WHO prequalification standards dictate the pricing tier structure across PEPFAR and Global Fund tender eligibility, with CDSCO and ANVISA alignment creating premium-mid-economy pricing differentiation based on regulatory certification completeness. Volume scale in Brazil's São Paulo laboratory networks and India's corporate hospital chains compresses per-unit costs for framework agreement winners, while cold chain infrastructure gaps in sub-Saharan Africa elevate landed costs for nucleic acid platforms. Pricing pressure stems from lyophilized reagent technology investments virtualizing traditional cold chain requirements, enabling domestic challengers to undercut established suppliers. Diagnostic laboratories exhibit highest price sensitivity due to amortization pressures across high-throughput automation, whereas blood banks prioritize sensitivity thresholds over unit economics.
Supply Chain Analysis
Extended payment terms from 60 to 120 days dominate supplier financing arrangements for regional medical supply distributors managing 2-8°C refrigerated warehousing networks. Manufacturing concentration rests on Germany, Switzerland, and the United States for precision instrumentation, with China tilting toward import substitution through Suzhou and Chengdu capacity additions. Raw material dependencies center on nucleic acid extraction chemistry, colloidal gold conjugates for immunochromatography, and nitrocellulose membrane substrates. Single-source vulnerability in enzyme-based rapid test kit chemistry elevates lot-to-tot variability risks under tropical humidity conditions. Distribution runs through direct sales teams for blood bank automation tenders and consolidated distributor networks for primary health center penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in point-of-care viral load monitoring, with decentralization of infectious disease testing to primary care networks creating niche entry points for cartridge-based microfluidic platforms. WHO target product profile alignment unlocks procurement pathways previously reserved for centralized laboratory systems.
For Market Incumbents: Pre-empt lyophilized reagent technology deployment to virtualize cold chain infrastructure before domestic Chinese manufacturers achieve NMPA certification scale. Anchor high-throughput automation placements in Brazil's ANVISA-regulated blood bank networks to capture transfusion safety mandate expansion. Defensive consolidation through parallel FDA 510(k) and EMA MDR submission tracks mitigates notified-body bottleneck risk in Germany and the Netherlands. For New Entrants and Emerging Players: Build out microfluidic cartridge manufacturing capacity targeting India's National AIDS Control Programme decentralization to sub-district primary health centers lacking laboratory infrastructure. White-space concentration appears in community-based antiretroviral therapy adherence programs requiring smartphone-connected viral load readers. Go-to-market leverage rests on WHO prequalification engagement preceding PEPFAR tender eligibility rather than direct hospital sales penetration. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated device-and-consumable vendors with established service infrastructure capturing consolidated procurement committee awards. Long-term viability across the analysis window hinges on lyophilization chemistry capabilities and regulatory pathway diversification. Acquisition target archetype: mid-scale manufacturers of point-of-care rapid tests with CDSCO or ANVISA alignment and dormant WHO prequalification applications. Signal to monitor: EMA MDR notified-body capacity expansion announcements affecting CE-marked IVD time-to-market compression.| Strategic Initiative | Industry Significance |
|---|---|
| Lyophilized Reagent Technology Investment | Virtualizes 2-8°C cold chain requirements for nucleic acid platforms in equatorial deployment zones. |
| WHO Prequalification Parallel Track | Accelerates PEPFAR and Global Fund tender eligibility ahead of EMA MDR notified-body bottlenecks. |
| Microfluidic Cartridge Platform Launch | Addresses WHO target product profile for decentralized HIV monitoring in community-based adherence programs. |
| Hospital System Partnership Consolidation | Captures unified reagent purchasing contracts across India's corporate hospital chains and Brazil's oncology networks. |
| Dual-Pathogen Assay Development | Aligns with tightening blood safety verification protocols for HIV/HBV and HIV/HCV combination detection. |
Research Methodology
The analysis maps rapid test kit, polymerase chain reaction, enzyme-linked immunosorbent assay, and antigen detection sub-sectors, each validated through laboratory directors, blood bank procurement officers, biomedical engineers, and GPO contracts managers. Primary interview intelligence combined with secondary validation from FDA 510(k) filings, EMA MDR submission databases, WHO prequalification lists, and hospital procurement records. Bottom-up instrument placement counts triangulate against top-down public health program budget allocations across the analysis window.
Assumption sets held regulatory divergence pathways and cold chain infrastructure penetration rates fixed while varying lyophilization technology adoption curves and decentralized testing policy implementation intensity. Segmentation dimensions modeled span detection chemistry, procurement authority concentration, care setting infrastructure tier, and regional regulatory cluster alignment. CAGRs derive from instrument replacement cycle analysis and reagent consumption run-rates across high-throughput automation platforms. Forecast inputs incorporate blood bank nucleic acid testing mandate expansion trajectories and primary health center placement targets under India's National AIDS Control Programme.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-backed Chinese biotech parks or accelerated EMA MDR notified-body capacity additions would shift outcomes. Macroeconomic deviation in emerging market currency stability, regulatory acceleration in FDA LDT oversight implementation, or breakthrough sensitivity thresholds in CRISPR-based detection chemistry would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Veterinary Rapid Diagnostic Tests Market
Diagnostics
Alzheimer's Diagnostics and Therapeutics Market
Diagnostics
Fungal Antigens Market
Diagnostics
Glaucoma Diagnostics Market
Diagnostics
Cushing's Syndrome Diagnostics and Therapeutics Market
Diagnostics
Global Oral Cancer Rapid Test Kit Market
Diagnostics
Global Chlamydia Infection Diagnostics Market
Diagnostics
Companion Animal Diagnostic Services Market
Diagnostics
Global RSV Diagnostics Market
Diagnostics
Asia-Pacific Ovarian Cancer Diagnostics Market
Diagnostics
Equine Diagnostic Services Market
Diagnostics
Global Digital Diagnostics Market
Diagnostics
Cancer IVD Market
Diagnostics
Antigen Kit Market
Diagnostics
IVD Antibody Market
Diagnostics
Asia Pacific Predictive Disease Analytics Market