
 State Transition Testing Market | 2026-2036
State Transition Testing Market Size, Share, and Industry Trends Forecast 2026-2036
State Transition Testing Market Outlook
The gap between premium automated testing suites and commodity manual testing services is recalibrating competitive dynamics across the State Transition Testing landscape. IBM Corporation leverages its enterprise software heritage to anchor high-value contracts in regulated industries. Sparx Systems Pty Ltd specializes in model-driven engineering tools that dominate architectural visualization segments. Tesena s.r.o. competes through focused QA consultancy services across Central European markets.
State transition testing evaluates software behavior by mapping valid and invalid transitions between defined system states, typically employing finite state machine models with explicit transition coverage criteria to detect unreachable states or incorrect state entry conditions. Its primary purpose is to verify that systems respond correctly to sequences of inputs in safety-critical and complex interactive applications. Automated testing commands the largest revenue pool due to recurring license structures, while cloud services deployment represents the fastest-expanding application domain as distributed architectures proliferate. Embedded systems maintains mature demand in automotive and avionics sectors where hardware-software integration requirements create durable margin pools.
The FAA mandates DO-178C compliance for airborne software verification, directly shaping state transition test coverage requirements in aerospace procurement. BSI IT-Grundschutz and ISO/IEC 27001 frameworks in Europe elevate demand for documented state validation in cloud security certifications. Stakeholders must monitor how AI-generated test case synthesis reshapes labor intensity assumptions across manual and automated testing segments.
Market Dynamics
The migration from manual test case generation to AI-assisted synthesis is compressing labor intensity assumptions and forcing recalibration of service pricing models across the State Transition Testing landscape.
Growth Catalysts
- DO-178C Mandates:The FAA's airworthiness directive requires formal verification protocols for flight control software, creating durable procurement pull from Boeing, Lockheed Martin, and Tier 1 avionics suppliers.
- BSI IT-Grundschutz:Germany's federal security framework mandates documented state validation for cloud deployments, concentrating demand among Bundesdruckerei and federal IT contractors.
- Automotive OTA Architectures:Over-the-air update pipelines in electric vehicles require exhaustive state transition coverage for safety-critical ECU firmware, expanding contract volumes with Bosch and Continental validation teams.
Market Restraints
- Specialized Labor Scarcity:Finite state machine expertise and formal methods training create hiring bottlenecks in Prague, Bangalore, and Austin test centers.
- Tool License Stacking:Enterprise-grade model checking suites from IBM and Cadence impose recurring cost burdens that exclude mid-tier QA consultancies from competitive bidding.
- Hardware-in-the-Loop Dependencies:Embedded system validation requires physical ECU access, constraining remote delivery models and inflating project timelines for automotive clients.
Strategic Opportunities
- EU AI Act Conformity:High-risk AI system classifications will mandate traceable state documentation for autonomous decision pipelines, opening validation contracts with Munich and Paris AI labs.
- Medical Device Convergence:Software-as-a-medical-device regulations under FDA 21 CFR Part 820 create unmet demand for state-based safety validation in insulin pump and infusion controller firmware.
- DevSecOps Integration:Shift-left security practices are embedding state transition checks into CI/CD pipelines, displacing late-stage manual review with automated gatekeeping at GitLab and Jenkins touchpoints.
Industry Challenges
- Formal Methods Talent Pipeline:University programs in finite state machine theory and temporal logic verification graduate fewer practitioners than industry absorption rates require.
- Legacy System Integration:Brownfield SCADA and industrial control systems lack instrumentation hooks for automated state extraction, forcing expensive manual model reconstruction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | State Transition Testing Market |
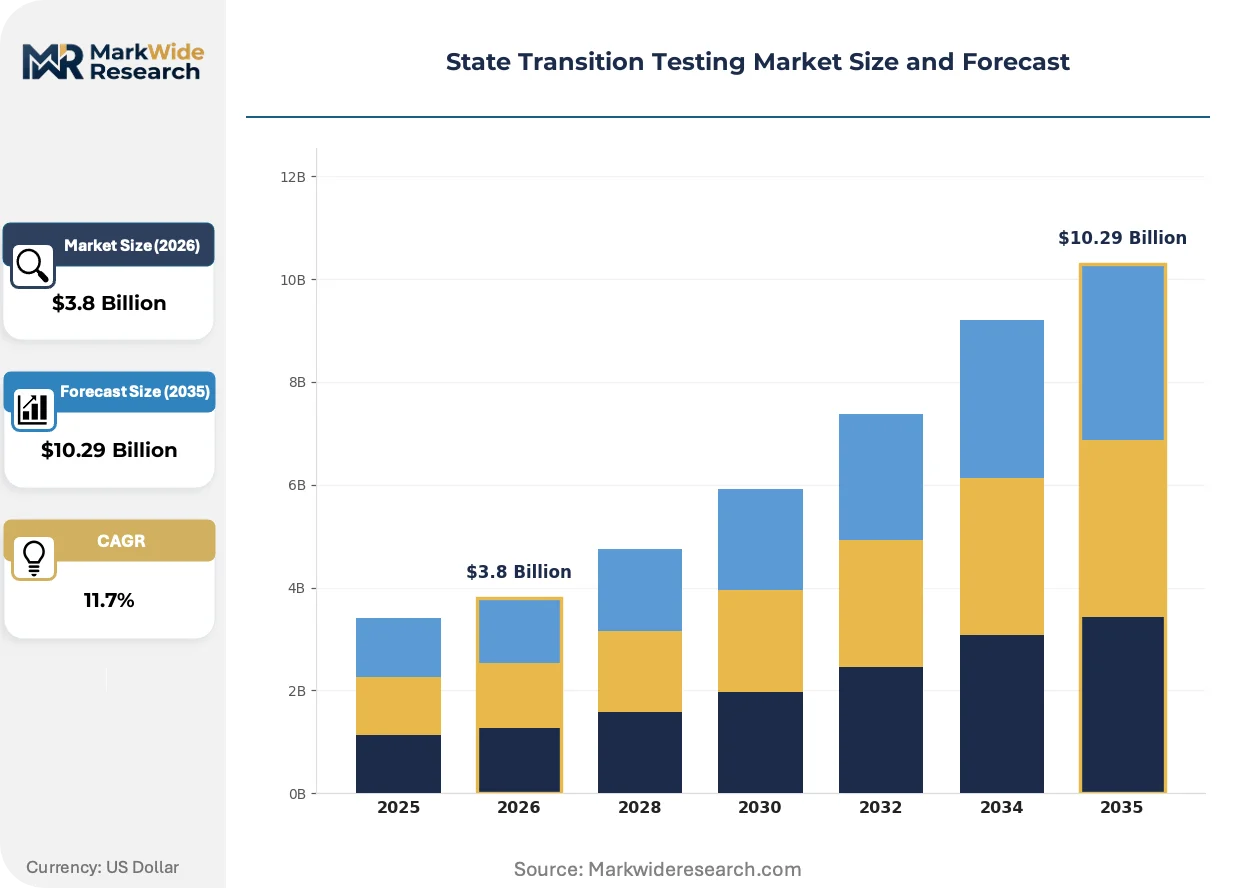
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Testing Type: Automated Testing, Manual Testing, Regression Testing, Performance Testing Application Domain: Web Applications, Mobile Applications, Embedded Systems, Cloud Services Deployment Model: On-Premises, Cloud-Based, Hybrid, Dedicated Hosting End User Sector: IT Services, Telecommunications, Healthcare, Aerospace |
| Companies Covered | Ideyatech, Inc., tesena s.r.o., DeRisk QA, Sparx Systems Pty Ltd., Prezi Inc., Intertek Group plc, Stratfor Enterprises, LLC, RiseSmart, Inc., IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
State Transition Testing Market Strategic Shifts
Test automation architectures are fragmenting into composable microservices that decouple model generation from execution engines, enabling vendor-agnostic toolchain assembly.
Property-based testing frameworks are modularizing state space exploration by generating randomized input sequences against formal specifications rather than handcrafted test vectors. Aerospace suppliers in Toulouse and Seattle are piloting these tools for flight software verification. The approach is modularizing quality assurance teams into specification authors separate from execution specialists, compressing headcount requirements per certification project.
REACH chemical safety assessments and the EU AI Act's risk classification system are converging on documentation-heavy conformity procedures. Industrial software vendors must now maintain auditable state transition logs for both physical process control and algorithmic decision chains. German automotive OEMs are responding by mandating ISO 26262-8 compliant toolchains that embed traceability matrices directly into model files.
Buyer procurement committees are unbundling test execution from test design, awarding separate contracts to Eastern European implementation houses and Western architectural consultancies. This bifurcation is most visible in Frankfurt and London financial services, where Basel III operational risk requirements demand independent model validation. Tier 1 banks now maintain dual vendor relationships that pit Tesena's Prague delivery center against IBM's UK advisory practice for annual contract renewal leverage.
State Transition Testing Market Segmentation
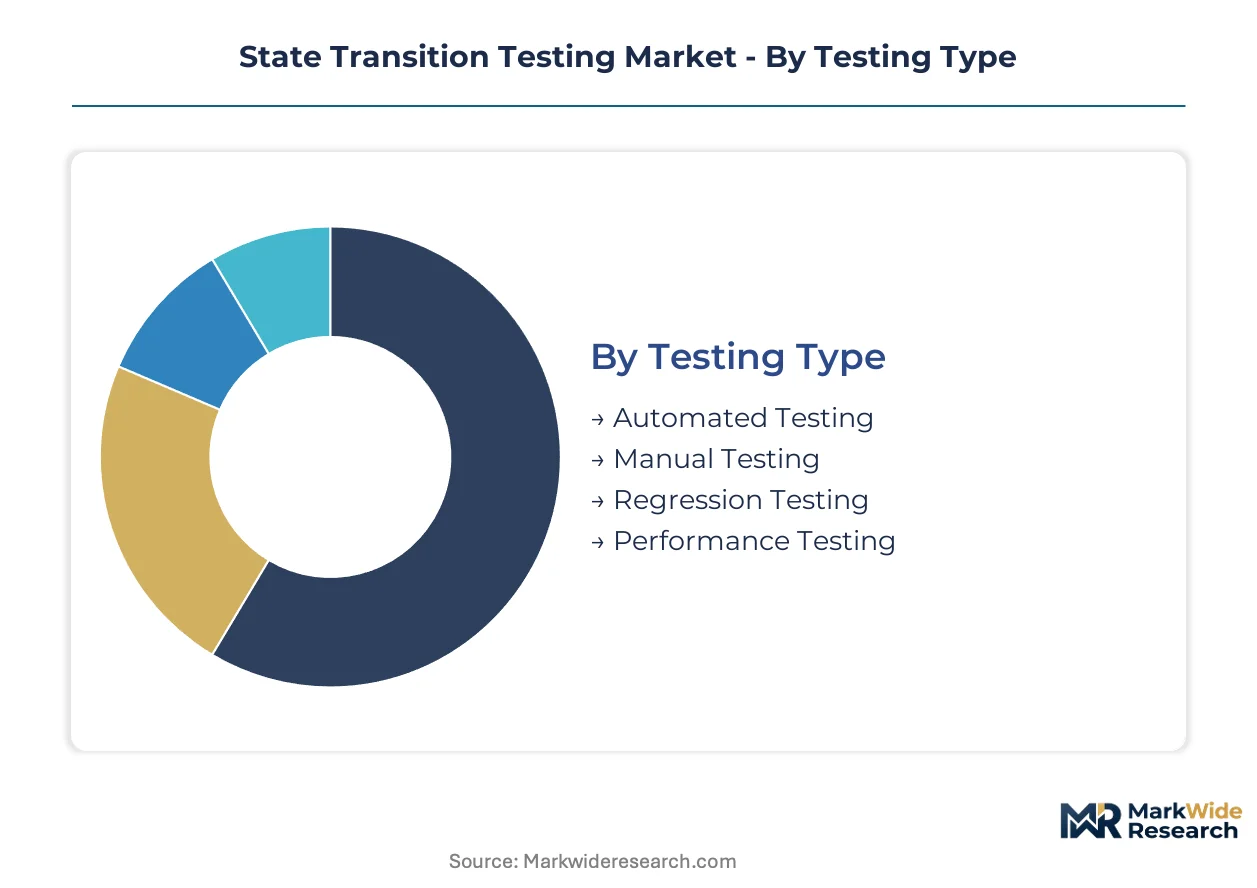
State transition testing procurement patterns diverge sharply across tooling sophistication, application architecture, and regulatory exposure. Segment boundaries determine pricing power, contract duration, and vendor selection criteria in aerospace, automotive, and federal IT verticals.
Testing Type:
Upgrade cycles compress as AI-assisted synthesis displaces manual test case generation, forcing recalibration of license renewal timing and service contract structures.
- Automated Testing:Recurring license structures dominate revenue pools, with model-checking engines and property-based frameworks anchoring multi-year enterprise agreements. DO-178C mandates in US aerospace procurement and BSI IT-Grundschutz requirements in German federal systems sustain premium pricing tiers.
- Manual Testing:Labor-intensive test case authoring faces margin compression as AI-generated synthesis tools penetrate QA consultancies. Prague and Bangalore delivery centers absorb residual demand for brownfield SCADA systems lacking instrumentation hooks.
- Regression Testing:CI/CD pipeline embedding accelerates contract velocity with DevSecOps teams.
- Performance Testing:Hardware-in-the-loop dependencies constrain remote delivery for embedded validation.
Automated Testing sits at the top of the volume ranking, with Regression Testing climbing the fastest.
Application Domain:
Margin profiles stratify by hardware dependency and certification burden, with safety-critical embedded workloads commanding durable pricing premiums.
- Embedded Systems:Hardware-software integration requirements in automotive ECU and avionics firmware create captive demand pools. Bosch and Continental validation teams maintain exhaustive state coverage for over-the-air update pipelines in electric vehicles.
- Cloud Services:Distributed architectures proliferate across federal and financial services deployments. BSI IT-Grundschutz mandates in Germany and Basel III operational risk requirements in UK banking concentrate procurement among Bundesdruckerei and Tier 1 London institutions.
- Web Applications:Shift-left practices embed state checks into GitLab and Jenkins touchpoints.
- Mobile Applications:Fragmented device matrices compress per-project margins.
Embedded Systems commands the largest contract values, while Cloud Services gains share fastest.
Deployment Model:
Security classification and data residency rules partition procurement between sovereign infrastructure and elastic cloud capacity.
- On-Premises:Air-gapped environments dominate defense and classified aerospace workloads. FAA-certified toolchains for flight control verification require physical isolation from external networks.
- Cloud-Based:Elastic capacity attracts SaaS-native development teams in fintech and healthtech. GDPR and EU AI Act documentation requirements drive German automotive OEMs toward ISO 26262-8 compliant hosted environments.
- Hybrid:Split architectures accommodate sensitive model files alongside scalable execution.
- Dedicated Hosting:Single-tenant infrastructure satisfies financial services audit requirements.
On-Premises retains the highest average contract value, with Cloud-Based deployment expanding most quickly.
End User Sector:
Regulatory density and safety-critical exposure determine procurement sophistication, with federal mandates creating non-discretionary demand.
- Aerospace:DO-178C compliance mandates formal verification protocols for Boeing, Lockheed Martin, and Tier 1 avionics suppliers. Toulouse and Seattle engineering centers pilot property-based testing for flight software certification.
- Healthcare:FDA 21 CFR Part 820 and software-as-a-medical-device regulations create unmet validation demand for insulin pump and infusion controller firmware.
- IT Services:Unbundled procurement separates test design from execution across Eastern European implementation houses.
- Telecommunications:5G network function virtualization introduces state complexity at scale.
Aerospace leads sectoral spending, with Healthcare showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates federal cloud validation demand under BSI mandates, while the United States anchors aerospace certification workflows through FAA-directed procurement channels.
United States
DO-178C compliance requirements from the FAA create non-discretionary procurement pull for flight control software verification. Boeing and Lockheed Martin engineering centers in Seattle and Fort Worth sustain multi-year validation contracts. Toulouse-based Airbus subsidiaries in Mobile, Alabama replicate European certification protocols for US-assembled narrow-body programs.
Germany
BSI IT-Grundschutz mandates documented state validation for federal cloud deployments, concentrating demand among Bundesdruckerei and defense IT contractors. ISO 26262-8 compliant toolchains dominate automotive procurement from Munich and Stuttgart OEMs. Berlin-based QA consultancies absorb overflow from Frankfurt financial services Basel III operational risk programs.
United Kingdom
Basel III operational risk frameworks require independent model validation for Tier 1 London banks, unbundling test design from execution across vendor relationships. The Financial Conduct Authority's operational resilience directives elevate state-based documentation for critical payment infrastructure. Edinburgh and Manchester delivery centers capture implementation work displaced from higher-cost capital markets teams.
India
Bangalore and Hyderabad test centers absorb residual manual test case generation for brownfield SCADA systems lacking instrumentation automation. The country's national software services regulator emphasizes export-oriented compliance capabilities for European automotive and aerospace clients. Pune validation labs specialize in hardware-in-the-loop dependencies for embedded firmware regression cycles.
France
Toulouse aerospace clusters pilot property-based testing frameworks for flight software verification under EASA-aligned certification pathways. REACH chemical safety assessments converge with EU AI Act documentation requirements for industrial process control systems. Paris AI labs prepare conformity pipelines for high-risk autonomous decision system classifications.
State Transition Testing Market Competitive Environment
Top-tier vendors anchor multi-year enterprise agreements in regulated industries, while mid-tier consultancies compete on delivery velocity and geographic proximity. The vendor base stratifies across automated tooling licensors, model-driven engineering specialists, and pure-play QA implementation houses. Two strategic archetypes dominate: heritage technology conglomerates leveraging installed-base relationships, and focused engineering boutiques capturing architectural visualization segments. Competitive moves concentrate on unbundling procurement relationships and embedding validation checks into CI/CD pipeline touchpoints.
Within the heritage conglomerate tier, IBM Corporation occupies a position exemplifying enterprise software heritage leveraged for high-value regulated industry contracts. Sparx Systems Pty Ltd represents the model-driven engineering specialist archetype, anchoring architectural visualization toolchains. Tesena s.r.o. exemplifies the focused QA consultancy model, sitting within Central European delivery center networks that absorb implementation work from Western advisory practices.
| Leading Market Players |
|---|
| Ideyatech, Inc. |
| tesena s.r.o. |
| DeRisk QA |
| Sparx Systems Pty Ltd. |
| Prezi Inc. |
| Intertek Group plc |
| Stratfor Enterprises, LLC |
| RiseSmart, Inc. |
| IBM Corporation |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up QA specialists in Prague and Bangalore anchor supply-side discipline through labor-cost arbitrage, compressing project-based pricing for manual test case generation while preserving premium tiers for DO-178C-certified automated suites. This ownership pattern concentrates pricing power among heritage tool vendors who control recurring license structures for model-checking engines.
Pricing Analysis
The bundled-vs-unbundled service split stratifies pricing across the State Transition Testing landscape. Enterprise-grade automated testing suites command subscription-based recurring revenue anchored by DO-178C and BSI IT-Grundschutz certification requirements, while unbundled manual implementation services face margin erosion from AI-assisted synthesis tools. Price differentiation rests on certification grade and geographic delivery cost, with FAA-validated toolchains sustaining premium positioning against commodity QA labor in Eastern European delivery centers. Cost compression in manual testing intensifies as property-based testing frameworks displace handcrafted test vectors. Mid-tier consultancies exhibit highest price sensitivity due to tool license stacking burdens from IBM and Cadence model-checking suites.
Supply Chain Analysis
Certification and qualification gating concentrates supply among Germany, the United States, and India as dominant validation service hubs. German automotive OEMs and federal IT contractors anchor demand for ISO 26262-8 compliant toolchains, while US aerospace procurement channels feed Seattle and Fort Worth engineering centers. The supply chain draws from specialized finite state machine expertise, formal methods training pipelines, and hardware-in-the-loop ECU access for embedded validation. Single-source vulnerability runs through concentrated model-checking engine licensors. Distribution runs through direct enterprise sales for automated suites and unbundled subcontracting networks for implementation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Western advisory premiums and Eastern European implementation costs, exploiting the gap between FAA-mandated certification complexity and available formal methods talent in Prague and Bangalore delivery centers.
For Market Incumbents: Deploy certification-depth moats by embedding DO-178C and BSI IT-Grundschutz validation protocols directly into CI/CD pipeline touchpoints, displacing late-stage manual review. Consolidate around model-driven engineering toolchains that anchor architectural visualization segments against AI-generated test synthesis entrants. Lock in multi-year enterprise agreements with Boeing and Bundesdruckerei through recurring license structures that exclude mid-tier bidders. For New Entrants and Emerging Players: Begin with healthcare software-as-a-medical-device validation, where FDA 21 CFR Part 820 creates unmet demand for state-based safety documentation in insulin pump and infusion controller firmware. Target Paris and Munich AI labs preparing EU AI Act conformity pipelines for high-risk autonomous decision systems. Pursue partnership-led go-to-market with DevSecOps platform vendors embedding automated state transition gates at GitLab and Jenkins integration points. For Investors and Strategic Acquirers: Enterprise software conglomerates with installed-base relationships in regulated industries represent the most active acquirer category in this space, seeking to bolt on formal verification capabilities. The 5-10 year viability window favors targets with captive FAA or BSI certification credentials rather than commodity QA labor arbitrage. Monitor AI-generated test case synthesis penetration rates as the inflection signal for labor intensity assumptions and service pricing model durability.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding state transition checks into GitLab and Jenkins CI/CD pipelines displaces late-stage manual review cycles. |
| Acquisition of Specialist Firm | Capturing Prague or Bangalore QA consultancies with formal methods talent pipelines addresses hiring bottlenecks. |
| Strategic Partnership | Aligning with Bundesdruckerei or federal IT contractors secures BSI IT-Grundschutz-mandated validation contracts. |
| Product Launch | Introducing property-based testing frameworks targets Toulouse and Seattle aerospace suppliers piloting flight software verification. |
| Geographic Expansion | Establishing delivery presence in Stuttgart or Munich captures ISO 26262-8 automotive toolchain procurement. |
Study Parameters
Direct dialogue with test automation architects, QA consultancy principals, avionics certification leads, and federal IT procurement officers grounded this analysis, cross-referenced against DO-178C directive filings, BSI IT-Grundschutz compliance documentation, SEC 10-K disclosures from heritage software vendors, and EU AI Act draft regulatory texts. Bottom-up segment sizing triangulated against top-down market aggregation across automated testing, manual implementation, and embedded validation service lines.
Bottom-up modeling anchored volume and value outputs across the projection horizon, segmenting by testing type, application domain, deployment model, and end-user sector with additional granularity for regulatory certification tier. CAGRs were derived from segment-level growth trajectories informed by procurement cycle analysis, license renewal timing patterns, and AI-assisted synthesis adoption curves in aerospace and automotive verticals.
Several conditions sit outside the modeled scope, including potential FAA revisions to DO-178C coverage requirements, sudden BSI framework amendments, and disruptive AI capabilities that fully automate formal specification authoring. A model refresh is warranted upon material change in regulatory certification burden or AI-generated test synthesis penetration thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Digital Weighing Machine Market
Test and Measurement
Test Benches Market
Test and Measurement
Battery Testing and Inspection Equipment Market
Test and Measurement
NIR Moisture Analyzers Sales Market
Test and Measurement
AI Inference Hardware Performance Benchmarking Test Systems Market
Test and Measurement
Semiconductor Metrology and Inspection Equipment Market
Test and Measurement
Ultrasonic Testing Equipment Market
Test and Measurement
Rohs Tester Market
Test and Measurement
Automated Optical Inspection Market
Test and Measurement
Global General Purpose Test Equipment (GPTE) Market
Test and Measurement
Automated Calibration-as-a-Service Platforms for Test and Measurement Assets Market
Test and Measurement
Receptacle Tester Market
Test and Measurement
Nanomechanical Testing Market
Test and Measurement
Wafer Inspection Market
Test and Measurement
Surface Inspection Market
Test and Measurement
MEMS and Sensor Performance and Reliability Test Equipment Market