
 Real-Time Spectrum Analysis Market | 2026-2036
Real-Time Spectrum Analysis Market Size, Share, and Industry Trends Forecast 2026-2036
Real-Time Spectrum Analysis Market Analytics
The capability gap between bench-top instrument specialists and software-defined radio challengers is bifurcating competitive investment patterns across the real-time spectrum analysis sector. Keysight Technologies leverages decades of microwave measurement heritage to sustain premium positioning in calibration-dependent aerospace applications. Rohde & Schwarz GmbH & Co. anchors European defense procurement through ITAR-aligned manufacturing and sovereign supply chains. ThinkRF Corp competes at the edge by specializing in compact, network-deployable monitors for distributed 5G interference hunting.
Real-time spectrum analysis denotes the continuous capture and frequency-domain visualization of electromagnetic signals with minimal gap time, typically achieving probability of intercept above detection thresholds through overlapping FFT processing or digital down-conversion architectures. The technique serves critical functions in telecommunications compliance testing, electronic warfare situational awareness, and broadcast interference remediation. Portable analyzers and software solutions are gaining structural share as field deployment models displace centralized lab workflows across telecommunications and military applications. Machine learning-enhanced detection represents the fastest-expanding technology segment, though FFT-based architectures still dominate installed base economics and service revenue pools.
The FCC governs spectrum allocation and equipment authorization standards in the United States, while the EU AI Act and CE marking frameworks shape product compliance for intelligent signal classification features sold into European markets. Military buyers additionally navigate ITAR and EAR export controls administered by the US Department of State and Commerce, which constrain component sourcing and channel partnerships for dual-use analyzers. Stakeholders must monitor evolving 6G research band designations and corresponding test specification drafts from standards bodies to anticipate capital deployment timing for next-generation measurement platforms.
Market Dynamics
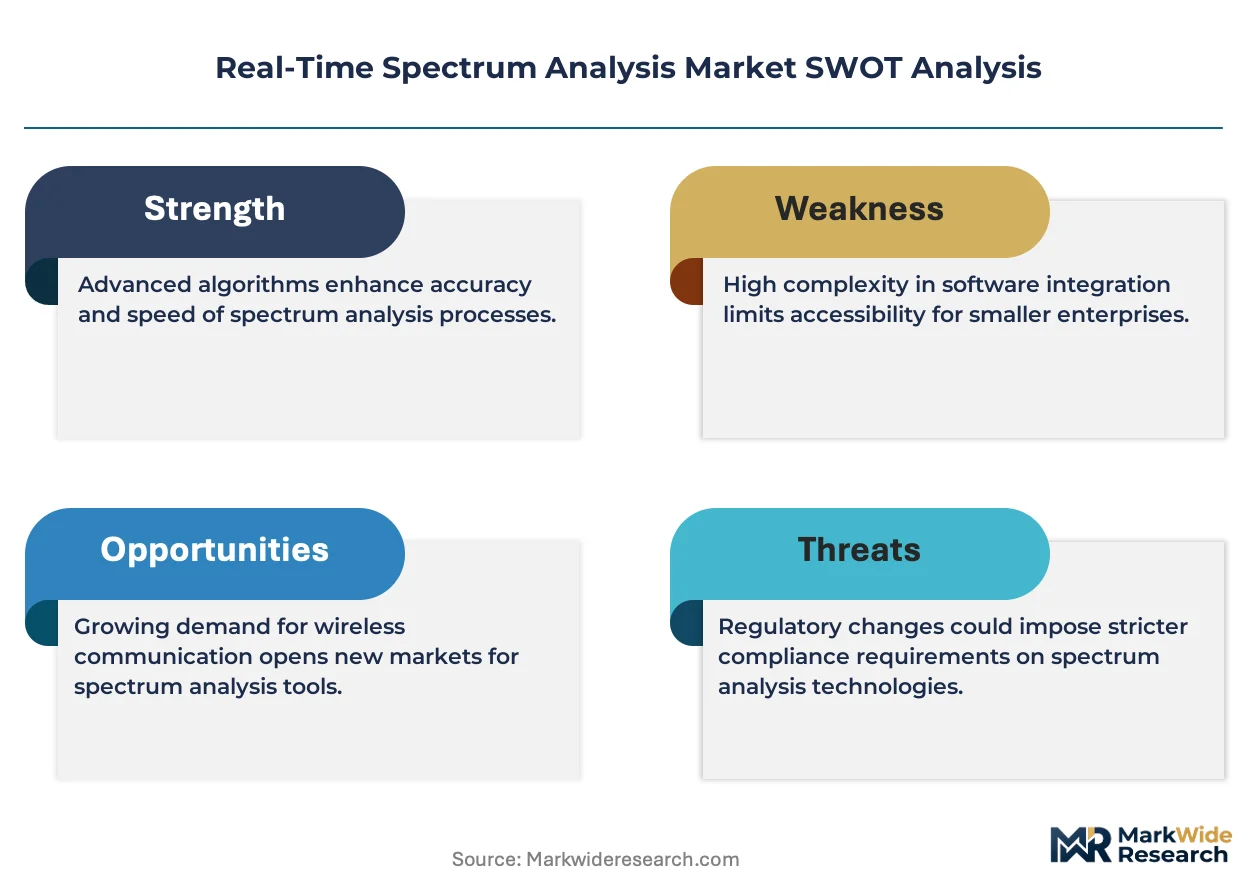
The FCC's spectrum reallocation mandates and 6G research band designations are compressing equipment refresh cycles, forcing test and measurement buyers toward software-defined architectures that decouple hardware from signal processing logic.
Growth Catalysts
- 6G Research Programs:National laboratories in the United States, Germany, and Japan are funding millimeter-wave testbeds that require real-time interference characterization capabilities.
- Electronic Warfare Modernization:Defense procurement across NATO member states prioritizes portable spectrum monitoring for contested electromagnetic environments.
- 5G Network Densification:Mobile operators deploy distributed interference hunting systems to manage co-channel congestion in urban microcell grids.
Market Restraints
- GaN and GaAs Component Concentration:High-frequency frontend modules depend on a narrow supplier base in East Asian foundries, creating single-source vulnerability.
- ITAR Compliance Friction:US State Department export controls restrict dual-use analyzer shipments to non-NATO defense customers, segmenting addressable demand.
- Calibration-Dependent Architectures:Legacy bench-top instruments require periodic recertification that field-deployable software-defined alternatives bypass.
Strategic Opportunities
- India Spectrum Auction Expansion:TRAI's 5G mid-band and 6G preparatory allocations create demand for indigenous test capacity outside traditional vendor strongholds.
- Machine Learning Classification:Converged signal processing and neural inference engines enable autonomous threat detection without human-in-the-loop analysis.
- Subscription-Based Firmware Licensing:Analyzer vendors monetize protocol-specific measurement personalities through recurring revenue rather than perpetual hardware sales.
Industry Challenges
- RF Engineering Talent Scarcity:Microwave circuit design and electromagnetic simulation expertise concentrates in aging workforces at aerospace primes and specialized consultancies.
- Multi-Standard Certification Complexity:Equipment must simultaneously satisfy CE marking, FCC Part 15, and MIL-STD-461G requirements for cross-vertical sales.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Real-Time Spectrum Analysis Market |
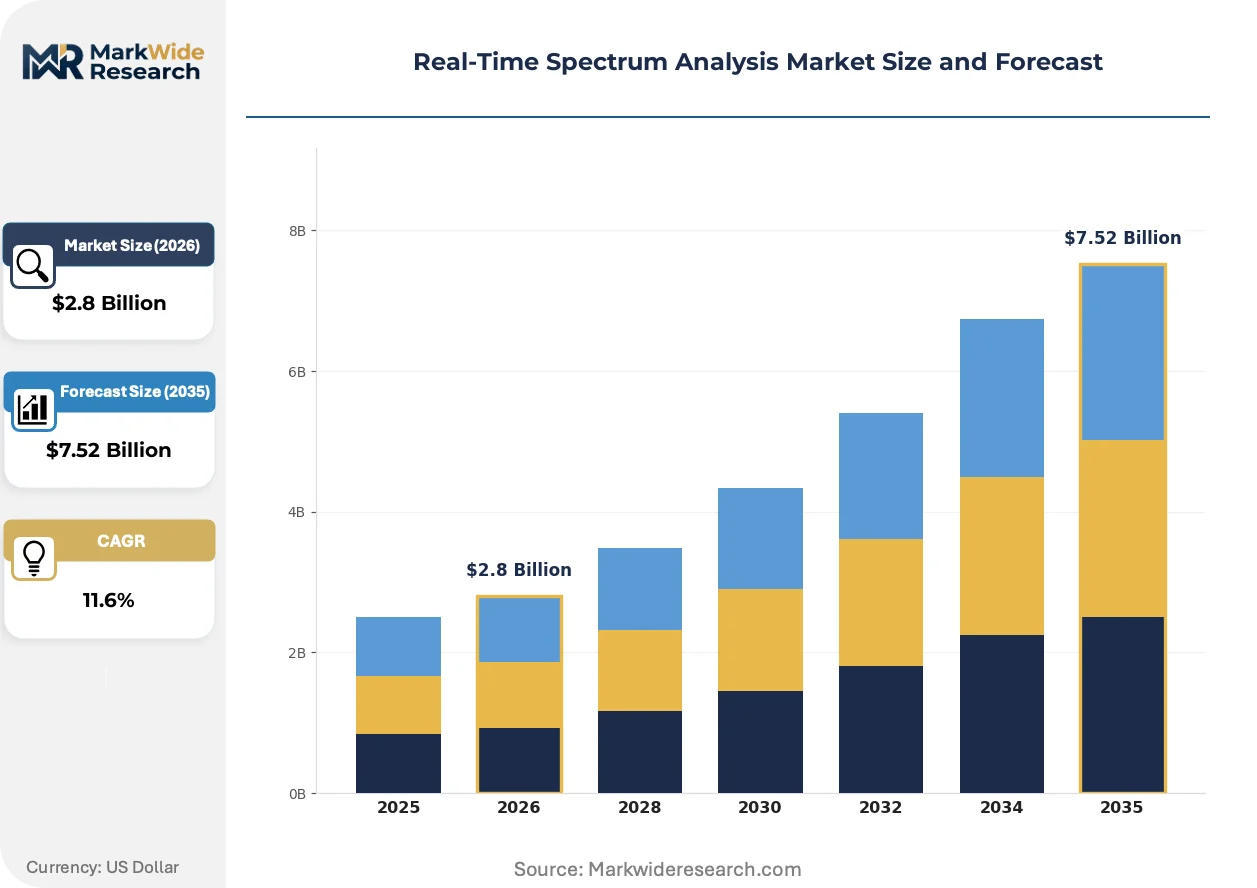
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.52 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Real-Time Analyzers, Spectrum Monitors, Portable Analyzers, Software Solutions Application: Telecommunications, Broadcasting, Military, Research End User: Network Service Providers, Aerospace, Government Agencies, Academic Institutions Technology: FFT, Wavelet Transform, Digital Signal Processing, Machine Learning |
| Companies Covered | Keysight Technologies, Rohde & Schwarz GmbH & Co., Anritsu Corporation, ThinkRF Corp, Tektronix, National Instruments Corporation, Yokogawa Electric Corporation, Advantest Corporation, Signal Hound, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Real-Time Spectrum Analysis Market Evolving Landscape
Software-defined radio architectures are collapsing the traditional boundary between general-purpose computing and dedicated signal acquisition hardware, redistributing value toward firmware and cloud analytics layers.
Deep learning-enhanced detection engines are displacing threshold-based energy detectors in electronic warfare and telecom compliance applications. Military signal intelligence units in the United States and allied nations now prioritize neural classifiers that identify modulation schemes without prior protocol knowledge. This capability compression is eroding the premium historically commanded by specialized measurement personalities.
The EU AI Act's risk classification framework imposes documentation and conformity assessment obligations on signal classification systems sold into European defense and critical infrastructure markets. Equipment vendors must maintain model provenance records and bias testing protocols that legacy hardware-centric quality systems never required. German and French procurement offices now embed AI Act readiness into technical evaluation criteria for spectrum monitoring tenders.
Telecom operators are unbundling hardware ownership from measurement service delivery, preferring managed spectrum assurance contracts over capital-intensive analyzer purchases. Field deployment teams in South Korea and Japan lease portable monitoring capacity from specialized service providers who maintain pooled equipment fleets. This consumption-pattern shift favors vendors with remote diagnostics and over-the-air calibration capabilities.
Real-Time Spectrum Analysis Market Segmentation
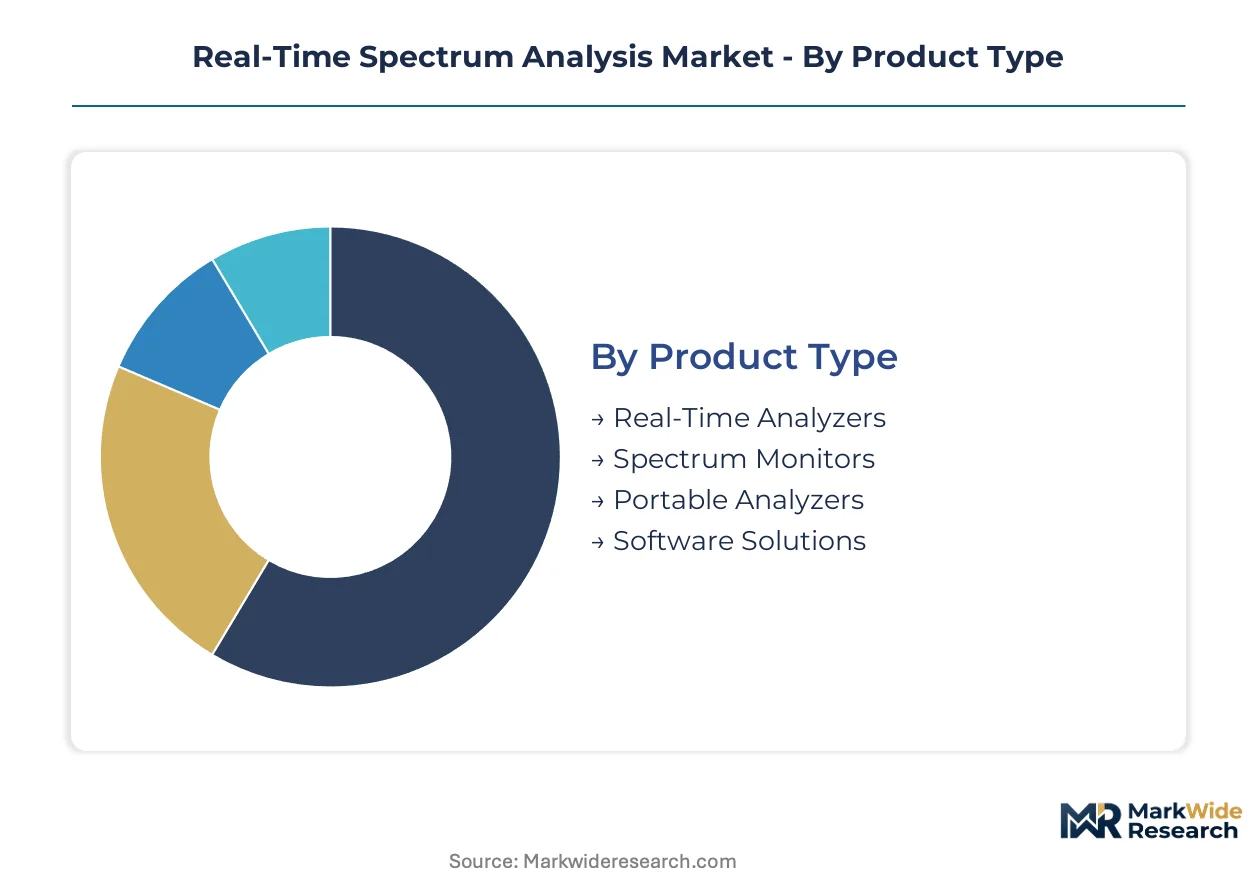
Real-time spectrum analysis equipment exhibits divergent substitution pressures across hardware-software boundaries and price-performance tiers. Procurement patterns fragment between bench-top instrument refresh cycles and distributed software-defined deployments.
Product Type:
Portable analyzers and software solutions face the strongest substitution threat from smartphone-based SDR peripherals and cloud-native signal processing platforms.
- Real-Time Analyzers:Bench-top instruments with overlapping FFT architectures achieve probability of intercept above detection thresholds for electronic warfare applications. Defense procurement in the United States and Germany sustains premium positioning despite calibration-dependent maintenance burdens.
- Spectrum Monitors:Fixed-installation units for broadcast and telecom compliance testing concentrate in urban microcell grids across Japan and South Korea. Network densification mandates from regulators like Japan's MIC and South Korea's MSIT accelerate refresh cycles.
- Portable Analyzers:Battery-powered units with field-replaceable frontends displace centralized lab workflows.
- Software Solutions:Protocol-specific measurement personalities monetize through subscription licensing rather than perpetual sales.
Real-time analyzers anchor the volume base while software solutions gain share at the steepest rate.
Application:
Cost tier stratification separates capital-intensive military deployments from operational expenditure-driven telecom managed services.
- Telecommunications:5G interference hunting and 6G testbed characterization drive demand for millimeter-wave capable platforms. Mobile operators in Germany and Japan lease monitoring capacity from specialized service providers rather than owning equipment fleets.
- Military:Electronic warfare modernization programs across NATO member states prioritize portable spectrum monitoring for contested electromagnetic environments. ITAR compliance friction segments addressable demand for dual-use analyzers.
- Broadcasting:Regulatory compliance mandates from the FCC and national regulators sustain replacement demand.
- Research:National laboratory funding for millimeter-wave testbeds in the United States, Germany, and Japan requires real-time interference characterization.
Telecommunications commands the largest revenue pool while military applications deliver the highest margin contribution.
End User:
Customer type determines procurement modality, with government agencies favoring sovereign supply chains and academic institutions prioritizing cost-flexible licensing.
- Government Agencies:Defense and spectrum regulatory bodies mandate ITAR-aligned manufacturing and domestic component sourcing. The FCC's equipment authorization standards and EU AI Act risk classifications impose documentation burdens on signal classification systems.
- Network Service Providers:Mobile operators in South Korea and Japan unbundle hardware ownership from measurement service delivery. Managed spectrum assurance contracts favor vendors with remote diagnostics capabilities.
- Aerospace:Prime contractors concentrate RF engineering expertise in aging workforces, creating capability scarcity.
- Academic Institutions:Research funding for 6G preparatory work drives demand for software-defined architectures.
Government agencies dominate absolute spending while network service providers are shifting fastest toward as-a-service consumption models.
Technology:
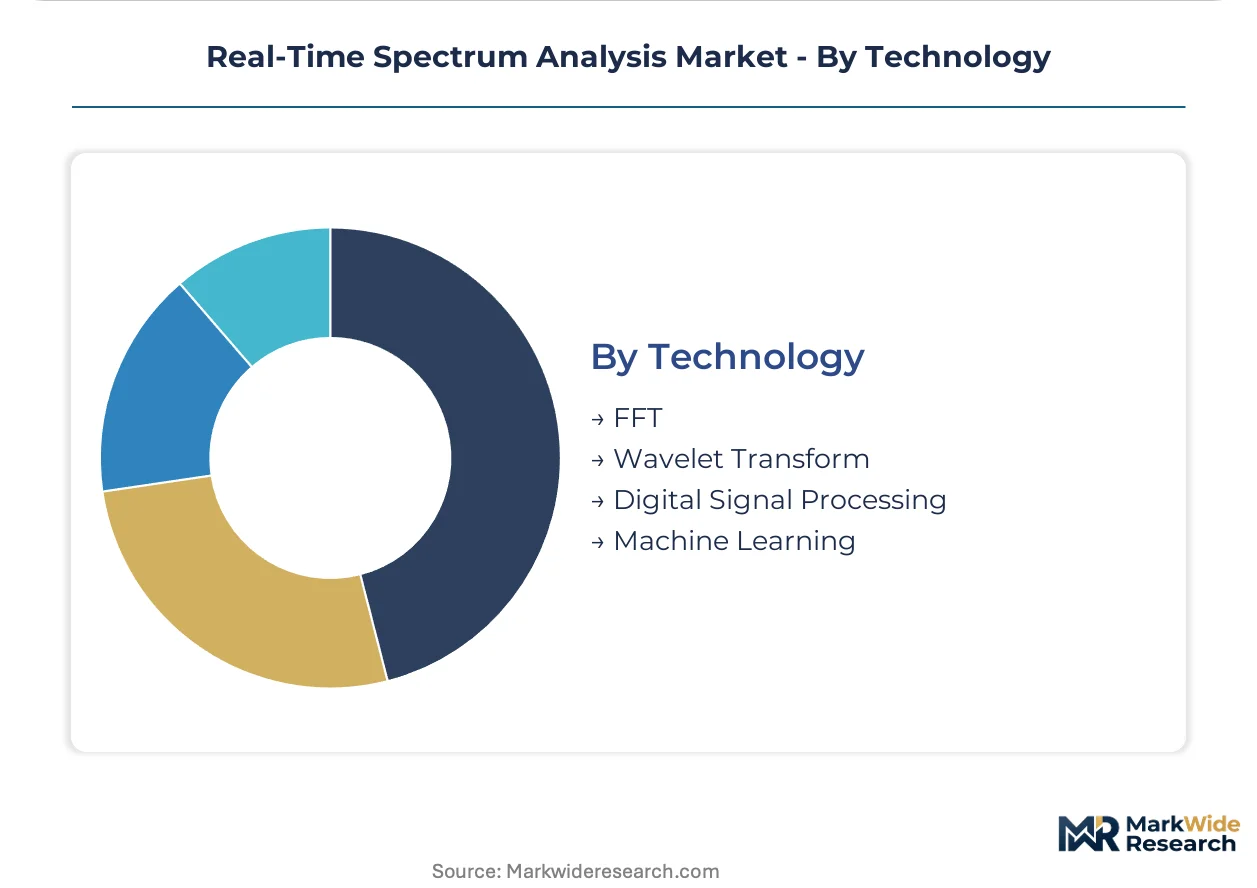
Technology maturity curves separate legacy FFT dominance from emerging machine learning inference integration.
- FFT:Fast Fourier Transform architectures still dominate installed base economics and service revenue pools through overlapping processing techniques. Legacy bench-top instruments require periodic recertification that field-deployable alternatives bypass.
- Machine Learning:Neural classifiers identify modulation schemes without prior protocol knowledge, eroding premiums historically commanded by specialized measurement personalities. The EU AI Act imposes model provenance and bias testing obligations on European defense sales.
- Digital Signal Processing:Software-defined radio architectures redistribute value toward firmware layers.
- Wavelet Transform:Time-frequency analysis methods serve niche transient signal detection applications.
FFT technology anchors current revenue while machine learning represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Telecom operators in Germany and Japan accept premium pricing for sovereign-manufactured equipment, while Indian and Brazilian buyers prioritize cost-flexible software-defined alternatives. Defense procurement in the United States shows lowest price elasticity, with ITAR compliance requirements insulating domestic vendors from margin compression.
United States
Defense agencies expand procurement of real-time spectrum monitoring systems for electronic warfare and signal intelligence operations. The FCC's spectrum reallocation mandates and 6G research band designations accelerate equipment refresh cycles among test and measurement buyers. National laboratories in California and Massachusetts fund millimeter-wave testbeds requiring real-time interference characterization capabilities.
Germany
Rohde & Schwarz and regional defense contractors anchor a dense cluster of RF technology development in Munich and surrounding Bavaria. The EU AI Act's risk classification framework imposes documentation obligations on signal classification systems sold into defense tenders. ITAR-aligned manufacturing and sovereign supply chains sustain premium positioning in European procurement.
Japan
Mobile operators deploy distributed interference hunting systems to manage co-channel congestion in Tokyo and Osaka microcell grids. Japan's MIC issues network densification mandates that accelerate refresh cycles for fixed-installation spectrum monitors. National research programs in the Kanto region fund 6G preparatory testbeds requiring millimeter-wave measurement platforms.
South Korea
Field deployment teams in Seoul and Busan lease portable monitoring capacity from specialized service providers who maintain pooled equipment fleets. The country's spectrum regulator drives managed spectrum assurance contracts that favor vendors with remote diagnostics capabilities. Machine learning-enhanced detection engines gain traction in telecom compliance applications nationwide.
India
TRAI's 5G mid-band and 6G preparatory allocations create demand for indigenous test capacity outside traditional vendor strongholds. Price-sensitive buyers in Bangalore and Hyderabad prioritize software-defined architectures that decouple hardware from signal processing logic. Academic institutions drive research funding for protocol-agnostic neural classifiers.
Real-Time Spectrum Analysis Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with heritage instrument manufacturers commanding premium positioning in calibration-dependent aerospace applications while software-defined radio challengers compete at the edge on deployment flexibility. The vendor base stratifies across three tiers: established measurement specialists with decades of microwave heritage, regional defense contractors with sovereign supply chain alignment, and compact monitor specialists targeting distributed 5G interference hunting. Consolidation pressure concentrates among mid-scale players lacking either deep calibration IP or software-defined agility. Dominant competitive moves include strategic partnerships for AI-enhanced detection capabilities and geographic expansion into spectrum auction expansion markets.
Within the heritage instrument tier, Keysight Technologies and Rohde & Schwarz GmbH & Co. occupy positions sustained by decades of microwave measurement heritage and ITAR-aligned manufacturing respectively. ThinkRF Corp exemplifies the compact monitor archetype, specializing in network-deployable form factors for distributed deployment models. These three companies represent the competitive poles around which procurement patterns fragment between premium aerospace applications and cost-flexible field deployments.
| Leading Market Players |
|---|
| Keysight Technologies |
| Rohde & Schwarz GmbH & Co. |
| Anritsu Corporation |
| ThinkRF Corp |
| Tektronix |
| National Instruments Corporation |
| Yokogawa Electric Corporation |
| Advantest Corporation |
| Signal Hound |
| Others |
Value Network & Pricing Analysis
Capacity utilization at GaN and GaAs foundries in Taiwan and Japan creates asymmetric pricing power between RF frontend suppliers and downstream analyzer assemblers, compressing margins for hardware vendors while elevating returns on firmware and service layers. Scale concentration in East Asian semiconductor fabrication anchors price floors for high-frequency instruments, forcing tiered positioning strategies across calibration-dependent bench-top systems and software-defined alternatives.
Pricing Analysis
Service contract attach rates and calibration recertification revenue sustain lifetime value for heritage instrument vendors serving aerospace primes and defense agencies. Pricing stratifies across premium ITAR-aligned systems, standard CE-marked commercial units, and economy-tier software-defined monitors targeting field deployment. Cost compression in the economy tier intensifies because smartphone-based SDR peripherals erode entry-level hardware premiums. Academic institutions and Indian test houses exhibit highest price sensitivity, while United States defense procurement shows lowest elasticity due to sovereign sourcing mandates.
Supply Chain Analysis
Strategic stockpiling of GaN-on-SiC wafers and precision ADC components characterizes procurement behavior among Tier 1 analyzer vendors, contrasting with just-in-time preferences for commodity compute hardware. Frontend module production concentrates in Taiwan, Japan, and the United States, drawing from specialized epitaxial growth and compound semiconductor foundries. Single-source vulnerability in millimeter-wave MMIC supply creates exposure to export control restrictions and foundry allocation constraints. Distribution runs through authorized channel partners for defense-qualified instruments, while software solutions deploy via direct cloud provisioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among managed service providers and sovereign procurement offices, fragmenting demand between as-a-service consumption and ITAR-governed direct sales. This consolidation among intermediaries reshapes vendor access to end-user relationships.
For Market Incumbents: Secure firmware update infrastructure and remote diagnostics capabilities to defend recurring revenue streams against software-defined challengers. Deepen backward integration into GaN frontend design to reduce foundry dependency and protect margin structure from component cost volatility. Channel control through authorized service networks remains critical as telecom operators consolidate procurement through specialized spectrum assurance contractors. For New Entrants and Emerging Players: Differentiate on AI-enhanced signal classification to bypass the calibration IP moats of heritage instrument vendors. Target India's spectrum auction expansion and academic 6G testbed funding as the most penetrable demand pockets outside NATO defense strongholds. A protocol-agnostic neural classifier go-to-market angle unlocks research institution budgets and positions for subsequent telecom compliance certification. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compact monitor specialists with software-defined architectures and established channel relationships in Asian telecom markets. Long-term viability hinges on recurring revenue conversion and AI Act compliance infrastructure for European defense sales. The signal to watch is 6G research band designation timing from national regulators, which triggers capital deployment cycles for next-generation measurement platforms.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enhanced Detection Partnership | Neural classifier integration addresses EU AI Act documentation requirements for European defense tenders. |
| Sovereign Manufacturing Expansion | ITAR-aligned production facilities capture United States defense procurement insulated from import competition. |
| Subscription Firmware Licensing | Protocol-specific measurement personalities monetize through recurring revenue rather than perpetual hardware sales. |
| Remote Diagnostics Platform | Over-the-air calibration capabilities align with South Korean and Japanese managed spectrum assurance contracts. |
| Millimeter-Wave Frontend Development | GaN-on-SiC module design reduces foundry dependency for 6G testbed characterization demand. |
Research Methodology
Desk research of FCC equipment authorization databases, ITAR compliance filings, and standards body specification drafts preceded structured interviews with RF test engineering directors, defense procurement officers, and telecom network operations leads. Primary fieldwork with spectrum monitoring system integrators and semiconductor foundry account managers combined with secondary validation against EAR export control classifications and EU AI Act technical documentation requirements. Bottom-up equipment shipment analysis and top-down defense budget allocation triangulation anchored market sizing.
Variance decomposition across product type, application vertical, technology architecture, and geographic procurement cluster shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include hardware-software deployment mode, end-user procurement modality, and regulatory compliance tier. CAGRs derived from equipment refresh cycle compression rates and research funding trajectories, with millimeter-wave testbed deployment timelines and spectrum auction schedules as key forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained 6G research funding levels or stable ITAR regulatory frameworks would require recalibration. Forecasts reflect assumptions regarding foundry capacity expansion and AI Act implementation timelines. Revision becomes warranted when GaN frontend supply constraints or neural classifier certification delays cross thresholds that alter equipment refresh cycle economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Kinetic Chromogenic Spectrophotometer Market
Analytical Instruments
Automatic Polarimeter Market
Analytical Instruments
Analytical Instrumentation for Food Applications Market
Analytical Instruments
Digital Vernier Caliper Market
Analytical Instruments
Laser-Based Gas Analyzers Market
Analytical Instruments
Global TOC Analyzer Market
Analytical Instruments
3D Touch Probe Market
Analytical Instruments
Automated Microplate Handling Systems Market
Analytical Instruments
Infrared Spectroscopy Devices Market
Analytical Instruments
TDLAS Moisture Analyzers Market
Analytical Instruments
Middle East and Africa Dissolved Gas Analyzer Market
Analytical Instruments
Ultraviolet (UV) Analyzer Market
Analytical Instruments
Logic Analyzer Market
Analytical Instruments
Portable Particle Counter Market
Analytical Instruments
Global Electron Microscopy and Sample Preparation Market
Analytical Instruments
Wireless Handheld Spectrometer Market