
 Submarine Communication Cables Market | 2026-2036
Submarine Communication Cables Market Size, Share, and Industry Trends Forecast 2026-2036
Submarine Communication Cables Market Outlook
Silica-core fiber is restructuring submarine cable economics by displacing legacy copper conductors in long-haul deployments. SubCom LLC leverages integrated marine installation assets to control project timelines from factory to seabed. NEC Corporation anchors its position through deep-water repeater technology developed at its Yokohama laboratories. Alcatel Submarine Networks dominates Atlantic corridor routes with manufacturing scale across its Calais and Greenwich facilities.
Submarine communication cables are armored fiber optic assemblies, typically comprising polyethylene sheathing, steel wire armor, and gel-filled copper tubes housing optical fibers, designed to transmit data across oceanic distances at terabit-per-second capacities. Fiber optic cables command the largest share of new installations due to their bandwidth scalability and signal integrity over transoceanic spans. Internet data transmission applications are expanding fastest as hyperscale data centers demand dedicated private cable systems. Shallow water installations remain the most mature segment with established trenching methods and predictable permitting.
The International Cable Protection Committee coordinates seabed corridor standards while national regulators including the FCC in the United States and Ofcom in the United Kingdom govern landing station licensing and data sovereignty compliance. China's MIIT and SAMR enforce domestic content requirements for cables landing within territorial waters. Stakeholders must monitor evolving seabed mining claims and exclusive economic zone designations that threaten existing cable routes.
Market Dynamics
Cloud service providers are consolidating procurement power through dedicated private cable systems, compressing traditional carrier consortium models and rewiring supplier-customer relationships across transoceanic routes.
Growth Catalysts
- Hyperscale data center expansion:Amazon Web Services, Microsoft Azure, and Google Cloud are commissioning proprietary cable systems to secure low-latency capacity between continental hubs, bypassing legacy carrier intermediaries.
- MIIT domestic content mandates:China's Ministry of Industry and Information Technology requires local manufacturing participation for cables landing in territorial waters, stimulating indigenous supply chain development.
- Silica-core fiber scalability:Single-mode fiber designs now support multi-terabit transmission per fiber pair, enabling capacity upgrades without additional seabed infrastructure.
Market Restraints
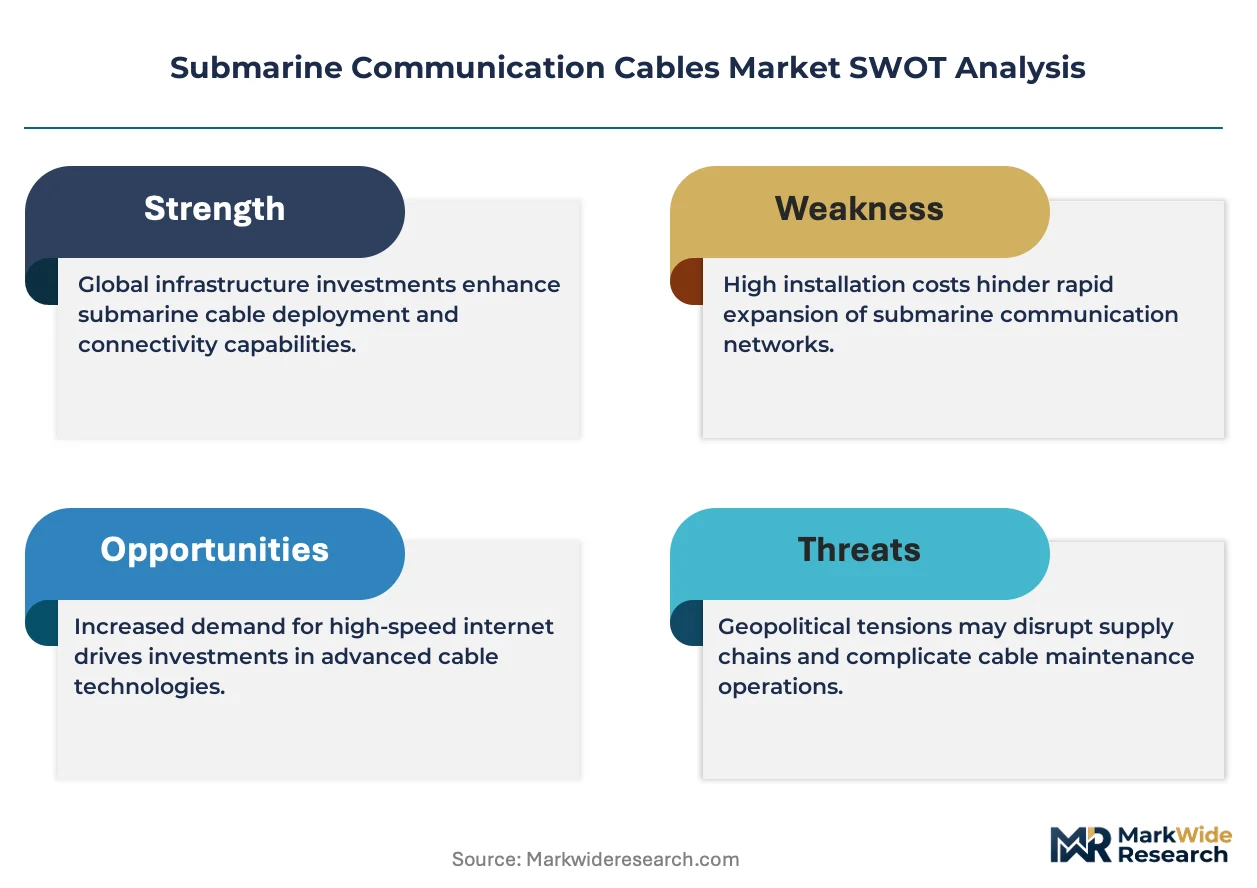
- Specialized vessel scarcity:Cable-laying ships number fewer than sixty worldwide, with shipyard backlogs extending deployment timelines for new systems.
- Copper price volatility:Power conductor requirements in repeater-fed systems expose projects to commodity swings that distort project economics.
- Exclusive economic zone fragmentation:Coastal nations are asserting seabed jurisdiction over established corridors, threatening route continuity and insurance coverage.
Strategic Opportunities
- Arctic route activation:Melting ice conditions are opening shorter paths between Europe and Asia, reducing latency for financial trading applications.
- Offshore wind farm integration:Cable manufacturers can bundle fiber infrastructure with power transmission to North Sea wind installations, capturing dual-revenue streams.
- CE marking harmonization:European Union standardization of marine equipment certification is reducing cross-border compliance friction for Atlantic corridor projects.
Industry Challenges
- Submarine splicing technician shortage:Deep-water fiber repair requires specialized skills that training programs have failed to replenish as veteran technicians retire.
- Permitting timeline compression:FCC environmental review and state coastal commission approvals for US landing stations now extend eighteen to thirty-six months, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Submarine Communication Cables Market |
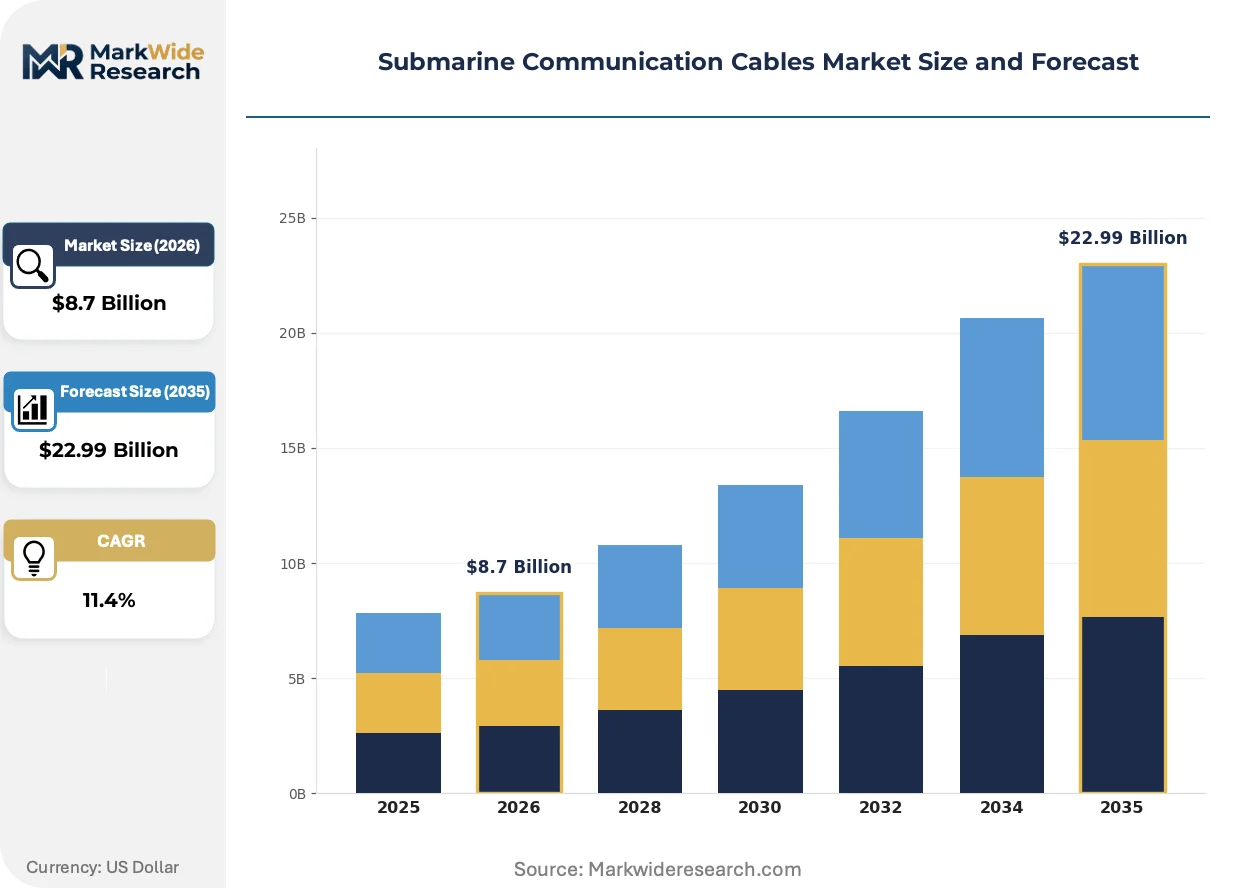
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber Optic Cables, Copper Cables, Hybrid Cables, Submarine Repeaters Application: Telecommunication, Internet Data Transmission, Military Communication, Oil & Gas Monitoring Installation Type: Shallow Water, Deep Water, Moderate Water, Coastal Waters End User: Telecommunication Companies, Government Agencies, Oil Companies, Research Institutions |
| Companies Covered | SubCom LLC, NEC Corporation, Alcatel Submarine Networks, HMN Tech, Nexans S.A., Prysmian Group, Hengtong Marine Cable System, ZTT Group, TE SubCom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Submarine Communication Cables Market Strategic Shifts
Capacity multiplication through spatial division multiplexing and power-efficient amplification is redefining cost-per-bit economics while regulatory pressure on seabed environmental impact intensifies route planning complexity.
Multicore fiber is absorbing investment from traditional single-core designs by multiplying transmission channels within identical cable diameters. SubCom and NEC are deploying seven-core and nineteen-core variants on trans-Pacific routes to defer new cable lays. This technology is absorbing capital that would otherwise fund entirely new seabed systems, stretching replacement cycles and concentrating maintenance revenue among incumbent suppliers.
REACH chemical registration requirements in the European Union are mandating toxicity assessments for cable sheath polymers and anti-biofouling coatings used in shallow-water installations. Manufacturers must reformulate polyethylene compounds to eliminate restricted substances or face market exclusion. The Baltic Sea and North Sea corridors, where EU member state jurisdiction is absolute, are experiencing the most acute compliance-driven procurement delays.
Consortium procurement structures are fragmenting as hyperscale buyers demand sole ownership of dedicated fiber pairs. Traditional carrier alliances that once pooled risk across twelve to fifteen members now compete against two-party private systems. This pattern is most pronounced on trans-Atlantic routes where Google and Meta have displaced legacy telecom operators as anchor tenants, rewriting contract terms and operational control provisions.
Submarine Communication Cables Market Segmentation
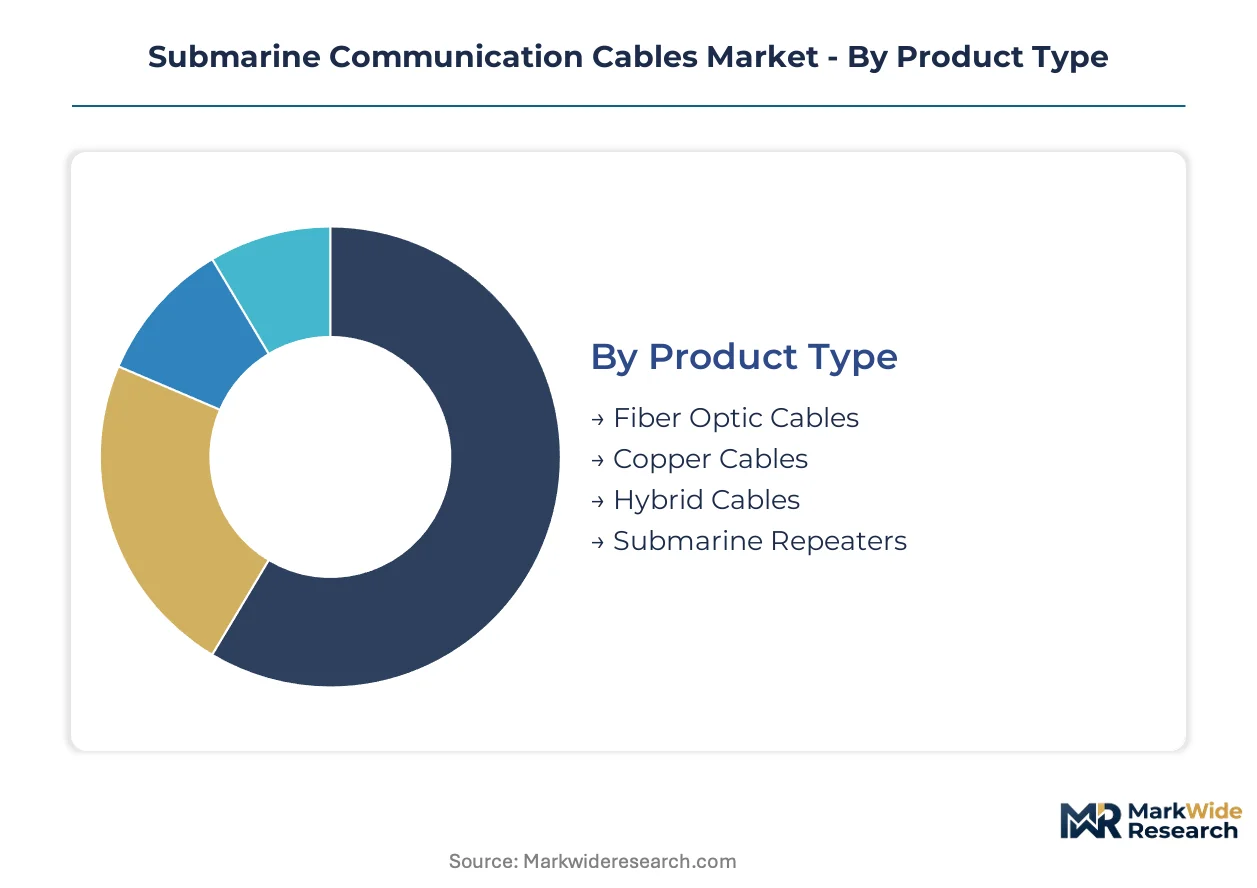
Submarine cable procurement channels diverge sharply by segment, with hyperscale buyers bypassing legacy carrier consortiums and national security applications triggering classified procurement protocols. Certification burdens from FCC, MIIT, and REACH reshape manufacturing priorities across product categories.
Product Type:
FCC Part 68 registration governs repeater electronics landing in United States territorial waters, while REACH compliance dictates sheath polymer formulations for European deployments. MIIT domestic content mandates bifurcate supply chains between China-landing and non-China-landing systems.
- Fiber Optic Cables:Silica-core single-mode designs with polyethylene sheathing and steel wire armor transmit multi-terabit signals across transoceanic distances. Demand concentrates in trans-Pacific routes serving Amazon Web Services and Google Cloud data center interconnects, driven by hyperscale procurement of dedicated private cable systems.
- Submarine Repeaters:Titanium-housed optical amplifiers with copper power conductors restore signal integrity every 50-100 kilometers along seabed routes. NEC Corporation's Yokohama-developed deep-water repeaters anchor procurement for Japan-landing systems, constrained by specialized vessel availability for installation at depths exceeding 6,000 meters.
- Copper Cables:Legacy coaxial constructions with gel-filled copper tubes retain niche military applications requiring electromagnetic shielding.
- Hybrid Cables:Fiber-power composites bundle optical transmission with electrical conductors for offshore oil platform integration.
Leading the category by volume: Fiber Optic Cables. Expanding most quickly: Submarine Repeaters.
Application:
Cost tiers separate commodity bandwidth from mission-critical services, with financial trading latency premiums commanding 10-20x per-bit pricing over standard internet transit.
- Internet Data Transmission:Dedicated fiber pairs on trans-Atlantic routes carry 95% of intercontinental data traffic at terabit-per-second capacities. Meta and Microsoft anchor procurement for private systems between Virginia Beach and Bilbao, displacing traditional carrier consortium structures.
- Telecommunication:Legacy carrier alliances pool risk across consortium members for public cable systems with open capacity leasing. SubCom LLC and Alcatel Submarine Networks dominate Atlantic corridor manufacturing for these multi-tenant deployments.
- Military Communication:NATO and national defense agencies require tamper-evident armoring and encrypted signaling for strategic seabed links.
- Oil & Gas Monitoring:Subsea sensor networks on North Sea platforms bundle fiber telemetry with power transmission for real-time reservoir management.
Steepest expansion trajectory: Internet Data Transmission. Highest margin stability: Military Communication.
Installation Type:
Permitting complexity escalates with water depth, as coastal commissions govern shallow-water trenching while international seabed authority frameworks manage abyssal plain routing.
- Shallow Water:Buried installations to 1,000 meters depth use established plough trenching methods with predictable environmental review timelines. United States Pacific coast landing stations concentrate procurement here, though California Coastal Commission approvals now extend thirty-six months.
- Deep Water:Untrenched surface lays across abyssal plains require dynamic positioning cable ships and remotely operated vehicle splicing. Arctic route activation between Norway and Japan shortens Europe-Asia latency for financial trading applications as ice conditions permit.
- Moderate Water:Continental shelf crossings between 1,000-4,000 meters balance trenching protection with installation economics.
- Coastal Waters:Surf zone landings demand specialized shallow-draft vessels and armored beach manhole terminations.
Greatest installation maturity: Shallow Water. Fastest route development: Deep Water.
End User:
Customer type determines contract structure, with oil companies demanding bundled engineering-procurement-construction terms and research institutions accepting shared-risk consortium participation.
- Telecommunication Companies:Traditional carriers including NTT and Orange retain ownership of legacy consortium systems while ceding anchor tenant status to hyperscale buyers on new routes. Their procurement now concentrates on maintenance and repair services rather than greenfield construction.
- Government Agencies:China's SAMR enforces domestic manufacturing participation for MIIT-licensed cables, stimulating indigenous supply chain development for state-directed projects landing in Qingdao and Shanghai.
- Oil Companies:Equinor and Shell bundle fiber infrastructure with offshore wind power transmission in North Sea developments.
- Research Institutions:Ocean observatory networks including NEPTUNE and MARS accept lower capacity allocations in exchange for co-funding seabed infrastructure.
Dominating procurement volume: Telecommunication Companies. Fastest contract structure evolution: Government Agencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale cloud procurement concentrates cable landing investments in three coastal corridors where data center clusters intersect with submarine fiber routes. FCC environmental review timelines and MIIT domestic content mandates reshape where manufacturers qualify cable systems for deployment. Each major market exhibits distinct regulatory friction and infrastructure maturity.
United States
Virginia Beach and Los Angeles anchor trans-Pacific and trans-Atlantic cable landings serving AWS and Microsoft Azure data centers. FCC Part 68 registration governs repeater electronics while California Coastal Commission approvals now extend thirty-six months for shallow-water trenching permits. SubCom LLC controls manufacturing scale through its New Jersey and Maryland facilities.
China
Qingdao and Shanghai landing stations absorb state-directed investment for state-owned carrier systems and hyperscale private cables. MIIT and SAMR enforce domestic manufacturing participation requirements that stimulate indigenous supply chain development. Hengtong Marine Cable System and ZTT Group anchor production capacity in Jiangsu and Zhejiang provinces.
Japan
Chiba and Kagoshima prefectures concentrate landing infrastructure for transpacific routes connecting Tokyo-Osaka data center corridors. METI coordinates seabed corridor standards with the International Cable Protection Committee while NEC Corporation's Yokohama laboratories develop deep-water repeater technology. Manufacturing clusters in Kanagawa and Shizuoka prefectures supply regional demand.
United Kingdom
Cornwall and Scotland host Atlantic corridor landing stations serving London financial trading latency requirements. Ofcom governs landing station licensing while REACH chemical registration mandates toxicity assessments for cable sheath polymers. Alcatel Submarine Networks maintains manufacturing presence through its Greenwich facility.
France
Calais and Marseille anchor Mediterranean and Atlantic cable systems with manufacturing scale at Alcatel Submarine Networks' northern facility. ANSM and CNIL coordinate with EU seabed authorities on environmental review while CE marking harmonization reduces cross-border compliance friction. The Brittany coast experiences acute permitting delays from marine protected area designations.
Submarine Communication Cables Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated marine installation assets conferring timeline control advantages on transoceanic projects. The vendor base concentrates among three firms controlling manufacturing scale and deep-water technology. Strategic archetypes include integrated marine contractors, component specialists, and state-supported national champions. Competitive moves center on captive cable-laying vessel fleets and regional licensing partnerships that secure landing rights.
Among integrated marine contractors, SubCom LLC exemplifies the archetype of factory-to-seabed project control. NEC Corporation occupies a position within the deep-water technology tier, representing Japanese industrial policy support for indigenous repeater development. Alcatel Submarine Networks anchors European manufacturing presence through its Calais and Greenwich facilities, sitting within the Atlantic corridor specialization archetype.
| Leading Market Players |
|---|
| SubCom LLC |
| NEC Corporation |
| Alcatel Submarine Networks |
| HMN Tech |
| Nexans S.A. |
| Prysmian Group |
| Hengtong Marine Cable System |
| ZTT Group |
| TE SubCom |
| Others |
Value Chain & Pricing Dynamics
Copper price volatility on the London Metal Exchange cascades through submarine cable procurement, amplifying cost differentials between repeater-fed deep-water systems and unpowered coastal fiber runs. MIIT domestic content mandates in China and FCC Part 68 registration requirements in the United States further stratify pricing tiers by imposing compliance premiums on cables landing in regulated territorial waters.
Pricing Analysis
Volume concentrates in commodity internet data transmission contracts while margins pool in military communication and oil & gas monitoring applications. Three-tier pricing structure across premium, standard, and economy levels separates encrypted NATO-specification armoring from commercial fiber pairs and unprotected coastal drops. Pricing pressure stems from hyperscale buyers consolidating procurement power through dedicated private cable systems, compressing carrier consortium premiums. Telecommunication companies exhibit highest price sensitivity due to legacy debt loads on depreciated systems, while cloud service providers prioritize latency guarantees over unit cost.
Supply Chain Analysis
Photonics-grade silica supply rests on Japanese and German specialty chemical producers, with titanium repeater housings drawing from aerospace-qualified foundries in the United States and France. Steel wire armor feeds from South Korean and Chinese metallurgical mills, while polyethylene sheathing compounds hinge on petrochemical complexes along the US Gulf Coast and in the Netherlands. Single-source vulnerability concentrates in cable-laying vessel availability, with fewer than sixty qualified ships worldwide creating deployment bottlenecks. Distribution runs through integrated marine contractors controlling factory-to-seabed project timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized vessel scarcity props pricing power for integrated marine contractors, constraining system deployment capacity and stretching order backlogs across transoceanic routes.
For Market Incumbents: Hedge against hyperscale buyer consolidation by securing long-term maintenance contracts on legacy consortium systems before private cable displacement accelerates. Deepen captive cable-laying vessel fleets to control installation timelines against emerging state-supported competitors from China. Prioritize Arctic route qualification to capture latency premiums from financial trading applications as ice conditions permit. For New Entrants and Emerging Players: Begin with offshore wind farm integration projects in the North Sea, bundling fiber infrastructure with power transmission to capture dual-revenue streams without competing directly on transoceanic routes. Target research institution consortium participation for ocean observatory networks, accepting lower capacity allocations in exchange for co-funding seabed infrastructure and building installation track records. For Investors and Strategic Acquirers: Distressed-cycle entries favor submarine splicing service specialists in Japan and the United Kingdom, where technician retirement waves are creating maintenance capacity gaps. Long-term viability centers on recurring revenue from repair and upgrade cycles rather than greenfield construction exposure. Watch Arctic route permitting acceleration as the inflection signal for latency-sensitive financial trading demand migration.| Strategic Initiative | Industry Significance |
|---|---|
| Cable-Laying Vessel Fleet Expansion | SubCom LLC's integrated marine assets compress project timelines from factory to seabed. |
| Multicore Fiber Technology Deployment | NEC Corporation's nineteen-core variants defer new seabed lays across trans-Pacific routes. |
| Arctic Route Qualification | Shorter Europe-Asia paths capture financial trading latency premiums as ice conditions permit. |
| REACH-Compliant Sheath Reformulation | Alcatel Submarine Networks adapts polyethylene compounds to retain EU market access. |
| MIIT Domestic Content Partnership | Hengtong Marine Cable System secures state-directed procurement for China-landing systems. |
Study Parameters
Document review covered FCC cable landing license databases, MIIT equipment certification registries, and ICPC seabed corridor incident reports, complemented by interviews with cable system procurement directors at hyperscale cloud providers, submarine repeater engineering leads at NEC and Alcatel Submarine Networks, and marine installation project managers at SubCom LLC. Secondary validation drew from customs trade data on fiber optic cable exports, SEC 10-K filings of listed cable manufacturers, and Lloyd's List vessel tracking for cable-laying ship deployments. Bottom-up capacity estimates and top-down demand projections were triangulated to anchor market sizing.
Historical deployment data was cross-referenced against expert panel input from the International Cable Protection Committee and regional regulator consultations. The analytical framework modeled capacity and value across product type, application, installation depth, and end user segments throughout the forecast period. CAGRs were derived from elasticity-adjusted demand curves and supply constraint modeling. Industry-specific forecast inputs included hyperscale data center capex disclosures and ice condition projections for Arctic route viability.
Underlying measurement precision varies by segment; internet data transmission and shallow water installation carry tighter precision than military communication and deep water routes due to disclosed contract values and permitting transparency. Forecasts reflect documented assumptions about vessel availability, regulatory timeline stability, and commodity price bands. Submarine splicing technician supply, exclusive economic zone jurisdiction disputes, and seabed mining claim overlaps warrant ongoing watch as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
GCC Cable Accessories Market
Cables
Insulated Wire and Cable Market
Cables
Cable Detector Market
Cables
South Africa Wire and Cable Market
Cables
High-Temperature Superconducting Cables Market
Cables
Nuclear Multi-Conductor Cables Market
Cables
Wire and Cable Label Market
Cables
India Wire and Cable Market
Cables
Cable Trunking Market
Cables
Patch Cable Market
Cables
Power and Signal Cables Market
Cables
Cable Tags Market
Cables
US Medium Voltage Cable Accessories Market
Cables
Global Low Voltage Cable Market
Cables
Smartphone Type-C Charging and Data Cable Market
Cables
Data Center Wire and Cable Market