
 North America Copper Wire and Cable Market | 2026-2036
North America Copper Wire and Cable Market Size, Share, and Industry Trends Forecast 2026-2036
North America Copper Wire and Cable Market Outlook
A capital-intensity divergence between integrated manufacturers and pure-play distributors is unwinding competitive stability across the North America copper wire and cable landscape. Southwire Company, LLC leverages its vertically aligned rod production and regional distribution density to dominate utility-scale contracts. Prysmian Group anchors its position through submarine and high-voltage specialization, competing aggressively in cross-border transmission corridors.
Copper wire and cable encompasses drawn copper conductors insulated with thermoset or thermoplastic compounds, typically rated between 600V and 35kV depending on application, engineered to transmit electrical power or data signals across industrial, commercial, and residential installations. Building wire occupies the largest volume pool across the product-type dimension, though magnet wire is capturing disproportionate margin expansion from electric motor and transformer reshoring. Within end-user categories, power generation and construction together concentrate the heaviest procurement volumes, while telecommunications infrastructure is shifting specification requirements toward higher-conductivity alloys and fire-resistant jacketing.
The National Electrical Code administered by the National Fire Protection Association governs product standards and installation compliance across the United States, while the Canadian Standards Association and UL Solutions maintain parallel certification regimes that shape cross-border market access. Mexico's national electrical utility standards, aligned with NOM certification requirements, create additional compliance layers for manufacturers serving integrated North American supply chains. Stakeholders must monitor how evolving grid-interconnection standards and building electrification mandates reshape procurement specifications before committing to capacity expansions.
Market Dynamics
Utility-scale renewable interconnection queues are compressing lead times across the North America copper wire and cable market, forcing manufacturers to pre-position inventory before final project approvals.
Growth Catalysts
- The Inflation Reduction Act:Production tax credits for domestic clean energy manufacturing are pulling forward capital commitments for transmission infrastructure across the United States.
- Data center construction:Hyperscale facility buildouts in Texas and Arizona are consuming medium-voltage power cable at volumes previously reserved for utility distribution networks.
- Semiconductor fabrication reshoring:CHIPS Act-funded fabs in Arizona, Texas, and New York are specifying high-purity magnet wire for precision motor and transformer applications.
Market Restraints
- Copper concentrate supply concentration:Smelter capacity constraints in Chile and Peru are transmitting volatility into North American rod pricing.
- LME warehouse inventory depletion:Exchange stock draws in the United States and Europe are narrowing the buffer against spot demand spikes.
- Aluminum substitution in overhead transmission:Utilities in cost-sensitive jurisdictions are specifying ACSR and ACSS conductors for new lines under 230kV.
Strategic Opportunities
- Mexico nearshoring corridor:Appliance and automotive OEMs in Querétaro and Nuevo León are localizing magnet wire procurement to satisfy USMCA content requirements.
- Grid-interconnection standard harmonization:IEEE 1547-2018 compliance mandates are opening specification windows for advanced power cable with integrated monitoring.
- Fire-resistant jacketing convergence:NFPA 70 National Electrical Code updates are creating pull for low-smoke zero-halogen compounds in commercial high-rise construction.
Industry Challenges
- Master electrician pipeline constriction:Journeyman certification backlogs in Texas and California are extending installation timelines for utility-scale projects.
- UL 1072 MV-105 certification queue:Third-party testing laboratory capacity limits are stretching medium-voltage product approval cycles.
- Legacy extrusion equipment retooling:Cross-linked polyethylene line conversions for tree-retardant formulations require extended downtime at regional manufacturing plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Copper Wire and Cable Market |
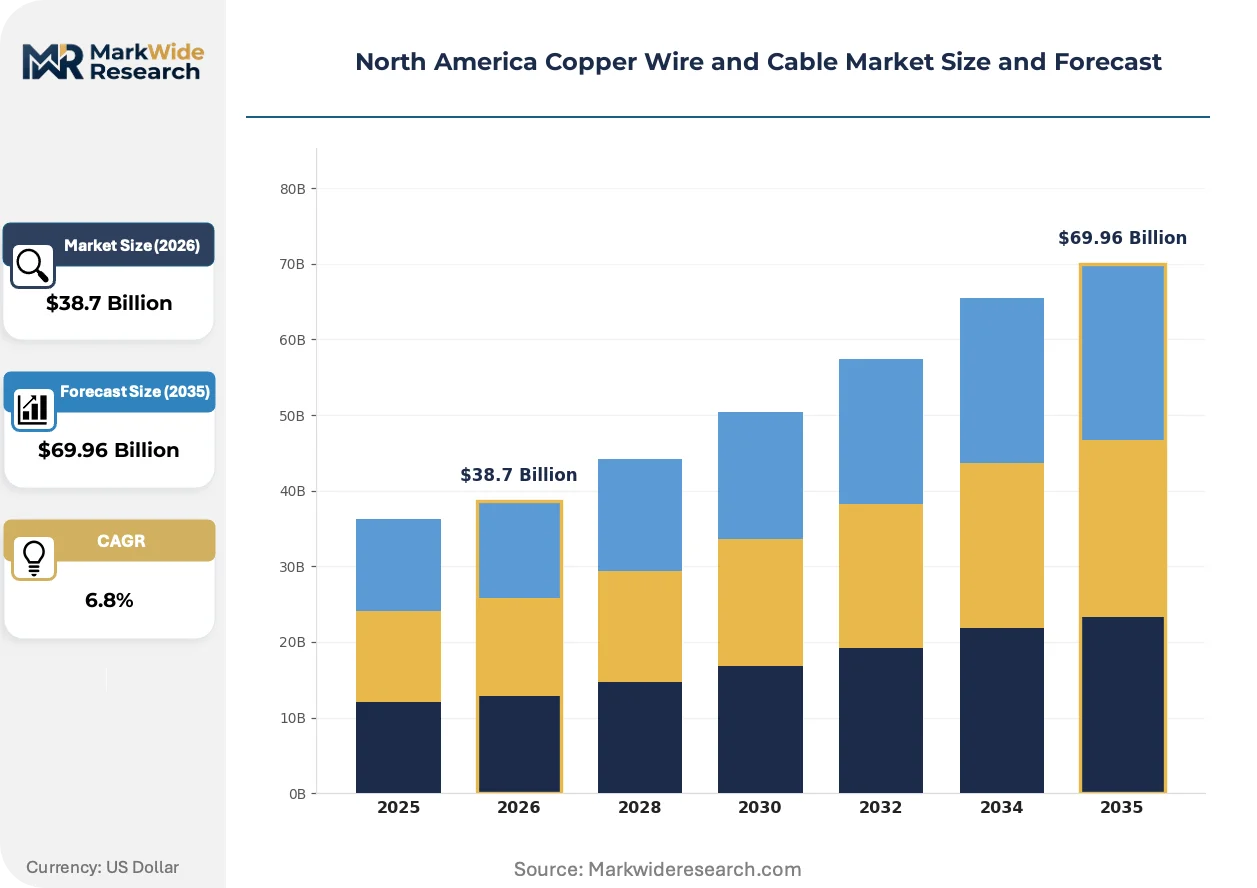
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Building Wire, Magnet Wire, Signal Cable, Automotive Wire End User: Construction, Telecommunications, Automotive, Power Generation Installation Type: Indoor, Outdoor, Underground, Overhead Application: Electrical Transmission, Data Communication, Wiring Harness, Industrial Equipment |
| Companies Covered | Southwire Company, LLC, Prysmian Group, Nexans, Belden Inc., Encore Wire Corporation, LS Cable & System Ltd., Superior Essex Inc., General Cable Corporation, CommScope Holding Company, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Copper Wire and Cable Market Strategic Shifts
Material science advances and procurement digitization are compressing product development cycles while elevating performance specifications across voltage classes.
Corrugated seamless aluminum sheathing is supplanting traditional lead and laminated tape constructions in medium-voltage distribution cables. Data center operators and renewable developers are specifying this construction for its reduced weight and simplified splicing protocols. The shift is compressing installed cost structures for underground feeder runs while eliminating lead-handling environmental controls.
The Inflation Reduction Act's domestic content bonus credits are reshaping supplier qualification requirements for federally funded transmission projects. Developers must now document North American smelting and rod production to capture full incentive values. This is concentrating procurement authority with integrated manufacturers possessing captive copper conversion capacity.
Specification-driven consolidation among electrical contractors is compressing vendor lists for major infrastructure awards. Tier-one contractors in Texas and Arizona are mandating single-source accountability for cable, terminations, and engineering support. This behavioral shift is marginalizing pure-play distributors from utility-scale project participation.
North America Copper Wire and Cable Market Segmentation
Copper wire and cable procurement patterns diverge sharply across technical specifications and end-use environments. Understanding where margin pools concentrate within each dimension enables suppliers to prioritize capacity investments and qualification efforts.
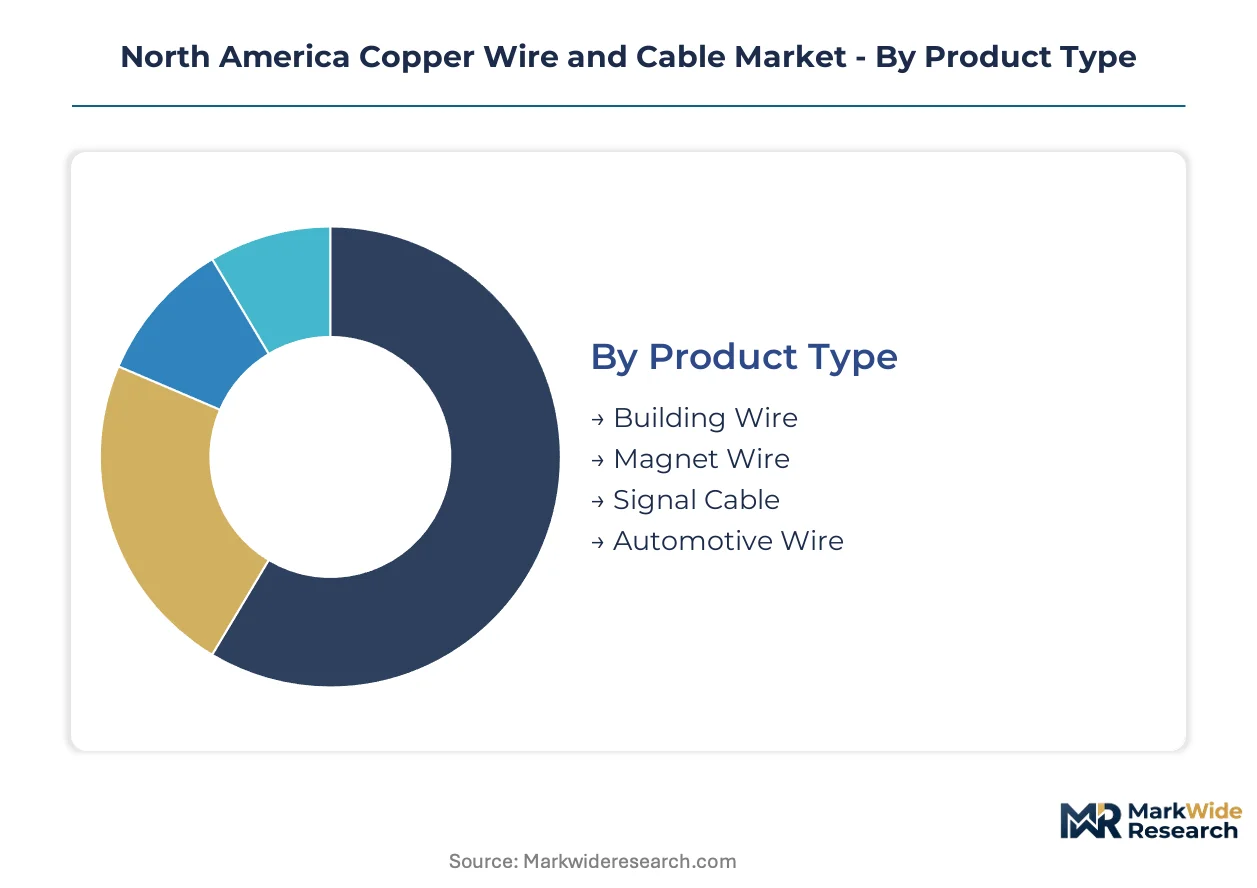
Product Type:
Margin capture varies dramatically by production complexity and certification barriers, with specialized formulations commanding premium pricing over commodity constructions.
- Building Wire:Thermoplastic-insulated conductors rated 600V dominate residential and commercial branch circuit installation. Construction activity in Texas and Arizona is absorbing record volumes of THHN/THWN-2 and NM-B cable for multifamily and single-family electrification.
- Magnet Wire:Continuously annealed copper conductors with thin film insulation enable high-efficiency motor and transformer windings. CHIPS Act-funded semiconductor fabs in Arizona and New York are specifying heavy-build polyester-imide formulations for precision equipment, compressing lead times for qualified suppliers.
- Signal Cable:Twisted-pair and coaxial constructions transmit data across structured cabling systems. Data center operators in Northern Virginia and Dallas-Fort Worth are driving specification upgrades toward Category 6A and fiber hybrid designs.
- Automotive Wire:Thin-wall and cross-linked polyethylene insulation withstands engine compartment temperatures and vibration. Electric vehicle battery pack manufacturers in Michigan and Tennessee are consuming high-voltage shielded cable at accelerating rates.
The dominant share belongs to Building Wire, while Magnet Wire is closing the gap fastest.
End User:
Procurement authority clusters differently across customer types, with project-scale buyers demanding integrated supply solutions that commodity distributors cannot fulfill.
- Construction:Electrical contractors specify cable for commercial, residential, and infrastructure projects. Master electrician shortages in Texas and California are extending installation timelines and forcing pre-positioned inventory strategies.
- Telecommunications:Hyperscale and regional carriers procure cable for network backbone and last-mile deployment. 5G densification in urban corridors is shifting demand toward fire-resistant jacketing and higher conductor counts.
- Automotive:OEMs and tier suppliers integrate cable into vehicle electrical architectures. The EV transition is displacing traditional low-voltage wiring with high-amperage shielded constructions for battery and motor connections.
- Power Generation:Utilities and independent developers source transmission and distribution cable for grid infrastructure. Renewable interconnection queues in ERCOT and CAISO territories are compressing procurement cycles for medium-voltage underground feeder.
Construction maintains the largest volume position, though Power Generation is expanding most quickly.
Installation Type:
Environmental exposure requirements dictate insulation compound selection and sheathing complexity, creating tiered pricing structures across deployment contexts.
- Indoor:Plenum and riser-rated constructions serve commercial building interiors. NFPA 70 updates are mandating low-smoke zero-halogen compounds for high-occupancy structures in jurisdictions adopting the latest National Electrical Code cycle.
- Outdoor:Sunlight-resistant and moisture-blocking jacketing protects aerial and exposed runs. Utility-scale solar farms in the Desert Southwest are consuming UV-stabilized PV wire at unprecedented scale.
- Underground:Direct-burial and conduit-rated cables require enhanced mechanical protection and water-blocking layers. Data center campus developments in Ashburn and Phoenix are driving demand for corrugated aluminum-sheathed medium-voltage feeder.
- Overhead:Aerial cable and weatherproof service drops span distribution networks. Aluminum substitution pressure is strongest here, though copper persists in coastal corrosion zones and high-density urban corridors.
Indoor installations retain the broadest application base, while Underground specifications are climbing the fastest.
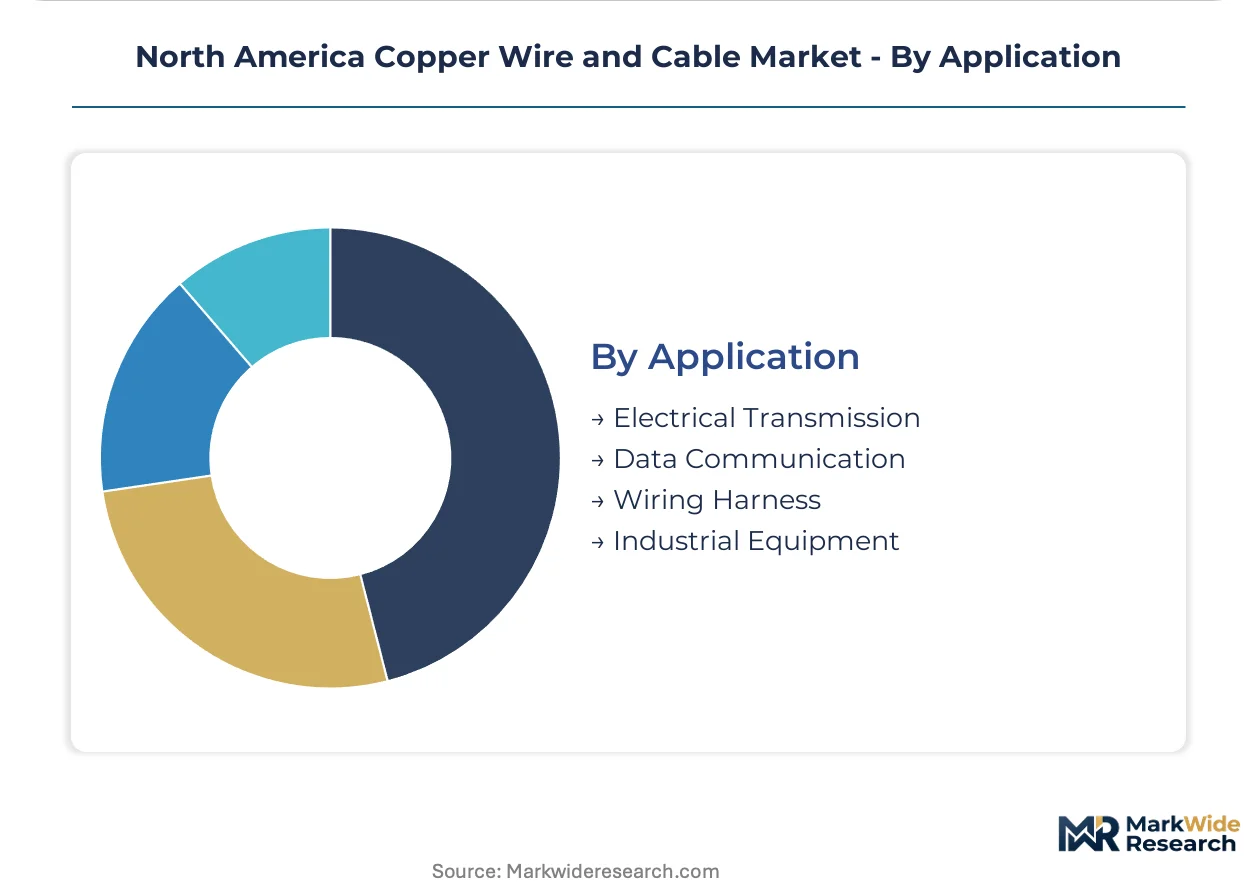
Application:
Performance requirements diverge by signal type and operational criticality, with mission-critical systems demanding enhanced reliability certifications.
- Electrical Transmission:High- and medium-voltage conductors move bulk power across utility networks. The Inflation Reduction Act's domestic content requirements are concentrating procurement with North American rod producers.
- Data Communication:Structured cabling and fiber optic interconnects enable digital infrastructure. Hyperscale facility buildouts are consuming cable volumes comparable to regional utility distribution networks.
- Wiring Harness:Bundled conductor assemblies organize complex electrical systems in transportation and industrial equipment. Aerospace and defense contractors in California and Connecticut are reshoring harness production under Buy American provisions.
- Industrial Equipment:Flexible and control cables serve manufacturing machinery and process automation. Reshoring of appliance and tool manufacturing to Mexico's Bajío region is pulling magnet wire and power cable demand southward.
Electrical Transmission anchors procurement volumes, while Data Communication is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American copper wire and cable market exhibits pronounced geographic specialization in consumption patterns. The United States dominates utility-scale transmission procurement, while Mexico concentrates automotive and appliance manufacturing demand. Canada maintains distinct preferences for mining-grade heavy-duty cable constructions.
United States
Texas and Arizona absorb unprecedented volumes of medium-voltage power cable for data center campuses and semiconductor fabrication facilities. The Inflation Reduction Act's domestic content bonus credits channel procurement toward integrated manufacturers with captive North American rod production. ERCOT interconnection queues in West Texas compress lead times for renewable developers sourcing underground feeder cable.
Canada
Ontario and Quebec drive demand through hydropower transmission maintenance and electric vehicle supply chain localization. Natural Resources Canada funding programs accelerate grid modernization procurement. Toronto-Waterloo corridor data center expansions specify fire-resistant low-smoke zero-halogen constructions for high-occupancy facilities.
Mexico
Nuevo León and Querétaro concentrate appliance and automotive OEM cable consumption under USMCA content requirements. NOM certification mandates shape cross-border supply chain configurations. Bajío region manufacturing reshoring pulls magnet wire demand southward from traditional U.S. sourcing patterns.
California
Silicon Valley hyperscale facilities and Central Valley solar farms compete for limited medium-voltage cable allocation. California Energy Commission building electrification mandates accelerate low-voltage construction wire specification upgrades. Los Angeles basin port electrification projects consume specialized marine-grade cable volumes.
North America Copper Wire and Cable Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the North America copper wire and cable market. Vertically aligned manufacturers with captive copper rod production dominate utility-scale transmission awards through cost and compliance advantages. Pure-play distributors and regional fabricators occupy fragmented positions in residential and light commercial segments. Strategic moves concentrate on qualification for Inflation Reduction Act domestic content requirements and pre-positioning inventory before project approvals.
Within the integrated leader tier, Southwire Company, LLC and Prysmian Group exemplify archetypes of regional distribution density and submarine specialization respectively. Nexans occupies a position bridging European technical standards with North American certification regimes. These three entities anchor competitive dynamics through their contrasting approaches to vertical integration and geographic coverage.
| Leading Market Players |
|---|
| Southwire Company, LLC |
| Prysmian Group |
| Nexans |
| Belden Inc. |
| Encore Wire Corporation |
| LS Cable & System Ltd. |
| Superior Essex Inc. |
| General Cable Corporation |
| CommScope Holding Company, Inc. |
| Others |
Value Chain & Pricing Dynamics
Aluminum conductor substitution in overhead transmission lines simultaneously redraws supply geography toward bauxite-rich regions and compresses pricing power for copper rod producers serving cost-sensitive utilities. This displacement dynamic intensifies margin pressure on commodity-grade cable manufacturers while elevating premium capture for suppliers of corrosion-resistant copper constructions in coastal zones.
Pricing Analysis
Long-term offtake agreements dominate procurement for utility-scale renewable and data center projects, insulating integrated manufacturers from spot volatility while exposing pure-play distributors to LME price swings. Price differentiation hinges on UL certification tier and captive rod production, with Inflation Reduction Act domestic content compliance commanding substantial premiums. Cost compression in standard-grade building wire intensifies as regional extruders compete for residential electrification volumes. Municipal utilities exhibit highest price sensitivity, whereas hyperscale data center operators prioritize lead-time certainty over unit economics.
Supply Chain Analysis
Inventory pre-positioning before final project approvals has compressed effective lead times across the North American market, forcing manufacturers to carry working capital through extended utility interconnection queues. Raw material supply concentrates in Chile and Peru for copper concentrate, with domestic rod production anchored in Georgia and Arizona. The supply chain rests on smelter capacity in Latin America, cross-linked polyethylene resin from Gulf Coast petrochemical complexes, and aluminum alloy feedstock from Canadian smelters. Single-source vulnerability in Chilean concentrate exposes pricing to geopolitical disruption. Distribution runs through electrical contractor networks and utility procurement departments, with specification authority consolidating at tier-one EPC firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America copper wire and cable market sits at an inflection driven by the Inflation Reduction Act's domestic content mandates, which are rewiring supplier qualification requirements and procurement authority structures across federally funded transmission projects.
For Market Incumbents: Fortify captive rod production capacity in the southeastern United States to capture Inflation Reduction Act bonus credits and lock out aluminum substitution threats in medium-voltage segments. Deepen UL 1072 MV-105 certification pipelines to accelerate approval cycles, pre-positioning inventory ahead of ERCOT and CAISO interconnection queue clearances.
For New Entrants and Emerging Players: Lead with fire-resistant low-smoke zero-halogen jacketing formulations targeting Toronto-Waterloo corridor data center expansions and California high-rise electrification mandates. The most penetrable white space sits in Mexico's Bajío region, where appliance and automotive OEMs seek USMCA-compliant magnet wire suppliers outside traditional U.S. sourcing patterns. Pursue qualification partnerships with NOM-certified testing laboratories to accelerate market access.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated mid-cap specialists with captive North American rod production and stranded utility-scale project relationships. Long-term viability hinges on exposure to data center and renewable interconnection cycles rather than residential construction volatility. Watch ERCOT and CAISO interconnection queue clearance rates as the signal for medium-voltage cable demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Rod Production | Captures Inflation Reduction Act domestic content credits for federally funded transmission awards. |
| UL 1072 MV-105 Certification Pipeline Expansion | Accelerates medium-voltage product approval cycles at third-party testing laboratories. |
| NOM Certification Partnership in Mexico | Unlocks USMCA-compliant supply to Querétaro and Nuevo León automotive OEMs. |
| Low-Smoke Zero-Halogen Compound Capacity Addition | Addresses NFPA 70 National Electrical Code updates for high-occupancy commercial construction. |
| Corrugated Aluminum Sheathing Line Conversion | Eliminates lead-handling costs while serving data center underground feeder specifications. |
Study Parameters
Desk research of customs trade records, FERC interconnection queue filings, and SEC 10-K disclosures preceded structured interviews with utility procurement officers, electrical contractor estimators, copper rod plant managers, and UL Solutions certification engineers. Primary fieldwork combined telephone and video interviews with downstream demand stakeholders across Texas, Arizona, and Ontario. Secondary validation drew from National Electrical Code amendment dockets, EIA electricity infrastructure datasets, and copper concentrate trade flow analysis. Bottom-up demand modeling triangulated against top-down macroeconomic drivers.
Variance decomposition across product type, end user, installation environment, and application dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level demand build-ups incorporating data center capex trajectories, renewable interconnection queue velocities, and semiconductor fabrication construction timelines. Modeled inputs included CHIPS Act funding disbursement schedules, ERCOT generation interconnection approval rates, and NFPA 70 adoption cycles across state jurisdictions.
Forecasts assume regulatory continuity in Inflation Reduction Act domestic content requirements and National Electrical Code enforcement regimes; material policy shifts would require re-modeling procurement incentive structures and specification mandates. Commodity price volatility in copper concentrate markets and master electrician certification backlogs in Texas and California constitute specific revision triggers. Revision becomes warranted when utility interconnection queue clearance rates or data center construction starts cross threshold deviations from baseline assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Cable Management Accessories Market
Cables
Europe HVAC Cables Market
Cables
XLPE Cables Market
Cables
Patch Cable Market
Cables
US Medium Voltage Cable Accessories Market
Cables
Twisted Pair Cable Market
Cables
Electric Vehicle Unshielded HV Cables Market
Cables
Electric Submersible Cable Sales Market
Cables
Control Cable Market
Cables
Submarine Cables Market
Cables
Sensing Cable Market
Cables
US Cables Market
Cables
Water Leak Sensing Cable Market
Cables
LED Cable Market
Cables
Solar Cable Market
Cables
India Optic Fiber Cable and Accessories Market