
 High-Temperature Superconducting Cables Market | 2026-2036
High-Temperature Superconducting Cables Market Size, Share, and Industry Trends Forecast 2026-2036
High-Temperature Superconducting Cables Market Intelligence
Japan's wire-drawing consortium is recalibrating rare-earth barium-copper-oxide (REBCO) tape capacity to meet utility-grade orders. Sumitomo Electric Industries leverages vertical integration from substrate to cable assembly, sustaining cost advantages in long-length conductors. Nexans anchors European project pipelines through its Lyon engineering center, while American Superconductor Corporation competes on cryogenic system integration for grid operators.
High-temperature superconducting cables carry electrical current with near-zero resistance when cooled below approximately 77 Kelvin using liquid nitrogen, typically constructed from bismuth-strontium-calcium-copper-oxide (BSCCO) or REBCO layers laminated onto flexible metallic tapes. These systems eliminate resistive losses in urban transmission corridors where conventional copper or aluminum cables face thermal and spatial constraints. Power transmission cables dominate current revenue as mature utility projects in Japan and South Korea validate operational reliability, while fault current limiting applications represent the fastest-growing segment as grid operators seek compact alternatives to mechanical breakers. Coated conductor technology commands premium positioning due to its higher critical current density under magnetic fields, though first-generation BSCCO retains cost advantages for shorter magnet coil runs.
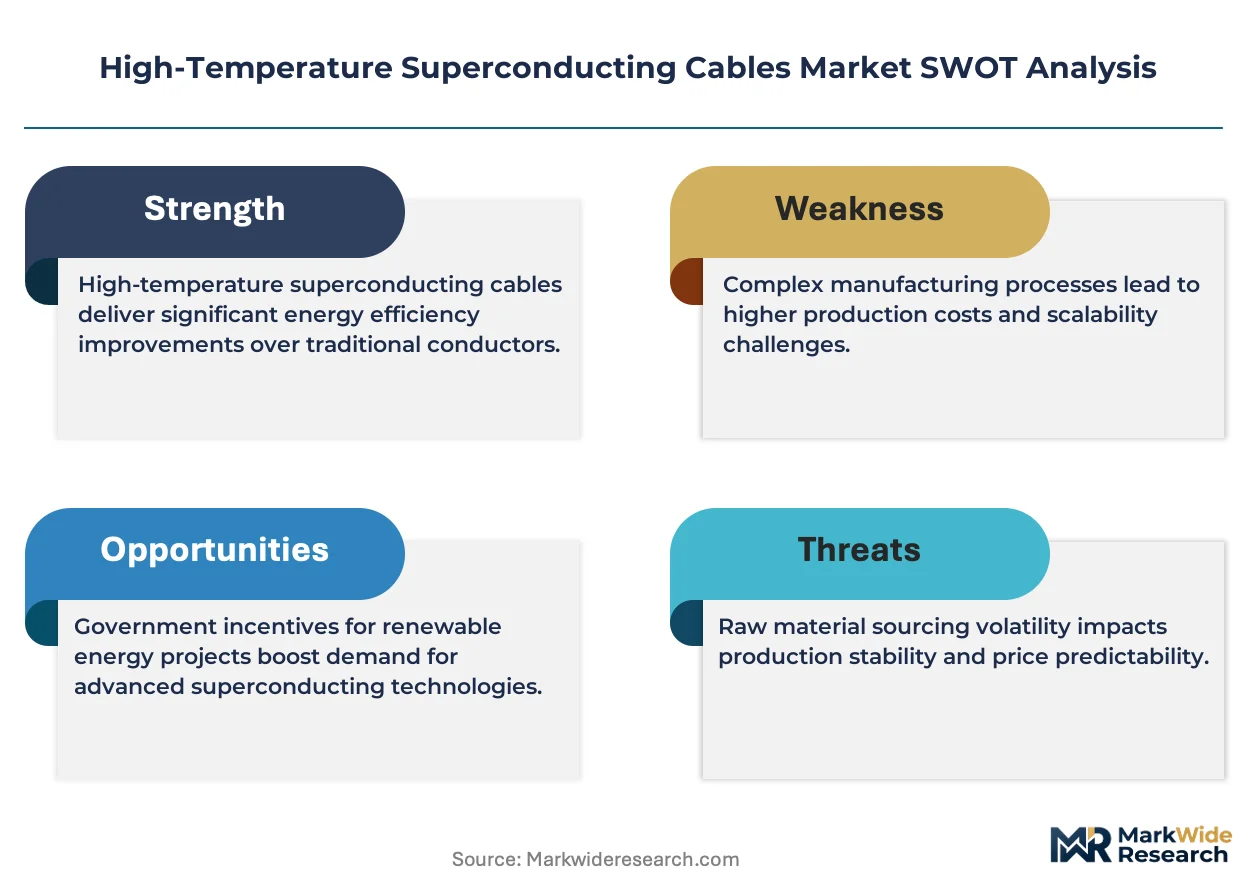
Japan's METI enforces efficiency benchmarks that effectively mandate superconducting solutions for dense metropolitan grids, while the EU F-Gas Regulation restricts sulfur hexafluoride insulation—indirectly favoring cryogenic HTS alternatives in substation design. China's GB standards for power cable testing now incorporate superconducting-specific protocols under NMPA-aligned technical committees. Stakeholders must monitor cooling system energy penalties and standardization progress across national testing regimes to time capital commitments.
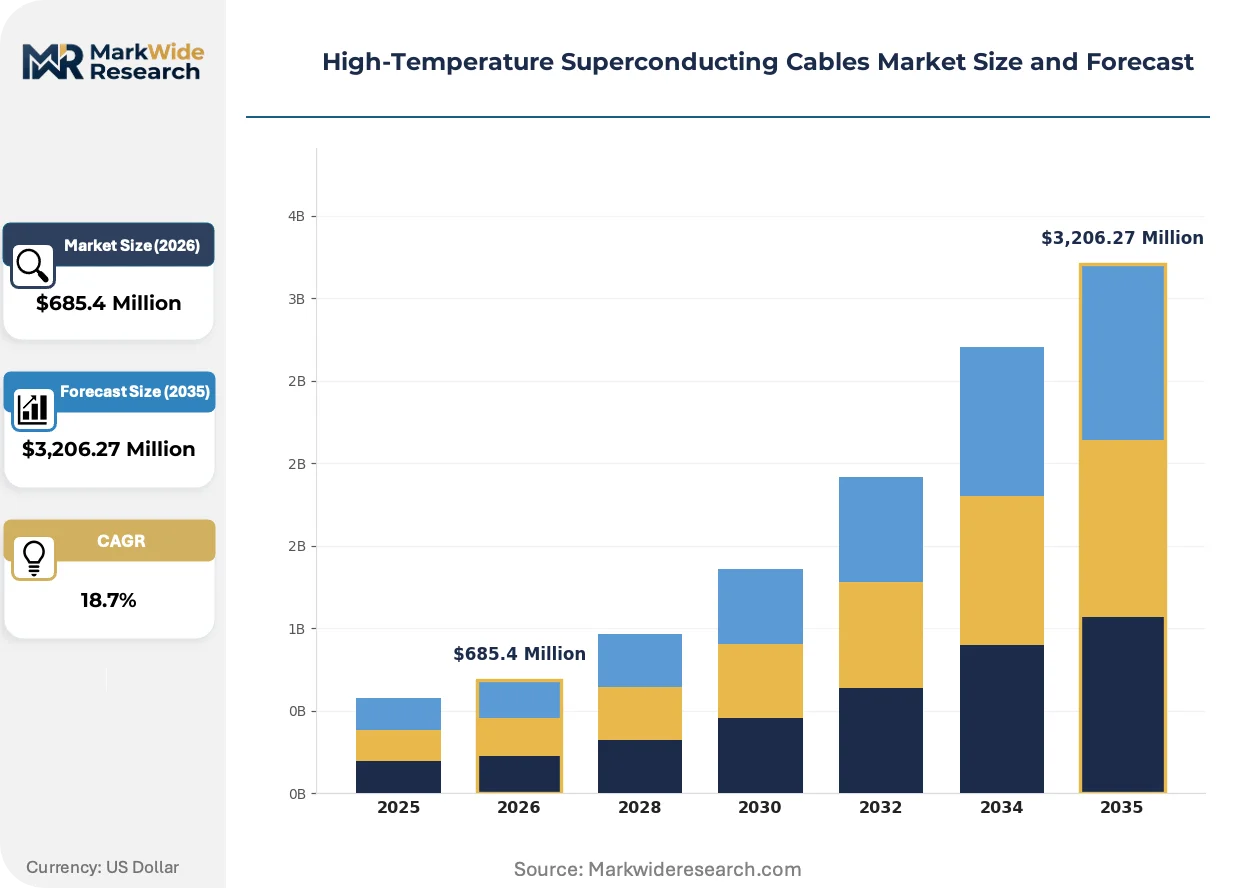
Market Dynamics
Urban grid congestion and liquid nitrogen cooling infrastructure deployment are compressing installation timelines for HTS cable projects, forcing utilities to sequence substation retrofits around cryogenic system availability rather than conventional cable lead times.
Growth Catalysts
- China's dual carbon goals:National mandates for carbon neutrality by 2060 accelerate replacement of resistive loss-heavy transmission corridors with superconducting alternatives in metropolitan clusters.
- REBCO tape manufacturing scale-up:Continuous deposition techniques for rare-earth barium-copper-oxide layers are reducing per-meter conductor costs for utility-grade lengths.
- Fault current limiting demand:Grid operators facing short-circuit capacity constraints in dense load centers specify HTS fault current limiters as compact breaker substitutes.
Market Restraints
- Liquid helium supply volatility:Rare gas extraction concentration in Qatar and Algeria creates input cost instability for cryogenic cooling system operators.
- Substrate manufacturing concentration:High-purity nickel-alloy tape production clusters in Japan and Germany, exposing buyers to single-source supply risk.
- EU F-Gas Regulation friction:Sulfur hexafluoride phase-down timelines compress substation design windows before HTS alternatives achieve full certification parity.
Strategic Opportunities
- India's metropolitan corridor buildout:Mumbai and Delhi distribution utilities pilot compact HTS substations where land scarcity prevents conventional equipment footprint expansion.
- Offshore wind grid integration:Subsea HTS cable runs from North Sea turbine clusters to onshore interconnectors eliminate reactive compensation hardware.
- Digital twin convergence:Physics-based thermal modeling software layered onto cable monitoring systems enables predictive maintenance contracts for grid operators.
Industry Challenges
- Cryogenic engineering talent scarcity:Specialized technicians for liquid nitrogen circulation system commissioning remain concentrated in Japan and South Korea, constraining project staffing for new entrants.
- Multi-standard certification timelines:IEC 62271 and GB/T cable testing protocol misalignment forces redundant validation cycles for suppliers serving both European and Chinese utilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Temperature Superconducting Cables Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $3,206.27 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cable Type: Power Transmission, Fault Current Limiting, Magnet Coils, Signal Transmission Technology: Second-Generation HTS, First-Generation HTS, Coated Conductors, Cryogenic Cooling Application: Electric Utilities, Renewable Energy Integration, Urban Power Grids, Data Centers End User Type: Energy Providers, Grid Operators, Research Institutions, Telecommunications Firms |
| Companies Covered | Sumitomo Electric Industries, Ltd, Nexans, American Superconductor Corporation, Fujikura Ltd, Furukawa Electric Co., Ltd, Superconductor Technologies Inc., Bruker Corporation, Theva Dünnschichttechnik GmbH, SuperPower Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Temperature Superconducting Cables Market Strategic Shifts & Innovations
Cooling system architecture and conductor manufacturing processes are undergoing parallel transformation as project economics shift from demonstration-scale validation toward repeatable utility deployment.
REBCO coated conductor technology is modularizing cryogenic cable system design. Grid operators in Japan and South Korea specify plug-and-play cooling skids that separate thermal management from cable routing. This modularization compresses outage windows for live grid insertions from weeks to days.
The EU F-Gas Regulation mandates sulfur hexafluoride phase-down in electrical equipment insulation. Substations in Germany and France face forced redesign timelines. HTS cryogenic alternatives bypass SF6 entirely, positioning nitrogen-cooled systems as compliance pathways for urban infrastructure locked into 2030 decarbonization deadlines.
Utility procurement teams now specify operational availability guarantees rather than equipment purchase alone. Japanese and Korean grid operators contract for 20-year cooling system performance, transferring operational risk to cable system integrators. This performance-contracting shift concentrates vendor selection on firms with captive cryogenic service capabilities.
High-Temperature Superconducting Cables Market Segmentation
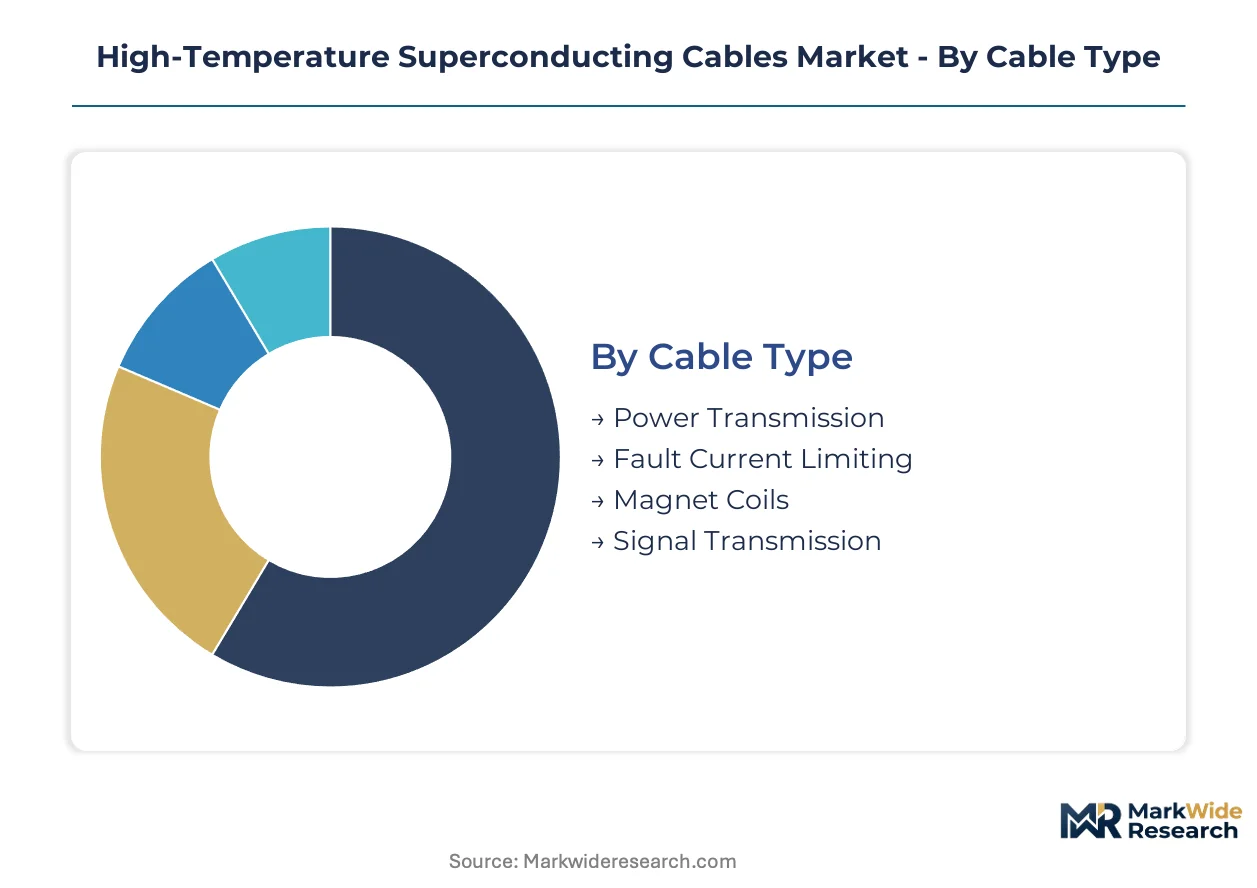
Segmentation in HTS cables reflects divergent technical maturity and procurement economics. Buyers prioritize critical current density for transmission corridors, fault response speed for grid protection, or field tolerance for magnet systems. Each segment carries distinct cooling infrastructure requirements and certification pathways.
Cable Type:
Procurement teams specify cable architecture based on grid integration constraints and thermal management complexity.
- Power Transmission:These systems carry bulk current across metropolitan corridors with near-zero resistive loss below liquid nitrogen temperatures. KEPCO in South Korea and Tokyo Electric validate reliability through decade-long urban deployments, though cooling station footprint remains the binding constraint in dense districts.
- Fault Current Limiting:Self-triggering resistance transitions protect substations from short-circuit damage without mechanical breaker intervention. German and French grid operators facing F-Gas Regulation deadlines specify these for compact urban substations where SF6 alternatives are mandated.
- Magnet Coils:BSCCO-based conductors dominate MRI and particle accelerator applications requiring persistent field stability.
- Signal Transmission:Low-noise characteristics serve specialized telecommunications and sensor networks.
Power Transmission leads on scale; Fault Current Limiting leads on momentum.
Technology:
Technology selection tracks the trade-off between performance ceiling and manufacturing yield.
- Second-Generation HTS:REBCO-coated conductors achieve critical current densities exceeding first-generation alternatives by an order of magnitude under magnetic field exposure. Japanese wire-drawing consortiums scale deposition throughput to meet utility-grade length requirements, though substrate polishing costs persist.
- First-Generation HTS:BSCCO tapes retain cost advantages for shorter runs and lower-field applications. Chinese manufacturers leverage established powder-in-tube processes for magnet coil supply.
- Coated Conductors:Epitaxial buffer layer architectures enable flexible tape geometries.
- Cryogenic Cooling:Closed-loop nitrogen circulation systems determine operational availability guarantees.
Second-Generation HTS commands premium positioning; First-Generation HTS sustains volume in magnet applications.
Application:
End-use specification varies by infrastructure vintage and land availability.
- Electric Utilities:Transmission operators in Japan and South Korea deploy HTS corridors to defer substation expansion in dense load centers. METI efficiency benchmarks effectively mandate superconducting solutions for new metropolitan infrastructure.
- Urban Power Grids:Compact substation retrofits exploit HTS current density where copper thermal limits bite. Mumbai and Delhi distribution utilities pilot installations where land scarcity prevents conventional equipment footprint expansion.
- Renewable Energy Integration:Offshore wind interconnection projects specify subsea HTS runs to eliminate reactive compensation hardware.
- Data Centers:Hyperscale facilities evaluate HTS busbars for power delivery density.
Electric Utilities anchor current procurement; Urban Power Grids are expanding most quickly.
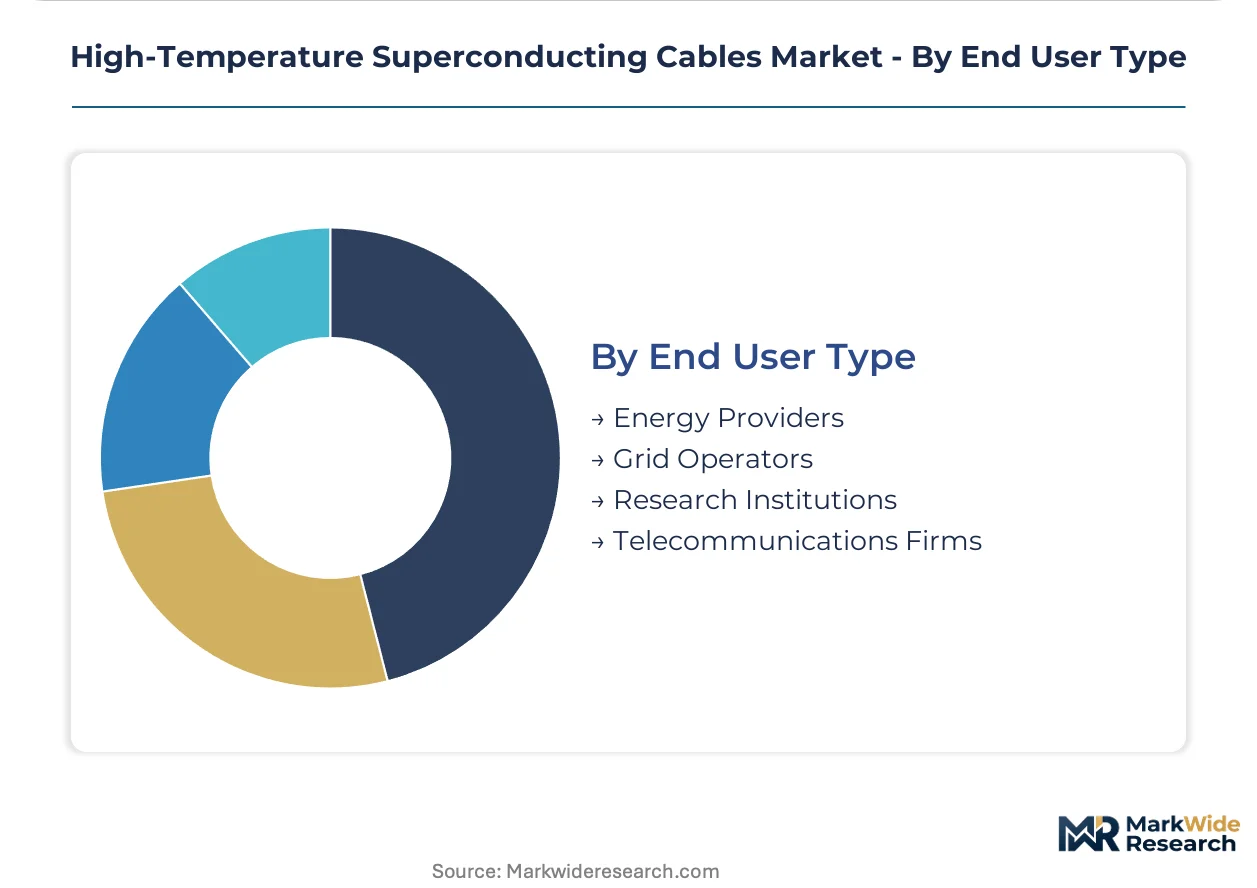
End User Type:
Contracting structures diverge by operational risk tolerance and technical capability.
- Energy Providers:Vertically integrated utilities in East Asia specify long-term cooling system performance contracts, transferring operational risk to cable system integrators. Twenty-year availability guarantees now standard in Japanese and Korean procurement.
- Grid Operators:Independent system operators prioritize interoperability with existing protection schemes and SCADA integration.
- Research Institutions:National laboratories drive specification evolution for next-generation conductor architectures.
- Telecommunications Firms:Specialized signal transmission applications require customized cryogenic packaging.
Energy Providers dominate contract value; Grid Operators are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost-of-compliance gaps between jurisdictions are redirecting HTS cable manufacturing investment toward economies with aligned superconducting standards and subsidized clean-energy infrastructure programs.
Japan
Metropolitan grid congestion and METI efficiency mandates drive utility procurement of compact superconducting corridors. The ministry's technical benchmarks effectively require superconducting solutions for new Tokyo and Osaka infrastructure. Kanto region utilities validate decade-long operational reliability through live urban deployments.
South Korea
KEPCO-led metropolitan corridor projects concentrate demand for fault current limiting substations. National renewable integration targets accelerate replacement of resistive transmission hardware. Seoul Capital Area distribution networks pilot modular cooling systems to compress installation timelines.
China
Dual carbon goals and NMPA-aligned GB standards for superconducting cable testing create regulatory pull for domestic REBCO tape manufacturing. Yangtze River Delta utilities evaluate compact HTS substations where land scarcity prevents conventional equipment expansion. Shanghai and Hangzhou grid operators incorporate superconducting protocols under technical committees.
Germany
EU F-Gas Regulation sulfur hexafluoride phase-down forces substation redesign toward cryogenic alternatives. Industrial clusters in Bavaria and North Rhine-Westphalia face compressed compliance windows before 2030 deadlines. Munich engineering centers advance cooling system integration for grid operator specifications.
United States
FERC grid reliability standards and state-level clean energy mandates create procurement incentives for lossless transmission. East Coast metropolitan utilities evaluate HTS corridors for dense load centers. Northeast corridor projects test operational availability guarantees as contracting structures shift toward performance-based procurement.
High-Temperature Superconducting Cables Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized cooling system integration and regional certification pathways. The market structures around three maturity tiers: integrated wire-to-cable manufacturers, cryogenic engineering specialists, and substrate material suppliers. Strategic differentiation concentrates on backward integration into REBCO tape production, captive cryogenic service capabilities, and multi-standard certification capacity. Competitive moves center on long-term performance contracting and modular cooling skid development.
Within the integrated manufacturing tier, Sumitomo Electric Industries and Furukawa Electric occupy positions representing Japanese vertical control from substrate through cable assembly. Nexans anchors European project pipelines through Lyon-based engineering operations. American Superconductor Corporation exemplifies the cryogenic system integration archetype, competing on thermal management packaging for grid operators. These three represent distinct strategic positions: captive tape production, regional project development, and cooling system specialization.
| Leading Market Players |
|---|
| Sumitomo Electric Industries, Ltd |
| Nexans |
| American Superconductor Corporation |
| Fujikura Ltd |
| Furukawa Electric Co., Ltd |
| Superconductor Technologies Inc. |
| Bruker Corporation |
| Theva Dünnschichttechnik GmbH |
| SuperPower Inc. |
| Others |
Cost & Logistics Intelligence
Captive REBCO tape production in Japanese wire-drawing consortiums anchors both supply security and pricing power for integrated cable manufacturers serving METI-mandated metropolitan grids. This backward integration into rare-earth barium-copper-oxide deposition insulates incumbents from substrate cost volatility while compressing procurement timelines for utility-grade lengths.
Pricing Analysis
Direct-to-utility contracting eliminates distributor margins, though cryogenic system integrators capture service-layer markups on 20-year availability guarantees. Three-tier pricing structure across premium, standard, and economy levels separates performance-contracted installations from equipment-only sales and pilot demonstration projects. Cost compression in first-generation BSCCO runs is intensifying because Chinese manufacturers leverage established powder-in-tube processes. Municipal utilities in land-constrained districts show least price sensitivity; research institutions piloting signal transmission applications show most.
Supply Chain Analysis
High-purity nickel-alloy tape supply rests on Japanese and German specialty metallurgy producers, with rare-earth element processing concentrated in China. REBCO-coated conductors draw from epitaxial buffer layer architectures, liquid nitrogen circulation hardware, and cryogenic insulation systems. Single-source vulnerability in substrate polishing equipment exposes buyers to 18-month lead time extensions. Distribution runs through integrated cable manufacturers with captive cryogenic service capabilities rather than independent distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between EU F-Gas Regulation compliance deadlines and China's dual carbon timeline creates geographic cost differentials favoring early HTS substation deployment in German industrial clusters before 2030 phase-down windows close.
For Market Incumbents: Lock in long-term REBCO tape offtake agreements with Japanese substrate producers before capacity allocation tightens. Defend margin position by expanding captive cryogenic service networks into India's metropolitan corridor buildout, transferring operational risk through performance contracting while emerging Chinese entrants lack comparable field service density.
For New Entrants and Emerging Players: EU F-Gas Regulation in Germany and France opens a window for specialized fault current limiting substation integration where SF6 alternatives face compressed redesign timelines. Target compact urban retrofit projects in Mumbai and Delhi where land scarcity prevents conventional equipment footprint expansion. Lead with modular cooling skid partnerships rather than full cable system manufacturing.
For Investors and Strategic Acquirers: Roll-up economics work for cryogenic engineering specialists because talent scarcity in liquid nitrogen circulation system commissioning concentrates operational capability in Japanese and Korean firms. Five-to-ten-year viability hinges on standardization progress across IEC and GB/T testing protocols. Watch for NMPA-aligned technical committee rulings on superconducting-specific cable certification as inflection signal for Chinese market entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into REBCO Tape Production | Sumitomo Electric's substrate-to-cable control insulates against rare-earth price volatility in Japanese utility procurement. |
| Modular Cooling Skid Development | Plug-and-play thermal management compresses live grid insertion windows from weeks to days in Seoul Capital Area pilots. |
| 20-Year Performance Contracting | KEPCO's availability guarantee structure transfers operational risk to vendors with captive cryogenic service networks. |
| Multi-Standard Certification Investment | IEC 62271 and GB/T protocol alignment reduces redundant validation cycles for suppliers serving European and Chinese utilities. |
| Offshore Wind Interconnection Partnerships | Subsea HTS cable runs from North Sea turbine clusters eliminate reactive compensation hardware in German grid integration. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with utility planning officers, HTS cable system integrators, cryogenic engineering specialists, and grid operator procurement leads with secondary validation from FERC filings, IEA reports, METI efficiency benchmark disclosures, and EIA transmission infrastructure databases. Bottom-up project pipeline enumeration and top-down regulatory mandate sizing were triangulated against manufacturer capacity announcements.
Historical reference periods anchored the forecast window to decade-long operational deployments in Japan and South Korea, with projection horizon segmentation across cable type, generation technology, application vertical, and end-user contracting structure. CAGRs were derived from utility capital expenditure tracking and regulatory mandate timeline analysis, incorporating REBCO tape manufacturing scale-up curves and liquid nitrogen infrastructure deployment rates as industry-specific inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged IEC-GB/T protocol misalignment or helium supply disruption scenarios. Forecasts reflect documented assumptions on regulatory enforcement timelines and cooling system energy penalty trajectories. A small set of named triggers—NMPA certification rulings, EU F-Gas Regulation amendment cycles, and KEPCO procurement award schedules—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Industrial Cable Reels Market
Cables
Europe Cable Accessories Market
Cables
Premise Cable Market
Cables
Military Fiber Optic Cables Market
Cables
Data Center Wire and Cable Market
Cables
Aluminium Battery Cable Market
Cables
Submarine Data Cables Market
Cables
Flat Flexible Cables Market
Cables
Submarine Communication Cables Market
Cables
XLPE Cables Market
Cables
Instrumentation Cables Market
Cables
Cable Carrier Market
Cables
Submarine Cable System Market
Cables
HVDC Cables Market
Cables
Global Cable Gland Market
Cables
EDM Wires Market