
 Europe Geographic Information System (GIS) Market | 2026-2036
Europe Geographic Information System (GIS) Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Geographic Information System (GIS) Market Intelligence
Cloud-native architectures are restructuring traditional GIS economics as subscription models displace perpetual software licenses. European Space Imaging leverages its satellite constellation control to sustain premium data delivery across defense and agriculture verticals. Esri UK anchors its position through deep integration with British government geospatial standards. Cadcorp differentiates via specialized mapping engines tailored to European cadastral systems.
A Geographic Information System integrates hardware, software, and data to capture, store, manipulate, analyze, manage, and present spatial or geographic information, typically operating with sub-meter accuracy through GPS integration and coordinate reference systems aligned to ETRS89. Its primary commercial purpose is enabling location-based decision support for asset tracking, environmental compliance, and infrastructure planning. Software segments dominate revenue as platform vendors consolidate toolsets, while Cloud deployment grows fastest among mid-tier municipalities shedding on-premises maintenance burdens. Services margins concentrate in bespoke application development for Utilities and Urban Planning end users requiring domain-specific spatial workflows.
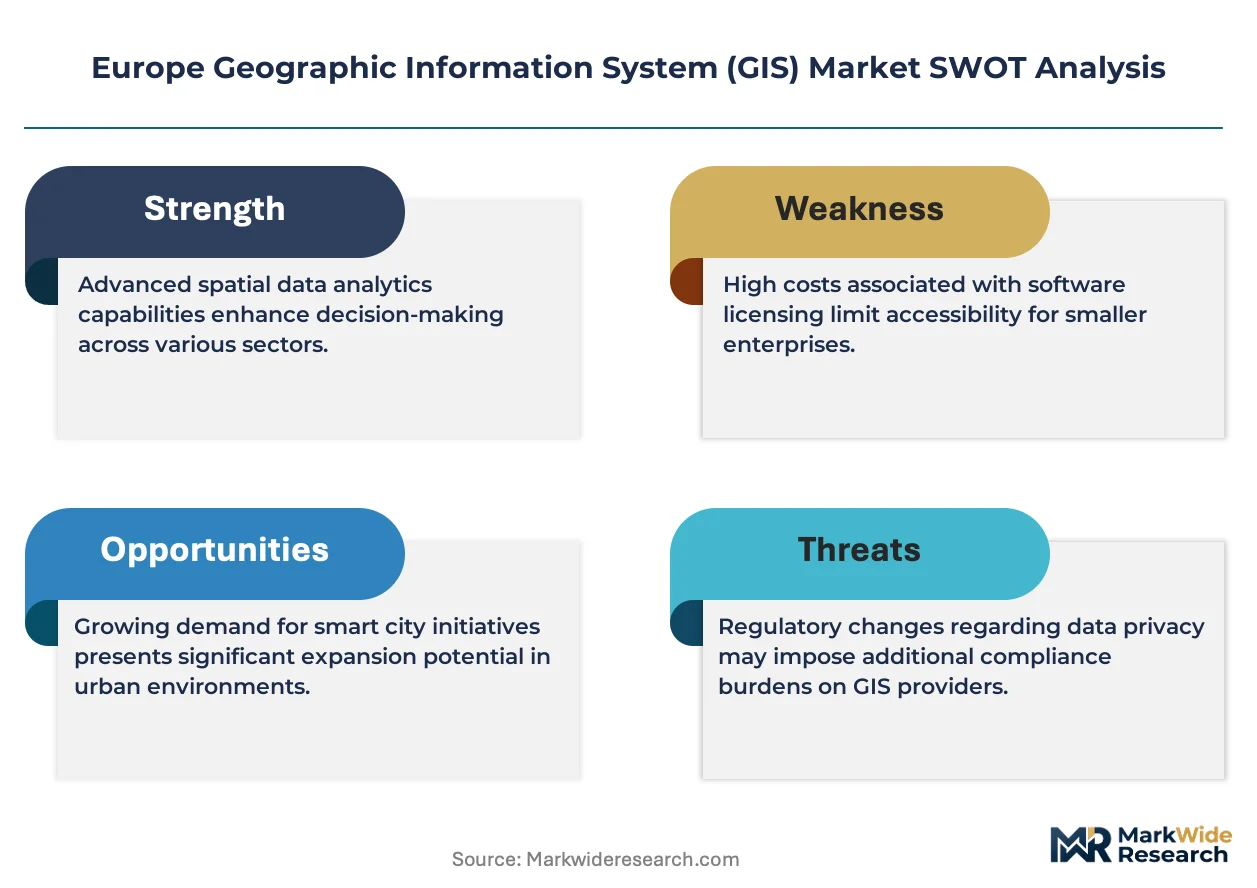
EU Green Deal targets and CSRD disclosure rules are reshaping procurement criteria across member states, forcing vendors to embed carbon accounting layers within spatial platforms. EMA environmental data standards and national implementations of INSPIRE directives create compliance moats for established European suppliers. Stakeholders must monitor how the EU AI Act classifies automated geospatial analytics, as this determination will gate market access for machine-learning-driven classification tools.
Market Dynamics
Cloud-native architectures are restructuring traditional GIS economics as subscription models displace perpetual software licenses, forcing vendors to rebuild revenue recognition and customer retention systems around recurring relationships rather than upfront transactions.
Growth Catalysts
- EU Green Deal carbon accounting mandates:Member states now require spatial tracking of emissions across supply chains, pulling enterprise GIS procurement into compliance workflows previously handled by standalone environmental software.
- German federal infrastructure digitization:Federal Transport Ministry programs are funding municipal procurement of 3D cadastral systems at scale unmatched elsewhere in the region.
- Real-time satellite imagery integration:Defense and agriculture buyers are demanding sub-daily refresh rates for asset monitoring, expanding platform utility beyond traditional mapping functions.
Market Restraints
- Specialized geospatial talent scarcity:European universities produce insufficient graduates combining GIS science with cloud engineering, inflating implementation timelines and service costs.
- INSPIRE directive compliance fragmentation:National interpretations vary across Denmark, France, and Poland, forcing vendors to maintain multiple metadata schemas and raising development overhead.
- Legacy on-premises infrastructure lock-in:Large utilities and defense agencies face multi-year depreciation cycles that delay SaaS migration and compress near-term addressable market.
Strategic Opportunities
- Eastern European municipal underpenetration:Romanian and Bulgarian local governments lack mature spatial data infrastructure, creating first-mover advantages for platform vendors offering bundled training and implementation.
- CSRD disclosure automation:The Corporate Sustainability Reporting Directive mandates geolocated asset-level emissions data, opening subscription revenue from compliance departments previously outside GIS buyer sets.
- Digital twin convergence with BIM:Construction and urban planning sectors are merging building information models with geospatial platforms, requiring new interoperability layers and integration services.
Industry Challenges
- ETRS89 coordinate system migration complexity:National mapping agencies are transitioning from legacy datums, forcing vendors to maintain dual-calculation engines and support parallel customer environments during extended cutover periods.
- EU AI Act classification uncertainty:Automated geospatial analytics involving machine learning face pending regulatory designation that will determine compliance burdens and market access requirements for classification algorithms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Geographic Information System (GIS) Market |
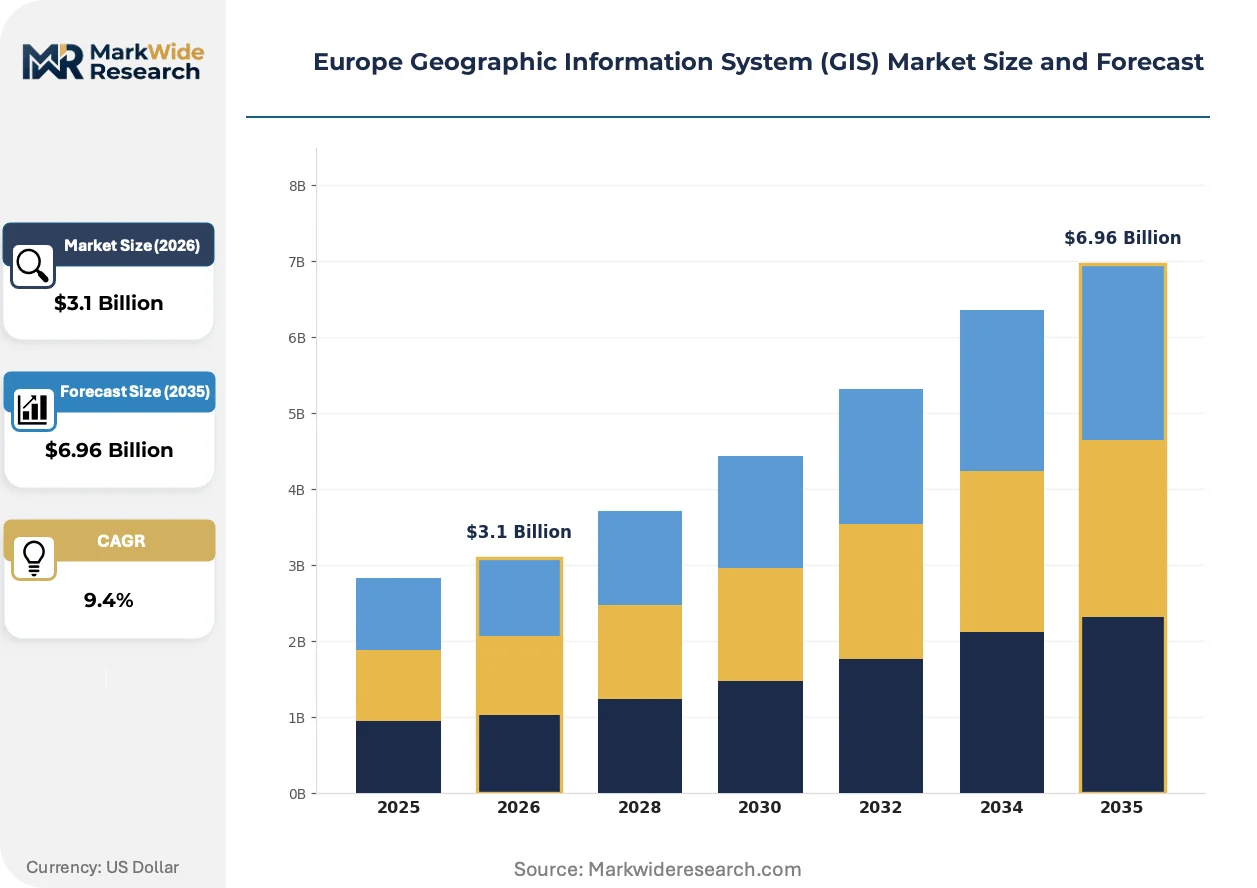
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $6.96 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
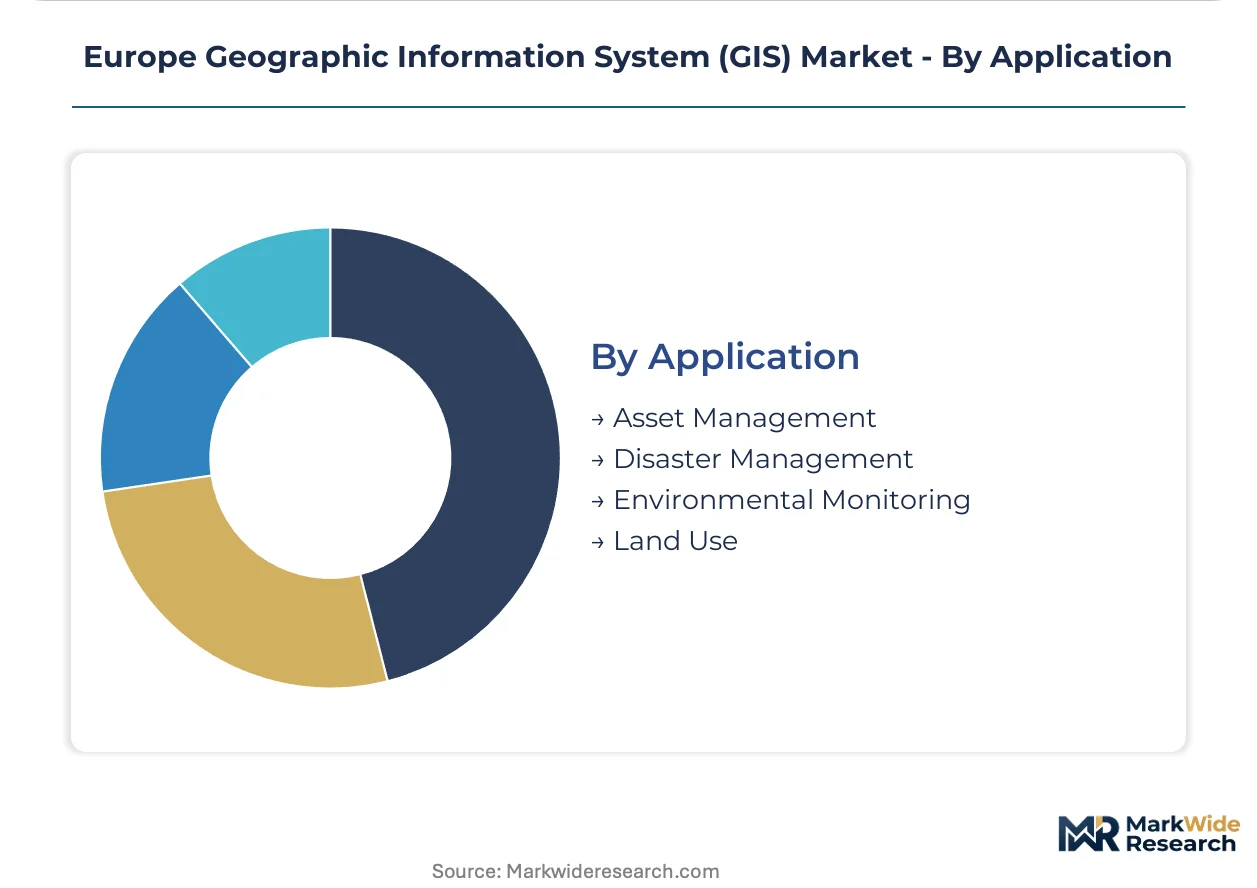
| Segmentation | Product Type: Software, Hardware, Services, Data End User: Government, Transportation, Utilities, Urban Planning Deployment: On-Premises, Cloud, Hybrid, Mobile Application: Asset Management, Disaster Management, Environmental Monitoring, Land Use |
| Companies Covered | LYRASENSE, European Space Imaging, Esri UK, GIS-Point, Geolytix, Cadcorp, GAF AG, Corsac Technologies, Sweco UK, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Geographic Information System (GIS) Market Strategic Shifts & Innovations
Artificial intelligence inference at the network edge is compressing latency for real-time spatial decision-making, while regulatory data-sharing mandates are dissolving traditional boundaries between public geospatial infrastructure and private platform layers.
Edge-deployed machine learning models are processing satellite and sensor feeds locally to enable sub-second anomaly detection for utility network monitoring and precision agriculture. Water utilities in the Netherlands and agricultural cooperatives in Spain are piloting these architectures to reduce backhaul costs. This capability is expanding into emergency response workflows where cloud connectivity cannot be assumed, creating new hardware-software bundling requirements for platform vendors.
CSRD disclosure rules are mandating geolocated emissions reporting at facility level, forcing spatial platforms to embed carbon accounting modules directly into core workflows. Industrial manufacturers in Germany and France must now submit verified spatial data alongside financial statements. Food processing and chemical production facilities face the steepest compliance curves, driving demand for integrated environmental compliance suites rather than standalone GIS tools.
Mid-tier municipalities are abandoning capital-intensive on-premises deployments in favor of consumption-based SaaS arrangements that transfer infrastructure risk to vendors. French and Italian provincial governments are leading this transition, unbundling implementation services from software subscriptions to preserve procurement flexibility. This pattern is most visible among 50,000-200,000 population cities that lack dedicated IT departments but face INSPIRE compliance deadlines requiring rapid capability deployment.
Europe Geographic Information System (GIS) Market Segmentation
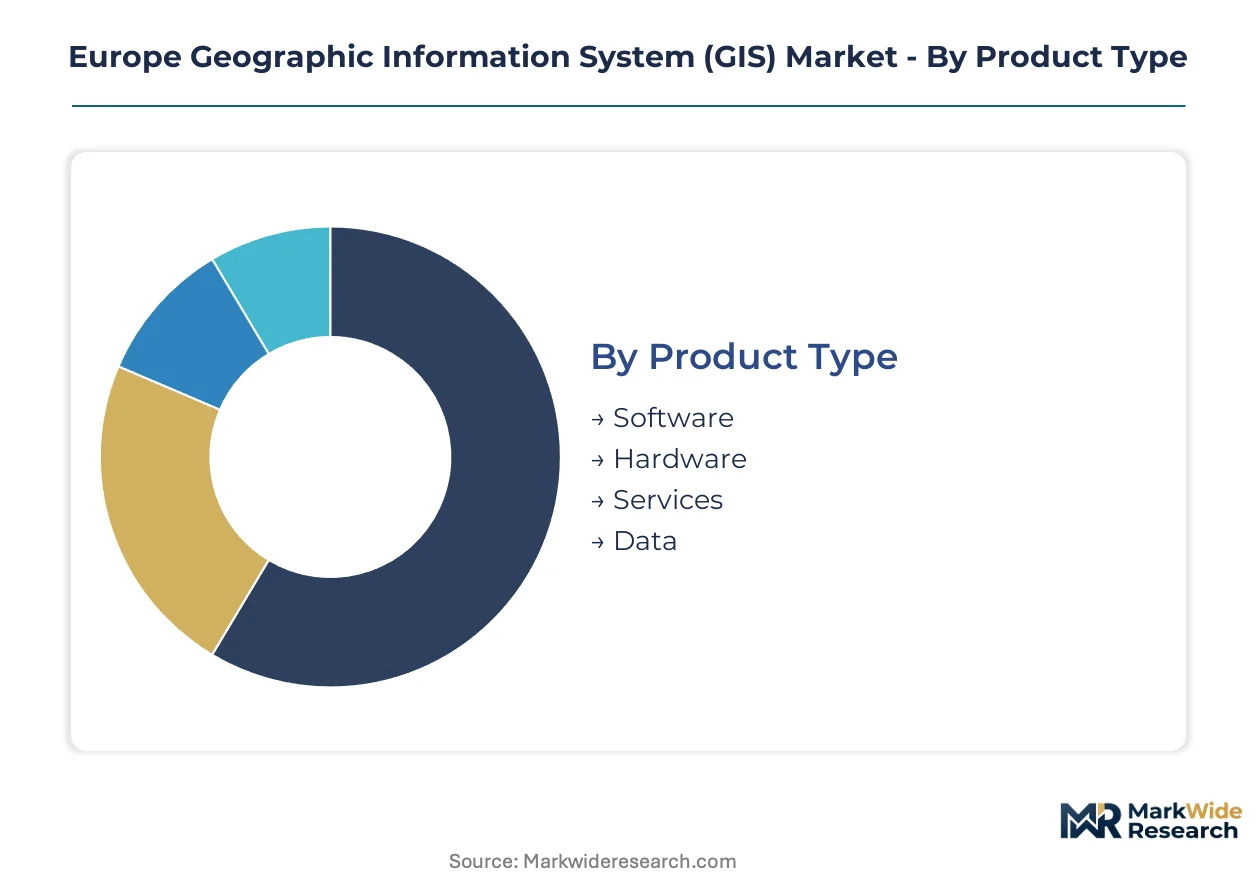
GIS procurement patterns diverge sharply across European member states based on regulatory maturity, infrastructure legacy, and compliance deadline proximity. Understanding these segment fault lines reveals where platform consolidation versus specialized tooling will dominate vendor strategy.
Product Type:
Cost tier separates enterprise buyers maintaining integrated suites from municipalities purchasing modular capabilities.
- Software:Platform vendors consolidate toolsets into unified environments spanning spatial analytics, visualization, and data management. German federal infrastructure programs and French departmental INSPIRE compliance deadlines concentrate procurement here, though perpetual license displacement by subscription models compresses upfront revenue recognition.
- Services:Bespoke application development and implementation support capture margins from utilities and urban planning departments lacking in-house geospatial engineering capacity. Romanian and Bulgarian municipalities drive expansion as first-mover vendors bundle training with platform deployment.
- Hardware:GPS receivers, ruggedized field tablets, and edge computing nodes for sensor integration.
- Data:Satellite imagery, cadastral records, and environmental sensor feeds licensed from specialized providers.
Volume sits with Software; growth tilts toward Services.
End User:
Application maturity determines whether buyers seek standalone spatial platforms or embedded analytics within existing enterprise systems.
- Government:National mapping agencies and municipal departments operate as both data providers and platform consumers, with INSPIRE directive compliance forcing metadata standardization investments. Polish and Danish national agencies exemplify divergent implementation timelines that fragment vendor development roadmaps.
- Utilities:Water, electricity, and gas network operators deploy real-time asset monitoring to reduce leakage and outage response times. Dutch water utilities pilot edge-deployed machine learning for sub-second anomaly detection, creating hardware-software bundling requirements.
- Transportation:Road and rail authorities managing linear infrastructure assets across jurisdictions.
- Urban Planning:Construction and city development offices merging BIM models with geospatial platforms for digital twin workflows.
Procurement concentrates in Government; expansion accelerates fastest in Utilities.
Deployment:
Infrastructure risk appetite separates capital-constrained buyers from organizations with depreciated on-premises investments.
- Cloud:SaaS arrangements transfer server maintenance and security patching to vendors, appealing to mid-tier municipalities lacking dedicated IT departments. French and Italian provincial governments in the 50,000-200,000 population range lead this transition, unbundling implementation services to preserve procurement flexibility.
- Hybrid:Sensitive defense and utility data remains on-premises while non-critical analytics shift to hosted environments. German defense agencies and large European utilities face multi-year depreciation cycles that enforce this intermediate architecture.
- On-Premises:Legacy installations in classified facilities and critical infrastructure with air-gapped security requirements.
- Mobile:Field data collection applications on smartphones and tablets for inspection and survey workflows.
Revenue dominance belongs to Hybrid; Cloud climbs the fastest trajectory.
Application:
Regulatory enforcement intensity determines platform investment priority and integration depth with compliance systems.
- Environmental Monitoring:CSRD disclosure rules mandate geolocated emissions reporting at facility level, forcing carbon accounting modules into core GIS workflows. German and French industrial manufacturers must submit verified spatial data alongside financial statements, pulling compliance departments into buyer sets previously outside geospatial procurement.
- Asset Management:Real-time tracking of infrastructure condition and location across distributed networks. Spanish agricultural cooperatives and Dutch utility operators demand sub-daily satellite refresh rates, expanding platform utility beyond traditional mapping functions.
- Disaster Management:Emergency response coordination requiring offline capability where cloud connectivity cannot be assumed.
- Land Use:Cadastral mapping and zoning administration for property registration and development control.
Investment weight falls on Asset Management; Environmental Monitoring gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany, France, and the UK, where federal infrastructure digitization programs and CSRD compliance deadlines are pulling procurement forward. Municipal governments across these markets face INSPIRE directive timelines that compress implementation windows. Eastern European markets remain underpenetrated, creating first-mover opportunities for vendors bundling training with platform deployment.
Germany
Federal Transport Ministry funding drives municipal procurement of 3D cadastral systems at unmatched scale. The EU Green Deal carbon accounting mandates require spatial tracking of industrial emissions across supply chains. Bavarian and North Rhine-Westphalian cities lead deployment of real-time utility monitoring platforms.
France
CSRD disclosure rules force industrial manufacturers to submit verified geolocated emissions data alongside financial statements. The EMA environmental data standards create compliance moats for established European suppliers. Île-de-France provincial governments in the 50,000-200,000 population range are abandoning on-premises deployments for consumption-based SaaS arrangements.
United Kingdom
Deep integration with British government geospatial standards anchors platform procurement decisions. The UK Environment Agency mandates spatial analytics for flood risk assessment and infrastructure resilience planning. London and Southeast municipal clusters drive demand for BIM-digital twin convergence in urban planning workflows.
Netherlands
Dutch water utilities pilot edge-deployed machine learning for sub-second anomaly detection in distribution networks. National implementations of INSPIRE directives vary from German and Danish interpretations, forcing vendors to maintain multiple metadata schemas. Randstad metropolitan governments consolidate spatial data infrastructure across Amsterdam, Rotterdam, and The Hague.
Poland
National mapping agencies face extended cutover periods transitioning from legacy datums to ETRS89 coordinate systems. Polish interpretations of INSPIRE compliance timelines diverge from Danish and French schedules, fragmenting vendor development roadmaps. Warsaw and Krakow municipal clusters lack mature spatial data infrastructure, creating training-bundling opportunities for platform vendors.
Europe Geographic Information System (GIS) Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with software platform vendors consolidating toolsets while services providers capture margins from bespoke implementation. The vendor base organizes around three archetypes: satellite constellation operators controlling premium data delivery, platform vendors with deep government integration, and specialized mapping engine developers tailored to European cadastral systems. M&A activity concentrates in cloud-native capability acquisition, while geographic expansion targets Eastern European municipal underpenetration.
Within the satellite imagery tier, European Space Imaging exemplifies constellation-controlled premium data delivery. Among UK-integrated platform specialists, Esri UK and Geolytix occupy positions tied to British government geospatial standards. Cadcorp represents the specialized mapping engine archetype, with its focus on European cadastral system requirements distinguishing it from generalized platform competitors.
| Leading Market Players |
|---|
| LYRASENSE |
| European Space Imaging |
| Esri UK |
| GIS-Point |
| Geolytix |
| Cadcorp |
| GAF AG |
| Corsac Technologies |
| Sweco UK |
| Others |
Cost & Logistics Intelligence
EU Green Deal carbon accounting mandates gate qualified supply and premium-tier pricing access, compelling vendors to embed compliance modules that separate certified environmental-data platforms from basic mapping tools. German industrial manufacturers and French CSRD-reporting entities now pay compliance premiums for spatial analytics suites that integrate verified emissions tracking, while municipalities in Eastern Europe face tiered entry pricing bundled with training services.
Pricing Analysis
Volume concentrates in subscription-based SaaS tiers displacing perpetual licenses, while margins accrue to specialized implementation services. Three-tier pricing structure across premium, standard, and economy levels differentiates by INSPIRE compliance certification and integration depth with national cadastral systems. Pricing pressure stems from mid-tier municipalities demanding unbundled software and service contracts. Government buyers show lowest price sensitivity due to federal infrastructure digitization funding; Bulgarian and Romanian municipalities exhibit highest sensitivity, driving bundled training-and-platform offerings.
Supply Chain Analysis
Local-content rules under EU public procurement directives reshape sourcing, favoring vendors with European satellite constellation control and ETRS89-certified data processing capabilities. Component supply concentrates in Germany, France, and the Netherlands for platform development, with specialized hardware sourcing from East Asian manufacturers. Raw material dependencies include gallium arsenide for GPS receivers, lithium for field-device batteries, and rare earth elements for sensor components. Single-source vulnerability sits with satellite imagery providers operating limited European orbital assets. Distribution runs through systems integrators and direct government procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native architectures are displacing legacy on-premises deployments, creating a technology-transition phase where subscription economics and edge-computing capabilities determine competitive survival.
For Market Incumbents: To counter SaaS-native entrants capturing mid-tier municipal accounts, deepen integration with British and German government geospatial standards while acquiring edge-AI capabilities for real-time utility monitoring. Prioritize certification investment for EU AI Act compliance on automated classification algorithms. For New Entrants and Emerging Players: Enter via Eastern European municipal underpenetration, specifically Romanian and Bulgarian local governments lacking mature spatial data infrastructure. Target bundled training-and-platform contracts as the most penetrable entry point, leveraging consumption-based SaaS pricing to bypass capital-budget barriers. For Investors and Strategic Acquirers: German federal infrastructure program accelerations are the leading indicator that 3D cadastral and real-time utility monitoring segments will consolidate. Long-term viability favors platform vendors with constellation-controlled data assets and INSPIRE-compliant metadata engines. Monitor EU AI Act classification determinations for machine-learning geospatial tools as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies spatial analytics, visualization, and carbon accounting for CSRD-compliant German manufacturers. |
| Acquisition of Specialist Firm | Captures edge-AI capabilities for Dutch water utility sub-second anomaly detection requirements. |
| Geographic Expansion | Targets Romanian and Bulgarian municipalities with bundled training and SaaS deployment models. |
| Strategic Partnership | Links BIM platforms with geospatial engines for UK urban planning digital twin workflows. |
| Product Launch | Introduces ETRS89-native calculation engines supporting Polish national mapping agency transitions. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across municipal GIS directors, utility asset managers, national mapping agency technical leads, and platform vendor product strategists. EU Space Programme Agency disclosures, EMA environmental data standards documentation, and member-state INSPIRE implementation reports provided compliance framework validation. Bottom-up procurement tracking and top-down market sizing triangulated segment estimates.
Country-level granularity modeled deployment mode transitions, vertical adoption intensity, and regulatory deadline proximity across the projection horizon. Segmentation dimensions spanned product type, end-user industry, deployment architecture, and application workflow depth. CAGRs derived from weighted scenario analysis incorporating federal funding trajectories and compliance mandate enforcement schedules. Satellite imagery refresh rate demands and edge-computing hardware adoption curves informed technology-transition assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU AI Act classification delays or ETRS89 migration timeline extensions. Projections reflect documented assumptions regarding German infrastructure program continuity and CSRD enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geographic Information Systems (GIS)
Europe Mobile Mapping Market
Geographic Information Systems (GIS)
Global HD Maps Market
Geographic Information Systems (GIS)
South Korea Location-Based Services Market
Geographic Information Systems (GIS)
Geographic Information System Analytics Market
Geographic Information Systems (GIS)
India Location-Based Services Market
Geographic Information Systems (GIS)
India Satellite Imagery Services Market
Geographic Information Systems (GIS)
Global GIS Market
Geographic Information Systems (GIS)
United States 3D Mapping and Modeling Market
Geographic Information Systems (GIS)
Global GIS in Telecom Sector Market
Geographic Information Systems (GIS)
Digital Elevation Model Market
Geographic Information Systems (GIS)
Mobile Mapping Market
Geographic Information Systems (GIS)
IP Geo-Location Services Market
Geographic Information Systems (GIS)
High Definition (HD) Maps Market
Geographic Information Systems (GIS)
US Location-Based Services Market
Geographic Information Systems (GIS)
Brazil Location Based Services Market
Geographic Information Systems (GIS)
United States Geographic Information System (GIS) Market