
 United States 3D Mapping and Modeling Market | 2026-2036
United States 3D Mapping and Modeling Market Size, Share, and Industry Trends Forecast 2026-2036
United States 3D Mapping and Modeling Market Intelligence
Domestic LiDAR sensor production is shifting from import-dependent assembly toward localized manufacturing in Arizona and Colorado facilities. Trimble leverages its precision agriculture heritage to anchor surveying hardware sales across the Midwest farm belt. Bentley Systems competes in infrastructure digital twin deployments through deep ties with state transportation departments. Esri dominates geospatial software licensing across federal civilian agencies and municipal planning offices.
3D mapping and modeling encompasses the acquisition, processing, and visualization of spatial data through point clouds, mesh surfaces, and parametric models rendered at centimeter-scale accuracy. The technology serves primary commercial purposes in asset monitoring, urban planning, and mission rehearsal where volumetric understanding replaces two-dimensional abstraction. Software and services command margin concentration as recurring subscription revenue displaces perpetual licensing in enterprise accounts. Cloud-based deployment grows fastest among mid-market engineering firms seeking elastic compute for photogrammetry pipelines. LiDAR retains technology leadership in topographic and utility corridor applications despite photogrammetry cost advantages in orthophoto generation.
FAA Part 107 waivers and forthcoming Beyond Visual Line of Sight rules shape aerial data collection economics for commercial operators. NIST geospatial data frameworks and USGS 3D Elevation Program standards dictate interoperability requirements for federal contract eligibility. State-level DOT specifications in California, Texas, and Florida increasingly mandate BIM-Level 2 compliance for transportation infrastructure awards. Stakeholders must monitor evolving FAA certification timelines and state procurement standardization to align capability roadmaps with funded project pipelines.
Market Dynamics
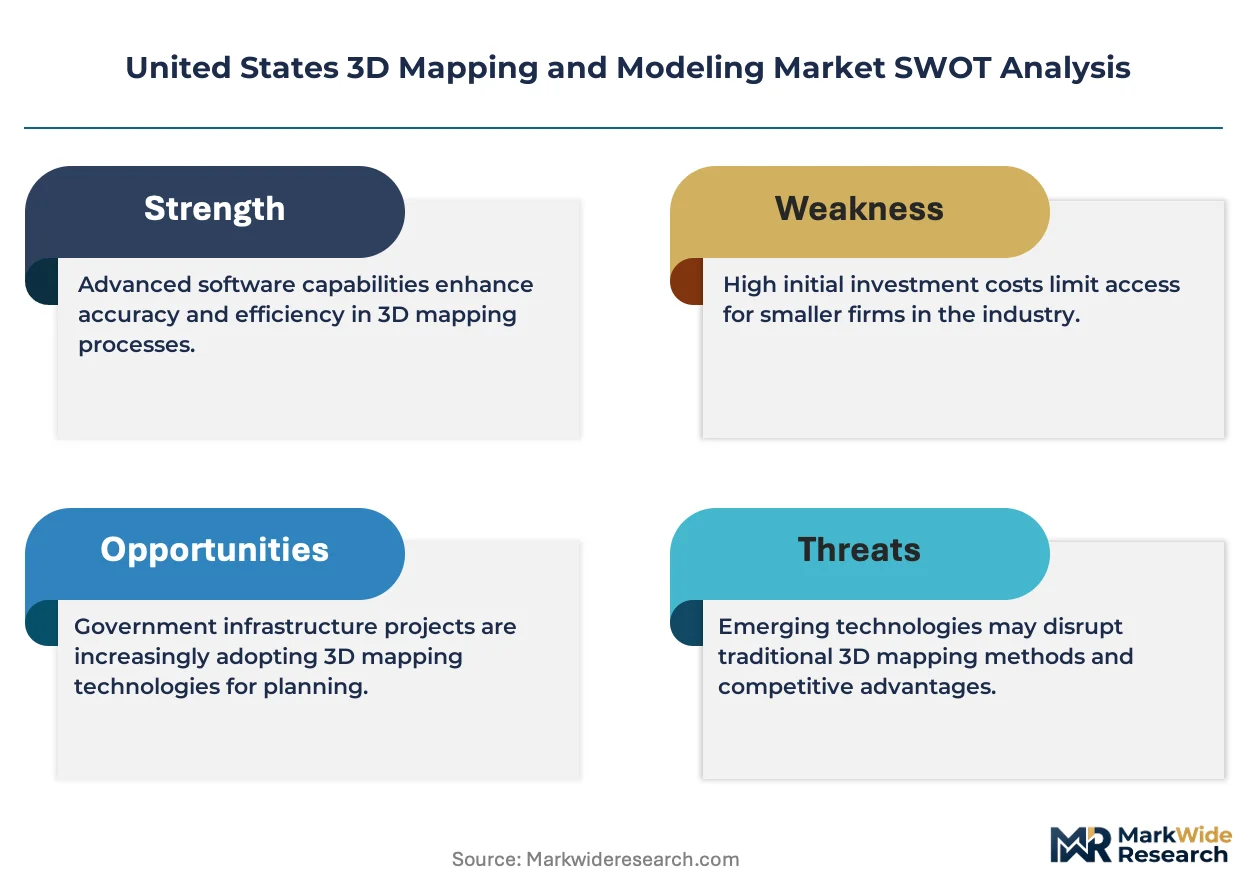
Defense procurement of geospatial intelligence platforms is compressing procurement cycles for dual-use LiDAR and photogrammetry systems across federal and state agencies. FAA regulatory relaxation on Beyond Visual Line of Sight drone operations is simultaneously expanding addressable aerial survey markets while fragmenting operator economics between capital-heavy fleet operators and software-centric data processors.
Growth Catalysts
- FAA Part 107 waiver expansion:Commercial drone operators now access broader airspace corridors for utility corridor and agricultural surveys, reducing mobilization costs for linear infrastructure projects.
- State DOT BIM mandates:California, Texas, and Florida transportation departments now require Level 2 Building Information Modeling compliance for major infrastructure awards, embedding 3D data deliverables into procurement specifications.
- USGS 3D Elevation Program:Federal funding for high-resolution topographic mapping sustains demand for airborne LiDAR services across federal land management and flood risk assessment applications.
Market Restraints
- LiDAR sensor import concentration:Domestic assembly remains dependent on foreign-sourced laser diode arrays and MEMS mirror components, exposing margins to tariff volatility and supply rationing.
- Photogrammetry substitution pressure:Advances in multi-camera drone arrays and GPU-accelerated dense matching software erode LiDAR's cost advantage in vegetation-free terrain applications.
- NIST interoperability compliance costs:Federal contract eligibility requires adherence to evolving geospatial data framework standards, forcing smaller survey firms into expensive certification cycles.
Strategic Opportunities
- Midwestern precision agriculture penetration:Variable-rate input application across Iowa and Illinois row-crop operations remains underpenetrated for centimeter-accurate elevation modeling relative to coastal infrastructure markets.
- Digital twin integration with IoT sensor networks:Convergence of static 3D basemaps with real-time structural health monitoring creates recurring revenue streams for infrastructure asset managers.
- Cloud-native photogrammetry pipelines:Elastic compute deployment allows mid-market engineering firms to bid large-area projects without capital-intensive on-premise render farms.
Industry Challenges
- Photogrammetrist skill scarcity:Pipeline operators struggle to hire technicians proficient in both traditional survey control and modern structure-from-motion software workflows.
- Legacy CAD-BIM integration friction:Municipal planning offices maintain decades of 2D as-built archives that resist automated conversion to parametric 3D models without manual feature extraction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States 3D Mapping and Modeling Market |
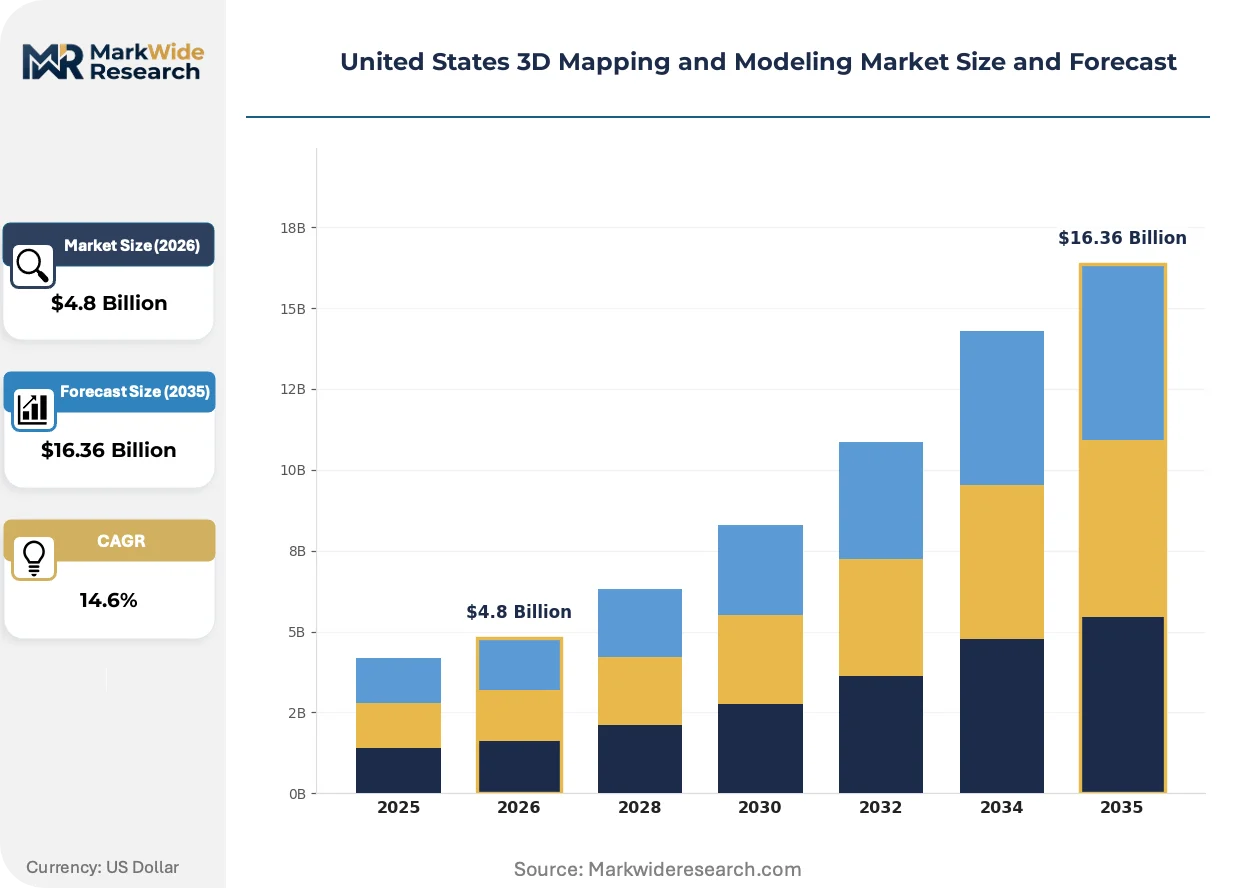
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Services, Solutions End User: Construction, Real Estate, Telecommunications, Defense Deployment Model: On-Premises, Cloud-Based, Hybrid, Mobile Technology: LiDAR, Photogrammetry, GIS, 3D Rendering |
| Companies Covered | Esri, Autodesk, Bentley Systems, Trimble, Hexagon AB, Google, Dassault Systèmes, Topcon Corporation, CyberCity 3D, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States 3D Mapping and Modeling Market Strategic Shifts & Innovations
LiDAR hardware economics and cloud compute accessibility are restructuring competitive boundaries between integrated sensor manufacturers and pure-play software analytics vendors. Three developments merit particular attention.
Neural radiance fields (NeRFs) are compressing photogrammetric reconstruction pipelines from hours to minutes for urban scene visualization. Real estate marketing teams and insurance adjusters are adopting NeRF-based walkthroughs for property documentation, displacing traditional 360-degree photography in high-value asset categories. The technology is converging with commodity smartphone LiDAR to democratize interior capture without dedicated survey equipment.
FAA forthcoming Beyond Visual Line of Sight regulations will establish type-certification pathways for automated drone-in-a-box systems. Long-haul pipeline and transmission line operators anticipate 24/7 aerial monitoring capabilities, though certification timelines remain uncertain. Texas energy corridor infrastructure managers are pre-positioning pilot programs to secure early operational approvals.
Subscription-based software licensing is displacing perpetual seat sales across municipal planning departments and mid-size engineering consultancies. Esri's maintenance renewal model and Bentley's iTwin platform demonstrate the transition. State transportation agencies in California and Florida now favor multi-year enterprise agreements with embedded training and support over capital-intensive upfront purchases.
United States 3D Mapping and Modeling Market Segmentation
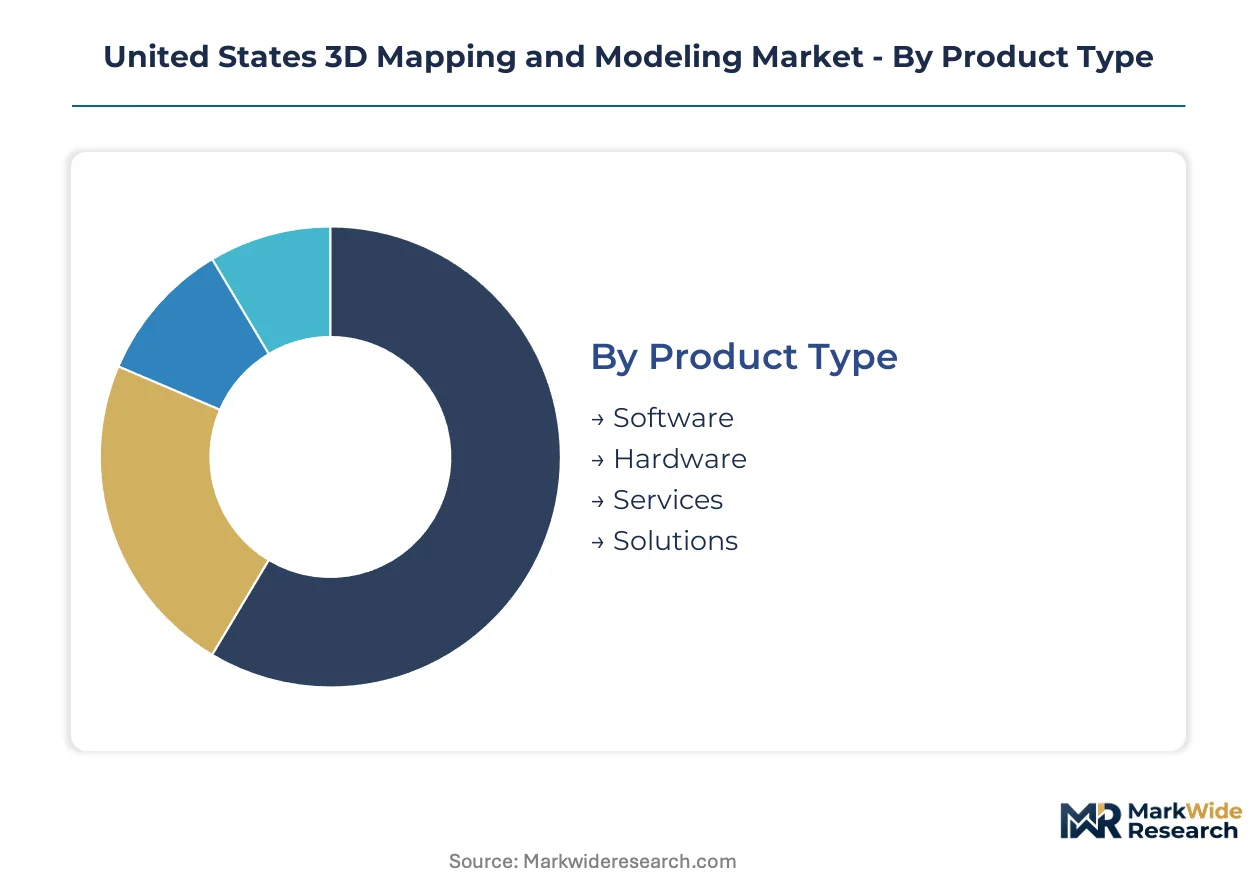
Segmentation in the United States 3D Mapping and Modeling Market reveals divergent capital requirements, deployment architectures, and buyer sophistication across federal, commercial, and municipal procurement channels. Understanding these fault lines enables vendors to align R&D roadmaps with funded project pipelines and recurring revenue opportunities.
Product Type:
Capital intensity varies sharply across product categories, with hardware requiring sensor fabrication facilities and software demanding elastic cloud infrastructure.
- Software:Cloud-native photogrammetry and point cloud processing platforms command recurring subscription revenue from engineering consultancies. California geospatial technology corridor firms and Texas energy infrastructure managers drive enterprise licensing for BIM-Level 2 compliance workflows.
- Hardware:LiDAR sensors, drone-mounted camera arrays, and GNSS receivers absorb the heaviest upfront manufacturing investment. Arizona and Colorado assembly facilities are localizing production to reduce dependency on foreign-sourced laser diode arrays and MEMS mirror components.
- Services:Aerial survey operators and data processing bureaus deliver project-based deliverables with lower fixed asset requirements.
- Solutions:Integrated hardware-software-service bundles target state transportation departments seeking turnkey digital twin deployments.
Hardware absorbs the bulk of installed capacity; software is expanding most quickly through subscription displacement of perpetual licensing.
End User:
Buyer sophistication and procurement cycle length create distinct margin profiles across vertical applications.
- Construction:General contractors and specialty trades deploy 3D models for clash detection and progress monitoring on federally funded infrastructure awards. State DOT BIM mandates in California, Texas, and Florida embed 3D deliverables into bid specifications.
- Defense:Geospatial intelligence platforms for mission rehearsal and terrain analysis command premium pricing through compressed federal procurement cycles. Dual-use LiDAR and photogrammetry systems bridge military and civilian agency demand.
- Real Estate:Property developers and insurance adjusters adopt NeRF-based visualization for high-value asset documentation.
- Telecommunications:5G network planners utilize centimeter-accurate elevation models for line-of-sight analysis in urban corridors.
Defense procurement concentrates the highest contract values; construction verticals are climbing the fastest as infrastructure stimulus flows through state agencies.
Deployment Model:
IT governance requirements and data sovereignty concerns shape enterprise architecture choices across federal and commercial accounts.
- Cloud-Based:Elastic compute for photogrammetry pipelines enables mid-market engineering firms to bid large-area projects without capital-intensive render farms. Municipal planning offices in Florida and California favor multi-year enterprise agreements with embedded training over upfront purchases.
- On-Premises:Classified defense applications and critical infrastructure operators maintain air-gapped processing environments for sensitive geospatial intelligence.
- Hybrid:Split architectures process raw sensor data locally while archiving finished models to cloud repositories.
- Mobile:Field crews leverage tablet-based visualization for real-time asset inspection and annotation.
On-premises deployments retain the largest installed base; cloud-based solutions are gaining share fastest among mid-market consultancies.
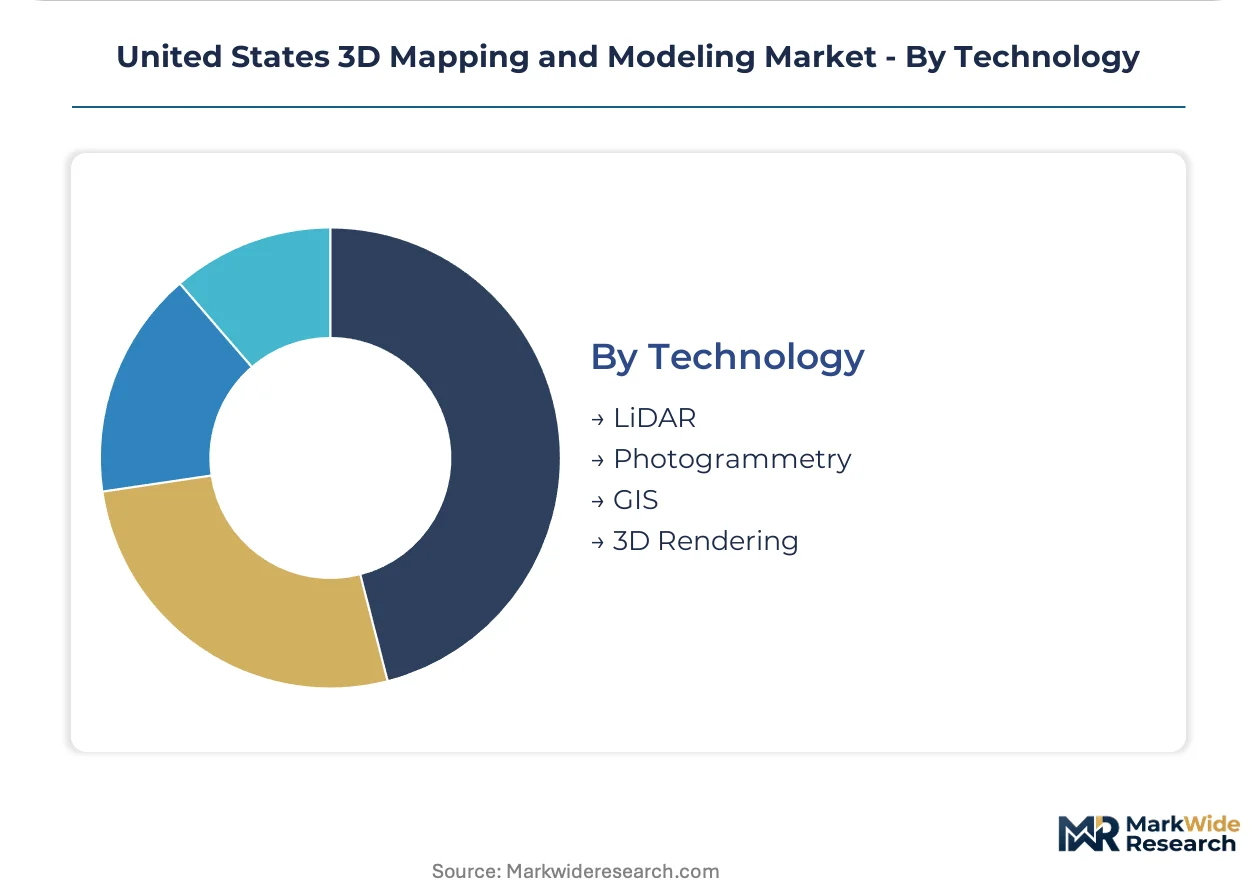
Technology:
Technical performance characteristics and cost economics drive substitution dynamics between competing data acquisition methods.
- LiDAR:Laser-based ranging achieves centimeter-scale accuracy through vegetation canopy and operates independent of lighting conditions. USGS 3D Elevation Program funding sustains airborne LiDAR demand across federal land management and flood risk assessment applications.
- Photogrammetry:Multi-camera drone arrays and GPU-accelerated dense matching software erode LiDAR's cost advantage in vegetation-free terrain. Neural radiance fields compress reconstruction pipelines from hours to minutes for urban scene visualization.
- GIS:Geospatial information systems provide the analytical backbone for layering 3D models with demographic, environmental, and infrastructure attribute data.
- 3D Rendering:Real-time visualization engines convert point clouds and mesh surfaces into immersive environments for stakeholder engagement and design review.
LiDAR retains technology leadership in topographic and utility corridor applications; photogrammetry is expanding most quickly through smartphone-based capture and NeRF democratization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's sensor fabrication ecosystem and Colorado's precision optics corridor anchor domestic LiDAR component sourcing for the national 3D mapping industry. State transportation departments in California, Texas, and Florida drive demand through BIM mandate enforcement.
California
Defense geospatial intelligence contracts and commercial drone surveying operations concentrate demand in the San Francisco Bay Area and Los Angeles basin. Caltrans BIM-Level 2 specifications for transportation infrastructure awards embed 3D deliverables into state procurement pipelines. The California geospatial technology corridor hosts software development clusters for point cloud processing and photogrammetry analytics.
Texas
Energy infrastructure corridor managers deploy centimeter-accurate elevation models for pipeline monitoring and transmission line planning across the Permian Basin and Gulf Coast. FAA Part 107 waiver expansion enables broader aerial survey access for utility corridor operators. Houston and Dallas-Fort Worth anchor service provider networks for oilfield asset digitization.
Florida
Flood risk assessment applications and coastal resilience planning sustain airborne LiDAR demand for federal and state land management agencies. Florida DOT mandates Level 2 Building Information Modeling compliance for major bridge and highway awards. Miami and Tampa metropolitan areas concentrate municipal planning offices adopting cloud-native photogrammetry platforms.
Colorado
USGS 3D Elevation Program funding supports high-resolution topographic mapping across federal land management jurisdictions in the Rocky Mountain region. Denver-Boulder corridor facilities localize LiDAR sensor assembly to reduce dependency on foreign-sourced laser diode components. Precision agriculture penetration remains underdeveloped relative to coastal infrastructure markets.
Illinois
Midwestern row-crop operations in Iowa and Illinois represent underpenetrated demand for variable-rate input application using centimeter-accurate elevation modeling. Chicago anchors engineering consultancy networks serving agricultural and transportation verticals. State procurement standardization lags California and Texas DOT specifications.
United States 3D Mapping and Modeling Market Key Industry Players
Global majors compete with regional champions across software licensing and sensor hardware segments. The vendor base stratifies between integrated platform providers and specialized component suppliers. Three archetypes dominate: precision agriculture heritage hardware vendors, infrastructure digital twin platform operators, and geospatial software licensing incumbents. Competitive moves center on subscription model transitions and cloud-native pipeline development.
Within the geospatial software tier, Esri and Autodesk exemplify platform incumbents transitioning maintenance renewal models toward multi-year enterprise agreements. Bentley Systems occupies a position among infrastructure-focused digital twin operators with state transportation department relationships. Trimble anchors precision agriculture and surveying hardware supply chains across Midwestern farm markets. These three companies represent divergent strategic positions without implying specific market share claims.
| Leading Market Players |
|---|
| Esri |
| Autodesk |
| Bentley Systems |
| Trimble |
| Hexagon AB |
| Dassault Systèmes |
| Topcon Corporation |
| CyberCity 3D |
| Others |
Cost & Logistics Intelligence
FAA Part 107 certification requirements for commercial drone operators gate qualified aerial survey supply and sustain premium-tier pricing for certified service providers. Equipment vendors bundle training credits and airspace compliance consulting into enterprise agreements, while unbundled hardware sales face margin compression from photogrammetry substitution.
Pricing Analysis
Warranty and service bundling separates incumbent platform vendors from commodity hardware suppliers. Three-tier pricing structure across premium, standard, and economy levels reflects software subscription tiers, sensor accuracy grades, and embedded training intensity. Cost compression in economy-tier photogrammetry hardware is intensifying because smartphone-based NeRF capture erodes dedicated equipment demand. Municipal planning offices exhibit highest price sensitivity; defense geospatial intelligence contracts show lowest sensitivity due to mission-critical procurement timelines.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese semiconductor foundries fabricating LiDAR signal processing chips and Chinese manufacturers of laser diode arrays. Domestic assembly draws from German precision optics, Japanese MEMS components, and domestic Arizona and Colorado fabrication facilities. Tariff exposure on foreign-sourced laser components threatens margin stability for hardware vendors. Distribution runs through authorized surveying equipment dealers and direct enterprise sales teams serving state transportation departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players pursue backward integration into LiDAR sensor fabrication to escape foreign component dependency and capture margin upstream.
For Market Incumbents: Anchor platform stickiness through multi-year enterprise agreements embedding FAA compliance training and cloud-native photogrammetry pipelines. Counter photogrammetry substitution by certifying proprietary sensor fusion algorithms for state DOT BIM mandates. Vertical integration into Arizona and Colorado assembly facilities reduces tariff exposure on foreign laser components. For New Entrants and Emerging Players: State transportation department channel partners offer the fastest path to contracted revenue without competing head-to-head with Esri's federal agency relationships. Target underpenetrated Midwestern precision agriculture markets in Iowa and Illinois where variable-rate input application demand lags coastal infrastructure corridors. Lead with subscription-based NeRF visualization tools for real estate and insurance verticals. For Investors and Strategic Acquirers: FAA Beyond Visual Line of Sight rule finalization is the leading indicator that automated drone-in-a-box systems will unlock 24/7 infrastructure monitoring revenue streams. Five-to-ten-year viability favors vendors with integrated hardware-software-service bundles and state procurement relationships. Watch Texas energy corridor pilot programs for early operational approval signals.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Photogrammetry Platform Launch | Elastic compute access allows mid-market engineering firms to bid large-area projects without capital-intensive render farms. |
| LiDAR Sensor Fabrication Scale-Up | Arizona and Colorado facilities localize production to reduce dependency on foreign-sourced laser diode arrays and MEMS mirror components. |
| FAA Part 107 Training Certification Program | Embedded airspace compliance consulting differentiates enterprise agreements from commodity hardware sales. |
| State DOT Digital Twin Partnership | California, Texas, and Florida transportation departments mandate BIM-Level 2 compliance for major infrastructure awards. |
| NeRF Visualization Software Acquisition | Neural radiance fields compress reconstruction pipelines from hours to minutes for real estate and insurance documentation. |
Research Approach
Independent corroboration across FAA regulatory filings, USGS 3D Elevation Program procurement records, and state DOT bid specifications underwrites the qualitative findings. Primary interviews with aerial survey operators, geospatial software product managers, state transportation procurement officers, and LiDAR hardware engineering directors combined with secondary validation from SEC filings, USGS technical standards documentation, and FAA waiver databases. Bottom-up segment sizing triangulates against top-down federal funding allocation analysis.
Comparable-period anchoring to historical USGS program cycles and state infrastructure stimulus deployment patterns shaped the projection horizon. Segmentation dimensions modeled include deployment architecture, end-user vertical, technology type, and state procurement maturity. CAGRs derive from funded project pipeline analysis and subscription revenue transition trajectories across municipal planning offices. Forecast inputs incorporate FAA certification timeline probabilities and photogrammetry algorithm advancement curves.
Caveats apply where FAA Beyond Visual Line of Sight rule delays, tariff escalation on Chinese laser components, or photogrammetry substitution acceleration could materially shift the outlook. Forecasts reflect documented assumptions about regulatory pacing and technology cost curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geographic Information Systems (GIS)
Asia Pacific Digital Maps Market
Geographic Information Systems (GIS)
Geographic Information System Analytics Market
Geographic Information Systems (GIS)
Mobile Map Market
Geographic Information Systems (GIS)
High Definition (HD) Maps Market
Geographic Information Systems (GIS)
India Satellite Imagery Services Market
Geographic Information Systems (GIS)
Geomarketing Market
Geographic Information Systems (GIS)
Nigeria Location-Based Services Market
Geographic Information Systems (GIS)
China Geospatial Analytics Market
Geographic Information Systems (GIS)
Japan Location-Based Services Market
Geographic Information Systems (GIS)
South Korea Geospatial Analytics Market
Geographic Information Systems (GIS)
Electronic Cartography Market
Geographic Information Systems (GIS)
Cloud GIS Market
Geographic Information Systems (GIS)
China Location-Based Services Market
Geographic Information Systems (GIS)
Geographic Information System (GIS) Software Market
Geographic Information Systems (GIS)
US Location-Based Services Market
Geographic Information Systems (GIS)
Location Intelligence Market