
 Global Hardware Security Modules (HSM) Market | 2026-2036
Global Hardware Security Modules (HSM) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hardware Security Modules (HSM) Market Analysis
Cloud-native key management architectures is tilting enterprise HSM deployment from on-premises appliances to subscription-based cloud HSM services. Thales Group leverages its Luna Cloud HSM portfolio to anchor hybrid deployments across North American and European financial institutions. Utimaco GmbH specializes in high-assurance hardware for government certification schemes, sustaining long-term contracts with defense and intelligence agencies. IBM Corporation competes through deep integration with its public cloud infrastructure, extending managed HSM services to enterprises seeking consolidated security stacks.
A Hardware Security Module is a physical computing device that safeguards and manages digital keys, performs encryption and decryption functions, and provides tamper-evident or tamper-resistant cryptographic processing within FIPS 140-2 or Common Criteria certified enclosures. Its primary commercial purpose is to establish a root of trust for sensitive operations including payment authorization, code signing, and identity verification in regulated industries. Network-attached HSM dominates enterprise data center deployments due to established interoperability with PKI and payment HSM standards, while cloud HSM represents the fastest-expanding product category as hyperscalers embed hardware roots of trust into multi-tenant environments. Embedded HSM occupies mature positions in automotive ECU and IoT gateway designs where physical footprint constraints and unit cost sensitivity limit margin expansion.
FIPS 140-3 certification requirements from NIST, Common Criteria evaluations under the international mutual recognition arrangement, and PCI HSM compliance mandates from the PCI Security Standards Council collectively elevate barriers to market entry and sustain premium pricing for certified vendors. GDPR data protection obligations across European Union member states and emerging post-quantum cryptography standards from NIST are reshaping product roadmaps and forcing accelerated refresh cycles. Stakeholders must monitor quantum-safe algorithm finalization timelines and cloud provider HSM API standardization efforts to anticipate displacement risks in existing installed bases.
Market Dynamics
Post-quantum cryptography migration timelines from NIST are compressing replacement cycles across financial and government installations, forcing accelerated capital deployment into quantum-resistant HSM infrastructure before algorithm standardization completes.
Growth Catalysts
- FedRAMP Compliance Mandates:United States federal zero-trust architecture requirements are reshaping enterprise security procurement patterns across cloud service providers and defense contractors.
- PCI HSM Standards:Payment card industry compliance mandates from the PCI Security Standards Council sustain premium pricing for certified vendors serving transaction authorization workloads.
- Cloud Key Management:Hyperscalers are embedding hardware roots of trust into multi-tenant environments, expanding subscription-based HSM service adoption across North American and European financial institutions.
Market Restraints
- FIPS 140-3 Certification Costs:NIST validation timelines and testing expenses create capital barriers for new entrants seeking federal procurement eligibility.
- Semiconductor Supply Concentration:Tamper-resistant enclosure manufacturing and secure microcontroller fabrication concentrate in East Asian foundries, exposing lead time vulnerabilities.
- Common Criteria Evaluation Backlogs:International mutual recognition arrangement processing delays extend product launch timelines for government certification schemes.
Strategic Opportunities
- Automotive ECU Integration:Embedded HSM designs for vehicle gateway security remain underpenetrated relative to connected car deployment rates in Germany and Japan.
- GDPR Data Protection:European Union member state enforcement of encryption key custody requirements creates procurement pull for high-assurance hardware across healthcare and banking sectors.
- Quantum-Safe Algorithm Convergence:Lattice-based cryptography standards from NIST are converging with existing PKI infrastructure, enabling hybrid cryptographic architectures in financial data centers.
Industry Challenges
- Post-Quantum Cryptography Expertise:Quantum-safe algorithm implementation skills remain scarce across firmware engineering and cryptographic architecture functions.
- Legacy PKI Integration Complexity:Certificate authority infrastructure built on RSA and elliptic curve standards requires phased migration planning without service disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hardware Security Modules (HSM) Market |
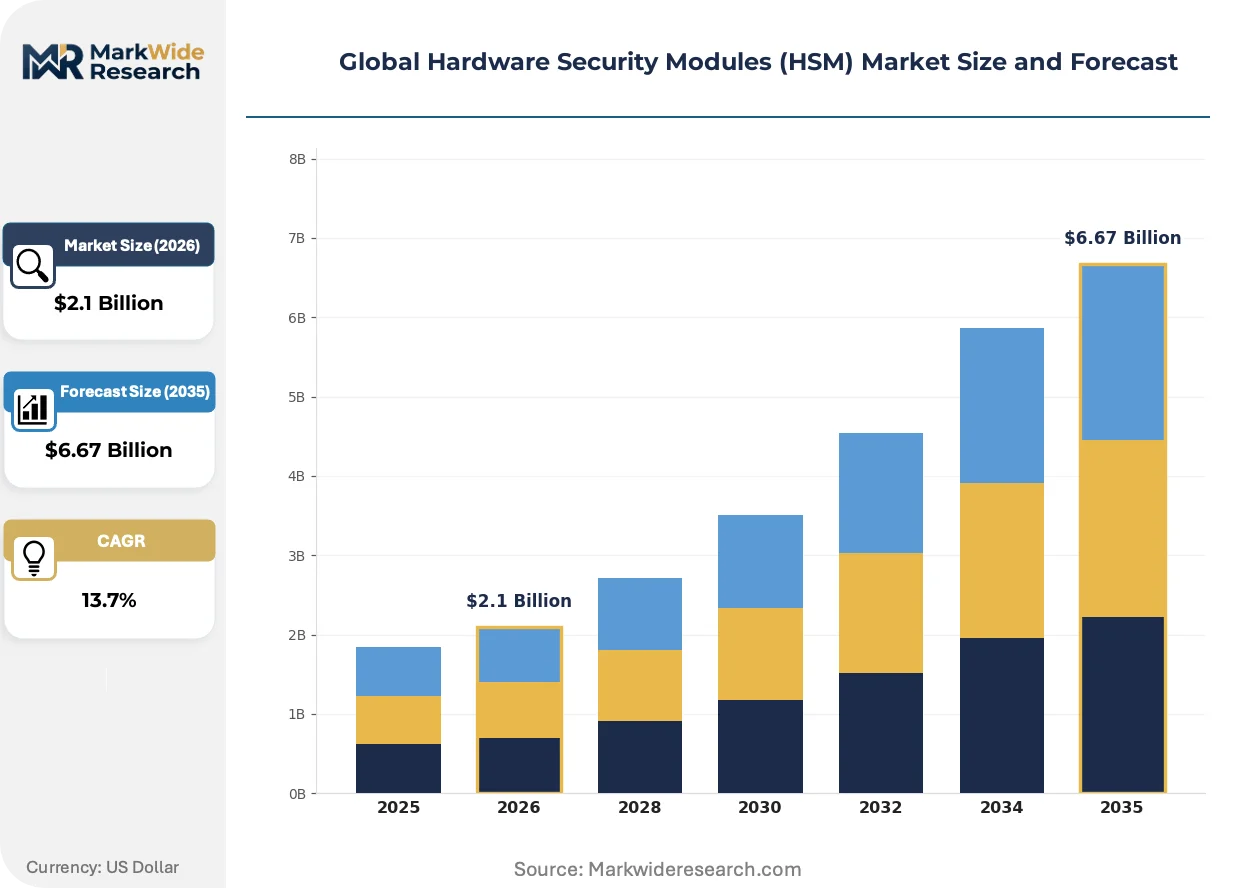
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $6.67 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embedded HSM, Network-attached HSM, Cloud HSM, Portable HSM Application: Payment Processing, Digital Signatures, Key Management, Secure Boot End User: Banking, Government, Telecommunications, Healthcare Technology: Asymmetric Cryptography, Symmetric Cryptography, Hybrid Cryptography, Quantum Cryptography |
| Companies Covered | Thales Group, IBM Corporation, Utimaco GmbH, Entrust Corporation, Futurex, Atos SE, Gemalto NV, Infineon Technologies AG, Securosys SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hardware Security Modules (HSM) Market Emerging Trajectories
Hardware security architecture is migrating from appliance-centric deployments toward distributed trust models embedded across cloud, edge, and endpoint environments. This structural shift redefines vendor competitive positioning around software integration depth rather than physical enclosure differentiation alone.
Network-attached HSM form factors are migrating from dedicated data center appliances toward containerized and virtualized implementations that preserve hardware root-of-trust guarantees. Financial institutions in the United States and Germany are adopting these hybrid deployments to maintain FIPS 140-2 Level 3 certification while enabling elastic scaling for peak transaction volumes. The technology is migrating from static perimeter security models toward identity-centric zero-trust architectures that demand continuous cryptographic verification.
GDPR data protection obligations across European Union member states are mandating encryption key custody controls that elevate hardware-based assurance over software-only implementations. The regulation's territorial scope forces multinational enterprises to deploy EU-resident HSM infrastructure for personal data processing workloads. Cloud service providers are responding with region-specific hardware deployments certified under Common Criteria EAL4+ and FIPS 140-3 schemes.
Enterprise procurement of HSM capacity is consolidating through managed security service providers and hyperscaler marketplaces rather than direct OEM relationships. Mid-market buyers in the United Kingdom and France are accessing Thales Luna Cloud HSM and comparable services through AWS, Azure, and GCP native integrations. This channel migration compresses vendor margins while expanding addressable market reach beyond traditional high-assurance buyers.
Global Hardware Security Modules (HSM) Market Segmentation
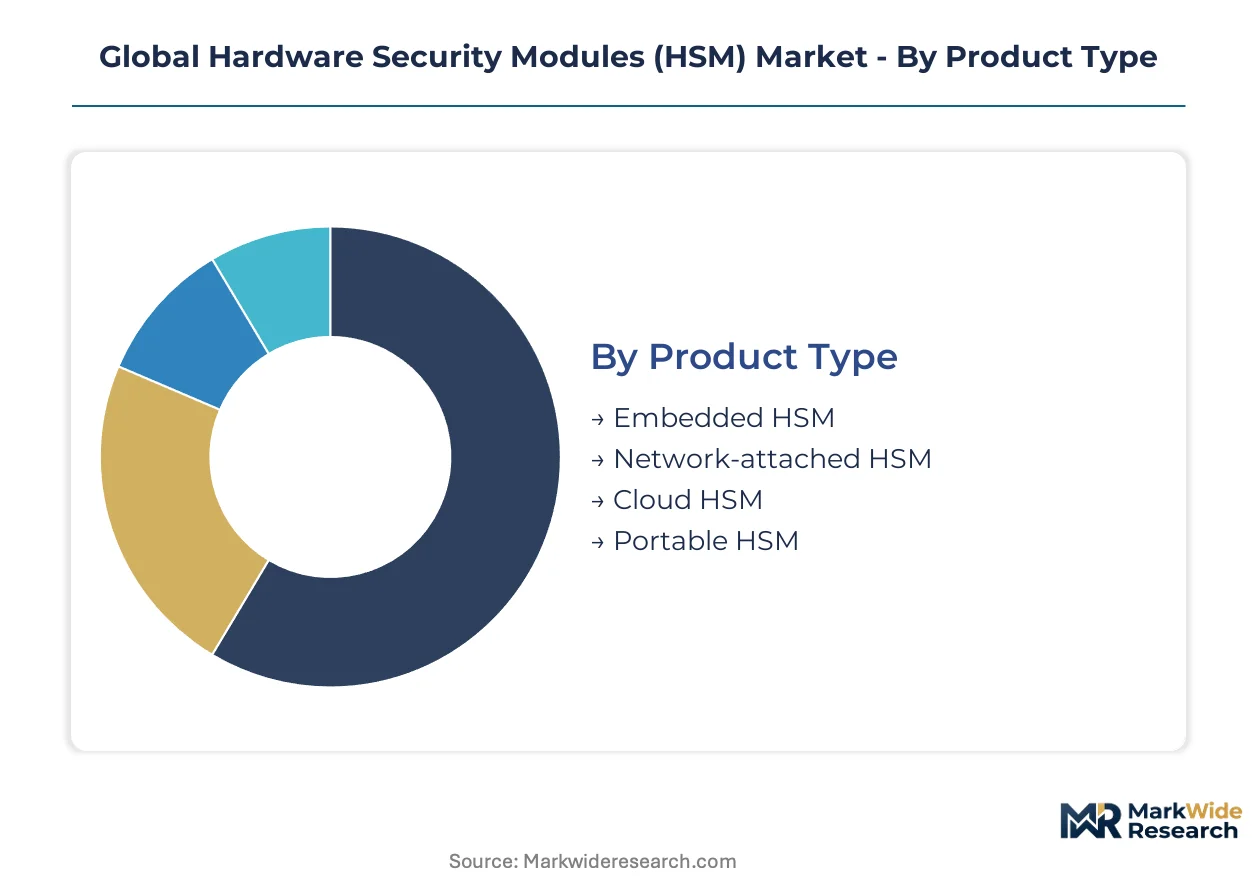
Hardware Security Module procurement patterns diverge sharply across deployment contexts, with certification requirements and integration complexity creating distinct service ecosystems around each segment. Understanding these structural divisions reveals where vendor margins concentrate and where commoditization pressures intensify.
Product Type:
After-sales service intensity varies dramatically across form factors, with network-attached appliances demanding perpetual firmware maintenance while cloud subscriptions shift operational burden to provider infrastructure.
- Network-attached HSM:Rack-mounted appliances delivering FIPS 140-2 Level 3 certified cryptographic operations through Ethernet or PCIe interfaces. Banking data centers in the United States and Germany dominate procurement, driven by PCI HSM compliance mandates for transaction authorization workloads and legacy PKI infrastructure that resists cloud migration.
- Cloud HSM:Subscription-managed hardware roots of trust provisioned through hyperscaler APIs, abstracting physical infrastructure while preserving certification boundaries. Financial institutions across the United Kingdom and France are consolidating procurement through AWS, Azure, and GCP native integrations, compressing vendor margins while expanding addressable market reach.
- Embedded HSM:Tamper-resistant secure elements integrated directly into circuit board designs for physical footprint-constrained applications.
- Portable HSM:USB-connected or battery-powered devices enabling key custody mobility for field operations and disaster recovery scenarios.
By volume, Network-attached HSM leads. By growth pace, Cloud HSM is ahead.
Application:
Margin structures align with regulatory enforcement intensity, with payment processing commanding premium pricing due to PCI Security Standards Council certification requirements while secure boot operates in cost-sensitive embedded supply chains.
- Payment Processing:Transaction authorization and PIN verification workloads requiring dedicated PCI HSM compliance, hardware acceleration for symmetric cryptography, and tamper-detection mechanisms that destroy key material upon physical intrusion. Demand concentrates in United States acquiring banks and German card issuers facing network tokenization mandates and contactless volume surges.
- Key Management:Enterprise-wide cryptographic key lifecycle governance encompassing generation, distribution, rotation, and destruction across heterogeneous infrastructure. Cloud service providers in North America and European Union member states are expanding procurement for multi-tenant encryption services, responding to GDPR data protection obligations that mandate hardware-based key custody controls.
- Digital Signatures:Code signing, document authentication, and certificate authority operations establishing non-repudiation for software distribution and legal transactions.
- Secure Boot:Firmware integrity verification and trusted execution environment establishment for connected devices and industrial control systems.
Payment Processing captures the highest average selling prices. Key Management demonstrates the steepest expansion trajectory.
End User:
Procurement sophistication tiers separate banking and government buyers with dedicated cryptographic architecture teams from healthcare and telecommunications purchasers relying on systems integrators.
- Banking:Tier-one financial institutions operating 24/7 transaction processing infrastructure with zero-downtime certificate rotation requirements and regulatory capital implications for security failures. United States money center banks and German Landesbanks are accelerating post-quantum cryptography migration timelines ahead of NIST standardization, compressing replacement cycles for RSA and elliptic curve infrastructure.
- Government:Defense, intelligence, and civilian agencies mandating Common Criteria EAL4+ or FIPS 140-3 Level 4 certifications for classified and high-impact unclassified workloads. Long-term contracting patterns in the United States and selective European NATO members sustain premium pricing for Utimaco and Thales high-assurance product lines.
- Telecommunications:Mobile network operators and equipment manufacturers securing subscriber identity modules, lawful intercept interfaces, and 5G infrastructure.
- Healthcare:Payers and providers encrypting protected health information under HIPAA technical safeguards in the United States and national implementations across European Union member states.
Banking generates the largest absolute revenue pool. Government contracts deliver the longest visibility horizons.
Technology:
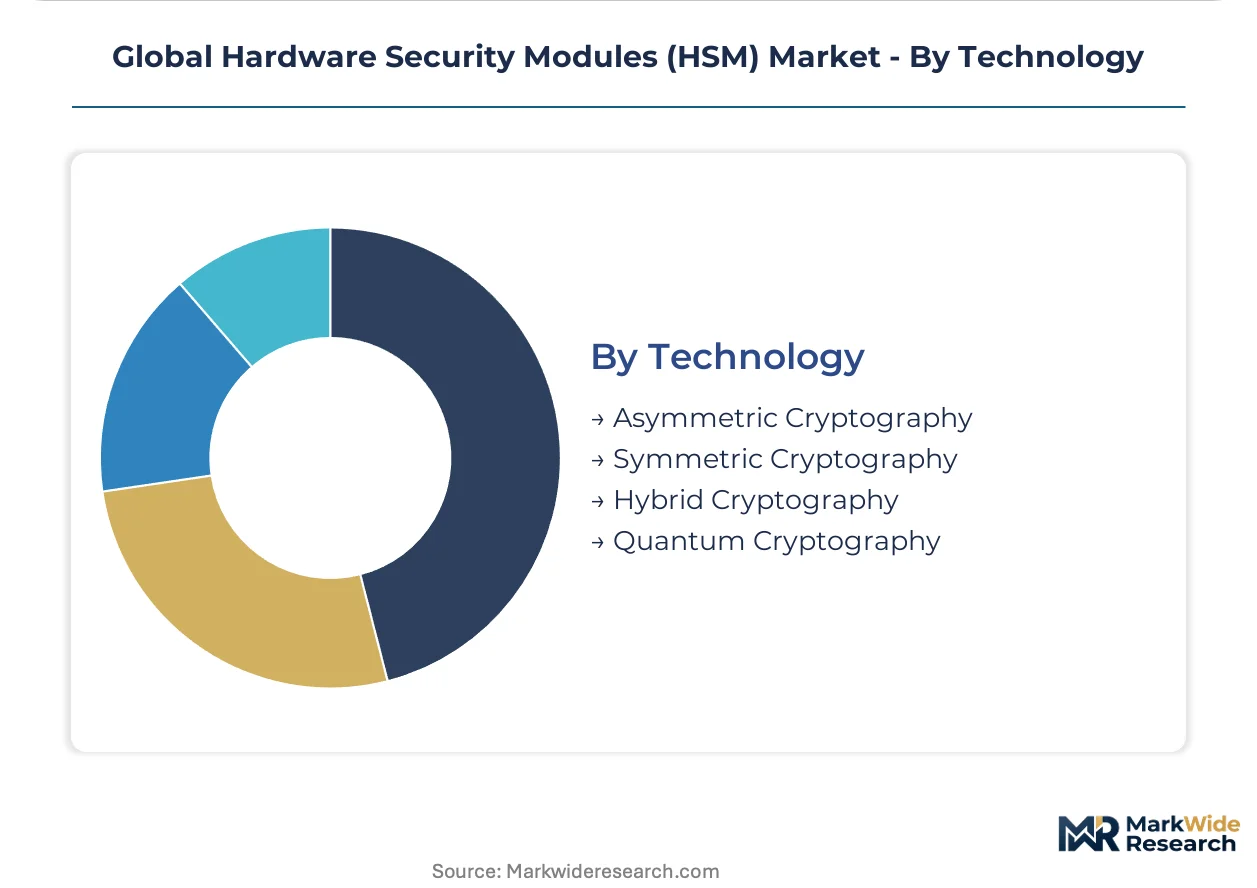
Algorithm migration roadmaps are fragmenting vendor development resources across concurrent standards tracks, with asymmetric cryptography requiring phased deprecation planning while quantum cryptography remains pre-commercial.
- Asymmetric Cryptography:RSA and elliptic curve algorithms dominating current PKI infrastructure, certificate authorities, and digital signature implementations. Financial institutions in the United States face NIST-mandated migration timelines toward quantum-resistant alternatives, forcing capital deployment into hybrid architectures before lattice-based standardization completes.
- Hybrid Cryptography:Concurrent deployment of classical and post-quantum algorithms within single HSM enclosures, enabling phased migration without service disruption. German automotive suppliers and United States federal contractors are piloting these configurations to satisfy procurement requirements that demand crypto-agility without premature commitment to unproven standards.
- Symmetric Cryptography:AES and Triple-DES implementations for bulk data encryption and payment PIN processing.
- Quantum Cryptography:Quantum key distribution and quantum random number generation technologies operating at experimental scale.
Asymmetric Cryptography dominates installed base value. Hybrid Cryptography is gaining share fastest among new deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Banking and defense procurement teams in the United States, Germany, United Kingdom, Japan, and Australia concentrate the majority of certified HSM purchasing authority. Federal mandates and payment industry standards drive replacement cycles across these jurisdictions.
United States
Money center banks and cloud hyperscalers dominate procurement volumes. NIST FIPS 140-3 mandates and FedRAMP compliance requirements reshape vendor selection criteria. Northern Virginia data center clusters host the densest concentration of cloud HSM deployments for federal workloads.
Germany
Automotive suppliers and Landesbanks accelerate post-quantum cryptography pilot programs. GDPR enforcement by German data protection authorities mandates EU-resident key custody infrastructure. Munich and Frankfurt financial districts anchor high-assurance hardware procurement for transaction processing.
United Kingdom
Mid-market financial institutions access HSM capacity through AWS and Azure native integrations. The Financial Conduct Authority's operational resilience requirements elevate certified hardware deployment standards. London fintech clusters drive cloud HSM subscription growth ahead of continental European peers.
Japan
Mobile network operators and automotive ECU manufacturers sustain embedded HSM demand. METI guidelines on critical infrastructure protection reinforce hardware-based cryptographic assurance. Tokyo and Nagoya industrial corridors concentrate secure element integration for connected vehicle platforms.
Australia
Commonwealth agencies and major banks align procurement with the Australian Cyber Security Centre's Essential Eight framework. The Reserve Bank's payment system oversight mandates PCI HSM compliance for domestic card schemes. Sydney and Melbourne financial centers anchor regional procurement authority.
Global Hardware Security Modules (HSM) Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement pathways. The vendor base stratifies between hyperscaler-integrated service providers and certification-focused hardware specialists. Three archetypes dominate: cloud-native platform vendors, government-certified high-assurance specialists, and embedded secure element manufacturers. M&A activity concentrates on API standardization capabilities and Common Criteria evaluation expertise.
Among European high-assurance specialists, Thales Group and Utimaco GmbH exemplify divergent strategic positioning. Thales leverages its Luna Cloud HSM portfolio to anchor hybrid deployment architectures across North American financial institutions. Utimaco occupies a position within government certification schemes, sustaining long-term contracting relationships with defense and intelligence agencies requiring Common Criteria EAL4+ enclosures. IBM Corporation represents the cloud-integrated archetype, competing through managed HSM services embedded within consolidated security stacks.
| Leading Market Players |
|---|
| Thales Group |
| IBM Corporation |
| Utimaco GmbH |
| Entrust Corporation |
| Futurex |
| Atos SE |
| Gemalto NV |
| Infineon Technologies AG |
| Securosys SA |
| Others |
Supply Flow & Price Mechanics
Taipei-based secure microcontroller foundries anchor global HSM component supply, with capacity utilization rates at these facilities directly transmitting into pricing leverage for downstream enclosure integrators. Certification backlog delays at NIST and Common Criteria evaluation labs amplify this dynamic, allowing certified vendors to command sustained premiums while uncertified competitors face margin compression from extended time-to-revenue cycles.
Pricing Analysis
Cost-plus contracts with semiconductor raw material indexation dominate procurement between enclosure manufacturers and secure element suppliers. Pricing stratifies across FIPS 140-2 Level 3, FIPS 140-3 Level 4, and Common Criteria EAL4+ certification tiers, with government buyers showing least price sensitivity due to long-term contracting mandates. Cloud HSM subscription tiers face cost compression from hyperscaler volume aggregation, while on-premises appliance margins hold firmer in banking data centers with legacy PKI lock-in.
Supply Chain Analysis
Foundry capacity at Taiwan Semiconductor Manufacturing Company and United Microelectronics Corporation concentrates secure microcontroller fabrication for tamper-resistant designs. East Asian supply draws from specialized ceramic substrate suppliers and electromagnetic shielding material providers concentrated in Japan and South Korea. Single-source vulnerability in tamper-detection mesh manufacturing exposes lead time risks. Distribution runs through direct OEM relationships for high-assurance government buyers and hyperscaler marketplace integrations for cloud service procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Hardware Security Modules market is entering a cyclical upswing driven by post-quantum cryptography replacement cycles, with NIST algorithm standardization timelines forcing premature capital deployment that will sustain demand velocity through the analysis window.
For Market Incumbents: Pre-empt displacement from cloud-native key management platforms by deepening API standardization investments and securing FedRAMP authorization boundaries before hyperscalers consolidate procurement channels. Anchor certification velocity through vertical integration into Common Criteria evaluation expertise, reducing time-to-market for FIPS 140-3 Level 4 products against emerging government requirements. For New Entrants and Emerging Players: Build out specialized post-quantum cryptography implementation capabilities to address acute firmware engineering scarcity across financial and defense contractor installations. Target automotive ECU security as the most penetrable embedded segment, leveraging existing relationships with Tier 1 suppliers in Germany and Japan to bypass incumbent certification moats in banking and government verticals. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud HSM service providers with hyperscaler marketplace integrations, positioning these archetypes for superior cash flow quality across a 5-10 year holding period. Prioritize acquisition targets possessing Common Criteria evaluation expertise and established EAL4+ product lines. Monitor NIST post-quantum algorithm finalization announcements as the critical inflection signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Quantum Cryptography Certification | FIPS 140-3 validation for lattice-based algorithms captures federal procurement eligibility before standardization completes. |
| Hyperscaler Marketplace Integration | Native AWS, Azure, and GCP API embedding compresses customer acquisition costs for cloud HSM services. |
| Common Criteria Evaluation Acquisition | In-house EAL4+ testing capability eliminates third-party backlog delays for government contract pursuit. |
| Automotive ECU Security Partnership | Collaboration with German Tier 1 suppliers establishes embedded HSM beachhead in connected vehicle platforms. |
| FedRAMP Authorization Acceleration | Pre-authorized status enables direct sales to U.S. federal agencies under zero-trust architecture mandates. |
Methodological Framework
A standing panel of cryptographic architecture directors, federal procurement officers, cloud security engineers, and Common Criteria evaluation lab technicians provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with these stakeholders against secondary validation from NIST certification databases, PCI Security Standards Council compliance registries, hyperscaler service documentation, and SEC filings of publicly traded cybersecurity vendors. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Scenario-bracketing around post-quantum algorithm standardization timelines and cloud adoption velocity bounded the projection range. The analytical framework modeled deployment model, certification tier, end-user vertical, and geographic regulatory cluster as core segmentation dimensions. CAGRs derived from elasticity-adjusted penetration curves incorporating NIST mandate enforcement intensity and GDPR territorial enforcement patterns. Forecast inputs included banking IT capex surveys and federal cybersecurity budget appropriation trajectories.
Practitioners should monitor NIST algorithm finalization announcements, hyperscaler HSM API roadmap disclosures, and Common Criteria evaluation queue lengths for early signals of demand inflection or supply constraint. Forecasts embed assumptions regarding certification timeline continuity and semiconductor foundry capacity expansion that material deviation could revise. Quarterly review of federal procurement award databases and cloud provider infrastructure capex disclosures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Content Protection and Watermarking Market
Security Software
Global Wireless Intrusion Prevention System Market
Security Software
Global Secure Access Service Edge Market
Security Software
Spam Blocking Software Market
Security Software
Global Network Encryption Market
Security Software
AI in Security Market
Security Software
Cloud Data Loss Prevention Solution Market
Security Software
Managed Security Services Market
Security Software
Global Network Security Software Market
Security Software
Endpoint Detection and Response [EDR] Market
Security Software
Automotive Endpoint Authentication Market
Security Software
Application Control Market
Security Software
Global Dynamic Application Security Testing Market
Security Software
Decentralized Identity Software Market
Security Software
Wi-Fi Based Home Camera Market
Security Software
Security Information and Event Management Software Market