
 United States Geographic Information System (GIS) Market | 2026-2036
United States Geographic Information System (GIS) Market Size, Share, and Industry Trends Forecast 2026-2036
United States Geographic Information System (GIS) Market Intelligence
State and local emergency management agencies is redrawing procurement patterns across the United States GIS landscape. Esri anchors government verticals through entrenched enterprise licensing and decades of institutional workflow integration. Trimble competes in precision field hardware, leveraging its dominance in GPS-enabled surveying instruments for construction and agriculture. Mapbox differentiates through developer-centric vector tile infrastructure, sustaining growth among logistics and mobility startups seeking customizable base mapping.
Geographic Information System technology constitutes spatial data infrastructure that captures, stores, analyzes, and visualizes georeferenced information through layered vector and raster datasets, typically operating with sub-meter coordinate accuracy and supporting real-time sensor fusion. Its primary commercial purpose centers on location-based decision support for asset tracking, land use optimization, and environmental monitoring. Software and cloud solutions command the dominant value share as agencies migrate from perpetual licenses to subscription architectures, while services revenue expands fastest where municipalities lack in-house geospatial analytics capacity. Hardware retains stable demand in field data collection, though margin pools have shifted decisively toward SaaS platforms and managed analytics.
FERC grid modernization standards, EPA environmental impact assessment protocols, and state-level open data mandates collectively shape product roadmaps and certification requirements for vendors serving public-sector buyers. These frameworks compel GIS providers to embed audit trails, interoperability standards, and climate scenario modeling tools directly into platform offerings. Stakeholders must monitor how federal infrastructure spending allocation formulas redirect procurement toward resilience-focused spatial analytics rather than traditional cadastral mapping.
Market Dynamics
Federal cloud-first mandates and FERC grid modernization directives are compressing procurement cycles across state transportation departments and utility operators, forcing legacy on-premise GIS installations toward SaaS architectures within compressed budget windows.
Growth Catalysts
- FERC Grid Modernization Directives:Federal Energy Regulatory Commission standards compel electric utilities to deploy real-time geospatial asset monitoring for wildfire risk corridors and storm resilience planning.
- California Wildfire Risk Mapping:State mandates for utility vegetation management and ignition probability modeling drive platform upgrades across Pacific Gas & Electric and Southern California Edison service territories.
- LiDAR Sensor Fusion:Integration of aerial LiDAR with mobile GIS platforms enables sub-meter accuracy for floodplain modeling and coastal erosion tracking in Florida and Louisiana.
Market Restraints
- Perpetual License Stranded Assets:State and municipal IT departments face write-downs on decade-old Esri enterprise agreements that resist cloud migration without full replacement costs.
- Geospatial Talent Concentration:Skilled GIS analysts cluster in coastal metro areas, creating hiring bottlenecks for Midwestern and Mountain West transportation agencies.
- Interoperability Friction:Proprietary data formats between competing platforms force costly translation layers for agencies managing legacy CAD and modern vector tile systems simultaneously.
Strategic Opportunities
- Texas Coastal Flood Modeling:Post-Hurricane Harvey infrastructure rebuilding creates demand for dynamic sea-level-rise scenario tools across Gulf Coast municipal planning departments.
- EPA Environmental Impact Assessment Automation:Streamlined NEPA compliance workflows embed geospatial analytics directly into permitting processes for energy and transportation projects.
- Edge Computing Convergence:Field-hardened tablets with onboard GPU processing enable real-time feature extraction without cellular backhaul, opening forestry and agriculture applications.
Industry Challenges
- Cloud Security Authorization Timelines:FedRAMP moderate and high baseline certifications delay SaaS GIS deployment at defense and intelligence agencies by 18-24 months.
- Legacy System Integration Complexity:Mainframe-hosted parcel tax databases in county assessor offices resist API-based connectivity without expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Geographic Information System (GIS) Market |
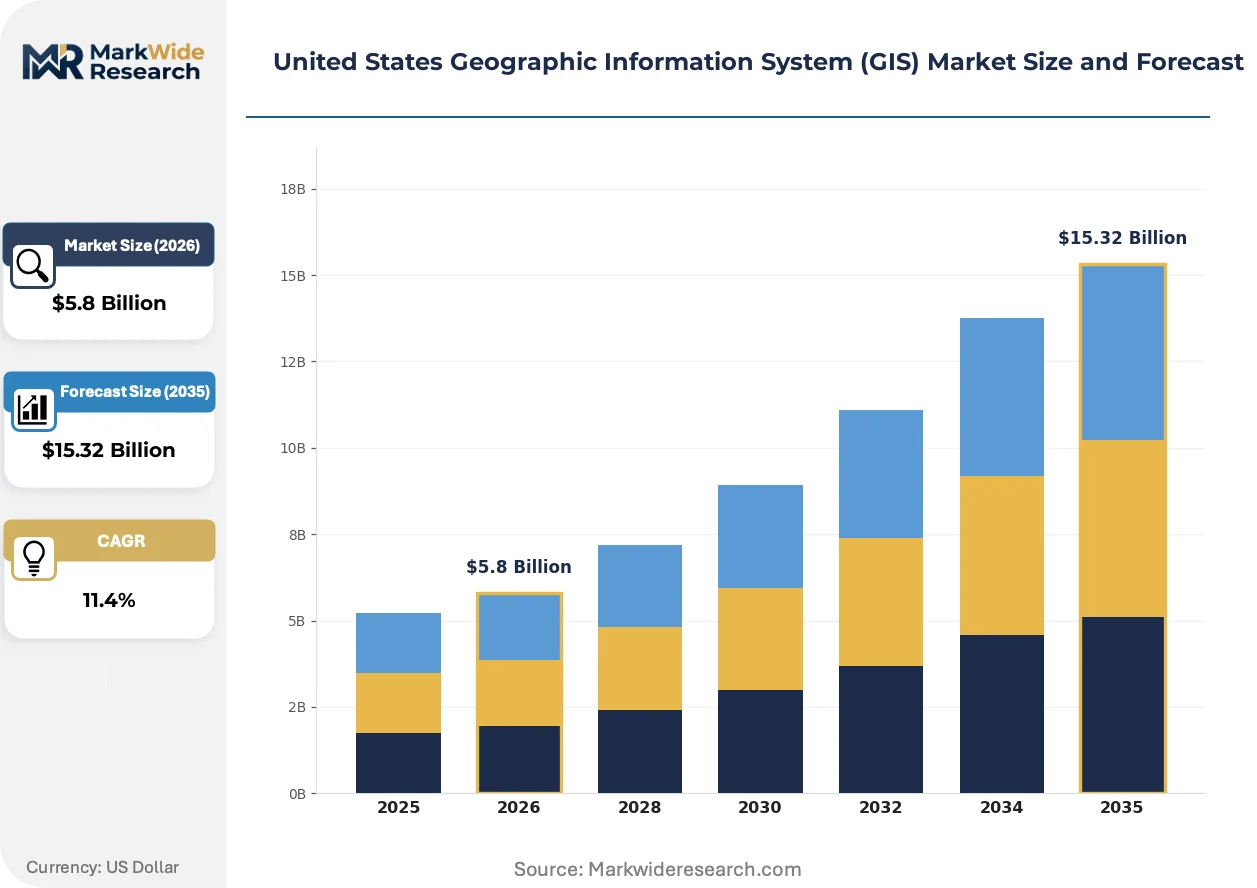
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $15.32 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Services, Cloud Solutions Deployment Model: On-Premises, Cloud-Based, Hybrid, Mobile End User: Government, Transportation, Utilities, Environmental Application: Urban Planning, Disaster Management, Resource Management, Natural Resources |
| Companies Covered | Trimble, Maxar Technologies, Esri, TomTom, Mapbox, Google, Hexagon AB, Precisely, HERE Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Geographic Information System (GIS) Market Strategic Shifts & Innovations
Vector tile streaming architectures and AI-assisted feature extraction are displacing traditional desktop-heavy workflows across public-sector GIS operations, compressing project delivery timelines while expanding real-time collaboration capabilities.
Containerized microservices architecture is decomposing monolithic GIS platforms into modular, API-first components that transportation departments and utilities can deploy selectively. State DOTs in Ohio and Pennsylvania pilot discrete routing engines and imagery pipelines without full-stack licensing. This decomposition enables vendor-agnostic data layers while pressuring incumbent providers to unbundle historically integrated offerings.
EPA environmental impact assessment protocols now mandate georeferenced audit trails for all major infrastructure permitting, compelling platform vendors to embed immutable timestamping and version control. Engineering consultancies serving energy clients reconfigure deliverable formats to satisfy automated compliance checking. The heaviest adaptation burden falls on mid-size firms previously relying on manual documentation workflows.
Municipal procurement offices increasingly unbundle implementation services from software licensing, creating separate RFP streams for platform access and analytics staffing. This bifurcation advantages specialized geospatial consultancies in Colorado and Virginia while squeezing full-service vendors accustomed to bundled pricing. The shift is most pronounced in mid-sized cities lacking in-house GIS capacity but possessing federal infrastructure grant flexibility.
United States Geographic Information System (GIS) Market Segmentation
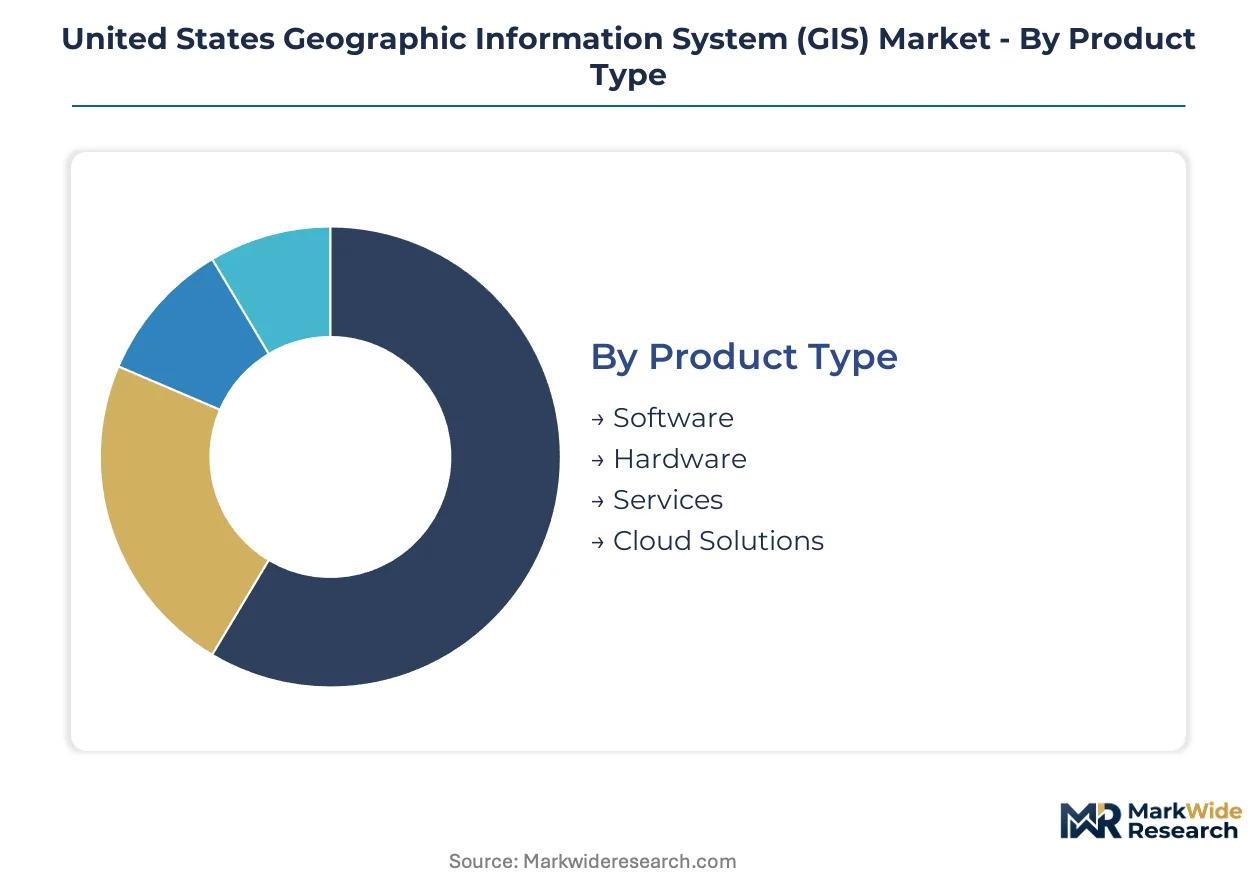
GIS procurement patterns diverge sharply across product architectures, with cloud-native platforms displacing legacy perpetual licenses while field hardware retains irreplaceable roles in precision surveying. Segmentation reveals where substitution pressures concentrate and which deployment models capture infrastructure resilience budgets.
Product Type:
Software and cloud solutions face the strongest substitution pressure as SaaS architectures displace perpetual licenses, while hardware segments defend entrenched positions through specialized sensor integration requirements.
- Software:Desktop and enterprise GIS platforms process layered vector and raster datasets with sub-meter coordinate accuracy. State transportation departments in California and Texas prioritize these tools for infrastructure resilience planning, though procurement cycles compress under federal cloud-first mandates.
- Cloud Solutions:Subscription-based platforms deliver real-time collaboration and automated feature extraction through containerized microservices. FERC grid modernization directives accelerate utility adoption across wildfire risk corridors in the Pacific Coast states.
- Hardware:GPS-enabled receivers, total stations, and field-hardened tablets capture ground-truth data where cellular connectivity fails. Demand concentrates in precision agriculture and construction surveying.
- Services:Implementation staffing, training, and managed analytics fill capability gaps for municipalities lacking in-house geospatial teams. Federal infrastructure grant flexibility expands procurement.
Software anchors the volume base while cloud solutions gain share at the steepest rate.
Deployment Model:
Cost tier differentiation separates capital-intensive on-premise installations from operational-expense cloud subscriptions, with hybrid architectures capturing agencies navigating stranded legacy assets.
- Cloud-Based:Fully managed SaaS platforms eliminate server maintenance burdens and enable automatic compliance updates for EPA environmental impact protocols. State DOTs in Ohio and Pennsylvania pilot discrete routing engines without full-stack licensing.
- Hybrid:Split architectures retain sensitive parcel data on-premise while pushing analytics workloads to cloud infrastructure. County assessor offices with mainframe-hosted tax databases favor this model.
- On-Premises:Air-gapped installations persist in defense and intelligence agencies where FedRAMP authorization timelines delay SaaS deployment by 18-24 months.
- Mobile:Field-hardened tablets with onboard GPU processing enable real-time feature extraction without cellular backhaul. Forestry and agriculture applications in the Mountain West drive adoption.
On-premises deployments retain the largest installed base while cloud-based architectures expand most quickly.
End User:
Application-specific requirements fragment procurement, with government verticals demanding audit-trail compliance while utilities prioritize real-time sensor fusion.
- Government:Federal, state, and local agencies mandate interoperable standards and climate scenario modeling tools embedded directly into platform offerings. Open data requirements reshape municipal procurement.
- Utilities:Electric power and water operators deploy geospatial asset monitoring for wildfire risk corridors and storm resilience planning. California vegetation management mandates drive platform upgrades.
- Transportation:State DOTs expand geospatial procurement for infrastructure resilience planning, with procurement cycles compressing under compressed budget windows.
- Environmental:Engineering consultancies reconfigure deliverable formats to satisfy automated NEPA compliance checking with georeferenced audit trails.
Government end users dominate current spending while utilities climb the fastest.
Application:
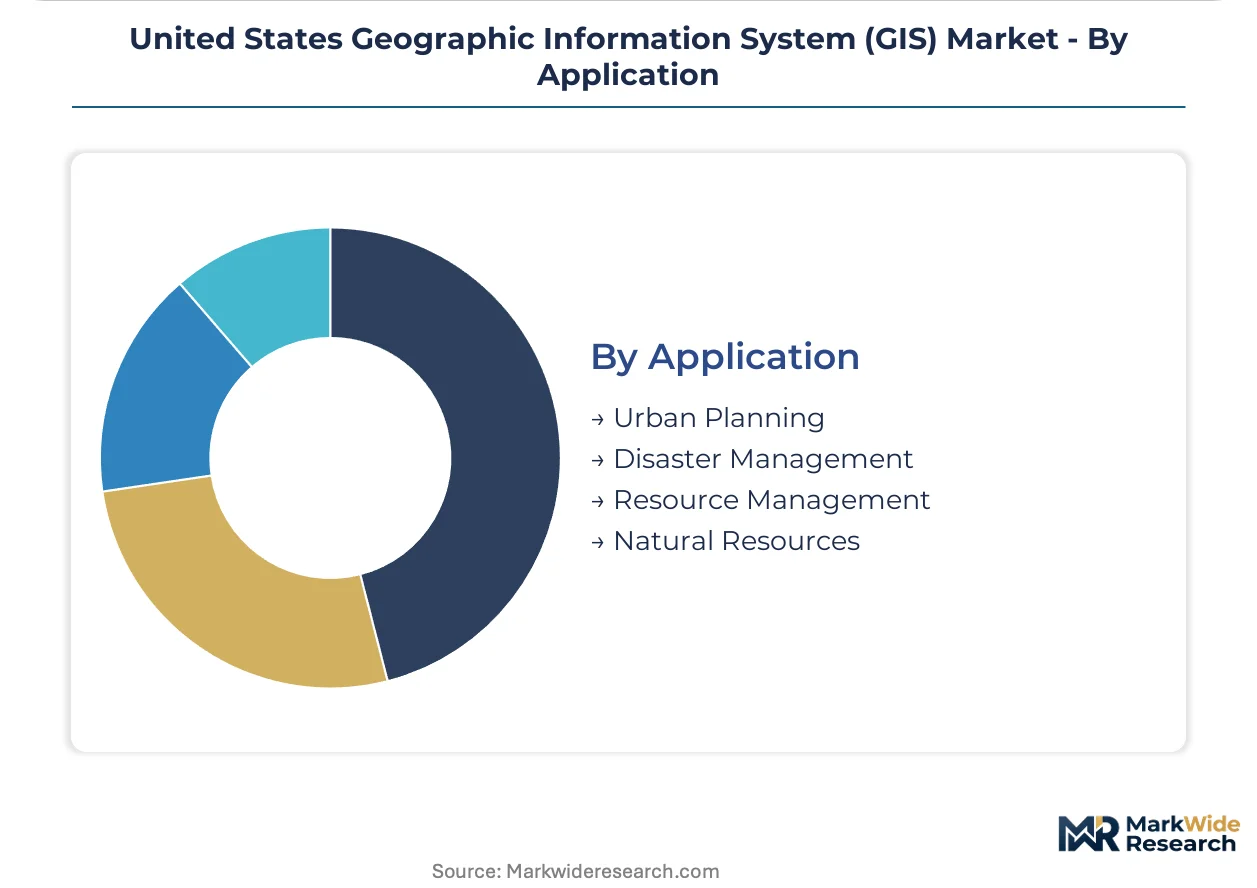
Maturity levels separate established urban planning workflows from emerging disaster management automation, with resource management applications capturing federal resilience funding.
- Urban Planning:Zoning analysis, transportation network optimization, and development impact assessment constitute mature workflows with entrenched vendor relationships. Municipal planning departments drive steady demand.
- Disaster Management:Real-time flood modeling, wildfire spread prediction, and evacuation route optimization compress project delivery timelines. Post-Hurricane Harvey rebuilding creates demand across Texas Gulf Coast departments.
- Resource Management:Timber inventory, mineral extraction monitoring, and agricultural yield mapping leverage LiDAR sensor fusion for sub-meter accuracy.
- Natural Resources:Coastal erosion tracking and wetland preservation planning in Florida and Louisiana integrate aerial imagery with mobile GIS platforms.
Urban planning anchors the volume base while disaster management gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GIS vendor concentration clusters along coastal states with dense federal infrastructure spending and acute climate exposure. California, Texas, and Florida anchor procurement volume through utility wildfire mandates, coastal flood programs, and transportation resilience budgets. The Mountain West and Midwest lag in platform adoption due to thinner geospatial talent pools and legacy IT stranded assets.
California
PG&E and Southern California Edison drive vegetation management platform upgrades under state wildfire risk mapping mandates. CPUC enforcement of ignition probability modeling compels real-time geospatial asset monitoring across transmission corridors. The Bay Area and Los Angeles basins concentrate SaaS procurement for urban planning and environmental impact workflows.
Texas
Post-Hurricane Harvey rebuilding funds dynamic sea-level-rise scenario tools across Gulf Coast municipal departments. FERC grid modernization directives accelerate electric utility deployment of storm resilience geospatial analytics. Houston and Dallas-Fort Worth anchor implementation services demand where federal infrastructure grant flexibility expands procurement.
Florida
Coastal erosion tracking and wetland preservation planning integrate aerial LiDAR with mobile GIS platforms. State environmental agencies mandate sub-meter accuracy for floodplain modeling in vulnerable counties. Miami-Dade and Tampa Bay metropolitan areas concentrate cloud-native platform adoption among water management districts.
Mountain West
Forestry and precision agriculture applications drive field-hardened tablet demand with onboard GPU processing for real-time feature extraction. Federal land management agencies deploy edge-computing solutions where cellular backhaul fails in remote terrain. Denver and Salt Lake City anchor sparse geospatial consultancy clusters serving regional transportation departments.
Midwest
Ohio and Pennsylvania state DOTs pilot containerized microservices for discrete routing engines without full-stack licensing. Legacy mainframe-hosted parcel tax databases in county assessor offices resist API-based connectivity. Chicago and Detroit metropolitan areas concentrate hybrid deployment adoption, retaining sensitive cadastral data on-premise while pushing analytics workloads to cloud infrastructure.
United States Geographic Information System (GIS) Market Key Industry Players
Concentration sits with enterprise platform incumbents that have embedded decades of institutional workflow integration across government verticals. The vendor structure stratifies into three tiers: full-stack platform providers with entrenched enterprise licensing, precision hardware specialists leveraging GPS-enabled field instrumentation, and developer-centric infrastructure vendors delivering customizable vector tile services. M&A activity targets niche analytics consultancies, while portfolio diversification pushes established players toward subscription architectures and managed services unbundling.
Within the enterprise platform tier, Esri anchors government and utility verticals through institutional workflow entrenchment. Trimble occupies a position among precision hardware specialists, leveraging GPS-enabled surveying instrument dominance for construction and agriculture field data collection. Mapbox exemplifies the developer-centric infrastructure archetype, sustaining growth among logistics and mobility startups seeking customizable base mapping and vector tile streaming capabilities.
| Leading Market Players |
|---|
| Trimble |
| Maxar Technologies |
| Esri |
| TomTom |
| Mapbox |
| Hexagon AB |
| Precisely |
| HERE Technologies |
| Others |
Cost & Logistics Intelligence
Twelve-to-eighteen-month FedRAMP authorization timelines for SaaS GIS platforms compress procurement windows while concentrating pricing power among cloud-native vendors with pre-certified infrastructure. This lead-time friction shapes how state transportation departments and utility operators balance stranded legacy license costs against subscription migration urgency.
Pricing Analysis
FERC grid modernization directives dictate the pricing tier structure across electric utility geospatial procurement. Three-tier pricing separates enterprise platform licensing from modular microservices subscriptions and project-based implementation services. Certification tier differentiation separates FedRAMP-authorized SaaS offerings from moderate-baseline pending solutions. Cost compression in on-premise perpetual licenses intensifies as municipal IT departments face write-down pressure. State DOTs with federal infrastructure grant flexibility demonstrate highest price sensitivity, while defense and intelligence agencies with air-gapped requirements show least elasticity.
Supply Chain Analysis
China and Taiwan anchor precision sensor fabrication for LiDAR components and GPU chipsets powering real-time feature extraction. Vietnam and Mexico assemble field-hardened tablets and GPS-enabled receivers for North American distribution. Rare earth element processing for magnetometers in surveying instruments rests on Chinese refining capacity. Single-source vulnerability concentrates in semiconductor lithography equipment. Distribution runs through authorized reseller networks serving state procurement offices and federal systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized geospatial analytics capacity clusters in coastal metro areas, leaving Midwestern and Mountain West transportation agencies dependent on external implementation staffing. This talent geography shapes competitive entry points and acquisition targeting across the vendor landscape.
For Market Incumbents: Consolidate enterprise platform positioning through deeper embedding of EPA environmental impact assessment protocols and immutable audit-trail functionality. Acquire niche consultancies in Colorado and Virginia to capture unbundled municipal implementation RFPs. Vertical integration into LiDAR sensor fusion pipelines defends margin position against modular microservices competitors.
For New Entrants and Emerging Players: Anchor in Texas coastal flood modeling and Florida wetland preservation planning, where post-disaster federal funding creates procurement flexibility outside entrenched Esri workflows. Target mid-sized cities lacking in-house GIS capacity but possessing infrastructure grant autonomy. Developer-centric vector tile APIs offer the sharpest go-to-market angle against legacy desktop platforms.
For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-resilience software play because federal spending allocation formulas redirect procurement toward climate scenario modeling and real-time asset monitoring. Acquisition targets include specialized geospatial consultancies with FERC compliance expertise and containerized microservices vendors serving state DOT pilot programs. Monitor FedRAMP authorization timeline compression as inflection signal for SaaS platform valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Acceleration | Pre-certified SaaS platforms capture defense and intelligence agency procurement previously reserved for on-premise installations. |
| Microservices Unbundling | Containerized routing engines and imagery pipelines let state DOTs pilot discrete capabilities without full-stack enterprise licensing. |
| LiDAR Sensor Fusion Integration | Sub-meter accuracy for floodplain modeling addresses FERC wildfire risk corridor mandates across Pacific Coast utilities. |
| Geospatial Consultancy Acquisition | Specialized implementation staffing fills capability gaps for municipalities navigating unbundled procurement RFP streams. |
| Edge Computing Convergence | Onboard GPU processing in field-hardened tablets opens forestry and agriculture applications where cellular backhaul fails. |
Research Approach
Cross-validation between primary interviews with state DOT planning officers, FERC compliance leads at electric utilities, municipal GIS managers, and geospatial consultancy principals anchors the qualitative findings. Secondary validation draws from EPA environmental impact assessment filings, FERC grid modernization orders, state procurement databases, and federal infrastructure grant allocation records. Bottom-up triangulation across county-level platform deployments and top-down reconciliation against state transportation budget appropriations ensures coverage integrity.
Sensitivity analysis around cloud migration timelines and perpetual license stranded asset assumptions shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, end-user vertical, application maturity, and regional talent concentration. CAGRs derive from logistic adoption curves fitted to SaaS subscription transitions and infrastructure resilience budget growth. Key inputs include FERC enforcement patterns, EPA protocol revision cycles, and federal grant formula reauthorization trajectories.
Underlying assumptions cover sustained federal infrastructure spending prioritization and steady EPA environmental impact assessment automation, with deviation risk concentrated in FedRAMP authorization timeline volatility and state budget austerity responses. Recalibration cycles align with material shifts in FERC grid modernization directives and federal cloud-first mandate enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geographic Information Systems (GIS)
Global Digital Maps Market
Geographic Information Systems (GIS)
High Definition (HD) Maps Market
Geographic Information Systems (GIS)
Brazil Location Based Services Market
Geographic Information Systems (GIS)
Geographic Information System Analytics Market
Geographic Information Systems (GIS)
Europe 3D Mapping and Modeling Market
Geographic Information Systems (GIS)
Russia Geospatial Analytics Market
Geographic Information Systems (GIS)
Europe Geographic Information System (GIS) Market
Geographic Information Systems (GIS)
Nigeria Location-Based Services Market
Geographic Information Systems (GIS)
Sales Mapping System Market
Geographic Information Systems (GIS)
Global GIS in Telecom Sector Market
Geographic Information Systems (GIS)
Digital Map Software Market
Geographic Information Systems (GIS)
Spain Location-Based Services Market
Geographic Information Systems (GIS)
Location-Based Marketing Software Market
Geographic Information Systems (GIS)
China Location-Based Services Market
Geographic Information Systems (GIS)
Germany Location-Based Services Market
Geographic Information Systems (GIS)
Germany Geospatial Imagery Analytics Market